
 Sanitary Napkin Equipment Market | 2026-2036
Sanitary Napkin Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Napkin Equipment Market Insights
The EU Green Deal is realigning equipment procurement criteria across European hygiene product suppliers, pushing manufacturers toward energy-efficient machinery with lower carbon footprints. Fameccanica.Data S.r.l. leverages its Italian engineering heritage to dominate high-speed wrapper machine production for premium brands. Jiangsu JWC Machinery Co. Ltd. anchors Asian supply chains with cost-competitive servo-driven lines. Zuiko Corporation specializes in precision die-cutting systems that sustain its reputation for minimal material waste.
Sanitary napkin equipment encompasses automated machinery designed to form, bond, cut, and package absorbent hygiene products at speeds exceeding 1,000 units per minute using servo-controlled motion systems. Thermoforming and ultrasonic bonding technologies create multi-layer cores with consistent absorbency profiles for mass-market reliability. The absorbent machine segment leads in capital allocation as manufacturers prioritize core formation precision where raw material costs concentrate. Ultrasonic bonding represents the fastest-growing technology dimension, displacing adhesive-dependent processes amid chemical reduction mandates from major retail buyers. Roll forming maintains stable demand in emerging markets where simpler equipment configurations reduce technical barriers to entry.
FDA oversight in the United States classifies certain feminine hygiene products as medical devices, imposing validation requirements on equipment used for disposable medical supplies that limit vendor qualification pools. REACH compliance in Europe restricts chemical adhesives and synthetic additives, redirecting R&D investment toward mechanical bonding platforms compatible with certified material inputs. India's BIS machinery safety standards and PLI scheme for domestic manufacturing create dual pressure on suppliers to localize assembly while meeting international performance benchmarks. Stakeholders must monitor how divergent regulatory timelines between developed and emerging markets reshape equipment standardization strategies and service network investments.
Market Dynamics
Ultrasonic bonding technology is rewriting competitive positioning as servo-driven systems displace adhesive-dependent platforms amid chemical reduction mandates from retail buyers and regulatory bodies.
Growth Catalysts
- India's PLI scheme:Domestic manufacturing incentives accelerate localized equipment procurement as rural distribution networks expand demand for absorbent hygiene products.
- Servo motor adoption:Energy-efficient motion systems align with EU Green Deal specifications, reducing carbon footprints while enabling production speeds exceeding 1,000 units per minute.
- Rural hygiene access programs:Southeast Asian governments channel subsidies toward feminine hygiene distribution, pulling automated capacity expansion from hygiene product suppliers.
Market Restraints
- Specialized steel and precision bearing costs:Input price volatility concentrates in high-speed wrapper machine components, compressing margin buffers for mid-tier equipment vendors.
- Italian engineering cluster concentration:Premium die-cutting and thermoforming expertise concentrates in Northern Italian manufacturing corridors, creating supply bottleneck risk.
- FDA validation requirements:Medical device classification for certain feminine hygiene products limits vendor qualification pools in the United States.
Strategic Opportunities
- Biodegradable core materials:Mechanical bonding platforms compatible with certified organic inputs capture premium positioning as REACH restrictions tighten chemical adhesive use.
- Aftermarket service unbundling:Predictive maintenance contracts and remote diagnostics create recurring revenue streams separate from capital equipment sales.
- Indonesia and Vietnam manufacturing:Underpenetrated automated production bases offer first-mover advantages as regional hygiene demand outstrips local equipment supply.
Industry Challenges
- Servo control programming expertise:Talent scarcity in motion system integration delays commissioning timelines for multi-axis production lines.
- Legacy adhesive system retrofit complexity:Existing installed base of thermal bonding equipment requires extensive reconfiguration to accommodate ultrasonic platform upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Napkin Equipment Market |
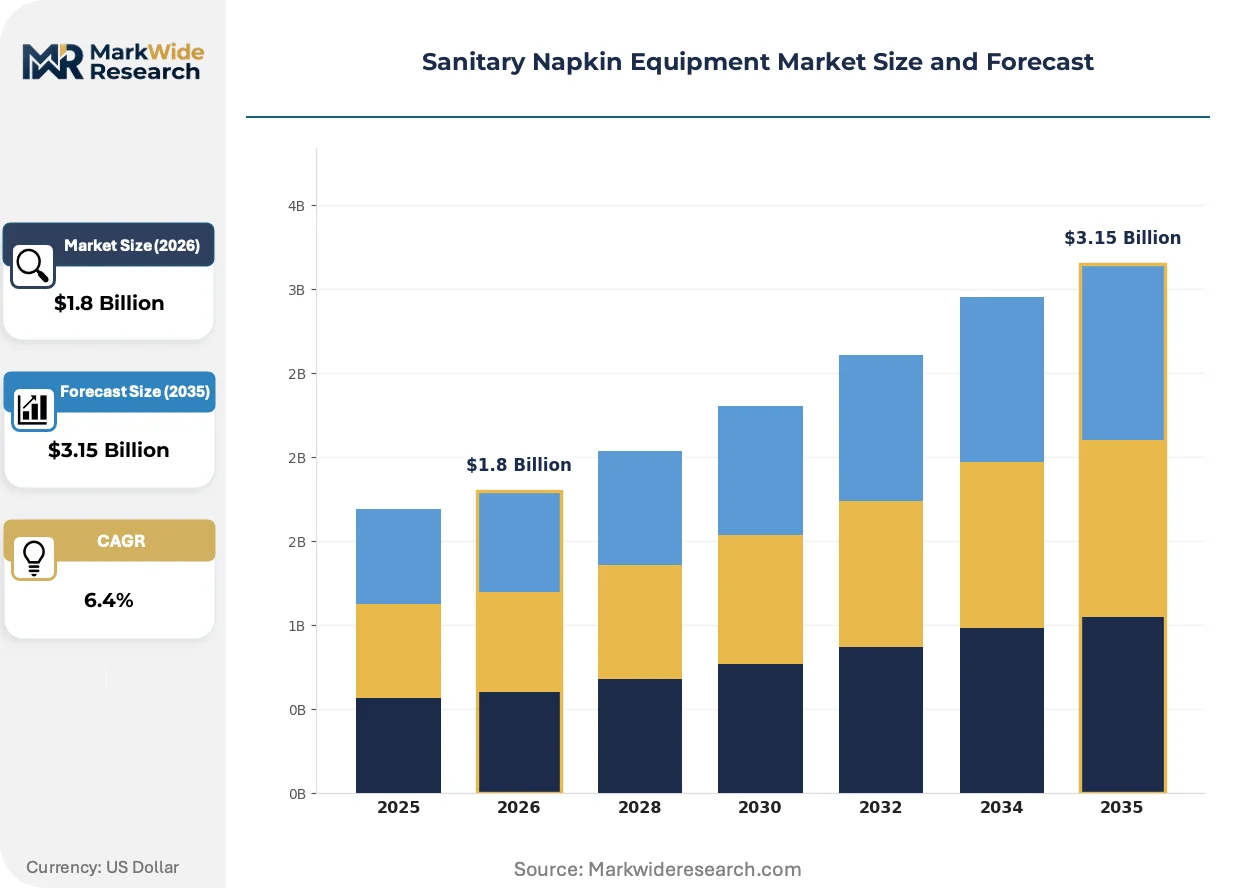
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Napkin Folder, Wrapper Machine, Packing Equipment, Absorbent Machine, Dispenser Technology: Thermoforming, Ultrasonic Bonding, Die-Cutting, Servo Motor, Roll Forming Application: Personal Care Products, Feminine Hygiene, Disposable Medical Supplies, Sanitation Solutions End User: Manufacturers, Contract Packers, Private Label Brands, Hygiene Product Suppliers |
| Companies Covered | Curt G Joa Inc., Fameccanica.Data S.r.l., MD Viola Macchine, Jiangsu JWC Machinery Co. Ltd., GDM S.p.A., Zuiko Corporation, ANDRITZ AG, SANIMAC SRL, HENGCHANG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Napkin Equipment Market Trends and Innovations
Equipment specification criteria are pivoting toward material efficiency and energy intensity metrics as buyers internalize lifecycle cost models and regulatory compliance burdens.
Servo-controlled ultrasonic bonding is rewriting process economics across absorbent core formation. This technology eliminates hot-melt adhesive consumption while enabling real-time weld strength adjustment through frequency modulation. Premium brand manufacturers in Western Europe are adopting these platforms at replacement cycle acceleration, compressing the competitive window for adhesive-dependent machinery suppliers.
REACH chemical restrictions are redirecting R&D investment toward mechanical bonding architectures compatible with certified material inputs. The regulation's substance authorization requirements extend to adhesive constituents used in feminine hygiene products, forcing equipment designers to validate process compatibility with reduced-chemistry substrates. German and French hygiene product suppliers now specify ultrasonic or thermal bonding as default procurement criteria.
Outcome-based equipment contracting is displacing traditional capital purchase models among Southeast Asian hygiene manufacturers. Leasing structures tied to output-per-hour guarantees shift technical risk to vendors while preserving buyer liquidity for distribution network expansion. This pattern concentrates in India and Indonesia where working capital constraints intersect with aggressive capacity scaling targets.
Sanitary Napkin Equipment Market Segmentation
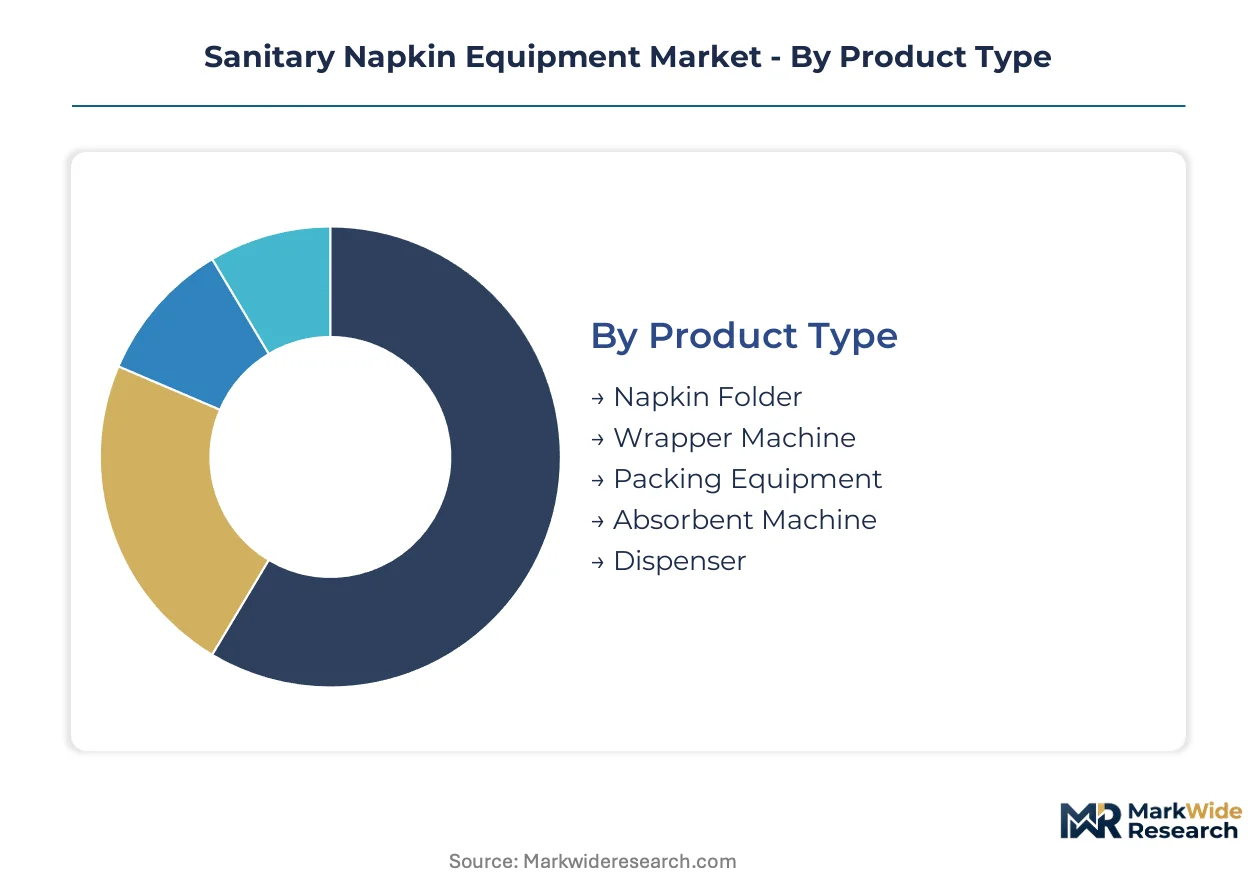
Segmentation in sanitary napkin equipment reveals how capital allocation priorities diverge across buyer archetypes. Equipment specifications vary sharply between mass-market volume producers and premium brand manufacturers seeking differentiation through precision engineering.
Product Type:
Buyers differentiate primarily by where raw material costs concentrate in their production economics.
- Absorbent Machine:Forms multi-layer cores through thermoforming and fiber deposition with consistent density profiles. Demand concentrates in India where domestic PLI incentives and rural distribution expansion pull localized procurement of high-throughput core formation lines.
- Wrapper Machine:Executes high-speed individual product wrapping at speeds exceeding 1,000 units per minute using servo-controlled film handling. Premium brand manufacturers in Western Europe specify Italian-engineered systems from Fameccanica.Data S.r.l. to meet EU Green Deal energy efficiency mandates.
- Napkin Folder:Configures final product dimensions through precision folding mechanisms.
- Packing Equipment:Aggregates individual units into retail-ready configurations.
- Dispenser:Produces vending and point-of-use distribution hardware.
Absorbent machines lead volumes today; wrapper machines are gaining share fastest.
Technology:
Process selection determines chemical compliance exposure and energy intensity benchmarks.
- Ultrasonic Bonding:Replaces hot-melt adhesives with mechanical welding through frequency-modulated servo systems. REACH restrictions on chemical adhesives redirect German and French hygiene suppliers toward this platform as default procurement criteria.
- Servo Motor:Enables real-time motion adjustment with 30-40% energy reduction versus pneumatic alternatives. EU Green Deal specifications now mandate servo architectures for new equipment qualification.
- Thermoforming:Shapes absorbent cores through heated mold compression.
- Die-Cutting:Executes precision material separation with minimal waste.
- Roll Forming:Maintains stable demand in emerging markets with simpler technical barriers.
Servo motor systems anchor current installed base; ultrasonic bonding shows steepest expansion trajectory.
Application:
Regulatory classification thresholds reshape equipment validation requirements across use cases.
- Feminine Hygiene:Drives equipment standardization for high-volume disposable absorbent products. India's rural access programs and Southeast Asian government subsidies pull automated capacity expansion from regional hygiene product suppliers.
- Disposable Medical Supplies:Triggers FDA medical device classification in the United States, limiting qualified vendor pools through validation requirements. Contract packers serving hospital supply chains face stricter documentation burdens.
- Personal Care Products:Encompasses broader consumer hygiene applications.
- Sanitation Solutions:Covers institutional and public facility deployment.
Feminine hygiene commands dominant equipment spend; disposable medical supplies are climbing the fastest.
End User:
Capital structure and technical integration depth separate procurement strategies.
- Manufacturers:Integrate full production lines with in-house process engineering capabilities. These buyers specify complete servo-driven systems with predictive maintenance integration to maximize uptime on 24-hour operations.
- Private Label Brands:Prioritize flexible equipment configurations enabling rapid product format switching. Outcome-based leasing structures tied to output-per-hour guarantees concentrate among these buyers in Indonesia and India.
- Contract Packers:Require validated systems for multi-client production with audit trail documentation.
- Hygiene Product Suppliers:Source equipment for captive production of branded lines.
Manufacturers lead capital deployment today; private label brands are expanding procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian engineering talent clusters around Bologna and Milan anchor European equipment design leadership, while Chinese manufacturing workforce concentration in Jiangsu province dominates Asian supply chains.
United States
FDA medical device classification for certain feminine hygiene products limits qualified vendor pools through validation requirements. Domestic contract packers serving hospital supply chains face stricter documentation burdens than consumer-facing producers. Equipment procurement concentrates in Wisconsin and Ohio industrial corridors where paper converting heritage supports absorbent product machinery integration.
Germany
REACH chemical restrictions redirect hygiene product suppliers toward mechanical bonding platforms compatible with certified material inputs. The country's national chemical regulator enforces substance authorization requirements extending to adhesive constituents. Equipment specification leadership clusters in Baden-Württemberg where precision engineering traditions serve premium brand manufacturers.
India
BIS machinery safety standards and PLI scheme incentives create dual pressure on suppliers to localize assembly while meeting international performance benchmarks. Rural distribution network expansion drives demand for high-throughput core formation lines. Manufacturing investment concentrates in Gujarat and Maharashtra where domestic hygiene brands scale automated capacity.
Italy
EU Green Deal specifications mandate energy-efficient servo motor architectures for new equipment qualification. Northern Italian manufacturing corridors around Bologna concentrate premium die-cutting and thermoforming expertise. Fameccanica.Data S.r.l. leverages this engineering heritage to dominate high-speed wrapper machine production for Western European premium brands.
China
Servo-driven production line adoption accelerates amid cost-competitive manufacturing scale targets. National standards for machinery safety and energy efficiency reshape procurement criteria for domestic hygiene brands. Equipment production clusters in Jiangsu province where Jiangsu JWC Machinery Co. Ltd. anchors Asian supply chains with localized assembly capabilities.
Sanitary Napkin Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered competitive strata. The vendor base separates between integrated machinery builders owning full fabrication capabilities and technology licensors outsourcing component manufacturing. Three archetypes dominate: Italian precision engineering specialists, Chinese scale-driven fabricators, and Japanese precision automation houses. Consolidation pressure intensifies through strategic partnerships linking European design expertise with Asian manufacturing scale.
Among Italian engineering specialists, Fameccanica.Data S.r.l. and MD Viola Macchine exemplify premium-tier positioning anchored in Northern Italian industrial corridors. Zuiko Corporation represents Japanese precision automation heritage in die-cutting specialization. Jiangsu JWC Machinery Co. Ltd. occupies the scale-driven Chinese fabricator archetype with cost-competitive servo-driven lines. These three entities collectively illustrate the geographic and capability segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Curt G Joa Inc. |
| Fameccanica.Data S.r.l. |
| MD Viola Macchine |
| Jiangsu JWC Machinery Co. Ltd. |
| GDM S.p.A. |
| Zuiko Corporation |
| ANDRITZ AG |
| SANIMAC SRL |
| HENGCHANG |
| Others |
Pricing and Supply Chain Analysis
Family-owned Italian engineering specialists concentrated around Bologna and Milan anchor premium equipment pricing through captive control over precision die-cutting and thermoforming expertise, while Chinese scale fabricators in Jiangsu province compress mid-tier pricing through localized servo motor assembly and working capital flexibility.
Pricing Analysis
The bundled-versus-unbunded service split distinguishes capital equipment transactions from recurring revenue streams. Premium-mid-economy pricing differentiation separates Italian-engineered wrapper machines with integrated predictive maintenance from Chinese cost-competitive lines sold bare. Cost compression in mid-tier configurations is intensifying because specialized steel and precision bearing input volatility erodes margin buffers. Private label brands in Indonesia and India exhibit highest price sensitivity through outcome-based leasing structures, while Western European premium manufacturers prioritize energy efficiency certification over upfront cost.
Supply Chain Analysis
Freight cost escalation from Northern Italian engineering clusters to Southeast Asian hygiene manufacturers reinforces regionalization pressures. Equipment fabrication draws from Italian precision component suppliers, Chinese servo motor manufacturers, and German automation control specialists. Single-source vulnerability concentrates in high-speed wrapper machine bearings sourced from Baden-Württemberg engineering corridors. Distribution runs through direct vendor relationships with major hygiene product suppliers, supplemented by regional agents serving private label brands and contract packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sanitary napkin equipment market functions as a stable compounder anchored by India's PLI scheme and rural distribution expansion, which generate sustained demand pull for automated core formation and wrapper systems.
For Market Incumbents: Anchor defensive positioning through backward integration into precision bearing supply chains and ultrasonic bonding R&D platforms. Servo control programming talent scarcity threatens commissioning timelines, making certification partnerships with German technical institutes a critical lever. Capacity addition in Gujarat and Maharashtra manufacturing corridors captures PLI-linked procurement from domestic hygiene brands scaling automated production.
For New Entrants and Emerging Players: Begin with Indonesia and Vietnam, where underpenetrated automated production bases outstrip local equipment supply. Napkin folder and packing equipment segments offer lower technical barriers than high-speed wrapper systems. A leasing-based go-to-market model tied to output-per-hour guarantees aligns with working capital constraints among Southeast Asian private label manufacturers.
For Investors and Strategic Acquirers: Valuations sit cheapest among Chinese scale fabricators with servo-driven line portfolios and underdeveloped aftermarket service revenue. The five-to-ten year viability window favors platforms with ultrasonic bonding technology compatibility and REACH-compliant mechanical bonding architectures. Acquisition targets should demonstrate installed base density in India or Southeast Asia. The signal to watch is replacement cycle acceleration among Western European premium brands adopting EU Green Deal-mandated energy efficiency specifications.
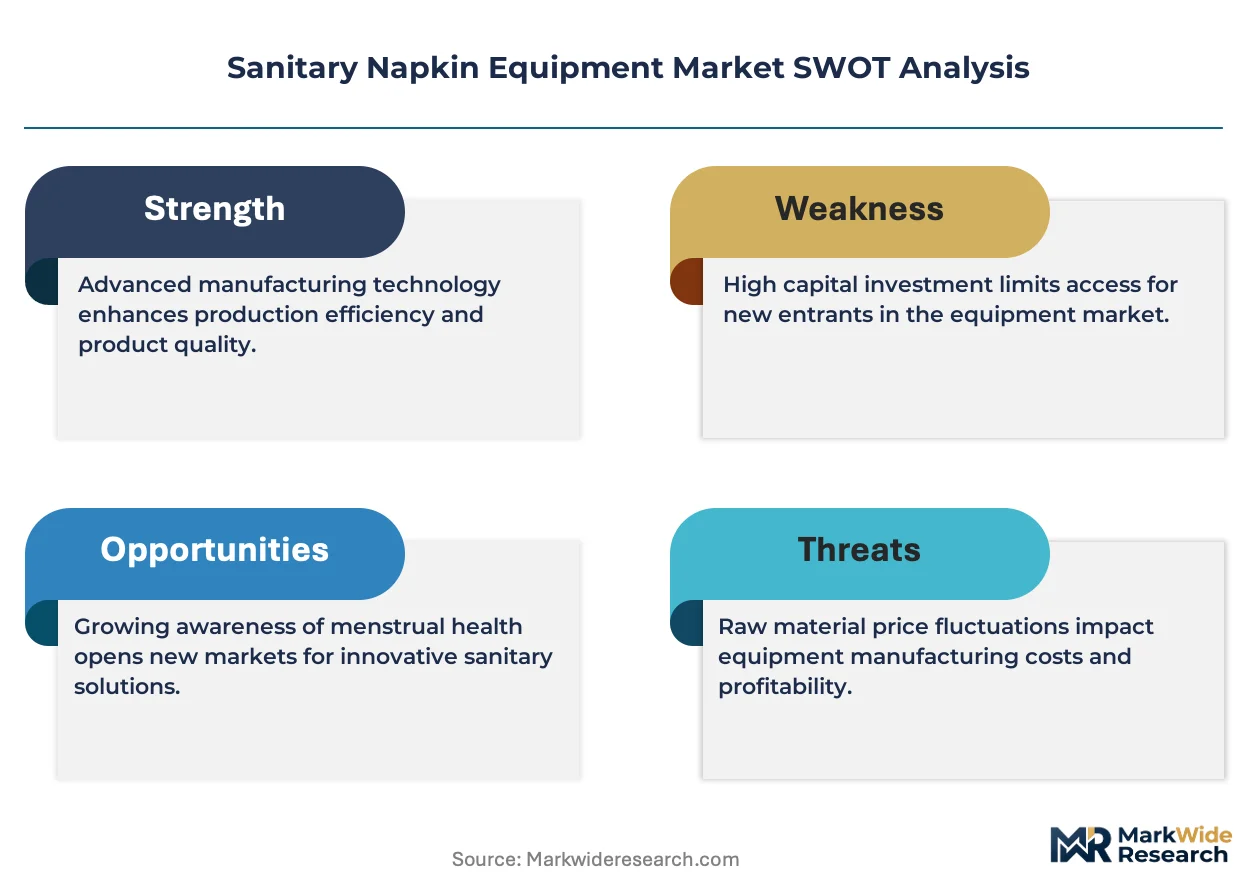
| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Bonding Platform Development | Eliminates REACH-restricted adhesive dependencies for German and French hygiene suppliers. |
| Servo Motor Architecture Migration | Aligns with EU Green Deal energy efficiency mandates while enabling 1,000+ unit-per-minute speeds. |
| Aftermarket Service Unbundling | Predictive maintenance contracts create recurring revenue separate from capital equipment sales. |
| Indonesia Manufacturing Localization | Captures first-mover advantage as regional hygiene demand outstrips local equipment supply. |
| PLI Scheme Alignment in India | BIS certification and localized assembly qualify suppliers for domestic manufacturing incentives. |
Research Methodology
Bottom-up hygiene product manufacturer modeling reconciled against top-down equipment supplier production tracking forms the analytical core of this study. Primary interviews with plant engineers at absorbent hygiene producers, procurement leads at private label brands, aftermarket service heads at Italian engineering specialists, and regulatory affairs managers navigating FDA and REACH compliance were cross-validated against secondary sources including BIS machinery safety filings, EU ETS energy efficiency disclosures, and Indian PLI scheme beneficiary registries.
Input-output matrices mapped equipment type, bonding technology, and end-user segment against regional production capacity and regulatory framework clusters across the modeling period. CAGRs were derived from segment-level demand elasticity modeling and supplier shipment trajectory analysis. Forecast inputs incorporated servo motor adoption curves, rural hygiene access program subsidy allocations, and REACH chemical restriction implementation timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory timeline shifts, raw material commodity price shocks, and geopolitical disruptions to precision component trade flows. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Europe Nuclear Medicine Equipment Market
Medical Equipment
Medical Gas Cylinders Market
Medical Equipment
MRI Transport Market
Medical Equipment
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Global Examination Lights Market
Medical Equipment
Global Surgical Table Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Global Radiation Therapy Equipment Market
Medical Equipment
Medical Oxygen Systems Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Global Mobile Operating Tables Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Proctologic Table Market