
 Global Healthcare Nanotechnology (Nanomedicine) Market | 2026-2036
Global Healthcare Nanotechnology (Nanomedicine) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Nanotechnology (Nanomedicine) Market Foresight
Switzerland is reshaping European nanomedicine manufacturing through Roche's Basel-based biologics-nanoparticle conjugation facilities. Pfizer Inc. leverages its lipid nanoparticle expertise from COVID-19 vaccine platforms to sustain leadership in mRNA-nanocarrier applications. Novartis anchors its position through the Basel cell and gene therapy hub, where nanotechnology intersects with CAR-T manufacturing. Sanofi competes by extending its Paris-Saclay research campus into nanotheranostics for cardiovascular applications.
Healthcare nanotechnology encompasses the engineering of materials at 1-100 nanometer scale for diagnostic, therapeutic, or preventive medical applications, utilizing lipid nanoparticles, polymeric micelles, and inorganic nanocrystals synthesized through bottom-up self-assembly or top-down lithographic methods to achieve targeted cellular interaction. Nanocarriers dominate current revenue pools due to their established role in oncology drug delivery, while theranostics represents the fastest-expanding delivery technology segment as clinicians seek combined diagnostic-therapeutic platforms. Quantum dots occupy a specialized niche in high-resolution imaging agents, though regulatory complexity constrains their clinical translation speed.
The FDA's nanotechnology regulatory science program and EMA's reflection paper on nanomedicine quality standards create divergent compliance pathways that fragment market access strategies. ISO/TS 19337:2021 provides the foundational characterization framework, yet gaps in batch-to-batch consistency requirements force manufacturers into redundant testing protocols. Stakeholders must monitor evolving pharmacovigilance expectations for long-circulating nanoparticles as post-market surveillance databases mature.
Market Dynamics
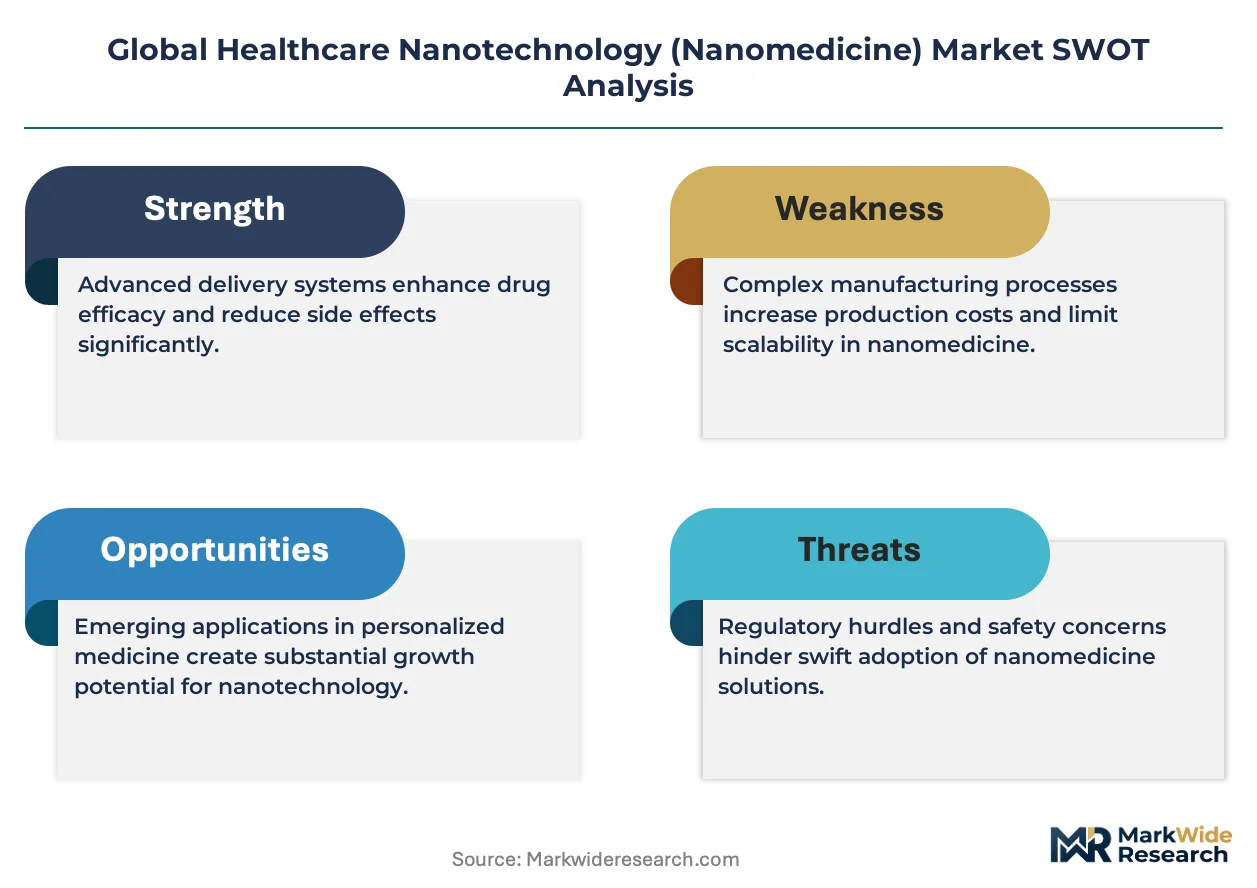
The nanomedicine market is compressing around regulatory convergence pressure as ISO/TS 19337:2021 characterization standards force manufacturers into redundant batch-testing protocols that fragment market access strategies across FDA and EMA jurisdictions.
Growth Catalysts
- Accelerated FDA approval pathways:The FDA's nanotechnology regulatory science program compresses development timelines for oncology nanocarriers, enabling faster clinical translation of lipid nanoparticle formulations.
- NIH funding concentration:Federal research dollars cluster around Boston and San Diego corridors, creating geographic innovation density that attracts venture capital flows into early-stage nanotherapeutic ventures.
- Oncology therapeutic demand:Pharmaceutical scaling of nanocarrier adoption for cancer drug delivery creates sustained revenue pools as clinicians seek targeted cellular interaction over systemic chemotherapy.
Market Restraints
- Batch-to-consistency gaps:ISO/TS 19337:2021 lacks enforceable batch-to-batch requirements, forcing manufacturers into redundant testing protocols that inflate quality assurance costs.
- Quantum dot regulatory friction:EMA reflection papers on nanomedicine quality standards create divergent compliance pathways that slow clinical translation of inorganic nanocrystal imaging agents.
- Long-circulating nanoparticle surveillance:Immature post-market pharmacovigilance databases for persistent nanomaterials create liability uncertainty that constrains insurer coverage decisions.
Strategic Opportunities
- Theranostics white space:Combined diagnostic-therapeutic platforms represent the fastest-expanding delivery technology segment as clinicians seek unified treatment monitoring capabilities.
- CAR-T manufacturing convergence:Nanotechnology intersects with cell and gene therapy production in Basel and Paris-Saclay hubs, creating integrated biologics-nanoparticle conjugation capabilities.
- mRNA-nanocarrier platform extension:Lipid nanoparticle expertise developed for infectious disease vaccines transfers to oncology and rare disease applications with minimal formulation redevelopment.
Industry Challenges
- Characterization scientist scarcity:Specialized talent in electron microscopy and dynamic light scattering for 1-100 nanometer material validation commands premium compensation that strains mid-cap R&D budgets.
- Bottom-up synthesis standardization:Self-assembly manufacturing methods produce inherent batch variability that conflicts with pharmaceutical cGMP requirements for reproducible therapeutic dosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Nanotechnology (Nanomedicine) Market |
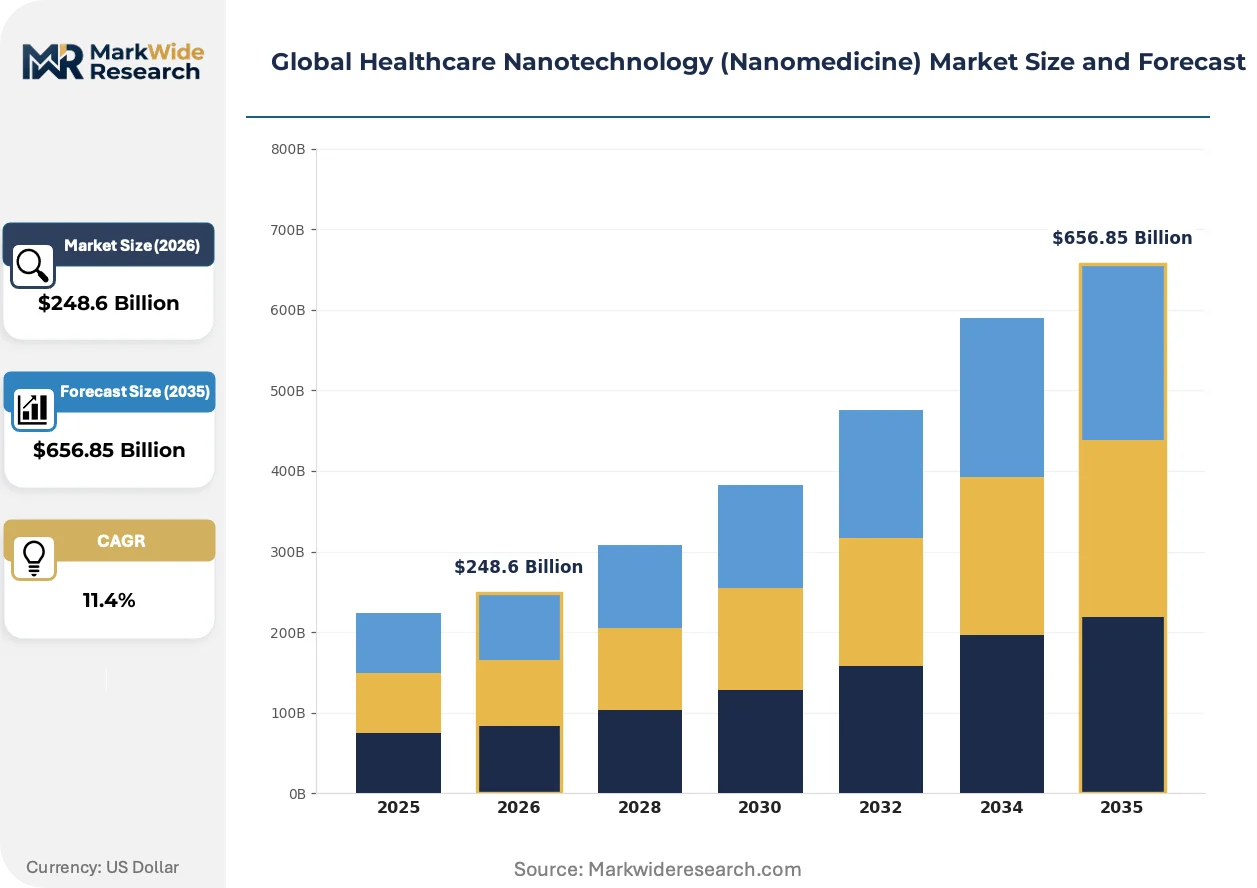
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $656.85 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanosensors, Nanocarriers, Quantum Dots, Nanorobots, Nanotubes Therapy Area: Oncology, Neurology, Immunology, Infectious Diseases, Cardiovascular End User: Hospitals, Research Laboratories, Diagnostic Centers, Pharmaceutical Companies, Academic Institutions Delivery Technology: Targeted Drug Delivery, Controlled Release, Imaging Agents, Biosensors, Theranostics |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Merck & Co., Sanofi, Novartis AG, Roche, Bristol-Myers Squibb, Amgen, Nanobiotix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Nanotechnology (Nanomedicine) Market Shifts & Advancements
Active pharmaceutical ingredient manufacturers are reconfiguring production footprints around converging demands for both traditional small-molecule synthesis and nanoscale formulation capabilities.
Polymeric micelle drug delivery systems are rendering obsolete conventional systemic chemotherapy administration in solid tumor oncology. Academic medical centers in Germany and Japan are adopting these platforms at accelerating pace for paclitaxel and docetaxel reformulations. The shift is compressing market share for conventional intravenous infusion protocols that lack tumor-targeting ligand functionalization.
EMA's reflection paper on nanomedicine quality standards is forcing divergence in European market access timelines relative to FDA pathways. Manufacturers now maintain parallel regulatory dossiers that inflate compliance staffing requirements by approximately forty percent for dual-territory launches. Oncology nanocarriers face the steepest documentation burden as EMA demands extended stability data beyond FDA requirements.
Hospital procurement committees are consolidating vendor relationships around integrated nanotheranostic suppliers capable of delivering both imaging agents and companion therapeutic payloads. The shift displaces standalone diagnostic contrast vendors from formulary access in tertiary oncology centers. Switzerland and the Netherlands exhibit the most pronounced consolidation as their national health technology assessment bodies prioritize total-cost-of-care metrics over unit pricing.
Global Healthcare Nanotechnology (Nanomedicine) Market Segmentation
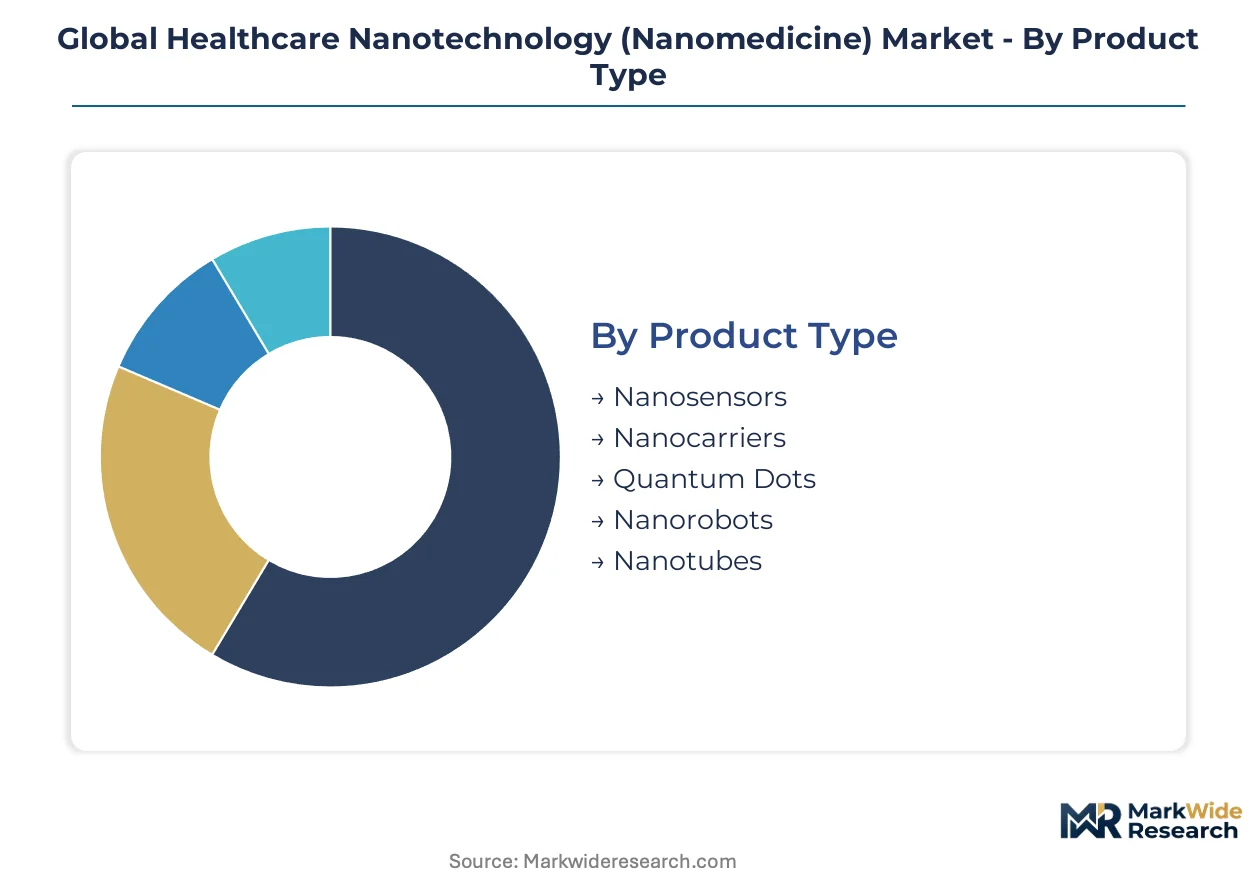
Healthcare nanotechnology segmentation reveals distinct commercial dynamics across product architectures, therapeutic targets, and delivery modalities. Product type differentiation separates established revenue pools from emerging platforms, while therapy area concentration directs R&D resource allocation toward oncology dominance.
Product Type:
Cost tier stratification across nanotechnology products separates high-volume manufacturing platforms from specialized precision-engineered systems requiring advanced fabrication infrastructure.
- Nanocarriers:Lipid nanoparticles and polymeric micelles engineered through bottom-up self-assembly methods enable targeted cellular interaction for oncology therapeutics. Demand concentrates in the United States where NIH funding accelerates clinical translation of paclitaxel and docetaxel reformulations. Manufacturing scale advantages from COVID-19 vaccine platform experience sustain competitive positioning.
- Quantum Dots:Inorganic nanocrystal imaging agents synthesized through colloidal chemistry deliver high-resolution optical properties for diagnostic applications. Clinical translation in Germany and Japan progresses slowly due to EMA regulatory complexity around long-term biopersistence concerns. Specialized niche status constrains volume expansion despite superior photostability.
- Nanosensors:Electrochemical and optical detection platforms functionalized with biomolecular recognition elements for real-time physiological monitoring.
- Nanorobots:Molecular machines and DNA origami structures enabling targeted mechanical intervention at cellular scales.
- Nanotubes:Carbon-based cylindrical nanostructures exploited for drug payload containment and electrical interface applications.
Nanocarriers command the established base. The steepest expansion runs through theranostics convergence platforms.
Therapy Area:
Application concentration across disease modalities reflects reimbursement dynamics and unmet medical need severity in target populations.
- Oncology:Solid tumor targeting through enhanced permeability and retention effect drives nanocarrier adoption for chemotherapy reformulation. Academic medical centers in Germany and Japan accelerate polymeric micelle administration protocols. The FDA's accelerated approval pathways compress development timelines for lipid nanoparticle oncology formulations.
- Neurology:Blood-brain barrier penetration challenges position nanotechnology as critical enabler for neurotherapeutic delivery. Research corridors in Boston and Basel concentrate funding for peptide-functionalized nanoparticles targeting glioblastoma and neurodegenerative indications. Clinical validation remains early-stage relative to oncology maturity.
- Cardiovascular:Nanotheranostic platforms for atherosclerotic plaque imaging and therapeutic intervention.
- Immunology:Nanoparticle adjuvants and immune cell modulation for autoimmune and vaccine applications.
- Infectious Diseases:mRNA-nanocarrier platform extension from COVID-19 vaccines toward antimicrobial resistance targets.
Oncology commands the established base. The steepest expansion runs through neurology as blood-brain barrier engineering matures.
End User:
Customer type segmentation distinguishes procurement authority, technical sophistication requirements, and volume concentration across the value chain.
- Pharmaceutical Companies:Integrated development and manufacturing organizations scaling nanocarrier platforms for commercial therapeutic portfolios. Roche's Basel facilities and Pfizer's lipid nanoparticle expertise exemplify vertical capability consolidation. Batch-to-batch consistency requirements from ISO/TS 19337:2021 drive quality assurance investment.
- Hospitals:Tertiary oncology centers consolidating vendor relationships around integrated nanotheranostic suppliers capable of delivering imaging agents and companion therapeutics. Procurement committees in Switzerland and the Netherlands prioritize total-cost-of-care metrics. Formulary access displaces standalone diagnostic contrast vendors.
- Research Laboratories:Early-stage characterization and preclinical validation facilities.
- Diagnostic Centers:Imaging-focused service providers adopting quantum dot and theranostic platforms.
- Academic Institutions:Fundamental nanomaterial synthesis and mechanism-of-action research.
Pharmaceutical companies command the established base. The steepest expansion runs through hospital procurement consolidation around integrated suppliers.
Delivery Technology:
Functional capability segmentation separates passive physical properties from active biological targeting and multimodal integration.
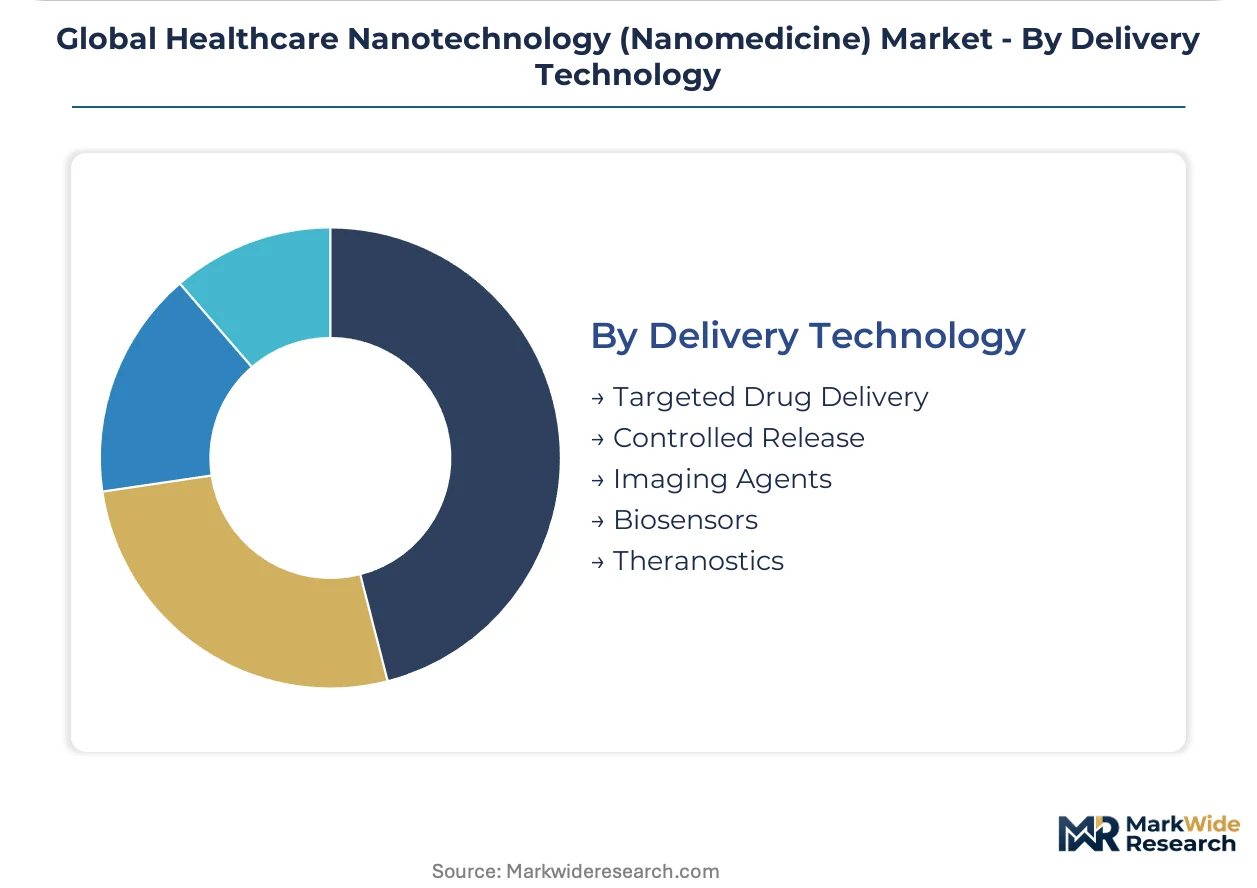
- Theranostics:Unified diagnostic-therapeutic platforms enabling real-time treatment monitoring and adaptive intervention. Clinicians in tertiary centers seek combined capabilities over fragmented diagnostic-then-therapeutic protocols. The fastest-expanding segment as regulatory pathways mature for companion payload systems.
- Targeted Drug Delivery:Ligand-functionalized nanocarriers achieving tumor-specific accumulation through receptor binding. Solid tumor oncology applications in the United States and Japan dominate clinical deployment. EMA stability data requirements extend European market access timelines relative to FDA pathways.
- Controlled Release:Temporal modulation of therapeutic payload availability through polymeric degradation kinetics.
- Imaging Agents:Contrast enhancement for MRI, CT, and optical modalities.
- Biosensors:Real-time molecular detection for point-of-care and continuous monitoring applications.
Targeted drug delivery commands the established base. The steepest expansion runs through theranostics as clinicians demand unified treatment monitoring capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's nanotechnology regulatory science program anchors the United States as the dominant geography, with NIH funding concentration in Boston and San Diego corridors accelerating clinical translation timelines for oncology nanocarriers.
United States
NIH funding clusters around Boston and San Diego research corridors, attracting venture capital flows into early-stage nanotherapeutic ventures. The FDA's accelerated approval pathways compress development timelines for lipid nanoparticle oncology formulations. Academic medical centers in these hubs accelerate polymeric micelle administration protocols for paclitaxel reformulations.
Switzerland
Roche's Basel-based biologics-nanoparticle conjugation facilities reshape European nanomedicine manufacturing capabilities. Swissmedic maintains alignment with EMA reflection papers while offering streamlined quality standard consultations for nanomedicine developers. The Basel cell and gene therapy hub integrates nanotechnology with CAR-T manufacturing infrastructure.
Germany
Academic medical centers accelerate adoption of polymeric micelle platforms for docetaxel reformulations in solid tumor oncology. The country's national pharmaceutical regulator applies extended stability data requirements beyond FDA standards for oncology nanocarrier dossiers. Research concentration in Munich and Heidelberg drives peptide-functionalized nanoparticle development for blood-brain barrier penetration.
Japan
PMDA guidelines for nanomedicine quality standards create distinct compliance pathways that compress market access timelines relative to European jurisdictions. METI funding programs target mRNA-nanocarrier platform extension toward antimicrobial resistance applications. Tokyo and Osaka academic medical centers lead clinical deployment of targeted drug delivery systems.
France
Sanofi extends its Paris-Saclay research campus into nanotheranostics for cardiovascular applications, competing with Swiss manufacturing dominance. ANSM consultation procedures for nanomedicine classification create regulatory clarity that attracts formulation development investment. The Île-de-France cluster concentrates lipid nanoparticle expertise transferred from infectious disease vaccine platforms.
Global Healthcare Nanotechnology (Nanomedicine) Market Competitive Landscape
Capability concentration sits with specialized nanocarrier developers; scale advantage sits with pharmaceutical majors leveraging COVID-19 vaccine platform experience. The market structure tiers between integrated biologics-nanoparticle conjugation facilities and standalone formulation specialists. Three archetypes dominate: lipid nanoparticle platform extenders, polymeric micelle oncology specialists, and theranostic integrated suppliers. Competitive moves center on backward integration into active pharmaceutical ingredient manufacturing and strategic partnerships for CAR-T manufacturing convergence.
Among U.S.-based pharmaceutical majors, Pfizer Inc. and Johnson & Johnson exemplify lipid nanoparticle platform extension strategies, while Roche represents the integrated biologics-nanoparticle conjugation archetype through its Basel-based capabilities. Novartis AG occupies a position at the intersection of nanotechnology and cell therapy manufacturing. These three anchors illustrate how COVID-19 vaccine-derived expertise transfers to oncology and rare disease applications with minimal formulation redevelopment.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Merck & Co. |
| Sanofi |
| Novartis AG |
| Roche |
| Bristol-Myers Squibb |
| Amgen |
| Nanobiotix |
| Others |
Supply & Pricing Matrix
Regulatory divergence between FDA and EMA jurisdictions creates dual-compliance cost burdens that widen pricing spreads between premium GMP-certified nanocarriers and economy-tier formulations while simultaneously fragmenting supplier qualification requirements across Atlantic manufacturing corridors.
Pricing Analysis
United States-based nanocarrier formulations command 15-25% premiums over European equivalents due to accelerated FDA approval pathways compressing time-to-market. Three-tier pricing structure across premium, standard, and economy levels separates Roche's Basel-originated biologics-nanoparticle conjugates from commodity lipid nanoparticle formulations. Cost compression in standard-tier oncology nanocarriers is intensifying because EMA extended stability data requirements inflate European dossier preparation costs. Hospital procurement committees in Switzerland and the Netherlands exhibit lowest price sensitivity due to total-cost-of-care reimbursement frameworks, while mid-cap pharmaceutical developers in Germany face acute margin pressure from redundant ISO/TS 19337:2021 batch-testing protocols.
Supply Chain Analysis
Supplier financing terms extending to 90-120 days characterize relationships between active pharmaceutical ingredient manufacturers and nanoscale formulation specialists, reflecting capital intensity of electron microscopy validation infrastructure. Manufacturing concentration centers on Switzerland, the United States, and Germany, with Roche's Basel facilities and Pfizer's lipid nanoparticle platforms anchoring Atlantic supply. Critical raw material dependencies include pharmaceutical-grade lipids, polymeric excipients, and high-purity solvents for bottom-up self-assembly synthesis. Single-source vulnerability around specialized electron microscopy characterization scientists strains mid-cap R&D budgets. Distribution runs through integrated biologics-nanoparticle conjugation facilities rather than standalone formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions and delivery technology segments creates niche entry points for specialists capable of bridging FDA-EMA compliance gaps or accelerating theranostics platform development.
For Market Incumbents: Pre-empt emerging entrant pressure in theranostics by securing backward integration into quantum dot imaging agent manufacturing before EMA biopersistence guidelines harden. Anchor capacity addition in Basel and Boston corridors where NIH funding density attracts scarce characterization talent. Defensive patent landscaping around lipid nanoparticle formulation IP blocks mRNA-platform extension by mid-cap competitors. For New Entrants and Emerging Players: Establish a beachhead in nanosensor platforms for real-time physiological monitoring, a segment where regulatory pathways remain underdeveloped relative to nanocarrier saturation. Target German academic medical centers accelerating polymeric micelle adoption for docetaxel reformulations, where procurement committees prioritize technical performance over incumbent brand loyalty. Lead with ISO/TS 19337:2021 pre-certification to compress pharmaceutical company vendor qualification timelines. For Investors and Strategic Acquirers: FDA nanotechnology regulatory science program maturation reshapes the acquisition landscape toward platforms with demonstrated accelerated approval track records. Five-to-ten year viability hinges on therapeutic area diversification beyond oncology dominance. Target acquisition archetype: mid-cap polymeric micelle specialists with established GMP infrastructure and blood-brain barrier peptide functionalization IP. Monitor PMDA guideline harmonization signals as inflection indicator for Asia-Pacific market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval compresses oncology nanocarrier development timelines relative to EMA reflection paper routes. |
| Backward Integration | Captive supply of pharmaceutical-grade lipids insulates margin pressure from commodity solvent volatility. |
| Hospital System Partnership | Integrated nanotheranostic supplier status secures formulary access in Switzerland and Netherlands tertiary centers. |
| Platform Integration | Lipid nanoparticle expertise from infectious disease vaccines transfers to oncology with minimal formulation redevelopment. |
| Strategic Partnership | CAR-T manufacturing convergence partnerships in Basel hubs integrate nanotechnology with cell therapy production. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA nanotechnology regulatory science program documentation, EMA reflection papers on nanomedicine quality standards, ISO/TS 19337:2021 characterization frameworks, and ClinicalTrials.gov nanocarrier protocol registrations. Primary interviews engaged drug development executives at lipid nanoparticle platform holders, regulatory affairs leads navigating dual-territory dossier preparation, hospital procurement managers consolidating vendor relationships, and formulary directors evaluating theranostics total-cost-of-care metrics. Bottom-up patient population modeling triangulates against top-down pharmaceutical R&D expenditure allocation analysis.
Forecast inputs span nanocarrier versus theranostics delivery technology splits, oncology versus neurology therapy area concentration, and United States versus European regulatory cluster adoption curves. Segmentation dimensions include product type differentiation, end-user procurement authority stratification, and geographic innovation corridor funding density. CAGRs derive from regression analysis of historical NIH funding flows correlated with venture capital deployment patterns and clinical trial initiation velocities across the projection horizon. Industry-specific inputs incorporate electron microscopy characterization capacity constraints and batch-to-batch consistency enforcement trajectories.
Sensitivities concentrate around FDA-EMA regulatory divergence resolution, quantum dot biopersistence guideline finalization, and long-circulating nanoparticle pharmacovigilance database maturation. Forecasts embody assumptions regarding sustained NIH funding concentration in Boston and San Diego corridors and stable lipid supply chain configurations. Macroeconomic contraction affecting pharmaceutical R&D budgets, unilateral regulatory restriction on inorganic nanocrystal applications, or breakthrough non-nanoscale blood-brain barrier penetration technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Electromyography Devices Market
Medical Devices
Global IVF Devices Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Pedicle Screw Systems Market
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Buccal Cavity Devices Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market