
 Europe Surgical Visualization Products Market | 2026-2036
Europe Surgical Visualization Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Surgical Visualization Products Market Foresight
LED illumination is consolidating around CMOS sensor architectures across surgical camera systems, reducing heat generation and extending instrument lifespan. Karl Storz GmbH & Co. KG anchors its position through in-house optical manufacturing in Tuttlingen. Olympus Corporation competes on fluorescence imaging integration for laparoscopic platforms. Stryker differentiates via its connected operating room ecosystems that bundle visualization with surgical navigation.
Surgical visualization products encompass endoscopes, cameras, software, and display systems that transmit, process, and render intraoperative imagery to guide precision procedures, typically operating at 1080p to 4K resolution with latency below 40 milliseconds to preserve hand-eye coordination. Endoscopes retain the largest installed base across European hospitals due to decades of procedural integration, though near infrared fluorescence is gaining fastest adoption in oncologic resections where tumor margin delineation determines outcomes. Visualization software captures expanding margin pools as hospitals seek AI-assisted annotation and cloud-based archive compliance under data governance frameworks.
The EU Medical Device Regulation (MDR) and CE marking requirements administered by notified bodies in Germany, the Netherlands, and France are extending approval timelines and elevating post-market surveillance obligations for camera-controller systems classified as Class IIa and above. The EMA's coordination with national health technology assessment bodies in England and Italy is linking reimbursement to demonstrated clinical utility of augmented reality overlays in spinal and cranial procedures. Stakeholders must weigh the capital intensity of 3D visualization upgrades against the operational savings from reduced revision surgeries as HTA evidence requirements tighten.
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines for camera-controller systems while simultaneously elevating post-market surveillance obligations, forcing manufacturers to restructure clinical evidence generation and notified body engagement strategies.
Growth Catalysts
- Near infrared fluorescence imaging:Oncologic resections in Germany and France are driving fastest adoption where tumor margin delineation directly determines surgical outcomes. University hospital clusters are prioritizing capital allocation toward fluorescence-integrated laparoscopic platforms.
- CE marking pathway harmonization:Notified bodies in Germany, the Netherlands, and France are consolidating technical documentation requirements, reducing redundant conformity assessments for multi-country hospital procurement.
- AI-assisted annotation software:Cloud-based visualization platforms are capturing expanding margin pools as hospitals seek automated surgical video archiving compliant with GDPR data governance frameworks.
Market Restraints
- Optical component supply concentration:CMOS sensor and precision lens manufacturing concentrates among Asian foundries, exposing European OEMs to geopolitical supply disruptions and extended lead times.
- Capital intensity of 3D visualization upgrades:Ambulatory surgical centers face compressed ROI timelines when upgrading from 1080p to 4K resolution systems amid constrained reimbursement schedules.
- Latency threshold rigidity:The sub-40 millisecond hand-eye coordination requirement limits viable wireless transmission architectures and constrains component sourcing flexibility.
Strategic Opportunities
- Poland and Romania hospital networks:Underpenetrated public procurement channels in Eastern Europe present first-mover advantages for standardized visualization bundles before HTA evidence requirements tighten.
- Connected operating room ecosystems:Bundling visualization with surgical navigation and instrument tracking is expanding addressable spend per procedure across France's public hospital networks.
- EU AI Act compliance infrastructure:High-risk medical device classification for augmented reality overlays creates service revenue streams around algorithm validation and post-market performance monitoring.
Industry Challenges
- Clinical engineering talent scarcity:Biomedical technicians with dual competency in optical systems and cybersecurity are in short supply across German university hospital clusters, extending installation and calibration timelines.
- Legacy PACS integration complexity:DICOM interoperability gaps between new visualization software and existing hospital archive systems are forcing costly middleware development or partial system replacements.
- Notified body capacity bottlenecks:Extended MDR audit queues are delaying market entry for Class IIa camera-controller systems, compressing commercialization windows before competitive alternatives secure installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Surgical Visualization Products Market |
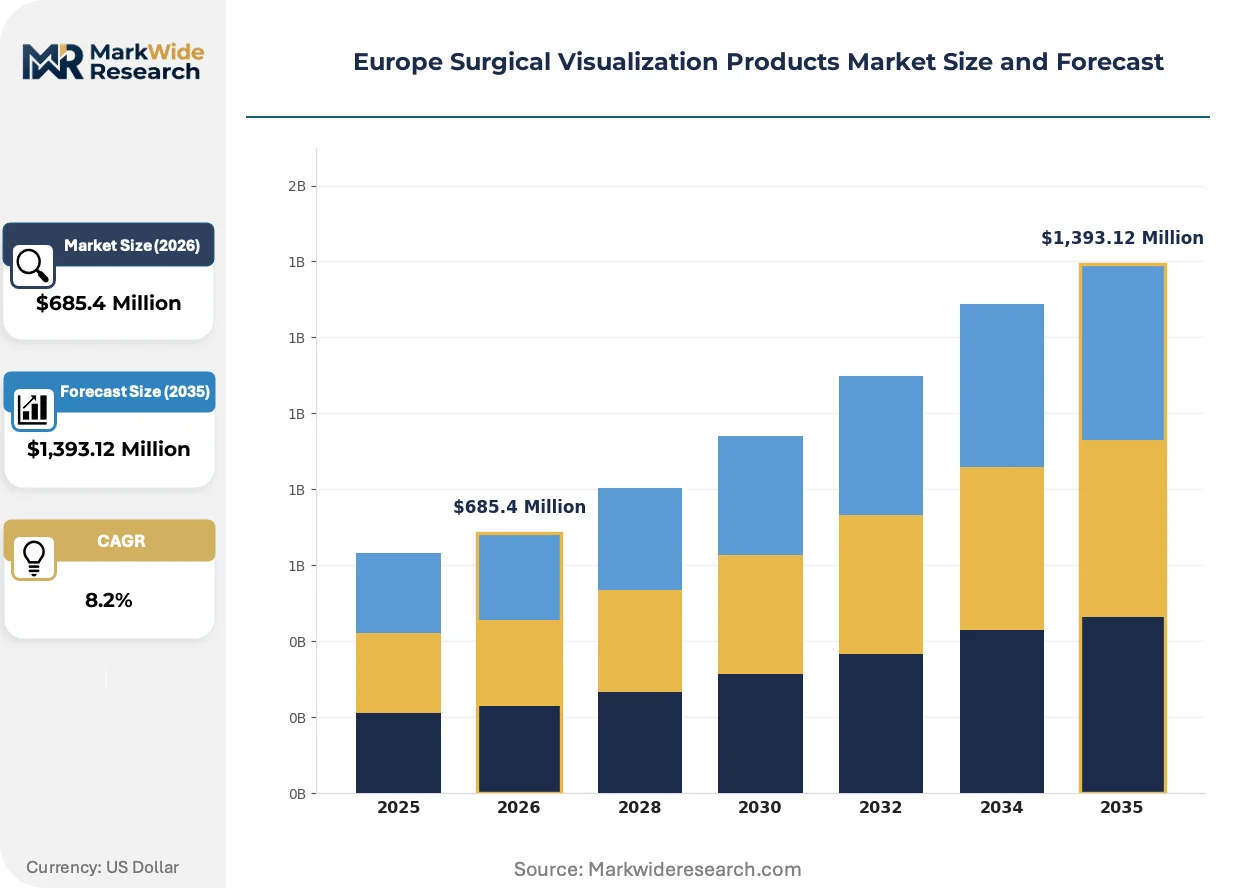
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Surgical Cameras, Visualization Software, Projection Systems Technology: 3D Visualization, Digital Imaging, Augmented Reality, Near Infrared Fluorescence Application: General Surgery, Neurosurgery, Orthopedic Surgery, Cardiothoracic Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions |
| Companies Covered | Karl Storz GmbH & Co. KG, Olympus Corporation, Stryker, Medtronic, FUJIFILM Holdings Corporation, Smith & Nephew, Carl Zeiss AG, B. Braun Melsungen AG, Koninklijke Philips N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Surgical Visualization Products Market Shifts & Advancements
CMOS sensor architectures are displacing CCD platforms across surgical camera systems, while fluorescence imaging and AI-assisted visualization are converging to redefine intraoperative decision support. Regulatory evidence requirements and procurement centralization are simultaneously reshaping competitive positioning.
Near infrared fluorescence imaging is expanding into standard-of-care protocols for oncologic and cardiovascular procedures. German university hospitals are adopting fluorescence-integrated platforms at accelerated replacement cycles compared to general surgery departments. This technology is expanding into resection margin assessment workflows previously dependent on frozen section pathology, compressing operative time and reducing revision rates.
MDR clinical evidence requirements are extending approval timelines for Class IIa and above camera-controller systems. Manufacturers must now generate prospective clinical data rather than relying on predicate equivalence, elevating development costs and favoring incumbents with established notified body relationships. Germany's BfArM coordination with health technology assessment bodies is linking reimbursement to demonstrated utility of augmented reality overlays in spinal procedures.
Hospital procurement centralization is consolidating purchasing authority from individual surgical departments to regional procurement consortiums. France's UNIOPSS and England's NHS Supply Chain are displacing decentralized capital equipment acquisition with framework agreements favoring multi-year service bundles. This shift is most visible in university hospital clusters where standardization mandates are reducing vendor fragmentation across endoscopy suites.
Europe Surgical Visualization Products Market Segmentation
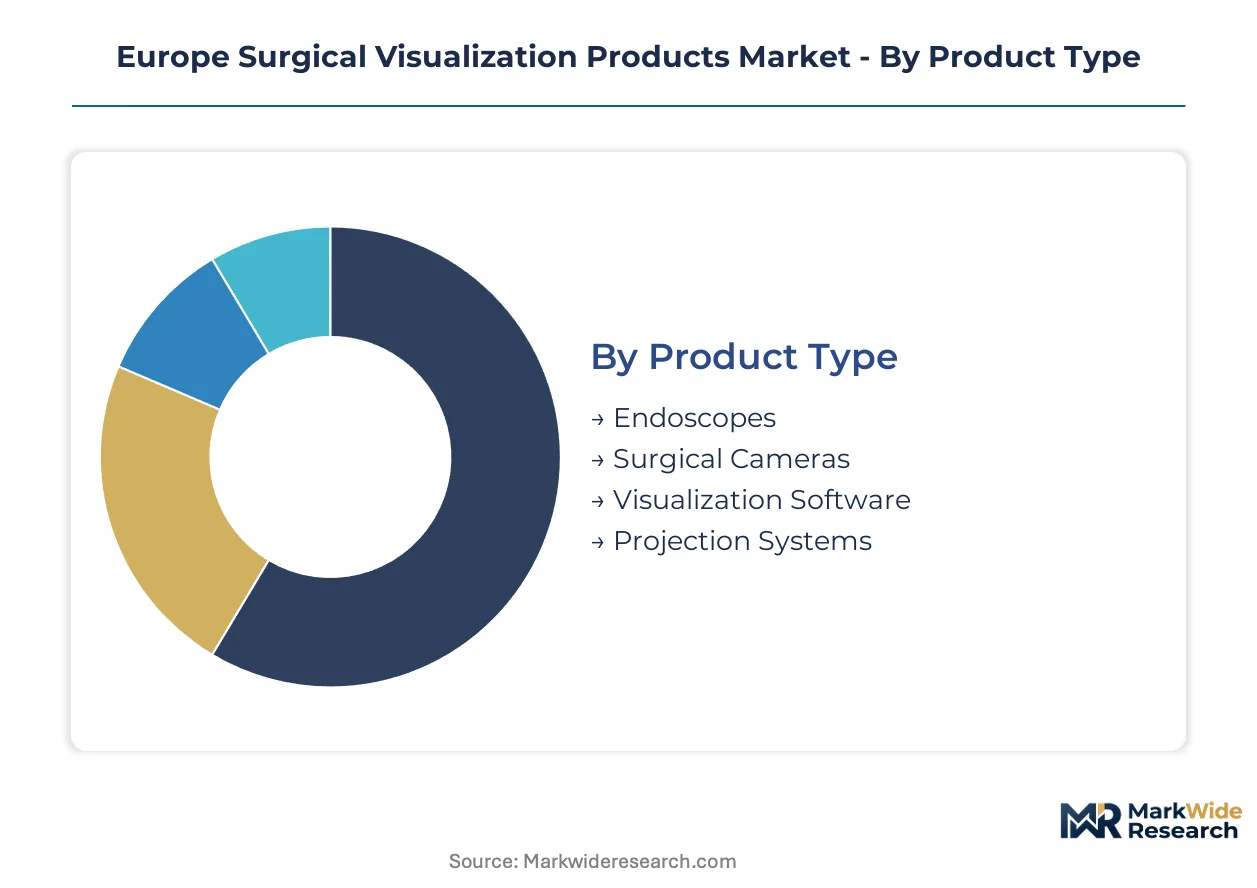
Surgical visualization markets fragment along technology maturity curves and capital intensity tiers. Product architecture choices determine integration complexity with hospital IT infrastructure. Application specialization drives reimbursement eligibility and procurement authority levels.
Product Type:
Volume concentration sits with reusable hardware platforms while premium expansion concentrates in software and disposable integration.
- Endoscopes:Rigid and flexible optical instruments with integrated light transmission channels dominate installed bases across European hospital networks. German university hospital clusters prioritize capital replacement cycles for 4K-compatible rigid systems amid MDR compliance deadlines.
- Surgical Cameras:CMOS sensor-based imaging heads operating at 1080p to 4K resolution with sub-40 millisecond latency specifications. France's public hospital networks concentrate procurement for fluorescence-integrated camera controllers under regional framework agreements.
- Visualization Software:AI-assisted annotation platforms with cloud-based archive compliance. GDPR data governance frameworks constrain vendor selection for German and Dutch hospital systems.
- Projection Systems:Large-format surgical displays and heads-up visualization for hybrid operating rooms. Ambulatory surgical centers in Poland and Romania lag adoption due to infrastructure requirements.
Mature deployment sits with Endoscopes. Newer deployment is concentrated in Visualization Software.
Technology:
Technology stratification follows clinical evidence generation timelines and HTA reimbursement linkage.
- Near Infrared Fluorescence:Intraoperative tissue perfusion and tumor margin assessment using indocyanine green contrast agents. German oncologic surgery departments in university hospital clusters drive fastest adoption where margin delineation determines resection completeness.
- 3D Visualization:Stereoscopic imaging for depth perception in laparoscopic and endoscopic procedures. England's NHS Supply Chain bundles 3D systems with surgical navigation under multi-year service contracts.
- Digital Imaging:Standard 2D capture and processing architectures with established CE marking pathways. Notified body capacity bottlenecks compress commercialization windows for novel digital platforms.
- Augmented Reality:Overlay projection of preoperative imaging onto live surgical fields. EMA coordination with HTA bodies in Italy and England links reimbursement to demonstrated utility in spinal and cranial procedures.
Digital Imaging anchors current revenue. Near Infrared Fluorescence is climbing the fastest.
Application:
Application segmentation reflects procedure reimbursement tiers and capital equipment utilization rates.
- General Surgery:Laparoscopic cholecystectomy, appendectomy, and hernia repair drive highest procedure volumes. France's UNIOPSS procurement consortium standardizes visualization bundles across public hospital networks.
- Neurosurgery:Cranial and spinal procedures requiring sub-millimeter navigation precision. Germany's BfArM links augmented reality overlay reimbursement to prospective clinical evidence in spinal fusion workflows.
- Orthopedic Surgery:Arthroscopic joint repair and replacement visualization. Ambulatory surgical centers in Germany concentrate investment in minimally invasive platforms for outpatient joint procedures.
- Cardiothoracic Surgery:Endoscopic and robotic-assisted cardiac procedures with fluorescence perfusion assessment. University hospital clusters in France and Italy lead adoption for valve repair visualization.
General Surgery captures highest unit volume. Neurosurgery commands premium pricing tiers.
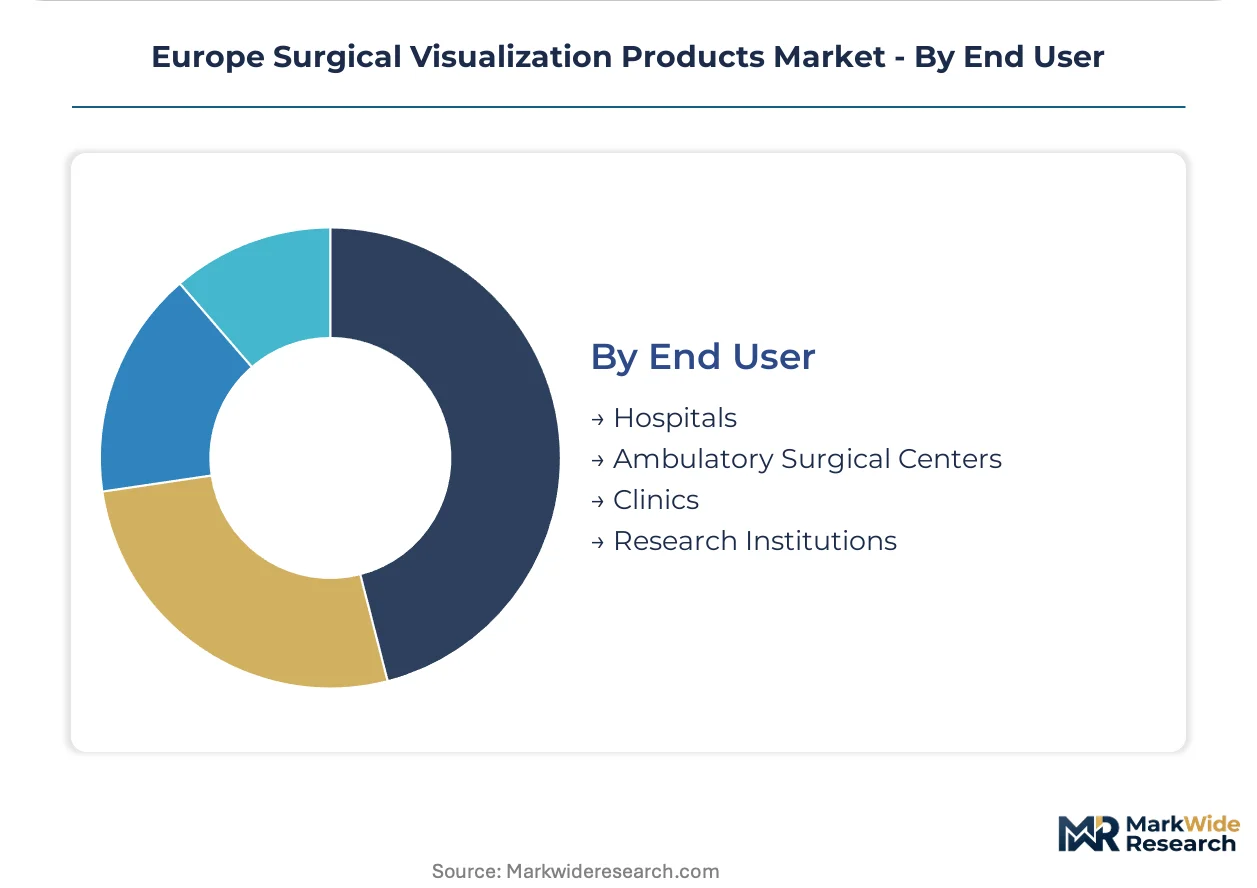
End User:
End user segmentation tracks procurement centralization and clinical engineering staffing levels.
- Hospitals:University hospital clusters and regional tertiary centers with dedicated biomedical engineering departments. Germany's hospital networks concentrate demand for connected operating room ecosystems bundling visualization with navigation.
- Ambulatory Surgical Centers:Freestanding outpatient facilities with compressed capital deployment timelines. France's expanding ASC sector prioritizes standardized 1080p platforms over 4K upgrades amid reimbursement constraints.
- Clinics:Smaller surgical facilities with limited procedure diversification. Polish and Romanian clinic networks present first-mover opportunities before HTA evidence requirements tighten.
- Research Institutions:Academic medical centers generating prospective clinical data for MDR compliance. EMA coordination with national HTA bodies elevates post-market surveillance obligations for high-risk device classifications.
Hospitals anchor current spending. Ambulatory Surgical Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University hospital clusters in Germany and France concentrate procurement authority for high-resolution visualization platforms, while Eastern European networks present expansion corridors before health technology assessment frameworks tighten.
Germany
BfArM coordinates with health technology assessment bodies to link reimbursement for augmented reality overlays to prospective clinical evidence in spinal procedures. Tuttlingen's optical manufacturing cluster anchors in-house production capabilities for endoscope supply chains. University hospital clusters in Baden-Württemberg and Bavaria drive replacement cycles for 4K-compatible rigid systems ahead of MDR compliance deadlines.
France
UNIOPSS procurement consortiums standardize visualization bundles across public hospital networks, consolidating purchasing authority from individual surgical departments. ANSM post-market surveillance obligations extend audit timelines for Class IIa camera-controller systems. The Île-de-France university hospital cluster prioritizes fluorescence-integrated laparoscopic platforms for oncologic resection workflows.
United Kingdom
NHS Supply Chain framework agreements displace decentralized capital equipment acquisition with multi-year service bundles bundling 3D visualization with surgical navigation. NICE health technology assessments link reimbursement to demonstrated utility metrics. England's regional procurement hubs concentrate demand for connected operating room ecosystems across tertiary centers.
Italy
AIFA coordination with EMA elevates post-market surveillance obligations for high-risk augmented reality classifications. Lombardy's university hospital networks generate prospective clinical data for MDR compliance in spinal fusion visualization. The Emilia-Romagna region's orthopedic surgery departments concentrate investment in minimally invasive arthroscopic platforms.
Poland
Underpenetrated public procurement channels in Warsaw and Kraków hospital networks present first-mover positioning for standardized visualization bundles. The national health fund's reimbursement schedules favor 1080p platforms over 4K upgrades in ambulatory surgical centers. Regional distribution partnerships concentrate service capabilities before EU AI Act compliance requirements phase in.
Europe Surgical Visualization Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with optical component fabricators capturing upstream margin pools while software vendors capture recurring service revenues. The vendor base concentrates around three strategic archetypes: in-house optical manufacturers with Tuttlingen-based production, integrated medtech conglomerates with navigation bundling capabilities, and imaging specialists with fluorescence platform expertise. M&A activity targets AI-assisted annotation software assets, while strategic partnerships address DICOM interoperability gaps with legacy PACS infrastructure.
Among Germany-based optical manufacturers, Karl Storz GmbH & Co. KG anchors the in-house fabrication archetype through its Tuttlingen production cluster. Olympus Corporation exemplifies the imaging specialist position with fluorescence integration capabilities. Stryker occupies a position within the integrated ecosystem tier, bundling visualization with surgical navigation platforms. These three entities represent distinct competitive vectors without implying specific market share claims or strategic actions beyond their observable structural positioning.
| Leading Market Players |
|---|
| Karl Storz GmbH & Co. KG |
| Olympus Corporation |
| Stryker |
| Medtronic |
| FUJIFILM Holdings Corporation |
| Smith & Nephew |
| Carl Zeiss AG |
| B. Braun Melsungen AG |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
CMOS sensor certification tiers bifurcate procurement economics across European hospital networks, with CE-marked Class IIa controllers commanding premium positioning against uncertified components while Asian foundry concentration in precision optics compresses margin structures at both ends. This divergence manifests in procurement negotiations where German university hospital clusters absorb 4K fluorescence-integrated premiums while Polish ambulatory surgical centers face extended lead times for standardized 1080p bundles.
Pricing Analysis
Volume concentration in 1080p digital imaging platforms sustains transactional per-unit pricing, while fluorescence-integrated 4K systems capture margin expansion through multi-year service bundling under France's UNIOPSS framework agreements. Price differentiation hinges on MDR compliance tier and regional procurement authority, with centralized hospital consortiums extracting volume discounts that independent surgical departments cannot match. Cost compression in standard digital tiers intensifies as Asian CMOS suppliers extend capacity, though latency-certified components for hand-eye coordination preserve pricing power in neurosurgical applications. Ambulatory surgical centers exhibit highest price sensitivity due to compressed reimbursement schedules, while German university hospital clusters prioritize clinical evidence linkage over upfront capital outlay.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany operate hub-and-spoke patterns serving hospital networks across Northern Europe, with Tuttlingen-based optical fabricators anchoring captive production for rigid endoscope assemblies. CMOS sensor supply concentrates in Taiwan, South Korea, and Japan, while precision lens grinding draws from German and Swiss optical clusters. Single-source vulnerability in indocyanine green contrast agent supply exposes fluorescence platform manufacturers to pharmaceutical regulatory bottlenecks. Distribution runs through authorized dealer networks with embedded biomedical engineering capabilities, particularly critical for MDR-mandated installation validation and post-market surveillance compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints for Class IIa camera-controller MDR audits prop pricing power for incumbents with established conformity assessment relationships, creating a supply-constrained entry barrier that compresses commercialization windows for unvalidated alternatives.
For Market Incumbents: To counter emerging AI-assisted annotation software entrants, deepen backward integration into CMOS sensor qualification pipelines and expand captive service engineering headcount across German university hospital clusters. Prioritize notified body relationship maintenance as audit queue delays extend competitive moats. For New Entrants and Emerging Players: Begin with underpenetrated Polish and Romanian public procurement channels where HTA evidence requirements remain less stringent than Western European frameworks. Target standardized 1080p visualization bundles for ambulatory surgical centers, leveraging regional distribution partnerships to establish service credibility before EU AI Act compliance phases tighten. For Investors and Strategic Acquirers: Re-rating potential sits with AI-assisted surgical video annotation platforms given GDPR-compliant cloud infrastructure requirements and recurring revenue visibility under multi-year hospital archive contracts. Long-term viability favors targets with demonstrated MDR technical documentation capabilities and existing notified body engagement. Monitor EMA coordination with national HTA bodies as the inflection signal for augmented reality overlay reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Consolidation | Harmonized technical documentation across German, Dutch, and French notified bodies reduces redundant conformity costs. |
| Hospital System Partnership | Multi-year service bundling under France's UNIOPSS framework agreements locks in replacement cycle visibility. |
| Software Companion Development | AI-assisted annotation platforms capture recurring revenue under GDPR-compliant cloud archive mandates. |
| Backward Integration into Optics | Tuttlingen-based captive production insulates against Asian foundry lead time volatility for precision lenses. |
| Reimbursement Strategy | BfArM-linked HTA evidence generation for augmented reality overlays in spinal procedures unlocks premium pricing tiers. |
Research Methodology
Multi-period observation of MDR approval timelines, hospital procurement contract structures, and fluorescence platform adoption rates anchored the trend analysis, supplemented by interviews with biomedical engineering directors, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at notified bodies. Secondary validation drew from EMA device registration databases, national HTA body reimbursement determinations, hospital procurement consortium framework agreements, and CE marking technical documentation filings. Bottom-up installed base modeling triangulated against top-down expenditure flows from national health accounts.
Segment-weighting across product architecture tiers, technology maturity curves, application reimbursement eligibility, and end-user procurement centralization levels structured the analytical framework throughout the forecast period. CAGRs derived from procedure volume elasticity to visualization upgrade cycles and capital equipment replacement patterns modeled under MDR compliance deadline scenarios. Forecast inputs incorporated notified body capacity constraints and EU AI Act implementation phasing for high-risk medical device classifications.
Underlying measurement precision varies by segment; mature digital imaging platforms carry tighter precision than emerging augmented reality applications where clinical evidence generation remains sparse. Forecasts reflect assumptions around MDR audit queue resolution, HTA body coordination timelines, and CMOS sensor supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
Medical Bionic Implant Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Global Brain Monitoring Devices Market
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Sleep Apnea Implants Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Controlled-Release Drug Delivery Technology Market