
 Global Automated Biochemical Analyzer Market | 2026-2036
Global Automated Biochemical Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Biochemical Analyzer Market Foresight
China's expanding in-vitro diagnostics manufacturing corridor is reconfiguring supply patterns for automated biochemical analyzers across Asia. Roche Diagnostics leverages integrated reagent-instrument systems to sustain premium positioning in high-throughput hospital labs. Siemens Healthineers anchors European demand through advanced photometric platforms, while Mindray competes aggressively on cost-engineered systems for mid-tier clinical settings.
An automated biochemical analyzer is a laboratory instrument that performs quantitative chemical analysis of biological samples—serum, plasma, urine, or cerebrospinal fluid—using photometric, electrochemical, or turbidimetric detection methods with throughput rates from 200 to over 2,000 tests per hour. Its primary purpose is to deliver rapid, reproducible diagnostic data for disease monitoring, therapeutic drug monitoring, and metabolic assessment in clinical and research environments. Discrete analyzers dominate installed bases due to their flexibility in handling heterogeneous test menus without cross-contamination between samples. Fluorescence and nephelometric technologies capture expanding margin pools in specialized immunochemistry and protein quantification segments where sensitivity requirements exceed standard photometric capabilities.
The FDA's Clinical Laboratory Improvement Amendments and the EU's In-Vitro Diagnostic Regulation impose escalating analytical performance and traceability standards that filter market access toward validated platform manufacturers. China's NMPA accelerates domestic approval pathways for locally produced systems, redirecting procurement flows within its hospital tiering system. Japan's PMDA maintains stringent post-market surveillance requirements that sustain replacement cycles among installed bases. Stakeholders must monitor divergence between harmonized international standards and jurisdiction-specific compliance architectures as they allocate R&D and registration resources.
Market Dynamics
Hospital consolidation across China's tiered healthcare system is compressing procurement timelines and favoring vendors with integrated reagent-instrument platforms capable of serving centralized laboratory networks.
Growth Catalysts
- CLIA Precision Mandates:The FDA's strengthening of Clinical Laboratory Improvement Amendments compels manufacturers to invest in higher analytical precision standards, filtering out non-validated competitors.
- Discrete Analyzer Flexibility:Photometric discrete systems dominate installed bases by eliminating cross-contamination between heterogeneous test menus, supporting multi-assay workflows in high-volume settings.
- Japan:PMDA's stringent post-market surveillance requirements sustain replacement cycles among legacy installed bases, generating predictable hardware refresh demand.
Market Restraints
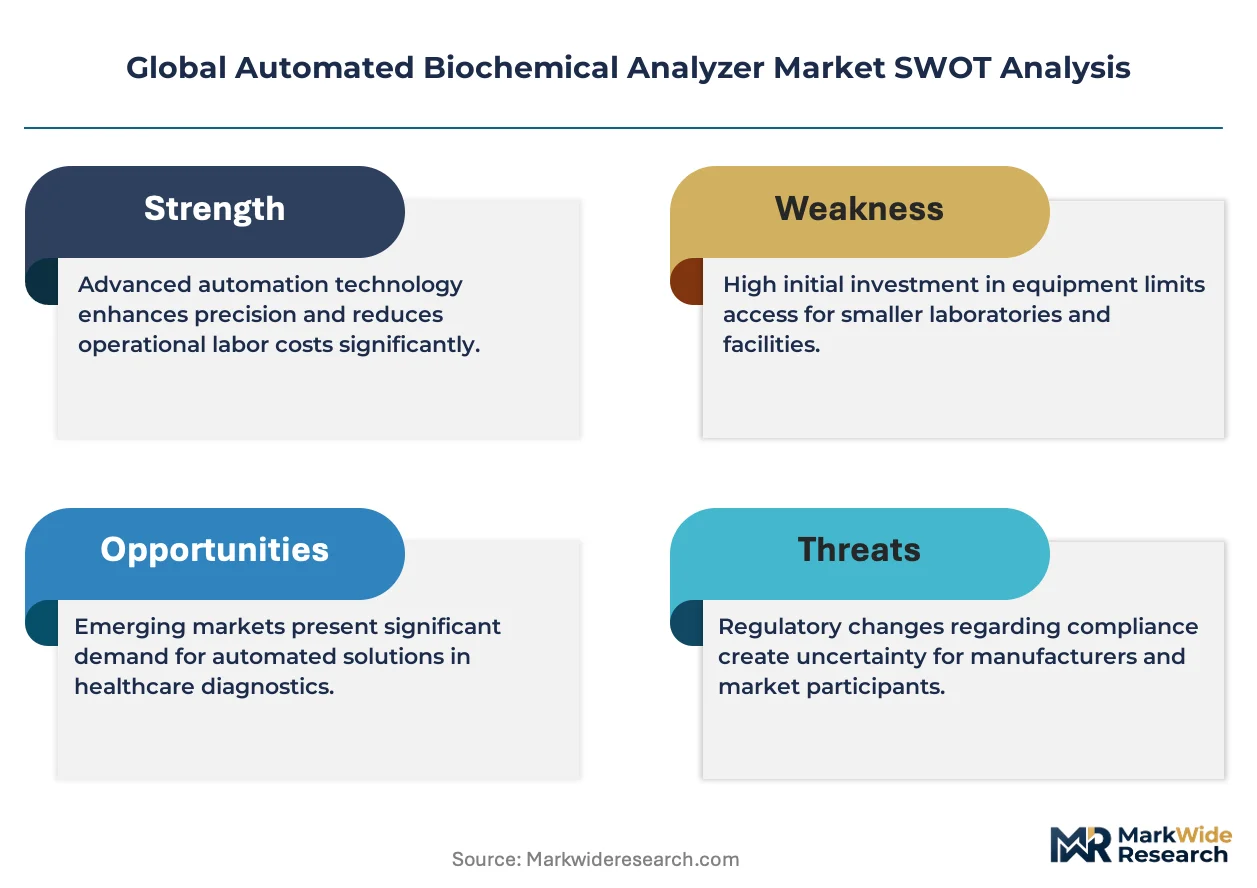
- Optical Component Concentration:Specialized photodetectors and monochromator assemblies concentrate among German and Japanese precision optics suppliers, exposing lead times to single-source dependencies.
- IVDR Compliance Burden:The EU's In-Vitro Diagnostic Regulation imposes escalating traceability and performance documentation requirements that extend registration timelines for non-European manufacturers.
- Fluorescence System Cost Floors:Sensitivity requirements for immunochemistry and protein quantification segments exceed standard photometric capabilities, locking mid-tier clinical settings out of specialized margin pools.
Strategic Opportunities
- India's Diagnostic Laboratory Expansion:Private diagnostic chains and hospital networks are scaling automated workflows to manage rising test volumes, creating entry points for cost-engineered platform vendors.
- Reagent-Instrument Integration:Closed-system architectures that lock consumables to hardware platforms enable recurring revenue streams and defend margin positions against standalone instrument competitors.
- NMPA Domestic Pathways:China's accelerated approval pathways for locally produced systems redirect procurement flows within its hospital tiering system, rewarding manufacturing footprint investments.
Industry Challenges
- Field Service Engineering Scarcity:Photometric calibration, electrochemical sensor maintenance, and software diagnostics require specialized technicians that concentrate in urban hospital clusters, leaving tier-2 and tier-3 facilities underserved.
- Legacy System Integration:Hospital information system interoperability with installed analyzer fleets demands customized middleware development, extending deployment timelines and inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Biochemical Analyzer Market |
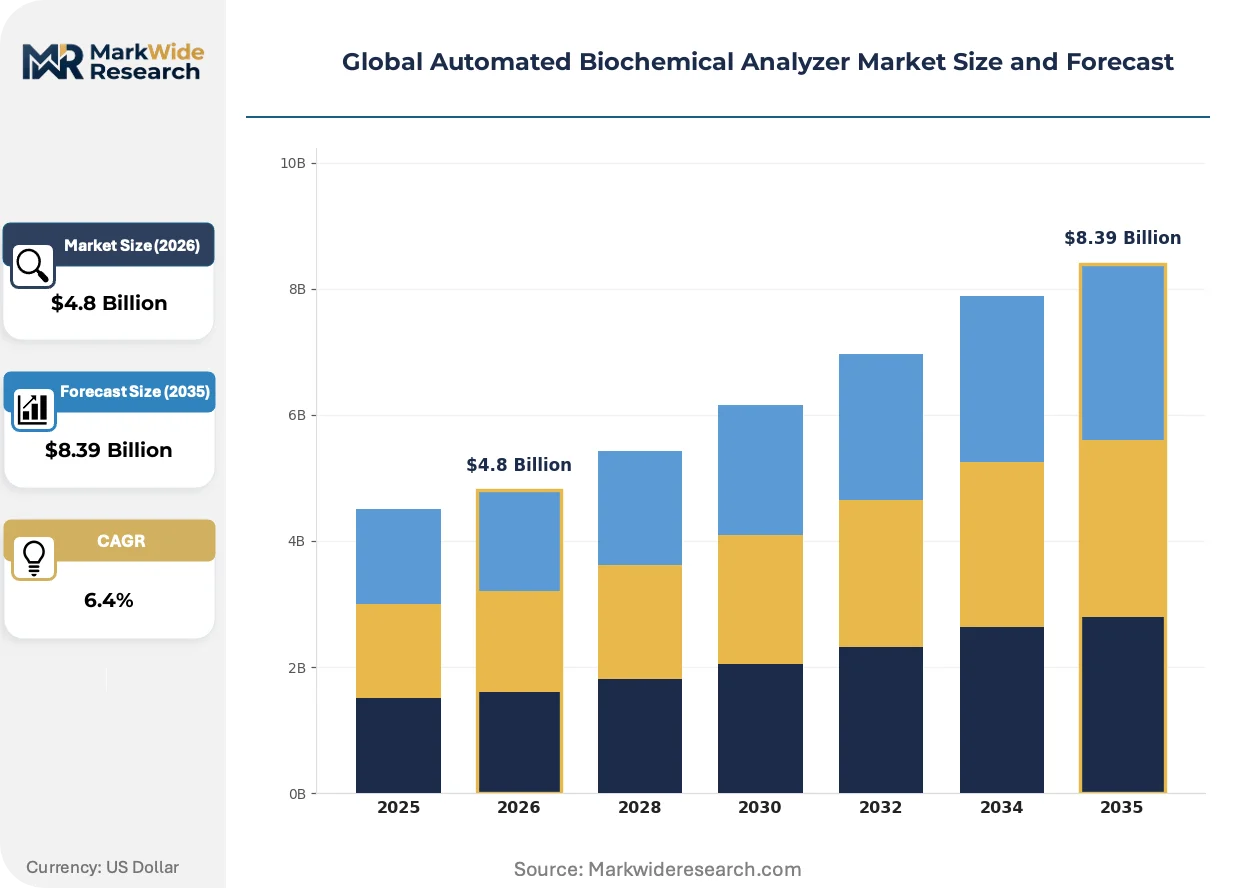
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Discrete, Continuous Flow, Semi-automated, Random Access Technology: Photometric, Electrochemical, Fluorescence, Turbidimetric, Nephelometric Application: Clinical Chemistry, Drug Discovery, Food Testing, Environmental Analysis End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Academic Centers |
| Companies Covered | Roche Diagnostics, Siemens Healthineers, Abbott Laboratories, Beckman Coulter, Mindray, Ortho Clinical Diagnostics, Danaher Corporation, Thermo Fisher Scientific, Transasia Bio-Medicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Biochemical Analyzer Market Shifts & Advancements
Detection modality convergence and regulatory harmonization pressures are compressing competitive differentiation around analytical precision, throughput scalability, and reagent-instrument integration depth.
Fluorescence and nephelometric detection systems are hybridizing with discrete analyzer architectures to capture specialized immunochemistry and protein quantification segments. Mid-tier hospital laboratories in China and South Korea are adopting these hybrid platforms at accelerating pace to access sensitivity thresholds previously restricted to reference laboratories. This convergence is compressing the historical segmentation between general chemistry and specialized immunoassay hardware categories.
The EU's In-Vitro Diagnostic Regulation is mandating expanded clinical evidence and post-market performance monitoring for all analyzer classes. Manufacturers must now maintain quality management systems that satisfy both MDR technical documentation requirements and ISO 15189 laboratory accreditation standards. European reference laboratories and university hospital networks are responding by consolidating procurement around vendors with established IVDR technical files and notified body certifications.
Centralized laboratory networks are unbundling after-sales service contracts from hardware procurement, instead negotiating performance-based maintenance agreements with specialized third-party service providers. This disintermediation is compressing OEM service margins and redirecting technical training investments toward independent service organizations. The pattern is most visible across China's provincial hospital consolidation initiatives, where centralized procurement offices negotiate multi-site service agreements separate from instrument acquisition.
Global Automated Biochemical Analyzer Market Segmentation
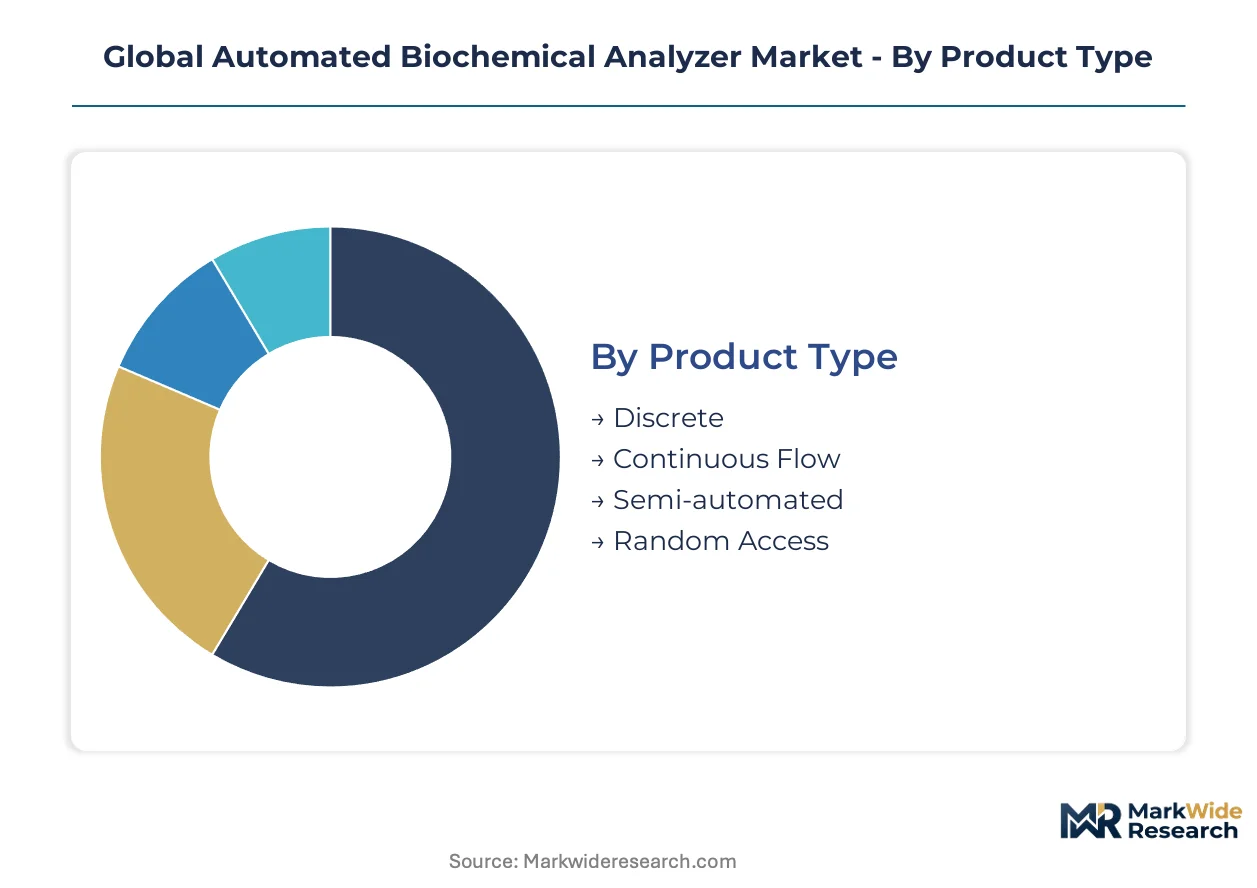
Automated biochemical analyzers segment across multiple technical and commercial dimensions that dictate procurement patterns, service intensity, and margin architecture. Understanding how product configurations, detection technologies, and end-use requirements intersect reveals where vendors must concentrate engineering resources and field support investments.
Product Type:
After-sales service intensity varies sharply across analyzer architectures, with discrete and random access systems demanding specialized calibration protocols while continuous flow platforms require dedicated reagent supply chain integration.
- Discrete:Self-contained reaction vessels eliminate cross-contamination between heterogeneous assays, supporting multi-test menus in high-throughput hospital laboratories. China's tier-2 and tier-3 hospitals favor these systems for flexibility in liver function, renal panel, and lipid profile combinations without batch reconfiguration.
- Random Access:Prioritizes urgent sample processing through non-sequential loading, critical for emergency departments and STAT laboratories. Demand concentrates in Japan's university hospital networks where PMDA-mandated turnaround times for critical care chemistry drive premium positioning.
- Continuous Flow:Legacy architecture suited for high-volume homogeneous test batches with lower per-test reagent costs. Remains entrenched in India's cost-sensitive public health reference laboratories.
- Semi-automated:Manual sample handling with automated detection reduces capital outlay for small diagnostic chains. South Korea's emerging private laboratory sector adopts these for entry-level chemistry panels.
Discrete analyzers hold the largest share; momentum sits with random access configurations.
Technology:
Detection modality selection determines reagent compatibility, sensitivity thresholds, and the depth of technical training required for field service engineers.
- Photometric:Dominant detection method using absorbance measurement across ultraviolet-visible spectra for enzyme and substrate quantification. Germany's reference laboratories specify these for standardized liver and cardiac marker panels under IVDR traceability requirements.
- Fluorescence:Enables picomolar sensitivity for immunochemistry and hormone assays through labeled antibody detection. China's NMPA-fast-tracked domestic systems are capturing mid-tier hospital demand for thyroid and fertility panels.
- Electrochemical:Ion-selective electrodes measure electrolytes and blood gases with minimal sample volume. Concentrated in Brazil's ANVISA-regulated intensive care unit deployments.
- Turbidimetric:Light scattering quantifies protein aggregates and immune complexes. Australia's TGA-accredited pathology networks specify these for coagulation and inflammatory marker workflows.
- Nephelometric:Forward-scatter detection achieves lower detection limits for specific proteins and immunoglobulins. Switzerland's university hospitals deploy these for specialized immunodeficiency diagnostics.
Photometric systems anchor installed bases; fluorescence platforms are climbing the fastest.
Application:
Application segmentation maps directly to regulatory pathway complexity and the documentation burden for analytical validation.
- Clinical Chemistry:Routine diagnostic testing for metabolic, renal, hepatic, and cardiac function constitutes the core revenue pool. FDA CLIA-mandated proficiency testing drives replacement demand in US hospital networks.
- Drug Discovery:High-content screening and pharmacokinetic analysis require customizable assay protocols. Contract research organizations in Singapore and the Netherlands specify open-architecture platforms.
- Food Testing:Mycotoxin, additive, and nutritional label verification applications. China's SAMR enforcement of GB standards accelerates domestic analyzer procurement for dairy and meat safety laboratories.
- Environmental Analysis:Water quality and toxicology screening with extended detection ranges. South Africa's national water quality monitoring program generates demand for portable electrochemical configurations.
Clinical chemistry commands the dominant revenue position; drug discovery applications are gaining share fastest.
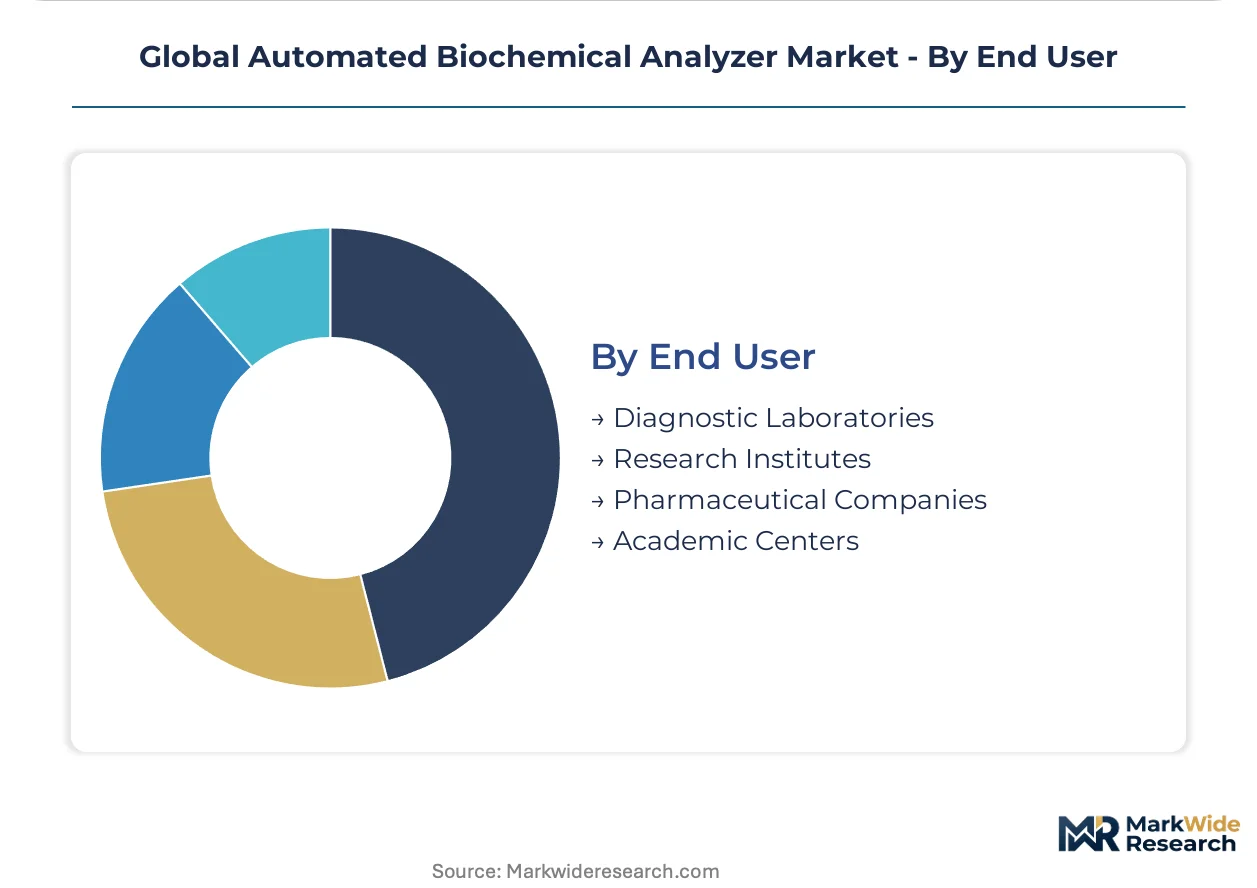
End User:
End-user category determines procurement authority structure, with diagnostic laboratories centralizing decisions while academic centers fragment across principal investigator preferences.
- Diagnostic Laboratories:High-volume commercial and hospital-affiliated testing facilities with standardized assay menus. India's Metropolis and Dr. Lal PathLabs chains are consolidating procurement for automated chemistry platforms.
- Pharmaceutical Companies:Quality control and clinical trial support with stringent audit trail requirements. FDA 21 CFR Part 11 compliance filters vendor selection in US-based manufacturing sites.
- Research Institutes:Method development and novel biomarker validation with flexible protocol requirements. France's INSERM network prioritizes modular platforms for proteomics integration.
- Academic Centers:Teaching and research with budget constraints and diverse user skill levels. Tier-3 Chinese medical universities favor cost-engineered systems with simplified maintenance protocols.
Diagnostic laboratories represent the largest installed base; pharmaceutical company procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese precision optics suppliers concentrate critical photodetector and monochromator assembly production, exposing lead times to single-source dependencies while diagnostic laboratory networks across multiple jurisdictions scale automated workflows.
United States
Hospital consolidation and reference laboratory network expansion drive centralized procurement of high-throughput systems. FDA's Clinical Laboratory Improvement Amendments mandate analytical precision standards that filter vendor selection toward validated platform manufacturers. The Research Triangle and Greater Boston clusters concentrate contract research organization demand for open-architecture drug discovery platforms.
Germany
Reference laboratories and university hospital networks specify photometric systems for standardized liver and cardiac marker panels under IVDR traceability requirements. The EU's In-Vitro Diagnostic Regulation imposes escalating documentation burdens that extend registration timelines for non-European manufacturers. Bavaria's medical technology corridor anchors metrology and precision optics supply chains serving analyzer assembly operations.
China
Hospital tiering system consolidation compresses procurement timelines and favors vendors with integrated reagent-instrument platforms for centralized laboratory networks. NMPA accelerates domestic approval pathways for locally produced systems, redirecting procurement flows toward domestic manufacturing footprints. The Yangtze River Delta in-vitro diagnostics manufacturing corridor reconfigures supply patterns across Asia-Pacific.
Japan
PMDA's stringent post-market surveillance requirements sustain replacement cycles among legacy installed bases, generating predictable hardware refresh demand. University hospital networks prioritize random access configurations to meet mandated turnaround times for critical care chemistry. The Kanto region's dense hospital clustering concentrates field service engineering capacity and technical training infrastructure.
India
Private diagnostic chains and hospital networks scale automated workflows to manage rising test volumes, creating entry points for cost-engineered platform vendors. Metropolis and Dr. Lal PathLabs chains consolidate procurement for automated chemistry platforms. Maharashtra and Karnataka's emerging private laboratory sector adopts semi-automated systems for entry-level chemistry panels.
Global Automated Biochemical Analyzer Market Competitive Landscape
Integrated-system specialists and cost-engineered platform vendors split the market between premium reagent-instrument bundles and accessible mid-tier configurations. Market structure tilts toward consolidation around manufacturers with established regulatory technical files and notified body certifications. Three archetypes dominate: multinational conglomerates with closed-system architectures, regional cost-optimized challengers, and specialized fluorescence platform innovators. Competitive moves concentrate on reagent-instrument integration depth and third-party service contract disintermediation.
Among multinational conglomerates, Roche Diagnostics and Siemens Healthineers exemplify integrated-system positioning through premium reagent-instrument bundles serving high-throughput hospital laboratories. Mindray occupies a position within the cost-engineered tier, representing regional challenger archetypes targeting mid-tier clinical settings with accessible platform economics. These three anchors illustrate the competitive tension between closed-system recurring revenue models and standalone instrument flexibility.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Siemens Healthineers |
| Abbott Laboratories |
| Beckman Coulter |
| Mindray |
| Ortho Clinical Diagnostics |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Transasia Bio-Medicals |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese precision optics suppliers determines both pricing tier spreads and supply chain shape for photodetector and monochromator assemblies. Tariff exposure between these manufacturing nodes and final assembly locations in China and the United States compresses margin buffers for mid-tier platform vendors while amplifying premium positioning for integrated-system specialists with captive component stocks.
Pricing Analysis
IVDR compliance dictates the pricing tier structure across European procurement, separating CE-marked premium systems from economy-tier configurations lacking notified body certification. Three-tier pricing structure across premium, standard, and economy levels reflects analytical precision grades, throughput scalability, and after-sales service bundling depth. Cost compression in economy tiers intensifies because Chinese domestic manufacturers exploit NMPA-fast-tracked pathways to undercut imported platforms. Diagnostic laboratories in India's private chains exhibit highest price sensitivity, while Japan's university hospital networks show lowest sensitivity due to PMDA-mandated performance thresholds.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for photometric analyzer assembly. Critical component production concentrates in Germany, Japan, and South Korea for precision optics, electrochemical sensors, and fluorescence detection modules. Raw material dependencies span rare-earth phosphors for fluorescence systems, borosilicate glass for reaction vessels, and ion-selective electrode membranes. Single-source vulnerability persists for specialized photodetectors from Bavaria's optics corridor. Distribution runs through centralized procurement offices of China's provincial hospital networks and India's diagnostic chain headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics now exceed hardware growth across automated biochemical analyzer markets, with performance-based maintenance agreements and reagent-instrument integration capturing recurring revenue pools that hardware procurement alone cannot match.
For Market Incumbents: Pre-empt third-party service disintermediation by consolidating field engineering capacity around China's tier-2 hospital clusters before independent service organizations capture multi-site maintenance contracts. Deepen reagent-instrument integration through closed-system architectures that lock consumables to hardware platforms, defending margin positions against standalone instrument competitors exploiting NMPA domestic pathways. Vertical integration into precision optics assembly reduces exposure to German and Japanese supplier lead times. For New Entrants and Emerging Players: Build out cost-engineered fluorescence platforms for China's mid-tier hospitals seeking sensitivity thresholds previously restricted to reference laboratories, exploiting the fastest-climbing technology segment. Target India's diagnostic laboratory expansion through semi-automated entry-level configurations that match Metropolis and Dr. Lal PathLabs consolidation timelines. Pursue reagent rental models that convert capital expenditure barriers into operational expenditure acceptance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors manufacturers with established IVDR technical files and notified body certifications as procurement filters tighten. Long-term viability over the next decade rests on regulatory dossier depth rather than hardware innovation velocity. Acquisition target archetype: regional challengers with NMPA approvals and Yangtze River Delta manufacturing footprints. Monitor divergence between harmonized international standards and jurisdiction-specific compliance architectures as the inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent-Instrument Integration | Closed-system architectures lock consumables to hardware, defending margins against standalone competitors in China's tiered hospitals. |
| IVDR Technical File Investment | Notified body certification opens European reference laboratory procurement currently filtering toward validated platform manufacturers. |
| Field Service Engineering Expansion | Technical training infrastructure in tier-2 and tier-3 geographies preempts third-party service disintermediation. |
| NMPA Manufacturing Footprint | Domestic production accelerates approval pathways and redirects procurement flows within China's hospital tiering system. |
| Fluorescence Platform Development | Hybrid detection systems capture mid-tier hospital demand for immunochemistry sensitivity exceeding photometric capabilities. |
Research Methodology
A standing panel of hospital laboratory directors, biomedical engineers, GPO contracts managers, and aftermarket service heads provided ongoing calibration against operating reality throughout this study. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, NMPA registration databases, hospital procurement records, and EU notified body certification lists. Bottom-up instrument shipment tracking and top-down diagnostic laboratory spending analysis triangulated market sizing across the analysis window.
Scenario bracketing anchored the analytical framework, modeling demand trajectories under varying CLIA precision mandate enforcement intensities and NMPA domestic preference policy shifts. Segmentation dimensions included product architecture, detection technology, application category, and end-user procurement authority structure. CAGRs derived from installed base replacement cycles, test volume growth, and reagent consumption intensity across the projection horizon. Forecast inputs incorporated PMDA-mandated turnaround times, IVDR documentation burden timelines, and field service engineer concentration patterns.
Practitioners should monitor regulatory divergence between harmonized international standards and jurisdiction-specific compliance architectures for early signals of market access constraint or expansion. Forecasts reflect assumptions regarding continued hospital consolidation in China, sustained IVDR enforcement rigor, and stable precision optics supply from established German and Japanese corridors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Bioprocess Containers and Fluid Transfer Solutions Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Global Recombinant Cell Culture Supplements Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Global Biological Microscope Objectives Market