
 Automated Cell Biology Systems Market | 2026-2036
Automated Cell Biology Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Cell Biology Systems Market Outlook
A shortage of trained cell culture technicians is redrawing competitive boundaries in life sciences instrumentation. Thermo Fisher Scientific leverages its integrated workflow portfolio to capture multi-product contracts with large biopharma customers. Danaher Corporation anchors its position through Beckman Coulter's installed base in flow cytometry and particle counting. Sartorius AG specializes in single-use bioreactor systems that reduce cross-contamination risk in automated cell culture.
Automated cell biology systems comprise electromechanical platforms that execute cell-based assays with minimal human intervention, typically achieving throughput rates of hundreds to thousands of samples per day. These systems integrate liquid handling, environmental control, and detection modules to maintain physiological conditions while performing serial manipulations for drug screening and therapeutic development. Automated cell culture systems command the largest revenue share among product types, reflecting biopharma's push toward continuous manufacturing paradigms. Cell therapy applications represent the fastest-expanding segment, driven by CAR-T process development and commercial manufacturing scale-up requirements. Pharmaceutical companies constitute the dominant end-user category, though academic institutions maintain outsized influence on early technology validation.
FDA 21 CFR Part 11 and EMA GMP Annex 15 guidelines shape equipment qualification protocols and data integrity requirements across automated cell biology platforms. ISO 13485 quality management standards govern design controls for systems deployed in diagnostic and therapeutic manufacturing environments. Stakeholders must evaluate regulatory divergence between US and European validation frameworks when configuring global instrument deployment strategies.
Market Dynamics
Continuous manufacturing mandates from FDA and EMA are compressing batch cycle times and forcing biopharma manufacturers to replace manual cell culture with integrated automation platforms. This regulatory pressure is restructuring capital allocation toward closed-system architectures.
Growth Catalysts
- CAR-T Commercial Scale-Up:Cell therapy manufacturers in the United States require high-throughput automated culture systems to meet commercial batch volumes for autologous treatments.
- EMA GMP Annex 15:European qualification requirements for computerized systems are accelerating replacement of legacy manual equipment with validated automated platforms.
- Single-Use Technology Maturation:Pre-sterilized, disposable bioreactor components eliminate cleaning validation burdens and reduce facility turnaround times.
Market Restraints
- Capital Intensity:Fully integrated automated cell culture suites require seven-figure upfront investment, limiting deployment to large biopharma and excluding mid-tier contract manufacturers.
- Consumables Supply Concentration:Single-use bags, sensors, and tubing assemblies concentrate production among a handful of European and North American suppliers, creating vulnerability to resin shortages.
- Interoperability Limitations:Proprietary data formats from competing instrument vendors prevent seamless integration of best-of-breed modules into unified workflows.
Strategic Opportunities
- India Biopharma Expansion:CDSCO's streamlined biosimilar approval pathways and PLI scheme incentives are attracting automated cell culture investment to Hyderabad and Bengaluru manufacturing clusters.
- Gene Therapy Vector Production:AAV and lentiviral vector manufacturing for in vivo gene therapies represents an emerging application with distinct automation requirements from cell therapy.
- Cloud-Native Platform Convergence:Integration of automated hardware with AI-driven process analytics enables real-time release and predictive maintenance capabilities.
Industry Challenges
- Specialized Technician Scarcity:Cross-trained professionals capable of operating electromechanical platforms while interpreting cell biology data remain in short supply across Boston, San Diego, and Basel clusters.
- Validation Timeline Compression:FDA 21 CFR Part 11 compliance documentation for custom automated workflows extends qualification periods by 12-18 months versus standard equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Cell Biology Systems Market |
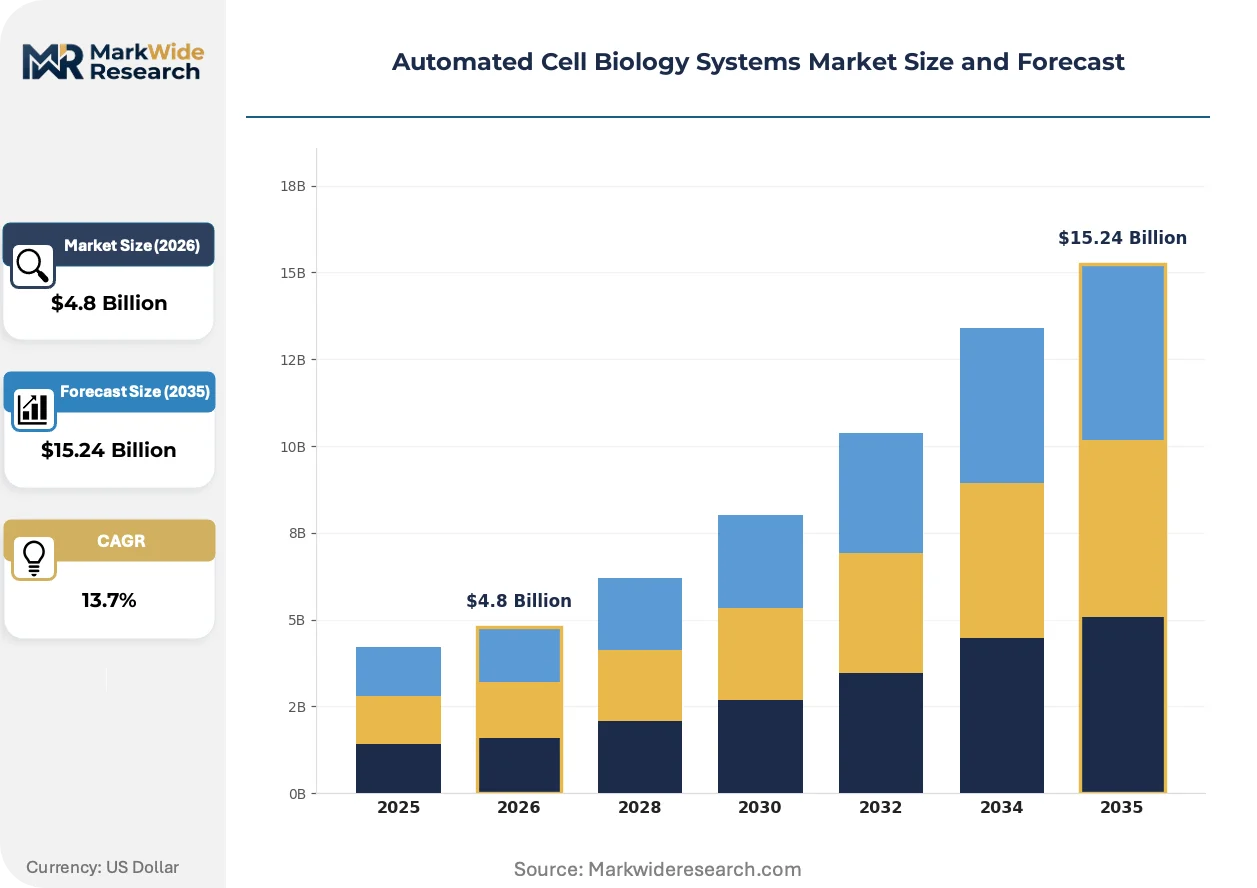
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometers, Cell Counters, Automated Cell Culture Systems, Microplate Readers Technology: Fluorescence Microscopy, Optical Tweezers, Digital Imaging, Nanoparticles Application: Drug Discovery, Disease Diagnosis, Genetic Research, Cell Therapy End User: Pharmaceutical Companies, Academic Institutions, Research Labs, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, Corning Incorporated, Merck KGaA, Danaher Corporation, Sartorius AG, Agilent Technologies, PerkinElmer, Lonza, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Cell Biology Systems Market Strategic Shifts
Process analytical technology integration and modular hardware architectures are displacing monolithic legacy systems. Vendors now compete on software ecosystem openness and data lineage capabilities rather than throughput specifications alone.
Perfusion-based automated bioreactor control is bifurcating the cell culture market between fed-batch adherents and continuous processing adopters. Gene therapy CDMOs in the United States are deploying perfusion platforms at pilot scale to demonstrate productivity gains for investor-backed scale-up decisions. This technology is compressing facility footprints and enabling flexible multi-product manufacturing within single cleanroom suites.
EMA's forthcoming revision to Annex 1 on sterile manufacturing will mandate enhanced environmental monitoring integration with automated cell culture enclosures. Manufacturers must retrofit existing platforms with continuous viable particle detection or face facility requalification delays. Cell therapy cleanrooms in Ireland and the Netherlands are piloting integrated environmental control systems ahead of enforcement deadlines.
Biopharma procurement teams are unbundling after-sales service contracts from capital equipment purchases and negotiating multi-vendor maintenance agreements. This behavior disrupts traditional single-source service revenue models and forces instrument vendors to certify third-party technicians. The shift is most visible among top-20 pharmaceutical companies with centralized global procurement functions in New Jersey and Basel.
Automated Cell Biology Systems Market Segmentation
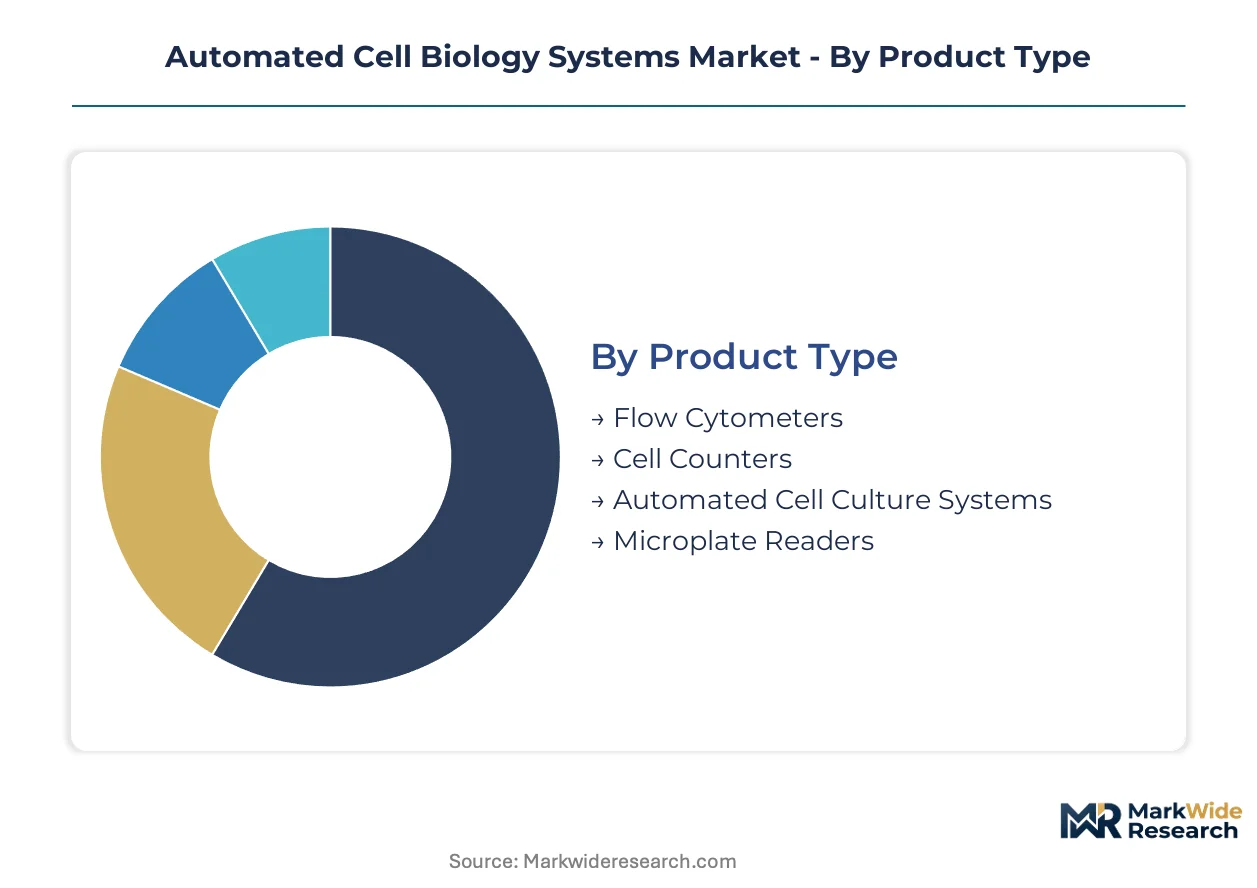
Segmentation in automated cell biology systems reveals how technical specifications align with distinct workflow requirements across therapeutic development pipelines. Equipment purchasing decisions diverge sharply between high-throughput screening environments and precision cell therapy manufacturing suites.
Product Type:
Substitution pressure runs strongest against standalone analytical instruments as integrated platforms absorb discrete functions into unified workflows.
- Automated Cell Culture Systems:Closed-system bioreactor platforms maintain physiological parameters through continuous perfusion or fed-batch protocols. CAR-T manufacturers in the United States deploy these systems to achieve commercial batch volumes for autologous therapies while maintaining FDA 21 CFR Part 11 data lineage.
- Flow Cytometers:Multi-parameter cell analysis instruments utilizing laser excitation and photodetector arrays for immunophenotyping. Academic medical centers in Boston and San Diego drive procurement for hematologic malignancy research, constrained by capital intensity limiting mid-tier laboratory access.
- Cell Counters:Automated viability and density quantification devices using impedance or image-based enumeration.
- Microplate Readers:Absorbance, luminescence, and fluorescence detection systems for high-throughput screening assays.
Automated cell culture systems anchor the volume base while cell counters gain share at the steepest rate as distributed manufacturing networks proliferate.
Technology:
Cost tier stratification separates capital-intensive imaging modalities from accessible particle-based detection methods.
- Digital Imaging:High-resolution CMOS and CCD sensor arrays coupled with computational segmentation algorithms for label-free cell analysis. Pharmaceutical companies in Switzerland and Germany prioritize these systems for reduced reagent consumption and real-time morphological monitoring.
- Fluorescence Microscopy:Confocal and widefield systems employing specific fluorophore excitation for multiparametric molecular localization. Contract development organizations in Ireland retrofit existing platforms with continuous environmental monitoring ahead of EMA Annex 1 enforcement deadlines.
- Optical Tweezers:Laser-based force manipulation for single-cell mechanical property characterization.
- Nanoparticles:Quantum dot and gold nanoparticle probes for enhanced signal amplification in detection assays.
Digital imaging commands the premium tier while fluorescence microscopy sustains the broadest installed base across institutional categories.
Application:
Volume concentration clusters around therapeutic modalities with the most demanding regulatory validation requirements.
- Cell Therapy:Autologous and allogeneic manufacturing workflows requiring sterile isolation and chain-of-identity tracking. Commercial-scale facilities in the Netherlands and Ireland pilot integrated environmental control systems to preempt EMA Annex 1 compliance deadlines.
- Drug Discovery:High-throughput screening and lead optimization pipelines leveraging automated liquid handling. Biotechnology firms in Hyderabad and Bengaluru expand capacity following CDSCO streamlined biosimilar approval pathways.
- Disease Diagnosis:Clinical laboratory automation for hematologic and oncologic testing protocols.
- Genetic Research:CRISPR screening and functional genomics applications in academic settings.
Drug discovery retains the largest equipment footprint while cell therapy expands most quickly as commercial manufacturing scales beyond clinical supply.
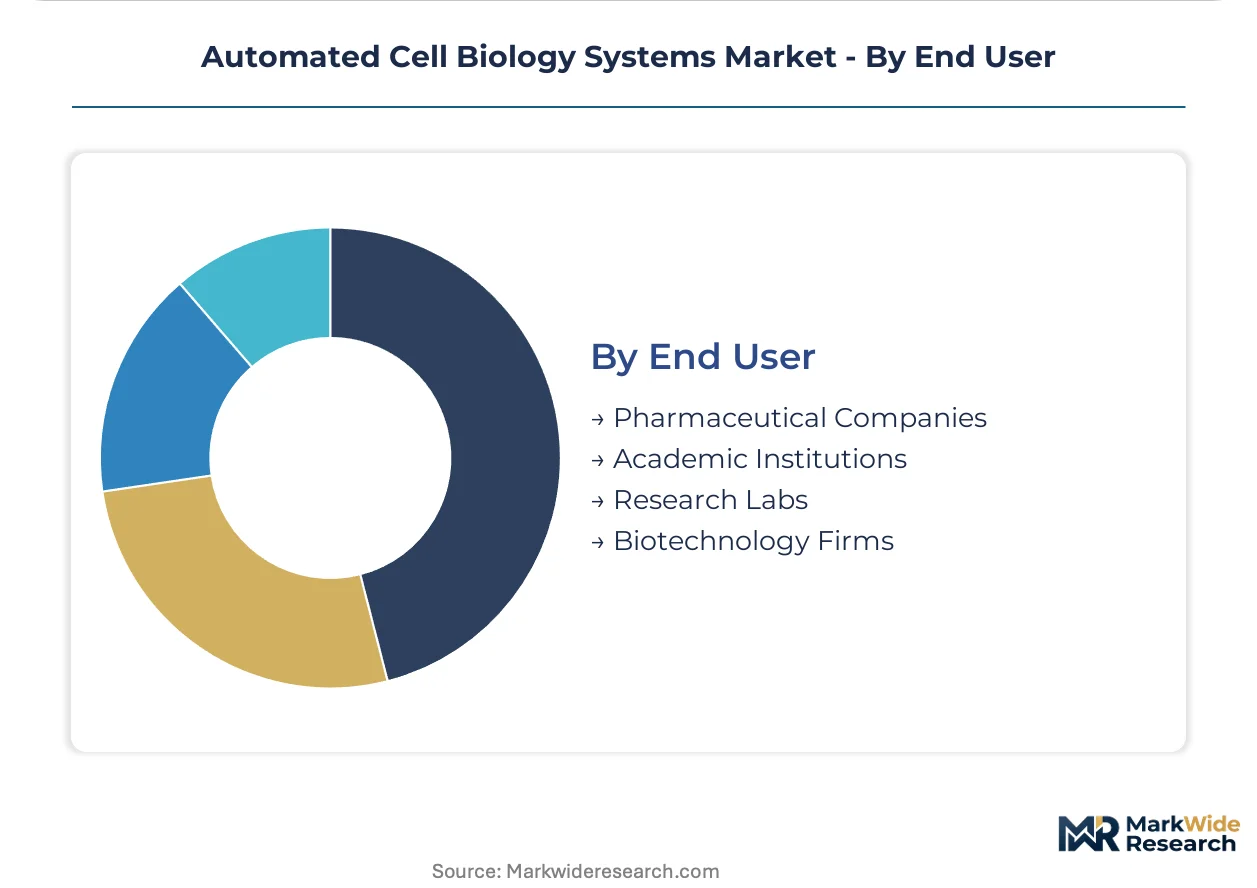
End User:
Customer type determines procurement authority structure and service contract negotiation leverage.
- Pharmaceutical Companies:Centralized global procurement functions in New Jersey and Basel unbundle after-sales service from capital purchases. These organizations negotiate multi-vendor maintenance agreements that disrupt traditional single-source revenue models.
- Biotechnology Firms:Investor-backed scale-up decisions drive pilot-scale perfusion platform deployment for productivity demonstration. Gene therapy CDMOs in the United States compress facility footprints through flexible multi-product manufacturing configurations.
- Academic Institutions:Early technology validation influence despite smaller transaction sizes and extended sales cycles.
- Research Labs:Fragmented demand across government and private non-profit facilities with constrained capital budgets.
Pharmaceutical companies dominate capital allocation while biotechnology firms exhibit the steepest procurement acceleration trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance requirements anchor procurement decisions in the United States, while EMA GMP Annex 15 guidelines reshape European qualification protocols. Biopharma manufacturing clusters in Boston, San Diego, Basel, and Hyderabad concentrate automated cell culture platform deployment.
United States
CAR-T commercial scale-up drives demand for high-throughput automated culture systems among autologous therapy manufacturers. FDA 21 CFR Part 11 mandates electronic records integrity, elevating equipment validation standards. Boston and San Diego biotech clusters dominate instrument procurement as cell therapy CDMOs compress facility footprints through perfusion platform adoption.
Germany
Pharmaceutical companies prioritize digital imaging systems for reduced reagent consumption and real-time morphological monitoring. EMA GMP Annex 15 qualification requirements for computerized systems accelerate replacement of legacy manual equipment. The Rhine-Main and Upper Bavaria regions concentrate single-use bioreactor deployment for flexible multi-product manufacturing.
Switzerland
Centralized global procurement functions in Basel unbundle after-sales service from capital purchases and negotiate multi-vendor maintenance agreements. Swissmedic oversight of therapeutic manufacturing reinforces stringent equipment qualification protocols. The Basel biotech cluster anchors European demand for closed-system automated cell culture architectures.
India
CDSCO streamlined biosimilar approval pathways and PLI scheme incentives attract automated cell culture investment to emerging manufacturing hubs. The country's national pharmaceutical regulator aligns with international GMP standards to accelerate facility approvals. Hyderabad and Bengaluru clusters expand capacity as biotechnology firms scale drug discovery pipelines.
Netherlands
Cell therapy cleanrooms pilot integrated environmental control systems ahead of EMA Annex 1 enforcement deadlines on sterile manufacturing. The national pharmaceutical regulator enforces EU-wide qualification frameworks for computerized systems. The Leiden and Amsterdam regions concentrate commercial-scale facilities requiring continuous viable particle detection retrofit.
Automated Cell Biology Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in automated cell biology systems. The upper tier captures multi-product contracts through workflow portfolio breadth, while specialists dominate single-use bioreactor and analytical subsegments. Three archetypes define competitive positioning: integrated workflow providers, single-use technology specialists, and analytical instrument incumbents. M&A activity and strategic partnerships represent the dominant competitive moves as vendors expand software ecosystem capabilities.
Within the integrated workflow tier, Thermo Fisher Scientific and Danaher Corporation occupy positions spanning liquid handling through detection modules. Sartorius AG exemplifies the single-use specialist archetype, anchoring its competitive position through disposable bioreactor systems that reduce cross-contamination risk. These three entities represent distinct strategic vectors: portfolio breadth, installed base leverage in flow cytometry, and pre-sterilized component supply concentration respectively.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Corning Incorporated |
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| Agilent Technologies |
| PerkinElmer |
| Lonza |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for single-use bioreactor bags from European suppliers concentrate pricing power among polymer resin converters in Germany and Massachusetts, while biopharma procurement teams exploit multi-year offtake agreements to compress unit economics. This inventory-band tension shapes how automated cell culture platform vendors structure capital equipment versus consumables revenue splits.
Pricing Analysis
Geographic price spreads of 15-25% separate North American list pricing from Indian procurement contracts for equivalent automated cell culture platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 21 CFR Part 11 validation depth and after-sales service bundling. Pricing pressure stems from CDSCO-aligned manufacturers in Hyderabad demanding localized service economics without global certification premiums. Mid-tier contract development organizations exhibit acute price sensitivity, whereas top-20 pharmaceutical companies with Basel and New Jersey procurement centers prioritize data lineage capabilities over capital expenditure minimization.
Supply Chain Analysis
Sixty-to-ninety-day inventory cycles for pre-sterilized bioreactor components tether automated cell culture system availability to resin allocation decisions in Germany, Massachusetts, and South Carolina. Supply draws from fluoropolymer film extruders, gamma-irradiation facilities, and precision sensor manufacturers concentrated in these three states. Single-source vulnerability concentrates in gamma-sterilization capacity, where facility qualification timelines exceed 18 months. Distribution runs through authorized distributor networks serving biopharma clusters in Boston, San Diego, and Basel with direct field service engineering attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated cell biology systems are crossing a platform-economics threshold where vendor lock-in through proprietary data formats yields to API-open architectures enabling multi-vendor workflow orchestration. This interoperability inflection restructures competitive moats from hardware throughput to software ecosystem breadth.
For Market Incumbents: Compound defensive positioning by acquiring cloud-native process analytics capabilities before gene therapy CDMOs consolidate procurement authority. Thermo Fisher Scientific and Danaher Corporation must preempt modular hardware disintermediation through API standardization investments that preserve installed base leverage. Certification investment in EMA Annex 1-aligned environmental monitoring modules defends against single-use specialists expanding into integrated platform territory.
For New Entrants and Emerging Players: Anchor in India's CDSCO-aligned manufacturing expansion where PLI scheme incentives and biosimilar approval velocity outpace validation-timeline constraints burdening established vendors. Hyderabad and Bengaluru drug discovery pipelines represent the most penetrable white-space for automated liquid handling modules priced below Thermo Fisher Scientific's portfolio entry points. Go-to-market execution should attach to CDMO facility buildout timelines rather than competing for retrofits at incumbent-protected pharmaceutical headquarters.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized life sciences instrumentation divisions lacking software ecosystem integration. Long-term viability in automated cell biology systems hinges on recurring consumables revenue attachment rates rather than capital equipment cyclicality. Monitor EMA Annex 1 enforcement deadline compliance spending as the signal indicating facility retrofit urgency and replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Open Platform Development | Enables multi-vendor workflow orchestration for CAR-T manufacturers requiring best-of-breed module integration. |
| Single-Use Technology Licensing | Accelerates CDSCO-aligned facility approvals in India through pre-validated disposable component supply. |
| Cloud-Native Process Analytics Acquisition | Captures real-time release and predictive maintenance revenue streams from gene therapy CDMOs. |
| EMA Annex 1 Compliance Retrofit Services | Monetizes environmental monitoring integration mandates affecting Netherlands and Ireland cell therapy cleanrooms. |
| Multi-Vendor Maintenance Certification | Responds to Basel and New Jersey procurement teams unbundling service contracts from capital equipment purchases. |
Study Parameters
Initial hypotheses were tested against primary input from bioprocess engineering directors, regulatory affairs leads at cell therapy manufacturers, GPO contracts managers, and single-use technology procurement specialists, then refined through secondary validation against FDA 483 inspection observations, EMA GMP inspection deficiency databases, and SEC 10-K instrument revenue disclosures. Bottom-up triangulation of installed base estimates with top-down capital expenditure tracking across Boston, San Diego, and Basel biotech clusters anchored volume and value projections.
Variance decomposition across product type, application, technology modality, and end-user procurement authority structure shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated CDSCO biosimilar approval velocity, EMA Annex 1 enforcement timeline assumptions, and perfusion platform adoption curves among gene therapy CDMOs.
Material uncertainties — resin supply disruptions, regulatory timeline delays, and interoperability standardization failures — sit outside the modeled envelope. Forecasts reflect documented assumptions about facility buildout schedules and qualification protocol durations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Exosomes Market
Biomedical Technology
Northern Blotting Market
Biomedical Technology
Imaging Biomarkers Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Asia-Pacific Exosome Research Products Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Global Autologous Conditioned Plasma Market
Biomedical Technology
ST2 Biomarker Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Blood Brain Barrier Technologies Market
Biomedical Technology
Fluorescent in Situ Hybridization Market
Biomedical Technology
Asia-Pacific Proteomics Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Europe Biobanks Market
Biomedical Technology
Oligonucleotide Synthesis Market