
 Cellbag Bioreactor Chambers Market | 2026-2036
Cellbag Bioreactor Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Cellbag Bioreactor Chambers Market Outlook
Switzerland is rewriting competitive dynamics in precision bioreactor film manufacturing. Thermo Fisher Scientific leverages integrated supply chains from raw polymer sourcing to sterile finished goods. Sartorius Stedim Biotech anchors European demand through specialized single-use platforms for cell therapy production. Danaher Corporation competes across multiple material grades with differentiated quality systems.
Cellbag bioreactor chambers are flexible, single-use vessels constructed from multi-layer polymer films—typically polyethylene or polypropylene composites—designed to provide sterile, closed-environment cell culture with working volumes from milliliters to thousands of liters. These systems eliminate cleaning validation requirements while enabling rapid campaign changeover in biopharmaceutical manufacturing. Disposable product types command the largest volume share due to their elimination of cross-contamination risk in multi-product facilities. Gene therapy applications represent the fastest-expanding segment as viral vector production scales beyond traditional stainless-steel infrastructure. Material selection increasingly stratifies around polyethylene for its extractables profile and polypropylene for mechanical resilience in rocking-motion bioreactors.
FDA guidance on chemistry, manufacturing, and controls for gene therapy products shapes extractables and leachables testing protocols for all film suppliers seeking US market access. EMA's Good Manufacturing Practice Annex 1 revisions on sterile manufacturing push adoption of fully closed cellbag systems over open or semi-closed alternatives. ISO 13485 quality management requirements extend compliance burdens to contract manufacturers assembling custom chamber configurations. Stakeholders must monitor evolving polymer supply constraints and regulatory divergence between FDA and EMA on single-use system validation timelines.
Market Dynamics
Single-use bioprocessing infrastructure is displacing stainless-steel systems as viral vector manufacturing scales beyond traditional capacity constraints, forcing film suppliers to validate extractables profiles under accelerated regulatory timelines.
Growth Catalysts
- FDA Chemistry, Manufacturing, and Controls Guidance:Gene therapy developers must document leachables testing for all contact materials, creating mandatory demand for pre-validated cellbag films.
- Cell therapy manufacturing:Autologous and allogeneic production lines require rapid campaign changeover that only disposable bioreactor chambers can deliver.
- Boston-San Francisco procurement corridors:Biopharma clusters concentrate purchasing power for high-capacity rocking-motion systems.
Market Restraints
- Specialty polymer supply concentration:Medical-grade polyethylene and polypropylene resin production clusters in Gulf Coast petrochemical corridors, exposing buyers to hurricane-related disruption.
- EMA-FDA validation divergence:Differing timelines for single-use system qualification create redundant testing burdens for suppliers seeking dual-market access.
- Stainless-steel infrastructure lock-in:Existing biologics facilities with depreciated capital resist full conversion to disposable platforms.
Strategic Opportunities
- ISO 13485-certified contract manufacturers:Outsourced assembly of custom chamber configurations captures value from biopharma firms avoiding captive film welding capacity.
- Closed-system processing mandates:EMA Annex 1 revisions on sterile manufacturing accelerate replacement of open or semi-closed alternatives.
- India biopharma manufacturing:CDSCO pathway harmonization with ICH standards positions domestic producers for export-oriented cellbag demand.
Industry Challenges
- Extractables testing expertise scarcity:Qualified analytical chemists capable of designing polymer-specific migration studies command premium compensation.
- Multi-layer film welding certification:Validated sterile sealing processes require 12-18 month qualification cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellbag Bioreactor Chambers Market |
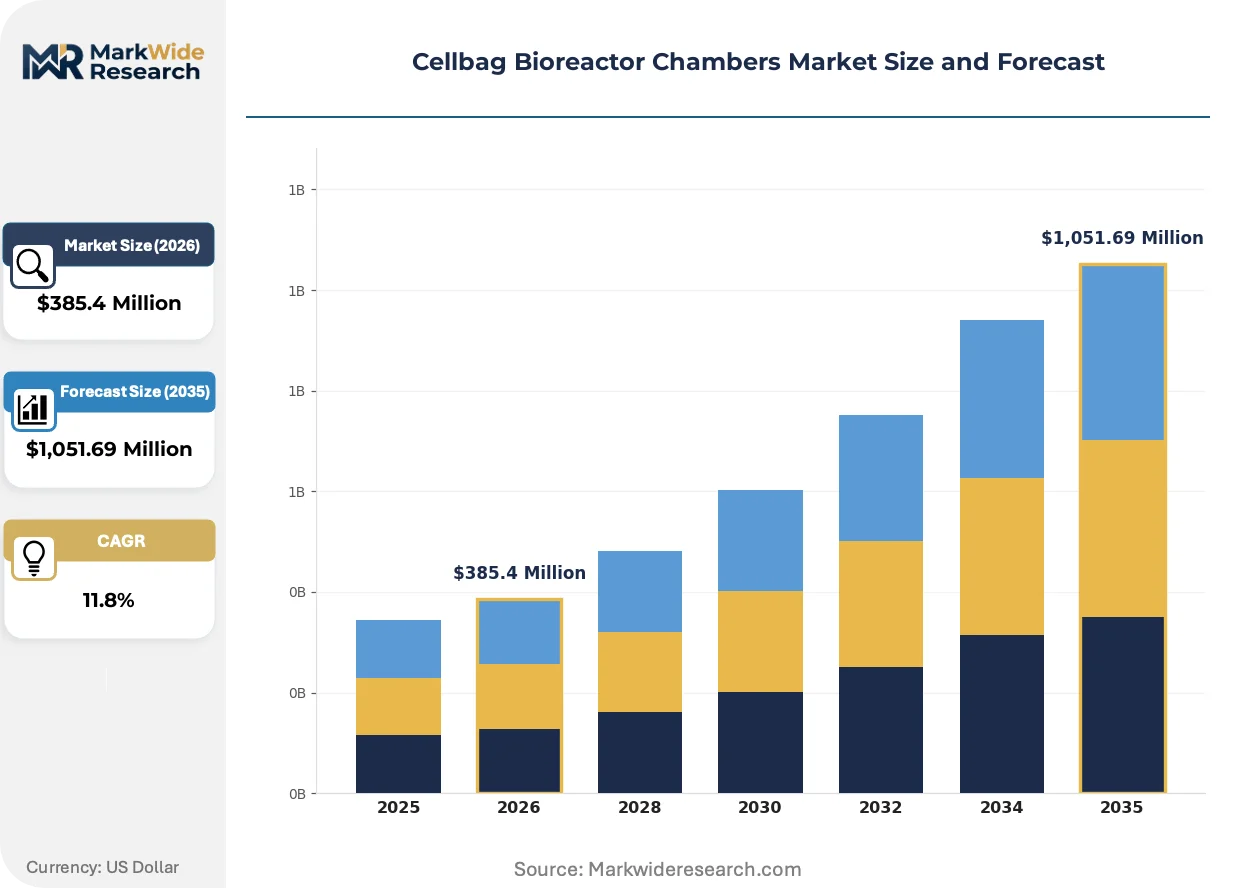
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,051.69 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suspension, Adherent, Disposable, Reusable End User: Biopharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Academic Labs Material: Polyethylene, Polypropylene, PVC, Nylon Application: Cell Culture, Protein Production, Vaccine Development, Gene Therapy |
| Companies Covered | Thermo Fisher Scientific, GE Healthcare Cytiva, Merck Millipore, Danaher Corporation, Sartorius Stedim Biotech, Avantor Inc., JW Therapeutics, Atara Biotherapeutics, Adolf Kuhner AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellbag Bioreactor Chambers Market Strategic Shifts
Film material selection is stratifying around performance-specific polymer grades as rocking-motion bioreactors impose distinct mechanical stresses on chamber walls.
Polyethylene formulations dominate extractables-sensitive applications due to their inert contact surface. Gene therapy manufacturers in the United States specify these grades for viral vector production. Film technology is migrating from commodity polyethylene toward engineered copolymers with tuned permeability coefficients.
EMA Annex 1 revisions mandate fully closed processing environments for sterile drug products. This policy compresses the addressable market for open or semi-closed cellbag configurations. European contract manufacturers are retrofitting facilities to eliminate manual interventions in cell culture operations.
Biopharma procurement departments now require supplier audit rights extending to raw polymer resin sources. This practice compresses the vendor base to integrated manufacturers with captive resin supply. The shift is most pronounced among CDMOs serving US-based gene therapy sponsors.
Cellbag Bioreactor Chambers Market Segmentation
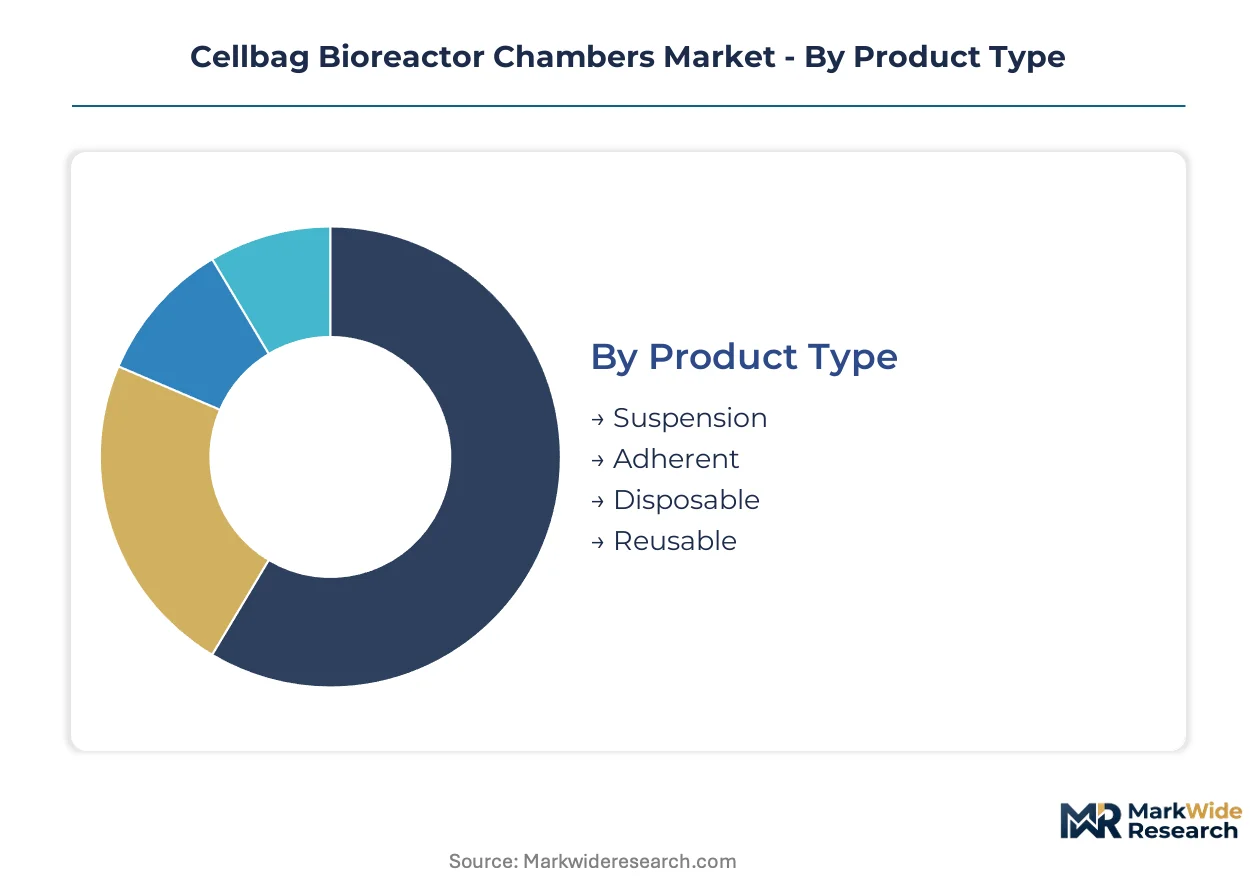
Cellbag bioreactor chambers serve distinct operational requirements across manufacturing scales and therapeutic modalities. Segmentation reveals how material science, product architecture, and end-use specifications create specialized procurement corridors within bioprocessing infrastructure.
Product Type:
Mature disposable formats anchor commercial procurement while adherent configurations emerge for specialized cell therapy applications.
- Disposable:Single-use polymer film chambers eliminate cleaning validation and enable rapid campaign changeover in multi-product facilities. Biopharmaceutical manufacturers in Boston and San Francisco procurement corridors specify these for viral vector production.
- Suspension:Configured for free-floating cell lines in rocking-motion bioreactors, these chambers handle high-density mammalian culture for monoclonal antibody manufacturing. Demand concentrates among contract manufacturing organizations scaling single-use capacity.
- Adherent:Surface-enhanced designs support anchorage-dependent cell types for stem cell and primary culture applications.
- Reusable:Stainless-steel hybrid systems persist in legacy biologics facilities with depreciated capital infrastructure.
Disposable handles the majority of throughput; adherent is the fastest mover on share.
End User:
Procurement scale stratifies sharply between commercial manufacturing and research-scale operations.
- Contract Manufacturing Organizations:CDMOs drive volume procurement of high-capacity rocking-motion systems as gene therapy sponsors outsource viral vector production. ISO 13485 certification requirements filter supplier selection to integrated manufacturers with validated film welding capacity.
- Biopharmaceutical Companies:Sponsor firms specify extractables-tested polyethylene grades for internal pipeline manufacturing, with FDA chemistry, manufacturing, and controls documentation mandating pre-validated film selections.
- Research Institutions:Early-stage process development employs small-volume chambers for cell line characterization and media optimization.
- Academic Labs:Grant-funded research programs utilize standard configurations for proof-of-concept studies.
Contract Manufacturing Organizations absorb the dominant procurement volume; biopharmaceutical companies are expanding fastest on capacity additions.
Material:
Polymer selection divides between extractables-sensitive gene therapy applications and mechanically stressed rocking-motion systems.
- Polyethylene:Inert contact surfaces dominate viral vector production where leachables testing documentation is mandatory. FDA guidance on gene therapy chemistry, manufacturing, and controls specifies these grades for US market access.
- Polypropylene:Superior mechanical resilience withstands repeated flexing in rocking-motion bioreactors at thousand-liter scales. European contract manufacturers specify these for EMA Annex 1 compliant closed-system processing.
- PVC:Legacy material persists in cost-sensitive research applications with lower regulatory documentation requirements.
- Nylon:Specialty barrier layers appear in multi-laminate constructions for oxygen-sensitive cell culture.
Polyethylene commands the largest installed base; polypropylene is climbing the fastest on mechanical performance specifications.
Application:
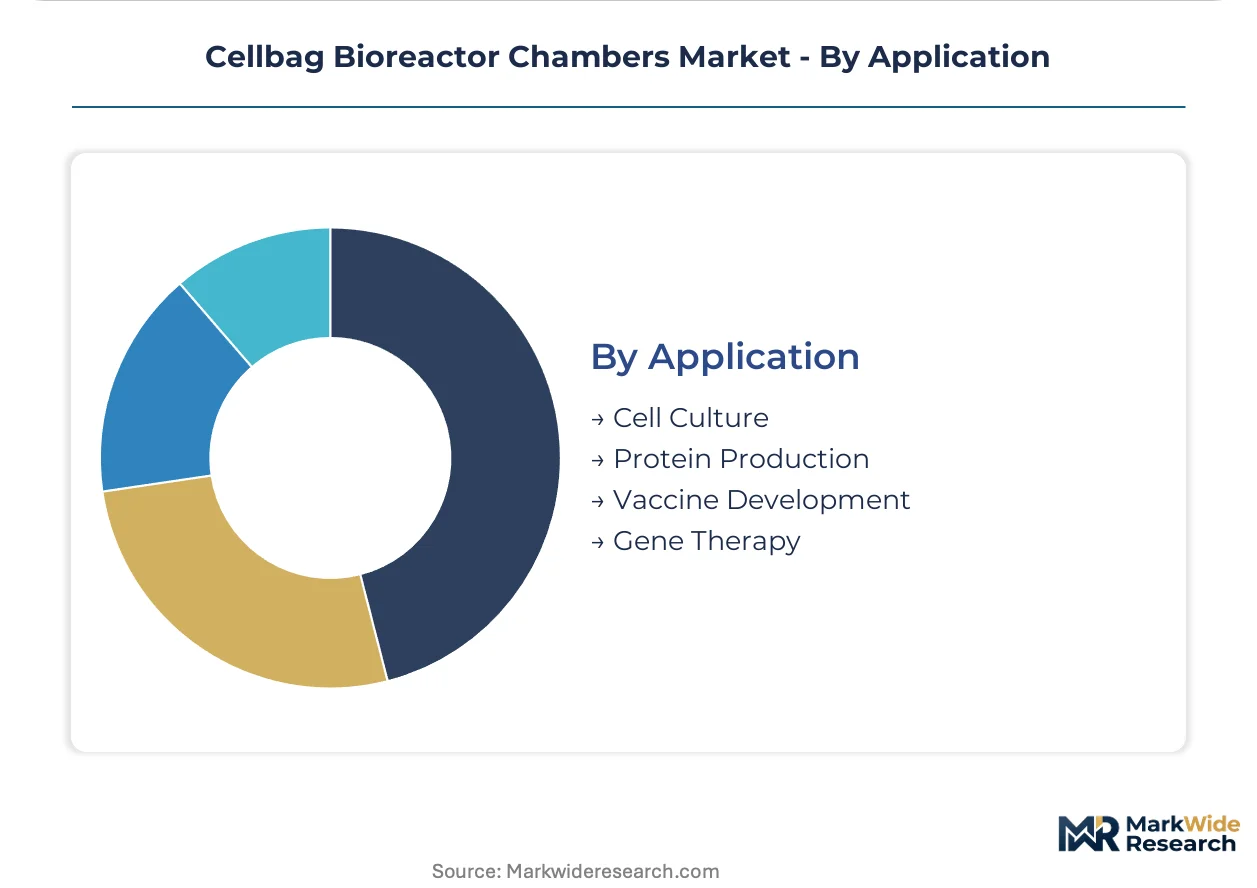
Gene therapy manufacturing imposes the most stringent material qualification burdens while cell culture remains the foundational use case.
- Gene Therapy:Viral vector production at commercial scale requires pre-validated extractables profiles and closed-system configurations. EMA Annex 1 sterile manufacturing mandates accelerate replacement of open processing alternatives.
- Cell Culture:Mammalian and microbial expansion for biologics manufacturing constitutes the core installed base across all material grades and chamber sizes.
- Protein Production:Recombinant protein manufacturing in CHO and HEK293 lines employs standardized suspension configurations.
- Vaccine Development:Rapid pandemic response capabilities favor disposable platforms for flexible manufacturing surge capacity.
Cell Culture maintains the broadest deployment footprint; gene therapy shows the steepest expansion trajectory on regulatory-driven qualification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA chemistry, manufacturing, and controls guidance for gene therapy products anchors procurement concentration in the United States. EMA Annex 1 sterile manufacturing mandates and CDSCO pathway harmonization shape qualification requirements across secondary markets.
United States
Boston and San Francisco biopharma clusters drive high-capacity rocking-motion system procurement for viral vector manufacturing. FDA guidance on leachables testing documentation mandates pre-validated film selections for all contact materials. Massachusetts and California contract manufacturers scale ISO 13485-certified assembly capacity to serve gene therapy sponsor demand.
Germany
European contract manufacturers retrofit facilities for EMA Annex 1 compliant closed-system processing. The country's national pharmaceutical regulator enforces sterile manufacturing revisions that eliminate open or semi-closed cellbag configurations. Baden-Württemberg and Bavaria host specialized single-use platform providers serving continental cell therapy production.
Switzerland
Precision bioreactor film manufacturing concentrates around integrated supply chains from raw polymer sourcing to sterile finished goods. Swissmedic guidelines align with EMA standards while maintaining distinct validation timelines for domestic manufacturers. Basel and Zurich anchor European demand for extractables-tested polyethylene grades in gene therapy applications.
India
CDSCO pathway harmonization with ICH standards positions domestic producers for export-oriented cellbag demand. The central drug regulator's alignment with international quality management requirements filters supplier selection to integrated manufacturers. Maharashtra and Gujarat biopharma manufacturing corridors scale disposable platform capacity for contract research and manufacturing services.
China
NMPA biologics manufacturing guidelines accelerate domestic validation requirements for single-use system films. The national medical products administration's chemistry, manufacturing, and controls documentation standards mirror FDA structures for gene therapy products. Yangtze River Delta biopharma clusters invest in rocking-motion bioreactor infrastructure for monoclonal antibody and viral vector production.
Cellbag Bioreactor Chambers Market Competitive Environment
Capability concentration sits with integrated polymer-to-film manufacturers; scale advantage sits with diversified life science conglomerates. The vendor base stratifies across three tiers: resin-integrated specialists commanding premium positioning, multi-product platform providers capturing volume procurement, and regional assemblers serving cost-sensitive research applications. Dominant competitive moves include backward integration into medical-grade polymer supply and ISO 13485 certification expansion for contract assembly services.
Within the integrated supply chain tier, Thermo Fisher Scientific and Danaher Corporation represent archetypes of resin-to-finished-goods control. Sartorius Stedim Biotech occupies a position among European specialists in single-use platform architecture. These three anchors demonstrate how geographic clustering—Waltham-based conglomerate diversification, Washington DC-area life science instrumentation, and Göttingen-centered bioprocessing specialization—shapes competitive positioning without requiring identical capability stacks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| GE Healthcare Cytiva |
| Merck Millipore |
| Danaher Corporation |
| Sartorius Stedim Biotech |
| Avantor Inc. |
| JW Therapeutics |
| Atara Biotherapeutics |
| Adolf Kuhner AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Gulf Coast medical-grade polymer resin production is compressing raw material costs while simultaneously intensifying supplier competition for qualified film welding capacity, creating divergent pricing pressure across integrated versus outsourced manufacturing tiers.
Pricing Analysis
Transatlantic price spreads of 15-25% separate US and European procurement corridors for ISO 13485-certified cellbag assemblies. Contract-based long-term offtake agreements dominate high-volume viral vector manufacturing, with price differentiation driven by extractables documentation depth and EMA-FDA dual-validation status. Cost compression in standard-grade polyethylene chambers is intensifying as Chinese film suppliers expand qualified welding capacity. Contract manufacturing organizations exhibit highest price sensitivity due to margin pressure from gene therapy sponsors, while integrated resin-to-film manufacturers command premium positioning through captive supply security.
Supply Chain Analysis
ISO 13485-certified contract manufacturers including Thermo Fisher Scientific and Sartorius Stedim Biotech hold dominant film welding and sterile assembly capacity across Switzerland, Germany, and the United States. Medical-grade polyethylene and polypropylene resins draw from Gulf Coast petrochemical corridors, while multi-layer laminate barrier films hinge on specialized Japanese and German coating equipment. Single-source vulnerability concentrates in validated sterile sealing process qualification, where 12-18 month certification cycles create captive relationships. Distribution runs through direct biopharma procurement channels and CDMO tier-one supplier programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cellbag bioreactor chambers market is cycling through a capacity expansion phase as gene therapy viral vector manufacturing scales beyond stainless-steel infrastructure constraints.
For Market Incumbents: Build regulatory documentation moats through preemptive EMA Annex 1 closed-system validation and FDA gene therapy CMC extractables profiling. Deepen backward integration into medical-grade resin supply to defend against Gulf Coast hurricane disruption exposure. Expand ISO 13485-certified welding capacity in Massachusetts and California corridors to capture CDMO outsourcing demand from sponsor firms avoiding captive film assembly investment. For New Entrants and Emerging Players: India's CDSCO-harmonized manufacturing corridors offer underpenetrated entry points for export-oriented cellbag assembly serving European and US gene therapy sponsors. Target mid-scale adherent chamber configurations for stem cell therapy applications where specialized surface engineering requirements filter out commodity competitors. Pursue joint development agreements with academic medical centers for custom chamber prototyping to establish clinical credibility before commercial scale-up. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gene therapy application segments as extractables testing and dual-validation requirements extend qualification timelines. Acquisition candidates with validated polymer-to-film supply chains and existing EMA-FDA regulatory files present strongest long-term viability through the capacity expansion cycle. Monitor CDSCO inspection readiness and USP Class VI certification backlogs as early indicators of supplier quality tier migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Resin Supply | Gulf Coast polymer sourcing secures qualified polyethylene supply against hurricane-related disruption. |
| EMA Annex 1 Closed-System Validation | Preemptive sterile manufacturing compliance eliminates open-configuration competitors from European procurement. |
| ISO 13485 Certification Expansion | Contract assembly accreditation captures gene therapy sponsor outsourcing demand in Boston-San Francisco corridors. |
| Extractables Testing Laboratory Investment | In-house polymer migration studies accelerate FDA CMC documentation for viral vector applications. |
| India Manufacturing Footprint Establishment | CDSCO-aligned quality systems position for export-oriented supply to ICH-standard markets. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with bioprocessing executives, regulatory affairs directors, CDMO procurement managers, and polymer supply specialists; and secondary validation through FDA CMC guidance documents, EMA Annex 1 revision drafts, ISO 13485 certification registries, and USP extractables testing protocols. Bottom-up cellbag procurement volume estimates from Boston, San Francisco, Basel, and Singapore biopharma clusters were triangulated against top-down single-use bioprocessing infrastructure investment disclosures.
Forecast inputs considered product type segmentation across disposable, suspension, adherent, and reusable configurations; material stratification between polyethylene and polypropylene grades; and end-user procurement patterns distinguishing contract manufacturing organizations from sponsor firm captive capacity. CAGRs were derived from viral vector manufacturing scale-up trajectories, EMA-FDA validation timeline convergence assumptions, and polymer supply elasticity estimates across the projection horizon. Gene therapy pipeline advancement rates and closed-system processing mandate compliance schedules served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity addition by diversified life science conglomerates or accelerated CDSCO harmonization by Indian regulators would shift outcomes. Forecasts assume sustained FDA-EMA validation divergence and stable Gulf Coast resin supply availability. Quarterly review of gene therapy sponsor outsourcing announcements and EMA inspection deficiency trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Amino Acid Analyzer Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Global Life Sciences Tools Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market