
 Autoimmune Disease Testing Market | 2026-2036
Autoimmune Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Autoimmune Disease Testing Market Analysis
Recurring assay panel subscriptions is broadening revenue models beyond one-time test sales. Quest Diagnostics sustains geographic dominance through its national reference laboratory footprint. Abbott Laboratories leverages integrated instrument-reagent ecosystems to lock in hospital laboratory contracts. F. Hoffmann-La Roche Ltd. anchors high-throughput autoimmune testing with its established immunochemistry platforms.
Autoimmune disease testing encompasses laboratory methods that detect autoantibodies, immune complexes, and inflammatory markers to diagnose conditions where the immune system attacks host tissues; these assays typically operate with analytical sensitivity thresholds in the nanogram-per-milliliter range and rely on antigen-coated solid-phase substrates for specific binding detection. The primary commercial purpose centers on enabling differential diagnosis of systemic and organ-specific autoimmune disorders to guide immunosuppressive therapy selection and monitor disease activity. ELISA-based test formats occupy the mature volume tier with established reimbursement codes and commodity pricing pressures, while immunofluorescence assays retain premium positioning in subspecialty rheumatology and nephrology reference settings where pattern interpretation demands skilled technologist labor. Clinical laboratories represent the dominant end-user channel with consolidated purchasing power, though homecare settings emerge as a growth frontier as capillary blood collection devices and remote result platforms gain technical validation.
FDA 510(k) premarket notification requirements shape assay development timelines and predicate device selection strategies for US market entrants, while CLIA laboratory certification standards govern test complexity classification and personnel qualification mandates. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking for autoimmune test kits sold in European member states. Stakeholders must monitor evolving payer coverage policies for multiplex autoantibody panels and algorithm-based diagnostic pathways that promise cost efficiency but threaten traditional fee-for-service test reimbursement structures.
Market Dynamics
Reference laboratory consolidation and the migration toward algorithm-based diagnostic pathways are compressing test reimbursement rates while elevating analytical specificity requirements for autoimmune assay platforms.
Growth Catalysts
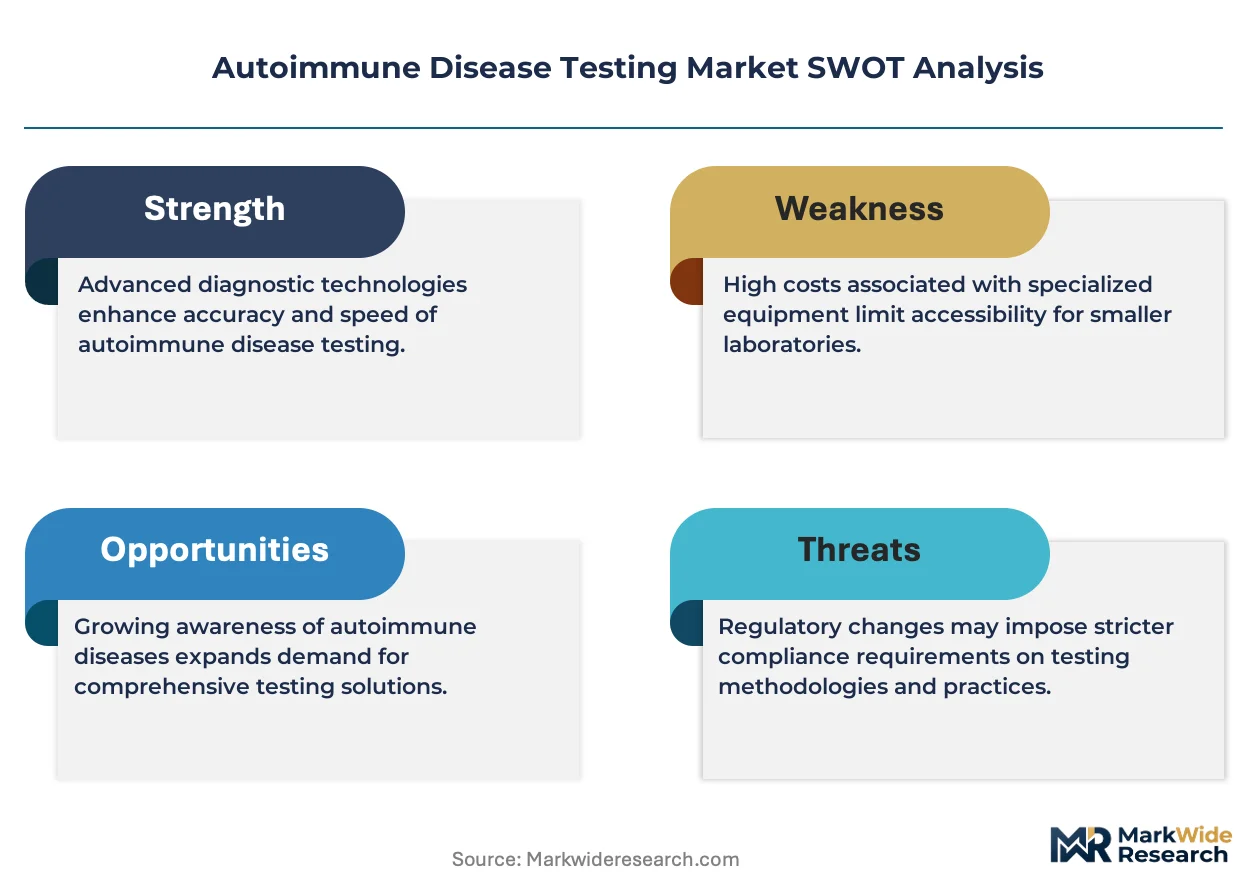
- Rheumatology referral volumes:Rising autoimmune disease prevalence in aging populations is expanding test panel utilization across hospital and outpatient settings.
- FDA 510(k) pathway streamlining:Predicate device selection strategies are shortening premarket notification timelines for novel autoantibody assays entering the US market.
- Multiplex platform adoption:Laboratories are consolidating multiple single-analyte tests into high-throughput screening panels to reduce per-test operational costs.
Market Restraints
- Reimbursement compression:Payer coverage policies for algorithm-based diagnostic pathways threaten traditional fee-for-service test structures.
- Skilled technologist scarcity:Immunofluorescence pattern interpretation requires specialized labor that concentrates in subspecialty reference settings.
- Commodity pricing pressure:ELISA-based test formats face margin erosion from established reimbursement codes and competitive bidding dynamics.
Strategic Opportunities
- Homecare testing frontier:Capillary blood collection devices and remote result platforms are gaining technical validation for patient self-sampling models.
- EU MDR transition:Stricter clinical evidence requirements for CE marking create barriers that favor well-capitalized manufacturers with robust post-market surveillance infrastructure.
- Subscription revenue models:Recurring assay panel subscriptions are broadening revenue streams beyond transactional test sales for laboratory networks.
Industry Challenges
- CLIA personnel mandates:Test complexity classification requirements constrain workforce flexibility and extend training timelines for high-complexity immunofluorescence assays.
- Predicate device selection:FDA 510(k) clearance strategies require careful navigation of substantial equivalence determinations that can delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autoimmune Disease Testing Market |
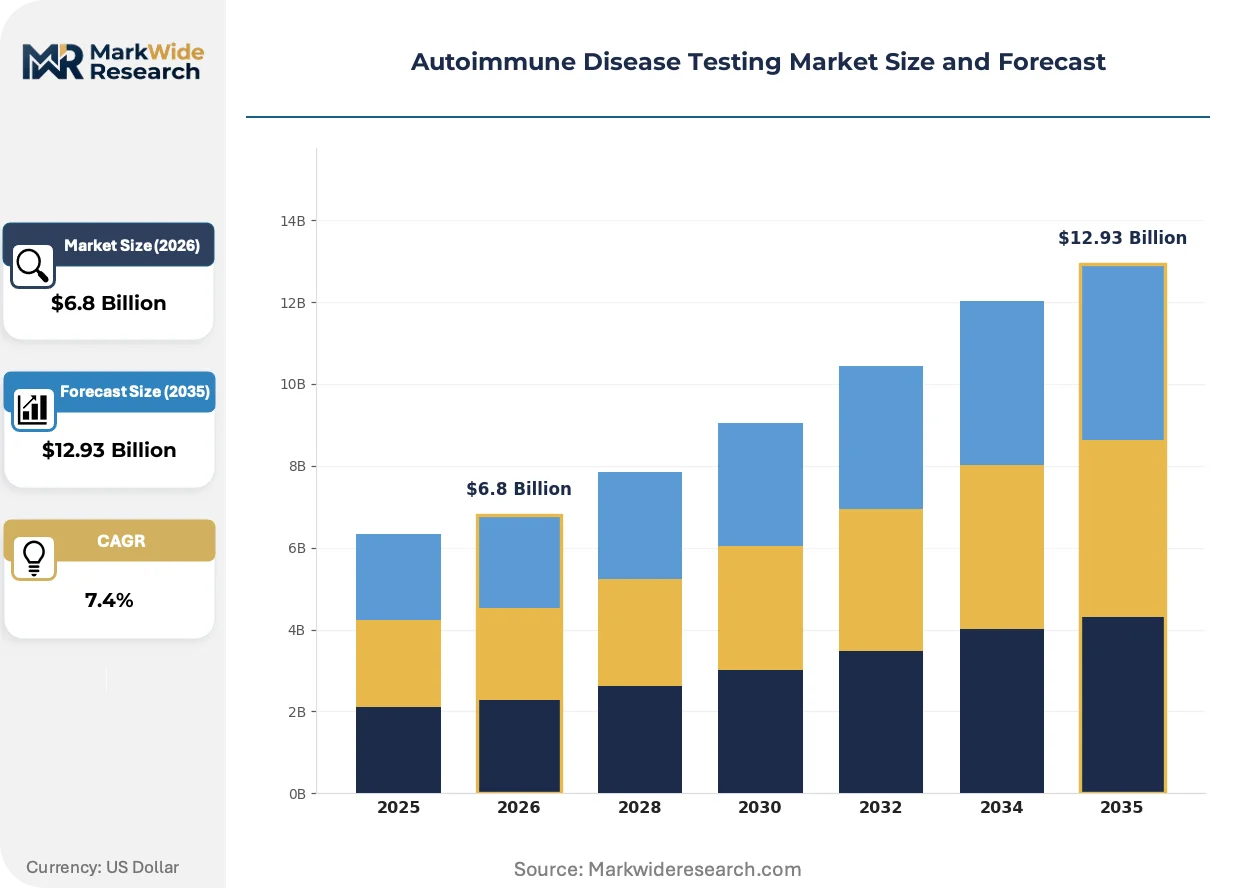
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ELISA, Immunofluorescence, Western Blot, Enzyme-linked Immunosorbent Assay Sample Type: Blood, Serum, Plasma, Saliva End User: Clinical Laboratories, Hospitals, Research Institutes, Homecare Settings Application Area: Rheumatology, Gastroenterology, Dermatology, Neurology |
| Companies Covered | Agilent Technologies, Inc., Quest Diagnostics, Inc., Abbott Laboratories, PerkinElmer, Inc., bioMerieux, Inc., F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific, Inc., Adaptive Biotechnologies Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autoimmune Disease Testing Market Emerging Trajectories
Automation and digital pathology integration are redefining how autoimmune diagnostics move from specimen collection to clinical decision support, compressing turnaround times while elevating interpretive consistency.
Next-generation multiplex immunoassays are unifying previously discrete autoantibody detection workflows onto single-platform architectures. Large reference laboratories are deploying these systems at scale to replace fragmented ELISA and immunofluorescence benches. This consolidation is unifying test menus under standardized reagent ecosystems that lock in multi-year supply contracts.
EU In Vitro Diagnostic Regulation enforcement is mandating expanded clinical performance studies and systematic post-market surveillance for autoimmune test kits seeking CE marking. Manufacturers are restructuring quality management systems to accommodate notified body oversight of technical documentation and vigilance reporting. European member states with established IVD regulatory infrastructure are experiencing the steepest compliance cost escalation.
Integrated health systems are consolidating laboratory purchasing decisions under centralized procurement functions that negotiate multi-analyte panel pricing across hospital networks. Independent reference laboratories are losing access to these decision-makers as health systems insource testing or award exclusive contracts to national laboratory partners. The United States exhibits the most pronounced buyer concentration, where three large networks control substantial autoimmune testing volume.
Autoimmune Disease Testing Market Segmentation
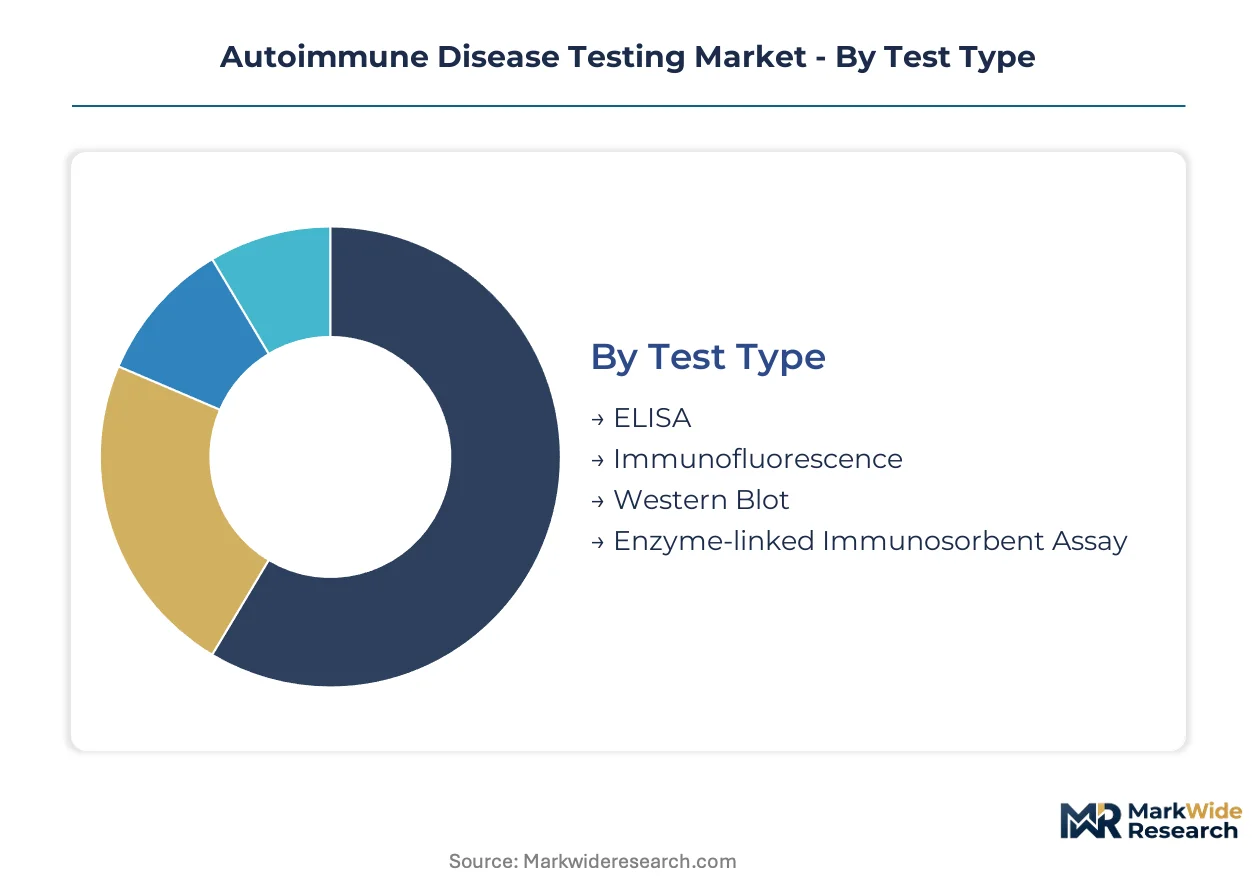
Test format selection in autoimmune diagnostics follows replacement cycles driven by automation economics and regulatory recertification timelines. Laboratories reevaluate platform investments when predicate device clearances expire or multiplex capabilities render single-analyte workflows obsolete.
Test Type:
Platform upgrade decisions hinge on throughput requirements and technologist availability, with automated systems displacing manual workflows in high-volume settings.
- ELISA:Solid-phase enzyme immunoassays with established predicate device pathways dominate routine screening volumes. Hospital laboratories in the United States favor ELISA for ANA and rheumatoid factor testing where reimbursement codes stabilize procurement budgets.
- Immunofluorescence:Substrate-based pattern detection demands specialized technologist interpretation for antinuclear antibody classification. Reference laboratories retain this format for subspecialty rheumatology referrals where pattern specificity justifies extended turnaround times.
- Western Blot:Electrophoretic protein separation confirms antibody specificity in equivocal ELISA cases. Confirmatory testing demand concentrates in academic medical centers with integrated immunology services.
- Enzyme-linked Immunosorbent Assay:Quantitative antigen-binding detection supports therapeutic monitoring applications. Contract research organizations deploy these platforms for clinical trial endpoints requiring standardized inter-laboratory correlation.
Volume placements concentrate in ELISA; the faster expansion belongs to Immunofluorescence automation platforms.
Sample Type:
Collection method economics shape segment selection, with capillary sampling devices opening access points beyond traditional phlebotomy infrastructure.
- Blood:Venipuncture whole blood remains the reference standard for multiplex autoantibody panels. United States health systems standardize on EDTA collection tubes for integrated health network logistics.
- Serum:Clotted blood centrifugation yields high-purity antibody fractions for quantitative assays. Commercial reference laboratories process serum in automated aliquoting systems that link to laboratory information management platforms.
- Plasma:Anticoagulated blood supports cytokine and immune complex detection with reduced complement activation artifacts. Research institutes prefer plasma for longitudinal biomarker studies requiring frozen archival stability.
- Saliva:Non-invasive IgA and IgG collection enables patient self-sampling models for screening applications. Homecare validation studies in the United States are establishing analytical correlation with serum reference methods.
Serum dominates current processing volumes; saliva is gaining share fastest through remote monitoring pilot programs.
End User:
Procurement authority consolidation is shifting purchasing decisions toward centralized supply contracts that span multiple testing sites.
- Clinical Laboratories:Independent and hospital-affiliated labs operate high-throughput autoantibody screening with consolidated test menus. United States reference networks negotiate multi-year reagent agreements that lock in pricing across regional footprints.
- Hospitals:Acute care settings require rapid turnaround for autoimmune crisis differential diagnosis. Emergency department demand in the United States drives stat ANA and anti-dsDNA ordering patterns.
- Research Institutes:Academic medical centers develop novel biomarker assays with investigational use only designations. National Institutes of Health funding priorities shape assay development roadmaps for systemic lupus and rheumatoid arthritis cohort studies.
- Homecare Settings:Patient-collected specimens with telemedicine result delivery are emerging as a channel for chronic disease monitoring. FDA 510(k) clearances for capillary collection devices are expanding reimbursement eligibility for remote testing models.
Hospital placements lead by volume; homecare shows the steepest expansion trajectory among emerging channels.
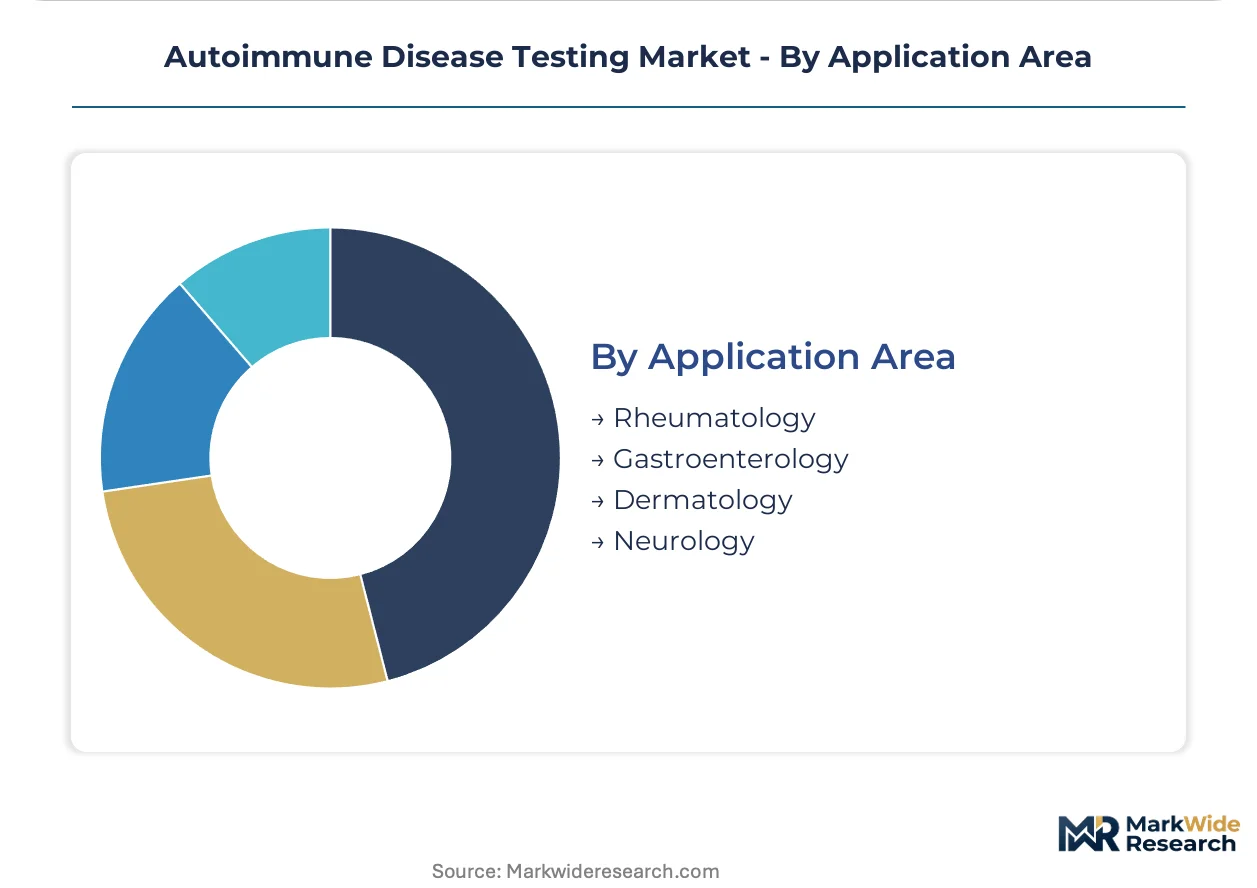
Application Area:
Disease prevalence and subspecialty referral patterns determine panel configuration complexity across clinical settings.
- Rheumatology:Systemic autoimmune disorders generate the broadest autoantibody testing demand with multi-analyte algorithm requirements. United States rheumatology practices order comprehensive connective tissue disease panels that cascade from screening to confirmatory testing.
- Gastroenterology:Celiac disease and inflammatory bowel disease serology requires tissue transglutaminase and ASCA antibody detection. Pediatric gastroenterology units in the United States prioritize non-invasive screening before endoscopic confirmation.
- Dermatology:Pemphigus and pemphigoid autoantibody testing supports blistering disease diagnosis with direct immunofluorescence correlation. Academic dermatology centers maintain specialized immunofluorescence capabilities for basement membrane zone pattern interpretation.
- Neurology:Paraneoplastic and autoimmune encephalitis antibody panels demand high analytical specificity for therapeutic intervention decisions. Mayo Clinic and Cleveland Clinic reference laboratories anchor United States volume for complex neuroimmunology testing.
Rheumatology commands the largest test volumes; neurology applications are climbing the fastest as antibody discovery expands treatable condition recognition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test production concentrates in the United States and Germany, while diagnostic consumption spreads across aging populations in Japan and Western Europe. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance timelines shapes where manufacturers prioritize launch sequencing.
United States
Quest Diagnostics and LabCorp reference networks process the majority of autoimmune test volume through centralized laboratory hubs. FDA 510(k) clearance pathways for novel autoantibody assays remain the fastest route to commercialization for domestic manufacturers. The Mayo Clinic in Rochester anchors specialized neuroimmunology and subspecialty rheumatology testing that draws specimens from across North America.
Germany
EU MDR enforcement has elevated clinical evidence requirements for CE marking, favoring well-capitalized manufacturers with established quality management systems. Siemens Healthineers and Roche Diagnostics anchor high-throughput immunochemistry production in the Mannheim and Basel corridor. The country's statutory health insurance system maintains distinct reimbursement codes for multiplex autoantibody panels that differ from single-analyte pricing.
Japan
PMDA regulatory timelines for in vitro diagnostics typically extend 12-18 months beyond FDA clearance, creating staggered product availability. Tokyo and Osaka metropolitan areas concentrate rheumatology referral volume in university hospital networks that favor automated platforms over manual immunofluorescence. METI industrial policy supports domestic IVD manufacturers through procurement preferences in public hospital systems.
United Kingdom
NHS England's consolidation of laboratory services into hub-and-spoke networks has reduced the number of sites performing complex immunofluorescence interpretation. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity assessment requirements for manufacturers seeking UKCA marking. The Cambridge-Oxford-London triangle anchors academic medical centers developing novel biomarker assays with investigational use designations.
China
NMPA Class III medical device registration requirements for autoimmune test kits mandate domestic clinical trials that extend time-to-market for multinational manufacturers. Shanghai and Beijing municipal health bureaus pilot centralized laboratory procurement that favors local reagent producers. The country's national medical insurance catalog expansion for autoimmune disease diagnostics is accelerating hospital laboratory test menu growth.
Autoimmune Disease Testing Market Vendor Landscape
Capital-heavy diagnostic instrument manufacturers compete with asset-light assay developers in autoimmune testing, creating tiered competitive dynamics. The market structure concentrates around three large reference laboratory networks in the United States and a fragmented base of regional hospital laboratories elsewhere. Strategic archetypes include integrated instrument-reagent ecosystem providers, national reference laboratory networks, and specialized autoimmune assay developers. Dominant competitive moves center on multi-year exclusive supply contracts and regulatory clearance racing for predicate device selection.
Within the integrated ecosystem tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd. exemplify capital-intensive platform strategies that lock hospital laboratories into standardized reagent supply agreements. Quest Diagnostics occupies a distinct position as a national reference laboratory network with geographic dominance through specimen logistics infrastructure. Thermo Fisher Scientific, Inc. represents the diversified life sciences conglomerate archetype with presence across research and clinical diagnostic segments. These three anchors illustrate how scale, integration depth, and channel control differentiate competitive positioning in autoimmune testing.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| Quest Diagnostics, Inc. |
| Abbott Laboratories |
| PerkinElmer, Inc. |
| bioMerieux, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Thermo Fisher Scientific, Inc. |
| Adaptive Biotechnologies Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Supply Flow & Price Mechanics
ELISA-to-multiplex platform bifurcation separates commodity screening from premium subspecialty testing, concentrating pricing power with automated high-throughput providers while fragmenting bargaining leverage among manual immunofluorescence operators. This tier divergence manifests in supply chain configurations where reagent manufacturers lock hospital laboratories into multi-year exclusive agreements, while reference laboratories competing on pattern interpretation face volatile spot purchasing for specialized substrates.
Pricing Analysis
Margin tightening in ELISA-based screening reflects established CPT reimbursement codes and competitive bidding dynamics among reference laboratory networks. Three-tier pricing structure across premium, standard, and economy levels tracks test complexity classification under CLIA standards, with high-complexity immunofluorescence commanding substantial premiums over waived rapid assays. Cost compression accelerates as integrated health systems consolidate purchasing decisions under centralized procurement functions. Price sensitivity concentrates among independent reference laboratories losing access to hospital network contracts, while academic medical centers exhibit lower elasticity for subspecialty confirmatory testing.
Supply Chain Analysis
FDA 510(k) clearance and EU MDR CE marking requirements gate reagent manufacturing concentration in the United States, Germany, and Switzerland. Antigen-coated solid-phase substrates, enzyme conjugates, and fluorochrome-labeled secondary antibodies anchor raw material dependencies. Single-source vulnerability persists for specialized tissue substrate production used in immunofluorescence pattern interpretation. Distribution runs through national reference laboratory networks and integrated health system central warehouses, with direct-to-laboratory relationships dominating high-volume reagent supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autoimmune disease testing market operates as a cost-of-compliance story where EU MDR clinical evidence requirements and FDA predicate device navigation create regulatory moats favoring manufacturers with established quality management infrastructure.
For Market Incumbents: Acquire post-market surveillance capabilities and notified body relationships to defend EU market position against emerging multiplex platform competitors. Consolidate reagent supply contracts through backward integration into antigen production, reducing exposure to substrate supplier concentration. Prioritize CLIA-waived assay development to capture outpatient and point-of-care volume migrating from high-complexity reference settings.
For New Entrants and Emerging Players: Capture homecare testing white space through capillary blood collection device validation and telemedicine platform partnerships. Target saliva-based IgA screening applications in pediatric gastroenterology where non-invasive collection commands premium positioning. Pursue reference laboratory co-development agreements to secure predicate device selection strategies for FDA 510(k) pathway entry.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated instrument-reagent ecosystem providers seeking assay menu expansion. Long-term viability hinges on regulatory clearance velocity and health system contract penetration rather than technology differentiation alone. Watch for Medicare coverage determination shifts on algorithm-based diagnostic pathways as inflection indicators for reimbursement model disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates US commercialization timelines for novel autoantibody detection platforms. |
| CE Marking Pathway | Unlocks European market access under EU MDR clinical evidence requirements. |
| Hospital System Partnership | Secures multi-year exclusive supply contracts through integrated health network procurement. |
| Software Companion Development | Enables automated pattern interpretation for immunofluorescence assays. |
| Reimbursement Strategy | Secures CPT code assignments and payer coverage for multiplex panel testing. |
Methodological Framework
Multi-period observation of rheumatology referral volumes, FDA 510(k) clearance timelines, and reference laboratory consolidation patterns anchored the trend analysis, supplemented by interviews with hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs specialists at IVD manufacturers. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare laboratory fee schedule filings, hospital procurement contract disclosures, and EU MDR notified body technical documentation. Bottom-up test volume modeling triangulated against top-down market sizing across the autoimmune disease testing landscape.
Segment-weighting approaches distributed value projections across test format, sample type, end user, and application area dimensions, with therapeutic monitoring and disease screening volume splits informing the analytical framework. CAGRs were derived from regression analysis of historical test utilization trends and projected rheumatology prevalence patterns. Forecast inputs incorporated CLIA laboratory certification expansion rates and EU MDR transition compliance timelines for autoimmune assay manufacturers.
The model holds under stable reimbursement code structures and regulatory clearance velocity; deviation in Medicare coverage policy for algorithm-based diagnostics or substantial EU MDR enforcement delays would shift volume projections. Forecasts reflect assumptions on reference laboratory network concentration and predicate device availability for novel platform entrants. A model refresh is warranted upon material change in FDA 510(k) review timelines or CMS national coverage determination outcomes for multiplex autoantibody panels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Sleep Testing Services Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Global CA 125 Test Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Point of Care Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Biological Indicator Vials Market
Testing Services
Point of Care Lipid Test Market
Testing Services
Rapid Sterility Testing Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Creatinine Testing Market
Testing Services
Pregnancy Point of Care Testing Market