
 Hospital Microbiology Testing Market | 2026-2036
Hospital Microbiology Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Microbiology Testing Market Foresight
Market Context
Clinical microbiologist staffing is collapsing across hospital networks, forcing laboratories to automate specimen processing and reduce manual culture interpretation. bioMérieux SA leverages its integrated VITEK and BIOFIRE platforms to capture replacement cycles for labor-intensive workflows. Thermo Fisher Scientific Inc. anchors North American supply through its direct hospital distribution infrastructure and consumables bundling. Becton, Dickinson and Company competes on closed-system automation that minimizes technologist hands-on time per blood culture.
Technical Definition and Segment Structure
Hospital microbiology testing encompasses the isolation, identification, and antimicrobial susceptibility profiling of pathogenic microorganisms from clinical specimens using culture-based, molecular, and proteomic methods, with turnaround time and analytical specificity serving as critical performance parameters for patient management decisions. PCR kits and molecular diagnostics platforms command premium positioning as healthcare facilities prioritize rapid pathogen detection over traditional phenotypic methods. Reagents and consumables sustain recurring revenue pools that equipment manufacturers exploit through locked-in platform chemistry, while genomic sequencing remains nascent in routine hospital settings due to workflow complexity and interpretive expertise requirements.
Regulatory Frame and Outlook
The FDA governs in vitro diagnostic platform clearances and antimicrobial susceptibility device performance standards, while the Centers for Medicare & Medicaid Services ties reimbursement to laboratory quality metrics that penalize diagnostic error rates. Clinical Laboratory Improvement Amendments enforcement shapes staffing minimums and competency documentation that directly affect platform selection criteria. Stakeholders must monitor evolving FDA guidance on next-generation sequencing-based infectious disease assays and corresponding proficiency testing requirements that will determine which hospital laboratories qualify for advanced molecular adoption.
Market Dynamics
Clinical microbiology laboratories face a workforce collapse that is accelerating automation adoption faster than equipment replacement cycles would normally allow. The FDA's enhanced antimicrobial susceptibility testing requirements compound this pressure by mandating platform upgrades that reduce manual interpretation dependency.
Growth Catalysts
- Hospital-Acquired Infection Surveillance Mandates:CMS reimbursement penalties for diagnostic error rates create institutional pressure for automated susceptibility platforms. United States acute care facilities prioritize rapid organism identification to avoid quality-metric penalties.
- Multidrug-Resistant Organism Detection Volumes:Carbapenem-resistant Enterobacteriaceae and Candida auris outbreaks force tertiary care hospitals to expand molecular diagnostic capacity. Phenotypic culture methods cannot match epidemiological containment timelines.
- Clinical Laboratory Improvement Amendments Enforcement:Competency documentation requirements for manual culture interpretation drive platform standardization. Laboratories substitute automated systems to reduce staffing minimums and audit risk.
Market Restraints
- Locked-In Platform Chemistry:Reagent and consumable bundling ties hospitals to single-vendor ecosystems. Switching costs span equipment replacement plus workflow revalidation under FDA quality system regulations.
- Genomic Sequencing Workflow Complexity:Next-generation sequencing demands interpretive expertise unavailable in routine hospital settings. Bioinformatics infrastructure and proficiency testing requirements limit adoption to academic medical centers.
- Capital Equipment Intensity:Automated blood culture and susceptibility platforms require substantial upfront investment. Smaller community hospitals defer replacement cycles despite diagnostic accuracy penalties.
Strategic Opportunities
- Point-of-Care Molecular Diagnostics:Syndromic respiratory panels and gastrointestinal pathogen detection expand into emergency departments and urgent care settings. BioFire FilmArray placement outside centralized laboratories accelerates turnaround time capture.
- Antimicrobial Stewardship Integration:Pharmacy informatics linkage creates value-based procurement models. Hospitals prioritize platforms with real-time susceptibility reporting to optimize formulary decisions.
- FDA Next-Generation Sequencing Guidance Evolution:Streamlined infectious disease assay clearances will qualify additional hospital laboratories for advanced molecular adoption. Proficiency testing requirements determine market access tiers.
Industry Challenges
- Clinical Microbiologist Staffing Collapse:Training program contraction and compensation competition from reference laboratories deplete hospital laboratory benches. Automation substitutes for expertise that cannot be recruited.
- Legacy System Integration Complexity:Laboratory information system connectivity and middleware standardization delay platform deployments. Vendor-specific data formats obstruct seamless workflow integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Microbiology Testing Market |
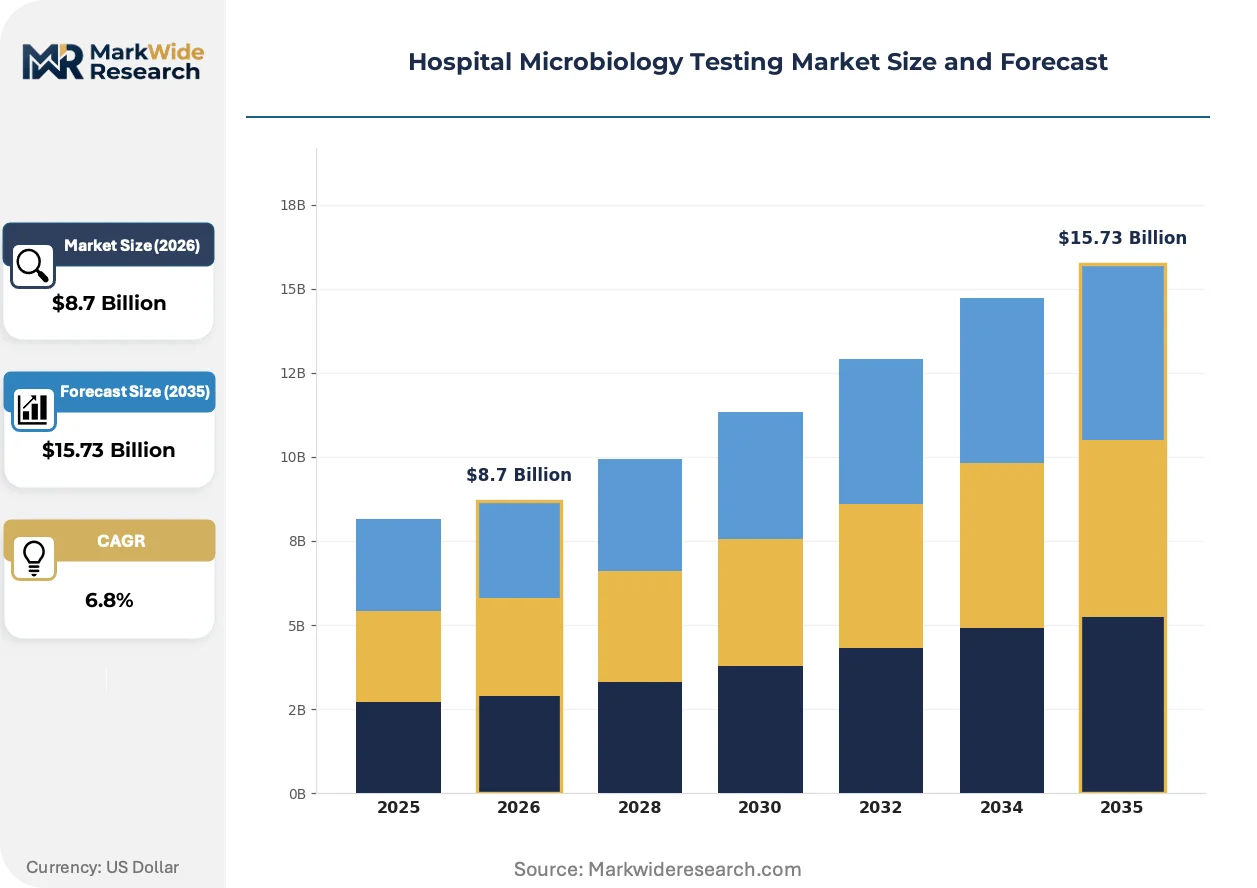
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Media, PCR Kits, Microscopes, Reagents End User: Laboratories, Research Institutions, Healthcare Facilities, Diagnostic Centers Technology: Molecular Diagnostics, Immunoassays, Mass Spectrometry, Genomic Sequencing Application: Infectious Disease Diagnosis, Antibiotic Susceptibility Testing, Blood Culture Testing, Surveillance |
| Companies Covered | bioMérieux SA, Thermo Fisher Scientific Inc., Becton, Dickinson and Company, Abbott Laboratories, Danaher Corporation, Merck KGaA, Bio-Rad Laboratories, Bruker Corporation, Neogen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Microbiology Testing Market Shifts & Advancements
Specimen-to-answer automation is compressing the diagnostic pathway from collection to susceptibility reporting. Laboratories prioritize platforms that eliminate manual transfer steps and reduce technologist hands-on time per specimen.
MALDI-TOF mass spectrometry is fragmenting organism identification workflows in mid-sized hospital laboratories. Community hospitals previously dependent on reference laboratory send-outs now adopt benchtop systems for rapid pathogen identification. This technology is fragmenting the reference laboratory market by capturing specimens that previously exited hospital networks entirely.
The FDA's evolving guidance on antimicrobial susceptibility testing device performance standards is accelerating platform obsolescence cycles. Manufacturers must recalibrate algorithms and update software to maintain 510(k) clearance under tightened accuracy thresholds. Blood culture system vendors face the most concentrated compliance burden as FDA scrutinizes time-to-detection claims.
Service unbundling is disrupting traditional equipment-procurement relationships. Hospitals now separate instrument acquisition from reagent supply and maintenance contracts, enabling multi-vendor consumable sourcing. This pattern is most visible in United States health systems with centralized supply chain governance, where laboratory directors negotiate chemistry flexibility independent of platform selection.
Hospital Microbiology Testing Market Segmentation
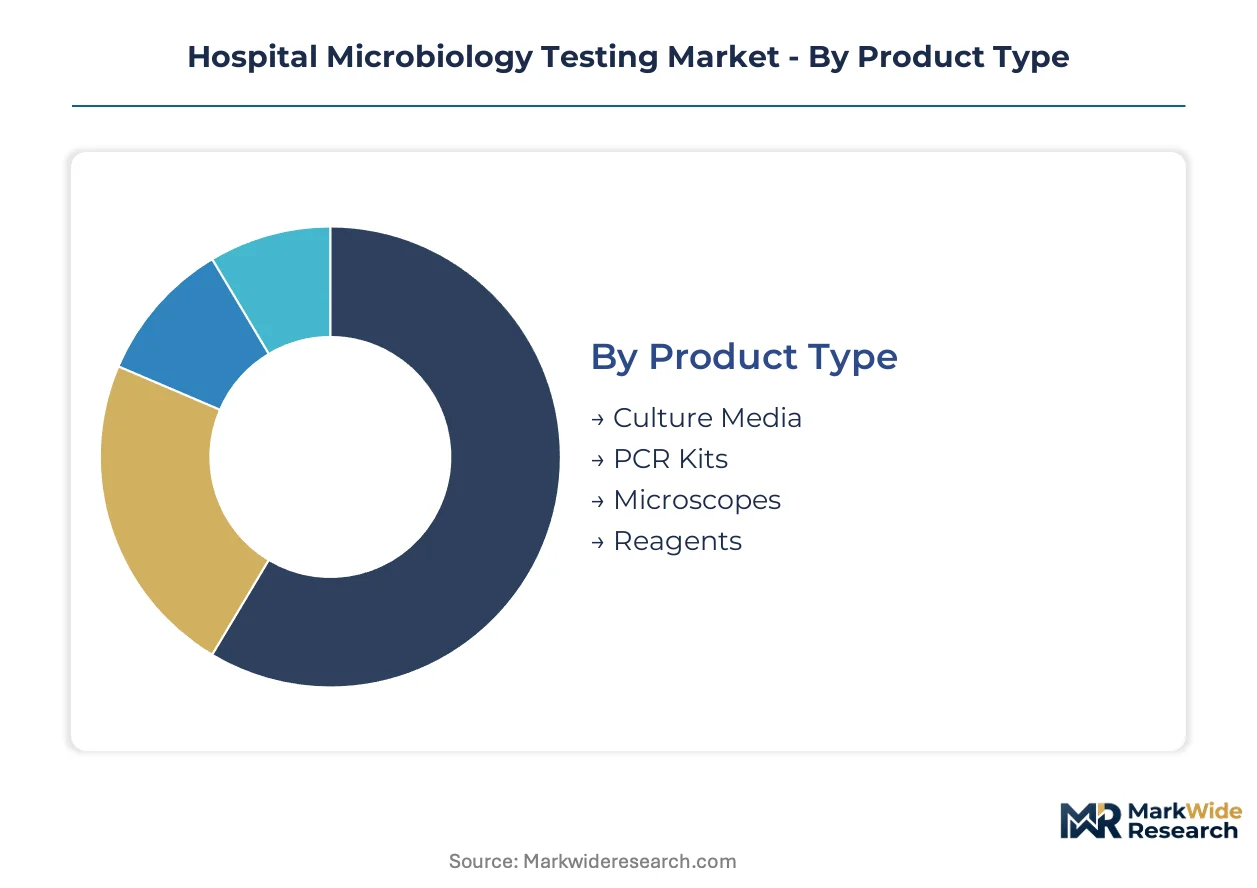
Hospital microbiology testing segments reflect divergent automation readiness across facility types. Procurement patterns split between centralized laboratories investing in integrated platforms and smaller sites prioritizing point-of-care molecular solutions.
Product Type:
Domestic production of culture media and reagents dominates North American supply chains, while PCR kits and specialized microscopes flow through concentrated import channels from European and Asian manufacturing hubs.
- Culture Media:Nutrient and selective formulations support bacterial isolation workflows in conventional hospital laboratories. Demand clusters in tertiary care facilities maintaining high-throughput susceptibility testing operations under FDA quality system regulations.
- PCR Kits:Nucleic acid amplification reagents enable rapid pathogen detection with turnaround times measured in hours rather than days. United States emergency departments and urgent care centers deploy syndromic respiratory panels to reduce antibiotic stewardship delays.
- Microscopes:Optical and digital imaging systems serve manual Gram stain interpretation and morphological assessment. Academic medical centers retain these for training and confirmatory workflows.
- Reagents:Biochemical identification panels and antimicrobial susceptibility testing strips sustain recurring consumable revenue. Locked-in platform chemistry ties hospitals to single-vendor ecosystems under FDA 510(k) cleared protocols.
Culture media commands the established base. The steepest expansion runs through PCR kits.
End User:
Laboratory consolidation is reshaping procurement concentration, with health system centralization favoring vendors offering multi-site service contracts and standardized training protocols.
- Laboratories:Hospital-based clinical microbiology units process the majority of infectious disease specimens using automated blood culture and susceptibility platforms. Staffing shortages accelerate replacement of manual methods with specimen-to-answer systems.
- Healthcare Facilities:Acute care hospitals and long-term care sites generate specimen volume tied to infection surveillance mandates. CMS reimbursement penalties for diagnostic error rates drive platform standardization across United States networks.
- Diagnostic Centers:Independent reference laboratories handle overflow testing and specialized molecular assays. These sites compete on turnaround time for community hospitals lacking in-house expertise.
- Research Institutions:Academic medical centers pilot next-generation sequencing workflows and develop novel antimicrobial susceptibility testing algorithms. FDA guidance evolution on sequencing-based assays shapes their technology adoption timelines.
Healthcare facilities anchor volume concentration. Diagnostic centers are climbing the fastest as outsourcing contracts expand.
Technology:
Cost tiers separate mature phenotypic methods from premium molecular platforms, with mid-sized hospitals navigating trade-offs between capital intensity and diagnostic accuracy requirements.
- Molecular Diagnostics:PCR and nucleic acid hybridization platforms deliver rapid pathogen identification and resistance marker detection. United States hospitals prioritize these for carbapenem-resistant organism outbreaks where epidemiological containment timelines compress.
- Mass Spectrometry:MALDI-TOF systems enable protein fingerprint-based organism identification within minutes of colony isolation. Community hospitals adopt benchtop configurations to retain specimens previously sent to reference laboratories.
- Immunoassays:Antigen and antibody detection methods serve screening applications with moderate analytical specificity. These occupy lower-cost niches in resource-constrained settings.
- Genomic Sequencing:Next-generation sequencing offers comprehensive resistance profiling and outbreak tracing. Workflow complexity and bioinformatics expertise requirements limit deployment to academic medical centers and specialized reference networks.
Molecular diagnostics commands the established base. Mass spectrometry is gaining share fastest through mid-market hospital penetration.
Application:
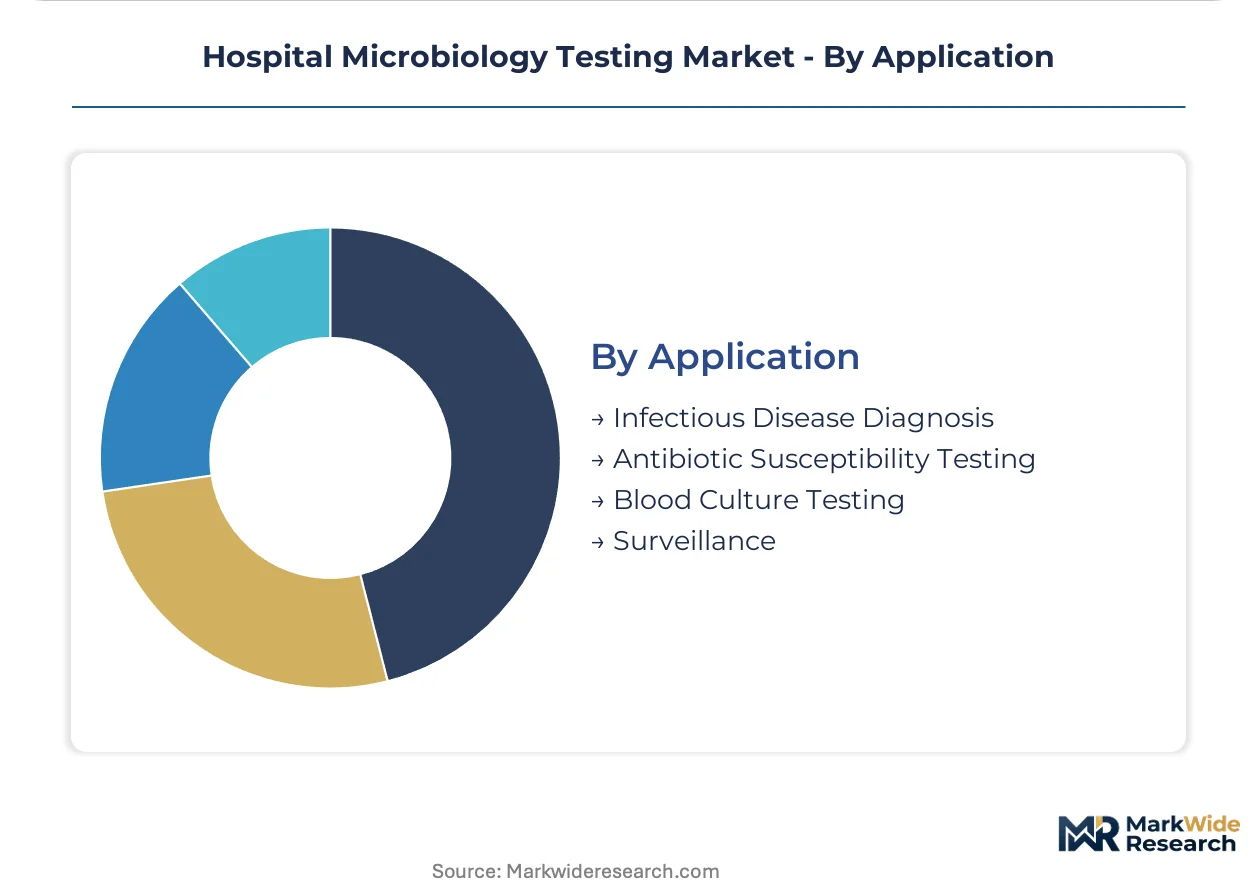
Regulatory pressure concentrates investment in applications tied to quality metrics and reimbursement penalties, while surveillance applications expand under public health reporting mandates.
- Infectious Disease Diagnosis:Pathogen identification from sterile and non-sterile sites directs antimicrobial therapy decisions. United States emergency departments prioritize rapid respiratory and gastrointestinal panels to reduce empiric antibiotic use.
- Antibiotic Susceptibility Testing:Minimum inhibitory concentration determination guides formulary decisions and resistance tracking. FDA enhanced performance standards accelerate platform upgrades across hospital networks.
- Blood Culture Testing:Sterile site specimen processing detects bloodstream infections with mortality implications. Automated continuous monitoring systems reduce time-to-detection and technologist hands-on time.
- Surveillance:Hospital-acquired infection tracking and multidrug-resistant organism screening satisfy CMS quality reporting and public health notification requirements. Tertiary care facilities expand capacity to meet mandatory reporting timelines.
Antibiotic susceptibility testing commands the established base. Surveillance is expanding most quickly under regulatory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA antimicrobial susceptibility testing mandates anchor procurement intensity in the United States, while parallel regulatory frameworks in Europe and Asia-Pacific shape divergent automation adoption timelines across hospital networks.
United States
CMS reimbursement penalties for diagnostic error rates drive automated platform procurement across acute care networks. The FDA enforces enhanced antimicrobial susceptibility testing device performance standards that accelerate equipment replacement cycles. Laboratory consolidation in the Northeast Corridor and Texas Medical Center clusters favors vendors offering multi-site service contracts and standardized training protocols.
Germany
EMA oversight of in vitro diagnostic clearances shapes platform selection criteria for university hospital networks. The country's national pharmaceutical regulator maintains stringent quality system requirements that favor closed-system automation with comprehensive documentation capabilities. Industrial concentration in Baden-Württemberg and Bavaria supports regional reagent manufacturing hubs serving Central European hospital networks.
China
NMPA regulatory pathways for molecular diagnostic platforms are streamlining as domestic manufacturers expand automated blood culture system production. The country's national medical products administration prioritizes local supply chain security for critical infectious disease diagnostics. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are scaling reagent production to serve hospital network procurement centralization.
Japan
PMDA regulatory review timelines for novel antimicrobial susceptibility testing algorithms influence technology adoption pacing in academic medical centers. METI industrial policy supports domestic diagnostic platform development to reduce import dependency for critical hospital infrastructure. The Kansai region's Osaka-Kobe medical device corridor hosts specialized manufacturers serving Southeast Asian export markets.
United Kingdom
NHS England diagnostic network consolidation is centralizing microbiology testing volume into regional hub laboratories with high-throughput automation requirements. The Medicines and Healthcare products Regulatory Agency maintains post-Brexit alignment with EU IVD regulations while streamlining domestic clearance pathways. London and Southeast laboratory clusters are piloting next-generation sequencing workflows under NHS genomic medicine service expansion mandates.
Hospital Microbiology Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in hospital microbiology testing, with platform bundling and consumable lock-in defining competitive moats. The upper tier commands automated blood culture and susceptibility system placements through direct hospital distribution infrastructure. Strategic archetypes include full-stack platform integrators, reagent-specialized consumables suppliers, and point-of-care molecular diagnostics pure-plays. Dominant competitive moves center on multi-year reagent supply contracts and antimicrobial stewardship software integration partnerships.
Among integrated platform manufacturers, bioMérieux SA and Thermo Fisher Scientific Inc. exemplify the full-stack archetype through combined instrument and consumables positioning. Becton, Dickinson and Company anchors the closed-system automation tier with blood culture platform specialization. These three entities collectively represent the competitive spectrum from European-centered platform integration to North American direct distribution scale.
| Leading Market Players |
|---|
| bioMérieux SA |
| Thermo Fisher Scientific Inc. |
| Becton, Dickinson and Company |
| Abbott Laboratories |
| Danaher Corporation |
| Merck KGaA |
| Bio-Rad Laboratories |
| Bruker Corporation |
| Neogen Corporation |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for specialized susceptibility testing reagents concentrate pricing power with manufacturers holding FDA-cleared platform chemistry, while hospital procurement committees face locked-in consumable contracts that resist competitive bidding. This supply structure rewards integrated vendors with recurring revenue streams and penalizes buyers seeking multi-source flexibility.
Pricing Analysis
United States hospital networks pay 15-25% premiums over European academic medical centers for identical automated susceptibility platforms, reflecting FDA quality system compliance costs and direct distribution infrastructure requirements. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform-acquisition bundles from standalone reagent supply and maintenance-only contracts. Pricing pressure stems from health system centralization forcing volume aggregation and service unbundling negotiations. Community hospitals exhibit highest price sensitivity due to capital equipment intensity, while tertiary care networks prioritize turnaround time metrics over per-test economics.
Supply Chain Analysis
Ninety-day inventory cycles for PCR kit enzymes and susceptibility testing panels expose hospital laboratories to single-source vulnerability when regional distribution hubs face disruption. Domestic production of culture media and reagents in the United States, Germany, and China draws from specialized fermentation capacity and pharmaceutical-grade chemical feedstocks. Supply chain risk centers on regulatory restriction: FDA 510(k) clearance requirements for alternative chemistry sources delay competitive substitution by 12-18 months. Distribution runs through direct hospital sales forces for capital equipment and group purchasing organization channels for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical microbiologist workforce attrition has created a capability-scarcity environment where automation expertise and antimicrobial stewardship integration determine competitive survival. Laboratories that cannot recruit interpretive specialists must purchase specimen-to-answer platforms or surrender volume to reference networks.
For Market Incumbents: Consolidate platform placements through multi-year reagent supply contracts that preempt switching decisions during replacement cycles. Defend against point-of-care molecular pure-plays by embedding pharmacy informatics linkage and real-time susceptibility reporting into existing installations. Prioritize backward integration into specialty reagent manufacturing to secure chemistry supply and margin capture. For New Entrants and Emerging Players: Differentiate on antimicrobial stewardship software integration rather than hardware specifications, where incumbent lock-in is weakest. Target mid-sized community hospitals with MALDI-TOF benchtop configurations that retain specimens previously sent to reference laboratories. Pursue emergency department placement for syndromic respiratory panels outside centralized laboratory workflows. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because health system laboratory centralization will eliminate sub-scale vendors lacking multi-site service infrastructure. Acquisition targets should demonstrate installed base density in consolidated markets and proficiency with FDA next-generation sequencing guidance evolution. Watch FDA streamlined infectious disease assay clearances as the signal determining which hospital laboratories qualify for advanced molecular adoption and platform upgrade eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Stewardship Software Integration | Pharmacy informatics linkage creates value-based procurement models that prioritize real-time susceptibility reporting. |
| Point-of-Care Molecular Platform Expansion | Emergency department placement of syndromic panels captures turnaround time premiums outside centralized laboratories. |
| Multi-Site Service Contract Standardization | Health system laboratory consolidation favors vendors offering standardized training protocols across regional hub networks. |
| FDA Next-Generation Sequencing Clearance Pursuit | Streamlined infectious disease assay approvals determine hospital laboratory qualification for advanced molecular adoption. |
| Reagent Manufacturing Backward Integration | In-house production of susceptibility testing chemistry secures supply continuity and captures consumable margin pools. |
Research Methodology
Initial hypotheses were tested against primary input from clinical laboratory directors, hospital procurement committee members, antimicrobial stewardship pharmacists, and biomedical engineers, and refined through secondary validation against FDA 510(k) clearance databases, CMS quality metric reports, hospital GPO contract disclosures, and Clinical Laboratory Improvement Amendments enforcement records. Bottom-up equipment placement estimates and top-down health system expenditure analysis were triangulated to converge on market sizing.
Variance decomposition across product type, end user facility tier, technology platform, and application use case shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling weighted by procurement intensity in consolidated health systems. Forecast inputs incorporated FDA antimicrobial susceptibility testing device performance standard evolution and clinical microbiologist staffing trajectory assumptions.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement penalty enforcement or accelerated FDA next-generation sequencing guidance would require recalibration. Forecasts reflect documented assumptions regarding health system consolidation pacing and workforce attrition rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Home Care Testing Market
Testing Services
Allergy Skin Test Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Platelet Function Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Global Roadside Drug Testing Devices Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
Ovulation Testing Kits Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
North America Drug Screening Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
US Viral Clearance Market