
 Alcohol Breathalyzer and Drug Testing Equipment Market | 2026-2036
Alcohol Breathalyzer and Drug Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Alcohol Breathalyzer and Drug Testing Equipment Market Analysis
Multi-source procurement of fuel cell sensor arrays is expanding as manufacturers diversify beyond single Japanese component suppliers. Draeger leverages its German engineering heritage to sustain premium positioning in law enforcement channels. Lifeloc Technologies anchors North American manufacturing with in-house calibration capabilities. Abbott competes across healthcare and workplace segments with integrated toxicology platforms.
Alcohol breathalyzer and drug testing equipment encompasses portable and fixed systems that detect blood alcohol concentration or illicit substance metabolites through breath, saliva, blood, or urine samples, typically achieving BAC precision within 0.001% using electrochemical fuel cell oxidation. These devices serve occupational safety compliance, criminal justice evidence collection, and clinical diagnostic screening. Breathalyzers utilizing fuel cell technology command the highest margin pools due to superior specificity against acetone interference. Semiconductor sensor models occupy the economy tier, while saliva test devices represent the fastest-growing format for rapid workplace deployment. Court-admissible evidence applications require the strictest calibration chain-of-custody protocols, creating barrier-protected revenue streams for certified providers.
FDA 510(k) clearance requirements shape medical testing device specifications, while DOT workplace regulations under 49 CFR Part 40 mandate standardized evidential breath alcohol measurement procedures across safety-sensitive employers. OSHA general duty clause enforcement in industrial settings drives employer liability for impairment-related incidents. Stakeholders must monitor state-level cannabis legalization trends that fragment per se impairment thresholds and complicate zero-tolerance policy enforcement across multi-jurisdictional operations.
Market Dynamics
Fuel cell sensor procurement concentration in Japanese component suppliers is forcing manufacturers toward multi-source strategies, while DOT workplace testing mandates under 49 CFR Part 40 create structural demand pull across safety-sensitive employers.
Growth Catalysts
- DOT 49 CFR Part 40 Mandates:Federal regulations require standardized evidential breath alcohol testing across transportation, aviation, and pipeline sectors, institutionalizing replacement cycles for compliant equipment.
- Workplace Safety Liability:OSHA general duty clause enforcement in industrial settings drives employer investment in impairment detection systems to mitigate incident-related litigation exposure.
- Fuel Cell Specificity Advantages:Electrochemical oxidation technology eliminates acetone interference that plagues semiconductor sensors, commanding premium positioning in court-admissible applications.
Market Restraints
- Platinum Catalyst Cost Volatility:Fuel cell electrodes depend on platinum group metals subject to commodity price swings, compressing margins on precision-grade devices.
- Calibration Infrastructure Concentration:Certified wet-bath simulator maintenance requires specialized technical labor pools concentrated in metropolitan compliance hubs, limiting rural deployment scalability.
- Cannabis Legalization Fragmentation:State-level per se impairment threshold variations complicate zero-tolerance policy enforcement for multi-jurisdictional logistics operators.
Strategic Opportunities
- Saliva-Based Rapid Deployment:Oral fluid testing formats bypass medical technician requirements, opening workplace screening to smaller employers without on-site nursing staff.
- Healthcare Diagnostic Integration:FDA 510(k) clearance pathways for medical-grade breathalyzers enable hospital emergency department adoption for acute intoxication assessment.
- Remote Calibration Services:Cloud-connected device monitoring allows predictive maintenance alerts, converting capital equipment sales into recurring revenue streams.
Industry Challenges
- Forensic Toxicology Talent Scarcity:Certified breath alcohol technician training programs face enrollment shortfalls, constraining testing capacity expansion.
- Chain-of-Custody Documentation Burden:Court-admissible evidence protocols require exhaustive calibration logs and maintenance records, elevating administrative overhead.
- Legacy Semiconductor Inventory Displacement:Economy-tier device manufacturers face stranded asset risk as fuel cell costs decline toward parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alcohol Breathalyzer and Drug Testing Equipment Market |
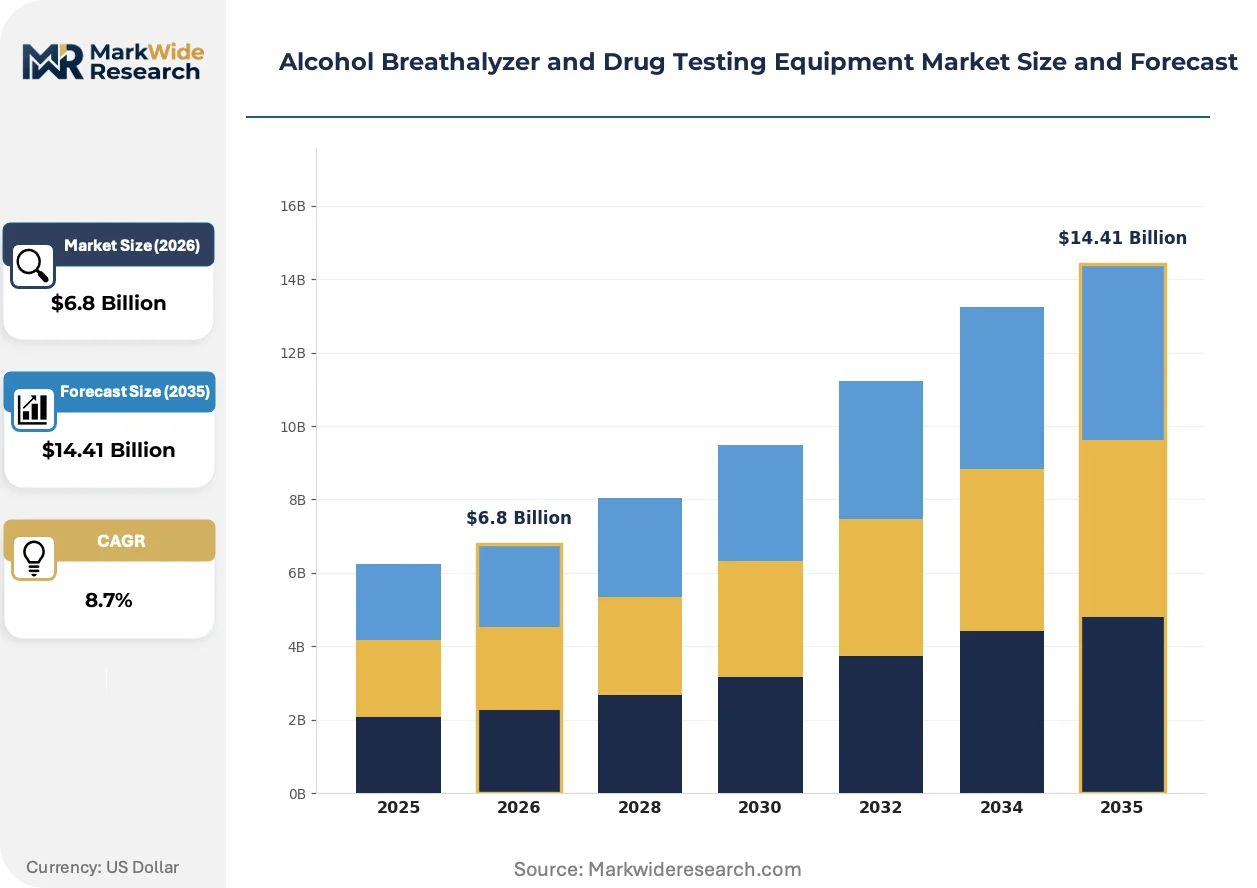
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breathalyzers, Drug Test Kits, Saliva Test Devices, Fingertip Testers Technology: Infrared Spectroscopy, Semiconductor Sensors, Fuel Cell Technology, Chemical Sensor Technology End User: Law Enforcement, Industrial Safety, Healthcare Providers, Educational Institutions Application: Workplace Screening, Roadside Testing, Medical Testing, Court-admissible Evidence |
| Companies Covered | Lifeloc Technologies, Lion Laboratories, Draeger, C4 Development, Quest Products, Abbott, BACtrack, Alcohol Countermeasure Systems, Intoximeters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alcohol Breathalyzer and Drug Testing Equipment Market Emerging Trajectories
Connected device architectures and non-invasive sampling modalities are compressing testing timelines while fragmenting procurement authority across safety, legal, and operations departments.
Bluetooth-enabled fuel cell breathalyzers with automated data logging are decentralizing workplace testing administration by allowing supervisors to conduct screenings without centralized laboratory coordination. Fleet operators and construction site managers are adopting these systems to reduce downtime from off-site collection site visits. The technology is decentralizing compliance workflows and compressing the traditional third-party testing service model.
EMA guidance on point-of-care diagnostic device interoperability is pressuring manufacturers to adopt standardized data exchange protocols for healthcare system integration. European hospital networks are requiring HL7 FHIR compatibility for emergency department intoxication screening purchases. German and French medical device distributors are prioritizing inventory positions that satisfy both clinical workflow and occupational health regulatory requirements.
Employer purchasing committees now split authority between risk management, human resources, and fleet operations functions, fragmenting traditional single-channel distributor relationships. Integrated toxicology platform vendors are responding with modular pricing that unbundles hardware, consumables, and software subscriptions. United States logistics conglomerates with multi-state terminal networks exhibit the most pronounced procurement committee complexity.
Alcohol Breathalyzer and Drug Testing Equipment Market Segmentation
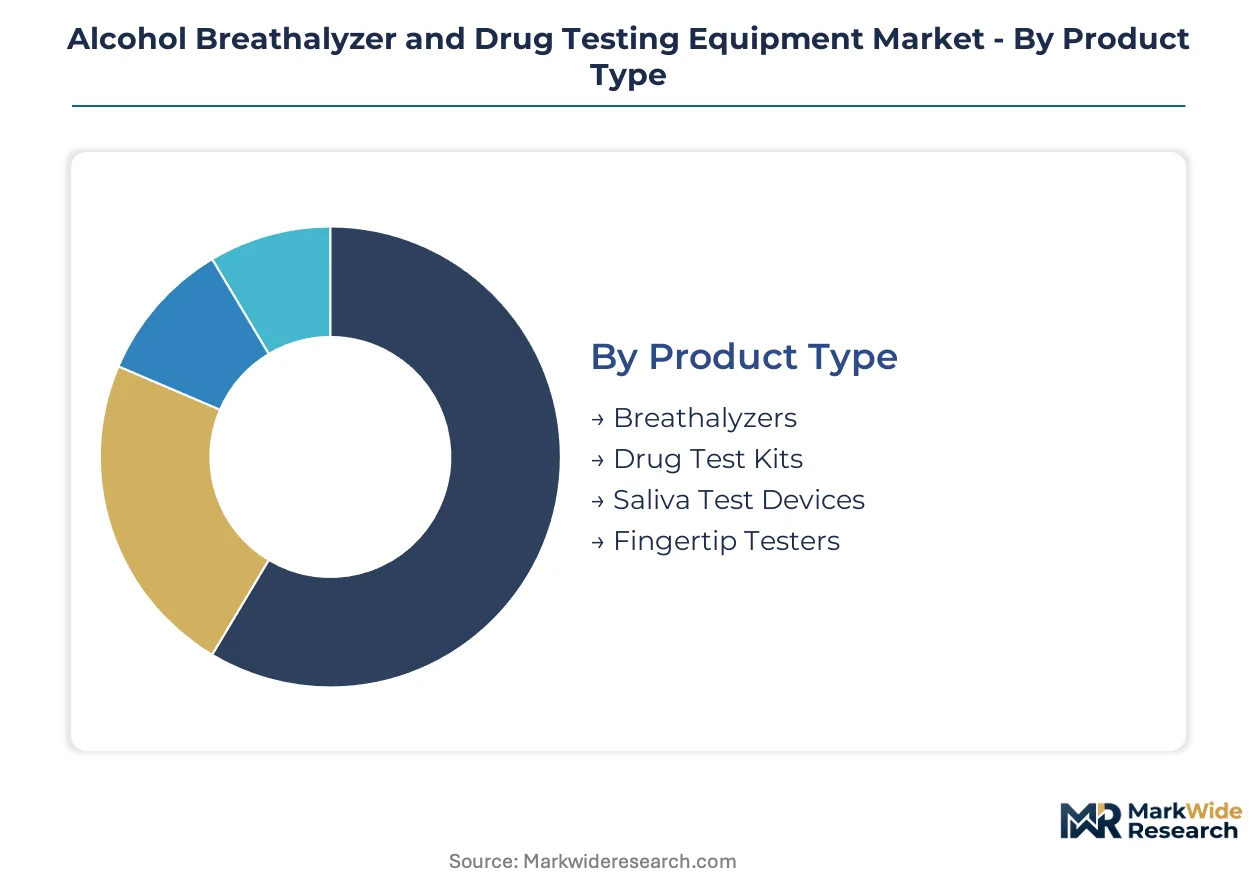
Segmentation in alcohol breathalyzer and drug testing equipment reveals how procurement authority fragments across safety, legal, and clinical functions. Technology tiers separate court-admissible precision from rapid-deployment economy, while end-user diversity creates parallel demand channels with incompatible compliance protocols.
Product Type:
Volume concentrates in disposable test formats, while premium margins attach to reusable precision systems with calibration infrastructure.
- Breathalyzers:Fuel cell and semiconductor sensor configurations detect blood alcohol concentration through electrochemical oxidation of breath samples. Law enforcement agencies in the United States mandate fuel cell models for evidential use under DOT 49 CFR Part 40, while workplace programs adopt lower-cost semiconductor variants for preliminary screening.
- Drug Test Kits:Immunoassay-based lateral flow cassettes detect multiple drug classes from urine samples with laboratory confirmation capability. Logistics fleets and construction contractors across Germany and France deploy these for pre-employment and random testing compliance with occupational safety regulations.
- Saliva Test Devices:Oral fluid collection systems eliminate medical technician requirements for rapid workplace deployment.
- Fingertip Testers:Compact semiconductor sensors target consumer and small-business economy tiers with limited accuracy.
Today's leader: Breathalyzers. Tomorrow's challenger: Saliva Test Devices.
Technology:
Cost tiers stratify sharply around platinum catalyst dependency and forensic certification requirements.
- Fuel Cell Technology:Electrochemical oxidation using platinum electrodes achieves specificity against acetone interference essential for court-admissible evidence. German law enforcement procurement specifications and United States DOT regulations institutionalize this technology for evidential applications, commanding premium pricing through calibration chain-of-custody requirements.
- Infrared Spectroscopy:Non-dispersive infrared absorption enables simultaneous multi-substance detection with laboratory-grade precision. Hospital emergency departments in Switzerland and Australia specify these systems for acute intoxication assessment where clinical diagnostic accuracy overrides cost considerations.
- Semiconductor Sensors:Metal oxide semiconductor technology occupies economy tiers with vulnerability to environmental interference.
- Chemical Sensor Technology:Colorimetric and enzymatic reactions support single-use disposable test formats.
Current premium concentration: Fuel Cell Technology. Steepest expansion trajectory: Infrared Spectroscopy.
End User:
Customer type determines compliance burden intensity and procurement committee composition.
- Law Enforcement:Police departments and highway patrol agencies require NHTSA-approved evidential breath testing devices with rigorous calibration documentation for prosecutorial admissibility. State-level procurement in the United States concentrates authority through centralized forensic laboratory certification programs.
- Industrial Safety:Manufacturing, logistics, and construction employers implement OSHA general duty clause compliance through random and post-incident testing programs. Multi-state operators face fragmentation from varying cannabis impairment thresholds across United States jurisdictions.
- Healthcare Providers:Hospital emergency departments and occupational health clinics demand FDA 510(k) cleared devices for clinical diagnostic integration.
- Educational Institutions:University and secondary school athletic programs adopt rapid saliva testing for substance abuse deterrence.
Dominant procurement volume: Industrial Safety. Emerging policy driver: Healthcare Providers.
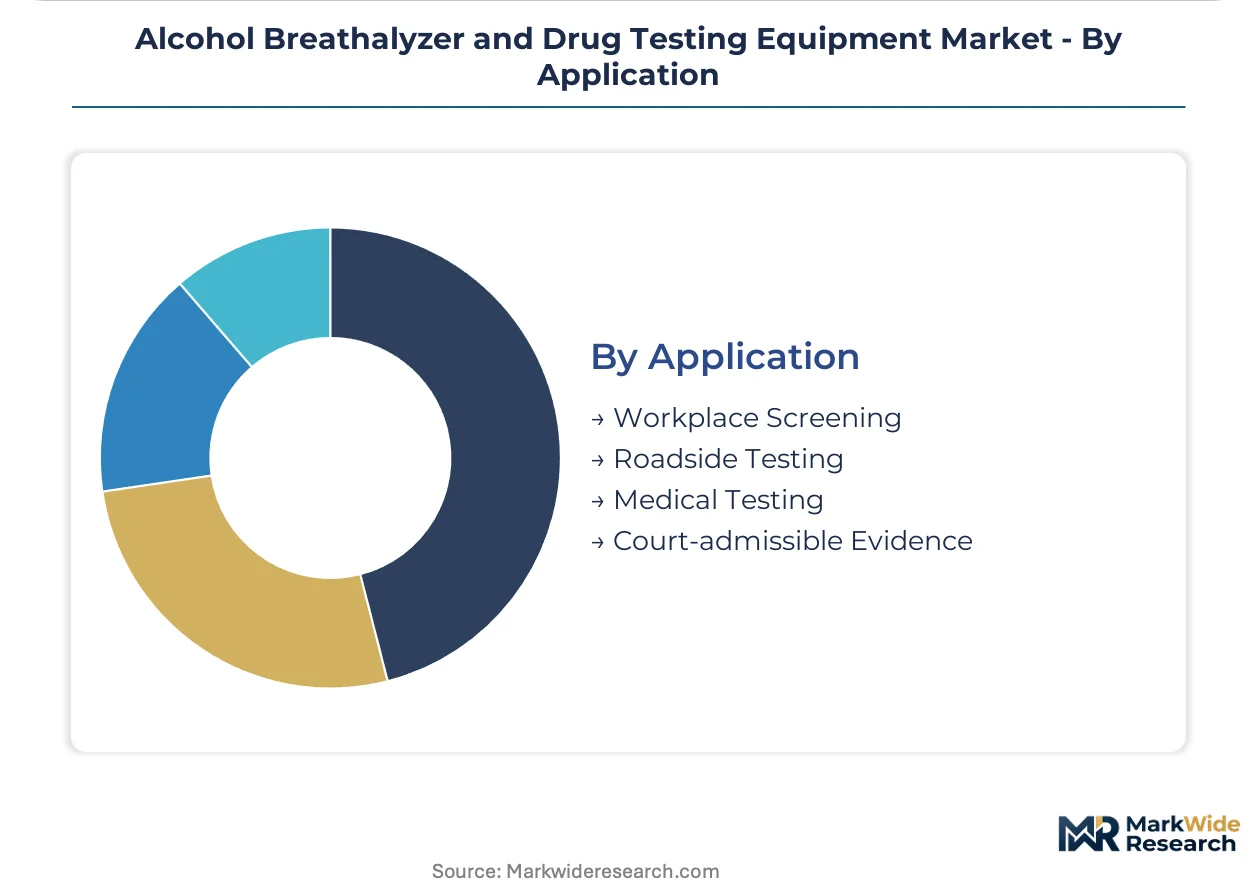
Application:
Margin structure inverts between high-frequency routine screening and low-volume forensic precision.
- Workplace Screening:Pre-employment, random, and post-incident testing programs across transportation, manufacturing, and energy sectors drive equipment replacement cycles. United States logistics conglomerates with multi-state terminal networks exhibit the most complex procurement committee structures splitting authority between risk management, human resources, and fleet operations.
- Court-admissible Evidence:Criminal justice applications demand strictest calibration chain-of-custody protocols creating barrier-protected revenue streams. Prosecutorial standards in Germany, France, and the United States require documented maintenance logs and certified technician administration.
- Roadside Testing:Traffic safety enforcement relies on portable preliminary breath test devices.
- Medical Testing:Clinical diagnostic applications require FDA 510(k) or EMA conformity assessment clearance.
Highest margin concentration: Court-admissible Evidence. Volume expansion: Workplace Screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers migrate production toward jurisdictions with streamlined medical device clearance pathways, exploiting cost-of-compliance gaps between FDA 510(k) and EMA conformity assessment timelines. Fuel cell sensor assembly concentrates where precision electronics clusters intersect with occupational health regulatory enforcement.
United States
DOT 49 CFR Part 40 mandates institutionalize replacement demand across transportation, aviation, and pipeline sectors. OSHA general duty clause enforcement drives employer liability investments in impairment detection systems. Dallas-Fort Worth logistics hubs deploy multi-site screening networks to comply with federal safety-sensitive employer requirements.
Germany
Industrial safety regulations under Arbeitsschutzgesetz expand workplace testing protocols across manufacturing and logistics employers. KBA certification requirements for evidential devices protect domestic engineering-intensive producers. Munich and Stuttgart automotive clusters integrate breathalyzer protocols into fleet safety management systems.
China
Road traffic safety law amendments intensify law enforcement procurement of roadside testing equipment. NMPA medical device registration pathways attract manufacturers seeking dual-use clinical and occupational health positioning. Shenzhen electronics manufacturing bases supply semiconductor sensor components to regional device assemblers.
Japan
METI industrial safety guidelines encourage pre-employment and random testing expansion across chemical and heavy manufacturing sectors. PMDA medical device approval requirements shape specifications for hospital emergency department adoption. Osaka precision instrument clusters sustain fuel cell electrode fabrication capabilities.
Australia
State-level workplace health and safety regulations mandate impairment screening across mining and construction operations. TGA medical device inclusion requirements filter clinical-grade product entry. Perth mining services corridors deploy ruggedized portable units for remote site compliance enforcement.
Alcohol Breathalyzer and Drug Testing Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue saliva-based rapid deployment formats and connected device architectures. Market structure stratifies around calibration infrastructure ownership, forensic certification depth, and healthcare regulatory clearance breadth. Three archetypes dominate: German-engineered precision specialists, North American integrated toxicology platform vendors, and Asian component-integrated assemblers. Competitive moves concentrate on multi-source fuel cell sensor procurement strategies and cloud-connected predictive maintenance service launches.
Among German-engineered precision specialists, Draeger occupies a position exemplifying premium law enforcement channel anchoring. Lifeloc Technologies and Abbott represent contrasting archetypes within North American market positioning—one emphasizing in-house manufacturing and calibration capabilities, the other spanning healthcare diagnostic and workplace screening segments through integrated platform breadth. These three anchors illustrate how geographic origin and organizational structure shape competitive differentiation without converging on identical capability bundles.
| Leading Market Players |
|---|
| Lifeloc Technologies |
| Lion Laboratories |
| Draeger |
| C4 Development |
| Quest Products |
| Abbott |
| BACtrack |
| Alcohol Countermeasure Systems |
| Intoximeters |
| Others |
Supply Flow & Price Mechanics
Family-owned precision instrument specialists in Germany and Japan anchor premium tier pricing through captive calibration service networks, while private-equity-rolled-up North American distributors compress margins on economy-tier semiconductor devices through volume aggregation. This ownership fragmentation creates divergent supply behaviors: engineering heritage producers defend pricing through forensic certification depth, while financial buyers prioritize inventory velocity over technical service bundling.
Pricing Analysis
Distributor margin layers absorb 25-40 points on fuel cell breathalyzers sold through law enforcement channels, while direct-to-OEM contracts for fleet operators trade price for multi-year calibration service lock-in. Pricing stratifies across evidential-grade fuel cell systems, workplace semiconductor screening devices, and disposable saliva test formats, with platinum catalyst cost pass-throughs squeezing mid-tier manufacturers most acutely. Fleet procurement committees exhibit highest price sensitivity, whereas forensic laboratories prioritize calibration chain-of-custody reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale logistics fleet demand, while medical device distributors manage hospital emergency department procurement with FDA 510(k) clearance documentation. Fuel cell electrode fabrication concentrates in Japan and Germany, with platinum group metal sourcing tethered to South African and Russian mining output. Semiconductor sensor assembly draws from Shenzhen electronics clusters. Single-source dependency on Japanese precision component suppliers creates vulnerability to METI export licensing delays. Distribution runs through certified technician networks for evidential devices, bypassing traditional industrial distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alcohol breathalyzer and drug testing equipment market functions as a stable compounder, with DOT 49 CFR Part 40 mandates institutionalizing replacement demand across safety-sensitive employers regardless of economic cycle position.
For Market Incumbents: To counter margin compression from platinum catalyst cost volatility, deepen backward integration into fuel cell electrode fabrication or secure long-term offtake agreements with South African platinum suppliers. Fortify position by converting hardware sales into recurring calibration service subscriptions through cloud-connected device monitoring, locking out independent service competitors. For New Entrants and Emerging Players: OSHA general duty clause enforcement in United States industrial settings opens a window for saliva-based rapid deployment formats that bypass certified technician requirements. Target mid-sized construction and warehousing employers in cannabis-legal states where impairment threshold confusion fragments incumbent zero-tolerance policy enforcement. Lead with subscription pricing that unbundles hardware from consumables and software, mirroring enterprise SaaS procurement patterns. For Investors and Strategic Acquirers: Valuations sit cheapest among North American distributors with stranded semiconductor inventory exposure as fuel cell costs decline toward parity. Focus on calibration infrastructure owners with forensic laboratory certification relationships, which generate annuity-like revenue streams insulated from hardware price erosion. Watch state-level cannabis per se impairment threshold standardization as the signal for policy clarity that would accelerate employer testing program adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Cell Sensor Multi-Sourcing | Diversification beyond Japanese suppliers mitigates METI licensing risk for Draeger and Lifeloc. |
| Saliva Test Platform Launch | Oral fluid formats bypass medical technician requirements, opening mid-market employer segments. |
| Cloud-Connected Calibration Service | Predictive maintenance alerts convert capital equipment sales into recurring revenue streams. |
| FDA 510(k) Clearance Pathway | Medical-grade positioning enables hospital emergency department adoption for acute intoxication assessment. |
| Integrated Toxicology Platform Expansion | Modular pricing unbundles hardware, consumables, and software to match fragmented procurement committee authority. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with breath alcohol technician training program directors, forensic laboratory certification managers, fleet safety compliance officers, and hospital emergency department purchasing committees with secondary validation against FDA 510(k) clearance databases, DOT Office of Drug and Alcohol Policy and Compliance guidance documents, OSHA enforcement action records, and state-level cannabis impairment threshold legislation. Bottom-up equipment unit demand estimates and top-down market value reconstructions were triangulated for consistency.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation modeling spanning technology tier, end-user compliance burden intensity, application format, and regional regulatory framework cluster. CAGRs were derived from equipment replacement cycle analysis, regulatory mandate expansion timelines, and employer liability litigation trend patterns. Platinum group metal price volatility coefficients and forensic technician training program enrollment rates served as industry-specific forecast sensitivity inputs.
Revisions become necessary when state-level cannabis impairment threshold standardization accelerates, platinum supply disruptions from South African mining labor actions materialize, or FDA 510(k) clearance pathways for novel sensing modalities shift materially. Forecasts reflect documented assumptions regarding DOT mandate enforcement continuity and employer litigation exposure trends. Periodic stress-testing of base assumptions against OSHA general duty clause precedent evolution and fuel cell cost decline curves is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
D-Dimer Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Test Strips Market
Testing Services
Tablet Hardness Testers Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
US Pharmaceutical Sterility Testing Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Anderson Cascade Impactor Market
Testing Services
Global Bioburden Testing Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Global Legionella Testing Market
Testing Services
West Nile Virus Testing Market