
 Biological Indicator Vials Market | 2026-2036
Biological Indicator Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Indicator Vials Market Outlook
Aftermarket service revenue is reshaping profit pools as instrument manufacturers bundle calibration and requalification with vial consumables. 3M Company leverages its installed base of sterilization equipment to sustain recurring vial sales across North American hospital networks. Mesa Laboratories anchors its position through specialized biological indicator manufacturing for pharmaceutical quality control labs.
Biological indicator vials are sealed glass or plastic containers housing standardized bacterial spore populations, typically Bacillus atrophaeus or Geobacillus stearothermophilus, designed to verify sterilization cycle lethality in steam, ethylene oxide, or hydrogen peroxide environments. Self-contained vials dominate unit volume by integrating growth media directly within the vessel, eliminating external transfer steps and reducing contamination risk. Spore strips retain relevance in legacy pharmaceutical validation protocols where customers require direct inoculation into custom broth formulations.
FDA enforcement of ISO 11138 standards for biological indicator performance elevates compliance costs for manufacturers seeking 510(k) clearance, while EMA's Annex 1 revision on sterile manufacturing drives European pharmaceutical companies toward more frequent sterilization verification cycles. The EU Medical Device Regulation imposes additional conformity assessment requirements on vial suppliers serving device sterilization facilities. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP biological indicator chapters to anticipate specification convergence or divergence that could reshape product portfolios.
Market Dynamics
FDA enforcement of ISO 11138 performance standards is compressing manufacturer margins while forcing consolidation among vial suppliers seeking 510(k) clearance for sterilization validation products.
Growth Catalysts
- EMA Annex 1 Revision:The European Medicines Agency's sterile manufacturing guidance mandates more frequent sterilization verification cycles, expanding biological indicator consumption across pharmaceutical quality control labs in Germany, France, and Italy.
- Self-Contained Vial Technology:Integrated growth media designs eliminate external transfer contamination risks, accelerating hospital adoption for steam sterilization monitoring in acute care settings.
- United States:Joint Commission accreditation requirements for biological indicator use in hospital sterilization departments create mandatory replacement demand across 6,000+ acute care facilities.
Market Restraints
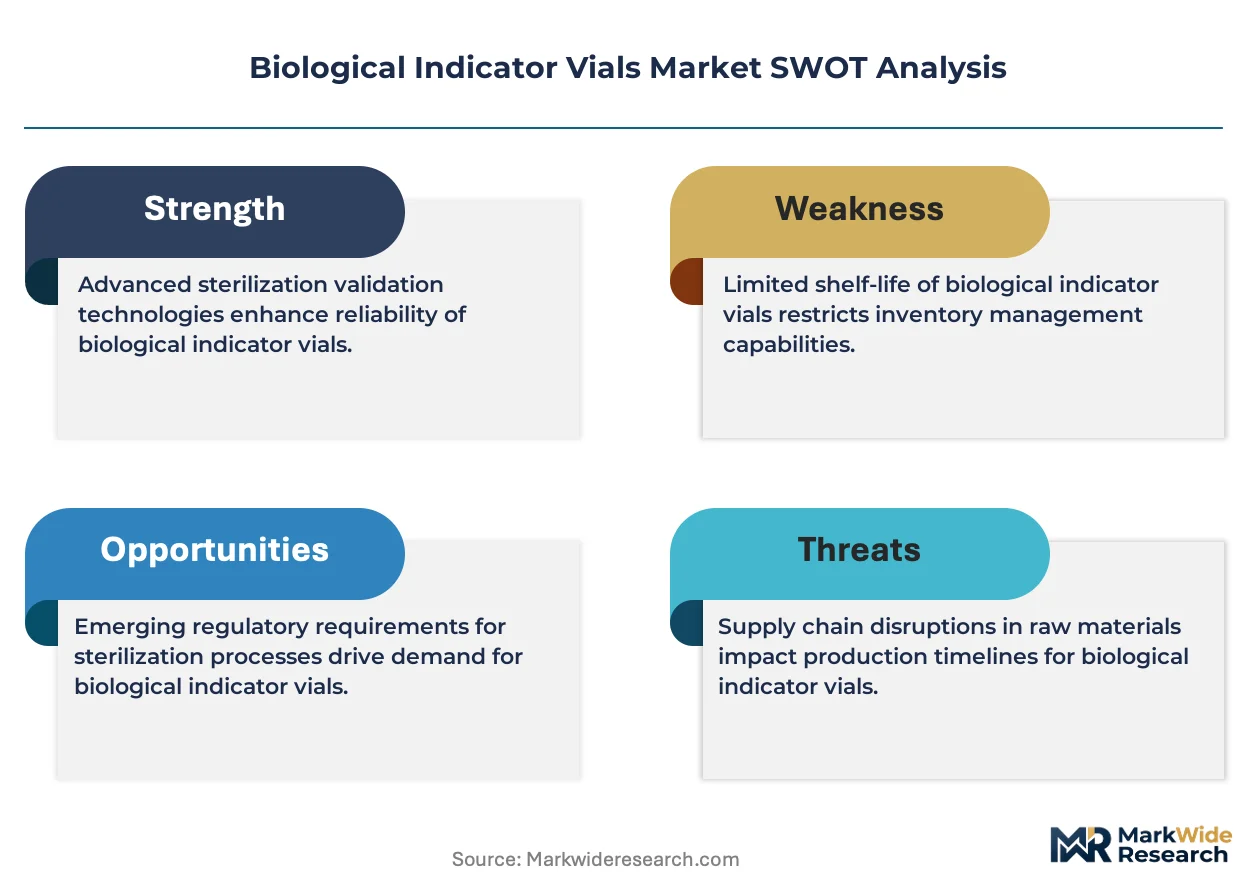
- Glass Supply Concentration:Borosilicate glass vial sourcing depends on limited European and North American specialty glass manufacturers, exposing producers to input volatility and geographic supply disruption.
- Spore Strip Substitution:Legacy pharmaceutical validation protocols retain direct inoculation methods using Geobacillus stearothermophilus strips, slowing self-contained vial penetration in established manufacturing sites.
- EU MDR Conformity Costs:The Medical Device Regulation imposes additional conformity assessment burdens on vial suppliers serving device sterilization facilities, elevating compliance overhead for mid-tier manufacturers.
Strategic Opportunities
- India Pharmaceutical Manufacturing:CDSCO regulatory alignment with international sterilization standards creates entry pathways for biological indicator suppliers as domestic vaccine and injectable production scales.
- Hydrogen Peroxide Vapor Applications:Isolator and restricted access barrier systems in aseptic filling lines require specialized Bacillus atrophaeus indicators, opening premium product segments beyond traditional steam monitoring.
- Direct-to-Laboratory Distribution:E-commerce platforms serving hospital central sterile supply departments and pharmaceutical QC labs are compressing traditional distributor markups and enabling vial manufacturers to capture margin.
Industry Challenges
- Spore Crop Cultivation Expertise:Standardized Bacillus and Geobacillus spore production requires specialized microbiological capabilities that concentrate among limited contract manufacturers, creating supply bottlenecks.
- Pharmacopeial Harmonization Delays:Divergent USP, EP, and JP biological indicator chapters force manufacturers to maintain multiple product specifications, complicating inventory management and regulatory filing strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Indicator Vials Market |
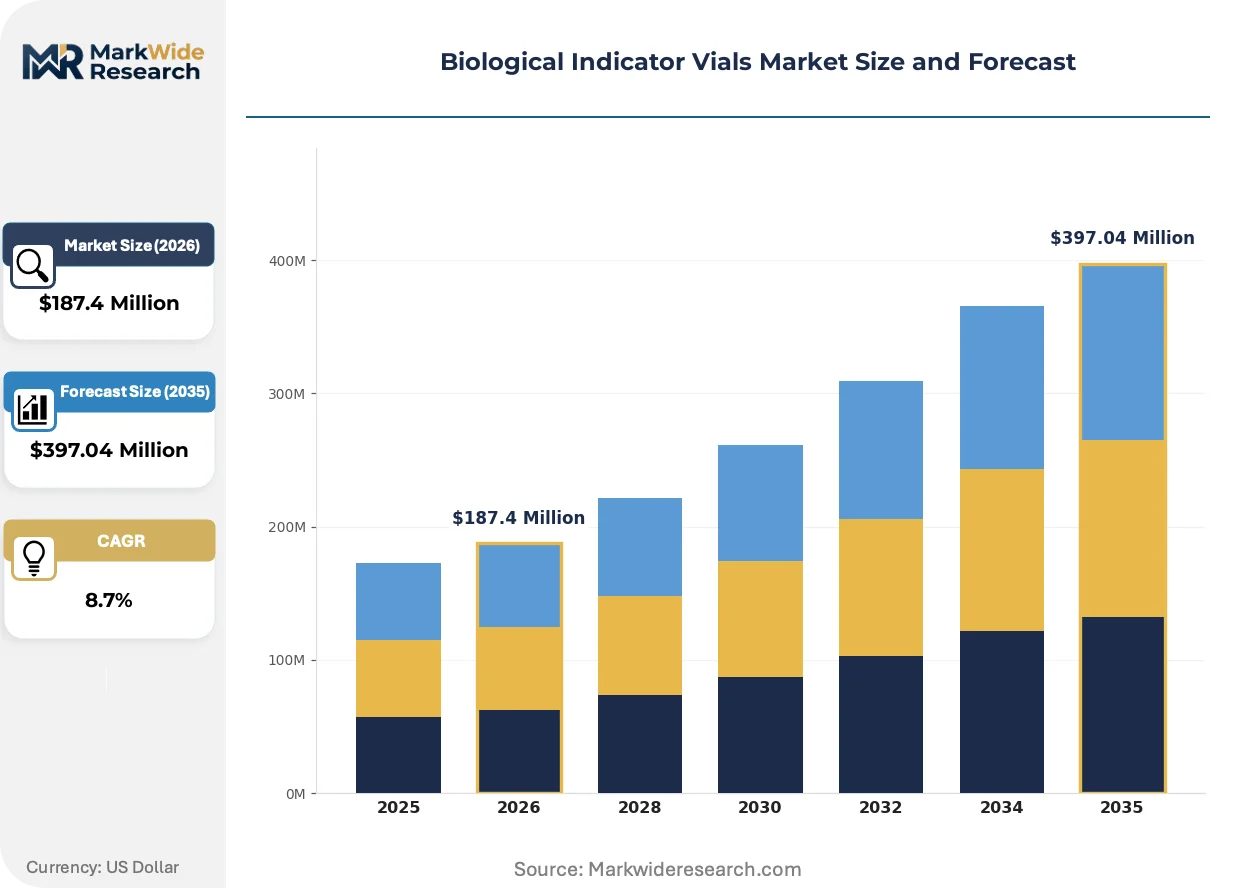
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Contained Vials, Spore Strips, Prepared Media, Custom Vials Application: Sterilization Monitoring, Quality Control, Product Validation, Environmental Testing End User: Laboratories, Hospitals, Pharmaceutical Companies, Research Institutions Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | 3M Company, STERIS plc, Mesa Laboratories, Inc., Getinge AB, bioMerieux SA, VWR Corporation, Ecolab, Solventum, Cantel Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Indicator Vials Market Strategic Shifts
Digital integration is transforming biological indicator verification from manual incubation and visual reading to automated detection systems that compress result turnaround times and eliminate human interpretation error.
Rapid microbial detection platforms incorporating fluorescence-based spore viability assessment are digitizing sterilization validation workflows. Pharmaceutical manufacturers with high-throughput sterilization cycles are adopting these systems to reduce incubation periods from seven days to under twenty-four hours. This compression is digitizing quality control staffing models and enabling real-time release decisions for aseptic production batches.
The FDA's 2023 guidance on aseptic processing and sterilization validation is elevating documentation requirements for biological indicator lot certificates of analysis. Manufacturers must now provide expanded spore population data and D-value verification traceable to ISO 17025-accredited laboratories. Pharmaceutical contract manufacturing organizations in the United States are responding by mandating supplier qualification audits that extend upstream to spore crop cultivation facilities.
Hospital central sterile supply departments are consolidating vendor relationships to reduce qualification overhead, favoring suppliers offering bundled indicator portfolios across steam, ethylene oxide, and vaporized hydrogen peroxide modalities. This concentration is visible most acutely in United States health systems exceeding 500 beds, where procurement functions now mandate single-source contracts for all sterilization monitoring consumables.
Biological Indicator Vials Market Segmentation
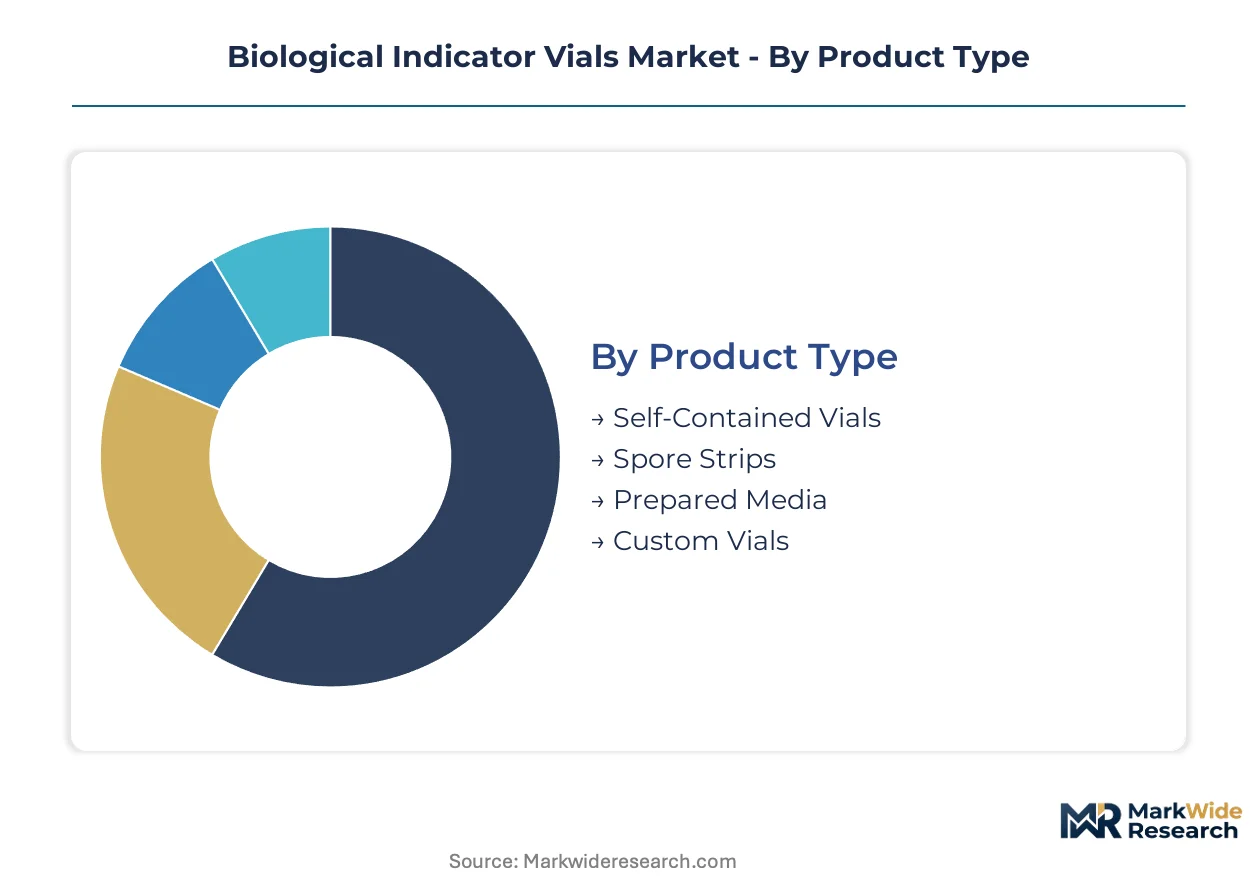
Biological indicator vials serve distinct sterilization verification workflows across healthcare and pharmaceutical manufacturing. Segmentation reveals how product form factors, application intensity, and procurement channels reshape vendor competitive positioning and margin capture.
Product Type:
Mature formats dominate hospital procurement while emerging designs penetrate pharmaceutical validation protocols.
- Self-Contained Vials:These sealed units integrate Bacillus atrophaeus or Geobacillus stearothermophilus spores with sterile growth media in a single vessel, eliminating transfer steps that risk contamination. Hospital central sterile supply departments in the United States drive replacement demand through Joint Commission-mandated steam sterilization monitoring programs.
- Spore Strips:Paper or cellulose carriers impregnated with standardized spore populations require external inoculation into custom broth formulations. Legacy pharmaceutical manufacturing sites in Germany and France retain these strips for ethylene oxide validation cycles where direct media transfer remains protocol-specified.
- Prepared Media:Pre-sterilized broth tubes and ampoules packaged separately from biological indicators streamline workflow for laboratories processing high volumes of spore strip tests.
- Custom Vials:Specialty configurations with modified spore populations or alternative container geometries serve isolator and restricted access barrier system manufacturers.
Self-contained vials retain volume leadership; custom vials hold the steepest expansion curve.
Application:
Cost tier differentiation separates high-frequency monitoring consumables from capital-intensive validation services.
- Sterilization Monitoring:Routine verification of steam, ethylene oxide, and vaporized hydrogen peroxide cycles in hospital and pharmaceutical production environments. United States acute care facilities generate recurring demand through accreditation-mandated cycle documentation.
- Quality Control:Lot release testing and in-process verification for sterile drug manufacturing. EMA Annex 1 revision drives European pharmaceutical companies toward expanded biological indicator consumption in Germany, France, and Italy.
- Product Validation:Initial qualification of sterilization equipment and process development studies for new aseptic manufacturing lines.
- Environmental Testing:Assessment of cleanroom and isolator decontamination efficacy in pharmaceutical filling operations.
Sterilization monitoring commands the largest revenue base; quality control applications are expanding most quickly.
End User:
Customer type determines pricing power and contract structure across the procurement landscape.
- Laboratories:Independent testing facilities and pharmaceutical quality control labs process biological indicators as part of sterilization validation services. ISO 17025 accreditation requirements elevate supplier qualification barriers.
- Hospitals:Central sterile supply departments in United States health systems exceeding 500 beds consolidate vendor relationships to reduce qualification overhead, favoring bundled indicator portfolios.
- Pharmaceutical Companies:Sterile drug manufacturers and contract manufacturing organizations mandate expanded lot certificate documentation under FDA guidance.
- Research Institutions:Academic medical centers and biotechnology incubators utilize biological indicators for protocol development and equipment qualification.
Hospitals anchor volume demand; pharmaceutical companies deliver the steepest margin expansion.
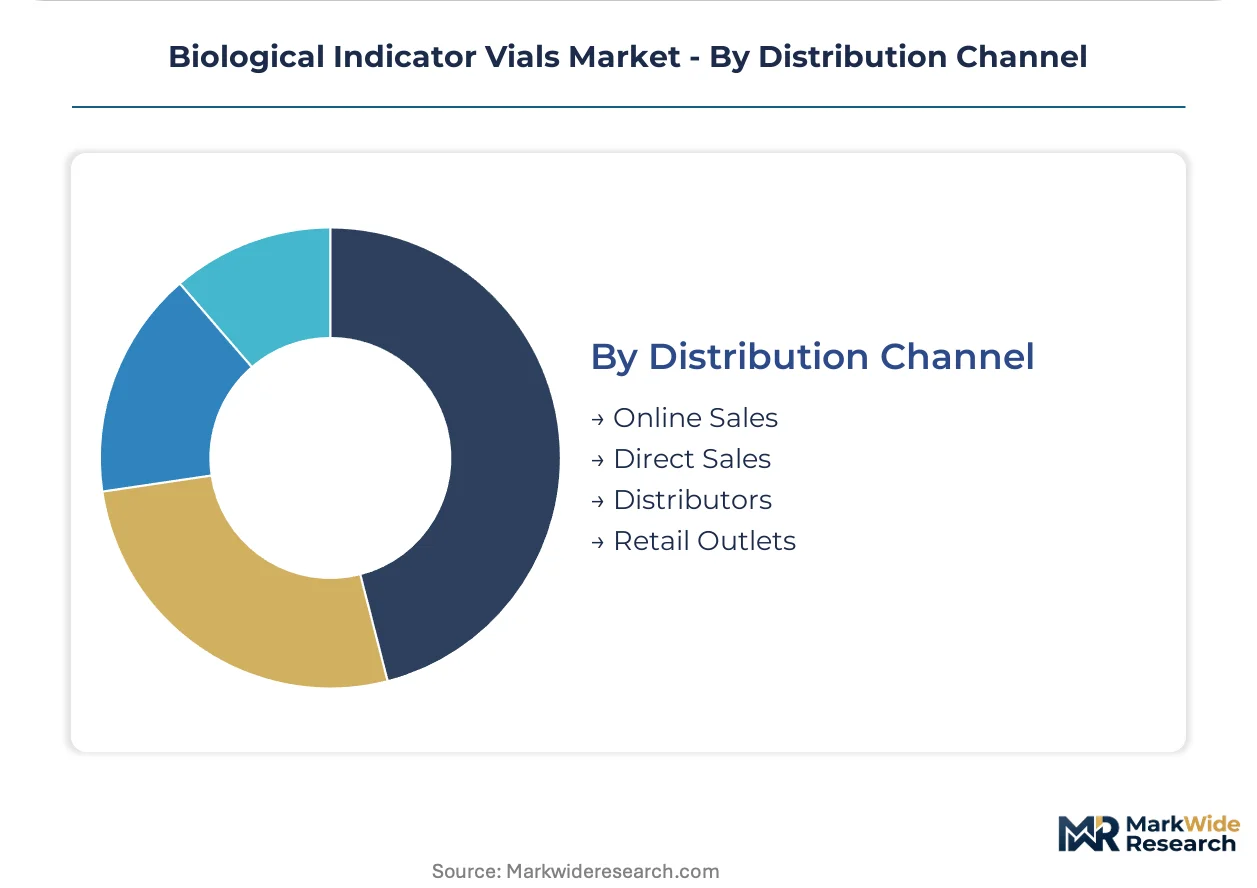
Distribution Channel:
Supply concentration varies by customer scale and geographic reach.
- Online Sales:E-commerce platforms serving hospital central sterile supply departments compress traditional distributor markups and enable manufacturers to capture margin directly.
- Direct Sales:Manufacturer field representatives manage large pharmaceutical accounts with complex technical qualification requirements and multi-site contracts.
- Distributors:Regional medical supply intermediaries serve mid-tier hospitals and laboratories with consolidated procurement functions.
- Retail Outlets:Limited penetration through scientific supply catalogs for research and educational institutions with sporadic purchasing patterns.
Distributors retain volume leadership; online sales channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States hospitals favor self-contained vials for steam sterilization monitoring, while European pharmaceutical manufacturers retain spore strips for ethylene oxide validation protocols. Asian markets are accelerating adoption of rapid-readout technologies for high-throughput sterilization cycles.
United States
Joint Commission accreditation mandates drive replacement demand across 6,000-plus acute care facilities. FDA enforcement of ISO 11138 performance standards elevates compliance costs for vial suppliers seeking 510(k) clearance. The Boston-Cambridge pharmaceutical cluster consumes specialized indicators for aseptic processing validation in contract manufacturing organizations.
Germany
EMA Annex 1 revision on sterile manufacturing expands biological indicator consumption in quality control laboratories. The country's national pharmaceutical regulator enforces strict documentation requirements for sterilization validation protocols. The Rhine-Main region hosts concentrated pharmaceutical manufacturing where legacy spore strip protocols persist in ethylene oxide cycle verification.
India
CDSCO regulatory alignment with international sterilization standards creates entry pathways as domestic vaccine and injectable production scales. The national pharmaceutical regulator mandates biological indicator use in sterilization validation for export-oriented facilities. The Hyderabad-Visakhapatnam corridor concentrates injectable manufacturing where quality control labs are upgrading from manual to automated indicator reading systems.
Japan
PMDA guidance on aseptic processing elevates documentation requirements for biological indicator lot certificates of analysis. METI industrial standards promote harmonization with ISO 11138 for sterilization validation products. The Kansai pharmaceutical cluster around Osaka maintains rigorous spore population verification protocols for legacy manufacturing sites.
France
ANSM oversight of sterile manufacturing drives adoption of rapid microbial detection platforms in pharmaceutical quality control. The national pharmaceutical regulator enforces EMA Annex 1 compliance through facility inspection programs. The Lyon-Grenoble biotechnology corridor generates demand for specialized indicators in isolator and restricted access barrier system validation.
Biological Indicator Vials Market Competitive Environment
Capability concentration sits with specialized microbiological cultivators; scale advantage sits with diversified sterilization equipment manufacturers. The market structures around three tiers: integrated hospital supply conglomerates with bundled indicator portfolios, dedicated biological indicator specialists with spore crop expertise, and regional distributors serving mid-tier laboratories. Consolidation pressure intensifies as FDA 510(k) clearance requirements compress margins for smaller suppliers. Dominant competitive moves include backward integration into spore cultivation capabilities and strategic partnerships with rapid-readout detection platform developers.
Among diversified healthcare conglomerates, 3M Company and STERIS plc exemplify the equipment-anchored model that sustains recurring vial sales through installed base leverage. Mesa Laboratories, Inc. occupies a position within the specialist tier, representing the concentrated microbiological capability that pharmaceutical quality control laboratories require for validation protocols. These three entities illustrate the competitive tension between scale-driven bundling and expertise-driven specialization that defines vendor positioning.
| Leading Market Players |
|---|
| 3M Company |
| STERIS plc |
| Mesa Laboratories, Inc. |
| Getinge AB |
| bioMerieux SA |
| VWR Corporation |
| Ecolab |
| Solventum |
| Cantel Medical Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European borosilicate glass manufacturing is compressing input costs while simultaneously eroding supplier pricing power, forcing vial manufacturers to absorb ISO 17025 certification investments without full pass-through to hospital and pharmaceutical customers.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between large United States health systems and sterilization equipment manufacturers, locking in recurring vial volumes at fixed unit prices. Price differentiation separates FDA 510(k)-cleared premium tiers from standard ISO 11138-compliant products, with certification investment acting as the primary margin wedge. Pricing pressure stems from Joint Commission-mandated replacement cycles that commoditize base-grade steam sterilization indicators. Hospital central sterile supply departments exhibit highest price sensitivity, while pharmaceutical quality control labs prioritize lot certificate traceability over unit cost.
Supply Chain Analysis
Extended payment terms from United States health system procurement functions are squeezing working capital for mid-tier vial manufacturers without spore cultivation capabilities. Geographic supply concentration draws from Germany and France for specialty borosilicate glass, India for contract spore crop production, and the United States for ISO 17025-accredited testing services. Raw material dependencies rest on standardized Bacillus atrophaeus and Geobacillus stearothermophilus spore populations, sterile growth media formulations, and pharmaceutical-grade container sealing components. Single-source vulnerability in contract spore cultivation creates supply bottlenecks. Distribution runs through consolidated e-commerce platforms serving hospital networks and direct manufacturer relationships with pharmaceutical quality control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rapid-readout detection platform interoperability is creating platform-economics dynamics where vial manufacturers must embed digital compatibility to retain hospital procurement contracts.
For Market Incumbents: Harden spore crop cultivation capabilities through backward integration into contract microbiological production facilities, eliminating single-source dependency on limited cultivators. Defend installed base relationships by bundling calibration services with vial consumables to increase switching costs for United States health systems facing Joint Commission audits. ISO 11138 compliance investment acts as the primary defensive lever against mid-tier competitors seeking 510(k) clearance. For New Entrants and Emerging Players: Establish a beachhead in hydrogen peroxide vapor indicator segments for isolator and restricted access barrier system manufacturers, where specialized Bacillus atrophaeus configurations command premium positioning. Target CDSCO-aligned pharmaceutical quality control laboratories in India as regulatory harmonization creates entry pathways without legacy spore strip protocol entrenchment. Direct-to-laboratory e-commerce distribution offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward microbiological cultivation specialists with captive spore populations and ISO 17025-accredited testing infrastructure. Long-term viability across the analysis window favors assets with regulatory certification moats rather than undifferentiated vial assembly capacity. The signal to watch is FDA enforcement intensity against non-compliant sterilization validation products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spore Cultivation | Eliminates single-source vulnerability in Bacillus and Geobacillus supply for vial manufacturers. |
| Rapid-Readout Platform Partnership | Secures interoperability with automated fluorescence detection systems in pharmaceutical QC labs. |
| CDSCO Regulatory Alignment Investment | Opens entry pathways into Indian vaccine and injectable manufacturing quality control workflows. |
| Direct-to-Laboratory E-Commerce Launch | Captures margin compression from traditional distributor markups in hospital central sterile supply. |
| Hydrogen Peroxide Vapor Product Line Extension | Addresses isolator validation demand from aseptic filling line manufacturers in biotechnology corridors. |
Study Parameters
A spread of perspectives from sterilization validation managers at pharmaceutical contract manufacturing organizations, hospital central sterile supply directors, biological indicator quality control leads, and FDA regulatory affairs specialists converged on the working assumptions. Primary interview insights were cross-referenced against FDA 510(k) clearance databases, EMA Annex 1 guidance documents, ISO 11138 performance standard filings, and hospital procurement contract disclosures. Bottom-up vial volume estimates from end-user consumption patterns were triangulated with top-down sterilization equipment installed base analysis.
Demand-supply balance modeling across the projection horizon calibrated biological indicator consumption rates against pharmaceutical manufacturing capacity expansion and hospital accreditation cycle frequencies. Segmentation dimensions included product form factor, sterilization modality, end-user archetype, and geographic regulatory cluster. CAGRs were derived from sterilization validation intensity trends and replacement cycle documentation requirements. Spore population standardization protocols and rapid microbial detection platform adoption curves served as industry-specific forecast inputs.
Stress conditions across borosilicate glass supply disruption, FDA enforcement intensity variation, and pharmacopeial harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and technology substitution patterns. Macroeconomic contraction, unilateral regulatory divergence, or breakthrough sterilization validation technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Urodynamic Testing Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Apoptosis Testing Market
Testing Services
Creatinine Testing Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Global Anti Thrombin III Testing Market