
 Rapid Sterility Testing Market | 2026-2036
Rapid Sterility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Sterility Testing Market Outlook
Platform licensing revenue is reconfiguring margin pools away from standalone consumables toward integrated automation ecosystems. Thermo Fisher Scientific leverages its end-to-end laboratory workflow portfolio to anchor recurring service contracts across pharmaceutical quality control labs. Charles River Laboratories competes through specialized biologics testing capacity, while Sartorius AG dominates membrane filtration hardware with upstream control over single-use bioprocessing consumables.
Rapid sterility testing encompasses accelerated microbiological detection methods that replace fourteen-day compendial incubation with bioluminescence, PCR amplification, or colorimetric signal detection, typically delivering definitive results within five days for pharmaceutical and biologic products. Membrane filtration systems retain the largest installed base among product types due to regulatory familiarity, though PCR technology captures the fastest expansion as nucleic acid detection sensitivity improves for cell therapy and gene therapy matrices. Pharmaceutical applications absorb the majority of current spending, while biologics manufacturing generates the steepest growth trajectory driven by accelerated batch release requirements for temperature-sensitive therapeutics.
FDA sterility testing guidance, EU GMP Annex 1, and USP Chapter 1223 collectively mandate method equivalence demonstrations that elevate barriers for novel platform entry while creating compliance-driven replacement cycles. The European Medicines Agency and Japan's PMDA maintain aligned but distinct validation frameworks that fragment approval pathways for multinational biopharma sponsors. Stakeholders must monitor harmonization progress between pharmacopeial standards and instrument-specific validation protocols to anticipate capital deployment timing for platform conversions.
Market Dynamics
Batch release timeline compression is forcing pharmaceutical manufacturers to abandon fourteen-day compendial incubation in favor of bioluminescence and nucleic acid detection platforms that compress sterility confirmation to seventy-two hours.
Growth Catalysts
- EU GMP Annex 1 revisions:The updated contamination control requirements mandate risk-based sterility assurance programs that accelerate validation of rapid microbiological methods across sterile manufacturing facilities in Germany and France.
- Cell therapy manufacturing:Autologous CAR-T production in Boston and San Diego clusters requires same-day sterility feedback loops that membrane filtration and ATP bioluminescence platforms uniquely satisfy.
- PCR sensitivity improvements:Real-time nucleic acid amplification now detects slow-growing contaminants in complex biologic matrices previously invisible to traditional culture methods.
Market Restraints
- Validation cost structure:FDA method equivalence studies for alternative sterility platforms demand parallel testing against USP Chapter 71 across twelve to eighteen months, elevating capital barriers for mid-tier contract manufacturers.
- Consumables supply concentration:Single-use filtration membranes and PCR reagents depend on polymer supply chains concentrated in Bavaria and North Rhine-Westphalia, exposing buyers to input volatility.
- Technical detection limits:ATP bioluminescence generates false positives from residual product matrix interference in protein-rich gene therapy formulations, constraining platform applicability.
Strategic Opportunities
- Japanese biologics expansion:PMDA accelerated approval pathways for regenerative medicines in Kobe and Osaka bioclusters create demand for localized rapid sterility validation services.
- Continuous manufacturing integration:Real-time release testing architectures for perfusion bioreactors require inline sterility monitoring systems that merge spectroscopic sensors with automated sampling robotics.
- ISO 17025 laboratory accreditation:Third-party testing facilities pursuing international quality standards can capture outsourced validation work from multinational sponsors seeking harmonized multi-site data packages.
Industry Challenges
- Microbiology talent scarcity:Rapid method specialists with combined expertise in molecular biology and GMP compliance command premium compensation in Basel and Cambridge labor markets, constraining facility expansion timelines.
- Legacy system integration:Paper-based batch records and isolated laboratory information management systems resist seamless data capture from automated sterility platforms, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Sterility Testing Market |
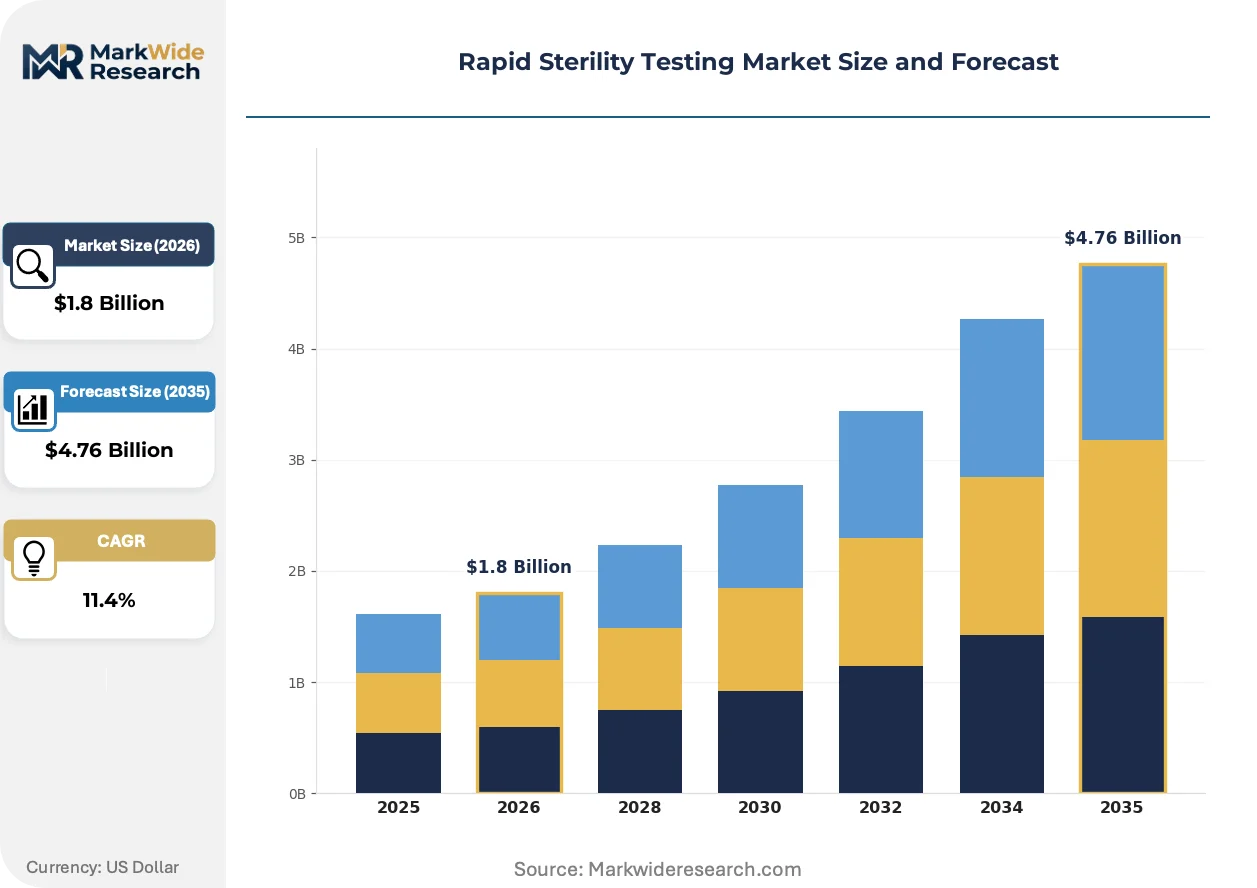
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Media Fill, Membrane Filtration, Automation Systems, Rapid Test Kits Technology: Bioluminescence, PCR, Colorimetric, Fluorescent Application: Pharmaceuticals, Biologics, Medical Devices, Research Laboratories End User: Contract Manufacturing Organizations, Hospitals, Pharmaceutical Companies, Academic Institutions |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, Charles River Laboratories, Rapid Micro Biosystems, Nelson Laboratories, SGS SA, Sartorius AG, BD, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Sterility Testing Market Strategic Shifts
Digital validation architectures and nucleic acid detection sensitivity gains are collapsing the traditional separation between manufacturing execution and quality control functions in sterile drug production.
Isothermal amplification technologies, including loop-mediated amplification and recombinase polymerase amplification, are virtualizing sterility confirmation by enabling instrument-free detection of bacterial and fungal contaminants at ambient temperatures. Gene therapy manufacturers in Maryland and North Carolina are deploying these platforms at point-of-use to bypass centralized laboratory bottlenecks. The technology is virtualizing capital allocation patterns, shifting investment from fixed analytical infrastructure toward distributed, disposable assay cartridges.
EMA's 2022 revision to the guideline on the sterilization of medicinal products introduced explicit recognition of parametric release for terminally sterilized products, creating precedent for alternative sterility assurance strategies. Sterile injectable manufacturers in Ireland and the Netherlands are restructuring validation protocols to leverage process analytical technology data in lieu of end-point testing. Small-molecule parenteral facilities face the steepest compliance recalibration as they retrofit legacy isolator lines for continuous monitoring architectures.
Consolidated procurement of sterility testing services through single-source quality agreements is displacing transactional relationships between pharmaceutical sponsors and contract testing laboratories. Large biopharma sponsors in New Jersey and California are bundling rapid sterility validation with broader release testing portfolios, compressing vendor rosters from twelve to three preferred partners. The shift is most pronounced among cell therapy developers where batch failure costs exceed analytical service fees by orders of magnitude.
Rapid Sterility Testing Market Segmentation
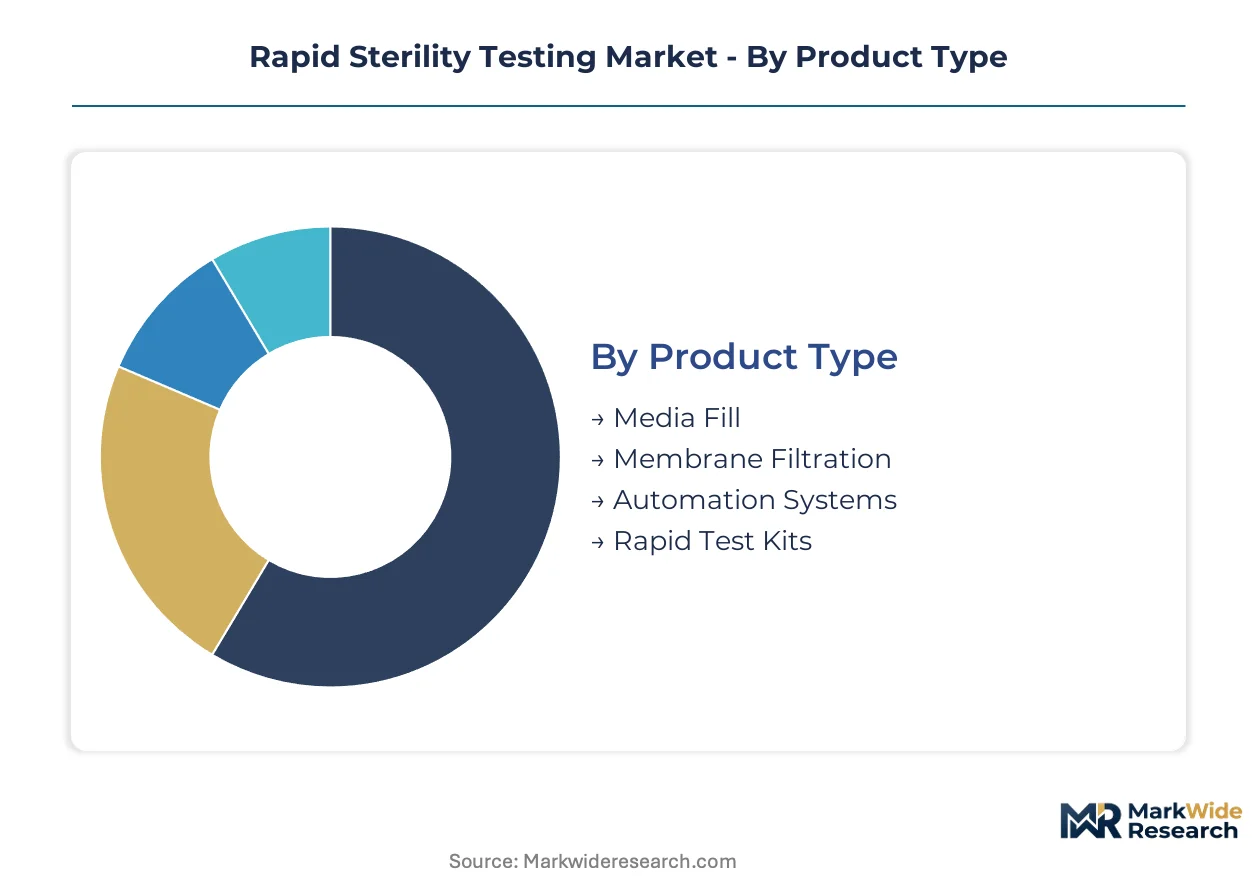
Segmentation in rapid sterility testing reveals divergent technology maturity curves and validation burden distributions across product architectures. Platform selection directly determines capital deployment patterns, regulatory pathway complexity, and service contract structures for quality control operations.
Product Type:
Membrane filtration retains regulatory precedence across sterile injectable workflows, while automation systems capture investment flows from continuous manufacturing retrofits.
- Membrane Filtration:Physical retention of microorganisms on porous membranes followed by culture-based detection remains the compendial reference method. Pharmaceutical facilities in Germany and the United States maintain the largest installed bases, though twelve-to-eighteen-month validation timelines constrain replacement cycles for legacy units.
- Automation Systems:Integrated platforms combining robotic sampling, incubation, and imaging reduce operator intervention and data integrity risks. Cell therapy manufacturers in Boston and San Diego clusters prioritize these systems for same-day batch release decisions where manual handling introduces contamination risks.
- Media Fill:Process simulation testing validates aseptic filling operations through surrogate microbial growth media rather than finished product analysis.
- Rapid Test Kits:Disposable cartridge-based assays enable point-of-use sterility confirmation without centralized laboratory infrastructure.
Established volume favors membrane filtration; emerging adoption favors automation systems.
Technology:
Detection sensitivity thresholds and matrix interference profiles segment technology selection across biologic complexity tiers.
- PCR:Nucleic acid amplification achieves detection limits below one colony-forming unit for slow-growing contaminants invisible to culture methods. Gene therapy manufacturers in Maryland deploy real-time PCR for mycoplasma and bacterial detection in protein-rich viral vector matrices where ATP bioluminescence generates false positives.
- Bioluminescence:ATP-based detection quantifies viable microbial biomass through light emission from luciferase reactions. Parenteral drug facilities in Ireland favor this platform for routine environmental monitoring where rapid turnaround outweighs absolute sensitivity requirements.
- Colorimetric:Enzymatic substrate reactions produce visible color changes upon microbial metabolism detection.
- Fluorescent:Vital staining and epifluorescence microscopy enumerate viable cells without extended incubation.
PCR commands the steepest expansion trajectory; bioluminescence retains the broadest regulatory acceptance.
Application:
Product stability windows and batch failure costs create divergent urgency profiles across therapeutic categories.
- Biologics:Temperature-sensitive monoclonal antibodies, cell therapies, and gene therapies require compressed sterility confirmation to prevent cold chain excursions. Autologous CAR-T production in San Diego demands seventy-two-hour turnaround timelines that exclude traditional fourteen-day incubation.
- Pharmaceuticals:Small-molecule sterile injectables and ophthalmic preparations absorb the majority of current testing volume. Facilities in New Jersey and Switzerland maintain high-throughput membrane filtration operations for established product portfolios with lower per-batch failure costs.
- Medical Devices:Implantable and contact lens sterilization verification follows ISO 11137 radiation or ethylene oxide validation protocols.
- Research Laboratories:Preclinical and process development applications tolerate longer turnaround times for method development purposes.
Pharmaceuticals anchor current spending; biologics generate the fastest growth.
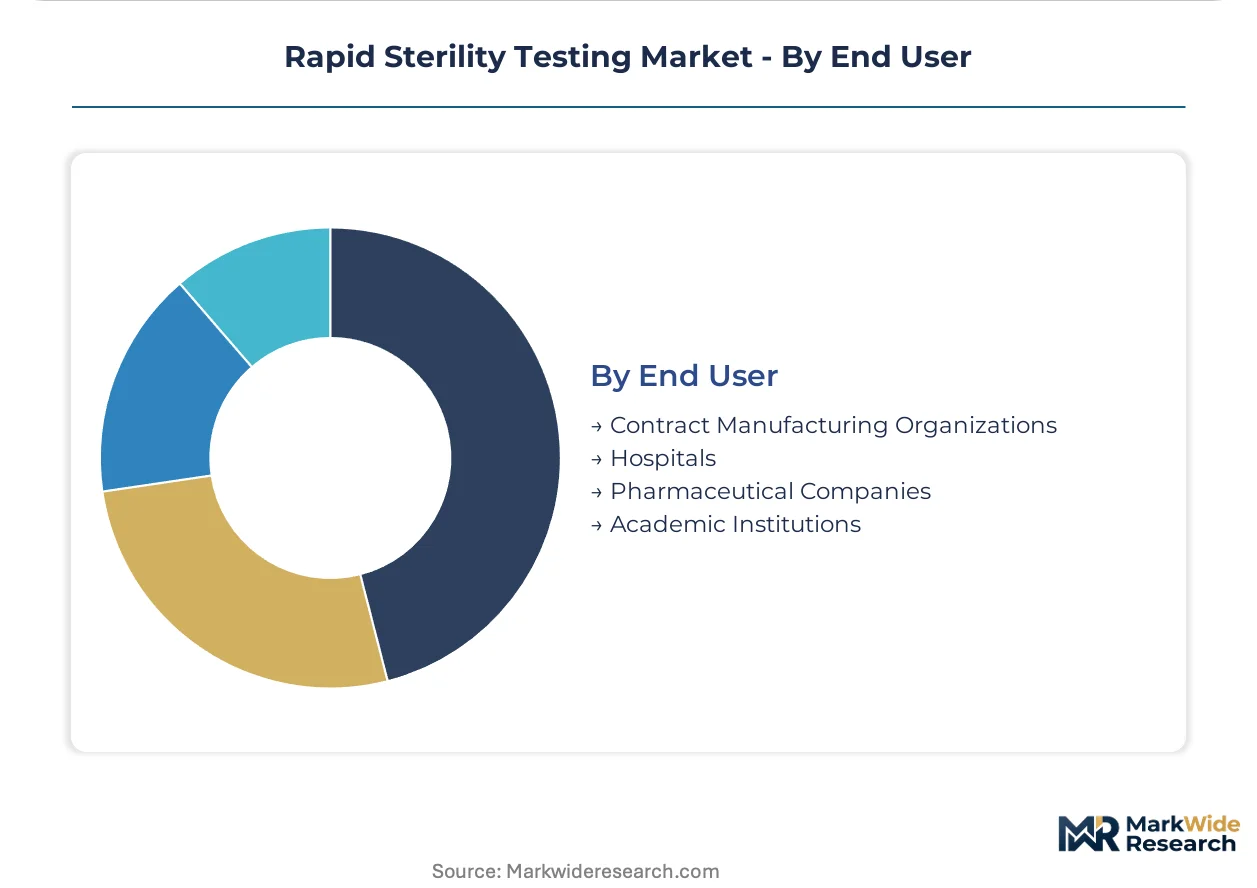
End User:
Outsourcing depth and in-house analytical capability determine platform investment rationale across organizational types.
- Pharmaceutical Companies:Large sponsors in California and New Jersey consolidate rapid sterility validation within captive quality control laboratories to protect proprietary process knowledge. These organizations negotiate enterprise service contracts with platform vendors spanning multiple manufacturing sites.
- Contract Manufacturing Organizations:CDMOs in Germany and Switzerland differentiate through rapid method validation credentials that attract biologics sponsors seeking accelerated batch release. Regulatory inspection history and pharmacopeial compliance documentation determine competitive positioning.
- Hospitals:Compounding pharmacies and stem cell processing facilities require point-of-use sterility confirmation for patient-specific therapies.
- Academic Institutions:Research-driven adoption focuses on method development and publication rather than GMP compliance.
Pharmaceutical companies dominate capital deployment; contract manufacturers capture outsourcing volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Switzerland and Japan absorb premium pricing for validated rapid sterility platforms with minimal elasticity, while contract manufacturers in India and emerging European markets demonstrate acute price sensitivity that favors modular, lower-capital configurations.
United States
FDA sterility testing guidance revisions and CAR-T manufacturing expansion drive platform demand. The FDA's 2023 method equivalence framework compresses validation timelines for alternative microbiological methods. Boston and San Diego bioclusters anchor domestic demand through autologous cell therapy production requiring seventy-two-hour batch release.
Germany
EU GMP Annex 1 contamination control mandates and Bavarian polymer supply chain concentration shape procurement patterns. EMA-aligned regulatory stringency elevates barriers for non-validated platform entry. Frankfurt and Munich pharmaceutical corridors deploy membrane filtration systems for sterile injectable production at industrial scale.
Japan
PMDA accelerated approval pathways for regenerative medicines and Kobe biocluster expansion concentrate demand. METI industrial policy supports domestic analytical instrumentation manufacturing. Osaka and Yokohama cell therapy facilities import rapid sterility validation protocols from European sponsors to satisfy local release requirements.
Switzerland
Swissmedic inspection rigor and Basel-headquartered pharmaceutical R&D density sustain premium platform pricing. The country's quality assurance standards exceed EU baseline requirements for sterile manufacturing. Geneva and Zurich CDMOs differentiate through rapid method credentials that attract multinational biologics sponsors.
India
CDSCO export-oriented manufacturing incentives and Hyderabad-Visakhapatnam API corridor growth expand quality control investment. Domestic biopharma sponsors adopt rapid sterility platforms to satisfy FDA inspection readiness for US-bound sterile products. Bengaluru contract research organizations build validation capabilities to capture outsourced analytical work from European sponsors.
Rapid Sterility Testing Market Competitive Environment
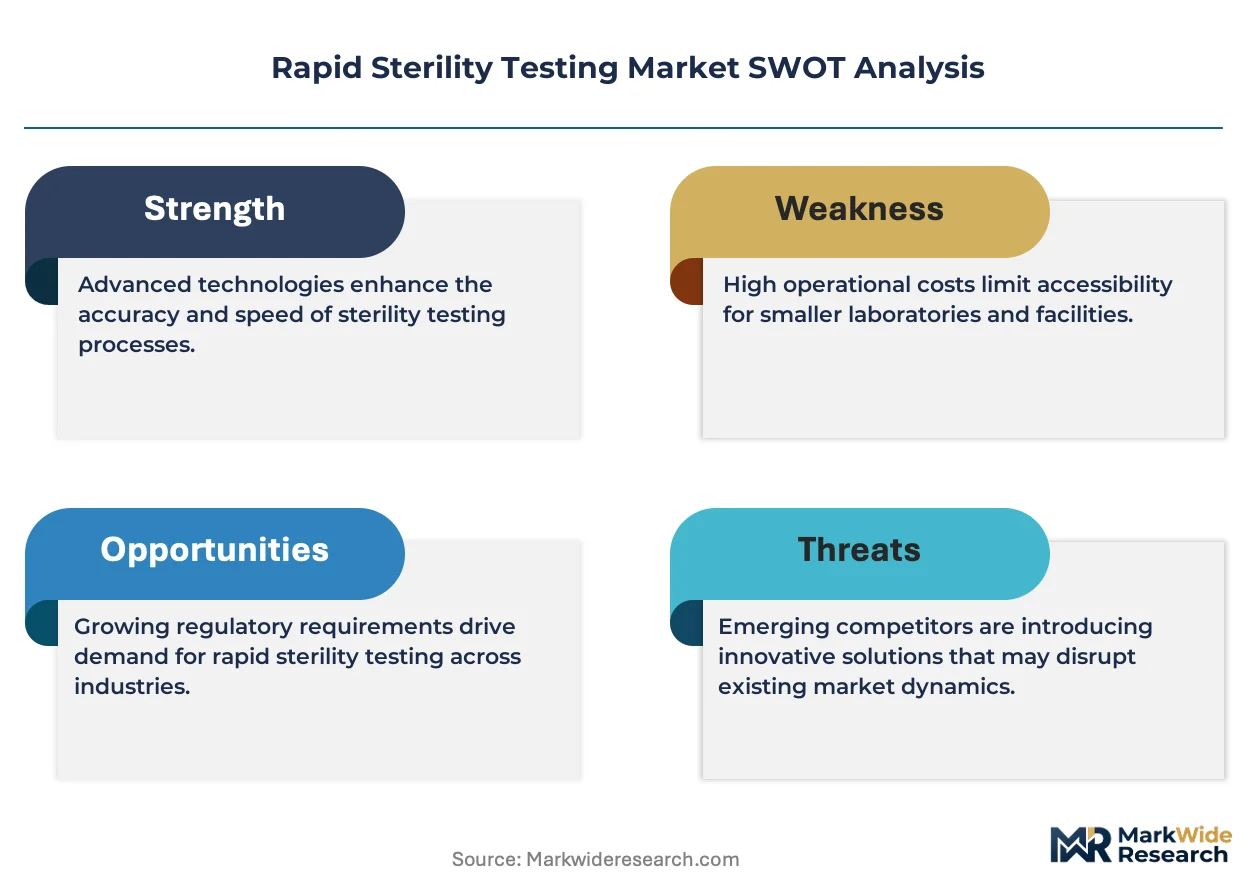
Capability concentration sits with specialized biologics testing providers; scale advantage sits with diversified laboratory workflow conglomerates. The market structures around three tiers: integrated automation ecosystem vendors, membrane filtration hardware specialists, and third-party validation service providers. Consolidation pressure intensifies as pharmaceutical sponsors reduce preferred vendor rosters from twelve to three partners. Competitive moves center on enterprise service contract bundling and pharmacopeial compliance documentation accumulation.
Among diversified laboratory conglomerates, Thermo Fisher Scientific anchors the integrated workflow tier through end-to-end quality control portfolio breadth. Charles River Laboratories exemplifies the specialized biologics testing archetype with dedicated cell and gene therapy validation capacity. Sartorius AG occupies the membrane filtration hardware position through upstream single-use consumables integration that locks in recurring filtration membrane demand.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| Charles River Laboratories |
| Rapid Micro Biosystems |
| Nelson Laboratories |
| SGS SA |
| Sartorius AG |
| BD |
| Eurofins Scientific |
| Others |
Value Chain & Pricing Dynamics
Bavarian polymer concentration for single-use filtration membranes and PCR reagents anchors margin capture downstream with platform vendors rather than consumables suppliers. Pharmaceutical quality control labs in Basel and Boston absorb premium pricing for validated automation ecosystems that compress batch release timelines.
Pricing Analysis
After-sales service contracts and recurring consumable revenue tiers drive lifetime value for rapid sterility platform vendors. Three-tier pricing structure across premium automation ecosystems, standard membrane filtration units, and economy rapid test kits segments buyers by validation burden and throughput requirements. Pricing pressure stems from CDMO consolidation in India and Eastern Europe favoring modular lower-capital configurations. Contract manufacturers demonstrate acute price sensitivity while Swiss and Japanese biologics sponsors absorb premium pricing with minimal elasticity.
Supply Chain Analysis
Export-control restrictions on nucleic acid amplification technologies and precision robotics components limit flows from US and German suppliers to certain end markets. Manufacturing concentration for PCR thermal cyclers rests on California and Massachusetts instrumentation clusters, while filtration membrane production centers on Bavaria and North Rhine-Westphalia. Single-source vulnerability for fluoropolymer resins creates exposure to input volatility. Distribution runs through authorized distributor networks serving pharmaceutical quality control laboratories and CDMO validation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pharmaceutical sponsors reducing preferred vendor rosters from twelve to three partners, compressing pricing leverage for testing service providers.
For Market Incumbents: Entrench platform ecosystem lock-in through enterprise service contracts spanning multiple manufacturing sites. Deepen upstream control over single-use consumables supply to defend against modular competitors. Cell therapy batch failure costs exceeding analytical service fees by orders of magnitude create stickiness for validated partners. For New Entrants and Emerging Players: Pursue point-of-use rapid test kit deployment for gene therapy manufacturers in Maryland and North Carolina seeking to bypass centralized laboratory bottlenecks. Target hospital compounding pharmacies and stem cell processing facilities in Japan's Kobe biocluster where localized validation services remain underdeveloped. Lead with isothermal amplification platforms requiring minimal capital infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CDMOs in Germany and Switzerland that have accumulated pharmacopeial compliance documentation but lack automation platform integration. Five-to-ten year viability hinges on continuous manufacturing retrofit cycles and regenerative medicine approval pathway expansion. Monitor PMDA harmonization progress with EMA validation frameworks as inflection signal for Japanese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Enterprise Service Contract Bundling | Thermo Fisher Scientific anchors recurring revenue across pharmaceutical quality control labs in New Jersey and California. |
| Pharmacopeial Compliance Documentation Accumulation | Charles River Laboratories differentiates through dedicated cell and gene therapy validation credentials. |
| Upstream Single-Use Consumables Integration | Sartorius AG locks in recurring filtration membrane demand through bioprocessing hardware ecosystem control. |
| Localized Rapid Sterility Validation Services | Third-party testing facilities in Bengaluru capture outsourced analytical work from European biologics sponsors. |
| Continuous Manufacturing Inline Monitoring Development | Spectroscopic sensor and automated sampling robotics integration enables real-time release testing architectures for perfusion bioreactors. |
Study Parameters
Desk research of FDA sterility testing guidance documents, EMA sterilization guidelines, USP Chapter 1223 method equivalence frameworks, and pharmacopeial validation protocols preceded structured interviews with pharmaceutical quality control directors, CDMO regulatory affairs leads, biologics manufacturing executives, and rapid microbiological method specialists. Primary fieldwork combined with secondary validation through SEC 10-K filings, instrument vendor annual reports, and customs trade data for analytical equipment imports. Bottom-up demand modeling across product types, technologies, and applications triangulated against top-down market sizing.
Assumptions held fixed include current FDA method equivalence study durations and EU GMP Annex 1 contamination control requirements, while variables included PMDA harmonization progress, continuous manufacturing adoption rates, and cell therapy production expansion across Boston, San Diego, and Kobe clusters. Segmentation modeling spanned product architecture, detection technology, therapeutic application, and end-user organizational type. CAGRs derived from installed base replacement cycles, validation timeline compression, and biologics manufacturing capacity expansion trajectories. Industry-specific inputs incorporated ATP bioluminescence false positive rates in protein-rich matrices and PCR sensitivity improvements for mycoplasma detection.
Sensitivities concentrate around regulatory harmonization delays between pharmacopeial standards and instrument-specific validation protocols, polymer supply chain disruptions affecting single-use consumables, and microbiology talent scarcity constraining facility expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Test Strips Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
STD Testing Devices Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Global Ovulation Test Market
Testing Services
Global Sterility Testing Market
Testing Services
Home Blood Testing Devices Market
Testing Services
Monkeypox Testing Market
Testing Services
Instrument Calibration Services Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Global Sleep Testing Services Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Global Electronystagmography Testing Market