
 Legionnaire Disease Testing Market | 2026-2036
Legionnaire Disease Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Legionnaire Disease Testing Market Foresight
Hospital infection control departments are redrawing procurement priorities for Legionella diagnostics, shifting volume toward molecular and rapid antigen platforms. Thermo Fisher Scientific leverages its PCR instrumentation installed base to sustain recurring reagent pull-through in hospital microbiology labs. Bio-Rad Laboratories anchors its position through specialized culture media and quality control products that laboratories depend on for confirmatory testing workflows.
Legionnaire disease testing encompasses laboratory and point-of-care methods for detecting Legionella pneumophila antigens, nucleic acids, or antibodies in clinical specimens, typically requiring urinary antigen immunoassay sensitivity below 1 ng/ml or PCR cycle threshold precision under 35 cycles to meet diagnostic accuracy standards. PCR testing commands the fastest expansion trajectory as laboratories replace slower culture-based confirmation with same-day molecular turnaround. Urinary antigen testing occupies the highest volume tier among product types due to its simplicity and dominance in initial emergency department screening, though its single-serogroup limitation creates margin pools for multiplex molecular alternatives.
The EPA regulates building water system Legionella management under the Safe Drinking Water Act framework, while FDA oversees in vitro diagnostic test performance claims and clinical validation requirements for commercial assay kits. CDC guidelines for healthcare-associated pneumonia investigation directly shape hospital laboratory testing menus and reimbursement pathways for Legionella detection. Stakeholders must monitor evolving CMS quality metrics that may mandate routine environmental surveillance as a condition of hospital accreditation, fundamentally altering the addressable testing base beyond acute diagnosis alone.
Market Dynamics
Hospital microbiology laboratories face mounting pressure to compress Legionella detection turnaround from days to hours, forcing capital reallocation toward molecular platforms and away from legacy culture workflows. This operational imperative is restructuring vendor relationships and reagent procurement patterns across acute care networks.
Growth Catalysts
- EPA Safe Drinking Water Act enforcement:The EPA's expanded building-level Legionella management rules are mandating environmental surveillance protocols for healthcare facilities, creating recurring testing demand beyond acute diagnosis alone.
- PCR platform expansion:Hospital laboratories are converting bench space to molecular diagnostics, with same-day nucleic acid detection replacing slower confirmatory culture methods in outbreak investigation workflows.
- Aging US infrastructure:Deteriorating municipal water distribution systems and dense urban healthcare clusters amplify outbreak detection needs, concentrating demand in metropolitan hospital networks.
Market Restraints
- Urinary antigen serogroup limitation:The dominant rapid antigen test detects only Legionella pneumophila serogroup 1, missing 15-30% of disease-causing strains and forcing laboratories to maintain parallel molecular confirmation capacity.
- Reagent supply concentration:Specialized PCR master mixes and fluorescent probe chemistries depend on concentrated upstream chemical suppliers, exposing testing programs to input volatility and single-source risk.
- Culture confirmation persistence:Regulatory frameworks and reference laboratory accreditation standards still mandate culture-based confirmation for public health reporting, preventing full workflow abandonment of slower methods.
Strategic Opportunities
- Multiplex syndromic panels:Convergent respiratory pathogen detection platforms incorporating Legionella alongside SARS-CoV-2 and influenza are capturing emergency department screening volume through single-sample efficiency.
- Long-term care penetration:Skilled nursing facilities remain underpenetrated for routine environmental surveillance, presenting white space for point-of-care antigen testing adoption as CMS quality metrics expand.
- ISO 15189 laboratory accreditation:The international quality standard is elevating demand for integrated quality control products and external proficiency testing services that anchor annual reagent contracts.
Industry Challenges
- Molecular diagnostic technologist shortage:Specialized training requirements for PCR assay validation and thermal cycler maintenance are outpacing laboratory workforce supply, constraining platform expansion timelines.
- Legacy LIS integration friction:Hospital information systems built around culture-based result reporting require costly middleware development to accommodate real-time molecular data streams and automated reflex algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legionnaire Disease Testing Market |
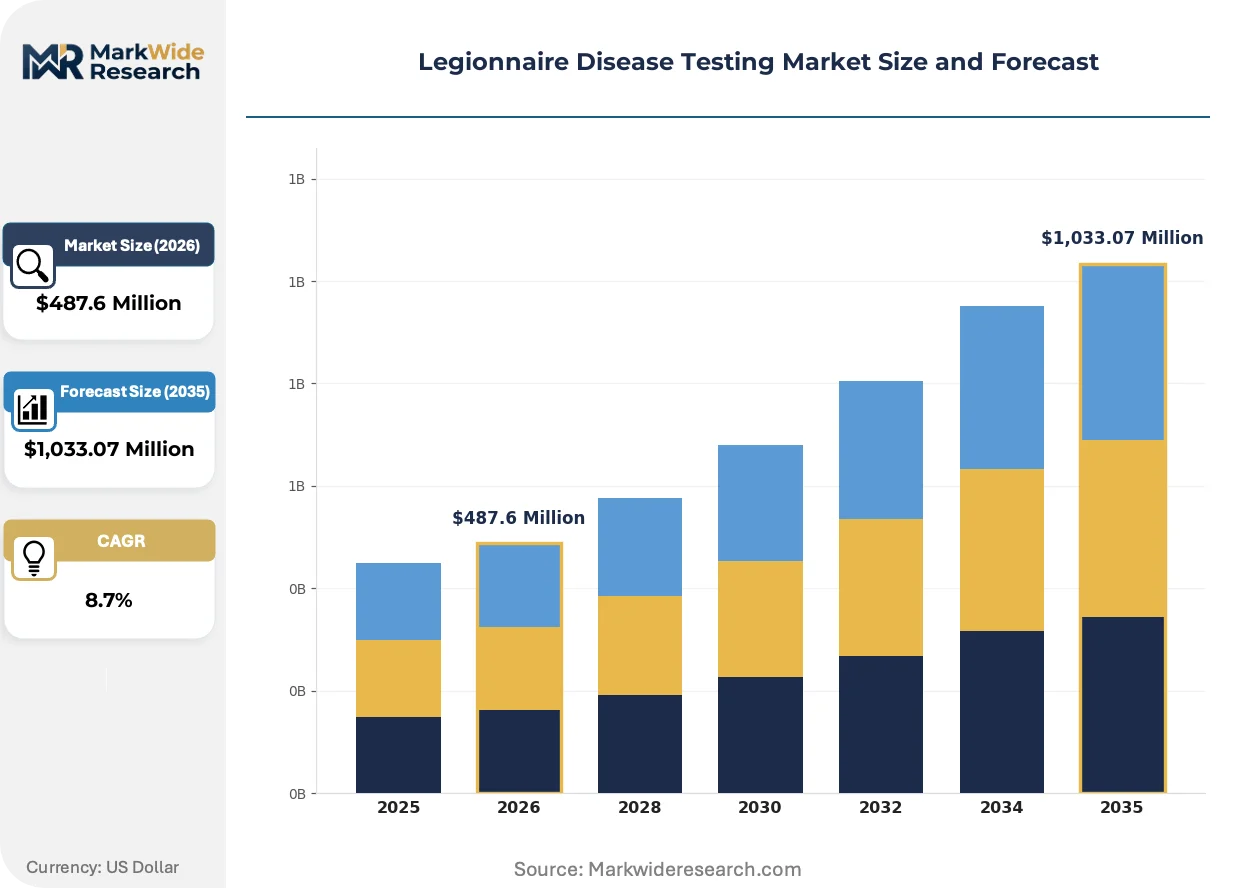
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Testing, PCR Testing, Urinary Antigen Testing, Serological Testing End User: Clinical Laboratories, Hospitals, Diagnostic Centers, Research Institutions Testing Method: Molecular Testing, Serological Methods, Rapid Tests, Antigen Detection Sample Type: Blood, Urine, Sputum, Respiratory Tract Secretions |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., IDEXX Laboratories Inc., bioMérieux SA, Becton, Dickinson and Company, Abbott Laboratories, Merck KGaA, Eurofins Scientific, Aquacert Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legionnaire Disease Testing Market Shifts & Advancements
Digital PCR and next-generation sequencing platforms are penetrating reference laboratory workflows, enabling strain-level epidemiological tracing that culture methods cannot provide. These technologies are compressing outbreak investigation timelines from weeks to days.
Loop-mediated isothermal amplification is decomposing the capital barrier to molecular testing in smaller hospital laboratories. Community hospitals and regional medical centers are adopting cartridge-based LAMP systems that eliminate thermal cycler infrastructure requirements. This technology is decomposing the historical concentration of advanced Legionella diagnostics in academic medical centers, democratizing access across hospital tiers.
The CDC's expanded healthcare-associated pneumonia investigation guidelines are tightening evidentiary standards for Legionella detection in outbreak scenarios. These protocols are forcing laboratories to document analytical sensitivity and specificity claims with greater rigor. Hospital infection control departments are responding by consolidating testing contracts with vendors offering comprehensive validation packages rather than commodity reagents alone.
Emergency departments are unbundling rapid screening from confirmatory testing, with triage nurses performing initial urinary antigen testing at point-of-care while routing complex cases to core laboratories. This bifurcation is fragmenting procurement authority between nursing supply chains and laboratory directors. The United States exhibits the most pronounced channel separation, driven by emergency medicine throughput pressures and reimbursement differentials between professional and technical billing components.
Legionnaire Disease Testing Market Segmentation
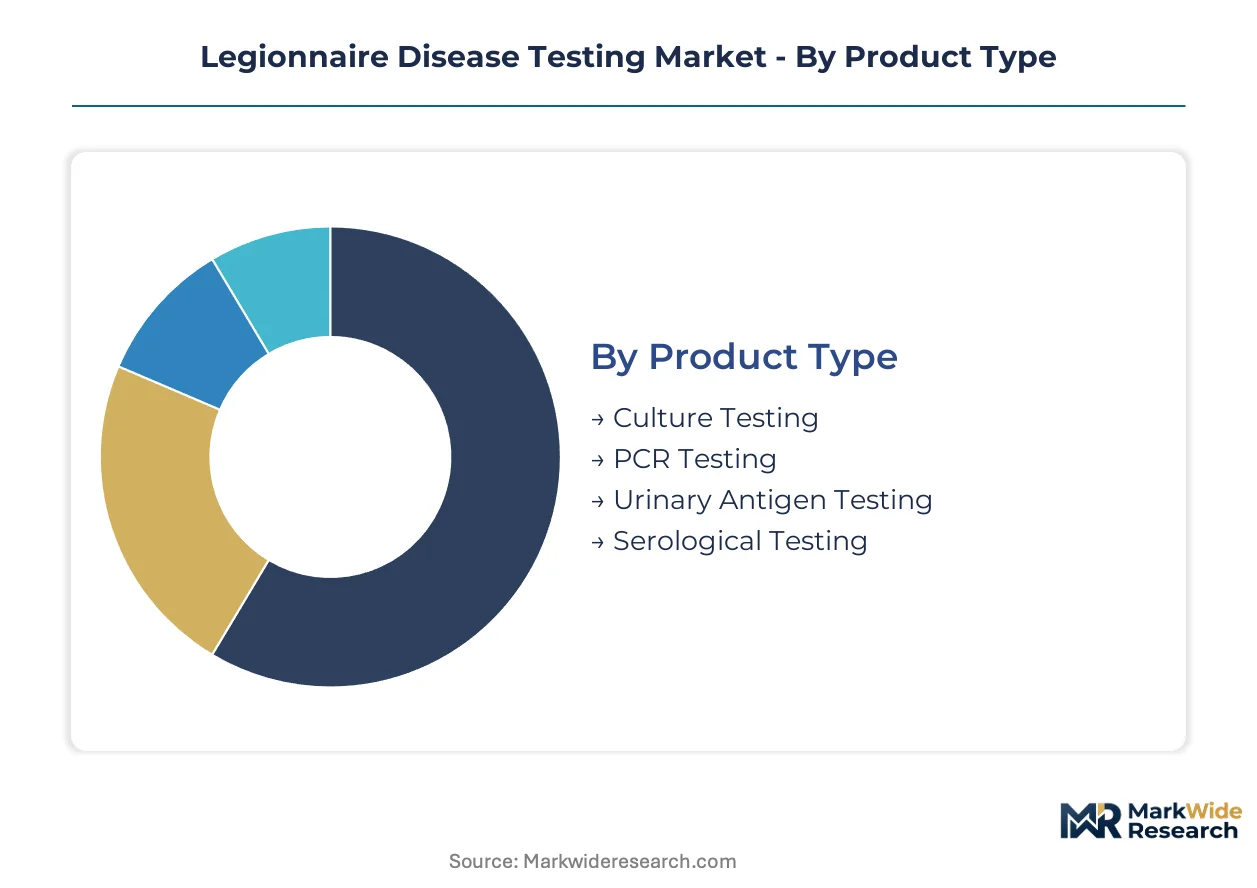
Legionnaire disease testing segments fragment across technical platforms, care settings, and specimen sources. Each dimension carries distinct procurement pathways, reimbursement codes, and regulatory validation requirements that reshape vendor positioning.
Product Type:
Domestic US demand concentrates in urinary antigen and PCR platforms, while European and Asia-Pacific markets still rely more heavily on culture confirmation for regulatory compliance.
- Culture Testing:Gold-standard confirmation requiring specialized buffered charcoal yeast extract media and 7-14 day incubation cycles. Reference laboratories in France and Germany maintain this capacity for outbreak epidemiology, though hospital microbiology labs are decommissioning benches.
- PCR Testing:Real-time nucleic acid amplification delivers same-day detection with cycle threshold precision under 35 cycles. US metropolitan hospital networks are converting capital budgets toward thermal cycler infrastructure, displacing legacy workflows.
- Urinary Antigen Testing:Lateral flow immunoassays dominate emergency department triage with sub-1 ng/ml sensitivity for serogroup 1.
- Serological Testing:Paired acute and convalescent antibody detection persists in retrospective outbreak investigations.
Urinary antigen testing holds the largest share; momentum sits with PCR testing.
End User:
Procurement authority fragments between laboratory directors and infection control officers depending on whether testing occurs in core labs or at point-of-care.
- Clinical Laboratories:Centralized microbiology operations process high-volume screening with automated liquid handling and LIS-integrated result reporting. These facilities anchor reagent contracts for hospital networks in California, Texas, and New York.
- Hospitals:Acute care institutions balance emergency department throughput demands against laboratory accreditation requirements. US hospitals face CMS quality metric pressure to implement environmental surveillance beyond patient diagnosis alone.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time for outpatient pneumonia workups.
- Research Institutions:Academic medical centers maintain specialized capabilities for strain typing and antimicrobial susceptibility profiling.
Clinical laboratories capture the highest testing volume; diagnostic centers are expanding most quickly into employer wellness screening.
Testing Method:
Capital intensity varies dramatically across methods, with molecular platforms requiring $50,000-$150,000 instrument investments versus rapid test disposable economics.
- Molecular Testing:PCR and emerging digital PCR platforms enable quantitative bacterial load monitoring. These methods are displacing culture confirmation in US outbreak investigations where speed outweighs cost sensitivity.
- Serological Methods:Indirect immunofluorescence and enzyme immunoassay detect antibody responses. Public health laboratories retain this capacity for retrospective case confirmation when acute specimens are unavailable.
- Rapid Tests:Lateral flow and immunochromatographic formats enable non-laboratory personnel to perform screening. Skilled nursing facilities represent underpenetrated demand for this format.
- Antigen Detection:Direct fluorescent antibody staining of respiratory specimens requires specialized microscopy infrastructure.
Molecular testing commands the steepest expansion trajectory; rapid tests address cost-constrained settings.
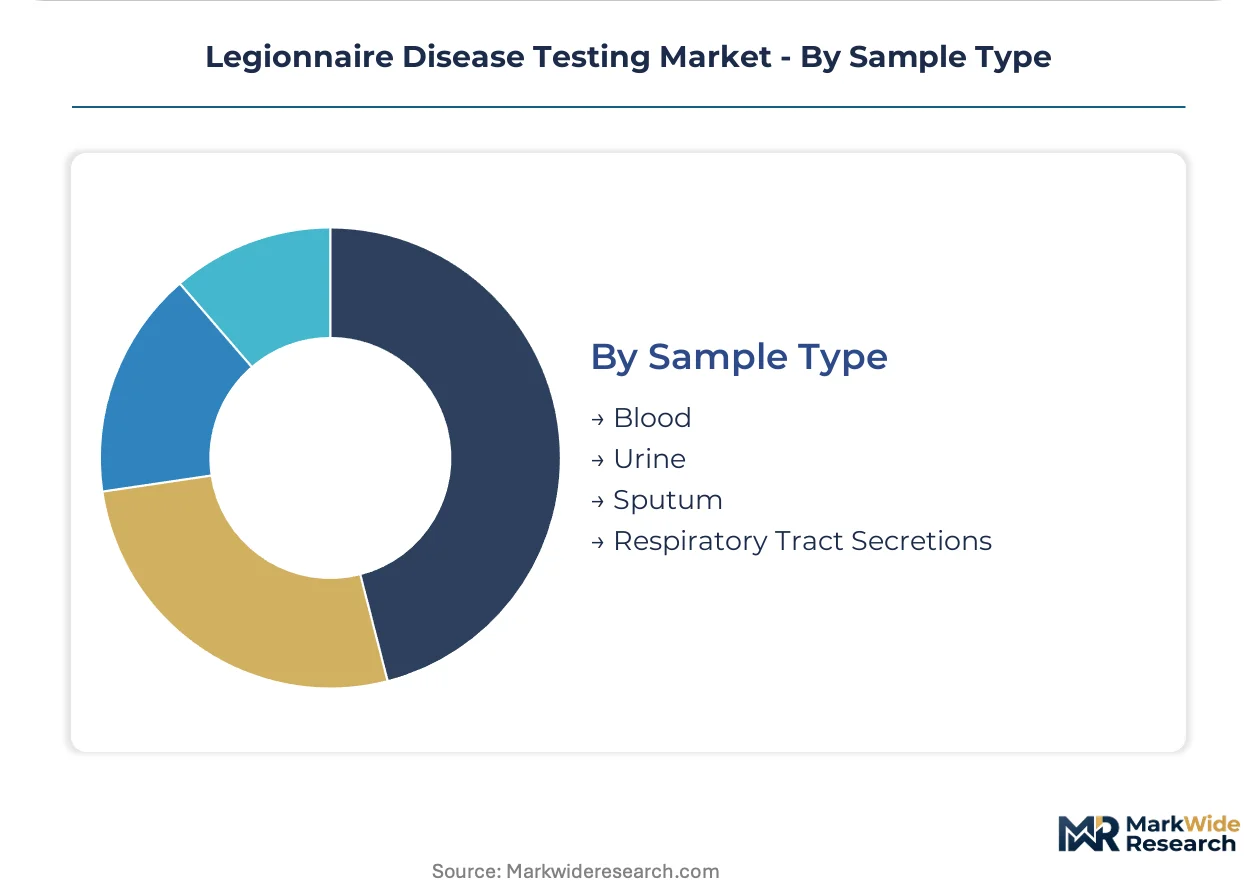
Sample Type:
Collection logistics and specimen stability determine whether testing occurs at point-of-care or requires transport to centralized laboratories.
- Urine:Non-invasive collection with superior antigen stability supports emergency department screening protocols. This specimen type anchors the highest testing volume tier across US healthcare networks.
- Respiratory Tract Secretions:Bronchoalveolar lavage and tracheal aspirates yield highest bacterial load for molecular detection. Intensive care units in academic medical centers favor this specimen for ventilator-associated pneumonia workups.
- Blood:Serum and plasma support antibody detection and PCR in disseminated disease cases.
- Sputum:Expectorated samples carry contamination risk that complicates culture interpretation.
Urine dominates screening volume; respiratory secretions deliver the highest diagnostic yield in severe cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized culture media and PCR reagents to hospital networks across France, Italy, and the Netherlands. This trade corridor channels European diagnostic demand toward Central European manufacturing clusters while regulatory divergence shapes local testing protocols.
United States
Metropolitan hospital networks in New York, Chicago, and Los Angeles drive molecular platform conversion as CMS quality metrics tighten. The EPA's expanded Safe Drinking Water Act enforcement mandates building-level Legionella surveillance for healthcare facilities. Texas Medical Center anchors the highest concentration of same-day PCR turnaround capacity in North America.
Germany
Reference laboratories in Munich and Heidelberg maintain specialized strain-typing capacity for outbreak epidemiology across the EU. The country's national pharmaceutical regulator enforces rigorous ISO 15189 accreditation standards for clinical microbiology. Baden-Württemberg's industrial corridor supplies buffered charcoal yeast extract media to hospital networks from Scandinavia to Southern Europe.
France
Parisian academic medical centers anchor the highest culture-confirmation volume for regulatory compliance within the EU framework. ANSM oversight shapes in vitro diagnostic validation requirements for commercial assay kits. The Lyon-Grenoble cluster concentrates environmental surveillance testing for hospitality and healthcare infrastructure.
Japan
Tokyo and Osaka hospital networks are adopting cartridge-based isothermal amplification systems to bypass thermal cycler infrastructure constraints. METI industrial policy supports domestic diagnostic reagent manufacturing to reduce import dependency. The Kansai region's aging hospitality infrastructure drives point-of-care antigen testing adoption in hotel chains.
United Kingdom
London's NHS trusts are consolidating testing contracts toward vendors offering comprehensive validation packages. The country's national pharmaceutical regulator enforces post-Brexit divergence from EU diagnostic device frameworks. Manchester and Birmingham hospital networks are expanding environmental surveillance beyond acute diagnosis alone.
Legionnaire Disease Testing Market Competitive Landscape
Listed leaders compete with private specialists across instrument platforms and reagent supply chains. The vendor base clusters around three tiers: diversified life science conglomerates with installed-base leverage, specialized diagnostic pure-plays with regulatory depth, and regional reagent suppliers with logistics proximity. Archetypes include platform-anchored recurring revenue players, validation-heavy compliance specialists, and flexible regional distributors. Competitive moves center on thermal cycler placement strategies for reagent pull-through and ISO 15189-aligned quality control bundling.
Among US-based diversified conglomerates, Thermo Fisher Scientific Inc. and Bio-Rad Laboratories, Inc. exemplify platform-anchored positioning. French diagnostic specialist bioMérieux SA occupies a position within the validation-heavy tier. German conglomerate Merck KGaA represents the chemical-reagent supply anchor. Each sits within distinct procurement pathways: capital-budget thermal cycler placements, compliance-driven annual reagent contracts, and upstream master-mix chemical supply.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| IDEXX Laboratories Inc. |
| bioMérieux SA |
| Becton, Dickinson and Company |
| Abbott Laboratories |
| Merck KGaA |
| Eurofins Scientific |
| Aquacert Ltd. |
| Others |
Supply & Pricing Matrix
ISO 15189 laboratory accreditation gates both supplier qualification and price differentiation simultaneously, forcing vendors to bundle validation documentation with reagent contracts while hospitals pay premiums for compliant quality control packages.
Pricing Analysis
Prior-generation culture-based workflows, current-generation real-time PCR platforms, and next-generation digital PCR systems stratify across three distinct price tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with ISO-aligned validation packages commanding 40-60% markups over commodity reagents. Price differentiation hinges on thermal cycler placement strategies versus cartridge-based consumables, with academic medical centers least sensitive and community hospitals most cost-constrained. Cost compression in the economy tier intensifies as LAMP-based alternatives eliminate capital infrastructure requirements.
Supply Chain Analysis
Germany and the United States anchor specialized culture media and PCR master mix production respectively. Fluorescent probe chemistries draw from concentrated upstream chemical suppliers in Switzerland and Japan, while plastic consumables feed from medical-grade polymer processors in China and Mexico. Single-source vulnerability concentrates in rare-earth-dependent fluorophores and proprietary enzyme formulations. Distribution runs through hospital GPO contracts, reference laboratory networks, and direct-to-laboratory reagent contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Safe Drinking Water Act enforcement creates a high-growth disruption as environmental surveillance mandates expand the addressable testing base beyond acute diagnosis alone.
For Market Incumbents: Fortify installed-base leverage by locking thermal cycler placements with multi-year reagent minimums before LAMP cartridge systems displace capital-intensive workflows. Deepen backward integration into fluorescent probe chemistries to insulate margin structures from upstream chemical volatility. Anchor annual contracts through ISO 15189-aligned proficiency testing bundling that smaller competitors cannot replicate. For New Entrants and Emerging Players: Point-of-care environmental surveillance in skilled nursing facilities represents the most penetrable white space, as CMS quality metric expansion outpaces incumbent field service capacity. Target cartridge-based LAMP systems for community hospitals lacking molecular technologist staffing. Pursue GPO contract carve-outs by offering validation-heavy compliance packages that accelerate laboratory accreditation timelines. For Investors and Strategic Acquirers: CMS quality metric expansion reshapes the acquisition landscape by elevating vendors with environmental testing capabilities above pure clinical diagnostic plays. Long-term viability centers on recurring reagent pull-through rather than instrument placement economics. Monitor EPA enforcement action frequency as the primary inflection indicator for testing volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Syndromic Panel Expansion | Captures emergency department screening volume through single-sample respiratory pathogen detection efficiency. |
| ISO 15189 Validation Package Development | Locks annual reagent contracts by addressing laboratory accreditation compliance requirements. |
| Point-of-Care Cartridge Manufacturing Scale-Up | Democratizes molecular access across community hospitals lacking thermal cycler infrastructure. |
| Environmental Surveillance Service Launch | Addresses EPA-mandated building water system testing beyond acute patient diagnosis. |
| Digital PCR Platform Integration | Enables strain-level epidemiological tracing for outbreak investigation compression. |
Research Methodology
The analysis maps urinary antigen testing, PCR platforms, culture confirmation, and emerging isothermal amplification methods, each validated through microbiology laboratory directors, infection control officers, hospital procurement managers, and diagnostic reagent distributors. Primary interviews with these stakeholders combined secondary validation from FDA 510(k) filings, EPA enforcement action databases, CMS quality metric releases, and hospital GPO contract disclosures. Bottom-up testing volume estimates triangulated against top-down market sizing from instrument placement data and reagent consumption rates.
Consistency checks validated volume and value outputs against external benchmarks including hospital capital expenditure surveys and reference laboratory billing code utilization. The analytical framework models product type, end user, testing method, and sample type dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macro healthcare expenditure trends. Forecast inputs incorporated thermal cycler replacement cycles, CMS quality metric implementation timelines, and EPA enforcement staffing levels.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act enforcement and CMS hospital accreditation requirements; material policy shifts would require re-modeling. Specific risks include molecular diagnostic technologist workforce shortages constraining platform expansion, and reagent supply concentration exposing testing programs to input volatility. Recalibration cycles align with material shifts in EPA enforcement intensity, CMS quality metric expansion, and breakthrough technology adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Fertility Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Candida Vaginitis Rapid Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Toxicology Testing Services Market
Testing Services
Osmometer Market
Testing Services
Continuous Tablet Manufacturing At-Line Quality Test Systems Market
Testing Services
Medical Device Testing Services Market
Testing Services
Asia-Pacific Newborn Screening Market
Testing Services
Cannabis Testing Services Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Fungal Testing Kits Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Large Molecule Bioanalytical Testing Services Market
Testing Services
Global Metabolic Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market