
 Viral Vector Integrity and Potency Analytics Test Instruments Market | 2026-2036
Viral Vector Integrity and Potency Analytics Test Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Vector Integrity and Potency Analytics Test Instruments Market Insights
Analytical chemist talent is rotating toward advanced modality companies faster than universities replenish pipelines, creating instrument utilization bottlenecks at established biopharma sites. Thermo Fisher Scientific leverages its chromatography-mass spectrometry portfolio to dominate high-resolution viral titer workflows. Bio-Rad Laboratories anchors its position through droplet digital PCR systems purpose-built for AAV copy number quantification. Sartorius AG specializes in integrated bioanalytical platforms that consolidate multiple potency readouts into single automated runs.
Viral vector integrity and potency analytics test instruments comprise calibrated systems that measure capsid protein ratios, genome titers, and infectivity indices using fluorescence detection, electrochemical signal transduction, or microfluidic separation with specification thresholds typically spanning picogram to nanogram sensitivity ranges. These instruments enforce release criteria for clinical-grade lentiviral, adeno-associated, and adenoviral vectors destined for human gene therapy and vaccine applications. Flow cytometry and mass spectrometry segments command the deepest margin pools due to capital intensity and consumables lock-in, while microfluidics-based platforms represent the fastest-expanding technology category as manufacturers prioritize sample-minimization for precious viral vector batches. Gene therapy application demand outpaces monoclonal antibody production instrumentation renewal cycles, redirecting vendor R&D investment toward cell therapy validation workflows.
FDA potency assay guidance and EMA's ATMP quality requirements compel viral vector manufacturers to deploy validated analytical platforms with documented traceability, directly inflating instrument replacement cycles and service contract values. The EPA and OSHA frameworks governing GMP facility emissions and operator exposure further constrain instrument design specifications for enclosed, automated sample handling. Stakeholders must monitor evolving FDA gene therapy CMC guidance and EU MDR in vitro diagnostic instrument classifications to anticipate compliance-driven procurement waves.
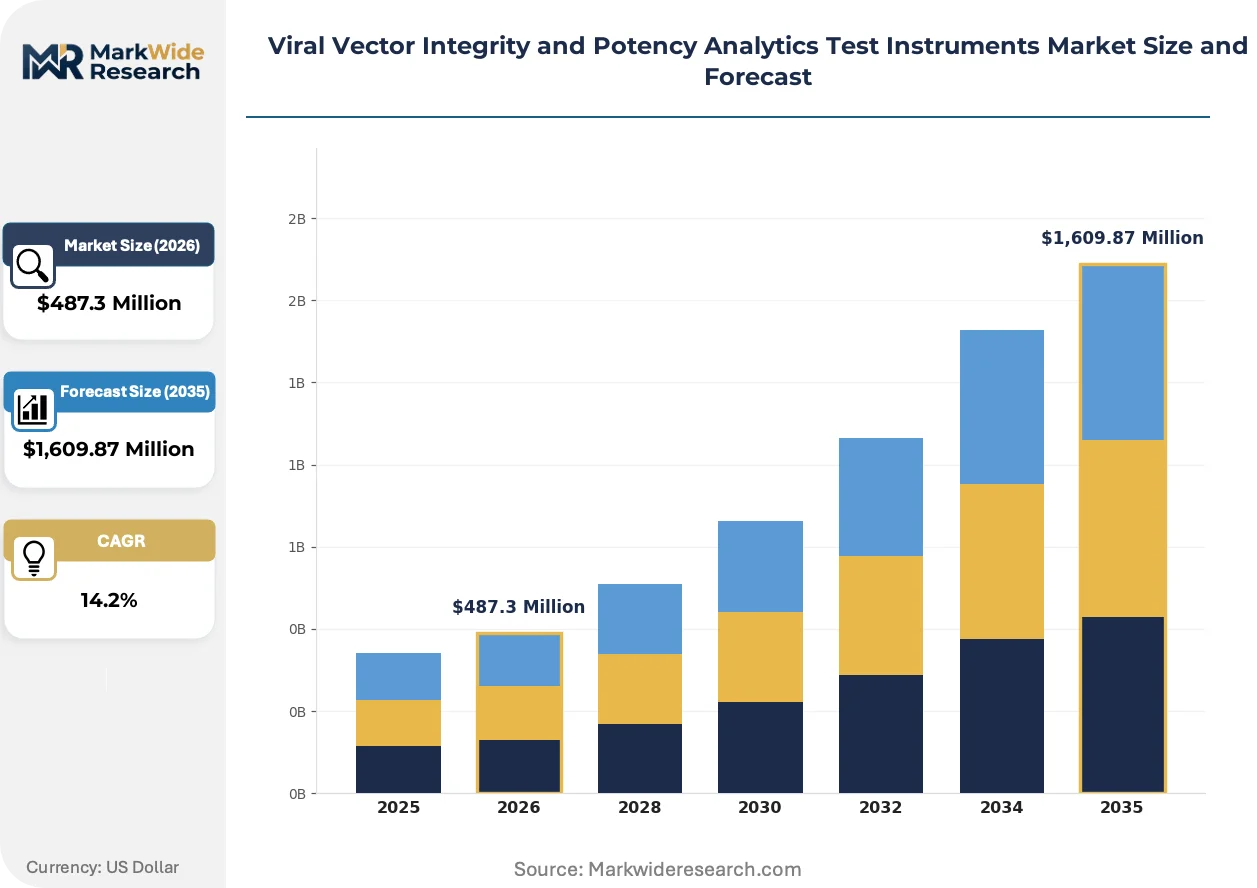
Market Dynamics
Gene therapy CMC requirements are compressing instrument replacement cycles as manufacturers rebuild analytical suites around potency assay mandates rather than incremental upgrades.
Growth Catalysts
- FDA potency assay guidance:Mandates for validated infectivity and titer measurements compel viral vector producers to acquire compliant platforms ahead of BLA submissions.
- Massachusetts and California manufacturing clusters:Concentrated CDMO buildouts in these states generate localized demand surges for integrated analytical systems.
- AAV gene therapy pipelines:Expanding clinical programs for inherited retinal and neuromuscular indications multiply testing volumes per manufacturing campaign.
Market Restraints
- Helium supply volatility:Mass spectrometry dependency on this constrained noble gas creates operational risk for high-resolution titer workflows.
- Massachusetts and Switzerland instrument concentration:Geographic clustering of qualified service engineers limits rapid deployment capacity elsewhere.
- EMA MDR classification uncertainty:Pending in vitro diagnostic instrument reclassification creates procurement delays among European gene therapy developers.
Strategic Opportunities
- India CDMO buildouts:Emerging viral vector manufacturing capacity in Hyderabad and Bengaluru lacks calibrated analytical infrastructure.
- Cell therapy potency convergence:Instruments measuring both viral vector and CAR-T potency readouts capture expanded wallet share per customer.
- Microfluidics-electrochemistry integration:Combined platforms reduce sample volumes below current fluorescence-based thresholds for precious clinical batches.
Industry Challenges
- Analytical chemist attrition:Talent migration toward advanced modality biotechs leaves established pharma sites with underutilized capital equipment.
- Multi-attribute method validation:Consolidated assays for capsid protein, genome titer, and infectivity require extended timeline-to-qualification versus legacy single-readout systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Vector Integrity and Potency Analytics Test Instruments Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometry, PCR Instruments, ELISA Readers, Spectrophotometers, Cell Counters Technology: Fluorescence Detection, Electrochemical Detection, Microfluidics, Optical Biosensors, Mass Spectrometry Application: Gene Therapy, Vaccine Development, Monoclonal Antibody Production, Viral Vector Manufacturing, Cell Therapy Validation End User: Biopharmaceutical Companies, Contract Research Organizations, Academic Research Labs, Quality Control Laboratories, Regulatory Agencies |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Sartorius AG, Agilent Technologies, Waters Corporation, Danaher, Bruker Corporation, QIAGEN, Merck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Vector Integrity and Potency Analytics Test Instruments Market Trends and Innovations
Instrument architectures are pivoting from modular benchtop units toward consolidated platforms that compress analytical timelines for release testing of gene therapy vectors.
Microfluidic separation technology is fragmenting the dominance of traditional chromatography workflows in viral titer quantification. Gene therapy CDMOs in Switzerland and California are adopting these platforms to reduce sample consumption for high-value AAV batches. The shift is fragmenting vendor market positions as specialists with droplet-handling expertise capture share from established chromatography houses.
EMA's ATMP quality requirements are forcing viral vector manufacturers to document analytical traceability across every release parameter. This industrial consequence elevates demand for platforms with embedded audit trails and electronic signature capabilities. European gene therapy developers are responding by prioritizing instrument vendors with established notified body relationships under MDR frameworks.
Service contract unbundling is accelerating as buyers separate hardware acquisition from validation and maintenance agreements. CDMOs in Massachusetts are negotiating standalone qualification packages to accelerate GMP readiness timelines. This behavioral shift is most visible among contract manufacturers managing multiple sponsor programs with divergent SOP requirements.
Viral Vector Integrity and Potency Analytics Test Instruments Market Segmentation
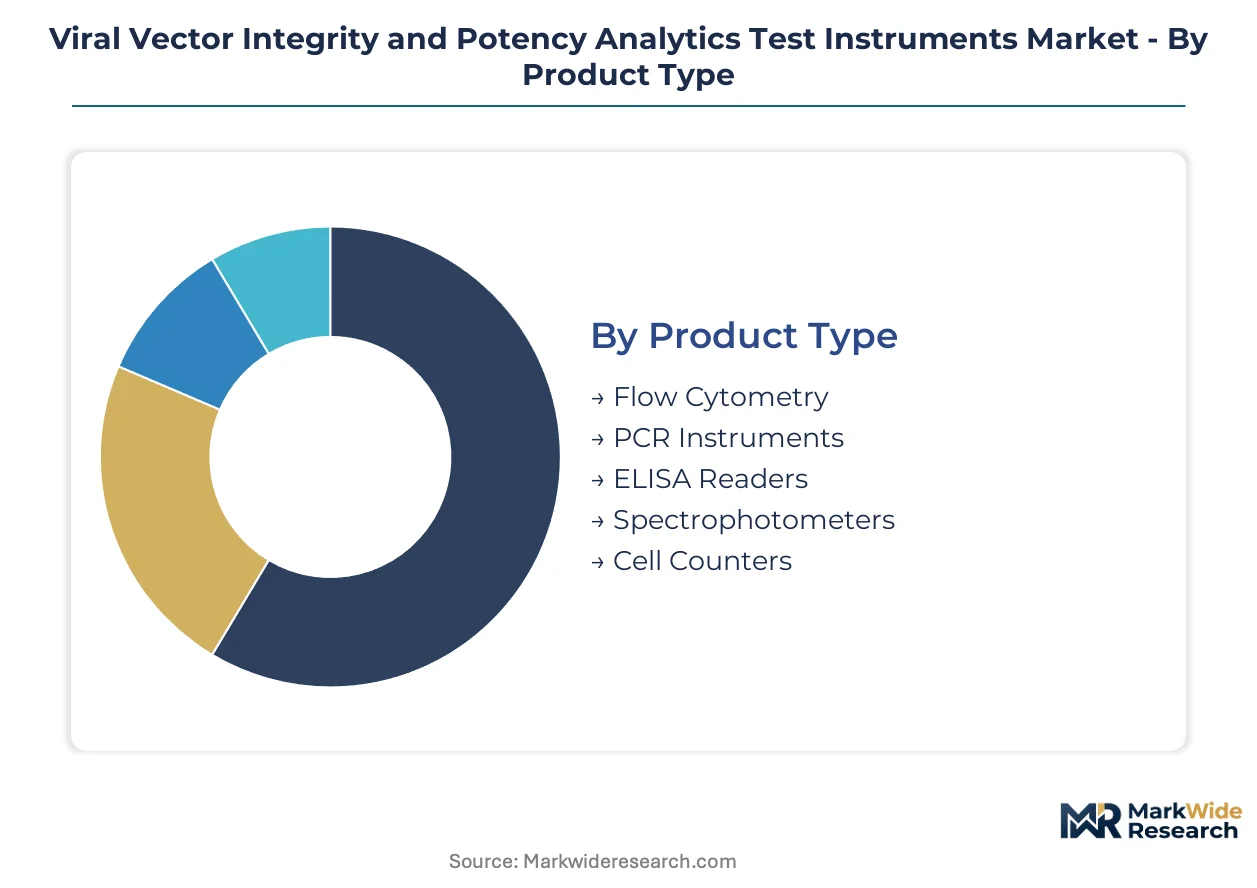
Viral vector analytics instrumentation fragments across multiple technical and commercial dimensions, each carrying distinct margin profiles and qualification burdens. Procurement patterns diverge sharply between GMP-grade manufacturing suites and exploratory research settings.
Product Type:
Flow cytometry and PCR systems anchor domestic demand in Massachusetts and California manufacturing clusters, while spectrophotometer procurement spreads across export-oriented academic markets in Switzerland and Germany.
- Flow Cytometry:Multi-parameter cell sorting platforms quantify viral infectivity through fluorescence-activated detection of transduced cell populations. Massachusetts CDMOs deploy these systems for AAV release testing under FDA potency assay mandates.
- PCR Instruments:Quantitative and droplet digital variants measure viral genome titers with copy number precision. California gene therapy developers favor these for high-throughput screening of lentiviral vector batches destined for clinical trials.
- ELISA Readers:Absorbance-based quantification of capsid protein ratios supports in-process monitoring at European viral vector facilities.
- Spectrophotometers:UV-Vis platforms provide rapid nucleic acid concentration checks for research-grade vector preparations.
- Cell Counters:Automated viability assessment tools integrate into potency assay workflows for cell therapy applications.
Flow cytometry holds the largest share; momentum sits with PCR instruments as droplet digital methods displace quantitative PCR for absolute quantification.
Technology:
Cost tiers separate capital-intensive mass spectrometry installations from benchtop fluorescence systems, with microfluidics platforms capturing mid-tier budgets seeking sample efficiency.
- Fluorescence Detection:Established signal transduction architecture dominates viral titer workflows through dye-based genome quantification. Biopharmaceutical quality control labs in Basel and Boston rely on these systems for compliant release testing.
- Microfluidics:Miniaturized separation platforms reduce sample volumes to sub-microliter scales for precious clinical-grade AAV batches. Swiss CDMOs adopt these for high-value neuromuscular gene therapy programs.
- Mass Spectrometry:High-resolution protein characterization enforces capsid integrity specifications at premium price points.
- Electrochemical Detection:Label-free biosensing approaches gain traction in academic research settings for rapid screening applications.
- Optical Biosensors:Surface plasmon resonance platforms enable real-time binding kinetics for vector potency assessment.
Fluorescence detection commands the deepest installed base; microfluidics platforms are climbing the fastest as manufacturers prioritize sample conservation.
Application:
Customer type stratification separates validated GMP manufacturing from exploratory research, with gene therapy developers commanding premium instrument configurations.
- Gene Therapy:Lentiviral, AAV, and adenoviral vector analytics enforce the most stringent instrument qualification requirements. FDA BLA submissions mandate documented traceability for every potency readout.
- Viral Vector Manufacturing:CDMOs in Hyderabad and Bengaluru seek calibrated platforms for export-compliant production, though local service infrastructure remains underdeveloped.
- Cell Therapy Validation:CAR-T potency assays create overlapping demand with viral vector instrumentation as manufacturers consolidate analytical suites.
- Vaccine Development:Adenoviral vector analytics for pandemic preparedness programs drive periodic demand surges.
- Monoclonal Antibody Production:Legacy bioprocess analytics divert vendor attention from faster-expanding gene therapy segments.
Gene therapy applications generate the highest revenue per instrument; viral vector manufacturing for CDMOs is expanding most quickly in emerging Asian markets.
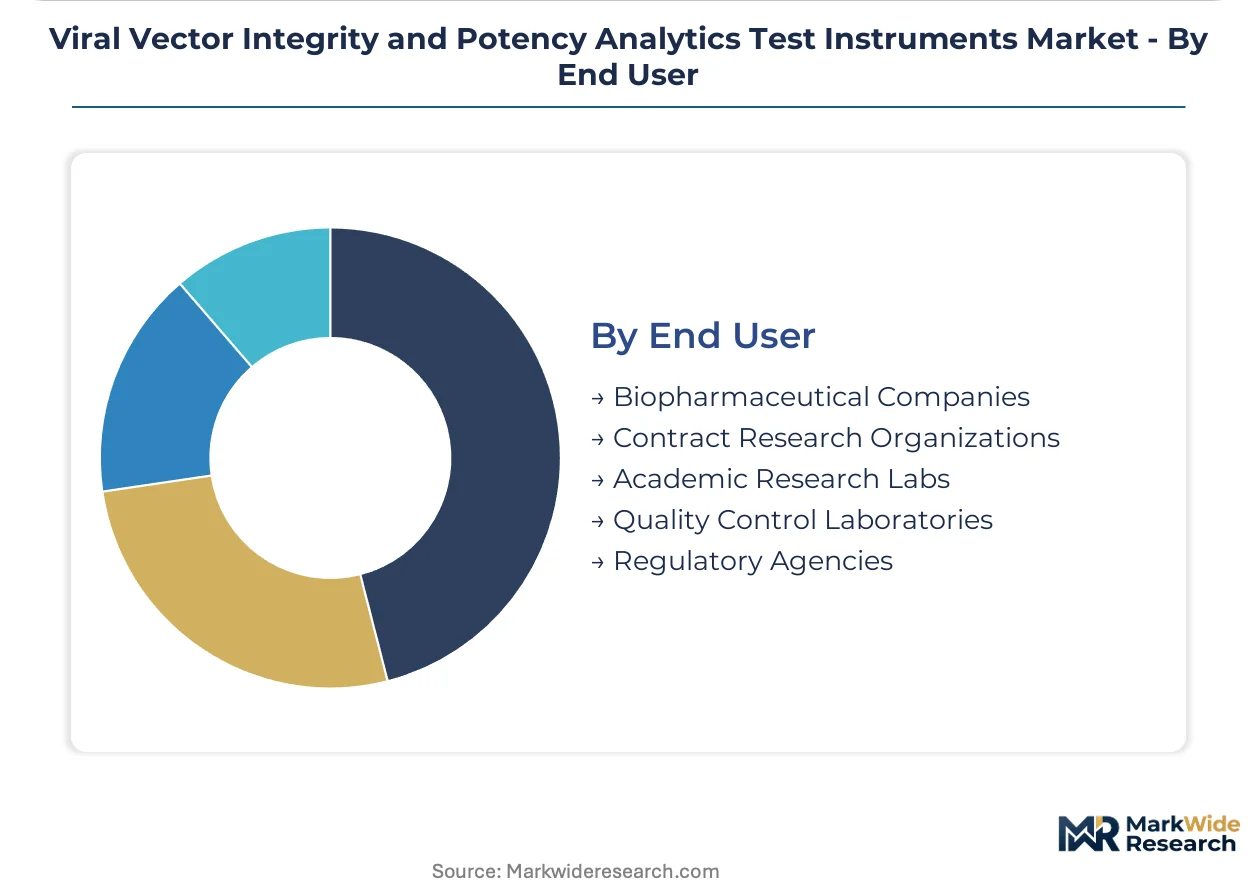
End User:
Procurement authority concentrates in biopharmaceutical quality control departments, while academic labs drive fluorescence and spectrophotometry volume through distributor channels.
- Biopharmaceutical Companies:Internal manufacturing and quality control functions specify GMP-validated platforms with embedded audit trails. Swissmedic and FDA inspection readiness dictates vendor selection criteria.
- Contract Research Organizations:Multi-sponsor program management demands flexible instrument configurations with rapid SOP adaptation capabilities.
- Quality Control Laboratories:Dedicated testing facilities prioritize throughput and regulatory documentation over research flexibility.
- Academic Research Labs:Grant-funded purchases favor modular benchtop systems with open protocol architectures.
- Regulatory Agencies:Reference laboratory instrumentation supports compendial method development and enforcement activities.
Biopharmaceutical companies dominate capital deployment; contract research organizations are gaining share fastest as gene therapy developers outsource analytical validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy developers in Switzerland consume analytical instruments for multi-attribute potency validation, while US manufacturers prioritize high-throughput titer quantification for accelerated BLA timelines.
United States
Massachusetts and California manufacturing clusters drive concentrated demand for flow cytometry and droplet digital PCR systems. FDA potency assay guidance compels viral vector producers to deploy validated platforms with documented traceability ahead of submissions. Greater Boston CDMOs are negotiating unbundled service contracts to accelerate GMP readiness timelines.
Switzerland
Basel-centered biopharma quality control labs anchor European demand for fluorescence detection systems with embedded audit trails. Swissmedic inspection readiness requirements elevate instrument vendors with established notified body relationships. Swiss CDMOs adopt microfluidics platforms to reduce sample consumption for high-value AAV batches destined for neuromuscular gene therapy programs.
Germany
Heidelberg and Munich academic research centers sustain spectrophotometer volume through distributor channels for exploratory vector preparations. EMA ATMP quality requirements force manufacturers to document analytical traceability across every release parameter. Southern German viral vector facilities prioritize ELISA readers for in-process capsid protein monitoring.
India
Hyderabad and Bengaluru CDMO buildouts lack calibrated analytical infrastructure for export-compliant viral vector production. The country's national pharmaceutical regulator enforces evolving GMP standards for gene therapy manufacturing. Emerging manufacturing capacity in Telangana and Karnataka seeks qualified service engineers for instrument deployment.
United Kingdom
London and Oxford gene therapy developers command premium instrument configurations for lentiviral and AAV vector analytics. MHRA alignment with EMA ATMP frameworks compels documented traceability for potency readouts. Southeast England quality control laboratories prioritize throughput and regulatory documentation over research flexibility.
Viral Vector Integrity and Potency Analytics Test Instruments Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the viral vector analytics instrumentation market. Chromatography-mass spectrometry conglomerates and life science conglomerates occupy the upper tier, while droplet digital PCR specialists and microfluidics platform developers populate the mid-market. Competitive positioning hardens around three archetypes: diversified analytical conglomerates, modality-focused precision specialists, and integrated bioanalytical platform builders. Market participants defend position through strategic partnerships with CDMOs and technology licensing arrangements for sample-minimization workflows.
Among diversified analytical conglomerates, Thermo Fisher Scientific and Danaher exemplify the integrated leader archetype through chromatography-mass spectrometry and life science tool portfolios. Bio-Rad Laboratories occupies a position within the precision specialist tier, representing droplet digital PCR expertise for absolute viral genome quantification. Sartorius AG anchors the integrated platform builder segment, consolidating multiple potency readouts into automated analytical runs for gene therapy manufacturers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Sartorius AG |
| Agilent Technologies |
| Waters Corporation |
| Danaher |
| Bruker Corporation |
| QIAGEN |
| Merck |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Massachusetts and California CDMOs runs above regional averages, compressing instrument lead times and elevating price floors for GMP-validated platforms. Swiss and German manufacturing clusters absorb premium pricing for embedded audit trail capabilities, while Indian buyers face cost-plus logistics penalties on imported calibration standards.
Pricing Analysis
Long-term service contracts dominate procurement for validated potency assay platforms, with Massachusetts CDMOs negotiating unbundled qualification packages separate from hardware acquisition. Price differentiation separates FDA-tier validation documentation from research-grade configurations, with helium-dependent mass spectrometry workflows commanding sustained premiums despite supply volatility. Cost compression in mid-tier fluorescence systems is intensifying as microfluidics specialists displace legacy chromatography vendors. Academic research labs exhibit highest price sensitivity; gene therapy developers with BLA timelines show lowest sensitivity to instrument premiums.
Supply Chain Analysis
Germany and Switzerland anchor precision optics and fluidics component fabrication for high-resolution viral titer workflows. China and Japan supply sensor arrays and electrochemical detection modules that feed into integrated platform assembly. The supply chain draws from single-source helium refineries in Qatar and Algeria, creating vulnerability for mass spectrometry-dependent installations. Distribution runs through authorized service networks with qualified field engineers concentrated in Massachusetts, Basel, and San Diego.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
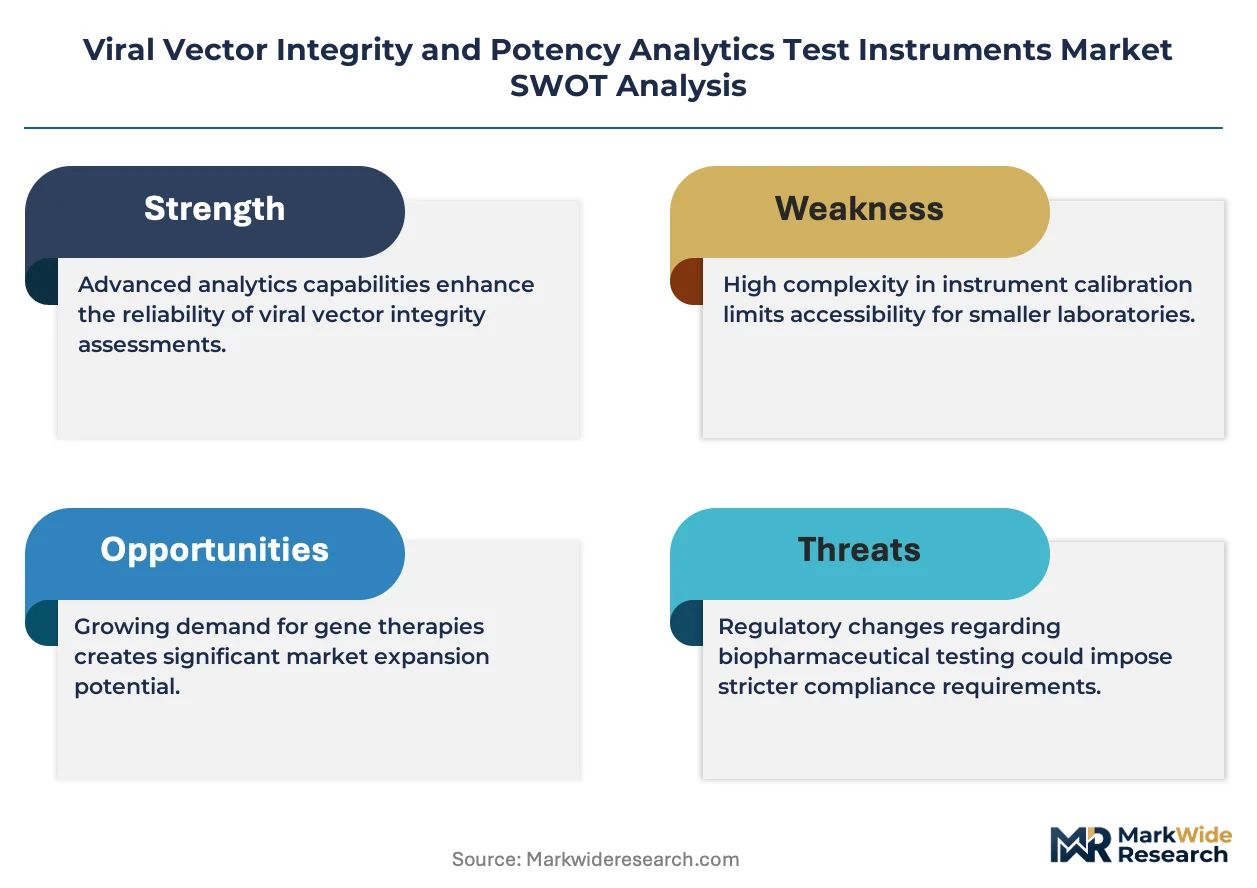
Gene therapy CMC investment cycles are recovering from post-pandemic retrenchment, with FDA potency assay mandates driving replacement demand ahead of BLA submission waves.
For Market Incumbents: Consolidate service engineer density in Massachusetts and Switzerland to defend response-time advantages against emerging microfluidics specialists. Deepen backward integration into consumables manufacturing to capture recurring revenue streams from locked-in titer workflows. For New Entrants and Emerging Players: Differentiate on sample-minimization architectures targeting Swiss neuromuscular gene therapy CDMOs with sub-microliter AAV quantification capabilities. White-space opportunities concentrate in Hyderabad and Bengaluru analytical infrastructure buildouts, where qualified service partnerships unlock CDMO procurement decisions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform builders with automated multi-attribute potency readouts over modular benchtop specialists. Long-term viability hinges on MDR compliance infrastructure and notified body relationships for European gene therapy developer access. Watch EMA in vitro diagnostic reclassification timelines as inflection signals for procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA potency assay validation accelerates BLA submission timelines for gene therapy sponsors. |
| Manufacturing Scale-Up | CDMO buildouts in Massachusetts and California concentrate demand for integrated analytical suites. |
| Strategic Partnership | Microfluidics licensing agreements with Swiss neuromuscular programs secure high-value AAV batch contracts. |
| Acquisition of Specialist Firm | Droplet digital PCR expertise fills capability gaps in absolute viral genome quantification portfolios. |
| Geographic Expansion | Hyderabad and Bengaluru service infrastructure addresses unmet analytical demand in emerging Asian manufacturing. |
Research Methodology
A spread of perspectives from gene therapy CMC executives, analytical chemist team leads, CDMO procurement officers, and regulatory affairs specialists converged on the working assumptions for instrument demand trajectories. Primary fieldwork combined structured interviews with secondary validation against FDA guidance documents, EMA ATMP quality frameworks, Swissmedic inspection protocols, and GMP facility certification databases. Bottom-up installation base modeling triangulated against top-down vendor revenue segmentation.
Segmentation dimensions modeled span product type, detection technology, application workflow, and end-user procurement authority across the projection horizon. CAGRs derived from instrument replacement cycle compression analysis and potency assay mandate compliance timelines. Forecast inputs incorporated analytical chemist labor market tightness indices and helium supply volatility scenarios.
The analysis sits within stated boundaries; outcomes outside sustained FDA enforcement of potency assay guidance or accelerated EMA MDR reclassification would require recalibration. Forecasts reflect documented assumptions regarding CDMO buildout pacing and academic research funding trajectories. Recalibration cycles align with material shifts in gene therapy clinical trial advancement rates and regulatory inspection backlog resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Platelet Function Test Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Global Ovulation Test Market
Testing Services
Global GMP Testing Service Market
Testing Services
Service Laboratory Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Home Care Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Antibiotic Susceptibility Testing Market