
 Skin Perfusion Pressure Testing Devices Market | 2026-2036
Skin Perfusion Pressure Testing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Perfusion Pressure Testing Devices Market Intelligence
Photoplethysmography sensors are displacing traditional laser Doppler modules in mid-range systems, a material-substitution event that is realigning product economics toward semiconductor-based optical arrays. Perimed AB leverages its Nordic manufacturing base to sustain premium positioning in research-grade perfusion platforms. Moor Instruments anchors its commercial presence through specialized laser Doppler systems for microvascular assessment. Viasonix competes on integrated waveform analytics that extend beyond raw perfusion pressure readings.
Skin perfusion pressure testing devices measure microcirculatory blood flow at the dermal capillary level, typically quantifying pressure thresholds between 30 mmHg and 100 mmHg to determine tissue viability and wound healing potential; these instruments serve primarily to guide amputation-level decisions, monitor diabetic foot ulcer progression, and validate revascularization outcomes in peripheral artery disease protocols. Laser Doppler systems dominate the device type landscape due to established clinical validation and reimbursement coding familiarity, while photoplethysmography segments capture faster expansion through lower hardware costs and simplified operator training curves. Non-invasive technology platforms concentrate margin pools where wireless data transmission enables remote monitoring revenue streams.
FDA 510(k) clearance pathways shape device commercialization timelines and predicate selection strategies for manufacturers targeting the US market, while the EU Medical Device Regulation imposes clinical evidence requirements that filter market access for smaller perfusion technology developers. ISO 10993 biocompatibility standards govern sensor materials that contact intact or compromised skin during repeated measurement sessions. Stakeholders must monitor evolving CMS reimbursement determinations for adjunctive perfusion testing in diabetic limb salvage protocols.
Market Dynamics
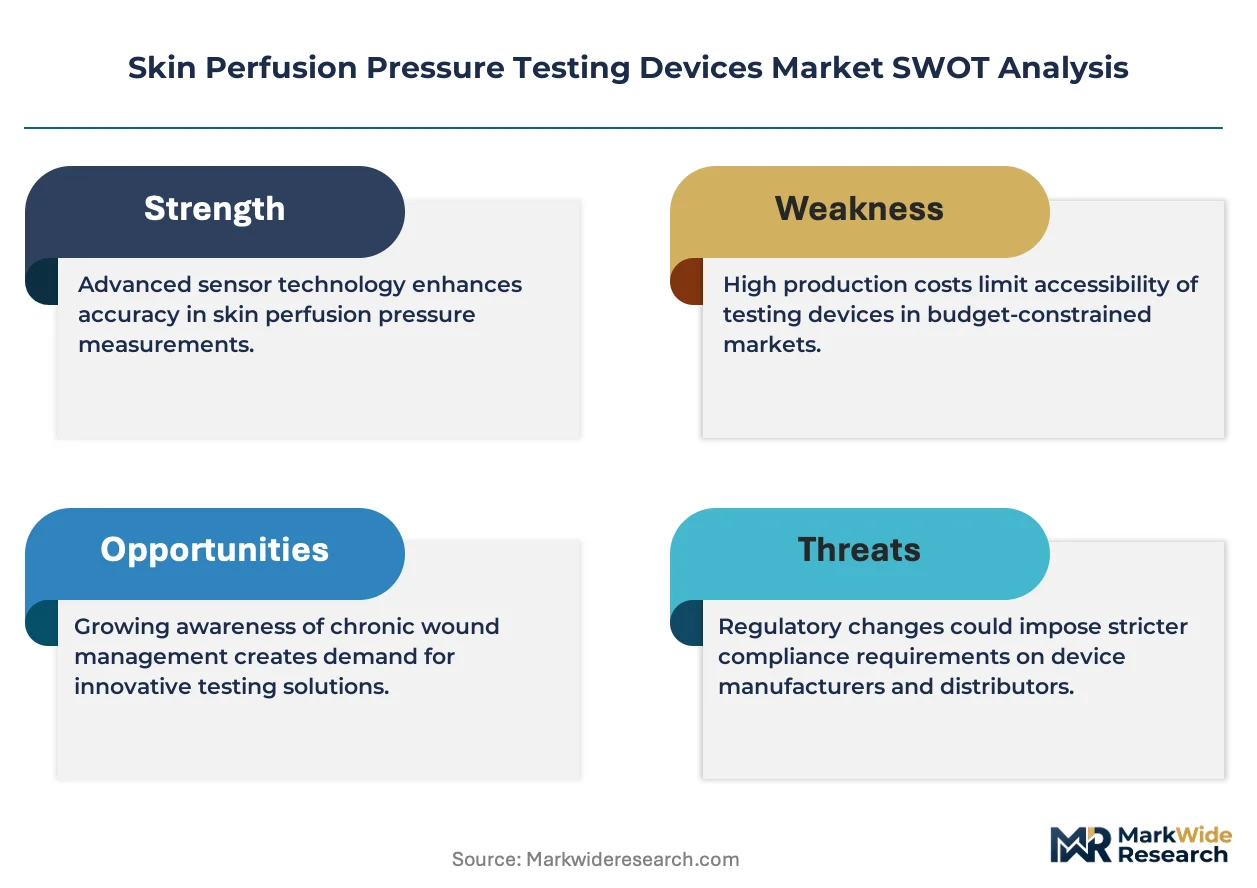
Photoplethysmography sensors are compressing hardware costs and shortening replacement cycles, fundamentally restructuring how wound care centers evaluate capital equipment investments against disposable sensor economics.
Growth Catalysts
- FDA 510(k) pathway streamlining:Predicate device strategies accelerate US market entry for photoplethysmography-based systems, reducing clinical trial burdens relative to novel laser Doppler submissions.
- Diabetic foot ulcer protocols:Hospital-based outpatient wound centers in Germany and Japan are embedding perfusion assessment into standard limb salvage pathways, creating recurring demand for validated measurement tools.
- Wireless connectivity modules:Bluetooth-enabled data transmission is enabling remote monitoring revenue streams that extend device lifetime value beyond initial hardware sales.
Market Restraints
- Semiconductor supply concentration:Optical sensor arrays depend on concentrated Asian foundry capacity, exposing manufacturers to input volatility and extended lead times for photoplethysmography chipsets.
- Laser Doppler reimbursement lock-in:Established CPT coding familiarity creates switching friction for photoplethysmography alternatives despite lower hardware costs.
- EU MDR clinical evidence requirements:Smaller developers face filtered market access as notified bodies demand expanded perfusion validation studies for Class IIa device certifications.
Strategic Opportunities
- Home-based wound monitoring:Post-acute care transitions in the United States are creating demand for simplified, patient-operated perfusion screening devices outside hospital settings.
- Reimbursement tailwinds:CMS adjunctive testing determinations for diabetic limb salvage protocols could expand covered indications beyond current vascular surgery carve-outs.
- Multi-modal sensor fusion:Integration of tissue oxygenation and temperature mapping with pressure readings is opening premium positioning in research-grade platforms.
Industry Challenges
- Operator training standardization:Variability in probe placement technique across wound care technicians produces measurement inconsistency that undermines clinical confidence in non-laser modalities.
- Legacy EMR integration:Proprietary data formats from specialized perfusion devices require custom interface development for seamless inclusion in electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Perfusion Pressure Testing Devices Market |
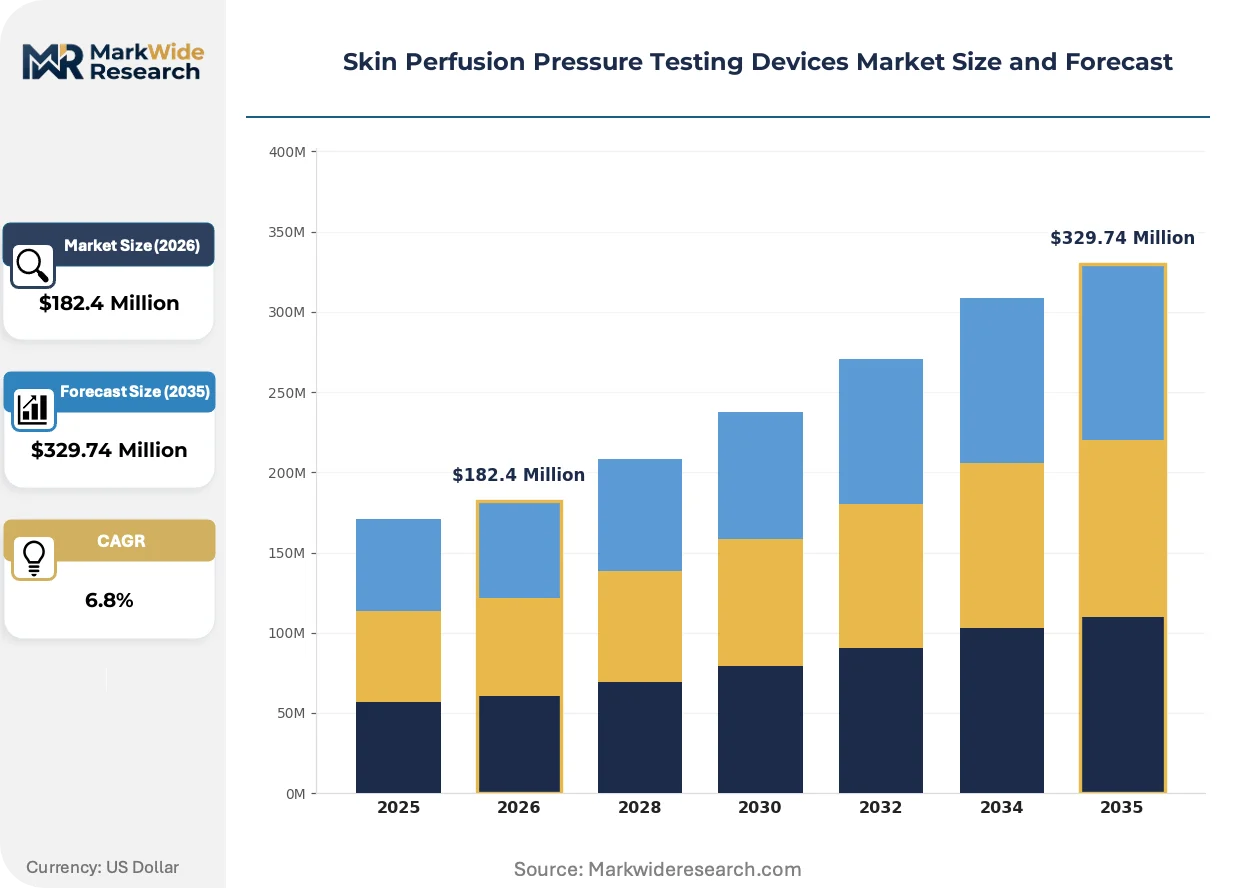
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $329.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laser Doppler, Transcutaneous Oxygen Monitors, Capillary Refill Devices, Photoplethysmography End User: Hospitals, Clinics, Research Institutes, Rehabilitation Centers Technology: Invasive, Non-Invasive, Wireless, Wearable Application: Critical Care, Diabetes Management, Wound Healing, Aesthetic Medicine |
| Companies Covered | Perimed AB, Moor Instruments, Viasonix, Vasamed, ADInstruments, CorVascular Diagnostics, Koven Technology, Promed Group, ELCAT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Perfusion Pressure Testing Devices Market Strategic Shifts & Innovations
Device architecture is pivoting from standalone measurement instruments toward connected diagnostic nodes, with software analytics and sensor miniaturization commanding greater R&D allocation than optical hardware refinement.
Photoplethysmography arrays are converging with machine learning-based waveform classification to enable automated tissue viability scoring without specialist interpretation. Outpatient wound centers in the United States are piloting these systems for nurse-operated screening protocols. The technology is converging with cloud-based decision support platforms that compress time-to-treatment decisions in high-volume diabetic foot clinics.
The EU Medical Device Regulation is mandating post-market clinical follow-up for perfusion devices, forcing manufacturers to maintain active surveillance registries rather than relying on pre-market validation alone. This surveillance obligation is elevating compliance costs disproportionately for single-product developers. Laser Doppler incumbents with established clinical publication libraries are leveraging historical data to satisfy PMCF requirements with lower incremental investment.
Hospital procurement committees are unbundling hardware acquisition from software subscription tiers, treating waveform analytics platforms as recurring service purchases rather than capital equipment add-ons. This shift is compressing upfront device pricing while extending vendor revenue visibility through multi-year data licensing agreements. Western European hospital networks are leading this contractual evolution, with Nordic procurement consortia establishing template terms that favor outcome-linked payment structures.
Skin Perfusion Pressure Testing Devices Market Segmentation
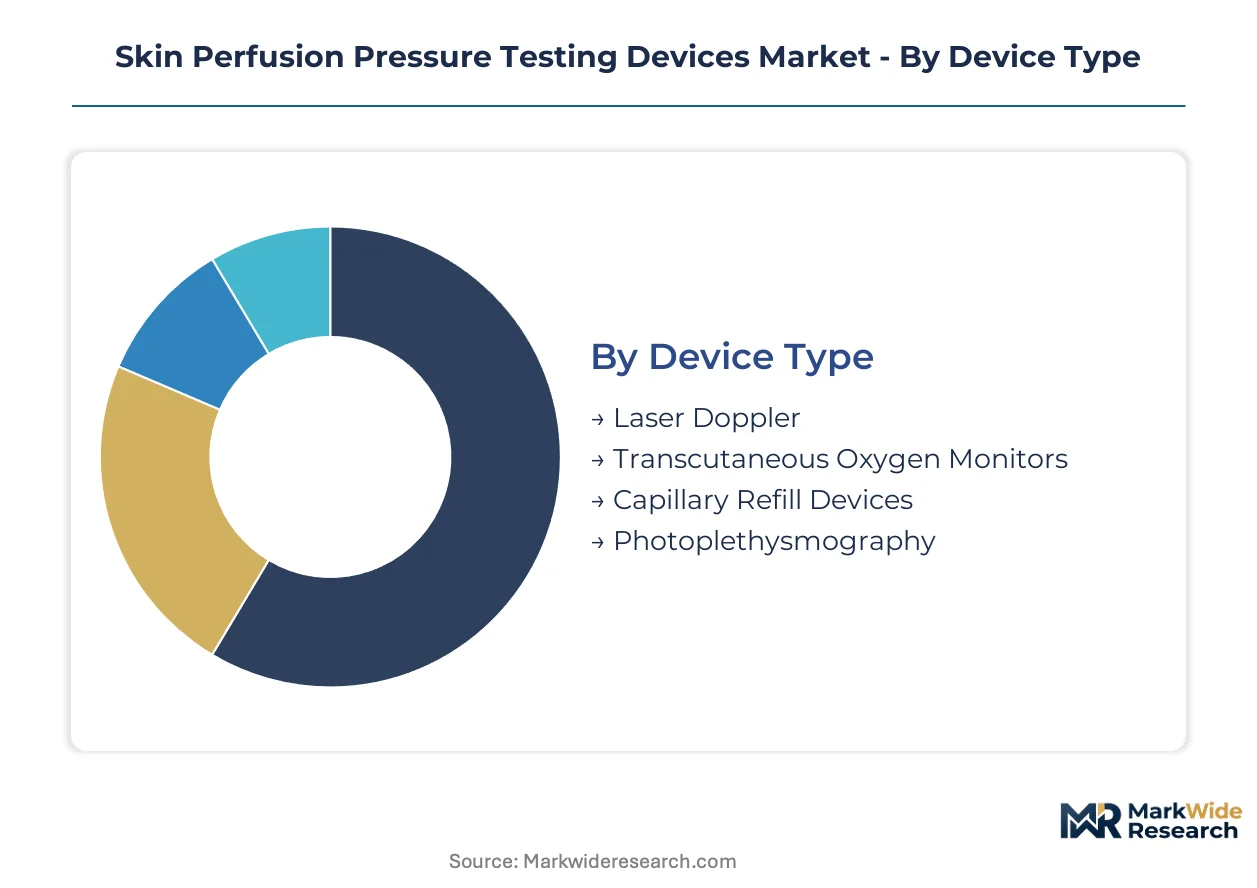
Segmentation in skin perfusion pressure testing reveals how clinical workflows, reimbursement structures, and technology maturation create divergent investment profiles across customer types. Understanding these splits enables manufacturers to align R&D allocation with segments where hardware economics and service revenue models intersect most favorably.
Device Type:
Customization intensity spans from research-grade modular platforms to standardized point-of-care units, with semiconductor content and optical complexity driving the standardization gradient.
- Laser Doppler:These systems employ coherent light scattering to quantify microvascular blood flow velocity at capillary beds. Vascular surgery departments in Germany and Japan maintain installed bases for amputation-level decision protocols, though replacement cycles lengthen as photoplethysmography alternatives capture mid-range evaluations.
- Photoplethysmography:Semiconductor optical arrays measure volumetric blood flow changes through transmitted or reflected light, eliminating moving parts and reducing per-test consumables. Outpatient wound centers in the United States are standardizing on these systems for diabetic foot screening given simplified operator training and lower capital thresholds.
- Transcutaneous Oxygen Monitors:Electrode-based systems quantify tissue oxygen tension through heated skin sensors.
- Capillary Refill Devices:Manual or semi-automated tools assess peripheral perfusion through pressure application and color return timing.
Most installed capacity flows through Laser Doppler systems given decades of clinical validation. Expansion is steepest in Photoplethysmography as cost compression and wireless integration reshape procurement economics.
End User:
Capital intensity and reimbursement access separate customers into equipment purchasers versus service subscribers, with hospital procurement committees demanding outcome-linked contracts that smaller facilities cannot negotiate.
- Hospitals:Academic medical centers and tertiary hospitals deploy multi-modal perfusion platforms integrating pressure, oxygenation, and temperature mapping for complex limb salvage cases. CMS reimbursement carve-outs for vascular surgery procedures sustain capital budget allocations in United States hospital-based outpatient wound centers.
- Clinics:Specialized vascular and wound care clinics prioritize portable, nurse-operated devices with cloud connectivity for remote physician oversight. These facilities in Western Europe are piloting subscription-based analytics tiers rather than perpetual software licenses.
- Research Institutes:Preclinical and clinical research organizations require calibrated, publication-grade systems with validated measurement protocols.
- Rehabilitation Centers:Post-acute facilities focus on simplified screening tools for monitoring healing progression after revascularization procedures.
Revenue concentration sits with Hospitals given bundled payment structures for diabetic limb salvage. Clinics are gaining share fastest as ambulatory site-of-care shifts accelerate in the United States and Germany.
Technology:
Connectivity architecture and patient contact duration distinguish segments, with wireless modules commanding premium positioning through recurring data service revenue streams.
- Non-Invasive:Optical and pressure-based sensors eliminate skin penetration, enabling repeated measurement sessions without infection risk or patient discomfort. These platforms dominate outpatient protocols where throughput and patient compliance determine operational viability.
- Wireless:Bluetooth and Wi-Fi enabled devices transmit waveform data to cloud analytics platforms, supporting remote monitoring and multi-site registry participation. The EU Medical Device Regulation's post-market clinical follow-up requirements are accelerating adoption of connected systems that simplify surveillance data collection.
- Invasive:Catheter-based or needle-probe systems for intraoperative or intensive care applications.
- Wearable:Miniaturized sensors for continuous ambulatory monitoring outside clinical settings.
Non-Invasive systems carry the majority of active installations. Wireless configurations are climbing the fastest as hospital procurement committees unbundle hardware from analytics subscriptions.
Application:
Clinical urgency and reimbursement specificity separate applications into acute intervention pathways versus chronic disease management programs with diverging equipment utilization rates.
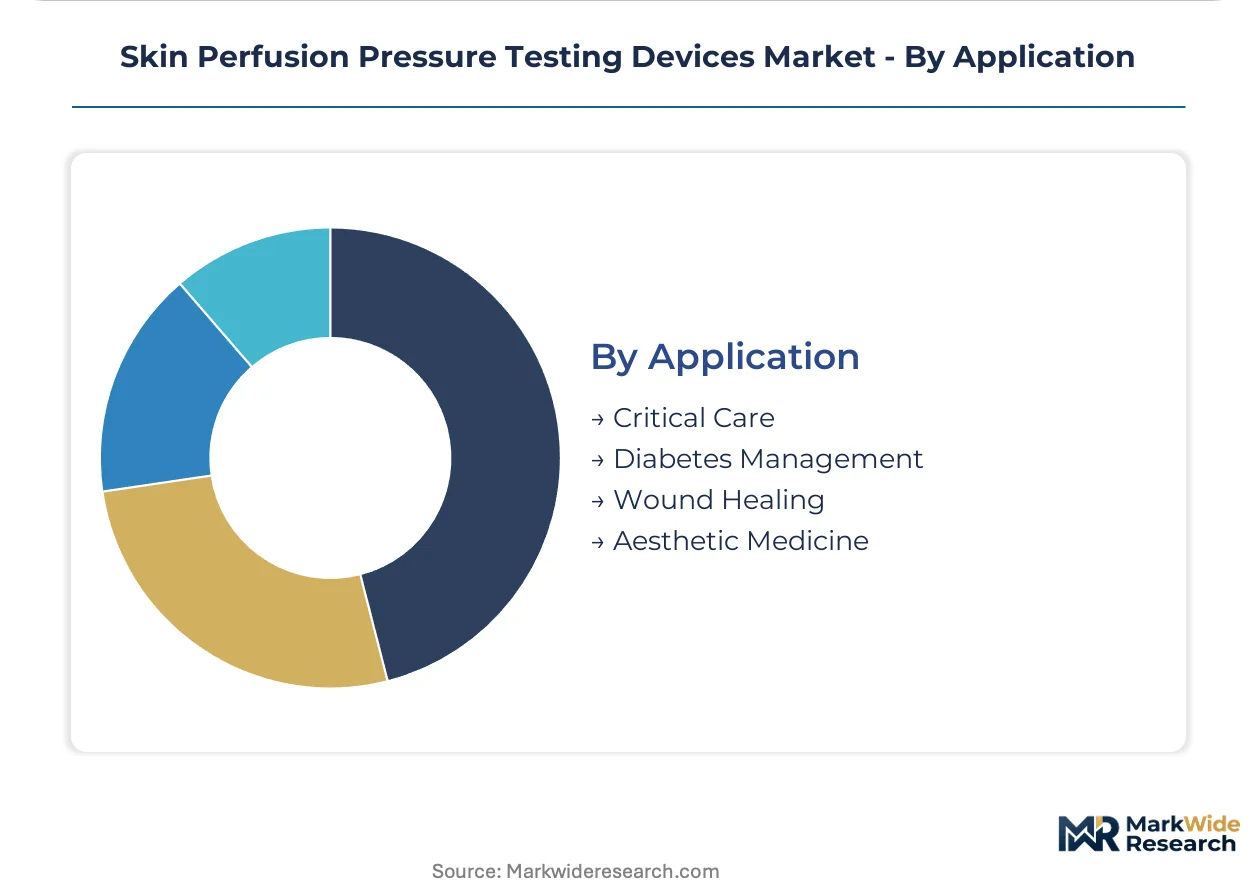
- Wound Healing:Perfusion assessment guides debridement timing, graft selection, and amputation level decisions in diabetic foot ulcer and pressure injury protocols. Hospital-based outpatient wound centers in the United States embed these measurements into standard limb salvage pathways with dedicated technician staffing.
- Diabetes Management:Routine screening for peripheral artery disease in diabetic patients enables early revascularization referral before critical limb ischemia develops. Endocrinology practices in Japan are integrating perfusion testing into annual complication screening protocols.
- Critical Care:Hemodynamic monitoring in intensive care units for shock assessment and resuscitation endpoint determination.
- Aesthetic Medicine:Perfusion evaluation for flap viability in reconstructive and cosmetic procedures.
Wound Healing applications account for the largest installed base given established diabetic foot ulcer protocols. Diabetes Management is expanding most quickly as screening guidelines broaden and point-of-care devices simplify technician workflow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital-based outpatient wound centers in the United States anchor commercial demand for skin perfusion pressure testing devices, while vascular clinics in Germany and Japan accelerate adoption of non-invasive perfusion assessment tools. Wireless connectivity integration is compressing device replacement cycles across wound care protocols in Western Europe and East Asia.
United States
CMS reimbursement carve-outs for vascular surgery procedures sustain capital budget allocations in hospital-based outpatient wound centers. FDA 510(k) clearance pathways shape predicate device strategies for photoplethysmography-based systems entering the market. Greater Boston and the Northeast Corridor concentrate academic medical center procurement of multi-modal perfusion platforms for complex limb salvage cases.
Germany
Vascular surgery departments in university hospitals maintain installed bases of laser Doppler systems for amputation-level decision protocols. EU Medical Device Regulation clinical evidence requirements filter market access for smaller perfusion technology developers seeking Class IIa certification. The Rhine-Ruhr metropolitan region hosts specialized vascular clinics embedding perfusion assessment into standard diabetic foot ulcer pathways.
Japan
Endocrinology practices integrate perfusion testing into annual diabetic complication screening protocols, creating recurring demand for point-of-care devices. PMDA regulatory frameworks govern commercialization timelines for non-invasive diagnostic devices entering the domestic market. The Kanto region around Tokyo concentrates hospital procurement of wireless-enabled systems for remote monitoring revenue streams.
United Kingdom
NHS procurement committees unbundle hardware acquisition from software subscription tiers, treating waveform analytics as recurring service purchases. MHRA post-market surveillance requirements align with EU MDR obligations for connected diagnostic devices. London and the Southeast lead pilot programs for nurse-operated screening protocols in outpatient wound centers.
France
Hospital networks in the Île-de-France region pilot outcome-linked payment structures for perfusion testing in diabetic limb salvage. ANSM oversight of Class IIa medical devices shapes clinical evidence requirements for market entry. The Auvergne-Rhône-Alpes cluster concentrates research-grade platform adoption for microvascular assessment in academic settings.
Skin Perfusion Pressure Testing Devices Market Key Industry Players
Global majors compete with regional champions across regulatory compliance capabilities and reimbursement navigation expertise. The vendor base separates into laser Doppler incumbents with established clinical publication libraries, photoplethysmography specialists exploiting semiconductor cost compression, and integrated diagnostics platforms bundling hardware with analytics subscriptions. Strategic moves concentrate on M&A for regulatory predicate acquisition and technology licensing for wireless connectivity modules.
Within the research-grade platform tier, Perimed AB exemplifies Nordic manufacturing-based premium positioning, while Moor Instruments anchors specialized laser Doppler presence for microvascular assessment. Viasonix occupies a position emphasizing integrated waveform analytics beyond raw perfusion pressure readings. These three entities represent divergent archetypes: geographic manufacturing advantage, modality specialization, and software-forward differentiation.
| Leading Market Players |
|---|
| Perimed AB |
| Moor Instruments |
| Viasonix |
| Vasamed |
| ADInstruments |
| CorVascular Diagnostics |
| Koven Technology |
| Promed Group |
| ELCAT |
| Others |
Cost & Logistics Intelligence
Optical sensor engineering talent concentration in Nordic manufacturing regions widens pricing-tier spreads between research-grade laser Doppler platforms and cost-optimized photoplethysmography systems, as semiconductor fabrication labor differentials compress mid-range device margins faster than premium instrumentation.
Pricing Analysis
Input-cost pass-through from optical sensor arrays to finished device pricing operates unevenly across tier levels. A three-tier pricing structure across premium, standard, and economy levels separates research-calibrated systems with ISO 17025 traceability from point-of-care units with simplified waveform outputs. Price differentiation hinges on certification grade and after-sales analytics bundling. Pricing pressure stems from photoplethysmography chip commoditization in Asian foundries. Outpatient wound centers in the United States exhibit highest price sensitivity, while academic medical centers in Germany tolerate premium positioning for publication-grade validation.
Supply Chain Analysis
Warehouse-distribution layer configuration centers on regional distribution hubs in Germany, Japan, and the United States that buffer lead-time volatility for semiconductor optical components. Photoplethysmography sensor arrays draw from concentrated foundry capacity in Taiwan and South Korea, while laser Doppler modules source precision optics from German and Swiss suppliers. Single-source vulnerability in photodiode fabrication creates exposure to foundry allocation disruptions. Distribution runs through authorized medical device distributors with cold-chain capabilities for calibrated sensor storage, supplemented by direct hospital contracting for multi-unit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and France exceed FDA 510(k) pathway expenditures in the United States, creating differential margin structures for manufacturers with dual-continent regulatory capabilities.
For Market Incumbents: Anticipate photoplethysmography substitution pressure by deepening software analytics moats through machine learning-based waveform classification. Laser Doppler specialists should leverage existing clinical publication libraries to satisfy EU MDR post-market clinical follow-up obligations with lower incremental investment than emerging competitors. Priority defensive moves include acquiring wireless connectivity module suppliers and securing long-term photodiode supply agreements with Taiwanese foundries. For New Entrants and Emerging Players: Cloud-native waveform analytics platforms offer the most penetrable entry vector against legacy hardware incumbents with proprietary data formats. Home-based wound monitoring in the United States post-acute care transition represents underserved white space with simplified regulatory pathways compared to hospital procurement. Target ambulatory surgery centers and specialized wound clinics in Western Europe with subscription-based analytics tiers rather than capital equipment sales. For Investors and Strategic Acquirers: Integrated diagnostics platforms with hardware-software bundling capabilities are the most active acquirer in this space, seeking regulatory predicate devices and wireless connectivity IP. Long-term viability favors vendors with recurring revenue visibility through multi-year data licensing rather than transactional hardware margins. Acquisition target archetypes include photoplethysmography chipset developers with FDA predicates and cloud analytics specialists with hospital EMR integration capabilities. Monitor CMS reimbursement determinations for adjunctive perfusion testing as the critical inflection signal for diabetic limb salvage protocol expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Predicate Acquisition | Accelerated US market entry for photoplethysmography systems reduces clinical trial burdens relative to novel submissions. |
| Wireless Connectivity Module Licensing | Bluetooth-enabled data transmission enables remote monitoring revenue streams extending device lifetime value. |
| Hospital System Partnership | Academic medical center alliances in Greater Boston anchor multi-modal platform adoption for complex limb salvage. |
| Software Companion Development | Machine learning-based waveform classification automates tissue viability scoring without specialist interpretation. |
| Reimbursement Strategy | CMS adjunctive testing determinations for diabetic limb salvage protocols expand covered indications beyond vascular surgery carve-outs. |
Research Approach
Direct dialogue with vascular surgeons, wound care technicians, hospital purchasing committee members, and biomedical engineers grounded qualitative insights, cross-referenced against FDA 510(k) filings, EU MDR notified body documentation, CMS reimbursement determinations, and hospital procurement databases. Bottom-up device shipment estimates triangulated with top-down healthcare expenditure allocation models across the analysis window.
Segment-level outputs across device type, end user, technology, and application dimensions were generated through structured modeling of replacement cycle dynamics, wireless adoption curves, and reimbursement expansion scenarios. CAGRs were derived from regression analysis of historical adoption patterns and forward projection of regulatory pathway efficiencies. Forecast inputs included semiconductor cost compression trajectories and EU MDR compliance cost escalations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement policy shifts and foundry capacity allocation for optical sensor arrays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Healthcare Analytical Testing Services Market
Testing Services
Europe Newborn Screening Market
Testing Services
North America Drug Screening Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Diagnostic Shipper Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Influenza Home Testing Market
Testing Services
Hospital Microbiology Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market