
 Global Sleep Testing Services Market | 2026-2036
Global Sleep Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sleep Testing Services Market Foresight
Telemedicine providers is expanding their share of sleep testing referrals as patients seek alternatives to overnight clinic visits. ResMed Inc. leverages its portable monitor ecosystem to sustain direct-to-consumer and clinical channel presence. Cleveland Clinic anchors academic credibility through integrated sleep medicine research and diagnostic volume. Koninklijke Philips N.V. competes across both hardware and service layers, differentiating through cloud-based platform integration with hospital EMR systems.
Sleep testing services encompass overnight physiological monitoring, daytime nap studies, and longitudinal activity tracking to diagnose disorders such as obstructive sleep apnea and narcolepsy. Polysomnography remains the gold standard, requiring EEG, EOG, EMG, airflow, and oximetry channels sampled at minimum 200 Hz for respiratory event scoring. Home sleep apnea testing captures the fastest growth trajectory among service types, driven by payer cost containment and patient convenience preferences, while wearable devices and portable monitors concentrate margin pools through recurring software subscriptions and remote interpretation fees.
The FDA regulates home diagnostic devices through 510(k) clearance pathways, while the EMA's MDR framework imposes stricter clinical evidence requirements on European service providers using novel sensors. Japan's PMDA maintains distinct approval standards for contactless monitoring technologies, creating market access friction for cloud-based platform vendors. Stakeholders must monitor reimbursement parity between in-lab polysomnography and home testing across Medicare, statutory health insurers, and private payers to anticipate volume shifts between service modalities.
Market Dynamics
The migration from facility-based polysomnography to home sleep apnea testing is compressing diagnostic costs while fragmenting service delivery across telemedicine platforms, wearable manufacturers, and traditional sleep centers competing for interpretation volume.
Growth Catalysts
- Reimbursement parity policies:Medicare's expanded coverage for home sleep apnea testing in the United States validates remote diagnostic pathways and accelerates payer adoption across commercial insurance networks.
- Aging demographics in Japan and Germany:Elevated sleep disorder prevalence among populations over 65 drives clinical referral volume and sustains demand for both in-lab and home-based testing modalities.
- Cloud-based platform integration:Sleep laboratories are deploying interoperable data architectures that streamline physician workflow and enable longitudinal patient monitoring beyond single-night studies.
Market Restraints
- Semiconductor supply concentration:Portable monitor production depends on specialized analog-to-digital converters and MEMS sensors sourced from concentrated Asian foundry capacity, creating input vulnerability.
- EMA MDR clinical evidence requirements:European service providers face extended validation timelines for novel sensor technologies, delaying market entry for contactless monitoring platforms.
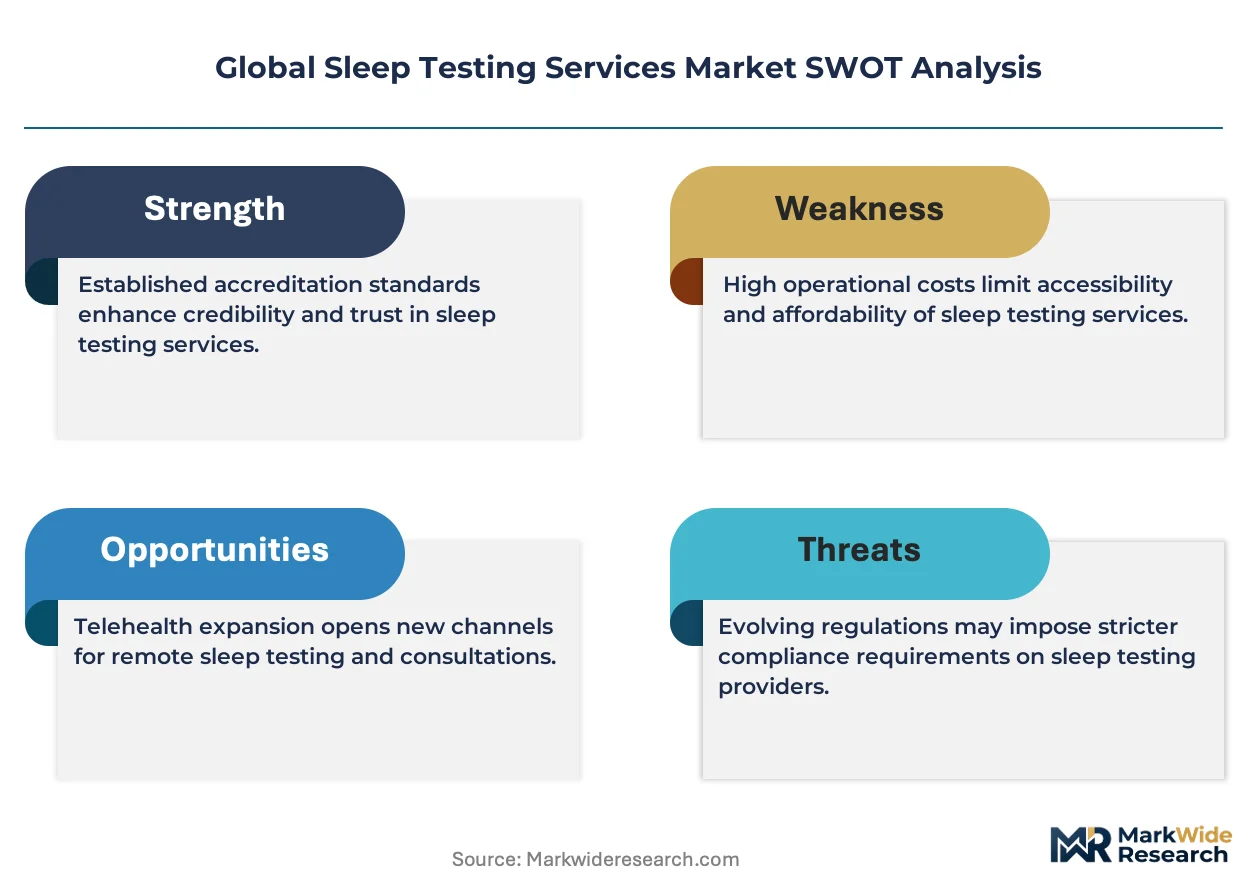
- Technical limitation in EEG signal fidelity:Home-based devices cannot replicate the cranial electrode density of in-lab polysomnography, constraining diagnostic certainty for narcolepsy and complex parasomnias.
Strategic Opportunities
- Underpenetrated rural United States:Sleep specialist deserts across Appalachia and the Mountain West create white space for asynchronous telemedicine interpretation services paired with mail-order diagnostic kits.
- Cardiovascular comorbidity screening integration:Sleep testing services are embedding into cardiology workflows as atrial fibrillation and hypertension management programs adopt apnea screening protocols.
- Japan PMDA contactless monitoring pathway:Regulatory clarity for radar-based and optical sleep monitoring without skin contact enables new hardware categories and service delivery models.
Industry Challenges
- Registered polysomnographic technologist scarcity:The specialized credentialing pipeline cannot match testing volume growth, creating interpretation bottlenecks and quality control risks.
- Legacy EMR integration complexity:Sleep data formats lack standardization across vendor platforms, forcing costly custom interfaces for hospital system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sleep Testing Services Market |
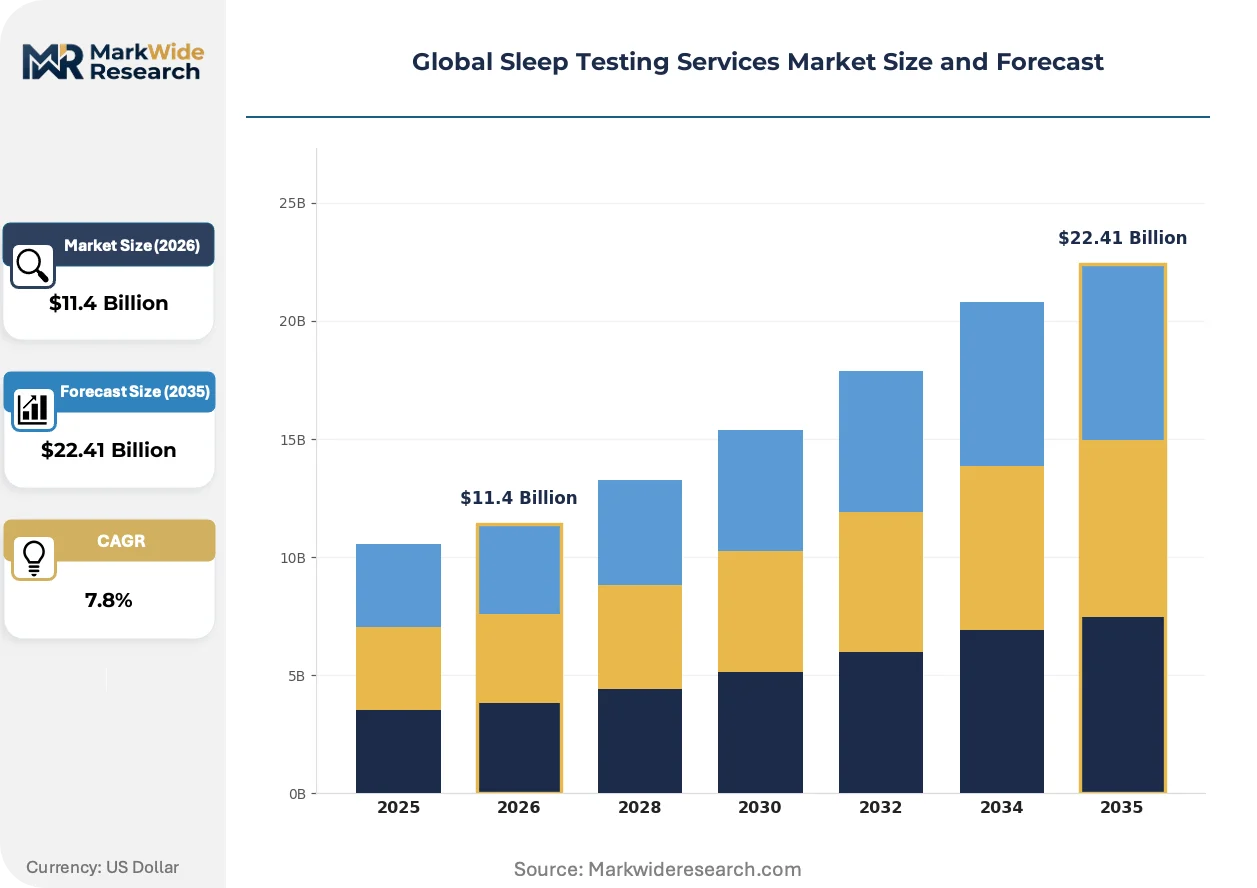
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Polysomnography, Home Sleep Apnea Testing, Multiple Sleep Latency Test, Maintenance of Wakefulness Test, Actigraphy End User: Sleep Clinics, Diagnostic Centers, Telemedicine Providers, Ambulatory Care Facilities, Specialty Hospitals Technology: Wearable Devices, Portable Monitors, Contact Sensors, Non-contact Sensors, Cloud-based Platforms Application: Obstructive Sleep Apnea, Narcolepsy, Restless Leg Syndrome, Insomnia, Circadian Rhythm Disorders |
| Companies Covered | SleepMed Inc., SOVA Sleep Services Inc., ResMed Inc., Cleveland Clinic, Itamar Medical Ltd, Koninklijke Philips N.V., Midwest Sleep Services Inc., Circle Health Group, Natus Medical Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sleep Testing Services Market Shifts & Advancements
Artificial intelligence interpretation algorithms and consumer-grade wearable sensors are redrawing the boundary between clinical-grade diagnostics and wellness monitoring, forcing service providers to defend their value proposition through physician oversight and diagnostic certainty.
Machine learning scoring algorithms are converging with polysomnography workflow software to automate respiratory event detection and sleep stage classification. Sleep laboratories in the United States and Germany are piloting FDA-cleared and CE-marked platforms that reduce technologist interpretation burden by 40-60%. This convergence is compressing turnaround times from 72 hours to same-day reporting and enabling higher test throughput without proportional staffing expansion.
The FDA's evolving 510(k) guidance for home-based medical devices is creating distinct clearance pathways for software-as-a-medical-device sleep scoring applications. Hardware manufacturers must now submit clinical validation data demonstrating diagnostic equivalence to in-lab polysomnography for specific disorder categories. Wearable device vendors targeting the United States market are responding by sponsoring prospective validation studies and partnering with academic sleep centers for regulatory-grade evidence generation.
Employer-sponsored wellness programs are unbundling sleep screening from traditional health benefit structures and contracting directly with telemedicine diagnostic platforms. Large self-insured employers in the United States are bypassing payer networks to negotiate per-employee-per-month fees for unlimited home sleep testing access. This channel disintermediation is most visible in the manufacturing and transportation sectors where untreated sleep apnea carries direct occupational safety liability.
Global Sleep Testing Services Market Segmentation
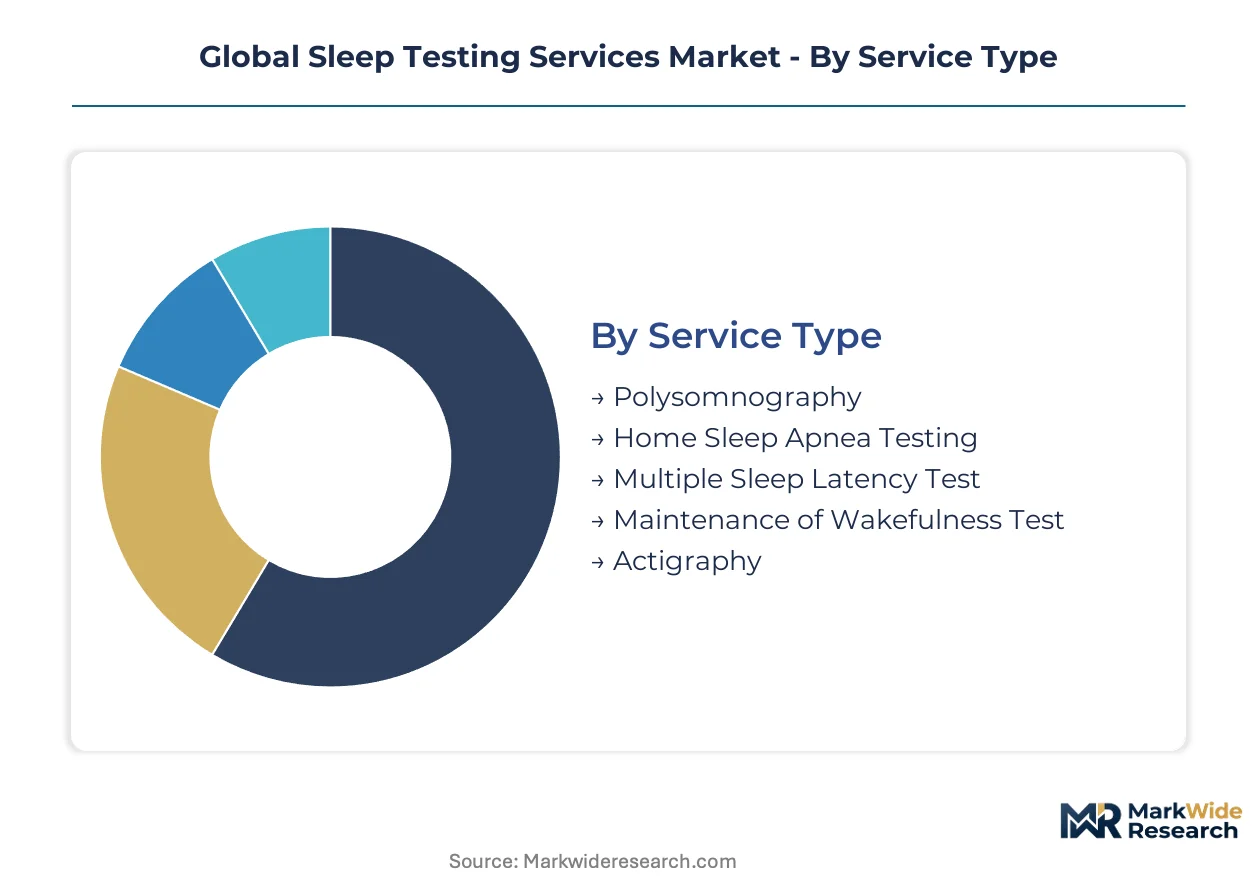
Sleep testing services fragment across four distinct dimensions that determine pricing power, capital requirements, and regulatory exposure. Service modality shapes reimbursement rates. Technology choices dictate hardware refresh cycles and software subscription economics. Understanding these segment boundaries clarifies where margin pools concentrate versus where commodification pressures intensify.
Service Type:
Capital intensity varies sharply across modalities, with in-lab infrastructure demanding the heaviest upfront investment in specialized facilities and credentialed staffing.
- Polysomnography:Comprehensive overnight monitoring captures EEG, EOG, EMG, respiratory airflow, and oximetry at 200+ Hz sampling rates. Sleep clinics in the United States and Germany maintain this capability for complex parasomnia and narcolepsy diagnosis where home-based alternatives lack cranial electrode density.
- Home Sleep Apnea Testing:Simplified portable monitors measuring airflow, respiratory effort, and blood oxygen saturation dominate volume expansion. Payer cost containment in Medicare and commercial networks accelerates patient preference for avoiding overnight facility stays.
- Multiple Sleep Latency Test:Daytime nap protocol quantifying sleep onset speed serves narcolepsy confirmation. Requires controlled laboratory environment limiting deployment to academic medical centers and specialty hospitals.
- Maintenance of Wakefulness Test:Sustained alertness assessment for occupational safety clearance in transportation and nuclear sectors. Regulatory mandates from the FAA and DOT sustain referral volume for commercial driver medical certification.
- Actigraphy:Wrist-worn accelerometer logging sleep-wake patterns over extended durations. Circadian medicine programs and psychiatric services deploy this for longitudinal behavioral monitoring where single-night snapshots prove insufficient.
Most installed capacity flows through polysomnography suites in hospital-affiliated sleep centers. Expansion is steepest in home sleep apnea testing as telemedicine platforms capture primary care referral streams.
End User:
Customer type determines procurement sophistication, with institutional buyers negotiating enterprise pricing while direct-to-consumer channels command premium per-test margins.
- Sleep Clinics:Dedicated facilities combining diagnostic testing with therapeutic intervention maintain the highest test throughput per square foot. Cleveland Clinic and Stanford Sleep Medicine anchor academic credibility while independent chains compete on geographic convenience.
- Telemedicine Providers:Virtual-first platforms coordinate mail-order device distribution with asynchronous physician interpretation. Employer-sponsored wellness programs in the United States manufacturing and transportation sectors bypass traditional payer networks for direct contracting.
- Diagnostic Centers:Multi-specialty imaging and laboratory chains add sleep testing to capture downstream cardiology and neurology referrals. Equipment utilization rates suffer against dedicated competitors lacking cross-referral density.
- Ambulatory Care Facilities:Urgent care and primary care networks embed basic screening for apnea detection. Limited to home testing modalities given overnight staffing constraints.
- Specialty Hospitals:Cardiovascular and psychiatric institutions integrate sleep evaluation into comorbidity management. Atrial fibrillation ablation programs and depression treatment protocols mandate pre-procedural apnea screening.
Revenue concentration sits with sleep clinics capturing complex diagnostic cases. Telemedicine providers are gaining share fastest through employer channel disintermediation.
Technology:
Hardware-software bundling strategies separate margin-accretive platform vendors from commodity sensor suppliers facing replacement pressure.
- Portable Monitors:FDA-cleared and CE-marked devices from ResMed and Philips capture the core home testing market. Recurring revenue attaches through proprietary cloud interpretation services and automated scoring subscriptions.
- Cloud-based Platforms:Interoperable data architectures enabling EMR integration and longitudinal patient dashboards command premium licensing fees. Hospital systems in Germany prioritize vendors with HL7 FHIR compliance for seamless workflow embedding.
- Wearable Devices:Consumer-grade accelerometers and optical heart rate sensors from Apple and Garmin encroach on clinical adjacencies. Diagnostic certainty limitations constrain reimbursement to wellness screening rather than definitive diagnosis.
- Contact Sensors:Traditional adhesive electrodes and nasal cannulas maintain gold-standard signal fidelity for in-lab polysomnography. Single-use consumable economics sustain recurring revenue for laboratory suppliers.
- Non-contact Sensors:Radar-based and thermal imaging technologies under PMDA review in Japan promise skin-free monitoring. Regulatory validation timelines in Europe under MDR clinical evidence requirements delay commercial deployment.
Portable monitors and cloud platforms together capture the dominant share of service delivery infrastructure. Non-contact sensors are climbing the fastest as regulatory pathways clarify for contactless physiological monitoring.
Application:
Disease prevalence and reimbursement clarity determine addressable market size, with cardiovascular comorbidity linkages expanding screening indications beyond symptomatic presentation.
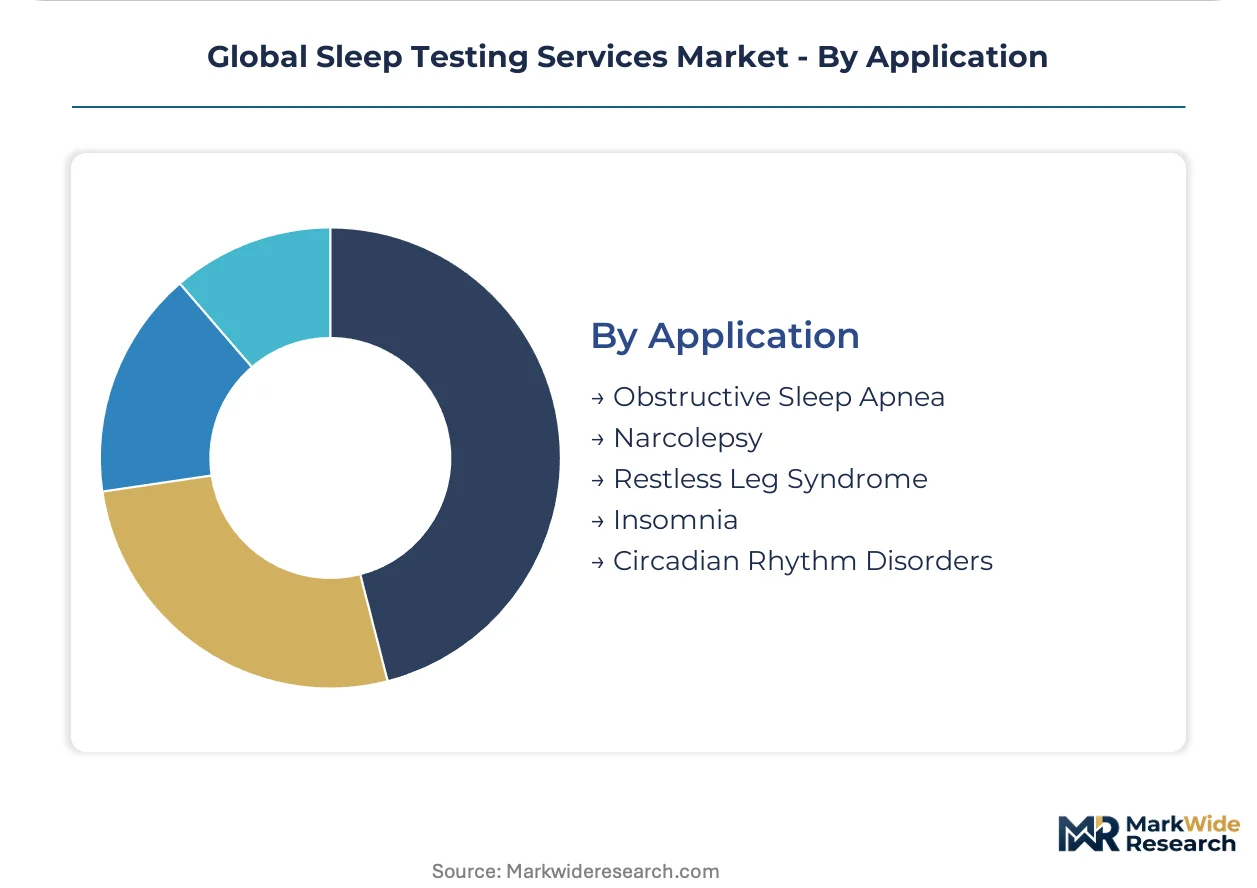
- Obstructive Sleep Apnea:Collapsible upper airway anatomy producing recurrent hypopnea and desaturation events affects an estimated one billion adults globally. Hypertension and atrial fibrillation management protocols in the United States and Japan now embed mandatory screening.
- Insomnia:Chronic sleep initiation and maintenance complaints drive cognitive behavioral therapy referral rather than physiological testing. Actigraphy and sleep diary validation support treatment monitoring where polysomnography adds limited diagnostic value.
- Narcolepsy:Hypocretin deficiency producing cataplexy and sudden sleep attacks requires multiple sleep latency testing for definitive diagnosis. Rare disease prevalence concentrates caseload at academic sleep centers with specialized expertise.
- Restless Leg Syndrome:Urge-to-move sensations disrupting sleep onset respond to dopaminergic therapy without mandatory physiological confirmation. Testing reserved for atypical presentations or treatment-resistant cases.
- Circadian Rhythm Disorders:Misalignment between biological clock and environmental demands affects shift workers and delayed sleep phase adolescents. Actigraphy and melatonin sampling guide chronotherapy intervention.
Obstructive sleep apnea commands the preponderance of testing volume and reimbursement dollars. Cardiovascular integration is expanding diagnostic capture fastest among asymptomatic populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping service delivery geography as vendors relocate interpretation capacity to jurisdictions with streamlined diagnostic device approval pathways. The FDA's 510(k) clearance efficiency draws platform investment toward United States telemedicine infrastructure. EMA's MDR clinical evidence requirements push European providers toward established sensor technologies rather than novel contactless systems.
United States
Medicare's expanded home sleep apnea testing coverage validates remote diagnostic pathways for commercial payers. The FDA maintains distinct 510(k) clearance tracks for software-as-a-medical-device scoring applications. Sleep specialist concentration in Boston and Stanford anchors academic interpretation volume for complex parasomnia cases.
Germany
Statutory health insurance reimbursement clarity sustains demand for both in-lab polysomnography and home testing modalities. The EMA's MDR framework imposes extended validation timelines on novel sensor technologies. Munich and Heidelberg cluster university-affiliated sleep laboratories with integrated cardiology comorbidity screening programs.
Japan
Aging demographics above age 65 drive elevated sleep disorder prevalence and clinical referral volume. PMDA maintains distinct approval standards for radar-based contactless monitoring technologies. Tokyo and Osaka concentrate diagnostic capacity at academic medical centers piloting non-contact sensor platforms.
United Kingdom
NHS cost containment policies accelerate shift from facility-based testing to mail-order home diagnostic kits. MHRA alignment with EMA MDR requirements shapes device procurement specifications. London's integrated sleep medicine programs at Guy's and St Thomas' NHS Foundation Trust anchor research-to-clinical translation pipelines.
Australia
Geographic dispersion of population creates demand for asynchronous telemedicine interpretation services paired with postal diagnostic distribution. TGA maintains regulatory equivalence pathways with FDA-cleared devices for streamlined market entry. Melbourne and Sydney anchor specialist sleep physician networks serving rural specialist deserts through remote platforms.
Global Sleep Testing Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with academic medical centers and dedicated sleep laboratories defending complex diagnostic caseloads against telemedicine platform encroachment. The vendor base separates into three strategic archetypes: integrated healthcare systems combining research with clinical volume, pure-play telemedicine platforms leveraging employer channel disintermediation, and device manufacturers extending into service layers through cloud interpretation subscriptions. Dominant competitive moves include M&A consolidation of regional sleep laboratory chains and strategic partnerships between wearable hardware vendors and academic centers for regulatory-grade validation studies.
Among North American integrated healthcare systems, Cleveland Clinic anchors academic credibility through research-volume integration. ResMed Inc. and Koninklijke Philips N.V. represent the device-to-service extension archetype, leveraging portable monitor ecosystems to capture recurring revenue through proprietary cloud platforms and automated scoring subscriptions. These three entities exemplify contrasting strategic positions: academic credibility defense, hardware-software bundling, and EMR-integrated platform scale.
| Leading Market Players |
|---|
| SleepMed Inc. |
| SOVA Sleep Services Inc. |
| ResMed Inc. |
| Cleveland Clinic |
| Itamar Medical Ltd |
| Koninklijke Philips N.V. |
| Midwest Sleep Services Inc. |
| Circle Health Group |
| Natus Medical Incorporated |
| Others |
Supply & Pricing Matrix
Captive cloud platform integration anchors pricing power for sleep testing service providers, binding diagnostic hardware to recurring software subscriptions and interpretation fees while insulating margin pools from pure commoditization. This vertical control over both device production and data interpretation layers concentrates value capture with vendors maintaining FDA-cleared and CE-marked ecosystems.
Pricing Analysis
Direct-to-employer contracting bypasses traditional payer markups and sustains premium per-test margins for telemedicine platforms serving self-insured transportation and manufacturing sectors. Pricing stratifies across premium in-lab polysomnography, standard home sleep apnea testing, and economy wellness screening tiers. Cost compression in the standard tier intensifies as Medicare reimbursement parity validates home testing pathways. Sleep clinics demonstrate lowest price sensitivity given complex case referral density, while ambulatory care facilities face acute margin pressure.
Supply Chain Analysis
Registered polysomnographic technologist scarcity in the United States and Germany constrains interpretation capacity expansion despite testing volume growth. Portable monitor production draws from concentrated Asian foundry capacity for specialized analog-to-digital converters and MEMS sensors. Single-source vulnerability for semiconductor inputs creates input disruption risk. Distribution runs through hospital-affiliated sleep centers, telemedicine platforms, and diagnostic center chains with varying procurement sophistication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sleep Testing Services Market functions as a stable compounder where aging demographics in Japan, Germany, and the United States generate durable referral volume with limited cyclical exposure.
For Market Incumbents: Anchor defensive positioning through exclusive hospital system partnerships that embed sleep testing into cardiovascular comorbidity workflows, while consolidating regional sleep laboratory chains to capture interpretation scale. Threat from consumer-grade wearable encroachment demands investment in FDA-cleared automated scoring algorithms that preserve diagnostic certainty differentiation. Vertical integration into proprietary cloud platforms sustains recurring revenue attachment. For New Entrants and Emerging Players: Employer-sponsored wellness program channels offer the most penetrable entry vector, particularly in US manufacturing and transportation sectors where occupational safety liability drives direct contracting. Rural specialist deserts across Appalachia and the Mountain West present white-space opportunity for asynchronous telemedicine interpretation paired with mail-order diagnostic kits. Go-to-market execution should prioritize per-employee-per-month pricing models that bypass traditional payer networks. For Investors and Strategic Acquirers: Roll-up economics work for regional sleep laboratory chains because reimbursement parity policies and technologist scarcity create barriers to greenfield capacity expansion. Long-term viability rests on platform vendors with demonstrated FDA 510(k) clearance efficiency and hospital EMR integration capabilities. Monitor PMDA regulatory clarity for radar-based contactless monitoring as inflection indicator for next-generation hardware categories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Validates home diagnostic equivalence and accelerates commercial payer adoption. |
| Hospital System Partnership | Embeds sleep testing into cardiology workflows at Cleveland Clinic and Stanford. |
| Software Companion Development | Automated scoring algorithms reduce technologist burden by 40-60% per laboratory. |
| Reimbursement Strategy | Medicare parity policies validate remote diagnostic pathways for commercial networks. |
| CE Marking Pathway | EMA MDR compliance enables European service deployment with clinical evidence backing. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Australia, with primary inputs from each market cluster combining structured interviews with sleep medicine directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation. Sources include FDA 510(k) device clearance databases, CMS Medicare reimbursement filings, EMA MDR submission records, hospital procurement databases, and statutory health insurance claims data. Bottom-up test volume modeling triangulates against top-down market sizing across service modalities.
Granularity-level modeling disaggregates revenue across polysomnography, home sleep apnea testing, multiple sleep latency test, maintenance of wakefulness test, and actigraphy service types; portable monitors, cloud platforms, wearables, contact sensors, and non-contact sensor technologies; and obstructive sleep apnea, insomnia, narcolepsy, restless leg syndrome, and circadian rhythm disorder applications. CAGRs derive from regression-based projection of referral volume against demographic aging curves and reimbursement policy trajectories. Forecast inputs incorporate technologist training pipeline capacity and semiconductor supply constraints.
The model assumes a particular technology adoption path where home sleep apnea testing captures volume share from in-lab polysomnography; alternative pathways for radar-based contactless monitoring under PMDA review would alter the outlook if clinical validation accelerates. Practitioners should monitor FDA guidance evolution on software-as-a-medical-device scoring applications and EMA MDR enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Legionella Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Americas Sterility Testing Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
IVD Quality Control Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Lab Screening Test Kit Market
Testing Services
CRO Mass Spectroscopy Services Market