
 Creatinine Testing Market | 2026-2036
Creatinine Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Creatinine Testing Market Analytics
Asian diagnostic reagent manufacturers is pivoting toward enzymatic creatinine assay production to reduce dependence on Jaffe-based imports. Siemens Healthineers leverages its installed base of chemistry analyzers to sustain recurring consumable revenue across European hospital networks. Abbott Laboratories anchors its creatinine testing portfolio through integrated i-STAT cartridge systems that dominate emergency department point-of-care workflows.
Creatinine testing measures the concentration of creatinine, a nitrogenous waste product from muscle metabolism with a molecular weight of 113.12 g/mol, in biological specimens to estimate glomerular filtration rate and assess renal function. Enzymatic methods now lead the test method segment due to superior specificity over Jaffe reaction approaches, which suffer from pseudocreatinine interference from ketones, proteins, and cephalosporins. Blood and serum samples occupy the highest volume share within sample type categories, though home care settings are driving urine-based self-testing adoption where biosensor technology enables smartphone-connected result transmission.
FDA CLIA regulations govern laboratory complexity classification and proficiency testing for creatinine assays performed in US clinical settings, while ISO 15189 standards shape quality management expectations for international laboratory accreditation. The EU In Vitro Diagnostic Regulation (IVDR) is forcing re-certification timelines that compress market access for legacy Jaffe-based products. Stakeholders must monitor reimbursement coding shifts for estimated glomerular filtration rate reporting bundles versus standalone creatinine tests.
Market Dynamics
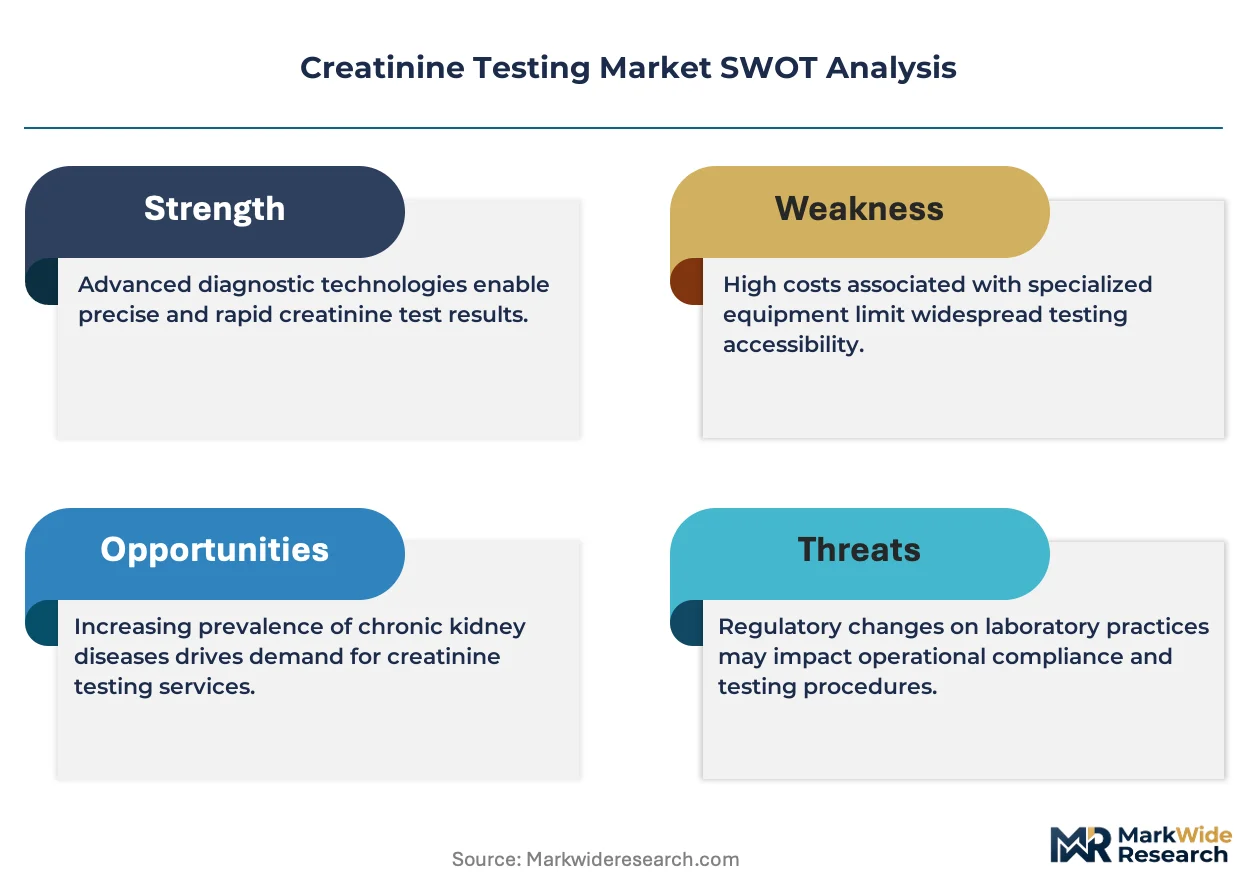
Enzymatic creatinine assays are displacing legacy Jaffe methods across hospital laboratories, driven by reimbursement penalties for inaccurate eGFR reporting and FDA CLIA quality mandates that penalize interference-prone testing platforms.
Growth Catalysts
- CLIA Waived Test Expansion:FDA's moderate-complexity classification pathway accelerates point-of-care creatinine deployment in emergency departments and surgical pre-admission units.
- Chronic Kidney Disease Surveillance:United States Medicare value-based care bundles incentivize routine creatinine monitoring for diabetic and hypertensive patient cohorts.
- Biosensor Miniaturization:Smartphone-connected electrochemical sensors enable home-based urine creatinine self-testing with cloud-based nephrologist review.
Market Restraints
- Enzyme Reagent Cost Volatility:Creatininase and creatinase supply concentrates in Chinese fermentation facilities, exposing assay manufacturers to input price swings.
- EU IVDR Recertification Burden:Legacy Jaffe-based products face compressed technical documentation timelines that delay market access for mid-tier diagnostic firms.
- Interference Limitations Persist:Bilirubin and hemoglobin continue to confound even enzymatic methods in icteric and hemolyzed specimens.
Strategic Opportunities
- India Preventive Health Expansion:Corporate wellness programs and diagnostic chain franchising create first-mover advantage for creatinine screening in tier-2 and tier-3 cities.
- Perioperative Acute Kidney Injury Protocols:Cardiac surgery and major abdominal procedure bundles now mandate pre- and post-operative creatinine surveillance.
- AI-Assisted Interpretation:Machine learning integration with laboratory information systems flags creatinine trajectory anomalies for earlier nephrology consultation.
Industry Challenges
- Cross-Platform Standardization Delays:IDMS-traceable creatinine reference materials remain inconsistently implemented across analyzer manufacturers.
- Laboratory Information System Integration:Point-of-care creatinine devices require HL7 FHIR connectivity upgrades that strain rural hospital IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Creatinine Testing Market |
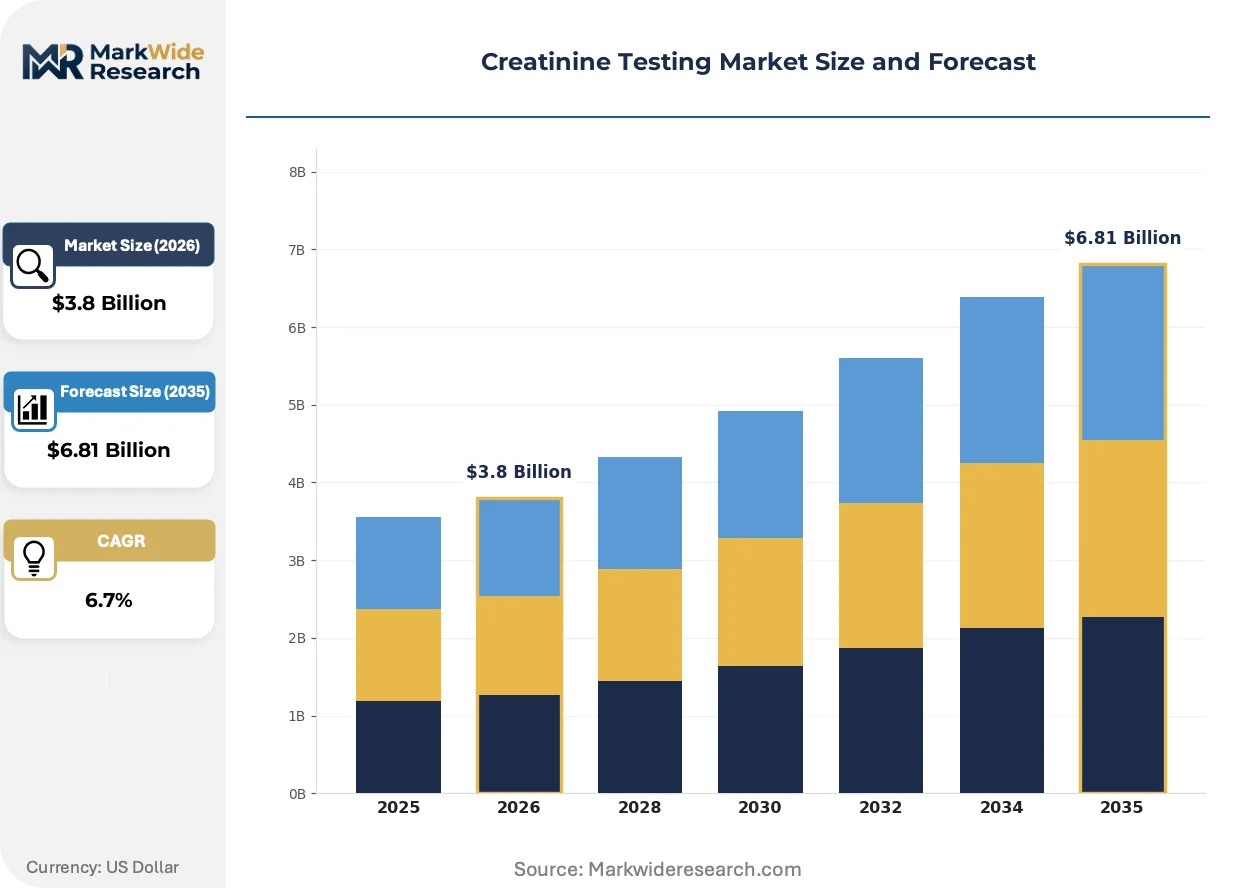
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: Enzymatic, Jaffe Reaction, Affinity Chromatography, HPLC Type of Sample: Blood, Urine, Plasma, Serum End User: Clinical Laboratories, Hospitals, Home Care, Diagnostic Centers Technology: Colorimetric, Photometric, Immunoassay, Biosensor |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, Merck KGaA, Quidel Corporation, Cell Biolabs, Randox Laboratories, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Nova Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Creatinine Testing Market Evolving Landscape
Creatinine testing infrastructure is fragmenting across centralized laboratory hubs and distributed point-of-care nodes, with connectivity standards and reimbursement coding struggling to keep pace with hardware decentralization.
Handheld cartridge-based analyzers is decentralizing perioperative creatinine surveillance from core laboratories to pre-operative holding areas and post-anesthesia care units. Anesthesia departments and surgical suites adopt these devices to meet same-day surgery discharge protocols. This shift compresses turnaround times from hours to minutes but fragments quality control oversight across non-laboratory clinical spaces.
EU In Vitro Diagnostic Regulation is forcing re-certification of legacy creatinine assays with expanded clinical evidence requirements for Class B and Class C devices. Manufacturers must submit post-market surveillance data and usability studies that Jaffe-based products never previously required. European hospital networks are responding by consolidating procurement around IVDR-compliant enzymatic platforms with established technical documentation.
Home-based biosensor testing is capturing creatinine monitoring volume previously directed to hospital outpatient laboratories. Direct-to-consumer renal function kits with smartphone result transmission appeal to chronic kidney disease patients in remote geographies. Australia and Canada exhibit the strongest early adoption where telehealth reimbursement covers remote monitoring data review.
Creatinine Testing Market Segmentation
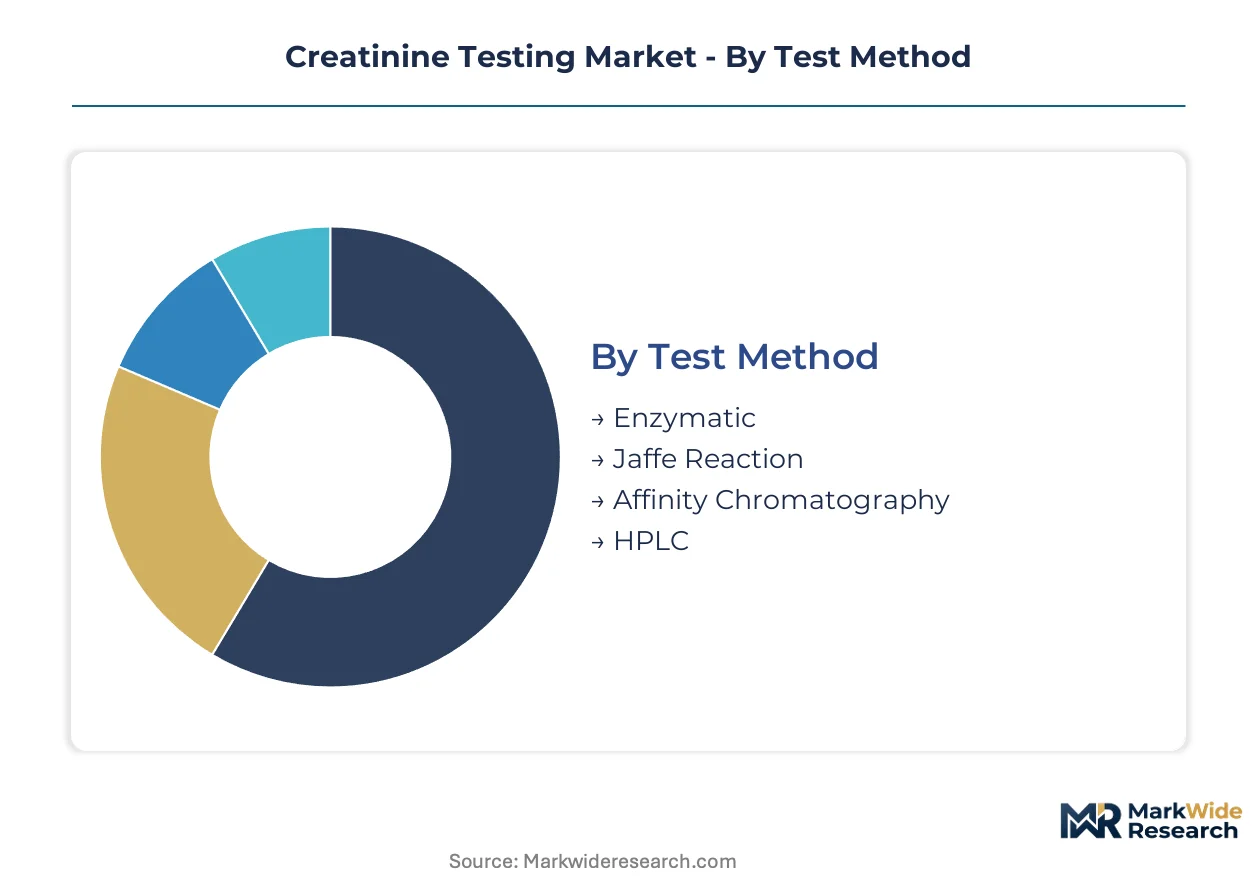
Creatinine testing segments diverge sharply by clinical setting complexity and reimbursement pathway. Hospital laboratories prioritize enzymatic precision for eGFR reporting accuracy, while point-of-care sites trade specificity for speed.
Test Method:
Hospital laboratories select methods based on interference tolerance and CLIA complexity classification.
- Enzymatic:Creatininase-creatinase enzyme cascade eliminates pseudocreatinine interference from ketones and cephalosporins. United States Medicare reimbursement penalties for inaccurate eGFR reporting drive hospital laboratory conversion from legacy platforms.
- Jaffe Reaction:Alkaline picrate colorimetry remains entrenched in cost-constrained settings despite susceptibility to protein and bilirubin interference. Chinese and Indian diagnostic chains retain Jaffe infrastructure for high-volume screening programs.
- Affinity Chromatography:Boronate affinity separation addresses hemoglobin interference in hemolyzed specimens from trauma centers.
- HPLC:Isotope dilution mass spectrometry reference methods anchor calibration traceability for IDMS-standardized enzymatic assays.
Volume sits with Jaffe Reaction; growth tilts toward Enzymatic.
Type of Sample:
Sample selection tracks care setting infrastructure and patient mobility constraints.
- Blood:Venipuncture serum and plasma specimens dominate hospital laboratory throughput. United States dialysis centers require pre-treatment blood draws for thrice-weekly monitoring.
- Urine:Creatinine clearance calculations from timed urine collections persist in nephrology specialist practices. Home care biosensor adoption concentrates in Australia and Canada where telehealth reimbursement covers remote result review.
- Plasma:Lithium heparin plasma enables rapid turnaround for emergency department point-of-care cartridges.
- Serum:Serum separator tube protocols standardize pre-analytical handling across United States hospital networks.
Clinical throughput clusters around Blood; patient convenience pushes expansion into Urine.
End User:
Procurement authority and reimbursement coding shape purchasing patterns across settings.
- Clinical Laboratories:High-throughput analyzers process thousands of specimens daily with automated quality control. United States reference laboratories anchor regional testing networks for smaller hospitals.
- Hospitals:Emergency departments and surgical suites deploy CLIA-waived point-of-care devices for perioperative acute kidney injury surveillance. Pre-operative holding areas demand sub-5-minute turnaround for same-day surgery protocols.
- Home Care:Direct-to-consumer biosensor kits with smartphone connectivity bypass traditional laboratory infrastructure. Chronic kidney disease patients in remote geographies access nephrologist review through cloud platforms.
- Diagnostic Centers:Franchise networks in India's tier-2 and tier-3 cities offer walk-in creatinine screening for corporate wellness programs.
Revenue concentrates in Clinical Laboratories; patient volume is climbing fastest in Home Care.
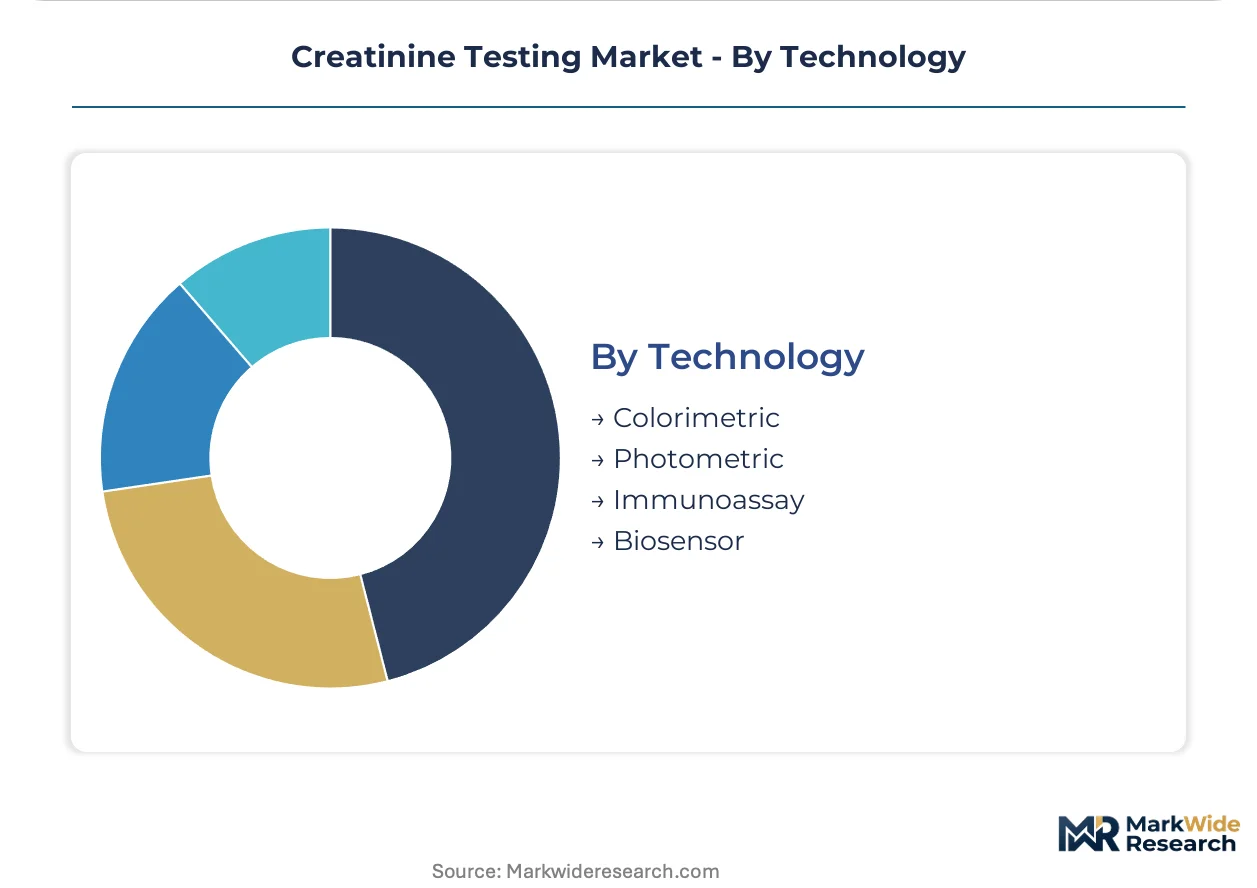
Technology:
Technology selection balances capital investment against regulatory compliance burden.
- Colorimetric:Enzymatic colorimetry dominates hospital chemistry analyzer menus with 340 nm endpoint detection. European IVDR recertification pressures favor established enzymatic colorimetric platforms with complete technical documentation.
- Photometric:Jaffe-based photometric systems persist in emerging market laboratories with legacy instrument investments.
- Immunoassay:Antibody-based detection addresses specialized research applications and confirmatory testing.
- Biosensor:Electrochemical smartphone-connected sensors enable home-based urine creatinine quantification with cloud data transmission.
Installed base favors Colorimetric; innovation investment flows toward Biosensor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme fermentation facilities in Zhejiang and Jiangsu provinces anchor reagent supply for enzymatic creatinine assays worldwide. Hospital procurement patterns and regulatory compliance timelines diverge sharply across national healthcare systems.
United States
Medicare value-based care bundles drive routine creatinine surveillance in diabetic and hypertensive cohorts across integrated delivery networks. FDA CLIA complexity classifications govern point-of-care deployment in emergency departments and surgical suites. The Cleveland Clinic and Mayo Clinic anchor reference laboratory networks that standardize IDMS-traceable calibration protocols regionally.
Germany
Hospital networks consolidate procurement around IVDR-compliant enzymatic platforms to avoid legacy re-certification delays. EMA quality management expectations shape post-market surveillance documentation for Class B in vitro diagnostic devices. The Rhine-Ruhr metropolitan laboratory cluster coordinates reference material distribution across Central European hospital alliances.
China
Domestic diagnostic chains in tier-2 and tier-3 cities expand creatinine screening for corporate wellness programs. NMPA regulatory pathways accelerate approval for enzymatic assays that reduce import dependence. Shanghai and Beijing hospital procurement consortia negotiate volume contracts with domestic reagent manufacturers.
India
Franchise diagnostic networks proliferate walk-in renal function testing in Maharashtra and Gujarat corporate wellness markets. CDSCO import substitution policies incentivize local enzymatic reagent production. Bangalore and Hyderabad diagnostic chains deploy point-of-care devices for perioperative screening in multispecialty hospital expansion zones.
Australia
Telehealth reimbursement codes enable home-based urine creatinine biosensor adoption for remote chronic kidney disease monitoring. TGA conformity assessment pathways align with IVDR technical documentation standards. Sydney and Melbourne nephrology practices integrate smartphone-connected results into cloud-based patient management platforms.
Creatinine Testing Market Competitive Landscape
Global majors compete with regional champions across reagent supply and analyzer installed base dimensions. The vendor base stratifies between diversified conglomerates with chemistry analyzer ecosystems and specialized point-of-care device manufacturers. Three archetypes dominate: integrated diagnostics platforms, enzymatic reagent specialists, and handheld biosensor innovators. Competitive moves concentrate on IVDR technical documentation completion and CLIA waived test portfolio expansion.
Within the integrated platform tier, Abbott Laboratories and Siemens Healthineers anchor recurring consumable revenue through chemistry analyzer installed bases. Thermo Fisher Scientific occupies a position spanning research-grade reagents and clinical diagnostic materials. These three entities exemplify contrasting geographic emphases: Abbott dominates emergency department point-of-care workflows, Siemens leverages European hospital network relationships, and Thermo Fisher channels life science distribution reach into clinical reagent supply.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Merck KGaA |
| Quidel Corporation |
| Cell Biolabs |
| Randox Laboratories |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Nova Biomedical |
| Others |
Value Network & Pricing Analysis
Enzyme fermentation specialists concentrated in Zhejiang and Jiangsu provinces command wage premiums that translate directly into pricing-tier spreads across enzymatic and Jaffe-based assay portfolios. Labor-cost differentials between Chinese bioprocessing hubs and European reagent finishing facilities widen the gap between premium IVDR-compliant platforms and economy-grade legacy systems.
Pricing Analysis
Service bundling separates analyzer manufacturers who include multi-year calibration contracts and field service engineering from reagent-only suppliers who unbundle post-sale support. Three-tier pricing structure across premium, standard, and economy levels reflects IVDR certification status and IDMS-traceable reference material integration. Pricing pressure stems from Medicare reimbursement compression for standalone creatinine tests versus bundled eGFR reporting. Hospital laboratories exhibit lowest price sensitivity due to value-based care penalties for inaccurate renal function assessment, while Indian franchise diagnostic chains prioritize economy-tier Jaffe platforms for high-volume screening programs.
Supply Chain Analysis
Reverse logistics for expired enzymatic reagents and analyzer refurbishment cycles create secondary supply channels for cost-constrained laboratories in emerging markets. Creatininase and creatinase enzyme concentrates draw from Chinese fermentation facilities, with boronate affinity chromatography resins and electrochemical sensor membranes sourced from Japanese and German specialty chemical producers. Single-source vulnerability concentrates in Zhejiang province bioreactor capacity. Distribution runs through regional diagnostic distributors who consolidate hospital network procurement and manage cold-chain logistics for temperature-sensitive enzyme shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The creatinine testing market sits in a method-transition phase, with enzymatic assays displacing Jaffe platforms as CLIA quality mandates and reimbursement penalties for inaccurate eGFR reporting reshape laboratory procurement priorities.
For Market Incumbents: Lock in recurring consumable revenue through long-term reagent supply contracts with integrated delivery networks and anchor chemistry analyzer installed bases with IVDR-compliant enzymatic platforms. Threat from point-of-care biosensor innovators demands preemptive cartridge-system partnerships with emergency department purchasing committees. Priority lever rests on backward integration into Chinese enzyme fermentation capacity to secure supply and compress input cost volatility. For New Entrants and Emerging Players: FDA's moderate-complexity CLIA waived test pathway in the United States opens a window for handheld cartridge developers to capture perioperative acute kidney injury surveillance volume from core laboratories. White-space targets include tier-2 and tier-3 Indian cities for franchise diagnostic chain partnerships and Australian telehealth reimbursement corridors for home-based biosensor adoption. Go-to-market angle centers on sub-5-minute turnaround guarantees for same-day surgery discharge protocols. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic reagent specialists given EU IVDR recertification timelines that compress market access for legacy Jaffe-based competitors. Long-term viability favors platforms with established technical documentation and hospital network procurement relationships over hardware-only device manufacturers. Signal to watch is consolidation velocity among mid-tier diagnostic firms unable to absorb IVDR compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Completion | Accelerates European market access for enzymatic platforms ahead of legacy re-certification deadlines. |
| CLIA Waived Test Portfolio Expansion | Captures emergency department and surgical suite point-of-care volume from core laboratories. |
| Enzyme Fermentation Capacity Addition | Reduces input cost exposure and secures supply chain leverage against Chinese price volatility. |
| Hospital System Partnership | Locks in multi-year reagent contracts with integrated delivery networks under value-based care models. |
| Telehealth Reimbursement Strategy | Enables home-based biosensor adoption in Australia and Canada through remote monitoring codes. |
Research Methodology
Document review covered FDA 510(k) filings, EU IVDR technical documentation databases, and CMS Medicare reimbursement coding manuals, complemented by interviews with laboratory directors, hospital purchasing committee members, diagnostic reagent procurement managers, and point-of-care device biomedical engineers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and clinical laboratory proficiency testing records. Bottom-up and top-down triangulation reconciled analyzer installed base estimates with reagent consumption patterns across regional hospital networks.
Segment-level value outputs were derived through modeling across test method, sample type, end user, and technology dimensions, with geographic regulatory clusters incorporated as cross-cutting variables. CAGRs were computed from baseline volume assessments and projected conversion rates from Jaffe to enzymatic platforms. Industry-specific inputs included CLIA complexity classification adoption curves, IVDR recertification timeline assumptions, and telehealth reimbursement code expansion patterns.
Caveats apply where FDA CLIA waiver pathway modifications, EU IVDR guidance document revisions, or enzyme fermentation supply disruptions could materially shift the outlook. Practitioners should monitor Medicare reimbursement bundling decisions and NMPA domestic substitution policy signals for early indicators of pricing pressure direction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Global Bioburden Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
Global Newborn Screening Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Radiographic Testing Market
Testing Services
Global Endocrine Testing Market
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Allergy Skin Test Market
Testing Services
Cholesterol Testing Services Market
Testing Services
Instrument Calibration Services Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Breath Biopsy Testing Market