
 Bulgaria Container Glass Market | 2026-2036
Bulgaria Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Bulgaria Container Glass Market Insights
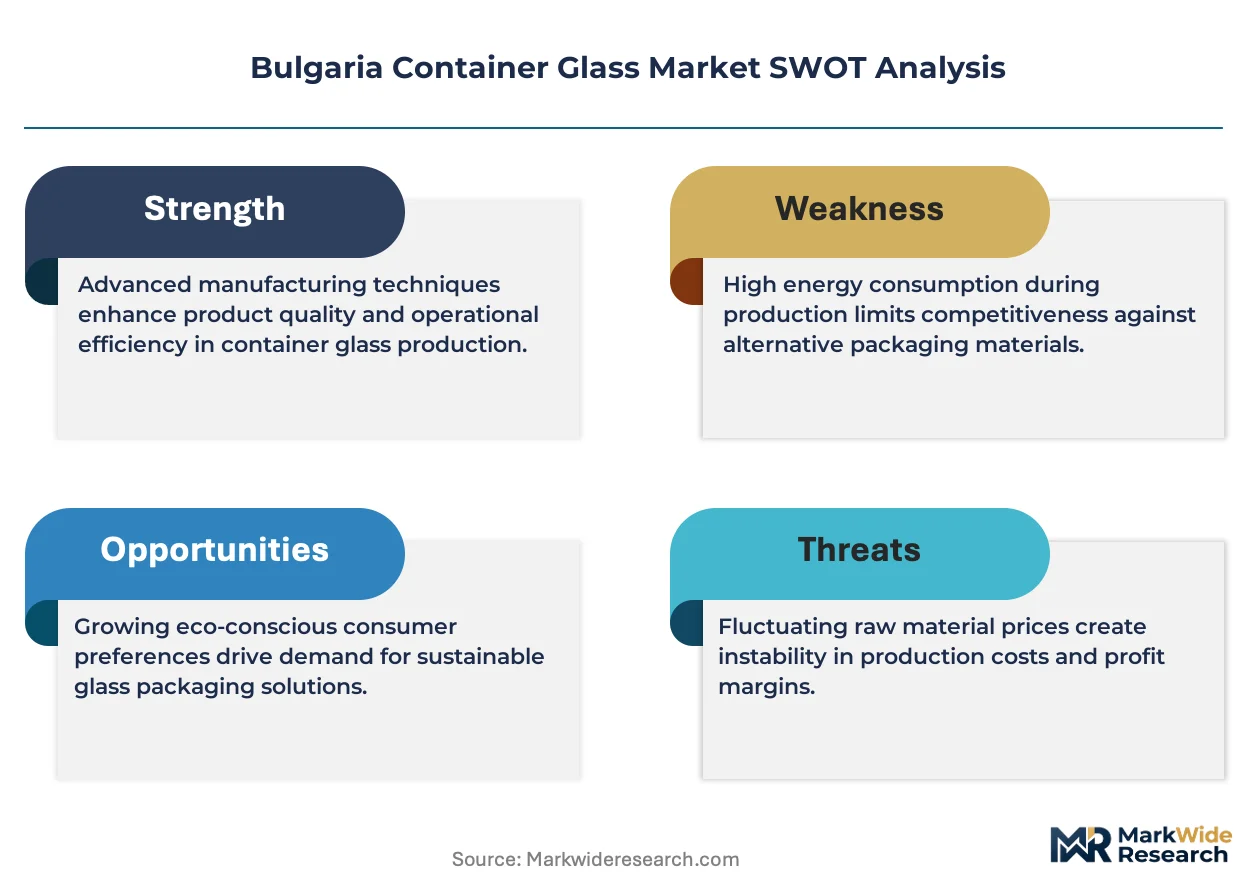
Buyer concentration among Bulgarian beverage manufacturers is restructuring procurement patterns across the container glass sector. BA Glass Bulgaria SA leverages its domestic furnace capacity to anchor supply relationships with regional soft-drink and mineral-water bottlers. Vetropack sustains cross-border distribution networks that extend into Romania and Serbia. Verallia competes through specialized wine-bottle formats tailored to Bulgarian and Macedonian vineyard clients.
Container glass consists of silica sand, soda ash, limestone, and recycled cullet melted at temperatures exceeding 1500°C to form rigid, chemically inert vessels for liquid and food storage. The material offers impermeability, optical clarity, and infinite recyclability without quality degradation. Beverage Packaging leads volume throughput as Bulgarian wine and beer exports expand, while Pharmaceuticals commands premium margin pools due to borosilicate durability requirements and EU pharmacopeia compliance. Food Packaging remains mature with steady jar demand for preserved vegetables and dairy spreads.
Bulgaria's container glass sector operates under EU REACH chemical safety protocols, the EU Green Deal decarbonization framework, and national waste-management ordinances transposing the Packaging and Packaging Waste Directive. These frameworks elevate energy-efficiency investment thresholds and mandate rising post-consumer cullet incorporation rates. Stakeholders must monitor furnace fuel-switching economics and carbon-border adjustment mechanisms to preserve cost competitiveness against imported alternatives.
Market Dynamics
The Sofia-Plovdiv industrial corridor is consolidating furnace capacity as Bulgarian beverage manufacturers restructure procurement toward domestic sourcing, compressing import-dependent supply relationships and elevating energy-efficiency investment thresholds under EU decarbonization mandates.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Rising recycled content mandates across member states are pulling post-consumer cullet into Bulgarian furnace feedstock, creating captive supply advantages for domestic producers.
- Beverage export expansion:Bulgarian wine and beer shipments are anchoring volume throughput for amber and flint glass formats, with vineyard clients specifying lightweight bottle designs.
- Natural gas price stabilization:Improved furnace fuel economics are restoring margin viability for container glass relative to imported PET alternatives.
Market Restraints
- Silica sand import dependency:High-purity feedstock concentrates in Romanian and Serbian deposits, exposing Bulgarian furnaces to cross-border logistics friction and currency fluctuation.
- Carbon-border adjustment exposure:The EU CBAM mechanism is elevating cost pressure on energy-intensive glass production relative to Turkish and Ukrainian imports.
- Electrification technical limits:Furnace temperature requirements exceeding 1500°C constrain renewable electricity substitution, locking producers into fossil fuel infrastructure.
Strategic Opportunities
- Pharmaceutical borosilicate expansion:EU pharmacopeia compliance requirements are opening premium margin pools for domestic producers capable of meeting CDSCO-equivalent durability standards.
- Macedonian vineyard penetration:Cross-border bottle supply to North Macedonian wine exporters remains underdeveloped relative to Romanian and Serbian competitors.
- Digital furnace control convergence:Integration of AI-driven temperature optimization with predictive maintenance platforms is compressing energy intensity per ton of melted glass.
Industry Challenges
- Specialized refractory engineering talent:Furnace rebuild cycles require expertise in zirconia-alumina-silica lining configurations that outpaces Bulgarian technical education output.
- REACH compliance documentation:Extended substance safety data sheet timelines for imported colorants and coatings are delaying new product qualification for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulgaria Container Glass Market |
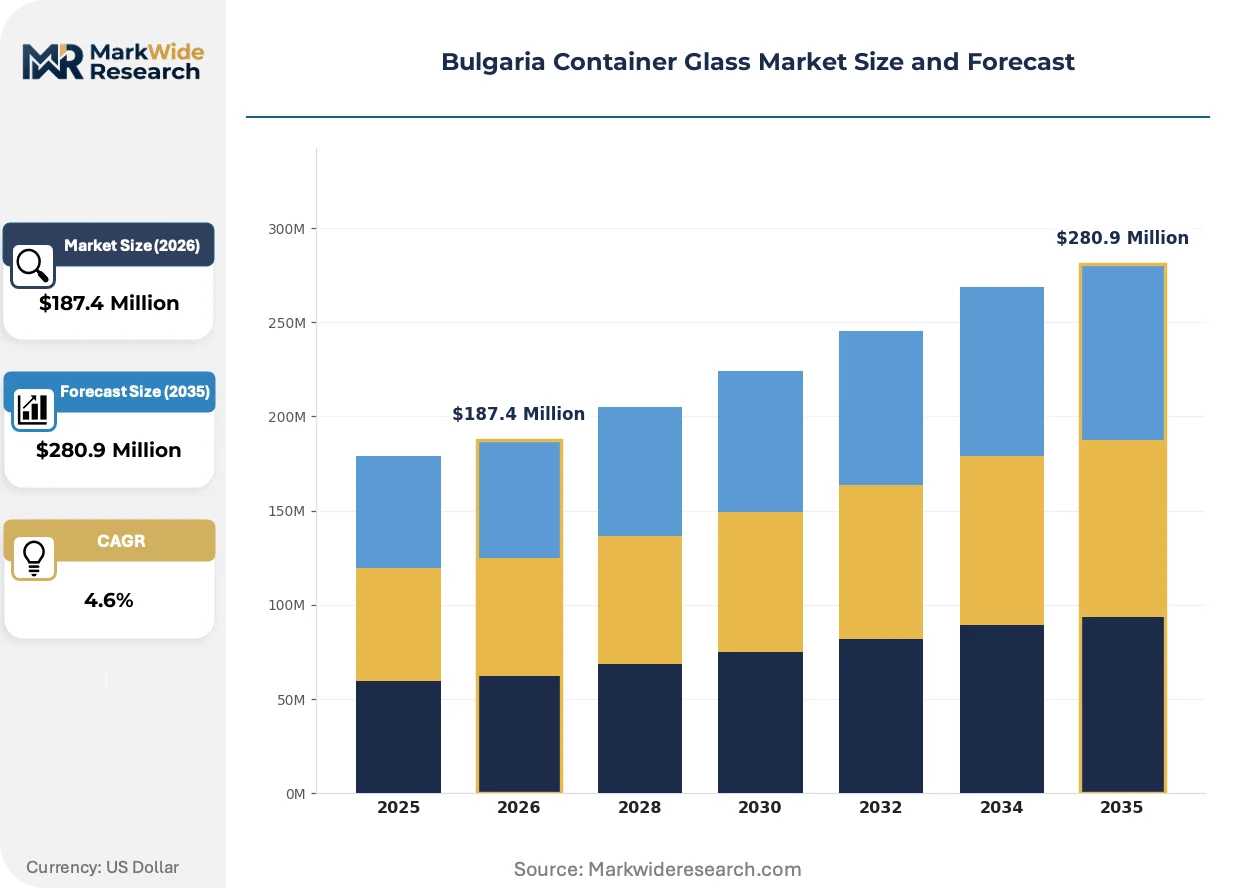
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Beverage Containers Application: Food Packaging, Beverage Packaging, Pharmaceuticals, Cosmetics End User: Food Industry, Beverage Manufacturers, Cosmetic Companies, Pharmaceutical Firms Capacity: 500ml, 1L, 2L, 3L |
| Companies Covered | BA Glass Bulgaria SA, Vetropack, Verallia, Rubin Trading JSC, Vials.Bg – Melampous Ltd, Glassy Bulgaria, Ecoprint Glass, Ltd., Frigoglass, Ardagh Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulgaria Container Glass Market Trends and Innovations
Electrification pilots and digital furnace controls are compressing energy intensity benchmarks while regulatory mandates accelerate cullet incorporation rates across Bulgarian production lines.
Hybrid oxy-fuel combustion technology is integrating electric boosting elements to trim natural gas consumption by fifteen to twenty percent in furnace operations. BA Glass Bulgaria and Vetropack are retrofitting Sofia-Plovdiv corridor facilities with these systems to preserve cost positioning against imported alternatives. The structural consequence is a narrowing margin gap between domestic production and cross-border supply.
The EU Green Deal decarbonization framework is mandating furnace fuel-switching roadmaps and elevating carbon audit disclosure requirements. Bulgarian producers must document Scope 1 and Scope 2 emissions intensity to maintain preferred supplier status with multinational beverage clients. Wine and spirits packaging segments are responding fastest, with vineyard procurement contracts now specifying low-carbon glass certification.
Consolidated buying by multinational beverage bottlers is compressing supplier qualification cycles and unbundling technical service from base product supply. Bulgarian mineral water and soft-drink manufacturers are consolidating purchase orders under longer-term framework agreements with volume commitments. This pattern concentrates procurement leverage in the Sofia-Plovdiv corridor where furnace capacity clusters.
Bulgaria Container Glass Market Segmentation
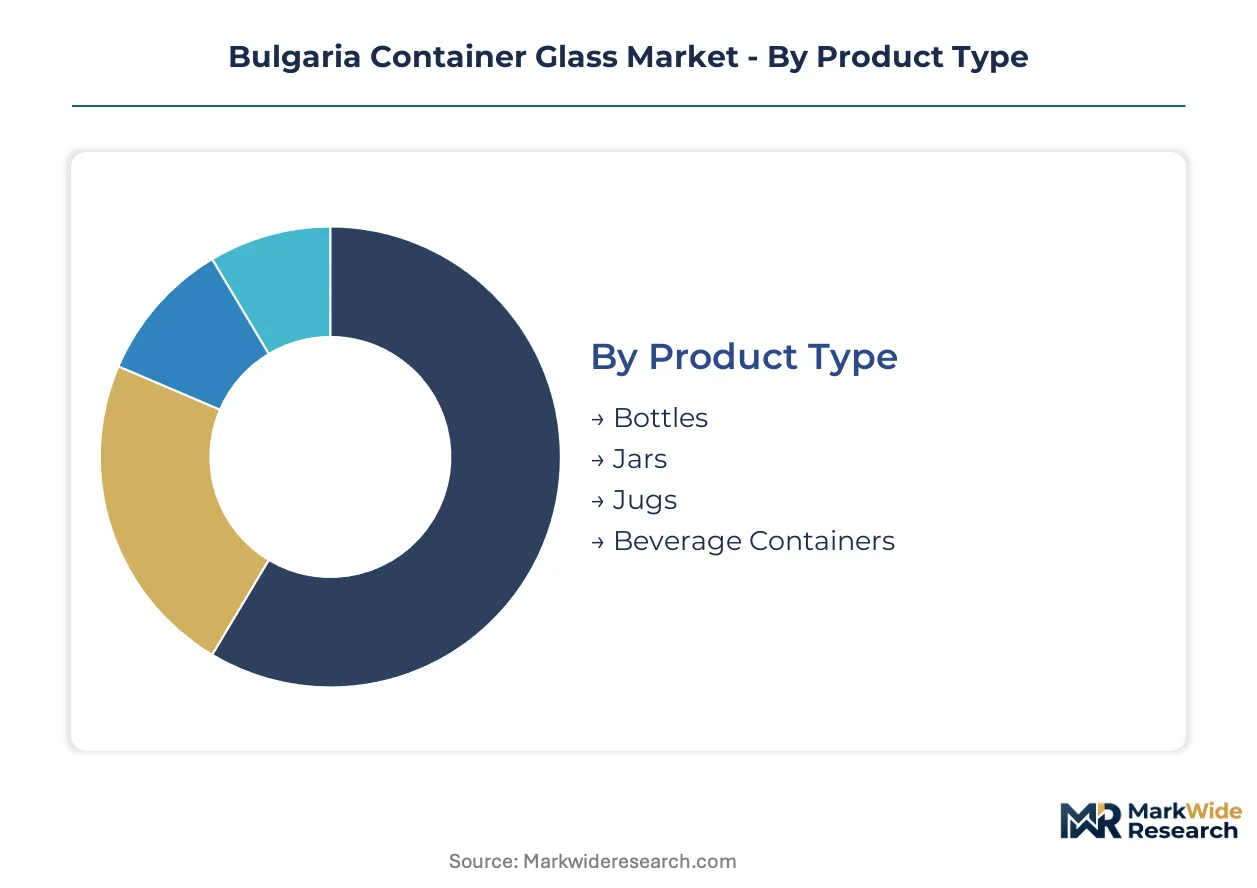
Segmentation in Bulgaria's container glass market reveals how procurement leverage concentrates among beverage manufacturers while pharmaceutical and cosmetic applications command divergent technical specifications. Understanding these divides exposes where furnace capacity investments align with margin structure versus volume throughput.
Product Type:
Bulgarian buyers prioritize format flexibility that matches filling-line speeds and shelf-presence requirements across retail channels.
- Bottles:Amber and flint glass formulations dominate wine and beer export packaging, with lightweighting specifications reducing transport costs for Plovdiv-based bottlers shipping to German and Romanian distributors. Sofia-Plovdiv corridor producers anchor supply relationships through dedicated mold libraries.
- Jars:Wide-mouth configurations with lug-finish threads preserve vacuum seals for pickled vegetables and dairy spreads, sustaining steady demand from Preserved Foods Bulgaria and regional dairy processors.
- Jugs:Handle-integrated formats concentrate in 2-3 liter edible oil and bulk beverage segments where ergonomic pouring requirements override premium aesthetics.
- Beverage Containers:Standardized neck-finish dimensions enable rapid line changeovers for mineral water and soft-drink bottlers operating high-speed rotary fillers.
Bottles lead on scale; Beverage Containers lead on momentum.
Application:
Margin concentration follows regulatory burden intensity, with EU pharmacopeia and REACH compliance creating tiered entry barriers.
- Food Packaging:Steady jar demand for preserved vegetables and dairy spreads operates at mature margins, with Bulgarian dairy processors specifying thermal-shock-resistant borosilicate alternatives for pasteurized product lines.
- Beverage Packaging:Wine and beer export expansion anchors volume throughput for amber and flint formats, with vineyard procurement contracts now specifying low-carbon glass certification under EU Green Deal frameworks.
- Pharmaceuticals:Borosilicate durability requirements and EMA pharmacopeia compliance open premium margin pools for domestic producers capable of meeting CDSCO-equivalent standards.
- Cosmetics:Frosted and coated decorative finishes command batch-scale production runs, with Sofia-based cosmetic formulators sourcing flaconnage from specialized furnace campaigns.
Beverage Packaging leads on scale; Pharmaceuticals leads on momentum.
End User:
Procurement consolidation patterns separate multinational framework agreements from fragmented regional buyer structures.
- Food Industry:Preserved vegetable processors and dairy spread manufacturers sustain steady jar demand through annual volume commitments with Sofia-Plovdiv corridor producers.
- Beverage Manufacturers:Wine exporters and mineral water bottlers are restructuring procurement toward domestic sourcing, compressing import-dependent supply relationships and elevating energy-efficiency qualification thresholds.
- Cosmetic Companies:Batch-scale decorative requirements favor smaller furnace campaigns with rapid color-change capability, limiting supplier consolidation.
- Pharmaceutical Firms:EMA compliance documentation and extended substance safety data sheet timelines for imported colorants delay new product qualification, favoring established supplier relationships.
Beverage Manufacturers lead on scale; Pharmaceutical Firms leads on momentum.
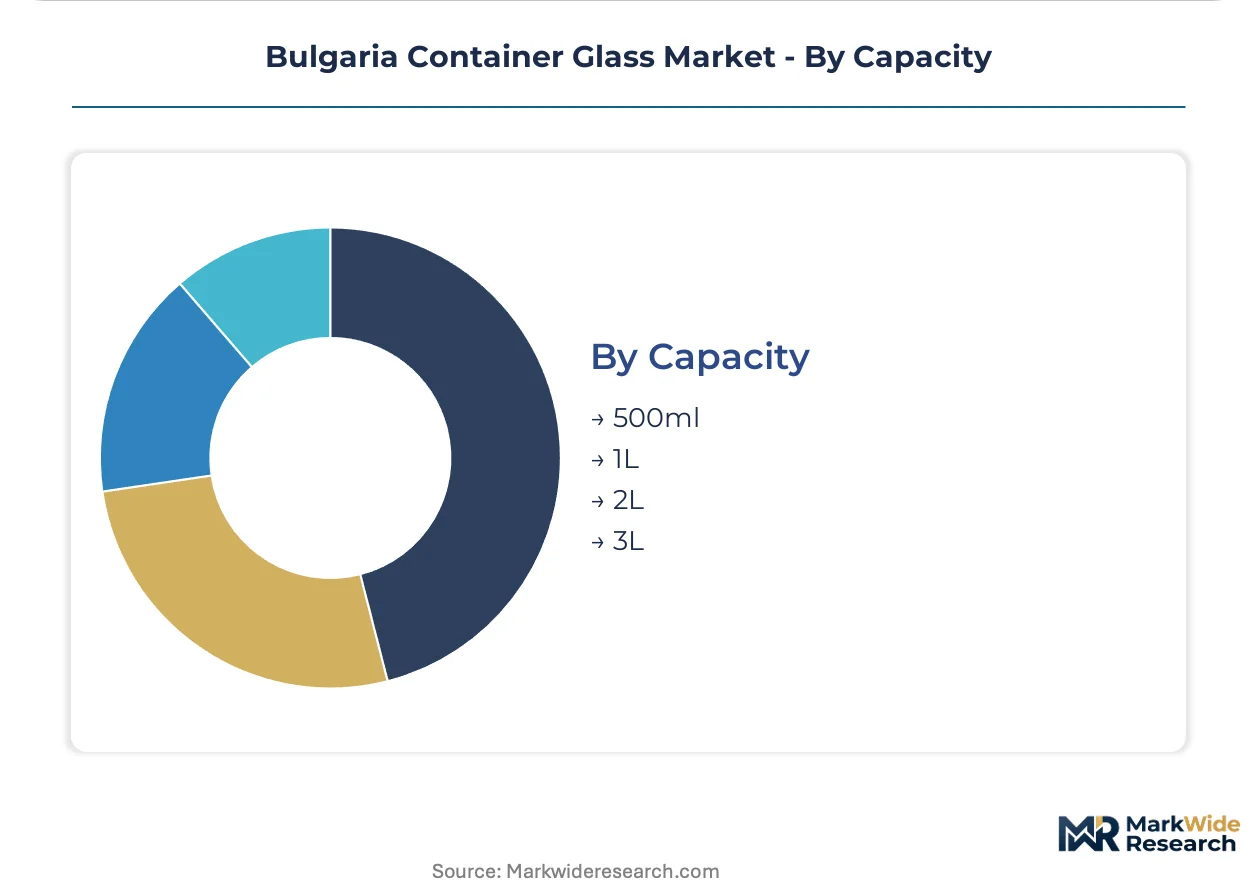
Capacity:
Furnace mold configuration economics favor mid-range formats that balance line-speed efficiency with logistics cube optimization.
- 500ml:Standard wine and spirits format dominating export shipments to German and Romanian markets, with lightweighting specifications reducing per-unit shipping costs.
- 1L:Mineral water and edible oil standard enabling pallet-stacking efficiency for retail distribution networks.
- 2L:Bulk beverage and family-size food packaging segment where handle-integrated jug designs concentrate.
- 3L:Institutional and food-service formats with limited retail presence, sustaining niche furnace campaign allocations.
500ml leads on scale; 1L leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Romania's container glass sector outpaces Bulgarian output in furnace scale, yet Sofia-Plovdiv corridor producers retain tighter integration with vineyard clients across the Balkan rim.
Romania
Transylvanian wine exports and Bucharest-based mineral water bottlers sustain amber and flint glass demand. The country's environmental regulator enforces EU Packaging and Packaging Waste Directive transpositions that elevate cullet incorporation targets. Production clusters around Timișoara and Ploiești where cross-border logistics connect to Hungarian and Serbian distribution networks.
Serbia
Domestic beer and rakija distilleries anchor stable container glass offtake despite currency volatility. Serbian competition authority oversight aligns with EU accession harmonization pressures on packaging standards. Manufacturing concentrates near Belgrade and Niš with furnace capacity serving both local bottlers and Bulgarian export spillover.
Greece
Olive oil and wine export packaging sustains specialized bottle demand with premium aesthetic specifications. Greek national waste management frameworks implement extended producer responsibility schemes that reshape recycler-producer contracts. Thessaloniki and Patras host the primary glassworks serving Aegean shipping routes to Italian and Turkish markets.
North Macedonia
Tikveš vineyard expansion and Skopje beverage manufacturing create import-dependent glass demand that regional suppliers contest. The country's economy ministry administers industrial development incentives targeting packaging localization. Production absence forces reliance on Bulgarian, Serbian, and Greek cross-border supply with Plovdiv-based producers holding logistics advantages.
Turkey
Thrace glassworks and Izmir-based furnaces export into Bulgarian beverage markets through price-competitive flint and amber formats. Turkish environmental ministry regulations lag EU decarbonization timelines, creating carbon-intensity arbitrage opportunities. Manufacturing concentrates in Çayırova and Mersin with coastal shipping access to Black Sea ports.
Bulgaria Container Glass Market Competitive Landscape
Sofia-Plovdiv corridor producers anchor one tier; cross-border specialists from Romania and Serbia hold import-dependent supply relationships with Bulgarian bottlers. Market structure consolidates around three furnace operators with domestic melting capacity while trading houses and decorative finishers occupy fragmented downstream niches. Strategic archetypes separate furnace-scale producers, specialized pharmaceutical glassmakers, and import-trading intermediaries. Capacity expansion and energy-efficiency retrofitting constitute the dominant competitive moves as EU Green Deal compliance deadlines approach.
Within the furnace-scale tier, BA Glass Bulgaria SA, Vetropack, and Verallia exemplify divergent geographic anchoring strategies. BA Glass Bulgaria SA occupies a position tied to domestic vineyard and mineral water procurement consolidation. Vetropack represents cross-border distribution architecture extending Romanian and Serbian supply relationships into Bulgarian territory. Verallia exemplifies premium-format specialization targeting wine export packaging with lightweighting specifications. These three entities collectively illustrate how furnace proximity to the Sofia-Plovdiv industrial corridor determines competitive positioning under tightening recycled content mandates.
| Leading Market Players |
|---|
| BA Glass Bulgaria SA |
| Vetropack |
| Verallia |
| Rubin Trading JSC |
| Vials.Bg – Melampous Ltd |
| Glassy Bulgaria |
| Ecoprint Glass, Ltd. |
| Frigoglass |
| Ardagh Group |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU Green Deal-compliant low-carbon glass and standard furnace output manifests in both contract premiums and supplier qualification tiers, with Sofia-Plovdiv corridor producers commanding preferred status through documented Scope 1 and Scope 2 emissions disclosure while import-dependent buyers absorb carbon-border adjustment exposure.
Pricing Analysis
Capacity additions in the Sofia-Plovdiv corridor are reshaping price floors for amber and flint formats as BA Glass Bulgaria and Vetropack retrofit hybrid oxy-fuel systems. Three-tier pricing structure across premium, standard, and economy levels reflects carbon certification status and volume commitment scale. Price differentiation follows EU Green Deal compliance documentation and lightweighting specification adoption. Cost compression in commodity-grade segments intensifies because Turkish Thrace glassworks exploit regulatory lag to undercut Bulgarian furnace economics. Multinational beverage bottlers exhibit lowest price sensitivity due to framework agreement consolidation, while regional mineral water processors face acute margin pressure from PET substitution threats.
Supply Chain Analysis
Dual-sourcing requirements mandated by multinational beverage clients force Bulgarian bottlers to qualify both domestic Sofia-Plovdiv corridor furnaces and Romanian Timișoara or Serbian Belgrade alternatives. Geographic supply concentration centers on Bulgaria, Romania, and Serbia for melted glass, with high-purity silica sand drawing from Romanian and Serbian deposits. Raw material dependencies include soda ash, limestone, and post-consumer cullet under EU Packaging and Packaging Waste Regulation mandates. Supply chain risk hinges on carbon-border adjustment exposure elevating landed costs from Turkish Çayırova and Izmir competitors. Distribution runs through palletized truckload networks anchored at Plovdiv logistics hubs serving Balkan rim vineyard clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bulgaria's container glass sector functions as a geographic-arbitrage play between EU Green Deal compliance premiums and Turkish regulatory lag, with furnace fuel-switching economics creating divergent cost trajectories across the Balkan rim.
For Market Incumbents: Hedge carbon-border adjustment exposure by accelerating hybrid oxy-fuel retrofits ahead of EU compliance deadlines, locking in preferred supplier status with multinational beverage clients through documented emissions intensity disclosure. Secure captive cullet supply via backward integration into Bulgarian waste-management networks to preserve margin positioning against Turkish imports. Prioritize zirconia-alumina-silica refractory engineering talent retention as furnace rebuild cycles compress.
For New Entrants and Emerging Players: Launch via specialized pharmaceutical borosilicate campaigns targeting EMA pharmacopeia compliance gaps, exploiting extended substance safety data sheet timelines that delay incumbent qualification. North Macedonian vineyard penetration remains the most penetrable geography, with Tikveš expansion creating import-dependent demand that Plovdiv-based logistics advantages can capture. Pursue batch-scale decorative finishes for Sofia-based cosmetic formulators as a go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with furnace-scale operators possessing EU Green Deal certification infrastructure and Sofia-Plovdiv corridor proximity. Long-term viability over the next decade hinges on fuel-switching roadmap execution and carbon audit disclosure capabilities. Target acquisition archetypes include mid-cap Bulgarian producers with hybrid oxy-fuel pilot capacity and established vineyard procurement relationships. Watch natural gas price stabilization durability as the inflection indicator for margin restoration against PET alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Oxy-Fuel Retrofit | BA Glass Bulgaria and Vetropack compress energy intensity fifteen to twenty percent through electric boosting integration. |
| Cullet Supply Integration | Domestic producers lock in post-consumer feedstock advantages under tightening EU recycled content mandates. |
| Pharmaceutical Borosilicate Expansion | EMA pharmacopeia compliance opens premium margin pools for producers meeting CDSCO-equivalent durability standards. |
| North Macedonian Vineyard Penetration | Plovdiv-based logistics advantages capture Tikveš expansion demand currently served by Romanian and Serbian competitors. |
| Digital Furnace Control Convergence | AI-driven temperature optimization with predictive maintenance platforms reduces per-ton energy intensity benchmarks. |
Research Methodology
Coverage spans Bulgaria, Romania, Serbia, and North Macedonia, with primary inputs from each market through structured interviews with furnace operations managers, beverage procurement directors at Bulgarian mineral water and wine exporters, pharmaceutical regulatory affairs leads, and Sofia-Plovdiv corridor logistics coordinators. Secondary validation draws from EU ETS emissions disclosure databases, Bulgarian national waste-management ordinance filings, EMA pharmacopeia compliance registries, and customs trade data tracking cross-border glass movements. Bottom-up segment sizing triangulates against top-down macroeconomic absorption models.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include product type, application, end user, and capacity tier alongside furnace fuel-source configuration and carbon certification status. CAGRs derive from production capacity utilization trajectories, export shipment patterns to German and Romanian distributors, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporate natural gas price stabilization assumptions and EU Packaging and Packaging Waste Regulation cullet incorporation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Turkish carbon-intensity arbitrage or abrupt natural gas price volatility. Deviation in EU CBAM enforcement stringency or Bulgarian waste-management cullet collection efficiency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Japan Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Italy Container Glass Market
Glass Packaging
Benelux Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Saudi Arabia Container Glass Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Mason Jars Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Vietnam Container Glass Market