
 Pharmaceutical Glass Packaging Market | 2026-2036
Pharmaceutical Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Glass Packaging Market Intelligence
Modular ready-to-fill systems is decoupling traditional bulk vial purchasing from integrated fill-finish contracts, giving pharmaceutical manufacturers flexibility to switch contract manufacturers without redesigning primary packaging. Schott AG leverages its FIOLAX borosilicate tubing dominance to sustain long-term supply agreements with top-tier injectable producers. Gerresheimer AG anchors European demand through specialized molded glass capacity for complex biologic containers. Stevanato Group differentiates by integrating glass primary packaging with drug delivery device engineering, controlling the interface between container and administration system.
Pharmaceutical glass packaging comprises chemically resistant containers fabricated from borosilicate or soda-lime glass, engineered to meet USP Type I, II, or III hydrolytic resistance standards and manufactured through tubular or molded forming processes to ensure drug stability and patient safety. Vials capture the largest volume share across injectable and vaccine applications, while ready-to-use syringes represent the fastest-expanding configuration as biologics manufacturers seek to eliminate compounding steps and reduce particulate risk. Ampoules retain niche demand in emerging market oral solutions and diagnostic kits, though their share contracts in premium regulated segments where break-resistance and resealability matter more than unit cost.
FDA's Container Closure System guidance and EMA's Annex 1 revision on sterile manufacturing impose escalating extractables and leachables testing burdens, directly shaping glass composition selection and supplier qualification timelines. USP <660> and <1660> standards on glass hydrolytic resistance and surface chemistry further constrain substitution toward lower-grade materials, reinforcing borosilicate's position in high-value biologics. Stakeholders must monitor evolving pharmacopeial harmonization between FDA, EMA, and China's NMPA, as divergent surface delamination testing protocols threaten to fragment supplier certification requirements and extend qualification cycles.
Market Dynamics
Biologics manufacturers are decoupling primary packaging selection from fill-finish contracts, forcing glass suppliers to qualify directly with drug sponsors rather than through contract manufacturing intermediaries. This shift concentrates purchasing power among top-tier pharmaceutical firms while fragmenting supplier access routes.
Growth Catalysts
- EMA serialization mandates:The European Medicines Agency's track-and-trace requirements for primary packaging are accelerating investment in pre-coded glass containers with integrated data matrix markings.
- Ready-to-use syringe adoption:Biologics manufacturers are eliminating compounding steps by specifying pre-sterilized glass syringes, reducing particulate contamination risk in high-value injectable production.
- German borosilicate clusters:Specialized tubing production concentrates in Mainz and Mitterteich, anchoring European supply security for USP Type I glass dependent on hydrolytic resistance certification.
Market Restraints
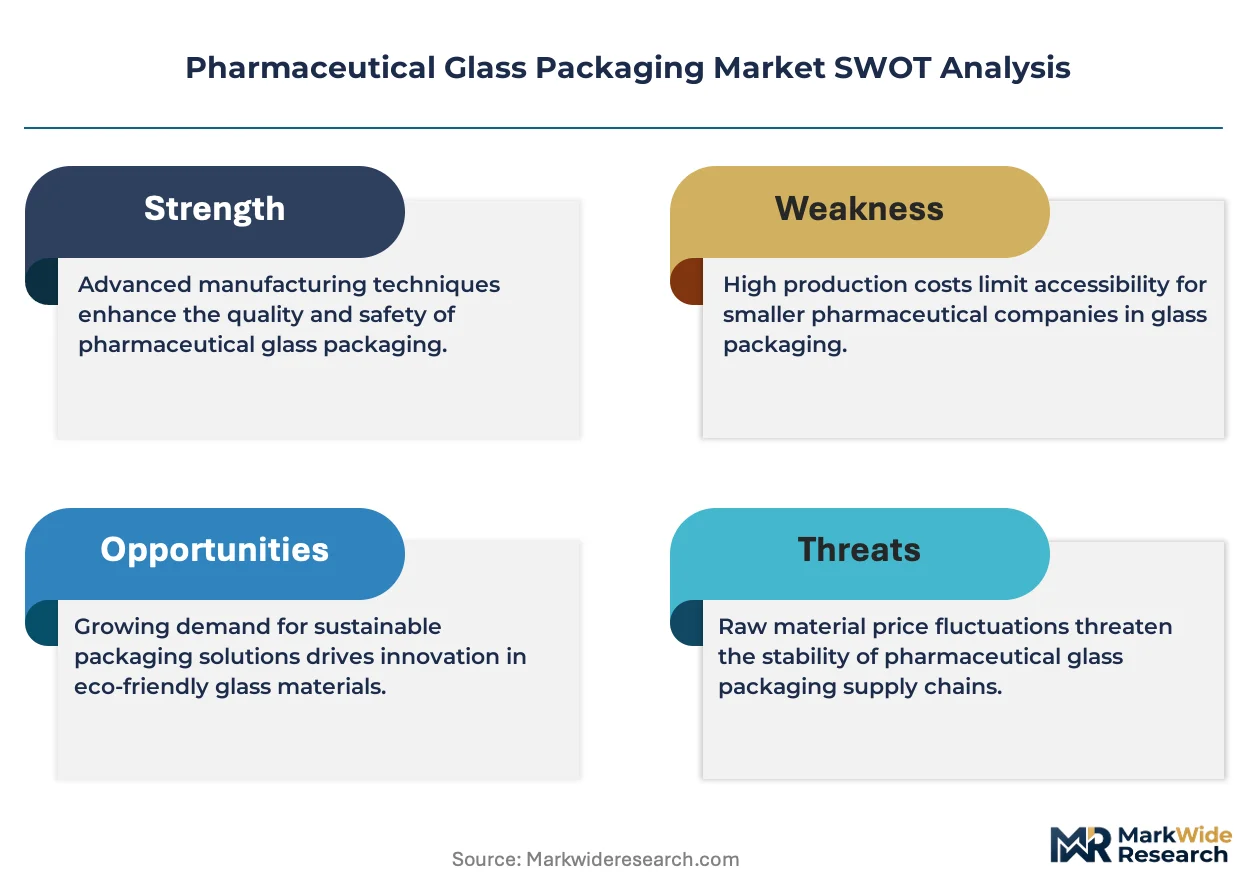
- Borosilicate raw material concentration:High-purity silica sand and alumina sourcing for pharmaceutical-grade tubing concentrates among limited specialty chemical suppliers, creating input cost volatility.
- FDA extractables testing burdens:The Container Closure System guidance imposes extended analytical timelines for glass surface chemistry validation, stretching supplier qualification cycles.
- Polymer substitution in diagnostics:Cyclic olefin polymers are displacing glass ampoules in point-of-care test kits where break-resistance outweighs chemical inertness requirements.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Ahmedabad are upgrading to USP Type I glass standards, creating qualified supplier demand.
- Dual-chamber cartridge convergence:Lyophilized drug and diluent integration within single glass containers is opening device-packaging hybrid categories for complex biologic administration.
- NMPA pharmacopeial harmonization:China's National Medical Products Administration is aligning surface delamination protocols with USP <1660>, reducing dual-certification burdens for multinational suppliers.
Industry Challenges
- Delamination analytical talent scarcity:Glass surface chemistry expertise for predictive testing remains concentrated among aging specialists in German and Swiss analytical laboratories.
- Fill-finish line reconfiguration costs:Pharmaceutical manufacturers face capital-intensive retrofitting when switching between molded and tubular glass formats due to dimensional tolerance mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Glass Packaging Market |
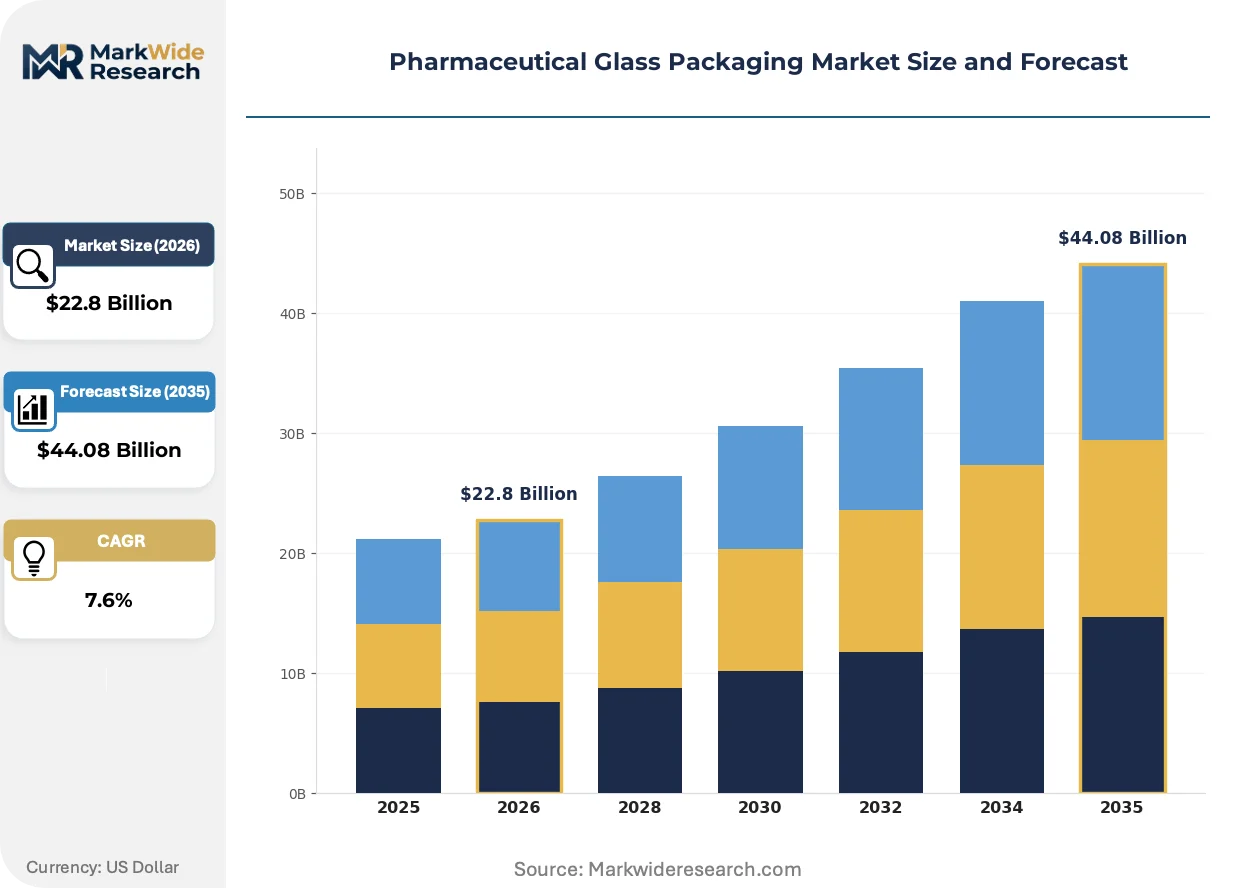
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $44.08 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ampoules, Vials, Carboys, Syringes Application: Injectables, Oral Solutions, Vaccines, Diagnostic Kits Delivery Mode: Standard Delivery, Controlled Delivery, Bulk Delivery, Custom Delivery End User: Pharmaceutical Manufacturers, Contract Packaging Organizations, Research Institutions, Hospitals |
| Companies Covered | SGD Pharma, Bormioli Pharma S.p.A., Schott AG, Stevanato Group, Nipro Corporation, Gerresheimer AG, Ardagh Group S.A., Şişecam, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Glass Packaging Market Strategic Shifts & Innovations
Glass primary packaging is evolving from commodity containment toward integrated drug delivery interfaces, with surface engineering and connectivity features becoming competitive differentiators beyond hydrolytic resistance baselines.
Inner-surface siliconization technology is integrating covalent bonding chemistries that reduce protein aggregation in monoclonal antibody formulations. Biologics sponsors in Switzerland and Massachusetts are specifying these treatments as standard for high-concentration injectables. The technology is integrating container and drug stability functions into unified specification sheets that bypass traditional compounding pharmacy steps.
REACH Annex XVII restrictions on heavy metal content are compelling reformulation of glass colorants and surface coatings across European manufacturing. Suppliers are accelerating migration to non-toxic alternatives for amber and red-tinted vials used in light-sensitive drug protection. Parenteral packaging for oncology applications faces the steepest compliance timelines, with German manufacturers leading substitution programs.
Pharmaceutical procurement teams are consolidating primary packaging specifications across global manufacturing networks to reduce qualification duplication. This standardization is compressing the supplier base accessible to individual drug sponsors while elevating technical service capabilities as selection criteria. The pattern is most visible among top-twenty biopharmaceutical firms with multi-continental fill-finish footprints.
Pharmaceutical Glass Packaging Market Segmentation
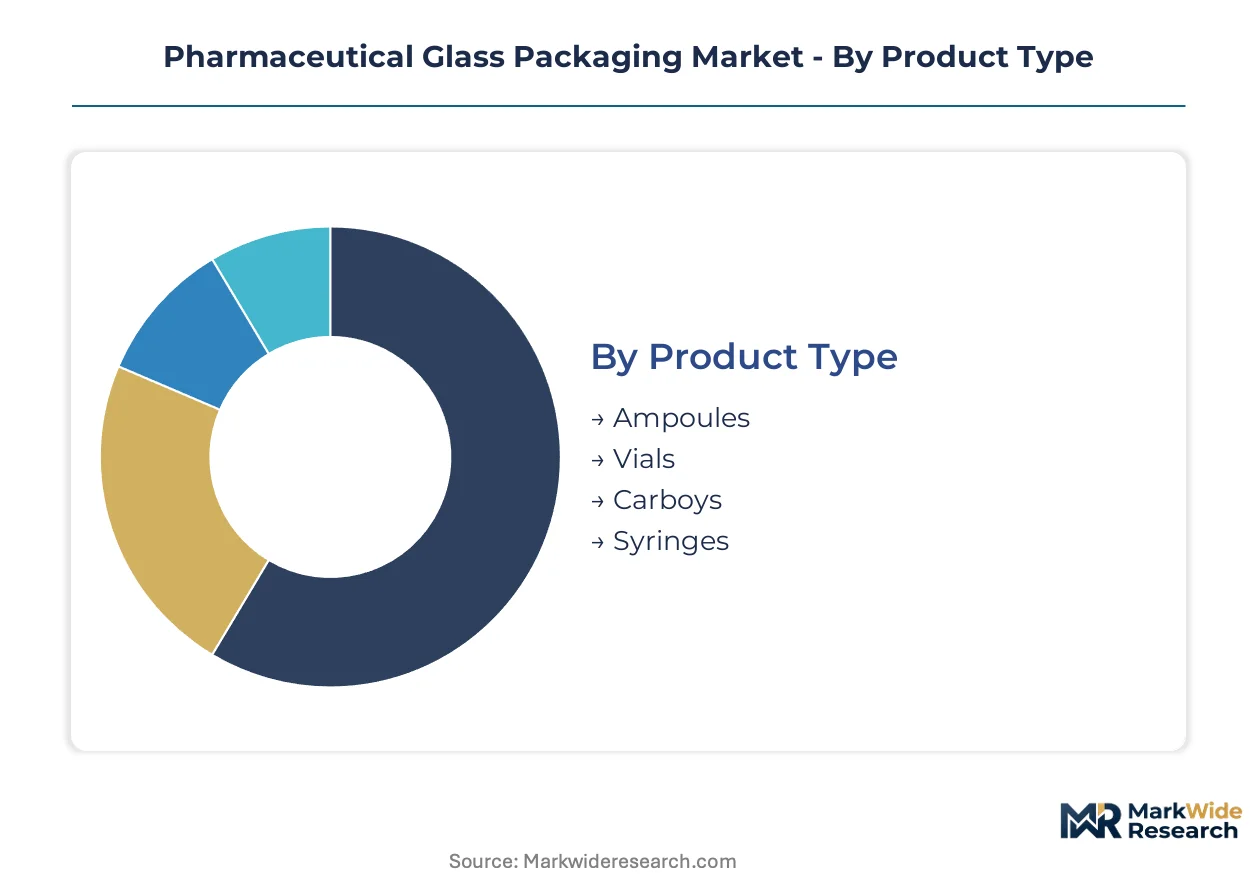
Segmentation in pharmaceutical glass packaging reveals how specification requirements fragment across therapeutic categories and supply chain positions. Each dimension—product geometry, clinical application, logistics mode, and customer type—imposes distinct certification burdens and margin structures on suppliers.
Product Type:
Standardization dominates high-volume tubular formats while molded configurations retain customization premiums for complex geometries.
- Vials:Tubular borosilicate construction dominates injectable and vaccine applications, with USP Type I hydrolytic resistance certification required across German and North American fill-finish networks. Demand concentrates among biologics manufacturers in Mainz and Massachusetts seeking dimensional consistency for automated inspection lines.
- Syringes:Ready-to-use pre-sterilized configurations eliminate compounding steps, with integrated plunger-stopper systems specified by monoclonal antibody sponsors in Switzerland. Surface siliconization treatments are becoming standard specifications for high-concentration protein formulations.
- Ampoules:Score-break neck designs persist in emerging market oral solutions and diagnostic reagents where unit cost outweighs resealability requirements.
- Carboys:Large-volume molded containers serve buffer and media preparation in bioprocessing facilities, with specialized coatings for pH-sensitive liquid storage.
Leading the category by volume: Vials. Expanding most quickly: Syringes.
Application:
Regulatory intensity varies sharply across therapeutic categories, with sterile injectable standards imposing the steepest qualification barriers.
- Injectables:Parenteral applications mandate USP Type I borosilicate with validated extractables profiles under FDA Container Closure System guidance. EMA Annex 1 sterile manufacturing revisions are accelerating surface delamination testing investments among European suppliers.
- Vaccines:Multi-dose vial formats with preservative compatibility requirements dominate public procurement, with aluminum adjuvant stability dictating specific glass composition selections.
- Oral Solutions:Soda-lime and treated Type III glass suffice for non-sterile liquid formulations, with amber tinting specified for light-sensitive API protection under REACH Annex XVII compliance timelines.
- Diagnostic Kits:Glass ampoules face displacement by cyclic olefin polymers in point-of-care applications where mechanical durability outweighs chemical inertness.
Dominating procurement volumes: Injectables. Steepest specification escalation: Vaccines.
Delivery Mode:
Logistics configuration determines whether packaging is qualified directly by drug sponsors or through contract manufacturing intermediaries.
- Standard Delivery:Bulk unsterilized vials and syringes supplied to fill-finish contractors remain the baseline procurement mode for generic injectable manufacturers.
- Controlled Delivery:Pre-sterilized nested configurations with validated seal integrity are specified by biologics sponsors decoupling packaging from fill-finish contracts.
- Bulk Delivery:Large-quantity shipments to pharmaceutical manufacturers with in-house washing and depyrogenation capabilities concentrate among established oral solid dose producers.
- Custom Delivery:Patient-specific kit assembly with integrated labeling and serialization responds to EMA track-and-trace mandates for direct-to-pharmacy distribution.
Highest volume flow: Standard Delivery. Fastest qualification shift: Controlled Delivery.
End User:
Purchasing authority is migrating from contract manufacturers toward drug sponsors, restructuring supplier relationship economics.
- Pharmaceutical Manufacturers:Top-tier biopharmaceutical firms with multi-continental fill-finish footprints are consolidating specifications to reduce qualification duplication, compressing accessible supplier bases.
- Contract Packaging Organizations:CDMOs in Hyderabad and Ahmedabad are upgrading to USP Type I standards, creating qualified supplier demand for Western tubing manufacturers.
- Research Institutions:Small-batch clinical trial material requirements favor flexible minimum order quantities and rapid specification change capabilities.
- Hospitals:Compounding pharmacy and in-house sterile preparation units specify ready-to-use formats to reduce manipulation steps and particulate risk.
Concentrating purchasing authority: Pharmaceutical Manufacturers. Fastest capability upgrade: Contract Packaging Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical glass production clusters in Mainz and Mitterteich anchor European supply security, while contract manufacturing upgrades in India and regulatory harmonization in China reshape procurement geography.
Germany
USP Type I borosilicate tubing demand concentrates among biologics manufacturers in Mainz seeking dimensional consistency for automated inspection lines. EMA serialization mandates accelerate investment in pre-coded glass containers with integrated data matrix markings. Gerresheimer and Schott anchor specialized production clusters in Mitterteich and Mainz.
United States
FDA Container Closure System guidance imposes extended analytical timelines for glass surface chemistry validation among Massachusetts-based monoclonal antibody sponsors. The Drug Supply Chain Security Act tightens traceability requirements for primary packaging across fill-finish networks. Boston-area biotech clusters specify ready-to-use pre-sterilized syringes to eliminate compounding steps.
India
Contract development and manufacturing organizations in Hyderabad and Ahmedabad upgrade to USP Type I glass standards, creating qualified supplier demand from Western tubing manufacturers. CDSCO alignment with international pharmacopeial standards reduces dual-certification burdens for multinational drug sponsors. Gujarat-based CDMOs invest in nested pre-sterilized configurations.
China
NMPA pharmacopeial harmonization aligns surface delamination protocols with USP standards, reducing certification duplication for multinational suppliers. Domestic biologics manufacturers in Shanghai and Suzhou expand ready-to-use glass syringe adoption to reduce contamination risk. Yangtze River Delta clusters concentrate molded glass capacity for complex biologic containers.
Switzerland
Swissmedic oversight of sterile manufacturing drives specification escalation for high-concentration protein formulations requiring surface siliconization treatments. Basel-area biologics sponsors integrate container and drug stability functions into unified specification sheets. Swiss analytical laboratories concentrate scarce glass surface chemistry expertise for predictive delamination testing.
Pharmaceutical Glass Packaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Consolidation concentrates among tubing-grade borosilicate suppliers holding long-term pharmaceutical agreements, while molded glass and diagnostic segments fragment across regional fabricators. Two strategic archetypes dominate: integrated device-packaging hybrids controlling container-to-administration interfaces, and pure-play tubing specialists leveraging material science certification. Competitive moves center on backward integration into raw material refining and geographic expansion through CDMO qualification partnerships.
Among German-based fabricators, Schott AG and Gerresheimer AG occupy positions anchoring European borosilicate supply security. Schott exemplifies the tubing-specialist archetype through FIOLAX borosilicate dominance, while Gerresheimer represents molded glass capacity for complex biologic geometries. Stevanato Group sits within the integrated hybrid tier, controlling the interface between primary packaging and drug delivery device engineering. These three entities represent distinct competitive positioning vectors—material certification, geometric customization, and system integration—rather than direct product rivalry.
| Leading Market Players |
|---|
| SGD Pharma |
| Bormioli Pharma S.p.A. |
| Schott AG |
| Stevanato Group |
| Nipro Corporation |
| Gerresheimer AG |
| Ardagh Group S.A. |
| Şişecam |
| Corning Incorporated |
| Others |
Cost & Logistics Intelligence
High-purity silica sand and alumina feedstock costs transmit downstream through three distinct pricing tiers, with USP Type I borosilicate tubing commanding premiums over soda-lime alternatives as German manufacturers pass through energy-intensive refining expenses.
Pricing Analysis
Margin tightening in standard-grade soda-lime vials reflects polymer substitution pressure from cyclic olefin competitors in diagnostic applications. Three-tier pricing structure across premium, standard, and economy levels separates USP Type I certified borosilicate from treated Type III and uncoated soda-lime alternatives. Cost-down pressure on molded glass carboys accelerates because Indian CDMOs are consolidating specifications to reduce qualification duplication. Generic injectable manufacturers exhibit highest price sensitivity, while Swiss biologics sponsors prioritize surface siliconization over unit economics.
Supply Chain Analysis
Borosilicate tubing supply rests on German specialty chemical producers in Mainz and Mitterteich, with secondary concentrations in Italy and Japan for molded glass capacity. Critical inputs include high-purity silica sand, aluminum oxide, and specialty barium carbonate for hydrolytic resistance certification. Single-source vulnerability concentrates around FIOLAX-grade tubing long-term agreements, creating qualification bottlenecks for second-tier pharmaceutical sponsors. Distribution runs through direct supply contracts to drug sponsors rather than contract manufacturing intermediaries, reflecting the decoupling trend in biologics procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical glass packaging functions as a cost-of-compliance market where FDA Container Closure System guidance and EMA Annex 1 revisions erect barrier-to-entry moats favoring incumbent suppliers with validated extractables profiles.
For Market Incumbents: Deploy backward integration into high-purity silica refining to secure input cost stability against alumina price volatility. Anchor capacity expansion in Indian CDMO qualification partnerships to capture Hyderabad and Ahmedabad upgrade cycles. Cyclic olefin polymer substitution in point-of-care diagnostics threatens ampoule volume; counter via surface siliconization service bundling for high-concentration protein formulations. For New Entrants and Emerging Players: Launch via dual-chamber cartridge engineering partnerships with Swiss device-packaging integrators, bypassing direct competition with Schott's tubing dominance. White-space concentrates in Chinese NMPA harmonization consulting services and predictive delamination analytical outsourcing. Target research institutions requiring flexible minimum order quantities for clinical trial materials. For Investors and Strategic Acquirers: NMPA-USP pharmacopeial convergence is the leading indicator that multinational certification burdens will compress, elevating asset values for pre-qualified tubing manufacturers. Five-to-ten-year viability hinges on surface chemistry expertise scarcity concentrated in German and Swiss analytical laboratories. Acquisition target archetype: molded glass specialists with complex biologic container geometries and existing EMA track-and-trace infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| USP Type I Certification Investment | EMA Annex 1 revisions extend qualification timelines, privileging pre-certified suppliers. |
| Indian CDMO Qualification Partnership | Hyderabad and Ahmedabad upgrades create captive demand for Western tubing manufacturers. |
| Surface Siliconization Service Expansion | Swissmedic oversight drives specification escalation for high-concentration monoclonal antibodies. |
| Dual-Chamber Cartridge Development | Lyophilized drug-diluent integration opens device-packaging hybrid categories. |
| Predictive Delamination Testing Capability | FDA extractables burdens concentrate analytical talent scarcity in Basel-area laboratories. |
Research Approach
Document review covered FDA Container Closure System guidance, EMA Annex 1 revision drafts, and USP <660>/<1660> pharmacopeial standards, complemented by interviews with regulatory affairs leads at biologics manufacturers, fill-finish operations directors, glass supplier technical service heads, and CDMO procurement managers. Secondary validation drew from FDA 483 inspection observations, EMA marketing authorization databases, and German trade association production statistics. Bottom-up demand modeling triangulated against top-down industry capacity assessments.
Segmentation outputs across product geometry, therapeutic application, delivery mode, and end-user type fed into volume and value projections over the analysis window. CAGRs derived from regression analysis against biologics pipeline expansion rates and fill-finish automation investment cycles. Industry-specific inputs included surface delamination test adoption curves and serialization mandate implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for cyclic olefin polymer substitution in diagnostics would alter the outlook for ampoule demand. Forecasts reflect assumptions about pharmacopeial harmonization progress and extractables testing standardization. EMA track-and-trace enforcement intensity and NMPA protocol alignment warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Ethiopia Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Egypt Container Glass Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Russia Glass Packaging Market