
 North America Pharmaceutical Glass Packaging Market | 2026-2036
North America Pharmaceutical Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pharmaceutical Glass Packaging Market Insights
Specialized glassblower and forming technician availability is collapsing across the Great Lakes and Mid-Atlantic manufacturing belts, forcing converters to automate or relocate training programs. Schott AG leverages its US-based tubular glass operations to sustain proximity to Northeast biotech clusters. Corning Incorporated anchors high-value pharmaceutical glass supply through its Valor Glass platform, which competes on chemical durability against legacy borosilicate alternatives.
Pharmaceutical glass packaging denotes containers fabricated from borosilicate, soda-lime, or treated glass formulations engineered to meet USP <660> and EP 3.2.1 chemical durability standards, manufactured via tubular or molded forming processes, and designed to maintain drug stability, prevent leachable migration, and ensure patient safety across shelf life. Borosilicate glass dominates parenteral applications where thermal shock resistance and low extractables prove critical, while soda-lime formulations occupy oral solid dosage segments where cost sensitivity outweighs performance premiums. Vials capture the largest volume share among product types, though high-performance glass variants are gaining traction in cell and gene therapy cold-chain logistics.
FDA enforces container closure integrity through its combination product regulations, while USP <1660> and <1664> guidance documents shape extractables and leachables testing protocols that directly determine material qualification timelines. Health Canada and PMRA alignment with ICH Q3D elemental impurity standards further narrows supplier eligibility for cross-border pharmaceutical distribution. Stakeholders must monitor evolving USP chapters and FDA draft guidance on nitrosamine contamination risks, as these will dictate next-generation glass surface treatments and supplier qualification burdens.
Market Dynamics
FDA serialization mandates and USP <660> container testing standards are compressing supplier qualification timelines while biologics manufacturers demand higher chemical durability from Type I borosilicate glass. This regulatory-performance tension is restructuring procurement relationships across the Northeast pharmaceutical corridor.
Growth Catalysts
- Biologics expansion:Cell and gene therapy developers require borosilicate vials with ultra-low extractable profiles for cold-chain parenteral delivery. FDA combination product regulations mandate container closure integrity that only specialized glass formulations satisfy.
- Serialization compliance:Drug Supply Chain Security Act track-and-trace requirements force secondary packaging integration with primary glass containers. Massachusetts and New Jersey sterile fill-finish facilities are retrofitting lines to accommodate serialized glass vial feeds.
- Elemental impurity standards:Health Canada and PMRA alignment with ICH Q3D narrows qualified supplier pools for cross-border distribution. US-based converters capturing dual-jurisdiction certification gain preferential access to integrated North American supply chains.
Market Restraints
- Specialized labor scarcity:Glassblower and forming technician availability has collapsed across Great Lakes and Mid-Atlantic manufacturing belts. Training program gaps constrain domestic tubular and molded glass capacity expansion regardless of capital deployment.
- Raw material concentration:High-purity boron and sand feedstocks concentrate among limited specialty chemical suppliers. Geopolitical friction or shipping disruption to US ports immediately compresses domestic glass melting operations.
- Plastic substitution pressure:Cyclic olefin polymers and advanced plastics penetrate oral solid dosage segments where cost sensitivity outweighs glass performance premiums. Soda-lime glass faces displacement in non-parenteral applications.
Strategic Opportunities
- Surface treatment innovation:Siliconization and barrier coatings for protein drug compatibility represent underexploited technical white space. Glass suppliers developing proprietary hydrophobic layer deposition capture premium positioning in monoclonal antibody containment.
- Mexico manufacturing expansion:Greenfield tubular glass facilities near Tijuana and Monterrey offer tariff-advantaged access to US Southwest distribution networks. Maquiladora structures reduce landed cost for standard-grade vial categories.
- USP <1660> leachables testing:Extractables protocol standardization creates service revenue streams for analytical laboratories supporting supplier qualification. Third-party testing partnerships accelerate FDA submission timelines for novel glass formulations.
Industry Challenges
- Automation capex intensity:Robotic forming and inspection systems require eight-figure capital commitments per production line. Mid-tier converters face binary choices between scale investment and contract manufacturing exit.
- Legacy equipment integration:Cold-end coating and printing systems from prior decades lack digital connectivity for Industry 4.0 traceability requirements. Retrofit complexity delays serialization compliance for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pharmaceutical Glass Packaging Market |
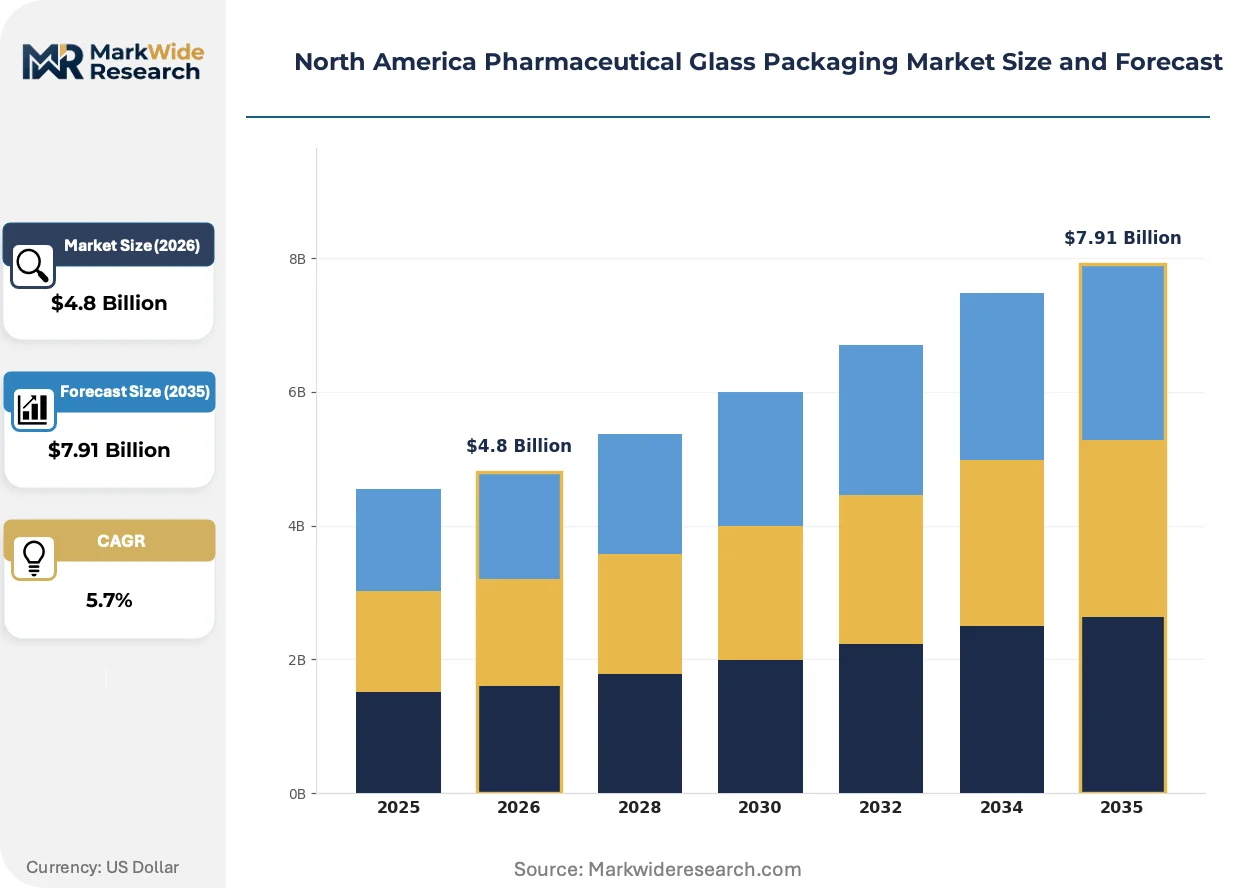
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Bottles, Jars Packaging Type: Rigid, Flexible, Semi-Rigid, Blister Packs End User: Pharmaceutical Manufacturers, Biotech Companies, Contract Packaging, Research Laboratories Materials: Soda-Lime Glass, Borosilicate Glass, Low Boron Glass, High-Performance Glass |
| Companies Covered | Schott AG, Corning Incorporated, Gerresheimer AG, West Pharmaceutical Services Inc., PGP Glass USA Inc., Stevanato Group, Nipro Corporation, Owens Illinois Inc., SGD Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pharmaceutical Glass Packaging Market Trends and Innovations
Pharmaceutical glass packaging is undergoing material science and process automation convergence that redefines performance benchmarks for parenteral drug containment. Three developments are compressing competitive differentiation windows across the North American supply base.
Valor Glass and chemically strengthened alternatives are miniaturizing the performance gap between legacy borosilicate and engineered solutions. Biologics manufacturers in Boston and New Jersey are piloting these platforms for high-value injectable portfolios. The technology is miniaturizing qualification timelines from multi-year validation cycles to compressed eighteen-month pathways.
FDA draft guidance on nitrosamine contamination risks is mandating surface chemistry documentation for all glass primary packaging. Container suppliers must now demonstrate absence of N-nitrosodimethylamine precursors in forming lubricants and coatings. Parenteral oncology drug sponsors in the Northeast corridor are demanding batch-level nitrosamine testing certificates, forcing glass converters to revalidate entire process chains.
Consolidated buying desks at major CDMOs are compressing supplier panels from twelve to three qualified vendors per container category. Thermo Fisher and Catalent procurement organizations are unbundling technical qualification from commercial negotiation, awarding multi-year sole-source contracts to glass suppliers with integrated analytical services. This concentration is most visible in New Jersey's contract fill-finish cluster, where purchasing power has shifted decisively toward integrated packaging-sourcing platforms.
North America Pharmaceutical Glass Packaging Market Segmentation
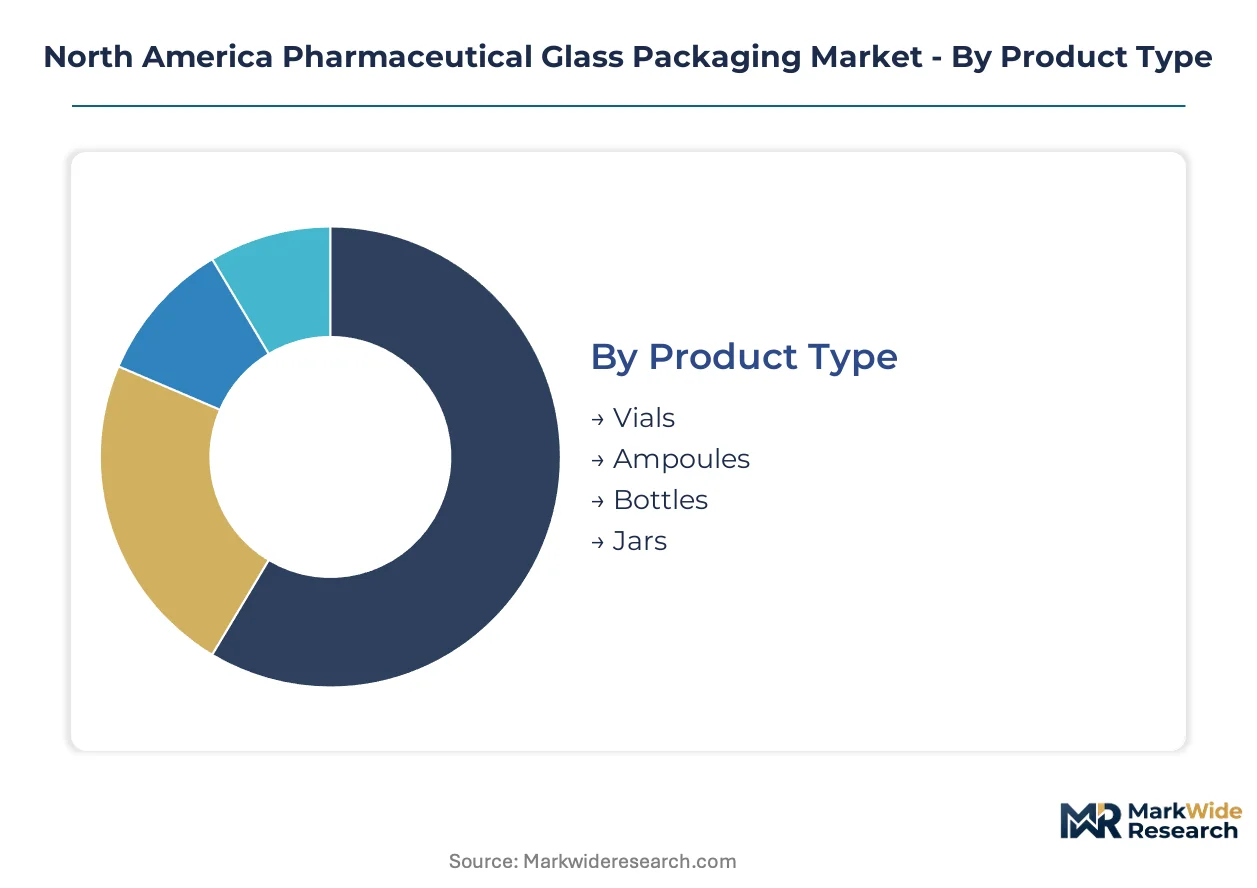
Pharmaceutical glass packaging segmentation reveals how regulatory requirements cascade through material specifications, container geometries, and end-user procurement patterns. Each dimension carries distinct FDA qualification burdens and supply chain implications across the Northeast biotech corridor.
Product Type:
FDA container closure integrity mandates and USP <660> testing protocols create divergent qualification timelines across primary container geometries.
- Vials:Cylindrical borosilicate containers with crimp or screw closures dominate parenteral drug containment. Massachusetts and New Jersey sterile fill-finish facilities specify Type I borosilicate for biologics cold-chain stability. FDA combination product regulations compress supplier validation cycles for vial-based injectable portfolios.
- Ampoules:Single-dose glass containers sealed by flame fusion eliminate elastomeric closure compatibility concerns. Boston-area cell therapy developers favor ampoules for gene therapy vectors requiring absolute barrier integrity. USP <1660> extractables documentation demands extend ampoule qualification timelines versus multi-dose alternatives.
- Bottles:Multi-dose containers with threaded closures serve oral liquid and topical formulations. Soda-lime compositions satisfy cost-sensitive over-the-counter segments where USP <660> Type III standards apply.
- Jars:Wide-mouth containers accommodate semi-solid dosage forms including ointments and creams. Mid-Atlantic compounding pharmacies drive regional demand for amber glass jar configurations.
Vials handle the majority of throughput; ampoules are expanding most quickly on share.
Packaging Type:
Cost tier differentiation separates capital-intensive rigid systems from flexible alternatives in secondary and tertiary configurations.
- Rigid:Glass primary containers with molded structural integrity withstand sterilization and distribution stresses. Northeast biotech clusters specify rigid vial systems for high-value monoclonal antibody portfolios where container deformation risks patient safety.
- Flexible:Polymer-based secondary packaging including overwrap films and pouch configurations. Cold-chain distribution networks for cell therapies integrate flexible barrier layers with rigid glass primaries.
- Semi-Rigid:Hybrid constructions combining glass stability with polymer handling advantages. Contract packaging organizations in New Jersey pilot semi-rigid formats for clinical trial materials requiring variable batch sizes.
- Blister Packs:Thermoformed cavities with lidding foil for unit-dose oral solids. Soda-lime glass compatibility limits restrict blister applications to non-parenteral dosage forms.
Rigid configurations command premium positioning; flexible systems are gaining share fastest in cold-chain logistics.
End User:
Customer type determines procurement scale, qualification depth, and supplier relationship structure across the pharmaceutical value chain.
- Pharmaceutical Manufacturers:Integrated drug developers with captive fill-finish operations. Major sponsors in the Northeast corridor maintain approved supplier lists with three-vendor maximums per container category, consolidating purchasing power.
- Biotech Companies:Emerging drug developers outsourcing manufacturing to contract partners. Boston and San Diego biotechs prioritize glass suppliers with integrated analytical services to accelerate IND timelines.
- Contract Packaging:CDMOs and CMOs serving multiple sponsor portfolios. Catalent and Thermo Fisher procurement desks unbundle technical qualification from commercial negotiation, reshaping supplier access.
- Research Laboratories:Academic and government institutions with small-volume, high-variety requirements. Preclinical glass sourcing follows less stringent USP <660> protocols than commercial manufacturing.
Pharmaceutical manufacturers anchor volume demand; biotech companies are climbing the fastest on procurement influence.
Materials:
Supply concentration in high-purity feedstocks and melting capacity shapes material tier availability.
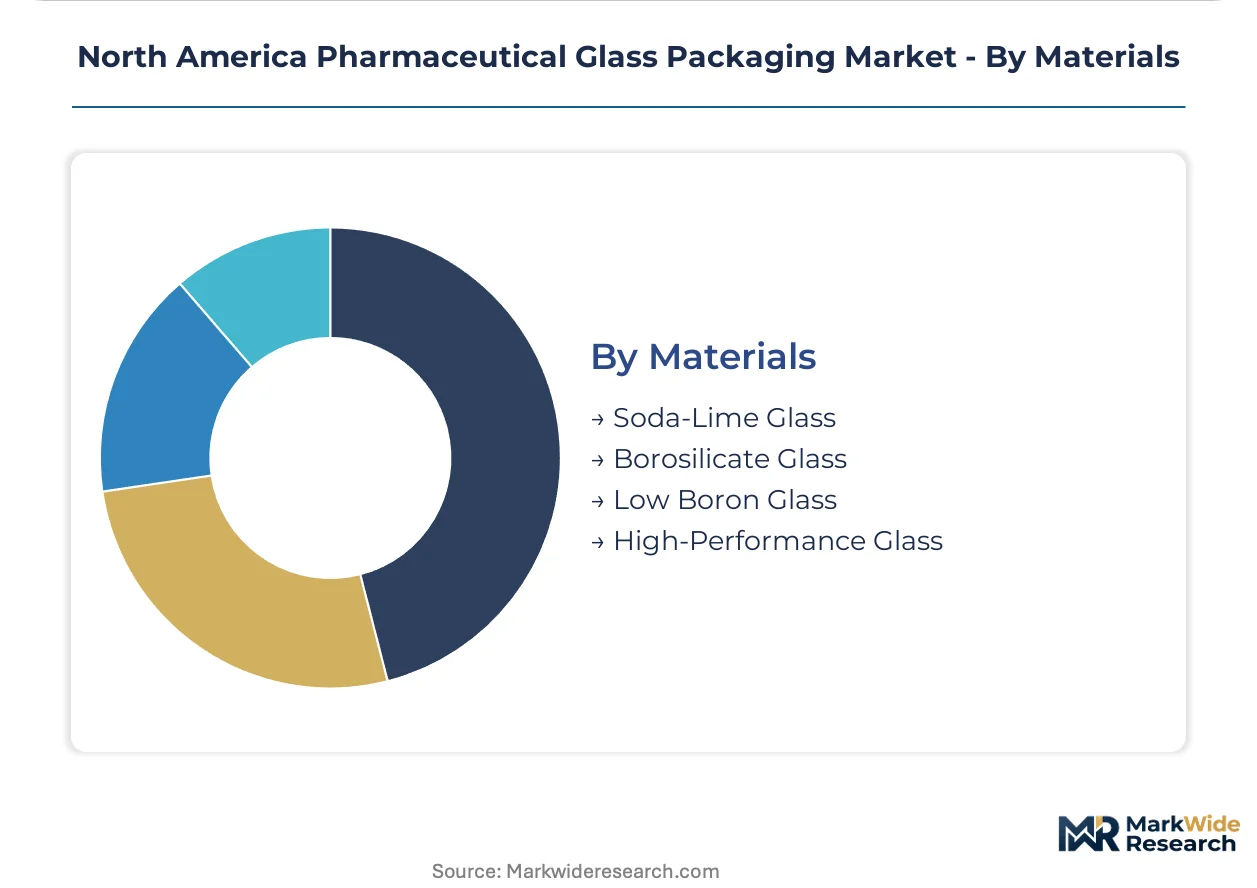
- Soda-Lime Glass:Cost-optimized formulations for oral solid and non-parenteral liquid applications. USP <660> Type III classification permits higher extractable profiles than borosilicate alternatives.
- Borosilicate Glass:Type I formulations with thermal shock resistance and low hydrolytic resistance. Northeast biologics manufacturing requires borosilicate for all parenteral containment.
- Low Boron Glass:Intermediate formulations reducing boron leachables for protein drug compatibility. FDA draft guidance on elemental impurities is accelerating low boron qualification.
- High-Performance Glass:Chemically strengthened or engineered surface treatments including siliconized barriers. Corning's Valor Glass platform and Schott's FIOLAX Pro compete in this tier for oncology and gene therapy applications.
Borosilicate glass dominates current throughput; high-performance variants are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates and USP container testing standards anchor United States regulatory requirements, while Health Canada and Mexico's COFEPRIS maintain aligned but distinct qualification pathways for cross-border pharmaceutical distribution.
United States
Biologics manufacturers in Massachusetts and New Jersey drive Type I borosilicate demand for injectable containment. FDA Drug Supply Chain Security Act track-and-trace requirements compress supplier validation timelines for serialized vial feeds. Greater Boston's cell therapy cluster and New Jersey's contract fill-finish corridor concentrate procurement power among three-vendor maximum approved supplier lists.
Canada
Health Canada alignment with ICH Q3D elemental impurity standards narrows qualified supplier pools for cross-border distribution. PMRA container closure integrity requirements mirror FDA combination product regulations for parenteral oncology drugs. Ontario's pharmaceutical manufacturing belt near Toronto sustains demand for USP Type III soda-lime bottles in oral solid dosage segments.
Mexico
Maquiladora structures near Tijuana and Monterrey offer tariff-advantaged access to US Southwest distribution networks for standard-grade vial categories. COFEPRIS regulatory convergence with FDA standards accelerates dual-jurisdiction certification for export-oriented glass converters. Northern border states concentrate greenfield tubular glass investments serving California and Texas biotech distribution hubs.
North America Pharmaceutical Glass Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American pharmaceutical glass packaging supply base. The market structure concentrates around integrated multinationals with captive melting capacity and regional converters dependent on outsourced feedstock. Two strategic archetypes dominate: premium-tier suppliers competing on chemical durability and surface treatment innovation, and scale-driven players optimizing throughput for oral solid dosage segments. Consolidated buying desks at major CDMOs are compressing supplier panels through multi-year sole-source contracts, while mid-tier converters face binary choices between eight-figure automation investments and contract manufacturing exit.
Within the premium-tier vector, Schott AG and Corning Incorporated exemplify technology-forward positioning. Schott's US-based tubular glass operations sustain proximity to Northeast biotech clusters requiring Type I borosilicate for parenteral applications. Corning occupies a position defined by engineered surface treatments and chemically strengthened alternatives competing against legacy borosilicate formulations. Gerresheimer AG represents the integrated multinational archetype with cross-border qualification capabilities serving both FDA and Health Canada jurisdictions.
| Leading Market Players |
|---|
| Schott AG |
| Corning Incorporated |
| Gerresheimer AG |
| West Pharmaceutical Services Inc. |
| PGP Glass USA Inc. |
| Stevanato Group |
| Nipro Corporation |
| Owens Illinois Inc. |
| SGD Pharma |
| Others |
Pricing and Supply Chain Analysis
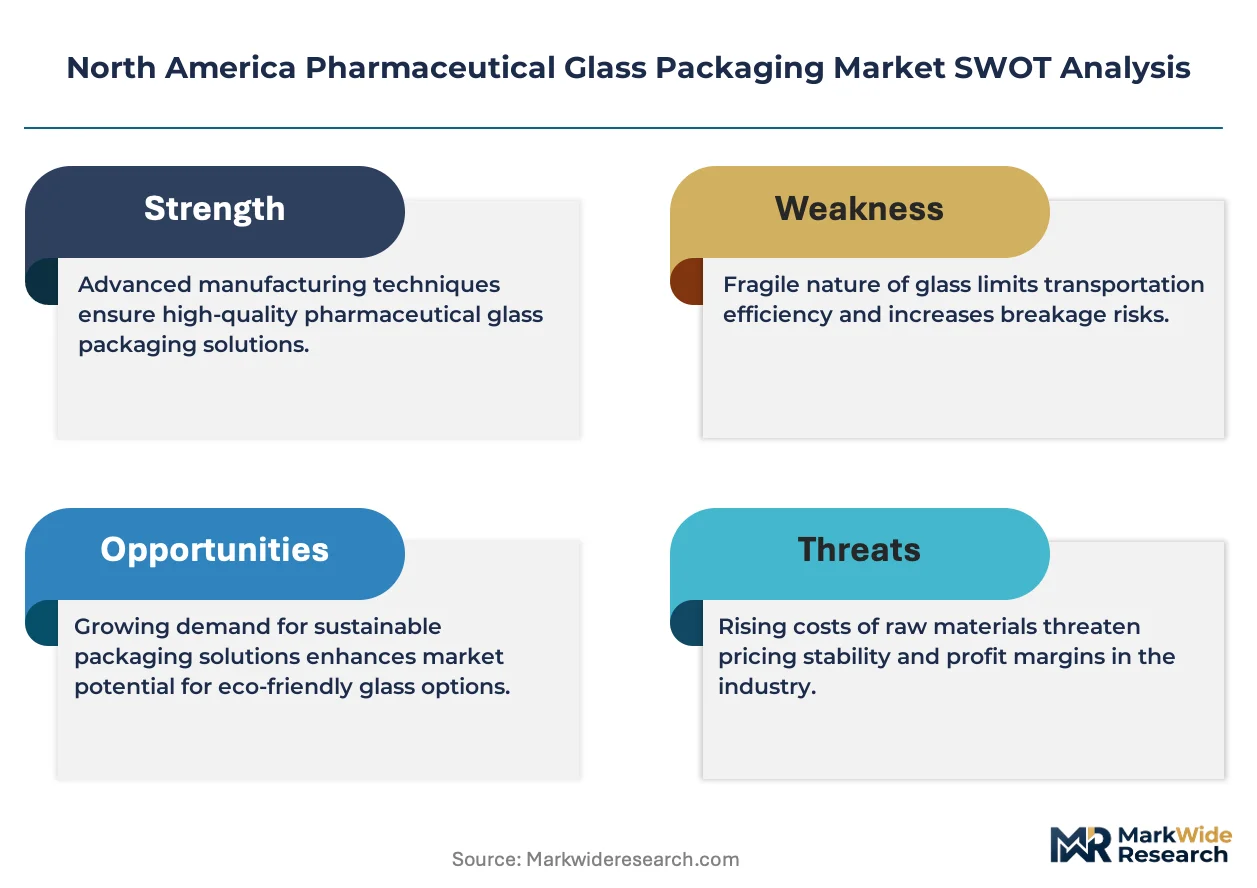
Plastic substitution in oral solid dosage segments simultaneously shifts production geography toward polymer converters in Mexico and compresses pricing premiums for soda-lime glass across the Mid-Atlantic distribution corridor. This material displacement forces traditional glass suppliers to defend borosilicate positioning through certification investments while repositioning commodity-grade output toward cost-sensitive markets.
Pricing Analysis
Massachusetts commands 15-20% premiums over Texas for Type I borosilicate vials due to sterile fill-finish cluster density and just-in-time delivery requirements. Three-tier pricing structure across premium, standard, and economy levels separates USP <660> Type I certified borosilicate from Type III soda-lime and uncoated commodity grades. Cost compression in standard-grade categories is intensifying because Mexican maquiladora output undercuts domestic converters on landed cost. Contract packaging organizations exhibit highest price sensitivity, while cell and gene therapy developers prioritize chemical durability over unit economics.
Supply Chain Analysis
United States and Mexico anchor tubular glass melting and forming operations serving the Northeast biotech corridor. High-purity boron from Turkey and specialty sand from Wisconsin feedstock sources rest on geopolitical stability and rail freight capacity. Single-source vulnerability concentrates in boron compound suppliers, where disruption immediately idles US melting furnaces. Distribution runs through regional converter networks with cold-end coating and serialization capabilities clustered around New Jersey and Boston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America pharmaceutical glass packaging market sits at a post-pandemic normalization phase that favors suppliers with captive certification capabilities and integrated analytical services.
For Market Incumbents: Secure backward integration into boron compound refining to insulate margin structures from feedstock volatility. Anchor capacity expansion in Monterrey and Tijuana maquiladora zones to capture tariff-advantaged access to California and Texas distribution networks. Plastic substitution in oral solid segments threatens soda-lime volume; defend positioning through USP <660> Type I certification investments that disqualify commodity converters from parenteral applications. For New Entrants and Emerging Players: Analytical testing service gaps where incumbents under-serve create entry pathways for laboratories offering USP <1660> extractables documentation. Target Boston-area cell therapy developers requiring batch-level nitrosamine testing certificates that established suppliers lack capacity to deliver. Pursue white-label partnerships with mid-tier converters seeking outsourced qualification support to accelerate FDA submission timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platforms with cross-border Health Canada and FDA dual certification. Long-term viability hinges on surface treatment innovation capabilities rather than commodity melting capacity. Monitor FDA draft guidance finalization on nitrosamine contamination as the inflection signal for revaluation of glass converter portfolios with validated process chains.| Strategic Initiative | Industry Significance |
|---|---|
| USP <1660> Testing Laboratory Partnership | Accelerates supplier qualification timelines for Boston biotech sponsors. |
| Monterrey Tubular Glass Facility | Captures tariff advantages for standard-grade vial supply to Texas. |
| Siliconization Process Development | Enables premium positioning in monoclonal antibody containment applications. |
| Health Canada Dual Certification | Unlocks cross-border distribution for Ontario pharmaceutical manufacturers. |
| Robotic Cold-End Inspection Deployment | Satisfies FDA serialization mandates for New Jersey fill-finish lines. |
Research Methodology
Initial hypotheses were tested against primary input from sterile fill-finish operations managers, regulatory affairs directors at CDMOs, pharmaceutical procurement leads, and glass converter technical sales executives and refined through secondary validation against FDA Drug Supply Chain Security Act implementation records, USP chapter revision notices, Health Canada ICH Q3D alignment documentation, and SEC filings from publicly traded packaging suppliers. Bottom-up demand modeling from biologics pipeline data and top-down supply capacity assessments from tubular glass furnace installations were triangulated to reconcile volume estimates.
Variance decomposition across product type, material grade, end-user category, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro pharmaceutical production indices. Forecast inputs incorporated biologics capacity expansion timelines from Massachusetts and New Jersey clusters, Mexican maquiladora investment announcements, and USP <660> testing protocol revision schedules.
Underlying assumptions cover sustained FDA serialization compliance deadlines, stable boron compound supply chains, and continued biologics outsourcing trends, with deviation risk concentrated in nitrosamine guidance finalization timing and plastics substitution acceleration in oral solid segments. Recalibration cycles align with material shifts in USP chapter revisions and FDA draft guidance promulgation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Middle East and Africa Glass Packaging Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Packaging Jars Market
Glass Packaging
India Container Glass Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
United Arab Emirates Glass Packaging Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Egypt Container Glass Market