
 Slovakia Container Glass Market | 2026-2036
Slovakia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Slovakia Container Glass Market Insights
Premium flint and extra-flint clarity grades is reorganizing procurement priorities across Slovak beverage bottlers. Vetropack Nemsova leverages its domestic furnace network to secure just-in-time supply contracts with regional distilleries. Ardagh Group anchors its position through backward integration into raw material sourcing and color consistency protocols. Saint-Gobain differentiates via specialized coating technologies that extend shelf-life performance for sensitive formulations.
Container glass denotes soda-lime silica vessels formed through blow-and-blow or press-and-blow processes, typically containing 70-74% silicon dioxide, 12-16% sodium oxide, and 10-13% calcium oxide, engineered to provide chemically inert, impermeable storage for consumable and pharmaceutical products. Bottles occupy the dominant volume position within the product type dimension, though vials command superior margin pools due to pharmaceutical certification requirements and dimensional tolerances. The food and beverage end-user segment sustains the broadest demand base, while personal care applications generate faster growth as Slovak cosmetic exporters expand branded glass packaging.
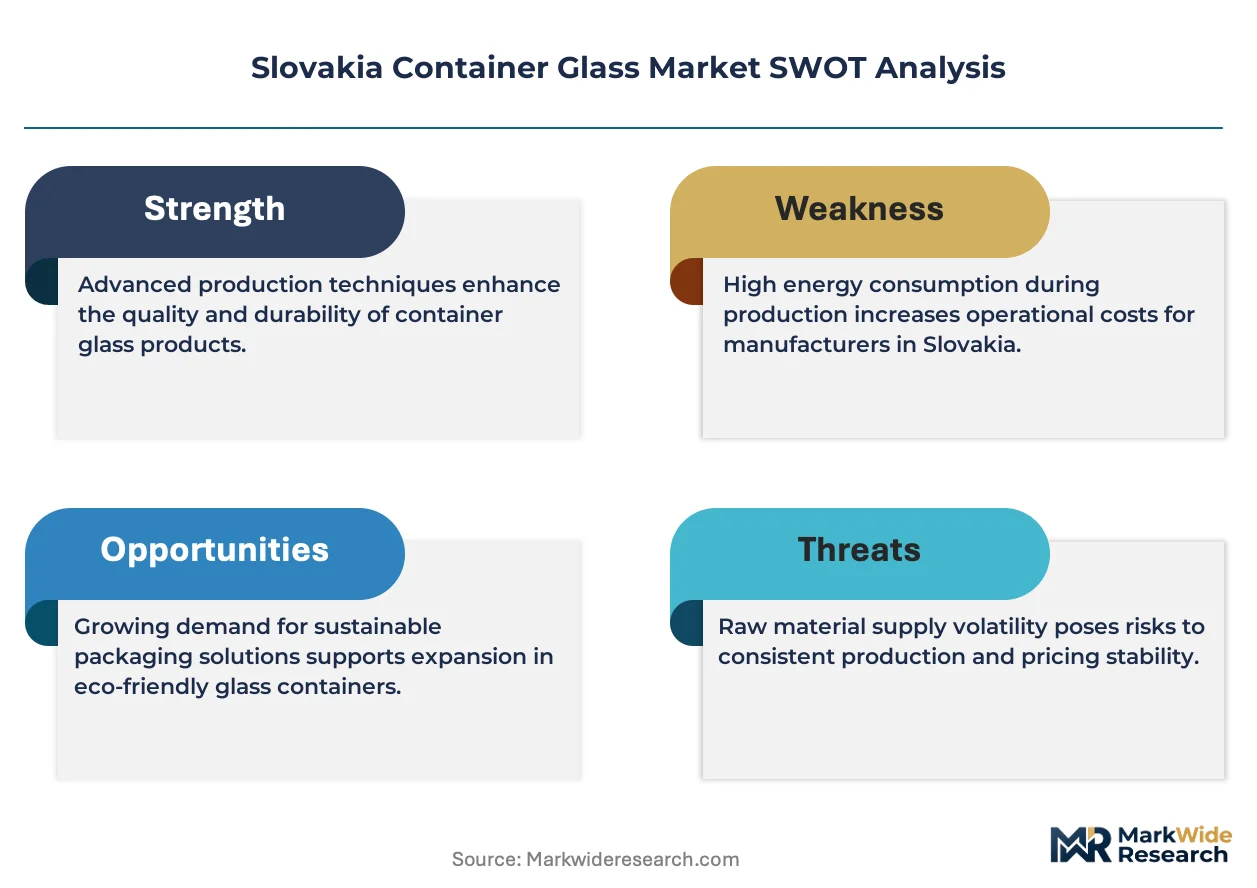
Slovakia's container glass sector operates under EU REACH compliance for chemical substance registration, CE marking for product safety conformity, and the EU Green Deal framework governing carbon-intensive manufacturing transitions. The country's national environmental regulator enforces emissions thresholds that push producers toward oxy-fuel furnace conversions and post-consumer cullet integration mandates. Stakeholders must monitor how tightening EU ETS carbon pricing affects furnace economics and whether Slovak glassmakers secure sufficient renewable energy contracts to maintain cost-competitive batch operations.
Market Dynamics
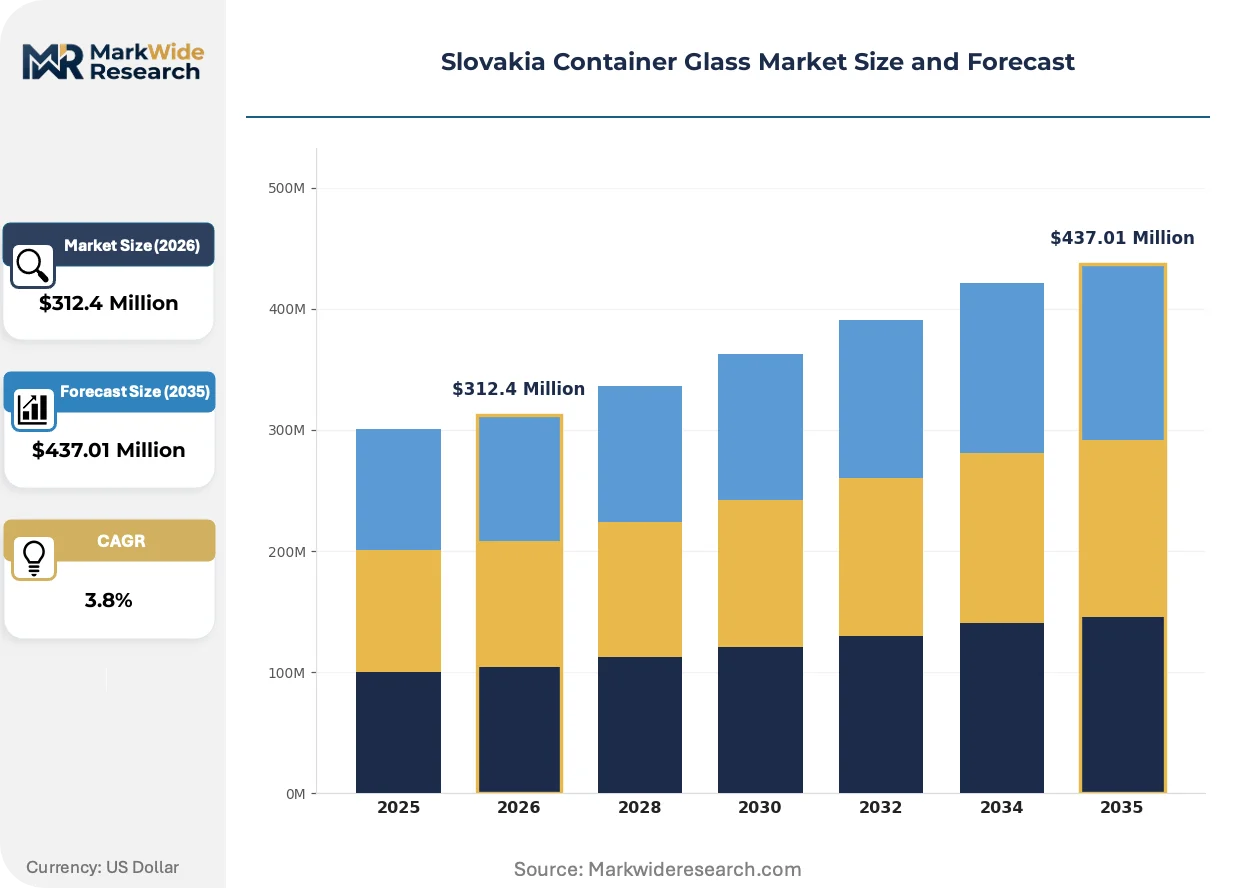
Furnace electrification trials across Slovakia's container glass sector are compressing the timeline for carbon-intensive asset replacement, while EU ETS carbon pricing forces immediate recalculation of batch economics.
Growth Catalysts
- EU Green Deal alignment:Slovakia's national environmental regulator enforces emissions thresholds that accelerate oxy-fuel furnace conversions and post-consumer cullet integration mandates across Bratislava-Trnava industrial corridor.
- Premium beverage packaging:Craft distilleries and spirits producers in Košice intensify procurement of amber and flint glass bottles with superior clarity grades.
- F-Gas Regulation compliance:The framework drives furnace technology upgrades that reduce fluorinated gas emissions from glass melting operations.
Market Restraints
- Natural gas price volatility:Batch operations remain tethered to fossil fuel inputs despite electrification pilots, exposing margin structures to energy cost swings.
- Supply concentration:Western Slovakia's furnace network dominates domestic capacity, creating geographic vulnerability to localized disruptions.
- Aluminum substitution:Lightweight metal packaging captures share in mass-market beverage segments where transport cost minimization outweighs premium glass aesthetics.
Strategic Opportunities
- Eastern Slovakia penetration:Košice and Prešov regions show underdeveloped glass packaging infrastructure relative to beverage production growth.
- Pharmaceutical vial certification:Dimensional tolerance requirements for sterile drug containment create margin pools above standard bottle production.
- Renewable energy contracting:Power purchase agreements with wind and solar providers enable cost-competitive electrified furnace operations under tightening EU ETS pricing.
Industry Challenges
- Electrical engineering talent scarcity:Electrified furnace operations demand specialized skill sets in high-temperature electrical systems that outpace regional vocational training output.
- Legacy batch house integration:New cullet preprocessing systems must interface with decades-old material handling infrastructure without production halts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slovakia Container Glass Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Pharmaceuticals, Personal Care, Cosmetics Size: Small, Medium, Large, Extra Large Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Vetropack Nemsova, Ardagh Group, Saint-Gobain, Owens-Illinois, Vitro, Verallia Packaging, Vidrala, Gerresheimer, BA Glass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slovakia Container Glass Market Trends and Innovations
Container glass manufacturing in Slovakia is undergoing simultaneous pressure from decarbonization mandates and premiumization demands, forcing technology choices that balance regulatory compliance against product performance specifications.
Electrified melting technology is fragmenting the traditional furnace supplier landscape. Regional beverage bottlers pilot all-electric and hybrid furnace configurations for specialty color runs. This fragmentation compresses equipment procurement cycles and diversifies vendor relationships beyond established combustion-system providers.
The EU F-Gas Regulation tightens emissions thresholds for industrial processes using fluorinated gases. Glass producers face accelerated capital deployment for abatement systems or process redesign. Slovak facilities in the Bratislava-Trnava corridor prioritize oxy-fuel conversions to maintain operating permits.
Brand owners now specify post-consumer recycled content minimums in supply agreements. Cosmetic exporters and premium spirits marketers lead this specification shift. Košice-based distilleries and Bratislava cosmetic formulators drive visible demand for certified high-cullet glass packaging.
Slovakia Container Glass Market Segmentation
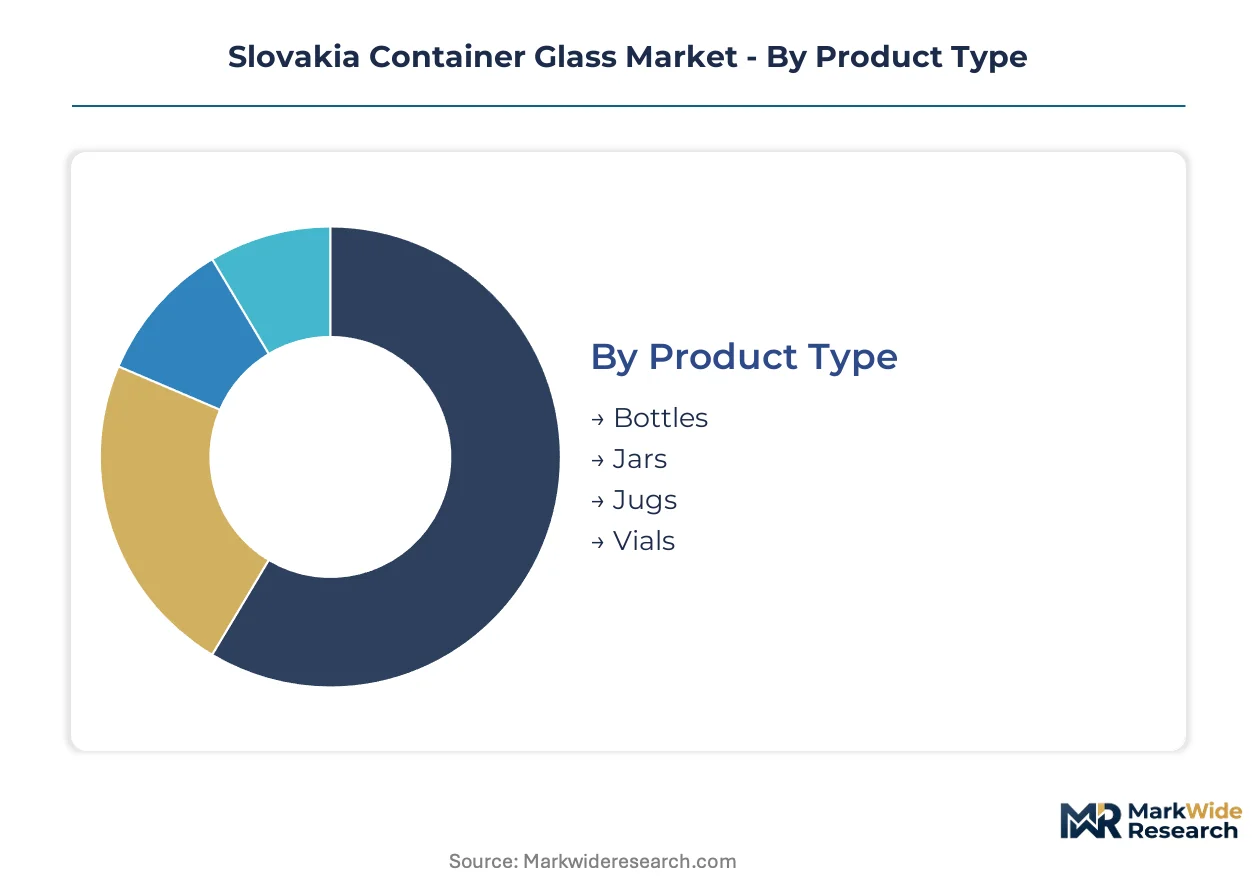
Slovakia's container glass market segments reflect divergent supply chain pressures. Premium beverage bottlers in Bratislava-Trnava drive specification intensity for clarity grades, while pharmaceutical certification demands reshape margin structures. Understanding segment boundaries clarifies where electrification investments concentrate and which channels absorb recycled content mandates.
Product Type:
Domestic demand concentrates in beverage-serving formats, while export-oriented pharmaceutical containment drives specialized capacity expansion.
- Bottles:Soda-lime silica vessels formed through blow-and-blow or press-and-blow processes, engineered for 70-74% silicon dioxide content. Bratislava craft distilleries and Košice spirits producers intensify procurement of amber and flint clarity grades, with Vetropack Nemsova securing just-in-time supply contracts across the western industrial corridor.
- Jars:Wide-mouth containers with thicker wall sections for food preservation and condiment storage. Slovak food processors in Trnava region specify heavier glass weights for premium positioning, though aluminum substitution pressures mass-market segments.
- Jugs:Large-format vessels for bulk beverage and industrial chemical containment. Limited domestic production capacity forces reliance on cross-border sourcing from Czech and Austrian furnace networks.
- Vials:Small-diameter pharmaceutical containers requiring dimensional tolerances within fractions of a millimeter. Sterile drug certification creates margin pools above standard bottle production, with Bratislava pharmaceutical exporters driving specification intensity.
Bottles command the established base. The steepest expansion runs through vials.
End User:
Cost tier differentiation separates premium specification buyers from price-sensitive mass-market procurement.
- Food & Beverage:Dominant volume position sustained by brewery and distillery packaging clusters across Bratislava-Trnava corridor. EU Green Deal cullet mandates reshape supply agreements, with brand owners specifying post-consumer recycled content minimums.
- Pharmaceuticals:Dimensional tolerance requirements and sterile containment certifications create superior margin pools. Slovak facilities prioritize oxy-fuel conversions to maintain operating permits under EU F-Gas Regulation thresholds.
- Personal Care:Bratislava cosmetic formulators drive visible demand for certified high-cullet glass packaging as branded export positioning intensifies.
- Cosmetics:Košice-based distilleries and premium skincare marketers lead specification shifts toward specialized coating technologies that extend shelf-life performance.
Food & Beverage anchors volume procurement. Pharmaceuticals deliver the steepest margin expansion trajectory.
Size:
Volume concentration patterns align with transportation economics and filling line automation investments.
- Small:Pharmaceutical vials and premium spirits miniatures. Dimensional precision requirements concentrate production in specialized furnace segments.
- Medium:Standard wine and spirits bottles dominating Bratislava bottling cluster procurement. Just-in-time delivery contracts compress inventory holding costs.
- Large:Food service and institutional beverage containers. Transport cost minimization pressures shift some demand toward lighter-weight formats.
- Extra Large:Limited domestic application; industrial chemical and bulk food storage relies primarily on imported capacity.
Medium sizes command the established base. Small formats gain share fastest through pharmaceutical certification demands.
Distribution Channel:
Customer type fragmentation separates direct procurement relationships from intermediated supply arrangements.
- Online:Emerging channel for standardized bottle specifications and small-batch cosmetic packaging. Limited penetration in furnace-direct procurement.
- Retail:End-user direct purchasing for replacement and specialty applications. Marginal share in industrial volume procurement.
- Wholesalers:Inventory consolidation for mid-size beverage bottlers lacking direct furnace contracts. Geographic coverage concentrates in western Slovakia.
- Distributors:Dominant channel for pharmaceutical and personal care segments, with certified handling protocols and batch traceability requirements.
Distributors command the established base. Direct digital procurement shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slovakia exports container glass through the Bratislava-Vienna corridor into Austrian and German beverage markets, while importing specialized pharmaceutical vials from Czech and German suppliers.
Bratislava Region
Western Slovakia's industrial corridor anchors domestic furnace capacity, with craft distilleries and premium spirits producers intensifying procurement of amber and flint clarity grades. EU Green Deal emissions thresholds enforced by the national environmental regulator accelerate oxy-fuel conversions across Trnava-area facilities. Vetropack Nemsova leverages its Nemšová furnace network to secure just-in-time supply contracts with regional bottlers.
Košice Region
Eastern Slovakia's underdeveloped glass packaging infrastructure contrasts with beverage production growth in Košice and Prešov. F-Gas Regulation compliance drives furnace technology upgrades that reduce fluorinated gas emissions from melting operations. Distilleries in this eastern cluster increasingly source from western Slovak furnaces or cross-border Czech suppliers.
Trnava Industrial Zone
Food processors in this western district specify heavier glass weights for premium jar positioning, though aluminum substitution pressures mass-market segments. REACH compliance governs chemical substance registration across batch operations. The Trnava bottling cluster sustains the broadest demand base for medium-format beverage containers.
Central Slovakia
Geographic vulnerability emerges as western furnace concentration leaves central regions dependent on distant supply chains. CE marking requirements for product safety conformity shape procurement specifications. Limited domestic production capacity for large-format jugs forces reliance on Austrian and Czech cross-border sourcing.
Slovakia Container Glass Market Competitive Landscape
Listed leaders compete with private specialists across furnace technology and color consistency capabilities. The vendor base concentrates around three major furnace operators with established western Slovak footprints, supplemented by specialized coating technology providers. Strategic archetypes include integrated furnace operators with captive batch houses, technology licensors with proprietary coating systems, and regional distributors with certified handling protocols. Competitive moves center on oxy-fuel furnace conversions and post-consumer cullet integration mandates.
Among integrated furnace operators, Vetropack Nemsova and Ardagh Group exemplify the scale-driven archetype with established Nemšová and regional furnace networks. Saint-Gobain occupies a position within the technology-differentiated tier, representing specialists in coating systems that extend shelf-life performance for sensitive formulations. These three companies anchor the competitive structure through distinct capability vectors rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Vetropack Nemsova |
| Ardagh Group |
| Saint-Gobain |
| Owens-Illinois |
| Vitro |
| Verallia Packaging |
| Vidrala |
| Gerresheimer |
| BA Glass |
| Others |
Pricing and Supply Chain Analysis
Fourteen-day furnace batch cycles compress inventory buffers across the Bratislava-Trnava corridor, amplifying pricing power for Vetropack Nemsova and Ardagh Group while forcing smaller bottlers into premium spot-market sourcing. This lead-time rigidity concentrates procurement leverage with integrated furnace operators who control both melt capacity and cullet preprocessing.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Slovakia's container glass sector. Pricing stratifies across premium flint clarity, standard amber, and economy green glass tiers, with quality grade and volume scale as the primary differentiation drivers. Cost compression in economy tiers is intensifying because aluminum substitution pressures mass-market beverage segments. Mass-market bottlers exhibit highest price sensitivity, while pharmaceutical exporters demonstrate lowest sensitivity due to sterile certification requirements.
Supply Chain Analysis
Soda ash rail deliveries from Germany and the Czech Republic constitute the critical raw material chokepoint for Slovak furnace operations. Domestic production draws from German soda ash, Italian dolomite, and local sand deposits from the Podunajská nížina basin. Single-source vulnerability persists in specialty coating chemicals sourced from German suppliers. Distribution runs through direct furnace contracts for large beverage clusters and wholesaler intermediation for mid-size processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container glass in Slovakia functions as a service-attach opportunity where coating technology subscriptions and cullet logistics management expand faster than base melt tonnage. Recurring revenue from shelf-life extension coatings and closed-loop recycling programs outpaces hardware growth across the analysis window.
For Market Incumbents: Secure renewable energy contracting positions ahead of EU ETS price escalations, locking in power purchase agreements with Slovak wind and solar developers. Backward integration into cullet preprocessing capacity defends margin structures against raw material volatility. Electrified furnace expertise scarcity threatens operational continuity; capture specialized electrical engineering talent through vocational partnerships before competitors exhaust the regional pipeline. For New Entrants and Emerging Players: Anchor in Košice and Prešov regions where beverage production growth outpaces local glass packaging infrastructure. Pharmaceutical vial certification represents the most penetrable high-margin segment, with dimensional tolerance requirements creating barrier-protected margin pools. Lead with specialized coating technology partnerships that extend shelf-life performance for sensitive cosmetic formulations. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because EU Green Deal compliance mandates and F-Gas Regulation thresholds permanently restructure furnace economics toward electrified assets. Target acquisition archetypes include mid-scale coating technology specialists with pharmaceutical certification pathways and oxy-fuel conversion capabilities. Watch EU ETS carbon price trajectories as the inflection signal for accelerated asset replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Conversion | EU F-Gas Regulation compliance secures operating permits across Bratislava-Trnava facilities. |
| Post-Consumer Cullet Integration | Brand owner mandates from Košice distilleries reshape raw material sourcing economics. |
| Electrified Melting Pilot Programs | Renewable energy contracting enables cost-competitive batch operations under tightening carbon pricing. |
| Pharmaceutical Vial Certification | Sterile containment specifications create margin pools above standard beverage bottle production. |
| Specialized Coating Technology Partnership | Shelf-life extension capabilities differentiate Saint-Gobain positioning for cosmetic exporters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with furnace operations managers, beverage procurement directors, pharmaceutical packaging specialists, and national environmental regulator officials. Secondary validation drew from EU ETS auction data, REACH substance registration databases, Slovak customs trade statistics, and CE marking conformity records. Bottom-up capacity modeling and top-down demand estimation were triangulated against actual production volumes reported across the Nemšová furnace network.
Across the analysis window, volume and value outputs were generated through segmented modeling by product type, end-user industry, glass clarity grade, and regional production cluster. CAGRs were derived from melt tonnage trajectories and price-per-ton movements across premium and standard tiers. Forecast inputs incorporated EU Green Deal implementation timelines, F-Gas Regulation phase-down schedules, and renewable energy penetration rates within Slovak industrial power contracts.
Material uncertainties — natural gas price volatility, aluminum substitution acceleration, and electrical engineering talent availability — sit outside the modeled envelope. Forecasts reflect documented assumptions about furnace electrification adoption curves and cullet supply chain maturation. Practitioners should keep alternative scenarios live as EU ETS carbon pricing trajectories and renewable energy auction results evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Austria Container Glass Market
Glass Packaging
Bulgaria Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
Canada Glass Bottles and Containers Market