
 Hungary Container Glass Market | 2026-2036
Hungary Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Hungary Container Glass Market Insights
Food and beverage bottlers is rotating toward pharmaceutical and personal care buyers as Hungary's cosmetics and OTC drug sectors expand their glass packaging specifications. O-I Hungary Kft leverages its large-scale furnace operations near Budapest to supply standardized bottles across Central European distribution networks. Észak Üvért Kft. anchors regional supply for specialty amber and cobalt glass vials used in pharmaceutical applications. Vetropack competes through its integrated recycling infrastructure, lowering cullet costs for premium-grade output.
Container glass comprises soda-lime-silica formulations formed through blow-and-blow or press-and-blow processes, typically achieving wall thicknesses of 2–5 mm for structural integrity and chemical inertness in liquid and semi-solid storage. The primary commercial purpose centers on preserving product shelf stability while enabling brand differentiation through color, shape, and label adhesion surface quality. Bottles and vials command the dominant volume position, though specialty-grade segments capture disproportionate margin pools due to pharmaceutical certification requirements and low batch minimums. Jars within the food end user channel sustain steady replacement demand, while recycled-grade output faces technical ceiling constraints from color-sorting purity thresholds.
Hungary's container glass sector operates under EU REACH chemical registration rules, the EU Green Deal circular economy packaging requirements, and national BIS-aligned quality benchmarks for food-contact materials. These frameworks elevate compliance costs for imported cullet and mandate recycled-content thresholds that reshape raw material procurement patterns. Stakeholders must monitor forthcoming EU packaging regulation revisions that will tighten extended producer responsibility obligations and alter investment timing for furnace modernization decisions.
Market Dynamics
Hungary's container glass sector faces structural pressure from EU Green Deal circular economy mandates tightening recycled-content thresholds and traceability rules, forcing furnace operators to reconfigure raw material procurement and cullet sourcing strategies.
Growth Catalysts
- EU Green Deal packaging requirements:Mandatory recycled-content floors for food-contact glass are pulling investment toward cullet beneficiation infrastructure and closed-loop collection systems.
- Pharmaceutical packaging specifications:Budapest-based OTC drug manufacturers and cosmetics formulators are expanding amber and cobalt glass vial orders for light-sensitive formulations.
- Northwestern industrial corridor concentration:Győr-Mosonmagyaróvár logistics connectivity enables just-in-time bottle supply to Austrian and Slovak beverage bottlers.
Market Restraints
- Natural gas cost volatility:Float-glass furnace operations depend on pipeline gas pricing indexed to TTF benchmarks, compressing margin visibility during heating season spikes.
- Cullet import purity ceilings:Color-sorting technology limits achievable recycled-content ratios for flint glass, capping cost reduction potential.
- Aluminum can substitution:Premium beer and sparkling water brands are testing lightweight metal formats for logistics efficiency.
Strategic Opportunities
- Transdanubian regional expansion:Pécs and Szeged pharmaceutical clusters lack proximate specialty glass supply, creating white space for certified vial production.
- EU F-Gas Regulation alignment:Leak detection and refrigerant containment mandates are driving demand for borosilicate glass components in cooling equipment.
- Digital printing convergence:Direct-to-glass inkjet decoration enables batch-size-one customization for craft spirits and limited-edition cosmetics.
Industry Challenges
- Refractory engineering talent scarcity:Furnace rebuild cycles require specialized ceramic expertise concentrated among retiring Central European workforces.
- REACH compliance documentation:Chemical substance registration for imported colorants and surface treatments extends new product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hungary Container Glass Market |
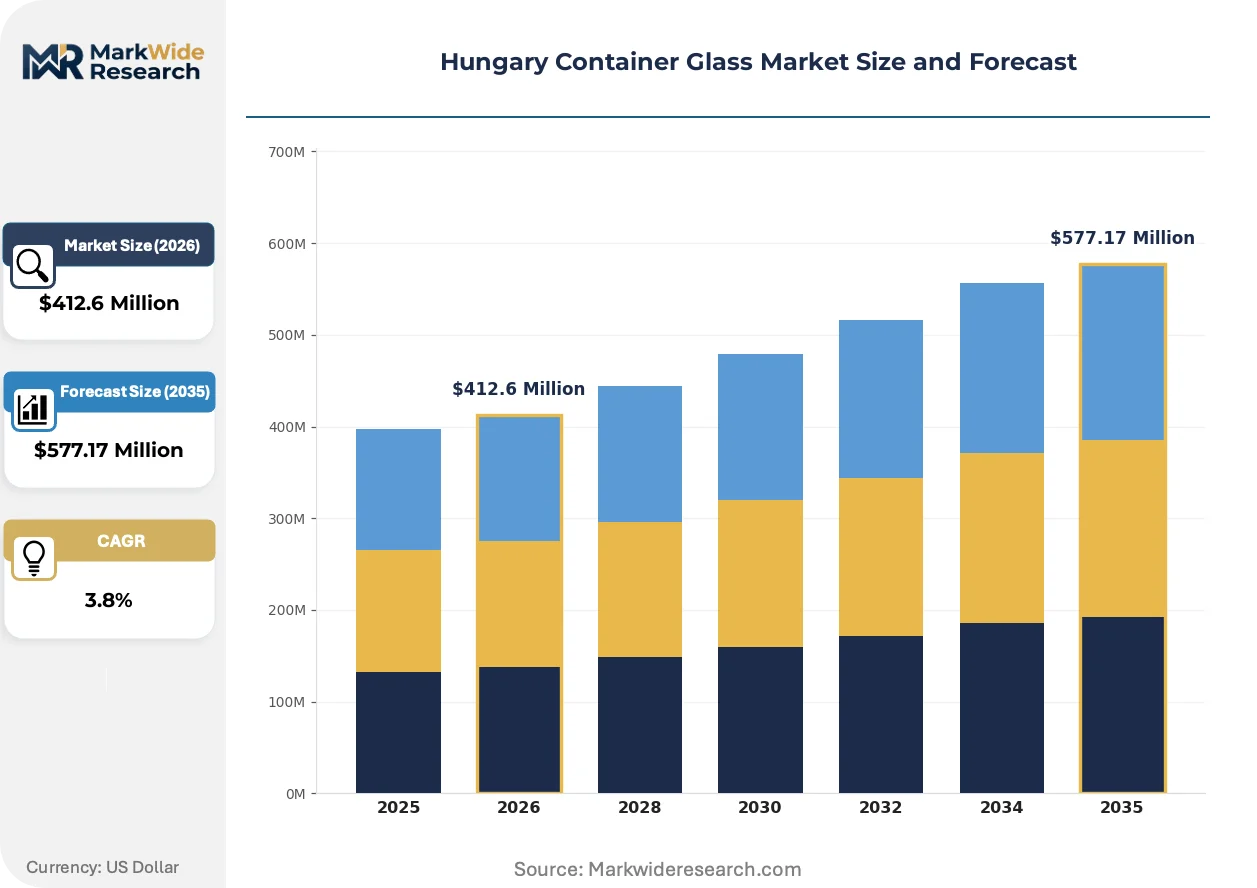
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $577.17 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Packaging Type: Rigid, Flexible, Stackable, Reusable Grade: Standard, Premium, Recycled, Specialty |
| Companies Covered | O-I Hungary Kft, Észak Üvért Kft., PLASTRADE Packaging Ltd., Feemio Group Co., Ltd., Şişecam, Gönci Üveggyártó Kft, Salamon Üveg Kft., Vetropack, Verallia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hungary Container Glass Market Trends and Innovations
Electrification of melting technology and digital supply chain traceability are compressing the traditional furnace economics and quality assurance models that have defined Hungarian glass manufacturing for decades.
Hybrid oxy-fuel furnace architecture is displacing conventional regenerative air-gas systems in Budapest-area plants. Beverage bottlers with carbon-neutral commitments are demanding verified low-emission glass, forcing furnace operators to accelerate oxygen-enriched combustion retrofits. The technology is displacing legacy cross-fired furnace designs that cannot meet tightening Scope 1 emission benchmarks under EU ETS phase-in schedules.
EU Green Deal extended producer responsibility revisions are mandating digital waste tracking and harmonized recycling targets across member states. Hungarian packagers must integrate national waste management data systems with EU-wide packaging registry requirements by the implementation deadlines. Pharmaceutical glass converters face the steepest compliance burden due to multi-layer label adhesives complicating cullet purity.
Consolidated procurement by Central European beverage distributors is compressing supplier lists and extending contract durations. Major retail chains now require single-source glass supply with volume guarantees spanning three-to-five-year horizons. The shift is most visible in Budapest, where multinational bottlers are reducing their approved vendor pools from six to two container glass suppliers.
Hungary Container Glass Market Segmentation
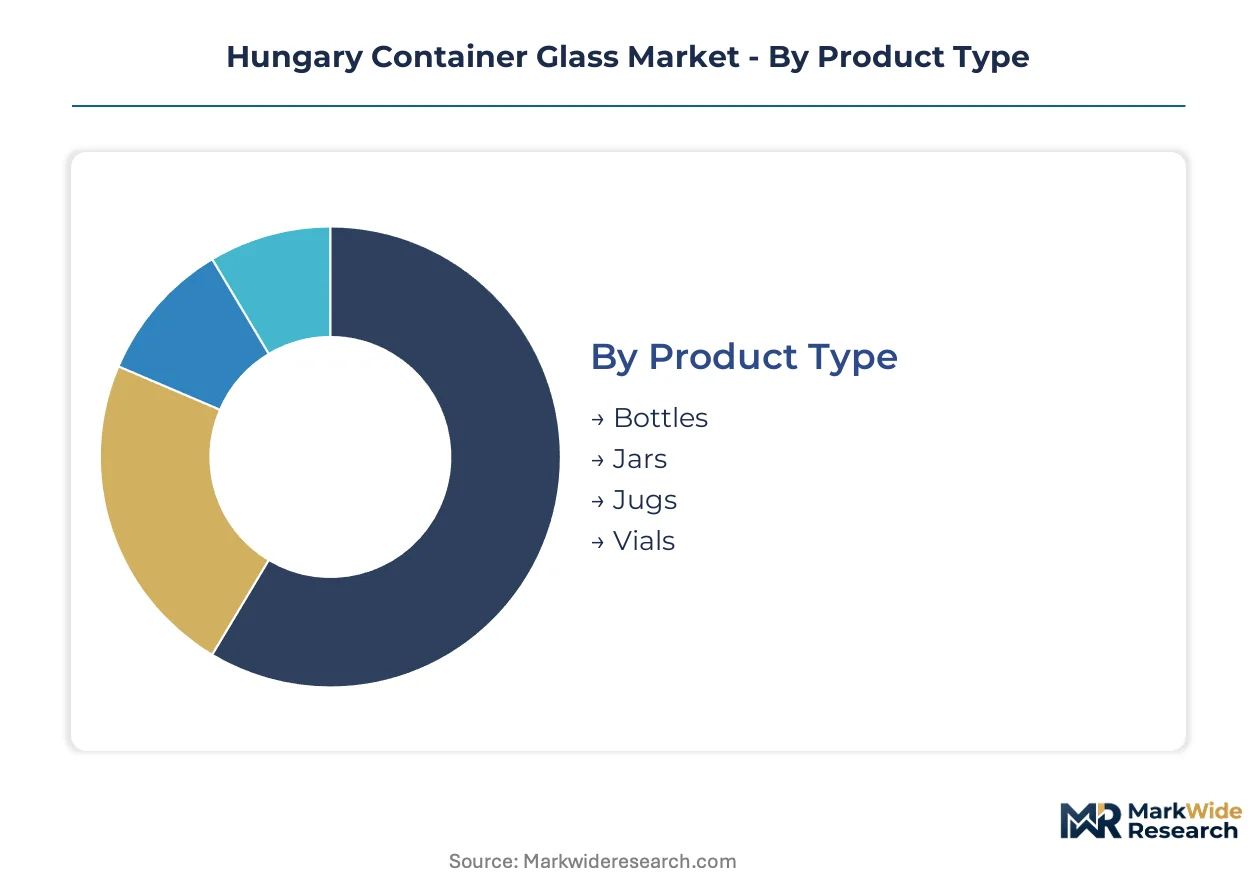
Hungary's container glass market segments reflect divergent compliance burdens and margin structures. Pharmaceutical-grade and food-contact specifications operate under distinct regulatory regimes that reshape procurement patterns across each category.
Product Type:
REACH registration requirements and EU food-contact material rules create divergent qualification timelines across container formats.
- Bottles:Soda-lime-silica formulations with 2–5 mm wall thickness dominate beverage and pharmaceutical liquid storage. Budapest-based bottlers and Győr-Mosonmagyaróvár logistics corridors absorb the majority of standardized output for Central European distribution networks.
- Vials:Amber and cobalt glass variants achieve chemical inertness for light-sensitive pharmaceutical formulations. Észak Üvért Kft. anchors regional supply as OTC drug manufacturers in Budapest expand their glass packaging specifications.
- Jars:Wide-mouth configurations serve food preservation and cosmetic cream applications with steady replacement demand cycles.
- Jugs:High-capacity formats for bulk beverage and household chemical storage face aluminum packaging substitution pressure.
Bottles handle the majority of throughput; vials are gaining share fastest on pharmaceutical sector expansion.
End User:
Customer procurement scale and certification requirements stratify pricing and contract structures across demand channels.
- Food & Beverage:Volume concentration among multinational bottlers drives consolidated supplier lists and extended contract durations. Major retail chains now mandate single-source glass supply with three-to-five-year volume guarantees.
- Pharmaceuticals:Amber glass vial demand climbs as Budapest-based OTC drug manufacturers expand production. EU MDR compliance and batch traceability requirements elevate entry barriers for non-certified converters.
- Personal Care:Cosmetics formulators in Budapest specify cobalt and flint glass for brand differentiation. Digital printing convergence enables batch-size-one customization for limited-edition product launches.
- Household Products:Standard-grade containers for cleaning chemicals and solvents compete with PET alternatives on cost.
Food & Beverage commands absolute volume; Pharmaceuticals shows the steepest expansion trajectory on regulatory-driven quality upgrades.
Packaging Type:
Logistics efficiency and EU Green Deal circular economy mandates reshape format preferences across the supply chain.
- Rigid:Structural integrity for carbonated beverages and pharmaceutical liquids remains non-negotiable. O-I Hungary Kft. leverages large-scale furnace operations to supply standardized rigid formats across Central European networks.
- Reusable:Returnable bottle systems align with extended producer responsibility revisions and closed-loop collection mandates. Deposit-return infrastructure investments concentrate in Budapest and northwestern industrial corridors.
- Stackable:Nesting geometries reduce transport cube and warehousing costs for food jar distribution.
- Flexible:Limited glass applicability; primarily refers to sleeve-labeled formats with decorative adaptability.
Rigid formats dominate absolute shipments; reusable configurations are climbing fastest on EPR regulation tightening.
Grade:
Raw material sourcing constraints and cullet purity thresholds create technical ceilings for recycled-content positioning.
- Standard:Soda-lime-silica formulations without specialized certification serve mass-market beverage and food applications. Natural gas cost volatility indexed to TTF benchmarks compresses margin visibility for furnace operators.
- Specialty:Borosilicate and pharmaceutical-certified grades command disproportionate margin pools. EU F-Gas Regulation alignment drives demand for borosilicate components in cooling equipment leak detection systems.
- Premium:Enhanced surface quality and decoration-ready finishes target craft spirits and luxury cosmetics segments.
- Recycled:Color-sorting technology limits achievable content ratios for flint glass, capping cost reduction potential. Vetropack competes through integrated recycling infrastructure lowering cullet costs for premium-grade output.
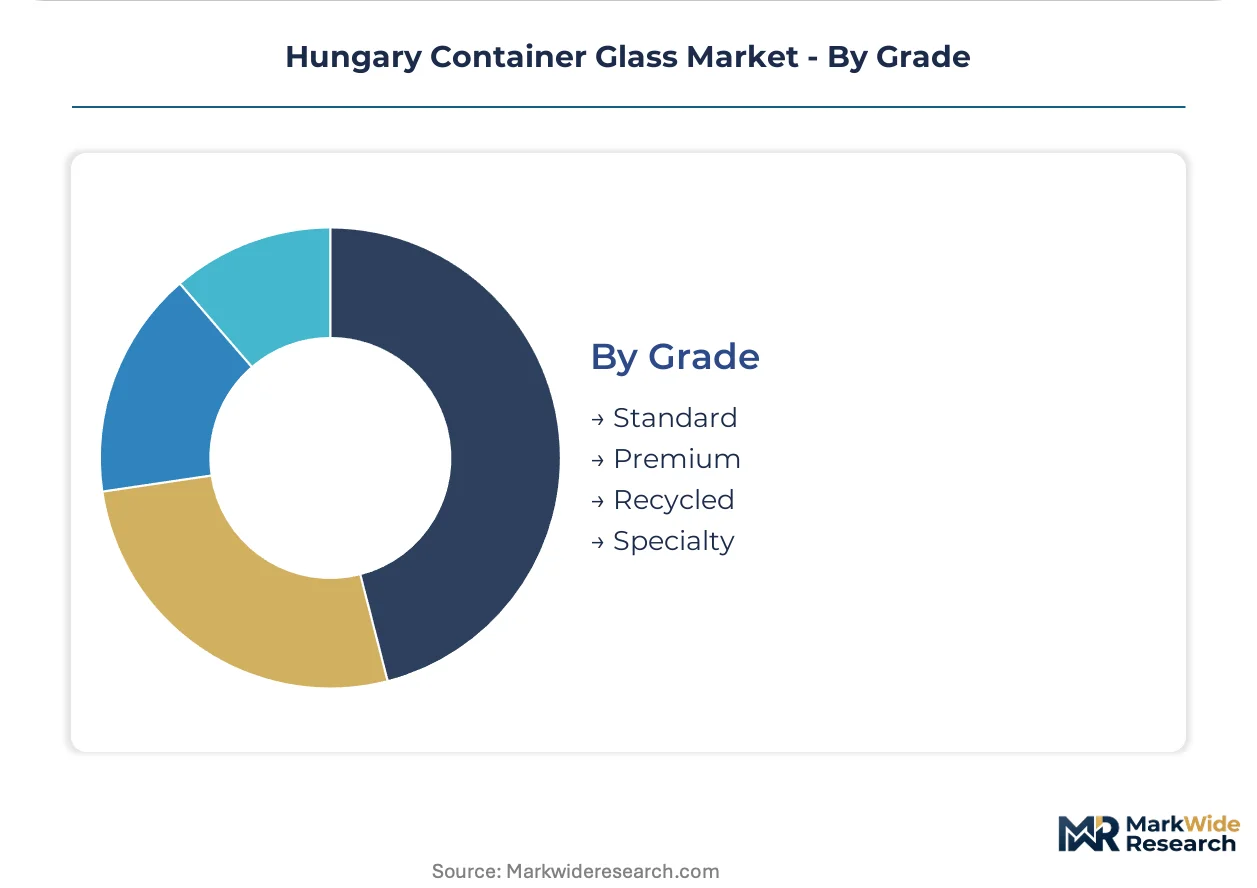
Standard grade moves the highest tonnage; specialty grade is expanding most quickly on pharmaceutical and technical application demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers and pharmaceutical manufacturers concentrate procurement decisions in Budapest and the northwestern industrial corridor, while regional supply networks extend into neighboring Central European markets.
Northwestern Industrial Corridor
Győr-Mosonmagyaróvár logistics connectivity enables just-in-time bottle supply to Austrian and Slovak beverage bottlers. EU Green Deal packaging requirements mandate recycled-content floors that pull investment toward cullet beneficiation infrastructure in this corridor. O-I Hungary Kft leverages large-scale furnace operations near Budapest to supply standardized bottles across Central European distribution networks.
Budapest Metropolitan Area
Cosmetics formulators and OTC drug manufacturers in Budapest specify cobalt and flint glass for brand differentiation and light-sensitive formulations. REACH compliance documentation for imported colorants extends new product qualification timelines for converters serving this cluster. Észak Üvért Kft. anchors regional supply for specialty amber and cobalt glass vials used in pharmaceutical applications.
Transdanubia
Pécs and Szeged pharmaceutical clusters lack proximate specialty glass supply, creating white space for certified vial production. National BIS-aligned quality benchmarks for food-contact materials elevate compliance costs for imported cullet. Vetropack competes through integrated recycling infrastructure, lowering cullet costs for premium-grade output serving this region.
Southern Great Plain
Food preservation and household chemical container demand sustains steady replacement cycles in Szeged-Kecskemét logistics zones. EU F-Gas Regulation alignment drives demand for borosilicate glass components in cooling equipment leak detection systems. Gönci Üveggyártó Kft and Salamon Üveg Kft. serve regional distribution networks with standardized jar and jug formats.
Central Transdanubia
Craft spirits producers and limited-edition cosmetics brands demand digital printing convergence for batch-size-one customization. Extended producer responsibility revisions mandate digital waste tracking that reshapes collection system investments. Feemio Group Co., Ltd. and PLASTRADE Packaging Ltd. position within specialty decoration and flexible packaging adjacencies.
Hungary Container Glass Market Competitive Landscape
Player mix skews toward integrated multinational furnace operators and specialized regional converters. Tiered competitive structure separates scale-driven standardized bottle suppliers from certified pharmaceutical-grade specialists. Strategic archetypes include: integrated recycling-cum-production operators leveraging cullet cost advantages; furnace-dependent volume players optimizing natural gas procurement; and decoration-specialist converters capturing premium cosmetic and craft spirit niches. Dominant competitive moves center on hybrid oxy-fuel furnace retrofits for emission compliance and extended producer responsibility infrastructure investments.
Among multinational furnace operators, O-I Hungary Kft and Vetropack occupy positions exemplifying scale-driven supply to Central European beverage networks. Észak Üvért Kft. represents the specialty pharmaceutical-grade archetype, anchoring regional capacity for certified amber and cobalt glass. Şişecam and Verallia sit within the integrated multinational tier, with geographic naming conventions suggesting Turkish and French origins respectively. Domestic Hungarian converters including Gönci Üveggyártó Kft and Salamon Üveg Kft. exemplify regional supply-focused structures serving food preservation and household chemical segments.
| Leading Market Players |
|---|
| O-I Hungary Kft |
| Észak Üvért Kft. |
| PLASTRADE Packaging Ltd. |
| Feemio Group Co., Ltd. |
| Şişecam |
| Gönci Üveggyártó Kft |
| Salamon Üveg Kft. |
| Vetropack |
| Verallia |
| Others |
Pricing and Supply Chain Analysis
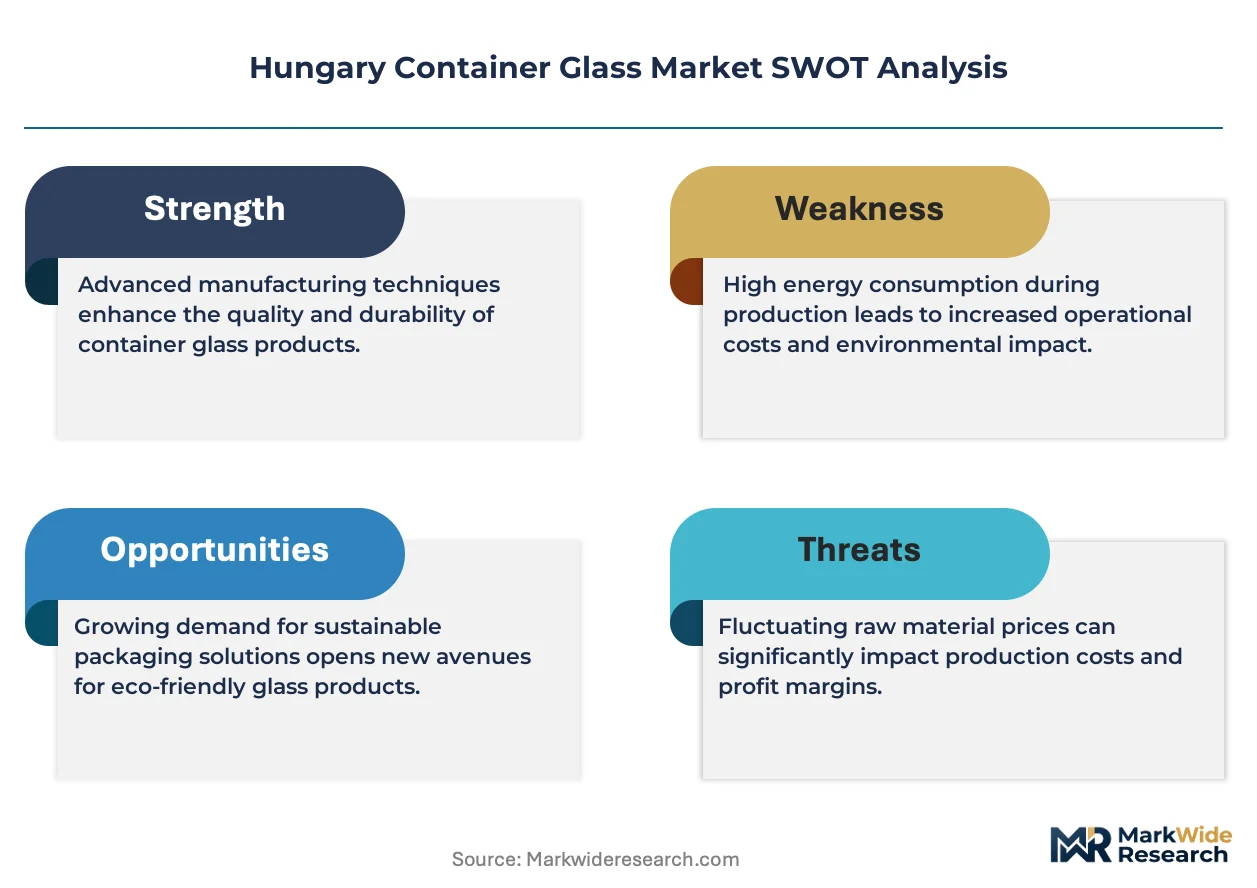
Large-scale furnace utilization rates near Budapest establish price floors that smaller regional converters cannot match, concentrating supply-side bargaining power among integrated operators while compressing margins for batch-specialty producers serving pharmaceutical niches. This scale asymmetry reinforces contract structures indexed to energy and cullet inputs, locking in divergent margin trajectories across the Hungarian container glass sector.
Pricing Analysis
Cost-plus contracts with TTF-indexed natural gas pass-through dominate beverage supply agreements, insulating O-I Hungary Kft from heating season volatility while exposing smaller operators to margin compression. Price differentiation hinges on pharmaceutical certification tier and volume scale, with amber glass vials commanding substantial premiums over standard flint bottles. Cost compression in standard-grade segments is intensifying because aluminum can substitution trials by premium beer brands are forcing glass suppliers to absorb logistics efficiency gaps. Food and beverage bottlers exhibit the highest price sensitivity due to consolidated procurement and extended contract durations, while pharmaceutical buyers prioritize batch traceability over unit cost.
Supply Chain Analysis
Inventory cycles stretch 6-8 weeks for imported colorants and surface treatments, extending new product qualification timelines for REACH-compliant converters. Raw material sourcing draws from German soda ash suppliers, Italian dolomite processors, and domestic cullet collection networks concentrated around Győr-Mosonmagyaróvár. Single-source vulnerability permeates specialty cobalt and amber glass colorant supply, where limited qualified European vendors constrain formulation flexibility. Distribution runs through Budapest-hubbed logistics corridors serving Austrian and Slovak bottlers, with just-in-time delivery mandates compressing safety stock buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hungarian container glass sector sits at a platform-economics inflection where EU Green Deal digital waste tracking mandates are forcing interoperability investments between packagers, waste managers, and national registry systems. This ecosystem shift rewards operators who capture data infrastructure positions early.
For Market Incumbents: Consolidate furnace capacity around hybrid oxy-fuel retrofits to defend margin position against EU ETS phase-in schedules, while acquiring cullet beneficiation assets to lock in recycled-content compliance ahead of threshold tightening. Aluminum can substitution in premium sparkling water and craft beer segments demands counter-positioning through verified low-emission glass certification.
For New Entrants and Emerging Players: Differentiate on pharmaceutical-grade vial production certified to EU MDR batch traceability standards, targeting the white space in Pécs and Szeged pharmaceutical clusters lacking proximate specialty glass supply. A go-to-market angle anchored in digital printing convergence for batch-size-one cosmetics customization bypasses scale disadvantages against Budapest-area furnace operators.
For Investors and Strategic Acquirers: Specialty pharmaceutical-grade converters with captive amber and cobalt glass formulations represent the most defensible acquisition archetype, given regulatory moats and expanding OTC drug packaging specifications. Long-term viability over the next decade rests on furnace electrification technology maturation and EU packaging regulation enforcement intensity. The signal to watch is hybrid oxy-fuel retrofit announcement velocity among Central European competitors, indicating competitive positioning for Scope 1 emission benchmarks.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Oxy-Fuel Furnace Retrofit | Enables EU ETS compliance and supplies carbon-neutral glass to beverage bottlers with net-zero commitments. |
| Cullet Beneficiation Infrastructure Investment | Secures recycled-content thresholds under EU Green Deal packaging mandates while lowering raw material costs. |
| Pharmaceutical Vial Certification Expansion | Captures margin pools from Budapest-based OTC drug manufacturers expanding amber glass specifications. |
| Digital Printing Convergence | Enables batch-size-one customization for craft spirits and limited-edition cosmetics in Central Transdanubia. |
| Extended Producer Responsibility Data Integration | Positions operators ahead of EU packaging registry interoperability requirements and digital waste tracking mandates. |
Research Methodology
Initial hypotheses were tested against primary input from furnace operations managers, pharmaceutical packaging procurement leads, beverage bottler supply chain directors, and waste management system operators, then refined through secondary validation against ECHA REACH registration databases, EU Green Deal implementation documents, Hungarian customs trade statistics, and SEC filings of listed glass manufacturers. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from end-use sector consumption patterns.
Variance decomposition across product type, end user channel, grade tier, and regional production cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and capacity expansion announcements. Key forecast inputs included natural gas price trajectory assumptions indexed to TTF benchmarks and pharmaceutical sector packaging specification expansion rates.
Forecasts assume regulatory continuity in EU REACH, EU Green Deal circular economy packaging requirements, and national BIS-aligned food-contact material standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
India Container Glass Market