
 UAE Container Glass Market | 2026-2036
UAE Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Container Glass Market Analytics
Plastic is restructuring container glass economics across the UAE as FMCG brands abandon polyethylene terephthalate for returnable and refillable glass formats in premium beverage lines. Al Tajir Glass Industries leverages its furnace capacity in Ras Al Khaimah to anchor supply for regional dairy and juice bottlers. O-I Jebel Ali competes through ISO-certified pharmaceutical amber glass output serving CDSCO-aligned export markets. RAK Ghani Glass LLC specializes in lightweight container engineering that reduces per-unit silica consumption without sacrificing burst strength.
Container glass denotes soda-lime-silica or borosilicate articles formed by blow-and-blow or press-and-blow methods, annealed to relieve thermal stress, then coated with tin or polyethylene for abrasion resistance during filling and transit. Its primary purpose remains hermetic containment of consumables against oxidation, UV degradation, and microbial ingress. Bottles dominate volume throughput across UAE forming halls, though vials command superior margin pools given pharmaceutical validation requirements and smaller batch sizes. Jars sustain steady demand from date paste and honey packers in Al Ain and Fujairah, while custom-scale capacity attracts European cosmetic houses seeking regional contract manufacturing.
MOHAP enforces pharmacopeial glass standards for all injectable and ophthalmic packaging distributed within the Emirates, effectively filtering out uncertified import sources. The UAE's alignment with Gulf Standardization Organization container integrity rules further tightens dimensional tolerance and thermal-shock thresholds for food-contact glass. Emirates Authority for Standardization and Metrology (ESMA) energy-efficiency codes now govern furnace rebuilds, pushing producers toward oxy-fuel combustion or electric melting retrofits. Stakeholders must weigh capital intensity against regulatory trajectory when committing to multi-decade furnace investments.
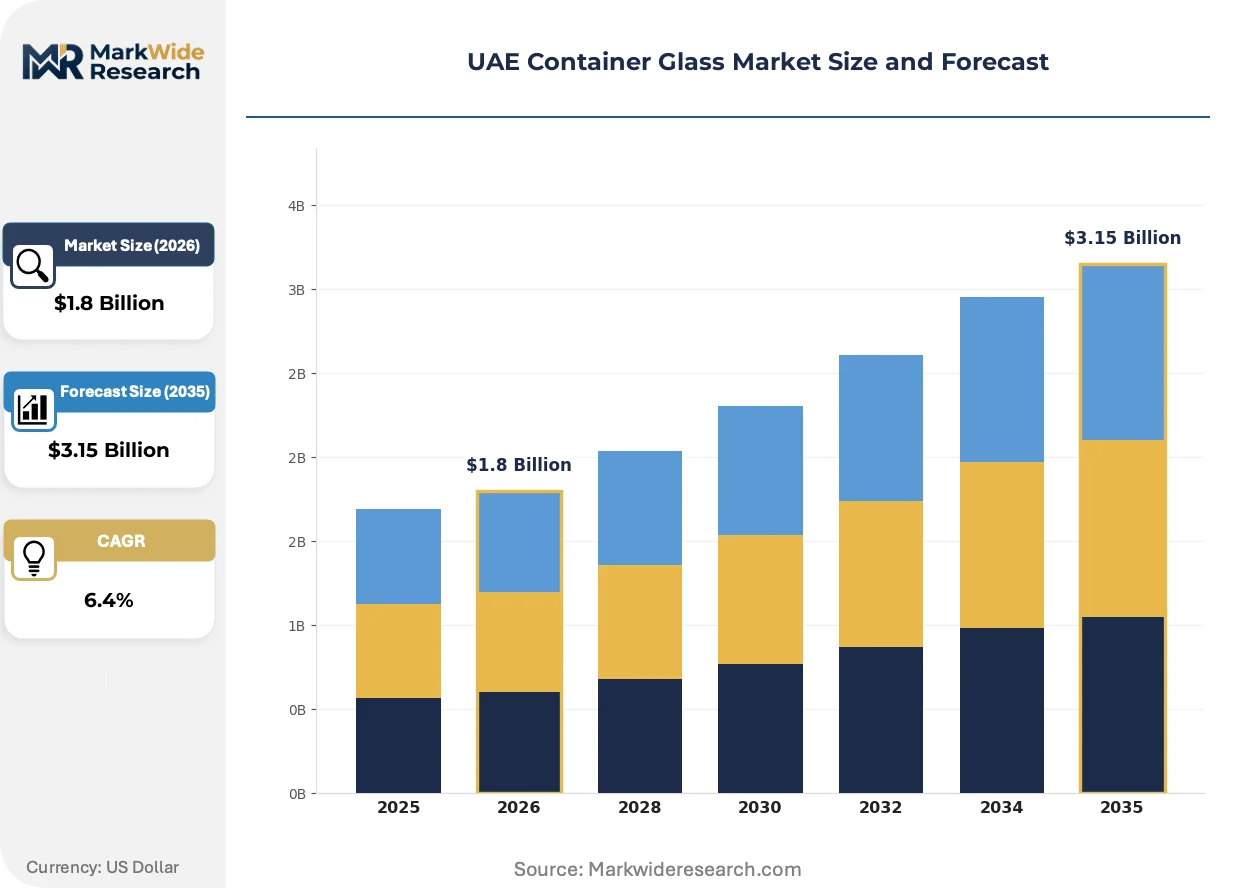
Market Dynamics
MOHAP's pharmacopeial glass mandate for injectables is compressing import competition and forcing domestic furnace upgrades across the Emirates, while premium cosmetic brands accelerate the shift from polyethylene terephthalate to refillable glass formats.
Growth Catalysts
- MOHAP Borosilicate Mandate:The pharmaceutical regulator now requires borosilicate-grade glass for all injectable and ophthalmic packaging distributed within the Emirates, eliminating uncertified import sources and anchoring domestic vial demand.
- Cosmetic Packaging Pivot:Premium beauty houses operating Dubai and Abu Dhabi retail corridors are abandoning plastic for returnable glass formats, creating sustained pull for lightweight container engineering.
- GCC Generics Manufacturing:The Gulf Cooperation Council's expanding pharmaceutical production base concentrates demand for validated vial supply within UAE forming halls serving regional drugmakers.
Market Restraints
- Silica and Soda Ash Volatility:Raw material input costs for container glass production fluctuate with global mineral supply chains, compressing margin pools for furnace operators without long-term offtake agreements.
- Furnace Rebuild Capital Intensity:ESMA energy-efficiency codes governing rebuilds demand oxy-fuel combustion or electric melting retrofits, requiring multi-decade capital commitments against uncertain regulatory trajectories.
- Plastic Substitution Persistence:Polyethylene terephthalate retains cost advantage in mass-market beverage lines, limiting glass penetration outside premium dairy and juice segments.
Strategic Opportunities
- European Contract Manufacturing:Custom-scale UAE capacity attracts cosmetic houses seeking regional production hubs, bypassing freight costs and import duties for Middle East distribution.
- Lightweight Engineering Premiumization:Reduced per-unit silica consumption without burst strength sacrifice commands pricing power among sustainability-focused brand owners.
- CDSCO-Aligned Export Markets:ISO-certified pharmaceutical amber glass output qualifies for Indian regulatory alignment, opening adjacent demand from South Asian generics manufacturers.
Industry Challenges
- Skilled Furnace Technician Scarcity:Oxy-fuel and electric melting retrofits require specialized operational expertise that remains concentrated among legacy European and North American engineering pools.
- Validation Timeline Compression:Pharmaceutical vial qualification protocols demand extended batch testing and stability studies, slowing capacity monetization for new furnace investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Container Glass Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Manufacturing Stage: Forming, Annealing, Coating, Finishing Capacity: Small Scale, Medium Scale, Large Scale, Custom Scale |
| Companies Covered | Al Tajir Glass Industries, Al Wara Group, RAK Ghani Glass LLC, Frigoglass Jebel Ali FZE, Emirates Glass LLC, Saverglass LLC, Hotpack Packaging Industries LLC, O-I Jebel Ali, Global Packaging FZC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Container Glass Market Evolving Landscape
Container glass production across the Emirates is undergoing simultaneous transformation on three fronts: furnace technology convergence, regulatory stringency escalation, and buyer procurement model evolution toward certified single-source relationships.
Lightweighting technology is unifying silica reduction targets with burst strength retention requirements across UAE forming halls. RAK Ghani Glass LLC and comparable specialists deploy computational modeling to thin wall sections without compromising thermal-shock thresholds. Premium cosmetic and pharmaceutical buyers now specify sub-gram weight reductions as standard tender requirements, compressing competitive differentiation around material efficiency rather than base capacity alone.
ESMA energy-efficiency codes are accelerating furnace rebuild decisions toward oxy-fuel combustion or electric melting architectures. The regulatory framework eliminates conventional regenerative furnace options for new investments, forcing capital allocation toward lower-carbon melting technologies. Al Tajir Glass Industries and O-I Jebel Ali must weigh higher upfront rebuild costs against multi-decade operational compliance and carbon pricing exposure.
Single-source certified supply agreements are displacing multi-vendor procurement patterns among pharmaceutical and cosmetic brand owners. Buyers now consolidate volume with ISO-certified domestic producers capable of MOHAP-aligned validation documentation, reducing supplier management overhead. This concentration is most visible among Dubai-based European cosmetic houses and Abu Dhabi pharmaceutical packers serving GCC export markets.
UAE Container Glass Market Segmentation
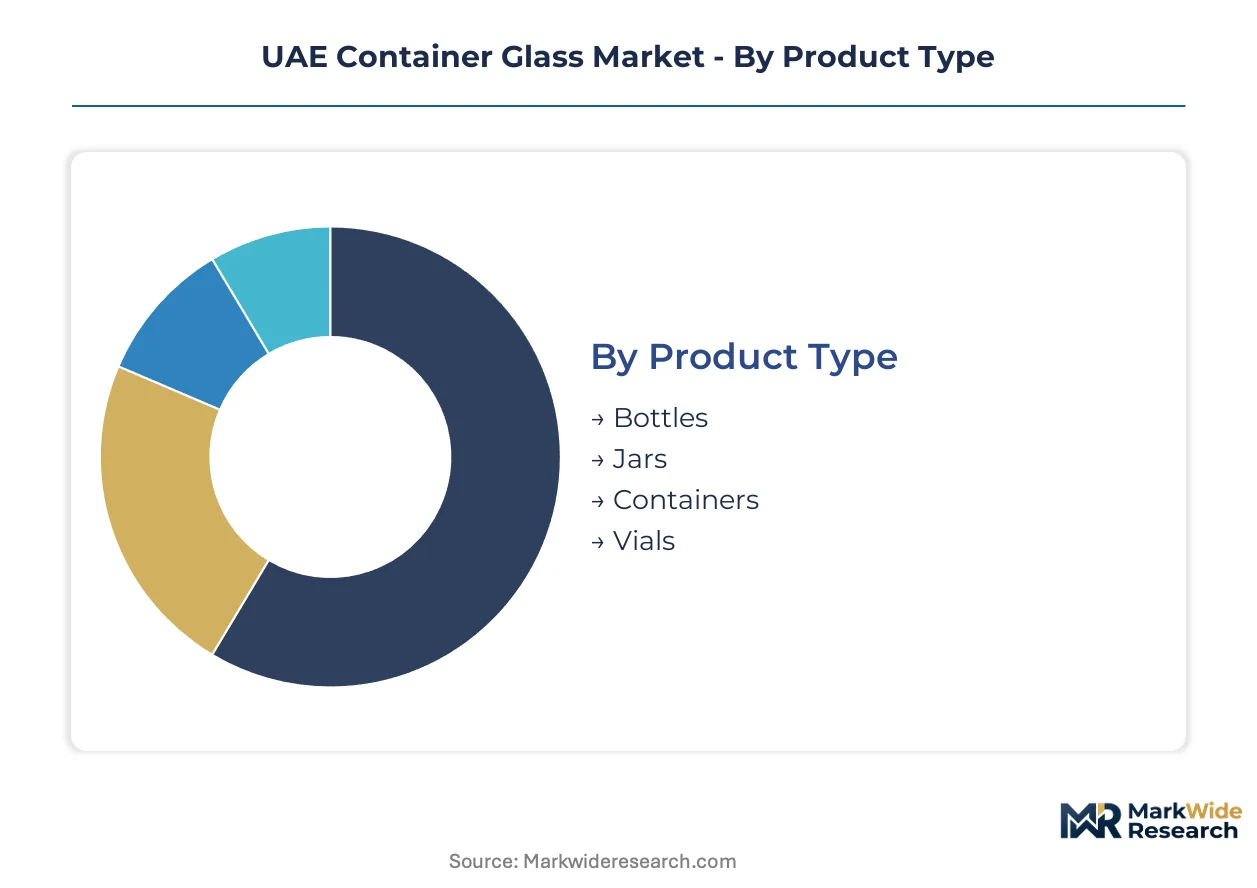
Segmentation in the UAE container glass market reveals how regulatory mandates and buyer procurement models reshape competitive positioning across product tiers. Distinct manufacturing capabilities and validation requirements separate premium pharmaceutical vial supply from commodity beverage bottling.
Product Type:
Buyers differentiate by containment performance needs — hermetic sealing, UV protection, and thermal shock tolerance — rather than price alone.
- Vials:Borosilicate-grade articles formed by precision blow-and-blow methods, annealed for thermal stress relief, then coated for pharmaceutical-grade surface integrity. Demand concentrates in Abu Dhabi pharmaceutical corridors serving MOHAP-mandated injectable packaging, where validation documentation and smaller batch sizes command superior margin pools.
- Bottles:Soda-lime-silica containers dominating volume throughput across UAE forming halls, engineered for hermetic containment against oxidation and microbial ingress. Dubai and Ras Al Khaimah dairy and juice bottlers anchor demand, though polyethylene terephthalate retains cost advantage in mass-market beverage lines outside premium segments.
- Jars:Wide-mouth containers sustaining steady demand from date paste and honey packers in Al Ain and Fujairah.
- Containers:General-purpose articles serving household and bulk food storage applications with lower specification thresholds.
Volume sits with bottles; growth tilts toward vials.
End User:
Application-specific regulatory stringency determines supplier qualification depth and contract duration.
- Pharmaceuticals:Injectable and ophthalmic packaging governed by MOHAP pharmacopeial standards, mandating borosilicate glass with documented thermal-shock thresholds and dimensional tolerances. Abu Dhabi packers serving GCC generics manufacturers concentrate demand for validated supply, compressing procurement to ISO-certified domestic producers.
- Cosmetics:Premium beauty houses across Dubai retail corridors specify lightweight returnable glass formats, abandoning polyethylene terephthalate for sustainability positioning. European contract manufacturers seek regional UAE capacity to bypass freight costs and import duties for Middle East distribution.
- Food & Beverage:Dairy and juice bottlers in Ras Al Khaimah and Dubai drive refillable glass demand, constrained by plastic substitution persistence in mass-market segments.
- Household:Lower-specification storage containers with minimal regulatory oversight and compressed margin structures.
Revenue concentrates in pharmaceuticals; cosmetics climbs fastest on premiumization.
Manufacturing Stage:
Capital intensity and technical specialization separate furnace operators from downstream finishers.
- Forming:Blow-and-blow or press-and-blow conversion of molten glass into article shapes, requiring oxy-fuel or electric melting furnace architectures under ESMA energy-efficiency codes. Ras Al Khaimah specialists anchor regional supply for dairy and juice bottlers.
- Annealing:Controlled cooling to relieve thermal stress, critical for pharmaceutical vial integrity and burst strength retention.
- Coating:Tin or polyethylene surface treatments for abrasion resistance during filling and transit, specified by premium cosmetic and pharmaceutical buyers.
- Finishing:Final dimensional verification and quality assurance, where validation timeline compression slows capacity monetization for new furnace investments.
Margin pools concentrate in forming; coating gains share on specification escalation.
Capacity:
Scale economics and customization depth determine buyer-supplier matching.
- Custom Scale:Flexible batch production attracting European cosmetic houses seeking regional contract manufacturing hubs, bypassing freight costs for Middle East distribution. Lightweight engineering capabilities command pricing power among sustainability-focused brand owners.
- Large Scale:High-throughput furnace operations serving standardized beverage and food container demand with compressed per-unit costs.
- Medium Scale:Mid-volume producers balancing efficiency against pharmaceutical validation requirements.
- Small Scale:Niche operators serving specialty household and artisanal food segments with limited economies of scale.
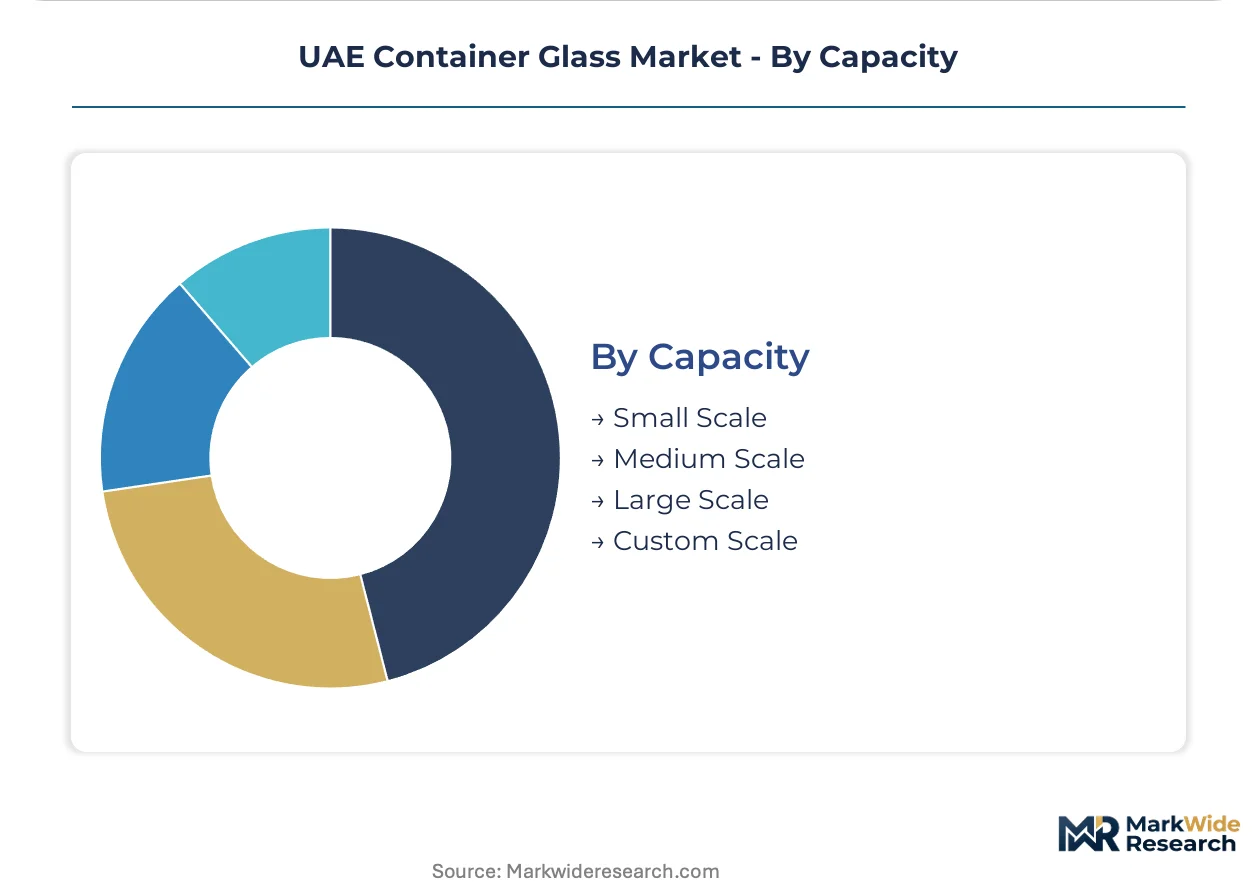
Output volume centers on large scale; value expansion tilts toward custom scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical vial demand concentrates in Abu Dhabi pharmaceutical corridors, while Dubai retail corridors anchor premium cosmetic glass procurement. Ras Al Khaimah furnaces supply dairy and juice bottlers across the Emirates.
Dubai
European cosmetic houses and premium beauty brands drive demand for lightweight returnable glass formats. ESMA energy-efficiency codes govern all new furnace investments in the emirate. Jebel Ali industrial zone hosts ISO-certified pharmaceutical amber glass output serving CDSCO-aligned export markets.
Abu Dhabi
Injectable and ophthalmic packaging demand from GCC generics manufacturers concentrates here. MOHAP pharmacopeial glass standards mandate borosilicate-grade validation for all distributed products. Khalifa Industrial Zone anchors domestic vial production with documented thermal-shock thresholds.
Ras Al Khaimah
Dairy and juice bottlers anchor beverage glass demand through refillable formats. The emirate's silica sand deposits support integrated raw material sourcing for furnace operations. Al Hamra Industrial Area hosts specialists in lightweight container engineering reducing per-unit material consumption.
Sharjah
Mid-scale forming operations serve food packers and household container segments. The emirate positions between Dubai's premium demand and northern industrial capacity. Industrial zones here attract secondary finishing and coating operations from larger furnace operators.
Northern Emirates
Fujairah and Al Ain sustain steady jar demand from date paste and honey packers. Lower regulatory stringency allows commodity-grade production for regional food distribution. These sub-regions function as cost-competitive supply bases for standardized container formats.
UAE Container Glass Market Competitive Landscape
Capacity expansion dominates the current landscape as furnace operators retrofit oxy-fuel combustion systems under ESMA energy-efficiency mandates. The vendor base clusters around three strategic archetypes: integrated furnace-to-finish specialists, lightweight engineering boutiques, and pharmaceutical-grade validation leaders. M&A activity concentrates on securing silica sand offtake agreements and acquiring ISO certification capabilities. Strategic partnerships between UAE operators and European engineering firms accelerate technology transfer for electric melting retrofits.
Among Ras Al Khaimah-based specialists, RAK Ghani Glass LLC exemplifies the lightweight engineering archetype through computational modeling capabilities. Al Tajir Glass Industries anchors the integrated production tier with furnace capacity serving regional dairy and juice bottlers. O-I Jebel Ali occupies the pharmaceutical-grade validation segment through ISO-certified amber glass output. These three entities represent distinct competitive positions without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Al Tajir Glass Industries |
| Al Wara Group |
| RAK Ghani Glass LLC |
| Frigoglass Jebel Ali FZE |
| Emirates Glass LLC |
| Saverglass LLC |
| Hotpack Packaging Industries LLC |
| O-I Jebel Ali |
| Global Packaging FZC |
| Others |
Value Network & Pricing Analysis
ESMA energy-efficiency codes governing furnace rebuilds gate qualified supply access for UAE container glass producers, anchoring premium-tier pricing power to oxy-fuel or electric melting compliance while compressing margin pools for conventional regenerative furnace operators.
Pricing Analysis
Volume concentrates in standardized soda-lime-silica bottles serving Ras Al Khaimah dairy and juice bottlers, while margin pools accrue to borosilicate vial producers meeting MOHAP pharmacopeial standards for Abu Dhabi pharmaceutical corridors. Price differentiation separates ISO-certified pharmaceutical amber glass from commodity beverage formats, with thermal-shock validation documentation commanding substantial premiums. Pricing pressure stems from polyethylene terephthalate cost advantage in mass-market beverage segments, forcing glass producers toward lightweight engineering to defend position. Pharmaceutical packers exhibit lowest price sensitivity given regulatory non-negotiability, while food and beverage buyers retain acute cost consciousness.
Supply Chain Analysis
Domestic-content alignment with MOHAP pharmacopeial mandates and ESMA energy-efficiency codes is reshaping sourcing patterns, privileging UAE-based furnace operators over uncertified import sources for injectable packaging. Silica sand deposits in Ras Al Khaimah anchor local raw material security, though soda ash and boron compounds draw from Turkey and the United States. Supply chain risk centers on single-source vulnerability for specialized borosilicate-grade inputs required for pharmaceutical validation. Distribution runs through Jebel Ali industrial zone for pharmaceutical amber glass serving CDSCO-aligned export markets, with direct furnace-to-bottler relationships dominating beverage supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's tightened pharmacopeial standards have erected a formidable compliance moat around UAE container glass production, concentrating viable supply among furnace operators capable of borosilicate-grade validation documentation and oxy-fuel retrofit investment.
For Market Incumbents: Extend certification capabilities into CDSCO-aligned export markets to capture adjacent demand from Indian generics manufacturers, while deepening backward integration into Ras Al Khaimah silica sand deposits to buffer soda ash volatility. Incumbent furnace operators must accelerate electric melting technology transfer partnerships with European engineering firms before ESMA codes eliminate regenerative rebuild options entirely. For New Entrants and Emerging Players: Computational modeling capabilities for lightweight container engineering represent the most penetrable technology wedge, targeting European cosmetic houses seeking regional UAE contract manufacturing hubs to bypass freight costs and import duties. New entrants should concentrate custom-scale capacity in Dubai industrial zones adjacent to premium beauty brand procurement offices, securing single-source certified supply agreements before incumbent qualification timelines harden. For Investors and Strategic Acquirers: MOHAP's expansion of borosilicate mandates to additional pharmaceutical packaging categories is the leading indicator that validation-capable furnace assets will command scarcity premiums across the Gulf Cooperation Council. Acquisition targets should display ISO certification depth, established MOHAP inspection histories, and oxy-fuel or electric melting architectures compliant with ESMA energy-efficiency codes.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | ESMA compliance eliminates regenerative rebuild options, forcing capital allocation toward lower-carbon melting. |
| Pharmaceutical Validation Investment | MOHAP pharmacopeial documentation requirements compress procurement to ISO-certified domestic producers. |
| Lightweight Engineering Capability | Sub-gram weight reduction specifications from premium cosmetic buyers command pricing power. |
| Silica Sand Offtake Agreement | Ras Al Khaimah deposit control buffers raw material volatility for integrated furnace operators. |
| CDSCO Export Market Alignment | Indian regulatory qualification opens adjacent demand from South Asian generics manufacturers. |
Research Methodology
Independent corroboration across furnace operations executives, pharmaceutical packaging procurement managers, cosmetic brand supply chain directors, and ESMA regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation from customs trade records, SEC filings of listed glass manufacturers, Gulf Standardization Organization technical specifications, and MOHAP pharmacopeial guidance documents. Bottom-up capacity assessments across UAE forming halls triangulate against top-down demand modeling from GCC pharmaceutical production databases.
Rate-of-change decomposition across the projection horizon separates volume growth in beverage bottles from value expansion in pharmaceutical vials and premium cosmetic containers. Segmentation dimensions modeled include product type, end-user regulatory stringency, manufacturing stage capital intensity, and capacity scale customization depth. CAGRs derive from furnace utilization trajectories, MOHAP mandate expansion timelines, and European cosmetic brand regional sourcing shifts.
Several conditions sit outside the modeled scope, including abrupt shifts in polyethylene terephthalate recycling economics, Gulf Cooperation Council pharmaceutical production relocation decisions, and carbon pricing implementation timelines affecting furnace fuel choices. Forecasts reflect assumptions around ESMA code enforcement consistency and MOHAP inspection capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Malaysia Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
South Africa Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Israel Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market