
 Asia Pacific Glass Packaging Market | 2026-2036
Asia Pacific Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Glass Packaging Market Outlook
The EU Green Deal's extraterritorial carbon border adjustments is decoupling virgin glass demand from traditional energy-intensive production models across Asia Pacific export corridors. Saint-Gobain leverages its furnace electrification roadmap to sustain cost parity in Southeast Asian markets. Owens-Illinois anchors regional supply through its Australian and New Zealand container glass networks. Nihon Yamamura Glass differentiates via pharmaceutical-grade borosilicate competence serving Japanese and Korean drug manufacturers.
Asia Pacific glass packaging denotes silica-based containers formed through blow-and-blow or press-and-blow processes, typically comprising 70-75% silicon dioxide with soda ash and limestone fluxes, engineered to provide inert barriers against oxygen and moisture ingress for sensitive contents. The Food & Beverage end user segment dominates volume throughput, with breweries and spirit distillers in Thailand and Vietnam driving repeat orders for amber and flint bottles. Cosmetics applications occupy the fastest-expanding margin pool, as K-beauty houses and Australian clean-skin brands specify heavier-walled custom shapes. Small capacity vials and ampoules lead pharmaceutical demand, particularly for parenteral drug delivery systems requiring Type I borosilicate conformance.
India's BIS mandates food-contact glass compliance with IS 15673 standards, while China's GB 4806.5 governs heavy metal migration limits in packaging materials; Japan's Ministry of Health, Labour and Welfare maintains positive list systems for glass additives in pharmaceutical applications. These frameworks collectively raise capital barriers for new furnace entrants and reward incumbents with certified quality systems. Stakeholders must monitor carbon accounting methodologies as CBAM-phase equivalent rules propagate through bilateral trade agreements, reshaping sourcing decisions for brand owners with European export exposure.
Market Dynamics
Electrification of container glass furnaces is rewriting cost structures across Asia Pacific, as energy-intensive silica melting confronts carbon border adjustments on export-bound shipments.
Growth Catalysts
- EU Green Deal extraterritoriality:CBAM-phase equivalent rules in bilateral trade agreements are pulling Asian exporters toward certified low-carbon glass, expanding addressable premium segments for compliant producers.
- K-beauty packaging pivot:South Korean cosmetics houses are specifying heavier-walled custom glass shapes, displacing plastic primary packaging and opening margin-rich customization contracts.
- Pharmaceutical-grade demand:Japanese and Korean drug manufacturers require Type I borosilicate conformance for parenteral delivery systems, tightening supply standards and rewarding certified incumbents.
Market Restraints
- Natural gas price volatility:Soda-lime furnace operations remain exposed to LNG import fluctuations across Southeast Asian production bases, compressing margin predictability for non-integrated operators.
- Jiangsu-Shandong supply concentration:China's eastern coastal manufacturing belt hosts disproportionate container glass capacity, creating geographic vulnerability to regional energy rationing or logistics disruption.
- Aluminum and PET substitution:Lightweight beverage cans and recycled polymer bottles compete aggressively in mass-market refreshment categories, capping glass volume expansion in price-sensitive segments.
Strategic Opportunities
- Vietnam-Thailand brewery expansion:Amber and flint bottle demand from spirit distillers and beer producers in these markets is outpacing local furnace capacity, creating import substitution openings for regional suppliers.
- Australian clean-skin brand specification:Premium skincare labels are mandating pharmaceutical-grade glass for serum and oil packaging, extending borosilicate competence into adjacent cosmetics applications.
- India BIS certification arbitrage:Tightening IS 15673 standards for food-contact glass are raising capital barriers for new entrants, rewarding early movers with certified quality systems and institutional buyer lock-in.
Industry Challenges
- Electrical furnace engineering talent scarcity:Conversion from fossil-fired to oxy-fuel and full-electric melting requires specialized refractory and process control expertise that remains concentrated in European technical institutes.
- Heavy metal migration testing timelines:China's GB 4806.5 compliance documentation for new glass formulations extends certification cycles, delaying product launches for reformulated compositions.
- Legacy batch plant integration:Pre-mixing infrastructure designed for conventional soda-ash-limestone recipes requires costly retrofit to handle alternative fluxes and recycled cullet streams at electrified furnace sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Glass Packaging Market |
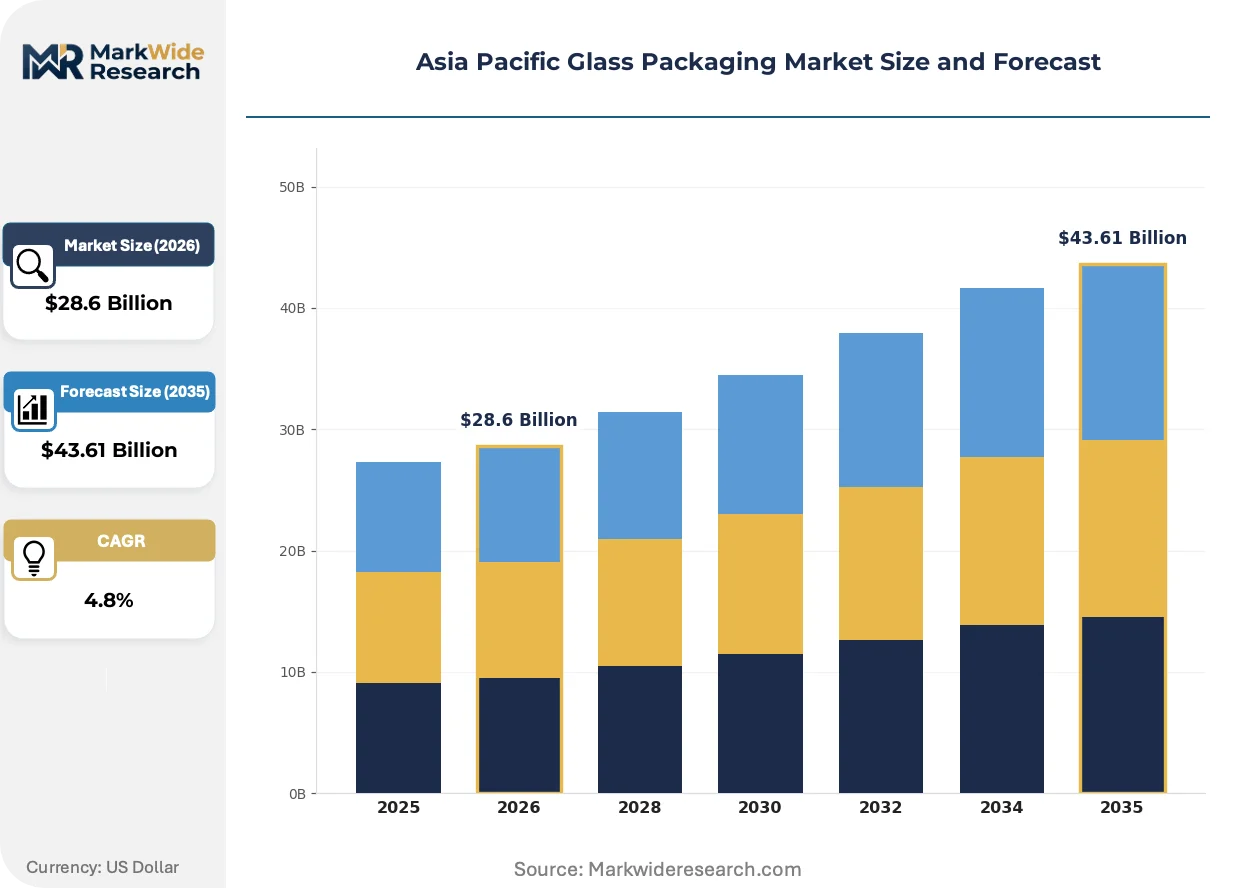
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubes End User: Food & Beverage, Cosmetics, Pharmaceuticals, Personal Care Capacity: Small, Medium, Large, Extra Large Shape: Round, Square, Rectangular, Custom |
| Companies Covered | Gerresheimer, Saint-Gobain, Owens-Illinois, Sonoco Products Company, Hindustan National Glass & Industries, Piramal Glass, Ardagh Group, Nihon Yamamura Glass, Amcor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Glass Packaging Market Strategic Shifts
Furnace technology, regulatory accounting, and buyer procurement logic are simultaneously shifting, compressing legacy operating models while opening new competence-based premiums.
Hybrid oxy-fuel and electric boosting systems are decentralizing production geography across Asia Pacific. Japanese engineering firms are retrofitting mid-scale furnaces with electrode arrays that reduce natural gas dependency by forty to sixty percent. Thai and Vietnamese bottlers are now sourcing from smaller, distributed melting facilities rather than concentrating purchases at single mega-sites, fragmenting procurement patterns and enabling regional supply resilience.
Japan's Ministry of Health, Labour and Welfare maintains positive list systems for glass additives in pharmaceutical applications. This framework is extending documentation requirements to cosmetics packaging as K-beauty houses seek drug-grade material traceability. Korean contract manufacturers are responding by segregating pharmaceutical and cosmetic production lines to maintain additive purity certifications.
Brand owners with European export exposure are embedding carbon accounting into supplier scorecards. Australian wine exporters and Japanese pharmaceutical shippers now require furnace-level emissions disclosure as a condition of contract renewal. This behavioral shift is most visible in procurement departments of mid-cap cosmetics houses, where sustainability credentials are displacing pure unit-cost ranking in vendor selection protocols.
Asia Pacific Glass Packaging Market Segmentation
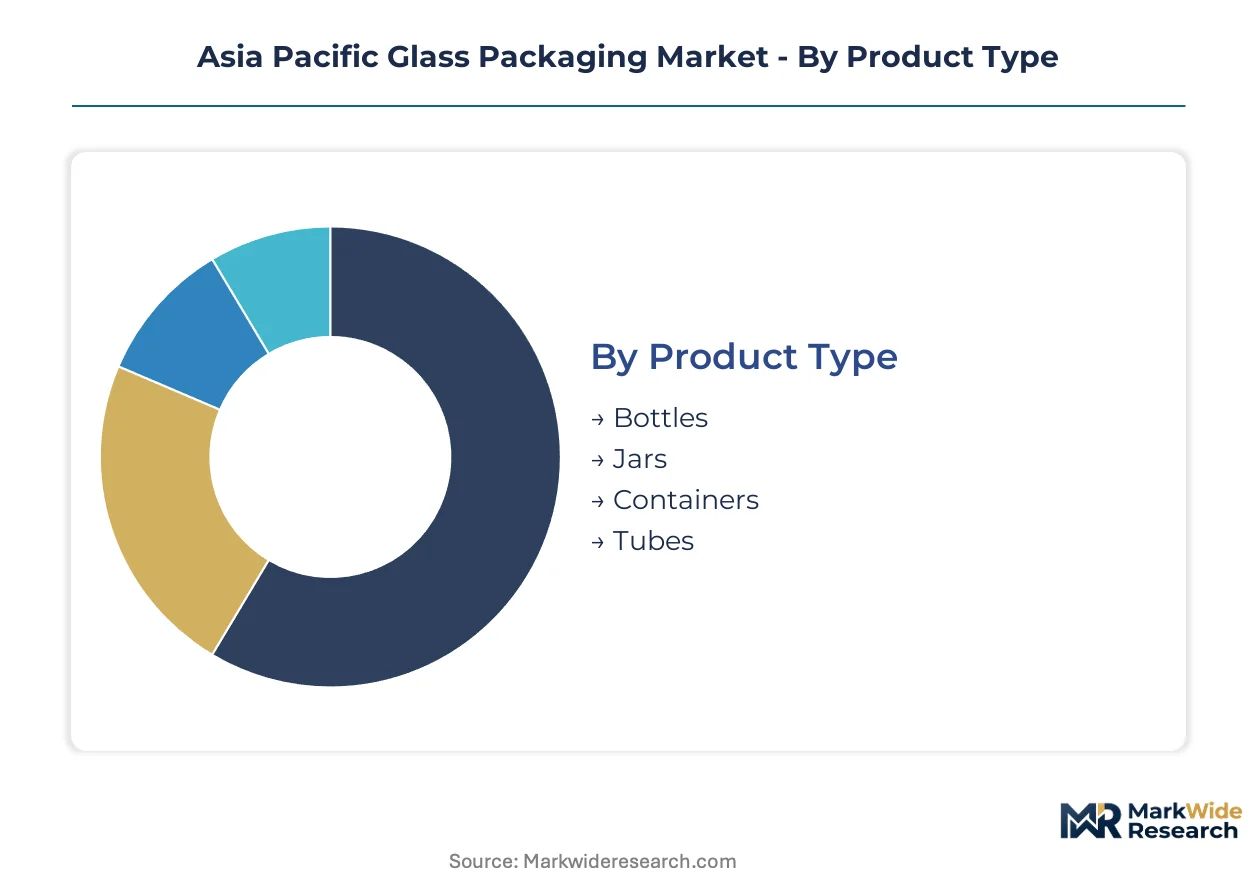
Glass packaging segmentation in Asia Pacific reflects divergent capital requirements across furnace configurations and forming technologies. Product geometry and end-use purity standards dictate equipment investment intensity, creating tiered competitive moats among regional suppliers.
Product Type:
Capital intensity peaks with container complexity and wall thickness precision, separating mass-market bottle producers from specialized pharmaceutical tube manufacturers.
- Bottles:Amber and flint soda-lime compositions dominate brewery and spirits procurement from Thailand and Vietnam. Thai distillers are driving repeat orders for standardized neck finishes, locking in multi-year furnace contracts with Jiangsu-based suppliers.
- Jars:Wide-mouth configurations with vacuum-lug closures serve food preservation and premium cosmetics. South Korean K-beauty houses specify heavier-walled custom shapes, displacing plastic primary packaging and opening margin-rich customization contracts.
- Containers:Rectangular and stackable designs optimize pallet density for export logistics. Australian wine shippers favor lightweighted Bordeaux and Burgundy profiles to reduce freight cost per case.
- Tubes:Collapsible aluminum-laminate and all-glass pharmaceutical tubes require dedicated forming lines. Japanese drug manufacturers source Type I borosilicate tubes for ointment and cream delivery, tightening supply standards.
Bottles absorb the bulk of installed capacity; tubes are expanding most quickly on pharmaceutical-grade demand.
End User:
Regulatory stringency varies sharply across end-use applications, with pharmaceutical and food-contact segments imposing the steepest compliance burdens on furnace operators.
- Food & Beverage:Soda-lime bottles and jars for breweries, distilleries, and preserved foods constitute the volume base. China's GB 4806.5 governs heavy metal migration limits, extending certification cycles for reformulated glass compositions.
- Cosmetics:Premium skincare and fragrance packaging demands optical clarity and decorative surface treatments. Australian clean-skin brands now mandate pharmaceutical-grade glass for serum and oil packaging, extending borosilicate competence into adjacent applications.
- Pharmaceuticals:Type I borosilicate vials, ampoules, and syringes for parenteral drugs require the highest material purity. Japan's Ministry of Health, Labour and Welfare maintains positive list systems for glass additives, segregating production lines to maintain certification.
- Personal Care:Shampoo, conditioner, and body wash bottles balance cost and aesthetic differentiation. Mass-market brands in Southeast Asia face aggressive substitution from PET and aluminum, capping glass volume expansion in price-sensitive segments.
Food & Beverage commands the deepest furnace commitments; cosmetics is gaining share fastest on premiumization trends.
Capacity:
Scale economics favor high-volume runs, yet pharmaceutical and niche cosmetics applications sustain profitable small-batch operations through premium pricing.
- Small:Vials, ampoules, and sample-size containers under 50ml serve pharmaceutical sampling and luxury cosmetics trial formats. Korean contract manufacturers run dedicated small-capacity lines to maintain additive purity certifications for drug-grade traceability.
- Medium:Standard wine bottles, spirits flasks, and cosmetic jars between 100-500ml balance throughput and flexibility. Vietnam-Thailand brewery expansion is outpacing local furnace capacity, creating import substitution openings for regional suppliers.
- Large:Family-size food jars and premium spirits magnums require specialized handling equipment. India's BIS mandates food-contact compliance with IS 15673 standards, raising capital barriers for new entrants in this volume tier.
- Extra Large:Bulk pharmaceutical carboys and industrial chemical containers demand reinforced wall structures. Limited regional furnace capacity for these formats creates dependency on European and Japanese imports.
Medium capacity captures the broadest demand base; small capacity delivers the steepest margin premiums.
Shape:
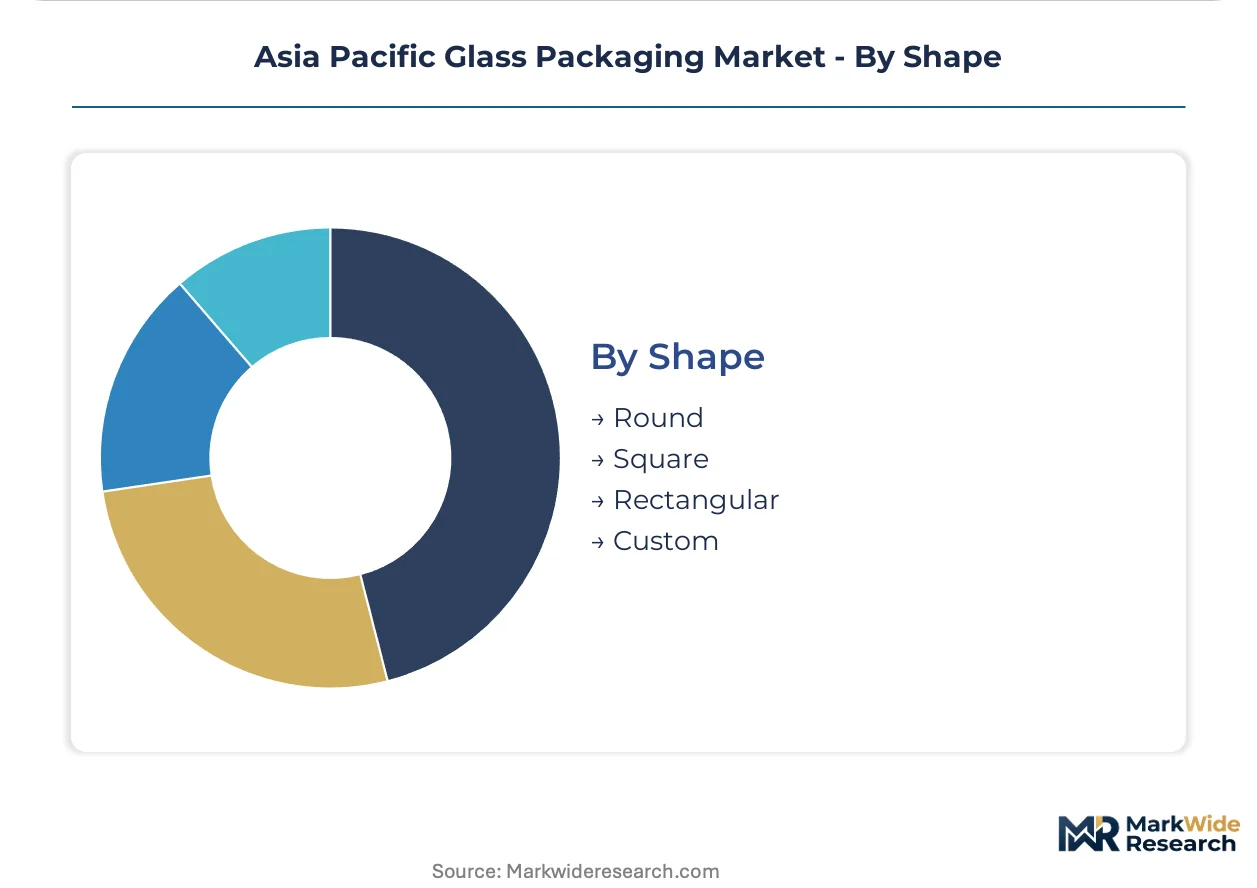
Geometric complexity determines forming speed and defect rates, with custom shapes requiring dedicated mold investments that amortize only at premium volumes.
- Round:Cylindrical profiles maximize forming efficiency and minimize stress concentrations. Beverage bottlers in China's eastern coastal manufacturing belt cluster near container glass furnaces in Jiangsu and Shandong provinces for round-bottle supply security.
- Square:Sharp corners require controlled cooling profiles to prevent thermal cracking. Japanese whiskey and shochu distillers favor square profiles for shelf differentiation and pallet optimization.
- Rectangular:Flat panels suit label adhesion and retail display geometry. Australian olive oil and sauce producers specify rectangular formats for export carton efficiency.
- Custom:Asymmetric and sculptural forms for luxury fragrances and limited-edition spirits carry the highest mold costs. K-beauty houses commission proprietary shapes that lock in supplier relationships through exclusive tooling ownership.
Round shapes dominate unit economics; custom shapes command the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Shandong provinces anchor Asia Pacific container glass capacity, hosting furnace clusters that supply beverage bottlers across China's eastern coastal manufacturing belt.
China
Brewery and spirits demand in Jiangsu and Shandong drives repeat orders for amber and flint bottles. GB 4806.5 governs heavy metal migration limits in packaging materials, extending certification cycles for reformulated glass compositions. Eastern coastal manufacturing clusters concentrate furnace capacity near Shanghai-Ningbo port logistics.
India
Food-contact glass compliance with IS 15673 standards tightens quality thresholds for domestic and imported products alike. BIS certification mandates raise capital barriers for new furnace entrants. Maharashtra and Gujarat host institutional buyers seeking certified quality systems for food jar procurement.
Japan
Pharmaceutical-grade borosilicate demand from drug manufacturers requires Type I conformance for parenteral delivery systems. The Ministry of Health, Labour and Welfare maintains positive list systems for glass additives. Kanto region production lines segregate pharmaceutical and cosmetic output to maintain additive purity certifications.
South Korea
K-beauty houses accelerate shifts from plastic to heavier-walled custom glass primary packaging. MFDS-aligned traceability requirements extend documentation standards to cosmetics packaging. Seoul Capital Area contract manufacturers run dedicated lines for drug-grade material segregation.
Australia
Clean-skin skincare brands mandate pharmaceutical-grade glass for serum and oil packaging, extending borosilicate competence into adjacent cosmetics applications. Wine exporters embed carbon accounting into supplier scorecards requiring furnace-level emissions disclosure. Melbourne and Sydney procurement departments weight sustainability credentials in vendor selection protocols.
Asia Pacific Glass Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and furnace-technology dimensions. The market exhibits tiered concentration with multinational furnace operators controlling high-volume beverage contracts while regional specialists capture pharmaceutical and cosmetics premiums. Three archetypes dominate: electrified-furnace multinationals with carbon-compliant export capacity, BIS-certified domestic incumbents serving institutional food buyers, and borosilicate specialists with pharmaceutical-grade additive traceability. Capacity expansion and backward integration into cullet preprocessing represent the dominant competitive moves.
Within the multinational tier, Saint-Gobain and Owens-Illinois occupy positions defined by furnace electrification roadmaps and Australian-New Zealand network coverage. Nihon Yamamura Glass exemplifies the pharmaceutical-grade specialist archetype, anchoring Japanese and Korean drug manufacturer supply relationships through borosilicate competence. Hindustan National Glass & Industries represents the BIS-certified domestic incumbent category, serving India's tightening food-contact standards with institutional buyer lock-in.
| Leading Market Players |
|---|
| Gerresheimer |
| Saint-Gobain |
| Owens-Illinois |
| Sonoco Products Company |
| Hindustan National Glass & Industries |
| Piramal Glass |
| Ardagh Group |
| Nihon Yamamura Glass |
| Amcor |
| Others |
Value Chain & Pricing Dynamics
Soda ash spot prices on the Yangtze River Delta commodity exchange cascade through Asia Pacific glass packaging tiers, compressing margins at fossil-fired furnace operators while electrified producers sustain premium positioning through carbon-compliant export contracts.
Pricing Analysis
Certified low-carbon throughput anchors value-based pricing for EU-export-bound glass, separating electrified furnace operators from commodity soda-lime suppliers. Three-tier pricing structure across pharmaceutical-grade borosilicate, food-contact certified, and standard container glass reflects additive traceability and BIS compliance investment. Pricing pressure stems from LNG import volatility at Southeast Asian production bases, squeezing non-integrated operators. Mass-market beverage bottlers exhibit acute price sensitivity, while K-beauty houses and Australian clean-skin brands absorb premiums for pharmaceutical-grade material segregation.
Supply Chain Analysis
Freight cost differentials between Jiangsu-Shandong furnace clusters and Vietnam-Thailand brewery demand centers favor regional import substitution over long-haul Chinese supply. Raw material sourcing draws from Australian silica sand, Chinese soda ash, and Indian limestone flux deposits. Single-source vulnerability concentrates at China's eastern coastal manufacturing belt, exposing buyers to regional energy rationing disruption. Distribution runs through institutional procurement contracts with Maharashtra food jar buyers and Seoul Capital Area cosmetics contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific glass packaging is consolidating around furnace electrification competence, with CBAM-phase equivalent rules in bilateral trade agreements forcing carbon-intensive operators toward distressed asset sales or exit.
For Market Incumbents: Deploy furnace electrification roadmaps to sustain cost parity in Southeast Asian markets. Saint-Gobain and Owens-Illinois anchor regional supply through Australian-New Zealand networks and oxy-fuel retrofit investments. Defensive consolidation moves include acquiring distressed fossil-fired capacity for electrode array conversion and locking in multi-year offtake with Thailand distillers before Vietnam-Thailand brewery expansion saturates import substitution openings.
For New Entrants and Emerging Players: Australian clean-skin brand procurement departments present the most penetrable buyer archetype, mandating pharmaceutical-grade glass for serum packaging without incumbent supplier lock-in. White-space targets include borosilicate competence for adjacent cosmetics applications and small-batch custom shape production for K-beauty limited editions. Go-to-market through sustainability credentialing that displaces pure unit-cost ranking in vendor selection protocols.
For Investors and Strategic Acquirers: Distressed-cycle entries favor BIS-certified domestic incumbents in India and pharmaceutical-grade specialists with Japanese Ministry of Health, Labour and Welfare additive traceability systems. Long-term viability hinges on carbon accounting methodology propagation through bilateral trade agreements. Watch for CBAM-equivalent rule adoption in ASEAN trade frameworks as the inflection signal for electrified furnace asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electrification Roadmap | Saint-Gobain sustains export cost parity through electrode array deployment at Southeast Asian sites. |
| Pharmaceutical-Grade Certification Investment | Nihon Yamamura Glass anchors Japanese and Korean drug manufacturer relationships through Type I borosilicate conformance. |
| Backward Integration into Cullet Preprocessing | Integrated operators reduce batch plant retrofit costs for alternative flux handling at electrified furnace sites. |
| Regional Import Substitution Capacity | Vietnam-Thailand brewery expansion outpaces local furnace supply, creating procurement openings for Jiangsu-based exporters. |
| BIS Certification Arbitrage | Early movers in India's IS 15673 compliance capture institutional food jar buyer lock-in before capital barriers rise. |
Study Parameters
Multi-period observation of furnace electrification investments, carbon border adjustment propagation, and BIS certification timelines anchored the trend analysis, supplemented by interviews with container glass plant managers, K-beauty packaging procurement leads, pharmaceutical contract manufacturing executives, and Australian wine exporter sustainability officers. Secondary validation drew from China's GB 4806.5 compliance documentation, India's BIS IS 15673 standards filings, Japan's Ministry of Health, Labour and Welfare positive list updates, EU Green Deal CBAM implementation notices, and customs trade data on soda-lime container glass flows. Bottom-up capacity modeling across Jiangsu, Shandong, Maharashtra, and Kanto production clusters triangulated against top-down end-use demand segmentation.
Input-output matrices mapped silica sand, soda ash, and limestone flux cost structures against furnace configuration tiers and forming technology intensity across the projection horizon. Segmentation dimensions modeled include product geometry complexity, end-use regulatory stringency, capacity scale economics, and regional production hub carbon intensity. CAGRs derived from trend extrapolation of electrification adoption curves and premium segment penetration rates, with furnace-level emissions disclosure requirements and pharmaceutical-grade additive traceability systems as key forecast inputs.
Revisions become necessary when CBAM-equivalent rules accelerate through ASEAN bilateral agreements, natural gas price volatility triggers furnace closure waves, or heavy metal migration testing timelines extend beyond current certification cycle baselines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Israel Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Egypt Glass Packaging Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Uzbekistan Container Glass Market
Glass Packaging
Glass Veil Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
North America Amber Glass Packaging Market
Glass Packaging
Amber Glass Packaging Market