
 Seborrheic Keratosis Treatment Market | 2026-2036
Seborrheic Keratosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Seborrheic Keratosis Treatment Market Outlook
CE marking under the EU Medical Device Regulation is collapsing the window for uncertified energy-based devices in European dermatology, forcing portfolio rationalization among manufacturers. Lumenis leverages its established laser platform architecture to sustain clinical credibility across multiple lesion indications. Quanta System anchors its competitive stance through specialized solid-state laser engineering for precise epidermal targeting. Alma Lasers competes on system modularity, allowing practices to extend capital equipment across diverse aesthetic and medical applications.
Seborrheic keratosis treatment encompasses the clinical and aesthetic management of benign epidermal proliferations through mechanical, thermal, chemical, or pharmacological modalities, typically targeting lesions ranging from millimeters to several centimeters in diameter with histological confirmation protocols. The primary purpose centers on symptomatic relief, cosmetic improvement, and pathological exclusion of malignancy mimics. Cryotherapy occupies the largest procedural volume due to its low capital requirements and established reimbursement pathways, while topical treatments represent the fastest-expanding category as patient preference shifts toward non-invasive, self-administered options. Electrosurgery retains concentrated margin pools in hospital outpatient settings where lesion complexity demands operative documentation.
The FDA oversees device safety and efficacy claims for laser and light-based systems through its Center for Devices and Radiological Health, while HIPAA governs the telehealth delivery mode segment emerging in post-treatment follow-up protocols. The EU MDR and REACH frameworks impose biocompatibility and substance restriction requirements on topical formulation excipients and device components, elevating compliance costs for market participants. Stakeholders must monitor regulatory divergence between the FDA's de novo pathway and the EU MDR's clinical evidence expectations when prioritizing geographic launch sequencing and portfolio investment.
Market Dynamics
The FDA's de novo pathway for energy-based dermatological devices is compressing product development timelines while elevating clinical evidence requirements, forcing manufacturers to front-load randomized trial investments before commercialization.
Growth Catalysts
- HIPAA-compliant telehealth protocols:Post-treatment follow-up via remote consultation reduces clinic burden and expands addressable patient populations in rural United States regions.
- Solid-state laser engineering advances:Improved epidermal targeting precision enables single-session lesion clearance, driving patient preference toward physician-administered modalities over self-treatment.
- Aging United States demographics:Elevated seborrheic keratosis incidence among patients over 65 sustains procedural volume growth in dermatology clinics and hospital outpatient departments.
Market Restraints
- EU MDR clinical evidence mandates:CE marking under the Medical Device Regulation demands extensive biocompatibility documentation, extending time-to-market for European device launches by 18-24 months.
- Histopathology confirmation requirements:Mandatory lesion biopsy protocols before thermal or laser intervention add cost and procedural friction, limiting same-day treatment completion rates.
- Topical formulation excipient restrictions:REACH substance limitations constrain preservative and penetration enhancer options, complicating self-administered product development pipelines.
Strategic Opportunities
- Underpenetrated Medicare Advantage integration:Value-based care contracts in United States managed care networks incentivize preventive lesion management, opening bundled payment models for clinic networks.
- Device modularity architectures:Platform systems spanning aesthetic and medical indications improve capital equipment utilization rates and reduce per-procedure amortization costs for mid-sized practices.
- Home-use topical delivery innovation:Hydrogel and microneedle patch formats address patient preference for non-clinic administration while maintaining pharmaceutical-grade active concentration stability.
Industry Challenges
- Laser safety certification timelines:ANSI Z136.3 compliance documentation and state-level medical device registration create multi-jurisdictional approval bottlenecks for new system launches.
- Reimbursement code fragmentation:Inconsistent CPT coding between cryotherapy, electrosurgery, and laser modalities complicates revenue cycle management and prior authorization workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seborrheic Keratosis Treatment Market |
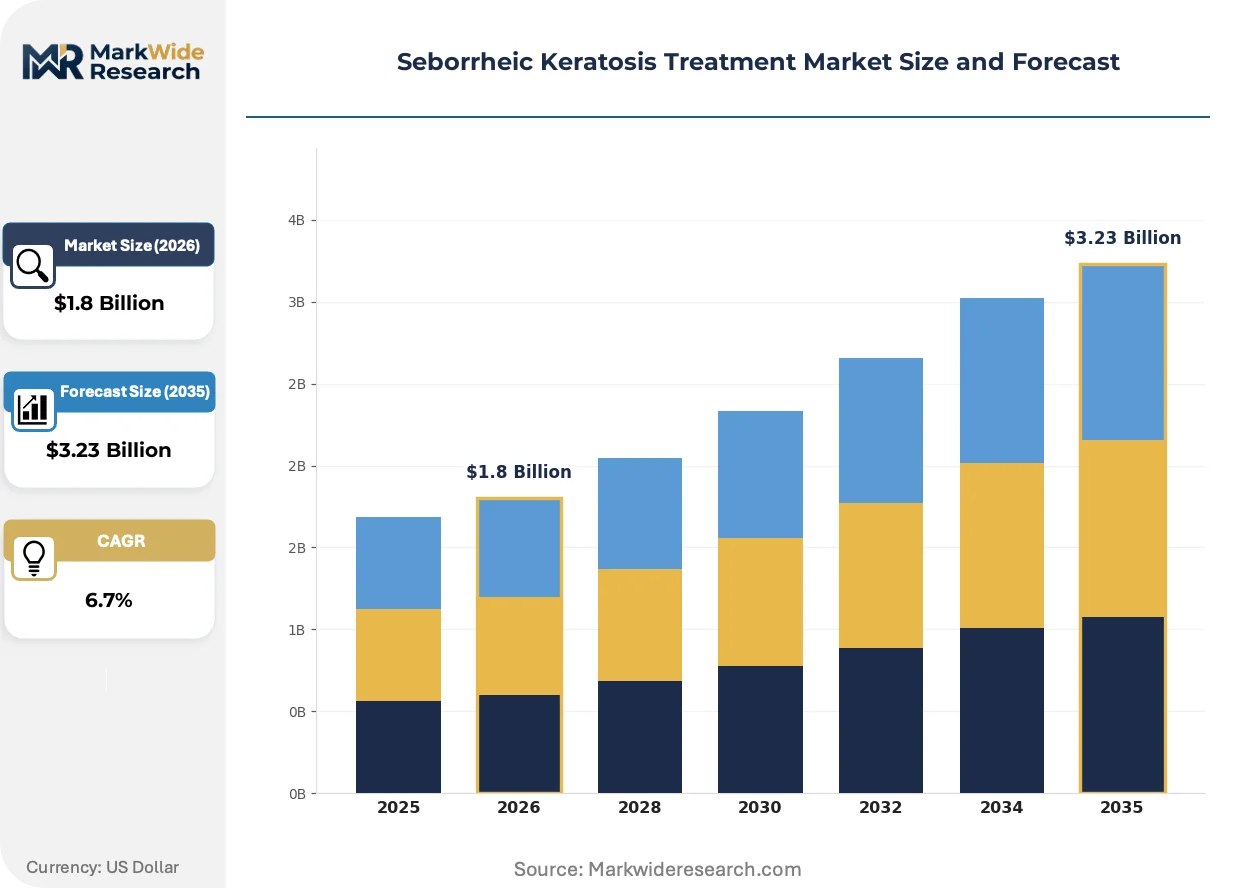
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryotherapy, Curettage, Electrosurgery, Topical Treatments Application: Dermatology Clinics, Hospitals, Home Care, Aesthetic Centers End User: Patients, Dermatologists, Aesthetic Practitioners, Healthcare Providers Delivery Mode: In-office Treatment, At-home Treatment, Surgical Intervention, Telehealth |
| Companies Covered | Lumenis, Quanta System, Aclaris Therapeutics, BioLineRx, BIOLASE, Alma Lasers, CryoConcepts LP, Novartis AG, Cutera, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seborrheic Keratosis Treatment Market Strategic Shifts
Energy-based modalities and self-administered pharmaceuticals are diverging along distinct innovation trajectories, with capital equipment manufacturers pursuing platform versatility while topical developers prioritize formulation stability and patient adherence.
Fractional laser technology is fragmenting the traditional monolithic lesion removal market by enabling staged, lower-downtime treatment protocols. Dermatology clinics in suburban United States markets are adopting these systems at accelerating rates to capture cosmetic-conscious patients who decline conventional ablative procedures. The resulting procedural segmentation is compressing average revenue per lesion while expanding total addressable procedure counts.
REACH substance restriction schedules are forcing reformulation of topical excipient portfolios across European supply chains. Manufacturers are substituting traditional penetration enhancers with biofermentation-derived alternatives to maintain regulatory compliance without sacrificing bioavailability. The compliance burden falls disproportionately on mid-sized pharmaceutical developers lacking dedicated regulatory affairs infrastructure.
Patient acquisition through direct-to-consumer channels is displacing traditional physician referral networks for initial lesion assessment. United States telehealth platforms are capturing triage volume through AI-assisted image screening, routing confirmed cases to affiliated dermatology practices for procedural intervention. This channel shift concentrates patient flow among platform-integrated clinic networks while marginalizing independent practitioners.
Seborrheic Keratosis Treatment Market Segmentation
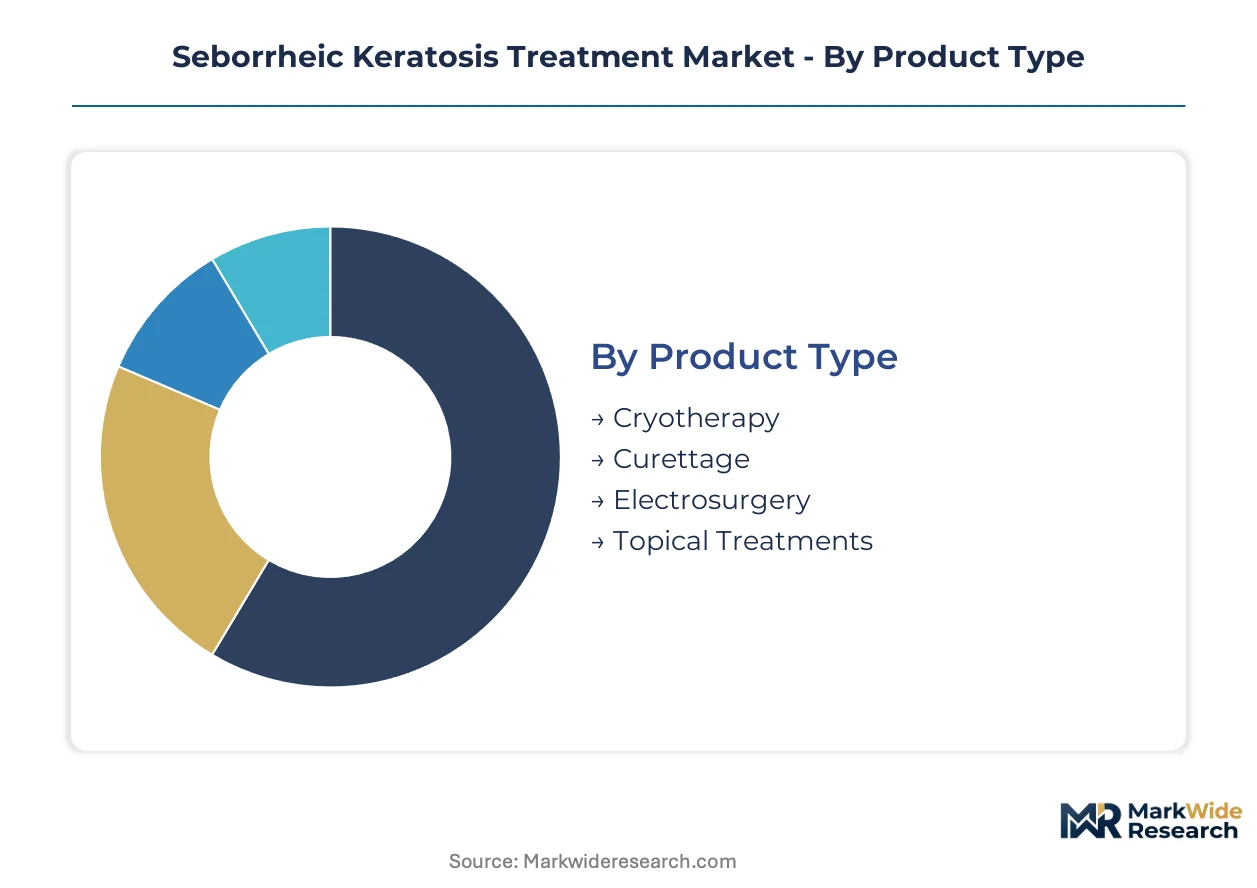
Seborrheic keratosis treatment modalities fragment across distinct capital intensity, reimbursement, and patient autonomy axes. Channel configuration determines which segments capture volume versus margin.
Product Type:
Cryotherapy and curettage flow through high-volume dermatology clinics with established Medicare reimbursement codes, while electrosurgery and topical treatments split between hospital outpatient departments and direct-to-consumer pharmacy channels.
- Cryotherapy:Liquid nitrogen application destroys lesions through controlled thermal injury to epidermal tissue. United States dermatology clinics concentrate demand here due to minimal capital requirements and streamlined CPT coding for reimbursement.
- Topical Treatments:Self-administered pharmaceutical formulations including hydrogen peroxide-based solutions enable patient-controlled lesion management without clinic visits. United States pharmacy chains and telehealth platforms are expanding distribution for cosmetic-conscious patients seeking non-invasive alternatives.
- Curettage:Mechanical scraping with spoon-shaped instruments requires local anesthesia and histopathological specimen handling.
- Electrosurgery:High-frequency electrical current ablation demands operative documentation and sterile field protocols.
Cryotherapy dominates installed base. Topical treatments are where expansion concentrates.
Application:
Cost tier stratification separates institutional settings with bundled payment models from retail aesthetic environments operating on fee-for-service cash economics.
- Dermatology Clinics:Specialized practices combine diagnostic confirmation with same-day procedural intervention, capturing the highest lesion throughput per square foot. United States suburban markets show particular concentration as independent practices consolidate into multi-site networks.
- Home Care:Patient-directed administration of prescription and over-the-counter formulations eliminates facility fees entirely. United States direct-to-consumer advertising and telehealth prescribing laws are accelerating channel shift away from traditional clinic dependency.
- Hospitals:Complex lesion presentations requiring histopathology and operative documentation.
- Aesthetic Centers:Cosmetic-focused facilities emphasizing premium positioning and elective procedure packaging.
Dermatology clinics dominate installed base. Home care is climbing the fastest.
End User:
Volume concentration varies sharply between prescriptive authority holders and the patient populations they serve, with reimbursement eligibility creating divergent economic profiles.
- Dermatologists:Board-certified specialists control diagnostic confirmation and procedural reimbursement pathways, anchoring clinical credibility for lesion management. United States Medicare fee schedules and prior authorization requirements reinforce their gatekeeper position.
- Patients:Ultimate decision-makers on cosmetic versus symptomatic treatment thresholds, increasingly influenced by direct-to-consumer advertising and telehealth triage platforms. United States aging demographics and elevated skin cancer awareness drive self-referral volumes toward clinical confirmation.
- Aesthetic Practitioners:Non-physician providers operating in cash-pay cosmetic environments.
- Healthcare Providers:Primary care and urgent care settings handling initial lesion assessment.
Dermatologists dominate installed base. Patients are gaining share fastest.
Delivery Mode:
Geographic penetration patterns separate modalities requiring physical infrastructure from those enabled by regulatory flexibility in remote care provision.
- In-office Treatment:Physician-administered procedural interventions with immediate histopathology handling and complication management capabilities. United States metropolitan and suburban clinic networks maintain highest per-capita density of treatment rooms equipped for cryotherapy and electrosurgery.
- Telehealth:Remote consultation and follow-up protocols enabled by HIPAA-compliant image transmission and e-prescribing infrastructure. United States rural regions and Medicare Advantage networks show steepest adoption curves as reimbursement parity laws expand.
- At-home Treatment:Self-administered topical regimens with periodic remote monitoring.
- Surgical Intervention:Operating room-based excision for complex or ambiguous lesions.
In-office treatment dominates installed base. Telehealth is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate Highway System and Medicare reimbursement infrastructure underwrite North American dominance in procedural dermatology, while European rail freight corridors and Asian port networks enable differentiated supply chain configurations for device and pharmaceutical distribution.
United States
Aging demographics and elevated skin cancer awareness drive patient volumes toward clinical confirmation of benign lesions. FDA oversight through the Center for Devices and Radiological Health shapes laser and light-based system commercialization pathways. Dermatology clinic networks in suburban Texas and Florida markets concentrate cryotherapy and electrosurgery capacity.
Germany
Precision engineering capabilities sustain domestic manufacturing of solid-state laser platforms for epidermal targeting. EU MDR clinical evidence mandates extend time-to-market for energy-based device launches by 18-24 months. Medical technology clusters in Baden-Württemberg anchor device assembly and biocompatibility testing operations.
Japan
Metropolitan aging populations generate sustained demand for cosmetic lesion management procedures. PMDA regulatory frameworks govern pharmaceutical and device approval timelines for topical and energy-based modalities. Osaka-based aesthetic clinic chains adopt fractional laser systems for staged treatment protocols.
United Kingdom
Private dermatology networks expand procedural menus to capture cosmetic-conscious patient segments outside NHS capacity constraints. MHRA post-Brexit regulatory divergence creates parallel compliance tracks for device manufacturers. London and Southeast England concentrate telehealth triage platform development and AI-assisted image screening capabilities.
Australia
High UV exposure rates elevate skin lesion assessment volumes across primary and specialist care settings. TGA medical device regulations align with international standards while maintaining independent approval pathways. Sydney and Melbourne metropolitan areas concentrate dermatology specialist density and private clinic investment.
Seborrheic Keratosis Treatment Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory compliance dimensions. The vendor base stratifies between platform-scale device manufacturers and focused pharmaceutical developers. Three archetypes dominate: laser system integrators leveraging modular architectures, topical formulation specialists pursuing patient-directed administration, and cryotherapy device fabricators serving high-volume clinic networks. Competitive moves concentrate on M&A for technology access and geographic expansion into Medicare Advantage contract territories.
Among laser platform developers, Lumenis and Alma Lasers exemplify system modularity strategies, while Quanta System occupies a position within specialized solid-state engineering. Aclaris Therapeutics and BioLineRx represent pharmaceutical archetypes pursuing topical innovation, with Novartis AG anchoring the diversified healthcare conglomerate tier. CryoConcepts LP and BIOLASE sit within focused device fabrication segments serving distinct procedural settings.
| Leading Market Players |
|---|
| Lumenis |
| Quanta System |
| Aclaris Therapeutics |
| BioLineRx |
| BIOLASE |
| Alma Lasers |
| CryoConcepts LP |
| Novartis AG |
| Cutera |
| Others |
Value Chain & Pricing Dynamics
Biofermentation-derived penetration enhancers substituting traditional chemical excipients are redrawing European topical formulation supply maps while compressing margin structures for mid-sized pharmaceutical developers lacking dedicated regulatory infrastructure. This input transition simultaneously elevates compliance costs and fragments pricing power across manufacturer tiers.
Pricing Analysis
Volume-discount tiering structures separate cryotherapy device procurement for high-volume United States dermatology clinic networks from premium single-unit laser system sales to hospital outpatient departments. Price differentiation hinges on FDA 510(k) clearance tier and bundled service contract duration. Pricing pressure stems from Medicare Advantage bundled payment compression. Cash-pay aesthetic patients exhibit lowest price sensitivity; rural clinic networks face highest budget constraints.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors constrain EU MDR-compliant device component flows, extending lead times for solid-state laser assemblies sourced from German precision engineering clusters. Supply concentrates in Germany, the United States, and Japan for laser platforms; China and India for generic excipient inputs. Single-source vulnerability sits with specialized epidermal-targeting optics. Distribution runs through manufacturer-direct field service teams for capital equipment and pharmacy wholesale for topical formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integrated clinical-regulatory affairs capabilities—spanning FDA de novo pathway navigation and EU MDR clinical evidence compilation—creates defendable positioning for firms that have built these competencies in-house.
For Market Incumbents: Fortify platform modularity architectures to improve capital equipment utilization across aesthetic and medical indications, defending against specialized solid-state laser entrants. Deepen backward integration into solid-state laser component fabrication to secure supply continuity amid German engineering capacity constraints. Prioritize Medicare Advantage contract penetration in United States suburban markets where lesion volume concentrates. For New Entrants and Emerging Players: Telehealth-enabled lesion triage and remote prescribing workflows represent underserved service layers where incumbents maintain minimal presence. Target United States rural regions and Medicare Advantage networks where reimbursement parity laws expand addressable populations. Pursue direct-to-consumer pharmacy partnerships for topical distribution to bypass established dermatology clinic gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap device manufacturers possessing EU MDR technical documentation packages and established United States reimbursement codes. Five-to-ten year viability favors firms with dual regulatory footprints. Monitor FDA de novo clearance velocity for fractional laser systems as inflection indicator for competitive intensity in physician-administered modalities.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | CE marking under EU MDR collapses windows for uncertified energy-based devices in European dermatology. |
| Medicare Advantage Contract Penetration | Value-based care contracts incentivize preventive lesion management in United States managed care networks. |
| Platform Modularity Architecture | System versatility across aesthetic and medical indications improves capital equipment utilization rates. |
| Telehealth Triage Platform Integration | AI-assisted image screening captures patient flow ahead of procedural intervention routing. |
| Biofermentation-Derived Excipient Sourcing | REACH-compliant penetration enhancers maintain regulatory compliance without sacrificing topical bioavailability. |
Study Parameters
Initial hypotheses were tested against primary input from dermatology clinic operators, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers, then refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR technical documentation repositories, and clinical trial registries. Bottom-up procedure volume estimates triangulated with top-down market sizing across the analysis window.
Variance-decomposition across treatment modality, application setting, and patient autonomy level shaped the analytical framework. CAGRs derived from segmented procedure volume projections and average revenue per lesion trajectories. Forecast inputs incorporated aging demographic incidence curves, regulatory pathway timelines, and channel shift velocity toward telehealth triage.
Underlying assumptions cover stable Medicare reimbursement parity, EU MDR enforcement continuity, and REACH substance restriction schedules, with deviation risk concentrated in regulatory pathway delays and topical formulation reformulation costs. Practitioners should keep alternative scenarios live as FDA de novo clearance velocity and EU MDR notified body capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Europe Scar Treatment Market
Dermatology
Global Radiodermatitis Market
Dermatology
Acne Vulgaris Treatment Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Erythema Treatment Market
Dermatology
Porokeratosis Treatment Market
Dermatology
Immunodermatology Market
Dermatology
Skin Cancer Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Microdermabrasion Market
Dermatology
US and Canada Skin Cancer Dermatology Market
Dermatology
Pigmented Lesion Treatment Market
Dermatology
Keratoacanthoma Market
Dermatology
Scleroderma Treatment Market
Dermatology
Impetigo Treatment Market