
 Global Skin Rejuvenation Market | 2026-2036
Global Skin Rejuvenation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Skin Rejuvenation Market Foresight
Subscription-based maintenance and software-upgrade programs for energy-based devices is pivoting how capital equipment vendors monetize installed bases. Lumenis leverages remote monitoring and predictive service contracts to sustain recurring revenue streams across its laser and IPL platforms. Alma Lasers competes through region-specific service tiering that anchors long-term client relationships in Asia-Pacific and Latin American markets. Galderma differentiates by bundling consumable replenishment with device leasing, controlling downstream revenue per treatment room.
Skin rejuvenation encompasses non-invasive and minimally invasive procedures that remodel dermal collagen, resurface epidermal layers, or modulate melanin distribution through controlled thermal, mechanical, or chemical injury, typically delivered at wavelengths between 532 nm and 10,600 nm or via fractional microneedle arrays. The primary commercial purpose centers on reversing photodamage, chronological aging, and acne sequelae in outpatient aesthetic settings. Laser devices and radio frequency platforms together occupy the dominant product-type tier, while wrinkle reduction and skin tightening applications generate the deepest margin pools due to repeat-visit scheduling and premium pricing power. Dermatology clinics and medical spas represent the fastest-growing end-user channel as physician supervision requirements tighten for higher-energy modalities.
FDA 510(k) clearance timelines and MDR technical documentation demands in Europe together shape which device innovations reach commercial scale first, filtering smaller entrants from premium segments. ISO 13485 quality management certification and CE marking under the EU Medical Device Regulation govern market access for fractional laser and intense pulsed light systems across OECD jurisdictions. Stakeholders must monitor how national health technology assessment bodies classify aesthetic energy devices—whether as medical equipment or wellness appliances—since this determination unlocks or forecloses reimbursement-adjacent financing channels that drive clinic purchasing decisions.
Market Dynamics
Subscription-based service contracts for energy-based devices are restructuring vendor revenue models away from one-time capital sales toward recurring software, maintenance, and consumable streams.
Growth Catalysts
- MFDS fast-track pathways:South Korea's medical device regulator accelerates domestic manufacturer approvals for fractional laser systems, compressing commercial launch timelines versus OECD averages.
- Dermatology clinic consolidation:United States med-spa chains aggregate procurement under national service agreements, creating volume anchors that stabilize vendor forecasting.
- Radio frequency microneedling:This hybrid modality delivers dermal remodeling at lower thermal thresholds than ablative lasers, expanding treatable patient populations and session frequency.
Market Restraints
- MDR technical documentation:Europe's Medical Device Regulation demands extensive clinical evidence for high-risk energy devices, filtering smaller developers from premium market tiers.
- Consumable cost concentration:Disposable applicators and single-use handpieces tie clinic margins to supplier pricing power, with limited backward integration options.
- Physician supervision mandates:State-level scope-of-practice regulations in the United States restrict technician-operated modalities, constraining throughput in high-volume settings.
Strategic Opportunities
- India's aesthetic clinic penetration:Metro-tier cities show device utilization rates below one-fifth of Seoul levels, presenting whitespace for fractional platform deployment.
- CE mark mutual recognition:Emerging regulatory harmonization between EU MDR and select ASEAN frameworks reduces duplicate certification burdens for export-oriented manufacturers.
- Photobiomodulation convergence:Low-level light therapy integration with existing laser platforms enables post-procedure recovery protocols that differentiate premium service tiers.
Industry Challenges
- ISO 13485 audit backlogs:Certification body capacity constraints delay quality management system approvals, freezing product registrations for 6-12 month intervals.
- Interoperability with legacy EMR:Device data output formats often conflict with established clinic management software, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Skin Rejuvenation Market |
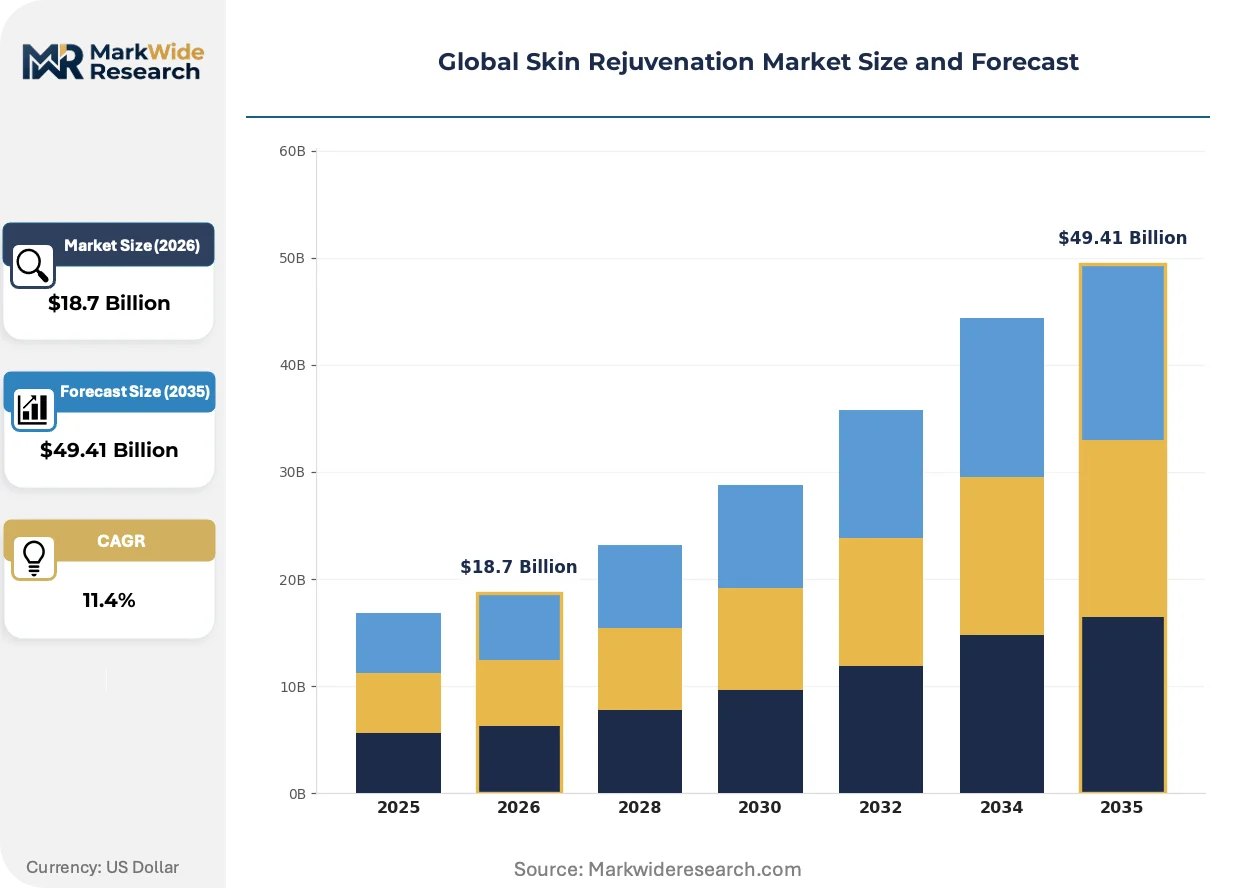
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Ultrasound Therapy, Microdermabrasion Equipment, Chemical Peels, Radio Frequency Devices Application: Wrinkle Reduction, Scar Treatment, Skin Tightening, Pigmentation Correction, Acne Management End User: Dermatology Clinics, Aesthetic Centers, Cosmetic Surgery Facilities, Medical Spas, Beauty Salons Technology: Fractional Laser, Cryotherapy, Intense Pulsed Light, LED Therapy, Microneedling |
| Companies Covered | Lumenis, Galderma, Merz Aesthetics, AbbVie (Allergan), Cutera, Cynosure (Hologic), Alma Lasers, Lutronic, Venus Concept, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Skin Rejuvenation Market Shifts & Advancements
Device intelligence and service unbundling are compressing traditional capital equipment sales cycles while elevating software and consumable attach rates as primary margin drivers.
Artificial intelligence-powered treatment planning is converging with handheld diagnostic imaging to enable real-time parameter adjustment based on individual collagen density mapping. Dermatology networks in Germany and Japan are piloting these systems to standardize outcomes across multi-site operations. This convergence is compressing the training curve for new operators while reducing adverse event liability exposure.
EU MDR recertification deadlines for legacy devices are forcing portfolio rationalization among manufacturers with extensive pre-2021 product lines. Technical file remediation costs are diverting R&D budgets toward highest-revenue platforms. High-intensity focused ultrasound systems face the steepest documentation demands, with several mid-tier suppliers withdrawing from European markets entirely.
Group purchasing organizations now aggregate demand across independent United States med-spas, extracting volume discounts that match national chain pricing. Device vendors respond with tiered service packages that unbundle training, warranty extensions, and software upgrades. This procurement compression is most visible in Texas and Florida, where aesthetic clinic density supports multi-buyer cooperative structures.
Global Skin Rejuvenation Market Segmentation
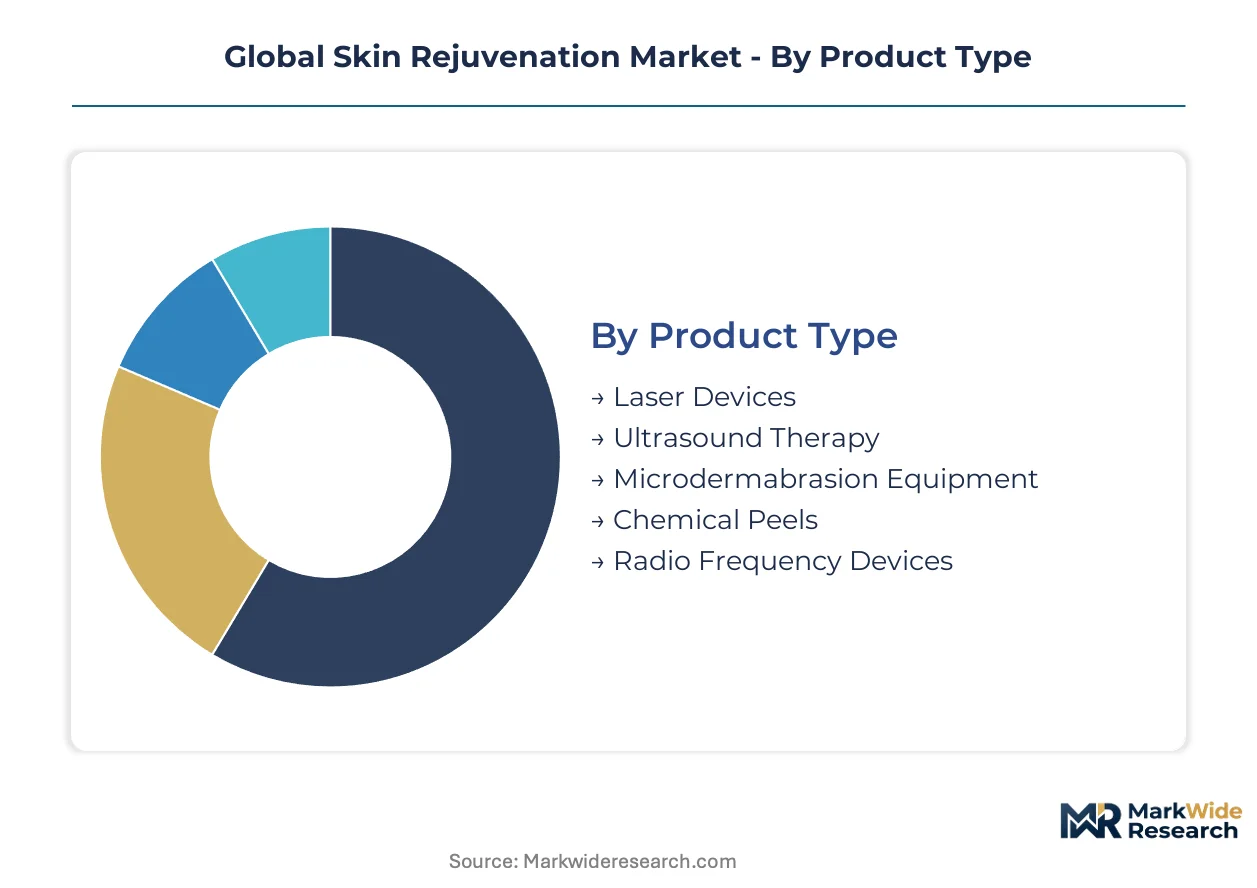
Skin rejuvenation equipment vendors calibrate R&D portfolios and service architectures around how distinct product configurations integrate into clinic workflows. Segmentation clarity determines whether manufacturers pursue capital-intensive platform sales or consumable-heavy recurring models.
Product Type:
Standalone capital platforms dominate high-value procurement cycles, while tabletop and handheld systems embed into broader aesthetic service menus.
- Laser Devices:These systems deliver controlled thermal injury across 532 nm to 10,600 nm wavelengths for collagen remodeling and epidermal resurfacing. Demand concentrates in South Korean dermatology networks where domestic manufacturers compress replacement cycles through aggressive service bundling.
- Radio Frequency Devices:Monopolar and bipolar configurations generate dermal heating at 1-6 MHz frequencies without epidermal ablation. United States med-spa chains anchor volume through national service agreements that prioritize predictable maintenance costs over upfront capital expenditure.
- Ultrasound Therapy:High-intensity focused ultrasound systems target subdermal tissue layers for non-invasive lifting.
- Microdermabrasion Equipment:Mechanical exfoliation platforms using aluminum oxide or diamond-tipped handpieces.
- Chemical Peels:Acid-based formulations for controlled epidermal injury and cell turnover acceleration.
Volume placements concentrate in Laser Devices; the faster expansion belongs to Radio Frequency Devices.
Application:
Procedure frequency and pricing power diverge sharply between maintenance-driven indications and one-time corrective interventions.
- Wrinkle Reduction:Botulinum toxin adjunctive therapies and energy-based collagen stimulation address rhytides across facial and décolletage zones. Repeat-visit scheduling in German dermatology networks sustains premium pricing power through membership-style treatment packages.
- Skin Tightening:Radio frequency and ultrasound modalities contract dermal collagen and stimulate neocollagenesis for laxity correction. Japanese aesthetic clinics report the highest per-capita session frequency among OECD markets, driven by aging demographics and technician-operated device permissiveness.
- Scar Treatment:Fractional laser and microneedling protocols for acne and trauma sequelae.
- Pigmentation Correction:IPL and Q-switched laser systems targeting melanin dysregulation.
- Acne Management:Photodynamic therapy and blue-light protocols for inflammatory lesion control.
Revenue concentration sits with Wrinkle Reduction; Skin Tightening climbs the fastest as non-invasive alternatives displace surgical lifting.
End User:
Regulatory oversight intensity and reimbursement proximity segment buyer sophistication and procurement authority.
- Dermatology Clinics:Physician-supervised facilities with full-scope energy device authorization and malpractice coverage structures. Texas and Florida multi-site operators leverage group purchasing organizations to extract national-chain pricing from vendors.
- Medical Spas:Hybrid aesthetic facilities operating under medical director supervision with expanded technician scope. South Korean chains achieve the highest device utilization rates globally through dense urban clustering and streamlined regulatory pathways.
- Aesthetic Centers:Standalone cosmetic facilities emphasizing non-invasive procedure portfolios.
- Cosmetic Surgery Facilities:Hospital-affiliated or independent surgical practices with ambulatory operating privileges.
- Beauty Salons:Unregulated or minimally regulated establishments limited to superficial modalities.
Procurement volume aggregates at Dermatology Clinics; Medical Spas gain share fastest as supervision mandates tighten selectively.
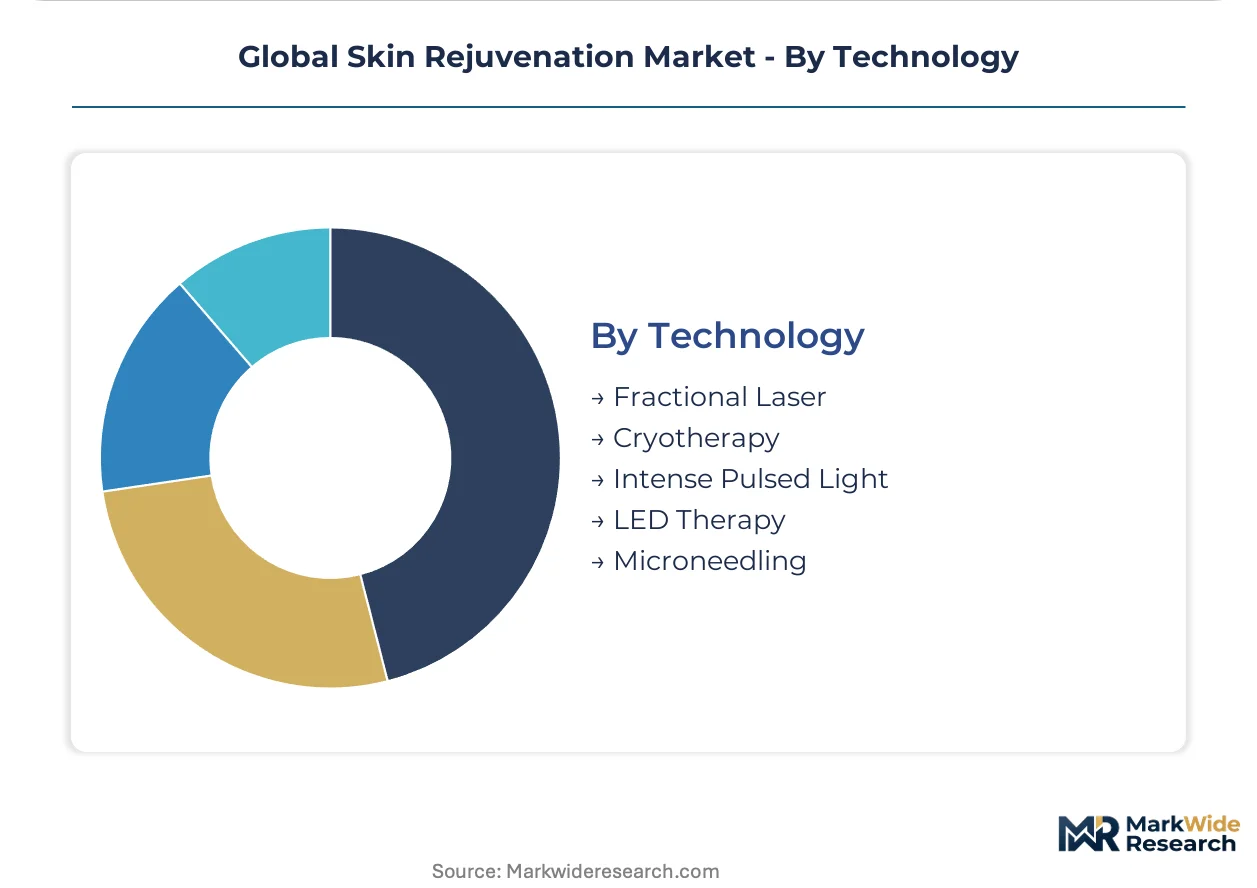
Technology:
Intellectual property density and regulatory clearance complexity stratify competitive moats across technical approaches.
- Fractional Laser:Ablative and non-ablative wavelength delivery through microbeam arrays creates controlled thermal columns while sparing surrounding tissue. FDA 510(k) clearance timelines shape commercial launch sequencing, with fractional CO2 systems facing the steepest clinical evidence demands.
- Microneedling:Percutaneous collagen induction using automated needle arrays with or without radio frequency energy coupling. India's metro-tier cities show utilization rates below one-fifth of Seoul levels, presenting whitespace for fractional platform deployment.
- Intense Pulsed Light:Broad-spectrum flashlamp systems for photorejuvenation and vascular lesion targeting.
- LED Therapy:Low-level light delivery for photobiomodulation and post-procedure recovery.
- Cryotherapy:Controlled cold exposure for epidermal lesion destruction and anti-inflammatory protocols.
Installed base concentration favors Fractional Laser; Microneedling expands most quickly as hybrid radio frequency configurations broaden treatable patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors global procedure density for skin rejuvenation, where Gangnam district alone hosts more aesthetic clinics per square kilometer than any comparable urban cluster worldwide.
United States
Med-spa chains in Texas and Florida drive procurement consolidation through group purchasing organizations that extract national-chain pricing from device vendors. FDA 510(k) clearance pathways for fractional laser systems shape commercial launch sequencing, with ablative modalities facing steeper clinical evidence demands. Dallas and Miami metropolitan areas concentrate the highest device utilization rates as independent clinics form cooperative buying structures.
South Korea
Domestic manufacturers compress replacement cycles through aggressive service bundling in dermatology networks concentrated in Seoul and Busan. MFDS fast-track pathways accelerate approvals for fractional laser systems versus OECD averages. The Seoul Capital Area achieves per-capita procedure volumes above any other national market through dense urban clustering and streamlined regulatory pathways.
Germany
Dermatology networks pilot artificial intelligence-powered treatment planning systems to standardize outcomes across multi-site operations. EU MDR technical documentation demands extensive clinical evidence for high-risk energy devices, filtering smaller developers from premium market tiers. Munich and Frankfurt industrial clusters concentrate technical file remediation expertise as legacy device recertification deadlines approach.
Japan
Aesthetic clinics report the highest per-capita session frequency among OECD markets for skin tightening applications. METI standards govern quality management system certifications that device vendors must obtain for market access. Tokyo and Osaka metropolitan areas concentrate technician-operated device permissiveness that drives aging-demographic demand.
India
Metro-tier cities show fractional platform utilization rates below one-fifth of Seoul levels, presenting whitespace for device deployment. CDSCO regulatory harmonization with select ASEAN frameworks reduces duplicate certification burdens for export-oriented manufacturers. Mumbai and Bangalore clusters concentrate emerging aesthetic clinic penetration as disposable income rises among urban professionals.
Global Skin Rejuvenation Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent revenue models in the skin rejuvenation equipment sector. The market structure concentrates around integrated platform vendors with captive service networks and specialized component suppliers lacking downstream presence. Three archetypes dominate: full-stack device manufacturers with predictive maintenance contracts, consumable-centric bundlers controlling per-treatment economics, and regional specialists leveraging regulatory familiarity for speed-to-market. M&A activity targets software-enabled service platforms, while geographic expansion focuses on emerging clinic networks in underpenetrated metro tiers.
Within the full-stack manufacturer tier, Lumenis and Alma Lasers occupy positions anchored by recurring revenue architectures. Lumenis exemplifies the predictive maintenance archetype through remote monitoring contracts that monetize installed bases beyond initial capital sales. Alma Lasers represents region-specific service tiering that anchors long-term relationships across Asia-Pacific and Latin American markets. Galderma sits within the consumable-bundling archetype, controlling downstream revenue through device leasing structures that tie clinic margins to supplier replenishment schedules.
| Leading Market Players |
|---|
| Lumenis |
| Galderma |
| Merz Aesthetics |
| AbbVie (Allergan) |
| Cutera |
| Cynosure (Hologic) |
| Alma Lasers |
| Lutronic |
| Venus Concept |
| Others |
Supply & Pricing Matrix
Flashlamp crystal and ytterbium fiber laser component indices cascade through fractional platform manufacturing costs, compressing margin structures for mid-tier suppliers while premium vendors absorb volatility through service-contract bundling in South Korean and United States clinic networks.
Pricing Analysis
Margin tightening in standard-tier equipment traces to MFDS-accelerated domestic manufacturer competition in Seoul, where aggressive replacement cycles compress residual value capture. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) clearance tier and predictive maintenance attach rates. Pricing pressure intensifies in consumable-heavy radio frequency segments as group purchasing organizations extract volume parity from independent United States med-spas. Dermatology clinic networks show lowest price sensitivity due to malpractice coverage structures and membership-model pricing power.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and the United States coordinate hub-and-spoke fulfillment for high-value laser resonator assemblies and disposable handpiece consumables. Manufacturing concentration for fractional CO2 laser tubes rests on German and Israeli precision optics clusters, while radio frequency generator modules source from Japanese and Taiwanese electronics hubs. Single-source vulnerability in ytterbium-doped fiber supply creates exposure to rare-earth export restrictions. Distribution runs through manufacturer-direct service engineers for capital platforms, with third-party logistics handling consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification deadlines and technical file remediation costs are forcing portfolio rationalization among manufacturers with extensive pre-2021 product lines, creating acquisition opportunities for well-capitalized consolidators.
For Market Incumbents: To counter mid-tier supplier withdrawal from European markets, pursue backward integration into ytterbium fiber laser component production and expand predictive maintenance contract penetration across Asia-Pacific dermatology networks. Lock in multi-year service agreements with Texas and Florida group purchasing organizations before independent clinic cooperative structures mature. For New Entrants and Emerging Players: Begin with India's metro-tier aesthetic clinic whitespace, where fractional platform utilization rates trail Seoul by over four-fifths and CDSCO regulatory harmonization reduces certification duplication. Target hybrid radio frequency microneedling applications as the fastest-expanding technology segment with lower FDA clinical evidence thresholds than ablative laser systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor software-enabled service platforms with installed base monitoring capabilities in Germany and Japan, where EU MDR compliance costs strain mid-tier manufacturers. Watch for ISO 13485 audit backlog resolution as the inflection signal for frozen product registration pipelines reopening.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR technical file remediation unlocks premium market tier access for compliant platforms. |
| Hospital System Partnership | Dermatology network consolidation in Texas and Florida creates volume anchors for vendor forecasting stability. |
| Software Companion Development | AI-powered treatment planning integration reduces operator training curves and adverse event liability exposure. |
| Reimbursement Strategy | Health technology assessment classification as medical equipment unlocks financing channels for clinic purchasing. |
| Geographic Manufacturing Footprint | Seoul and Busan production clusters leverage MFDS fast-track pathways versus OECD approval timelines. |
Research Methodology
Document review covered FDA 510(k) clearance databases, EU MDR technical file registries, and MFDS approval records, complemented by interviews with dermatology clinic procurement directors, biomedical engineers at multi-site networks, GPO contracts managers, and aftermarket service heads at capital equipment vendors. Secondary sources included hospital procurement databases, customs trade data for laser component imports, and SEC filings from publicly traded aesthetic device manufacturers. Bottom-up equipment shipment data triangulated against top-down clinic penetration estimates across metropolitan clusters.
Historical utilization rates from Seoul, Dallas, and Tokyo clinic networks cross-referenced against panel input from device vendor sales operations to construct procedure frequency models across the projection horizon. Segmentation dimensions encompassed product type, application indication, end-user channel, and technology platform with regional regulatory cluster overlays. CAGRs derived from installed base replacement cycles and consumable attach rate trajectories, incorporating radio frequency microneedling adoption curves and photobiomodulation convergence timing.
Underlying measurement precision varies by segment; laser device placements and South Korean procedure volumes carry tighter precision than emerging market whitespace estimates. Forecasts reflect documented assumptions regarding regulatory pathway timelines, certification body capacity, and clinic consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Skincare Serums Market
Skincare
Skin Barrier Market
Skincare
Body Scrub Market
Skincare
Global Anti-Aging Products and Services Market
Skincare
Facial Mask Market
Skincare
Sheet Face Mask Market
Skincare
Non-Surgical Skin Tightening Market
Skincare
Global Anti-Aging Market
Skincare
Marine Retinol Market
Skincare
Preoperative Skin Preparation Market
Skincare
Rice Water Skincare Market
Skincare
Herbal Skincare Products Market
Skincare
Sensitive Skin Care Products Market
Skincare
Skin Toner Market
Skincare
Ampoule Cream Market
Skincare
Skincare Ingredients Market