
 Microneedling Market | 2026-2036
Microneedling Market Size, Share, and Industry Trends Forecast 2026-2036
Microneedling Market Intelligence
Premium automated devices with integrated radiofrequency and consumable ecosystems is rebalancing against standalone manual rollers and basic pens. Candela Medical leverages its cross-platform aesthetic energy device portfolio to bundle microneedling with laser and RF systems in premium clinic accounts. Lumenis anchors its position through technology leadership in fractional radiofrequency microneedling platforms. Cutera differentiates by competing on physician training intensity and clinical outcome documentation rather than hardware price alone.
Microneedling employs arrays of fine sterile needles, typically 0.5 to 3.0 millimeters in length, to create controlled dermal micro-injuries that trigger collagen and elastin neogenesis for skin remodeling. Automated devices with programmable needle depth and speed parameters now dominate professional settings where precision and reproducibility determine clinical liability exposure. Consumables represent the fastest-expanding margin pool as recurring cartridge sales attach to installed device bases, while at-home users remain a constrained segment due to safety warnings from the FDA and dermatology societies regarding unsupervised deep needling.
The FDA Center for Devices and Radiological Health classifies motorized microneedling products as Class II medical devices requiring 510(k) premarket notification, while the European Medical Device Regulation imposes stricter clinical evidence thresholds for devices claiming therapeutic indications beyond cosmetic enhancement. ISO 13485 quality management certification has become a baseline procurement filter for clinic chains and hospital purchasing committees evaluating vendor qualification. Stakeholders must monitor evolving regulatory distinctions between wellness-grade and medical-grade devices as enforcement actions against uncleared at-home products intensify.
Market Dynamics
Combination protocols integrating radiofrequency energy with microneedling are compressing standalone device margins while expanding addressable treatment indications beyond cosmetic resurfacing into scar revision and hair restoration. This technology convergence is forcing manufacturers to rebuild product architectures around modular platform strategies rather than single-modality hardware.
Growth Catalysts
- Combination Protocol Normalization:Medical aesthetic chains in South Korea have standardized RF-microneedling paired with exosome delivery, establishing clinical efficacy benchmarks that drive equipment refresh cycles in other developed markets.
- FDA 510(k) Pathway Clarity:The FDA Center for Devices and Radiological Health's classification guidance for motorized microneedling systems has reduced regulatory uncertainty, accelerating premarket notification timelines for Class II device submissions.
- Collagen Induction Therapy Expansion:Dermatology clinics are repositioning microneedling as a maintenance modality between energy-based treatments, creating recurring revenue streams that justify premium automated device investments.
Market Restraints
- Consumable Cost Concentration:Single-use needle cartridges represent 60-70% of per-procedure costs for clinic operators, with proprietary cartridge lock-in limiting vendor switching flexibility.
- At-Home Device Safety Enforcement:FDA safety warnings and dermatology society position statements against unsupervised deep needling constrain consumer-grade market expansion.
- Clinical Evidence Thresholds:The European Medical Device Regulation imposes stricter clinical evidence requirements for therapeutic indications, extending time-to-market for devices claiming scar or stretch mark treatment.
Strategic Opportunities
- Men's Aesthetic Underpenetration:Hair restoration applications using microneedling for androgenetic alopecia represent an underserved demographic with distinct marketing and clinical training requirements.
- ISO 13485 Certification Arbitrage:Vendor qualification filters at hospital purchasing committees create competitive separation for manufacturers with established quality management systems.
- Post-Procedure Topical Integration:Device manufacturers can capture value from adjacencies by developing validated consumable ecosystems pairing needles with proprietary serums and recovery formulations.
Industry Challenges
- Physician Training Intensity:Proper technique for variable-depth needling on diverse skin types requires substantial hands-on education, creating bottlenecks for device adoption in mid-tier clinic accounts.
- 510(k) Clearance Timelines:FDA premarket notification review periods for RF-integrated systems extend development cycles and delay revenue recognition for platform upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microneedling Market |
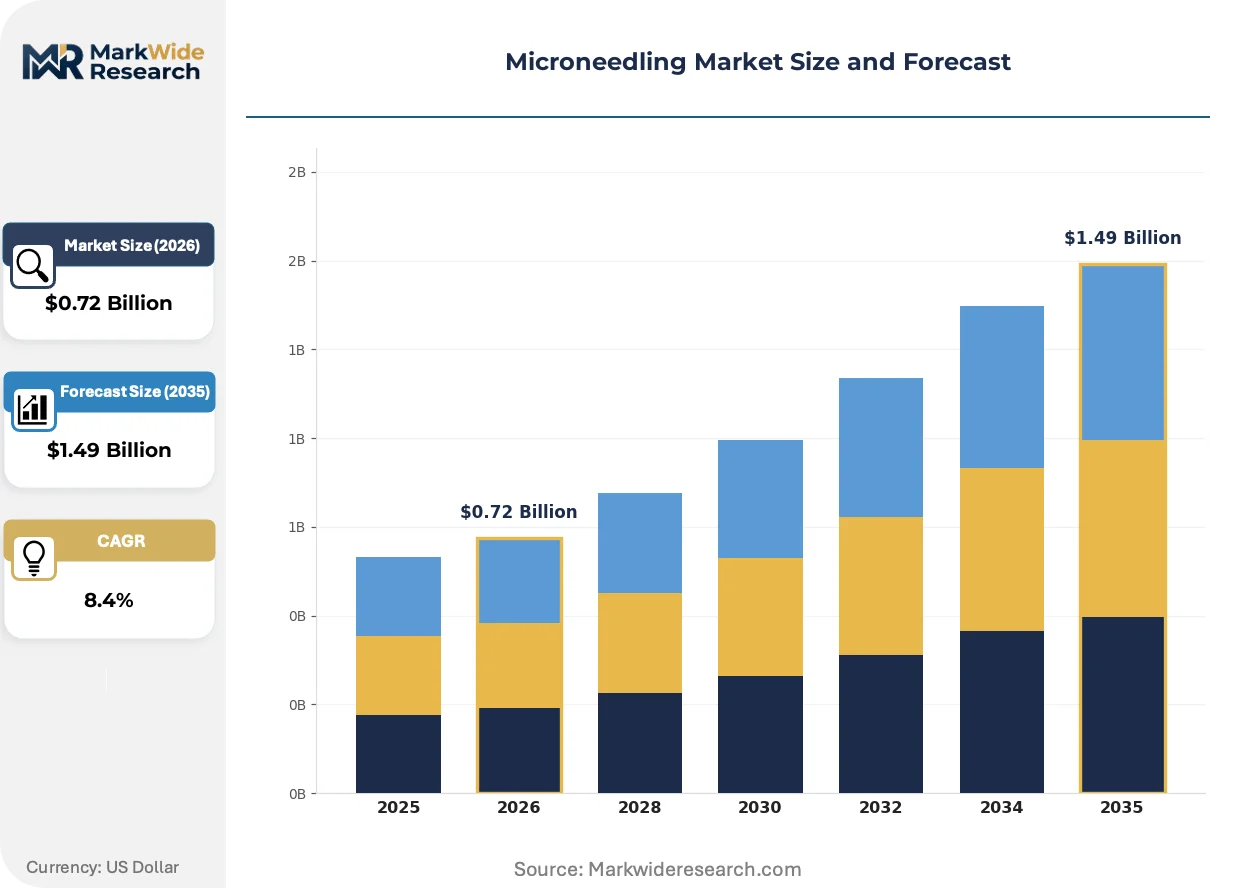
| Market Size in 2026 | $0.72 Billion |
| Market Size in 2035 | $1.49 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Devices, Manual Devices, Combination Devices, Consumables End User: Clinics, Spas, At-Home Users, Hospitals Application: Scar Treatment, Anti-Aging, Skin Rejuvenation, Hyperpigmentation Technology: Radiofrequency, Laser-Assisted, Traditional Microneedling, Microneedling Pens |
| Companies Covered | Candela Medical, Dermaconcepts, Lumenis, Dermapen, Eclipse Aesthetics, Cutera, Endymed Medical, Crown Aesthetics, Cynosure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microneedling Market Strategic Shifts & Innovations
Automated precision control is displacing manual technique dependency across professional microneedling applications. This shift is compressing training variability and enabling standardized outcome documentation that supports reimbursement conversations.
Fractional radiofrequency microneedling is expanding into scar revision and skin laxity applications previously dominated by ablative laser systems. Academic medical centers in Germany and the United States are publishing head-to-head efficacy studies that accelerate physician adoption beyond cosmetic practices. The technology is expanding into hospital-based dermatology departments seeking single-platform solutions for diverse patient populations.
The European Medical Device Regulation's stricter clinical evidence thresholds for therapeutic claims are forcing manufacturers to redesign trial protocols. Devices seeking scar or alopecia indications now require prospective studies with objective endpoints, extending development timelines by 18-24 months. Premium-tier manufacturers with established clinical affairs capabilities are capturing share from competitors reliant on cosmetic-only positioning.
Clinic procurement committees are consolidating vendor relationships around multi-modality platform providers. Single-source contracting for laser, RF, and microneedling systems reduces service contract complexity and training overhead. This concentration is most visible in United States dermatology group practices with 10+ provider locations seeking operational standardization.
Microneedling Market Segmentation
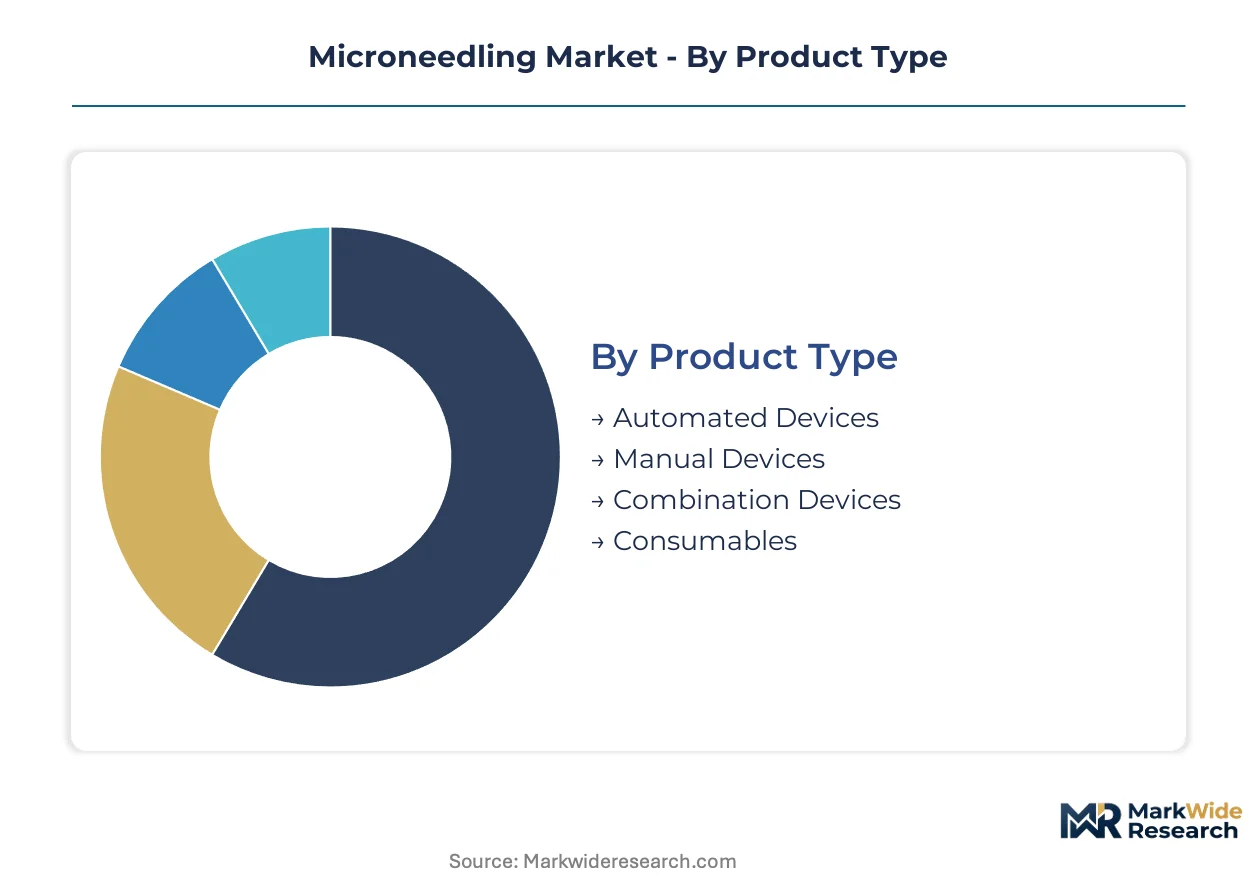
Microneedling market segmentation reveals distinct procurement patterns across professional and consumer channels. Device classification, end-user regulatory exposure, and technology integration intensity create divergent margin profiles that reshape vendor go-to-market priorities.
Product Type:
Professional buyers prioritize precision control and consumable lock-in; at-home users face FDA safety constraints that compress hardware margins.
- Automated Devices:Motorized systems with programmable needle depth and speed parameters dominate dermatology clinics where reproducibility reduces liability exposure. United States medical aesthetic chains favor these platforms for standardized outcome documentation that supports reimbursement conversations.
- Manual Devices:Handheld rollers with fixed needle arrays serve budget-conscious spa operators and emerging market clinics. Demand concentrates in Southeast Asia where capital constraints outweigh precision requirements.
- Combination Devices:Integrated radiofrequency-microneedling platforms from Lumenis and Candela Medical expand into scar revision applications.
- Consumables:Single-use needle cartridges generate recurring revenue streams with 60-70% per-procedure cost concentration for clinic operators.
Automated devices lead volumes today; combination devices are gaining share fastest.
End User:
Regulatory classification intensity separates institutional buyers from consumer segments.
- Clinics:Dermatology and medical aesthetic practices drive premium device adoption through combination protocol normalization. South Korean clinic chains have standardized RF-microneedling with exosome delivery, establishing clinical benchmarks that accelerate equipment refresh cycles in Germany and the United States.
- Hospitals:Academic medical centers in the United States and Germany publish head-to-head efficacy studies that validate fractional RF microneedling for scar revision, expanding hospital-based dermatology department procurement.
- Spas:Wellness-oriented operators in California and Florida purchase manual devices or entry-level automated pens to avoid FDA Class II medical device compliance costs.
- At-Home Users:FDA safety warnings and dermatology society position statements against unsupervised deep needling constrain this segment's expansion despite consumer marketing efforts.
Clinics lead volumes today; hospitals are climbing the fastest.
Application:
Clinical evidence thresholds vary sharply across cosmetic versus therapeutic indications.
- Scar Treatment:Acne and surgical scar revision applications require prospective studies with objective endpoints under European Medical Device Regulation guidelines, extending development timelines. German academic centers lead outcome documentation that supports therapeutic positioning.
- Anti-Aging:Collagen induction therapy for fine lines and wrinkles represents the most mature application with established reimbursement codes in United States dermatology practices.
- Skin Rejuvenation:Maintenance protocols between energy-based treatments create recurring revenue streams that justify premium automated device investments.
- Hyperpigmentation:Melasma and post-inflammatory hyperpigmentation treatments require variable-depth technique expertise that concentrates demand in specialized dermatology clinics.
Anti-aging leads volumes today; scar treatment shows steepest expansion trajectory.
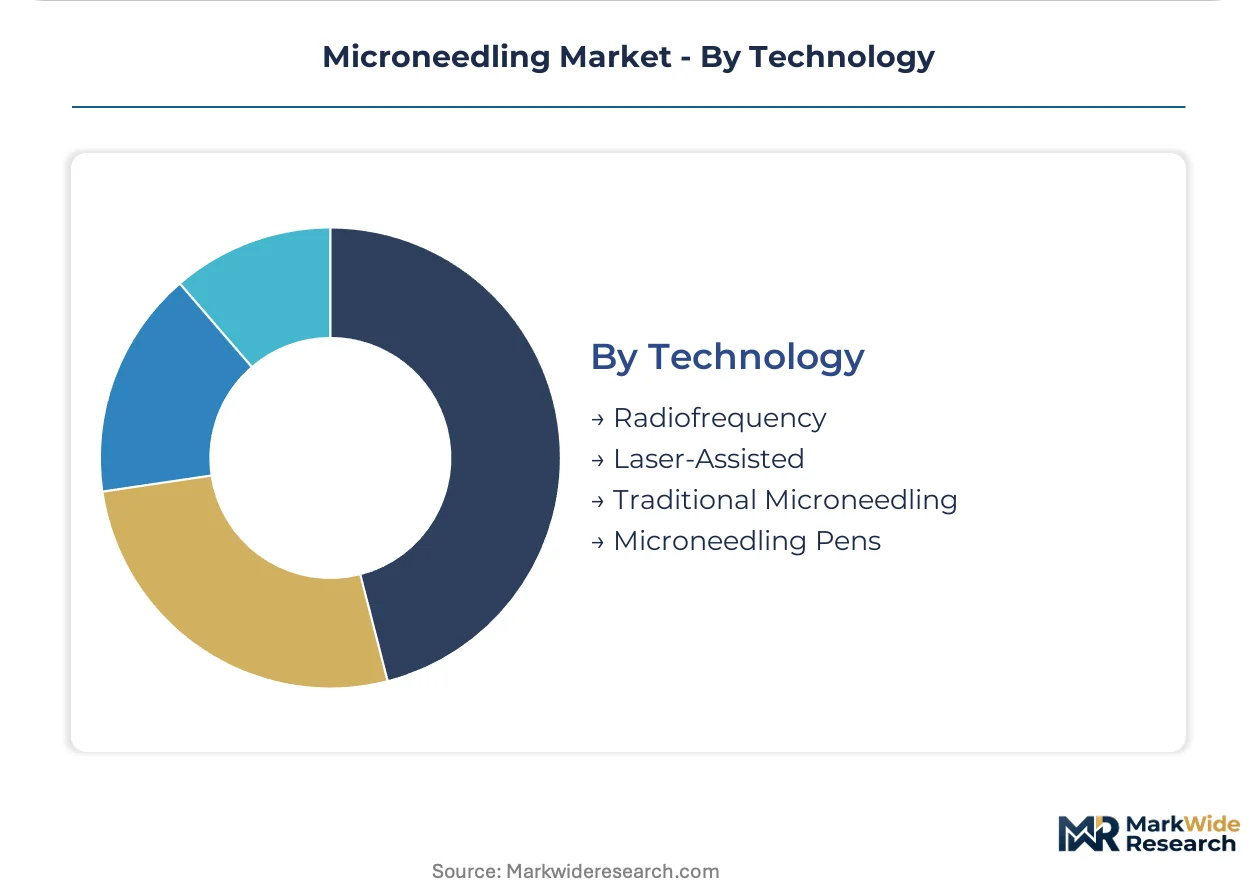
Technology:
Energy integration intensity determines platform architecture and regulatory pathway complexity.
- Radiofrequency:Fractional RF microneedling from Lumenis and Candela Medical displaces ablative laser systems in scar revision and skin laxity applications. United States hospital-based dermatology departments adopt these platforms as single-modality solutions for diverse patient populations.
- Traditional Microneedling:Needle-only systems without energy delivery serve price-sensitive clinic segments and training institutions where technique fundamentals remain prioritized.
- Laser-Assisted:Hybrid platforms combining microneedling with fractional laser energy face extended FDA 510(k) review timelines that delay revenue recognition.
- Microneedling Pens:Handheld automated devices with disposable cartridges dominate mid-tier clinic accounts seeking precision without multi-modality platform investment.
Traditional microneedling leads volumes today; radiofrequency platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatology-trained practitioners cluster in Seoul, Los Angeles, and Munich, anchoring procedural innovation and device procurement intensity across three continents.
United States
FDA 510(k) clearance pathways for Class II motorized devices concentrate development activity in Massachusetts and California medical device corridors. The Center for Devices and Radiological Health's classification guidance accelerates premarket timelines for RF-integrated systems. Academic medical centers in Boston and Stanford publish head-to-head efficacy studies that validate fractional radiofrequency microneedling for scar revision.
South Korea
Medical aesthetic chains in Gangnam and Seongnam have normalized combination protocols pairing microneedling with exosome delivery, establishing clinical benchmarks that drive equipment refresh cycles. The Ministry of Food and Drug Safety enforces medical device licensing for therapeutic indication claims. Seoul-based clinic networks export training protocols to Southeast Asian markets, extending Korean clinical influence.
Germany
ISO 13485-certified manufacturers in Baden-Württemberg and Bavaria supply precision needle cartridges to European clinic chains. The European Medical Device Regulation imposes stricter clinical evidence thresholds for scar and alopecia indications, extending development timelines by 18-24 months. Heidelberg and Munich university hospitals lead prospective outcome documentation that supports therapeutic positioning.
China
Domestic device manufacturers in Shenzhen and Suzhou compete on automated pen platforms for mid-tier clinic accounts. The National Medical Products Administration classifies motorized microneedling systems as Class II medical devices requiring registration. Shanghai dermatology departments adopt combination protocols from Korean training partnerships, accelerating RF-microneedling penetration.
Australia
Therapeutic Goods Administration oversight concentrates professional device distribution in Sydney and Melbourne dermatology networks. The TGA's medical device framework distinguishes wellness-grade from therapeutic-grade microneedling claims, shaping vendor qualification requirements. Queensland clinic chains source consumables through established relationships with German and Korean suppliers.
Microneedling Market Key Industry Players
Top-tier vendors anchor multi-modality platform strategies, while mid-tier specialists compete on consumable ecosystems and training intensity. The vendor base stratifies across premium RF-integrated systems, precision automated pens, and manual roller suppliers serving price-sensitive segments. Energy-integrated platform providers and consumable-centric specialists represent the dominant strategic archetypes. Competitive moves concentrate on modular platform architecture rebuilds and proprietary cartridge lock-in mechanisms that limit vendor switching.
Within the premium multi-modality tier, Candela Medical and Lumenis occupy positions exemplifying cross-platform aesthetic energy bundling. Cutera sits within the training-intensive differentiation archetype, competing on physician education and clinical outcome documentation rather than hardware price positioning. These three companies represent contrasting approaches to capturing value in a market where consumable recurring revenue increasingly determines vendor profitability.
| Leading Market Players |
|---|
| Candela Medical |
| Dermaconcepts |
| Lumenis |
| Dermapen |
| Eclipse Aesthetics |
| Cutera |
| Endymed Medical |
| Crown Aesthetics |
| Cynosure |
| Others |
Cost & Logistics Intelligence
Radiofrequency-integrated platform architectures are compressing standalone device margins while simultaneously concentrating supply relationships around multi-modality vendors with captive consumable ecosystems. This technological shift forces mid-tier manufacturers to choose between premium platform investments and margin erosion in needle-only segments.
Pricing Analysis
The bundled-versus-unbundled service split separates clinic procurement into subscription-style consumable contracts versus capital equipment purchases. Pricing stratifies across premium RF-integrated platforms, standard automated pens, and economy manual rollers, with ISO 13485 certification and FDA 510(k) clearance acting as primary price differentiation drivers. Pricing pressure stems from proprietary cartridge lock-in mechanisms that limit vendor switching flexibility. Budget-conscious spa operators in Southeast Asia exhibit highest price sensitivity, while United States dermatology group practices prioritize clinical liability reduction over hardware cost.
Supply Chain Analysis
Dual-sourcing requirements from hospital purchasing committees in Germany and the United States mandate multi-supplier qualification for precision needle cartridges. Manufacturing concentrates in Baden-Württemberg for ISO-certified consumables, South Korea for RF-integrated platform assembly, and Shenzhen for automated pen components. Supply chains draw from medical-grade stainless steel feedstock, biocompatible polymer housings, and RF generator subassemblies. Single-source vulnerability concentrates in proprietary cartridge electronics. Distribution runs through authorized medical device distributors serving clinic chains and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by recurring consumable revenue streams that attach to installed device bases across dermatology practices. The normalization of combination protocols sustains equipment refresh cycles independent of macroeconomic volatility.
For Market Incumbents: Anchor defensive positioning through backward integration into precision needle cartridge manufacturing and exclusive GPO contracts with United States dermatology group practices. The threat of modular platform competitors from Korean medical aesthetic chains demands investment in ISO 13485-certified quality systems as a procurement filter. Captive consumable ecosystems represent the priority lever for margin defense.
For New Entrants and Emerging Players: The price-point gap between premium RF-integrated systems and economy manual rollers opens white-space opportunity in mid-tier automated pens with programmable depth control. Hair restoration applications for androgenetic alopecia represent the most penetrable segment, with distinct clinical training requirements that favor specialized entrants. A go-to-market angle through Korean training protocol partnerships accelerates credibility in Asian markets.
For Investors and Strategic Acquirers: Roll-up economics work for consumable-centric specialists because recurring cartridge revenue generates predictable cash flows with low customer acquisition costs relative to capital equipment. The five-to-ten year viability window favors manufacturers with established clinical affairs capabilities for therapeutic indication claims. Acquisition targets should demonstrate FDA 510(k) clearance momentum or CE marking pathway progress. The signal to watch is enforcement action velocity against uncleared at-home devices, which would accelerate professional channel concentration.
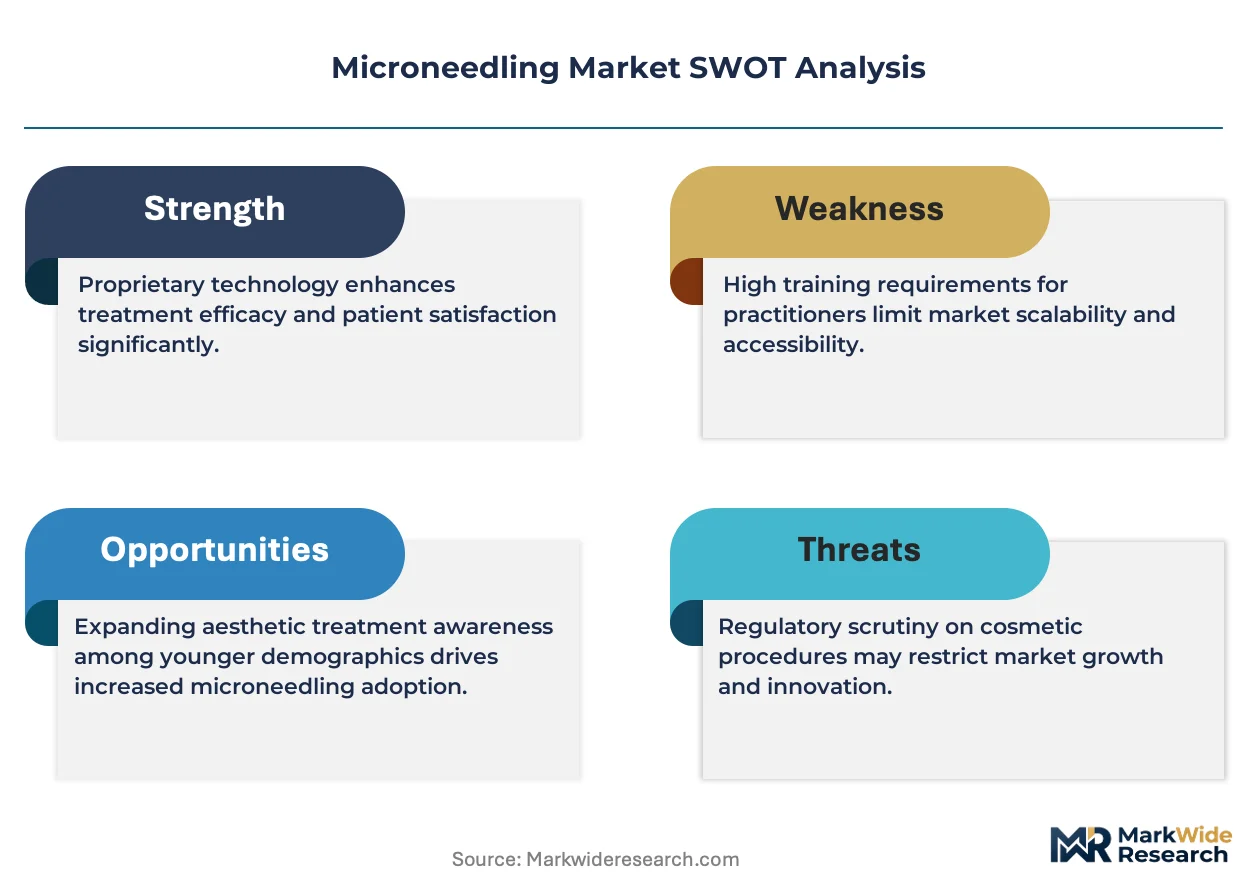
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Class II clearance for motorized RF-integrated systems accelerates United States market access timelines. |
| Hospital System Partnership | Academic medical center validation studies expand scar revision applications beyond cosmetic practices. |
| Software Companion Development | Outcome documentation platforms support reimbursement conversations with United States dermatology payers. |
| CE Marking Pathway | European Medical Device Regulation compliance enables therapeutic indication claims in Germany and France. |
| Reimbursement Strategy | Category III CPT code establishment for collagen induction therapy stabilizes procedure economics. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic directors, biomedical engineers at device manufacturers, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA 510(k) filings, European Medical Device Regulation submissions, hospital procurement databases, and ISO 13485 certification registries. Bottom-up device shipment analysis and top-down aesthetic procedure volume estimates were triangulated to anchor market sizing.
Segment-weighting approaches distributed value across product type, end user, application, and technology dimensions throughout the forecast period. CAGRs were derived from procedure volume elasticity models and equipment replacement cycle analysis. Key inputs included dermatology practice expansion rates in South Korea and the United States, RF-integrated platform adoption curves in academic medical centers, and consumable attach rates per installed device base.
Caveats apply where regulatory enforcement intensity against at-home devices or European clinical evidence requirement changes could materially shift the outlook. Forecasts reflect documented assumptions about procedure reimbursement stability and Korean clinical protocol export velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Global Radiodermatitis Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Dermabrasion Market
Dermatology
Common Warts Market
Dermatology
Erythema Treatment Market
Dermatology
UK Scar Treatment Market
Dermatology
Dermal Facial Fillers Market
Dermatology
Skin Hyperpigmentation Treatment Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Psoriasis Treatment Market
Dermatology
Androgenetic Alopecia Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Australia Skin Laser Market
Dermatology
Telogen Effluvium Treatment Market
Dermatology
Derma Rollers Market
Dermatology
Dermatology Drugs Market