
 Lyme Disease Treatment Market | 2026-2036
Lyme Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lyme Disease Treatment Market Analysis
Post-acute care revenue is tilting toward specialized infectious disease clinics managing persistent Lyme symptomatology. Pfizer Inc. leverages its established antibiotic manufacturing scale to sustain supply contracts across North American hospital networks. GlaxoSmithKline plc anchors its position through vaccine development pipelines targeting Borrelia burgdorferi prevention. Sanofi S.A. competes in the European therapeutic market with differentiated intravenous delivery formulations.
Lyme disease treatment encompasses pharmaceutical and non-pharmaceutical interventions targeting infection by Borrelia burgdorferi sensu lato complex spirochetes transmitted through Ixodes tick vectors, with doxycycline, amoxicillin, and ceftriaxone constituting first-line pharmaceutical protocols based on disease stage and patient tolerability profiles. The primary purpose centers on eliminating active infection, preventing disseminated manifestations including neurological and cardiac complications, and managing post-treatment symptom persistence. Antibiotics occupy the dominant value share across product type segmentation due to established clinical efficacy in early-stage disease and broad prescriber familiarity. Intravenous delivery mode categories capture premium pricing concentration as hospital-administered ceftriaxone protocols address neurologic involvement and treatment-refractory presentations.
FDA oversight shapes antibiotic approval pathways and post-market surveillance for Lyme therapeutics, while CDC epidemiological reporting standards influence diagnostic protocol adoption and treatment initiation thresholds across US clinical settings. EMA frameworks governing orphan drug designation and infectious disease therapeutics condition market access timelines for European developers. Stakeholders must monitor evolving vector range expansion patterns and corresponding shifts in endemic zone designation that will reshape patient access infrastructure and reimbursement geography.
Market Dynamics
Vector range expansion and shifting endemic zone designations are restructuring patient access infrastructure and reimbursement geography across the Lyme disease treatment landscape. FDA guidance revisions on persistent symptom management are compressing protocol standardization timelines while amplifying demand for specialized infectious disease clinic capacity.
Growth Catalysts
- CDC Surveillance Expansion:Enhanced epidemiological reporting standards are elevating diagnostic protocol adoption rates and compressing treatment initiation thresholds across US clinical settings.
- Specialized Clinic Infrastructure:Post-acute care revenue migration toward infectious disease clinics managing persistent Lyme symptomatology is expanding service capacity and prescriber specialization.
- Vector Ecology Shifts:Ixodes tick habitat expansion into previously non-endemic US counties is generating new patient populations and first-time diagnosis incidence.
Market Restraints
- Antibiotic Supply Concentration:Ceftriaxone API manufacturing concentrates in a limited number of contract manufacturers, exposing hospital networks to single-source vulnerability.
- Diagnostic Uncertainty:Serological test interpretation variability creates treatment delay friction and amplifies misdiagnosis rates in early-stage presentations.
- Reimbursement Compression:Persistent symptom management protocols face coverage denials from commercial payers, limiting patient access to extended antibiotic courses.
Strategic Opportunities
- Preventive Vaccine Development:EMA orphan drug designation pathways for Borrelia burgdorferi vaccines are accelerating European market access timelines for developers.
- Telemedicine Integration:Rural and semi-rural geographies with emerging vector exposure are adopting remote infectious disease consultation for diagnosis and treatment monitoring.
- Intravenous Formulation Innovation:Outpatient infusion center networks are capturing hospital-displaced ceftriaxone administration, creating new channel economics.
Industry Challenges
- Specialist Workforce Scarcity:Infectious disease physician training pipeline constraints limit clinic expansion capacity in high-incidence Northeast corridor states.
- Protocol Standardization Delays:Persistent symptom etiology disputes between IDSA and ILADS guidelines create prescriber confusion and liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lyme Disease Treatment Market |
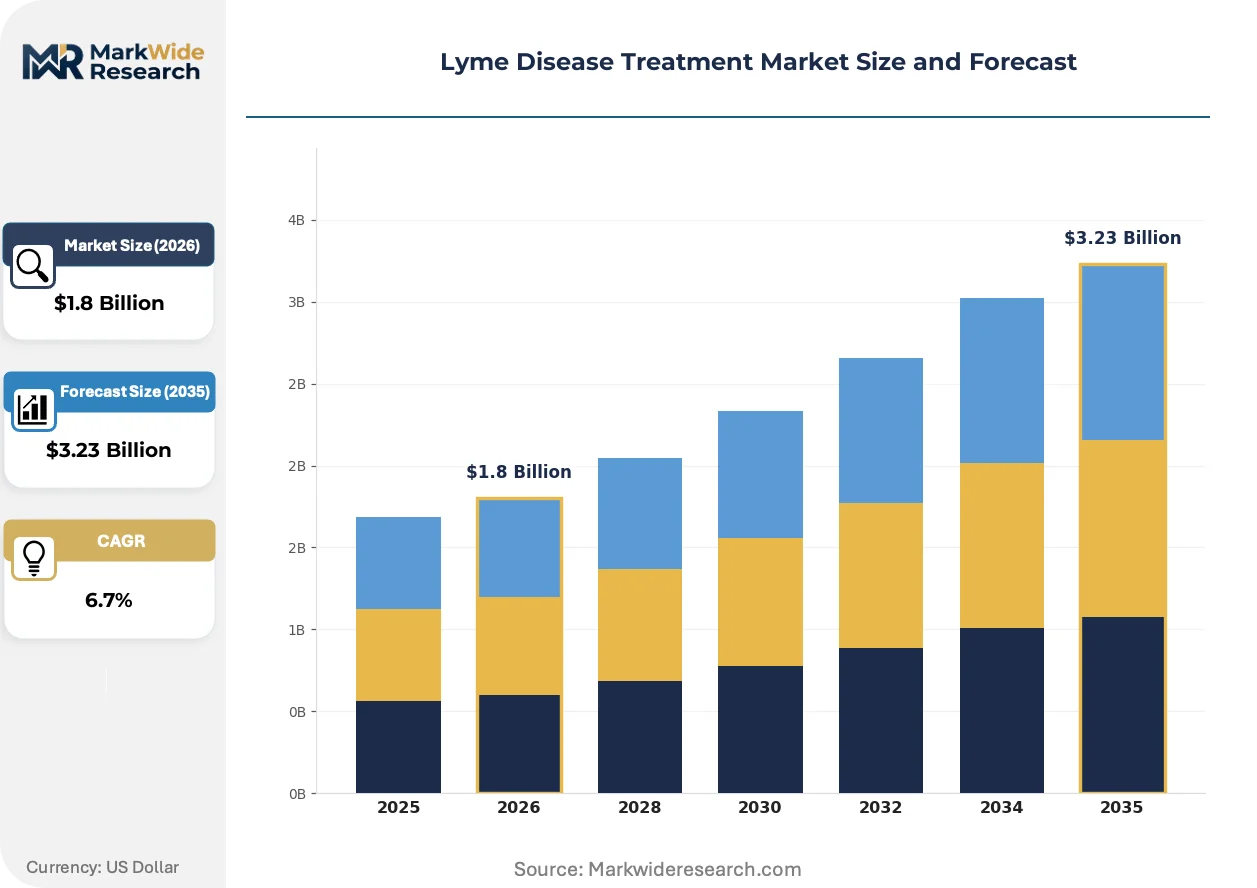
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Herbal Treatments, Homeopathic Remedies Delivery Mode: Oral, Intravenous, Topical, Injectable End User: Hospitals, Clinics, Home Healthcare, Pharmaceutical Companies Therapy Area: Infectious Diseases, Immunology, General Practice, Complementary Medicine |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Sanofi S.A., Novartis AG, AbbVie Inc., Merck & Co., Inc., Roche Holding AG, Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lyme Disease Treatment Market Emerging Trajectories
Diagnostic methodology and care delivery models are undergoing parallel transformation as vector-borne disease complexity outpaces legacy clinical infrastructure. Technology convergence, regulatory pathway evolution, and patient access restructuring are the dominant forces reshaping competitive positioning.
Multiplex molecular diagnostic platforms are migrating from reference laboratory settings to point-of-care deployment in urgent care and primary care clinics. These platforms enable simultaneous Borrelia species detection and coinfection screening, compressing time-to-diagnosis from weeks to hours. Early-adopter health systems in New York and Massachusetts are integrating these tools into emergency department triage protocols.
FDA guidance on persistent Lyme symptom management is reshaping clinical trial endpoint definitions and post-market surveillance requirements for antibiotic developers. The agency's 2024 draft guidance on patient-reported outcome measures is forcing protocol redesign for late-stage infectious disease therapeutics. Sponsors are responding by incorporating quality-of-life metrics into registrational studies.
Patient navigation toward specialized infectious disease clinics is displacing general practitioner management for complex or recurrent presentations. This channel shift concentrates revenue in academic medical center networks with established Lyme disease research programs. The pattern is most visible in Connecticut and New Jersey, where referral density correlates with endemic county designation.
Lyme Disease Treatment Market Segmentation
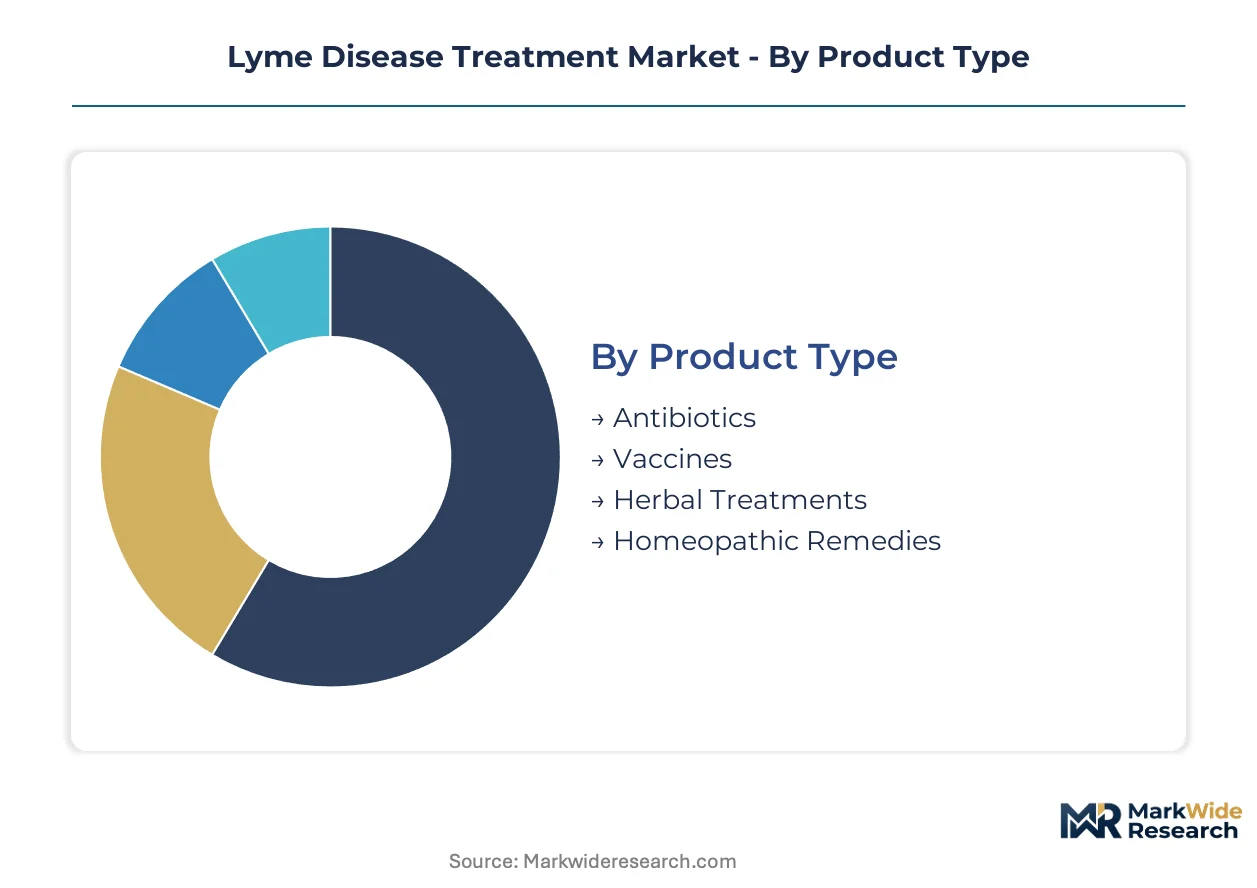
Lyme disease treatment pathways diverge sharply across patient acuity, disease stage, and care setting economics. Segmentation reveals how antibiotic protocols anchor hospital revenue while emerging channels reshape access geography.
Product Type:
Clinical protocols span pharmaceutical interventions to alternative modalities, with reimbursement eligibility and evidence standards determining channel viability.
- Antibiotics:Doxycycline, amoxicillin, and ceftriaxone formulations constitute first-line pharmaceutical protocols. Hospital networks in Connecticut and New York concentrate procurement contracts for intravenous ceftriaxone, driven by neurologic involvement cases requiring inpatient administration.
- Vaccines:Preventive immunization candidates target Borrelia burgdorferi surface proteins. EMA orphan drug designation pathways are accelerating European access timelines for developers, with clinical endpoints shifting toward quality-of-life metrics under FDA guidance.
- Herbal Treatments:Botanical protocols including Japanese knotweed and cat's claw extracts serve patients outside reimbursed pharmaceutical pathways.
- Homeopathic Remedies:Highly diluted preparations occupy non-prescription channels with minimal clinical evidence requirements.
The dominant share belongs to Antibiotics, while Vaccines is closing the gap fastest.
Delivery Mode:
Administration route selection hinges on disease dissemination stage, CNS involvement, and outpatient infusion network availability.
- Oral:Doxycycline and amoxicillin tablets dominate early-stage ambulatory care. Primary care prescribers in Massachusetts and Pennsylvania favor this route for erythema migrans presentations without systemic symptoms.
- Intravenous:Hospital-administered ceftriaxone captures premium pricing for neurologic and cardiac manifestations. Outpatient infusion centers in New Jersey are displacing hospital-based administration, creating new channel economics.
- Topical:Limited application for localized symptom management in adjunctive care settings.
- Injectable:Intramuscular formulations serve specific compliance-challenged populations.
Oral administration commands volume leadership, though Intravenous delivery expands most quickly through infusion center decentralization.
End User:
Care setting migration reflects symptom complexity, specialist availability, and reimbursement policy divergence.
- Hospitals:Acute inpatient units manage disseminated disease with neurologic or cardiac complications. Academic medical centers in endemic counties anchor referral networks for complex presentations.
- Clinics:Specialized infectious disease clinics capture post-acute revenue for persistent symptom management. IDSA-ILADS protocol disputes create prescriber liability exposure in this channel.
- Home Healthcare:Nursing services support prolonged oral antibiotic courses for mobile patients.
- Pharmaceutical Companies:Internal R&D and manufacturing operations constitute captive demand for clinical trial materials.
Hospitals retain the largest service volume, yet Clinics gain share fastest through specialized infectious disease capacity expansion.
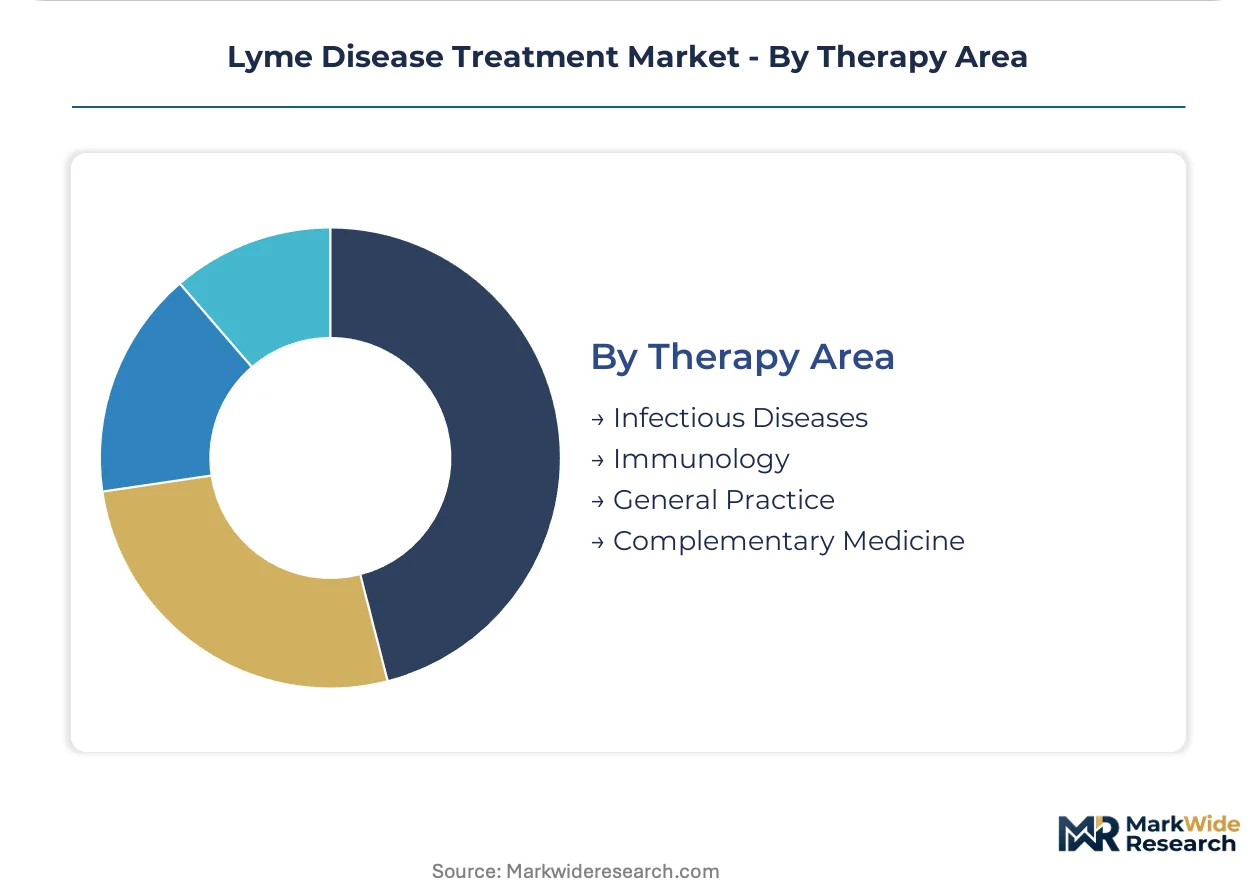
Therapy Area:
Specialty designation determines prescriber credentialing requirements and payer prior authorization thresholds.
- Infectious Diseases:Board-certified specialists manage refractory and recurrent presentations. Workforce scarcity in the Northeast corridor limits clinic expansion capacity.
- Immunology:Autoimmune mechanism hypotheses drive research program investment at academic institutions.
- General Practice:Primary care physicians initiate majority of early-stage treatment in low-incidence counties.
- Complementary Medicine:Naturopathic and integrative practitioners serve patients seeking alternatives to prolonged antibiotic courses.
Infectious Diseases holds the dominant clinical position, while Immunology climbs fastest through mechanistic research investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between established endemic corridors and emerging exposure zones, with the United States Northeast concentrating intravenous antibiotic administration while European markets prioritize preventive vaccine development and German outpatient infusion networks expand capacity.
United States
The Northeast corridor from Connecticut through New York anchors hospital-based ceftriaxone demand for neurologic Lyme presentations. FDA draft guidance on persistent symptom management is compressing clinical trial timelines for late-stage therapeutics. Boston and New York academic medical centers concentrate specialized infectious disease clinic capacity for post-acute revenue capture.
Germany
Outpatient infusion center networks in Bavaria and North Rhine-Westphalia are displacing hospital-administered antibiotic protocols for disseminated disease. EMA orphan drug designation pathways accelerate European vaccine developer access timelines. The Munich-Düsseldorf corridor anchors specialized infectious disease physician training programs addressing workforce scarcity constraints.
Switzerland
Basel and Zurich pharmaceutical clusters concentrate Borrelia vaccine R&D investment targeting surface protein immunization. Swissmedic oversight shapes clinical endpoint definitions for quality-of-life metrics in registrational studies. The country's cantonal health systems pilot telemedicine integration for rural vector exposure consultation.
United Kingdom
Scottish Highlands and Southern England counties report expanding Ixodes habitat generating first-time diagnosis incidence. NHS England reimbursement protocols for extended antibiotic courses face coverage compression for persistent symptom management. London teaching hospitals anchor referral networks for complex neurologic presentations requiring specialist intervention.
Canada
Ontario and Quebec public health agencies track vector range expansion into previously non-endemic counties. Health Canada regulates diagnostic test kit approval pathways while provincial formularies determine antibiotic reimbursement eligibility. Toronto and Montreal academic centers coordinate with US Northeast clinics on persistent symptom protocol standardization.
Lyme Disease Treatment Market Vendor Landscape
Capability concentration sits with research-intensive vaccine developers; scale advantage sits with established antibiotic manufacturers. The market structures around three tiers: multinational pharmaceutical conglomerates with infectious disease portfolios, specialized biotech vaccine developers, and generic antibiotic suppliers. Strategic moves center on preventive immunization pipeline advancement and intravenous formulation delivery network partnerships.
Among US-based pharmaceutical conglomerates, Pfizer Inc. and Johnson & Johnson occupy positions anchoring hospital antibiotic supply contracts across North American networks. European players GlaxoSmithKline plc and Sanofi S.A. exemplify the vaccine development archetype targeting Borrelia burgdorferi prevention through EMA-accelerated pathways. These four entities represent the dominant competitive anchors shaping R&D investment allocation and regional market access strategies.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Sanofi S.A. |
| Novartis AG |
| AbbVie Inc. |
| Merck & Co., Inc. |
| Roche Holding AG |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency for ceftriaxone API manufacturing in Indian and Chinese contract facilities determines both the premium pricing spreads for intravenous formulations and the vulnerability profile of North American hospital networks. This concentration forces procurement teams to balance long-term supply security against spot-market exposure for critical infectious disease therapeutics.
Pricing Analysis
Long-term offtake contracts dominate hospital network procurement for intravenous ceftriaxone, insulating acute-care buyers from spot volatility while compressing margins for generic suppliers. Three-tier pricing structure across premium branded, standard generic, and economy volume-tier formulations separates academic medical centers from community hospitals and outpatient infusion centers. Pricing pressure stems from formulary tier compression at CMS and commercial payers, with outpatient infusion networks exhibiting highest price sensitivity due to thin per-dose economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for doxycycline and amoxicillin active pharmaceutical ingredients. Manufacturing concentrates in India, China, and Italy for oral antibiotic formulations, with sterile injectable capacity anchored in the United States and Germany. Raw material dependencies include corn-derived fermentation feedstocks, specialized borosilicate vial glass, and cold-chain logistics infrastructure. Distribution runs through pharmaceutical wholesale networks with regional distribution center stocking patterns shaped by CDC endemic zone designations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lyme disease treatment market functions as a defensive-moat structure where FDA approval pathways and prescriber familiarity with established antibiotic protocols create substantial switching costs for hospital formulary committees.
For Market Incumbents: Harden supply chain resilience through backward integration into sterile injectable manufacturing or captive API sourcing from Indian facilities with FDA establishment inspection history. Lock in academic medical center formulary placement through infectious disease fellowship program sponsorships that shape future prescriber preferences. The priority threat is emerging European vaccine developers capturing prevention-oriented patient populations through EMA-accelerated pathways. For New Entrants and Emerging Players: Rural and semi-rural counties in Pennsylvania and Ohio experiencing first-time vector exposure represent the most penetrable geography for telemedicine-integrated infectious disease consultation platforms. Outpatient infusion center networks in secondary metropolitan markets offer channel white space for intravenous antibiotic administration alternatives. A direct-to-employer contracting model bypassing traditional payer prior authorization friction captures self-insured regional health systems. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized infectious disease clinic platforms with established Lyme research programs and payer contract density. Long-term viability hinges on positioning for post-acute symptom management revenue as FDA guidance reshapes reimbursement eligibility. The signal to watch is CDC surveillance expansion into previously non-endemic counties, which would inflect addressable patient population estimates.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Late-stage vaccine candidates targeting Borrelia surface proteins require FDA endpoint alignment with quality-of-life metrics. |
| Regulatory Approval Pathway | EMA orphan drug designation accelerates European market access timelines for preventive immunization developers. |
| Manufacturing Scale-Up | Sterile injectable capacity expansion in Germany addresses ceftriaxone supply concentration risk for hospital networks. |
| Hospital System Partnership | Academic medical center alliances in Connecticut anchor referral density for complex neurologic Lyme presentations. |
| Reimbursement Strategy | Prior authorization pathway redesign for persistent symptom protocols unlocks commercial payer coverage expansion. |
Methodological Framework
A standing panel of infectious disease specialists, hospital pharmacy directors, and payer formulary managers provided ongoing calibration across the primary research phase. Drug development executives at vaccine developers and regulatory affairs leads at antibiotic manufacturers contributed pipeline visibility and approval timeline assessments. Secondary validation drew from FDA Orange Book filings, EMA assessment reports, ClinicalTrials.gov registry entries, and CDC epidemiological surveillance databases. Bottom-up patient incidence modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Scenario-bracketing around vector range expansion velocity and FDA guidance finalization shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include disease stage, administration route, care setting economics, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation and therapeutic protocol adoption curves. Forecast inputs incorporated Ixodes habitat migration patterns from entomological surveillance and hospital discharge data for neurologic Lyme-coded diagnoses.
The forecast holds incumbent behavior within observed patterns; aggressive moves by European vaccine developers or disruptive telemedicine platforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market
Medical Treatment
Radiotherapy Induced Oral Mucositis Treatment Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Cholera Treatment Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Vaginitis Treatment Drugs Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Chagas Disease Treatment Market