
 Europe Medical Aesthetic Devices Market | 2026-2036
Europe Medical Aesthetic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Aesthetic Devices Market Foresight
Dermatology centers is restructuring the European channel mix as physician-owned clinics displace hospital outpatient departments for elective aesthetic procedures. Merz Pharma anchors its position through deep specialization in neurotoxin and filler portfolios across German-speaking markets. Lumenis Inc competes by sustaining technology leadership in fractional laser platforms for skin resurfacing applications. AbbVie Inc leverages the Allergan Aesthetics legacy to dominate injectable category presence in France and the United Kingdom.
Medical aesthetic devices encompass instruments and systems designed to alter or enhance human appearance through energy delivery, substance injection, or tissue manipulation, typically operating at wavelengths between 532 nm and 10,600 nm for laser modalities or utilizing hyaluronic acid and botulinum toxin formulations for injectable interventions. These systems serve commercial purposes in elective cosmetic medicine, enabling practitioners to perform hair removal, wrinkle reduction, and adipose tissue remodeling on an outpatient basis. Energy-based Devices command substantial margin pools due to capital equipment attach rates and consumable recurring revenue, while Dermal Fillers represent the fastest-expanding product category as hyaluronic acid formulations diversify beyond nasolabial applications into mid-face volumization and jawline contouring. Botox maintains mature volume leadership but faces structural pressure from next-generation neurotoxin entrants with faster onset profiles.
The European Medicines Agency and the EU Medical Device Regulation collectively shape market access through strengthened clinical evidence requirements and post-market surveillance obligations for Class III implantable and active devices. CE marking under the MDR now demands notified body involvement for all energy-based aesthetic systems previously self-certified under the Medical Devices Directive, extending approval timelines and consolidating vendor qualification thresholds. REACH compliance additionally constrains material selection for dermal filler cross-linking agents and laser housing polymers. Stakeholders must monitor evolving MDR guidance on substance-based device classification, as borderline determinations between medicinal and device frameworks will determine which neurotoxin and hyaluronic acid portfolios require centralized marketing authorization versus notified body certification.
Market Dynamics
The EU Medical Device Regulation is compressing vendor qualification thresholds while physician-owned clinic networks in Germany, France, and the United Kingdom restructure procurement patterns away from hospital outpatient departments toward independent dermatology centers.
Growth Catalysts
- MDR Certification Consolidation:The EU Medical Device Regulation's tightened clinical evidence requirements for Class III active devices is filtering out marginal suppliers and concentrating market share among notified body-qualified manufacturers.
- Energy-Based Platform Investment:Dermatology centers across German metropolitan networks are scaling capital deployment in fractional laser and radiofrequency systems for skin resurfacing and adipose tissue applications.
- Injectable Formulation Diversification:Hyaluronic acid portfolios are expanding beyond nasolabial folds into mid-face volumization and jawline contouring, opening new anatomical treatment zones.
Market Restraints
- Notified Body Bottlenecks:CE marking timelines under the MDR have extended substantially as limited notified body capacity confronts expanded device classification scope.
- Cross-Linking Agent Constraints:REACH compliance is restricting material selection for dermal filler polymers, elevating formulation costs and supplier qualification burdens.
- Neurotoxin Onset Competition:Next-generation botulinum toxin entrants with faster onset profiles are pressuring mature product margins and forcing portfolio refresh cycles.
Strategic Opportunities
- Eastern European Clinic Expansion:Underpenetrated dermatology center networks in Poland and Romania present whitespace for energy-based device penetration as private healthcare investment accelerates.
- Substance-Based Device Classification Clarity:Evolving MDR guidance on borderline determinations between medicinal and device frameworks will create regulatory arbitrage opportunities for centralized marketing authorization pathways.
- Consumable Recurring Revenue Models:Capital equipment attach rates for laser handpieces and injectable syringes are shifting vendor economics toward annuity-style revenue streams.
Industry Challenges
- Clinical Evidence Generation Capacity:Post-market surveillance obligations under the MDR are straining regulatory affairs functions and clinical trial infrastructure at mid-tier manufacturers.
- Practitioner Certification Fragmentation:Heterogeneous training requirements across German Länder, French regions, and UK devolved administrations complicate standardized service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Aesthetic Devices Market |
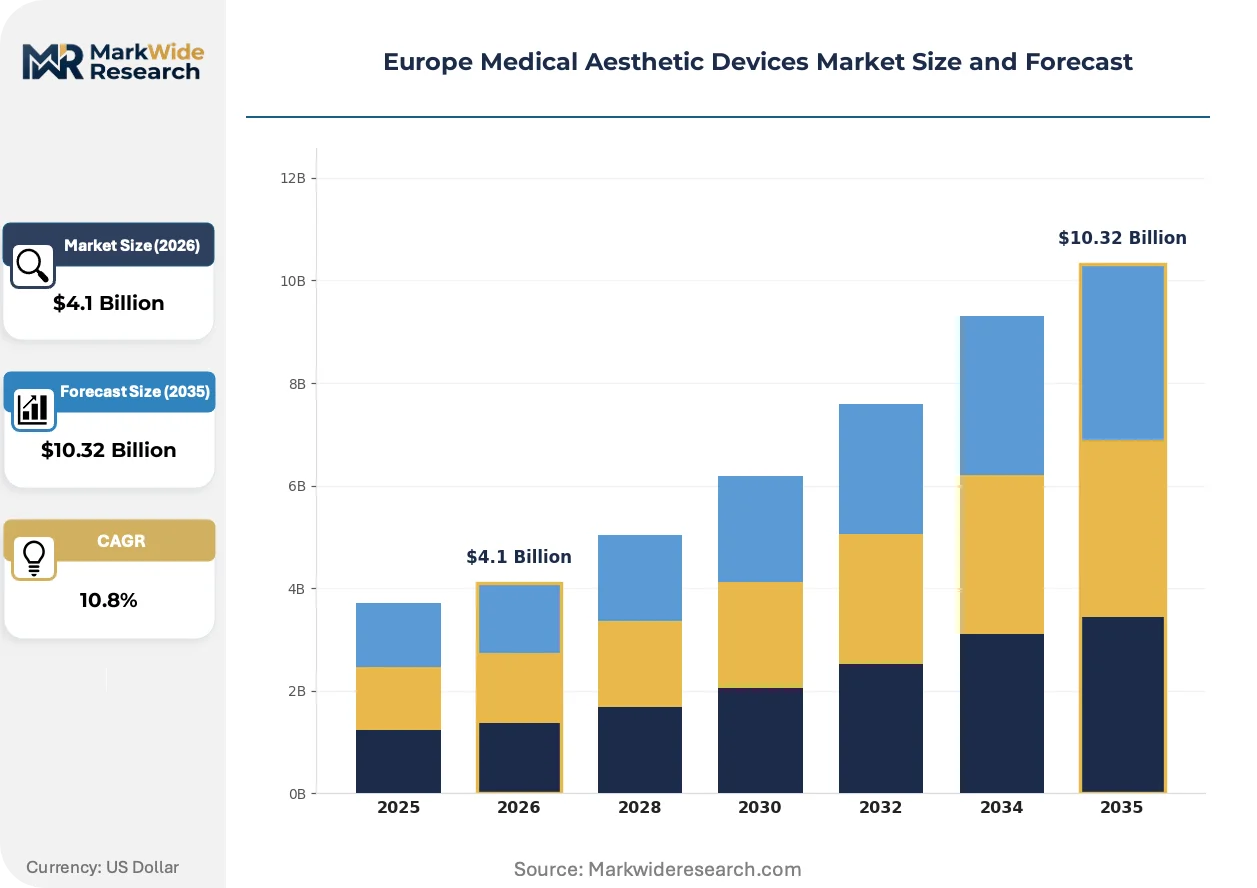
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $10.32 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Energy-based Devices, Dermal Fillers, Botox End User: Clinics, Hospitals, Medical Spas, Dermatology Centers Technology: Injectables, Radiofrequency, Ultrasound, Light Therapy Application: Skin Rejuvenation, Hair Removal, Body Contouring, Anti-aging |
| Companies Covered | Merz Pharma, Lumenis Inc, AbbVie Inc, Cutera Inc, Bausch Health Companies Inc, Galderma SA, Sisram Medical, Cynosure LLC, Johnson & Johnson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Aesthetic Devices Market Shifts & Advancements
Technology convergence between energy-based platforms and precision injection systems is redefining treatment protocols, while regulatory stringency and channel restructuring simultaneously reshape competitive positioning across European aesthetic medicine.
Non-ablative fractional laser systems is overtaking traditional ablative modalities in skin resurfacing applications. German and French dermatology centers are adopting these platforms at accelerated replacement cycles. The shift is compressing capital equipment depreciation schedules and elevating consumable attach rates as practitioners prioritize reduced downtime protocols.
The EU Medical Device Regulation's expanded scope for active implantable devices is forcing comprehensive technical documentation overhauls. Manufacturers face consolidated notified body engagement and extended conformity assessment timelines. Energy-based aesthetic systems previously self-certified under the Medical Devices Directive now face the steepest compliance reconfiguration.
Physician-led clinic networks are displacing hospital outpatient departments as the dominant channel for elective aesthetic procedures. Independent dermatology centers in the United Kingdom and Germany are consolidating purchasing power through group procurement organizations. This concentration is most visible in London, Munich, and Paris metropolitan clusters where multi-site clinic operators negotiate direct vendor relationships.
Europe Medical Aesthetic Devices Market Segmentation
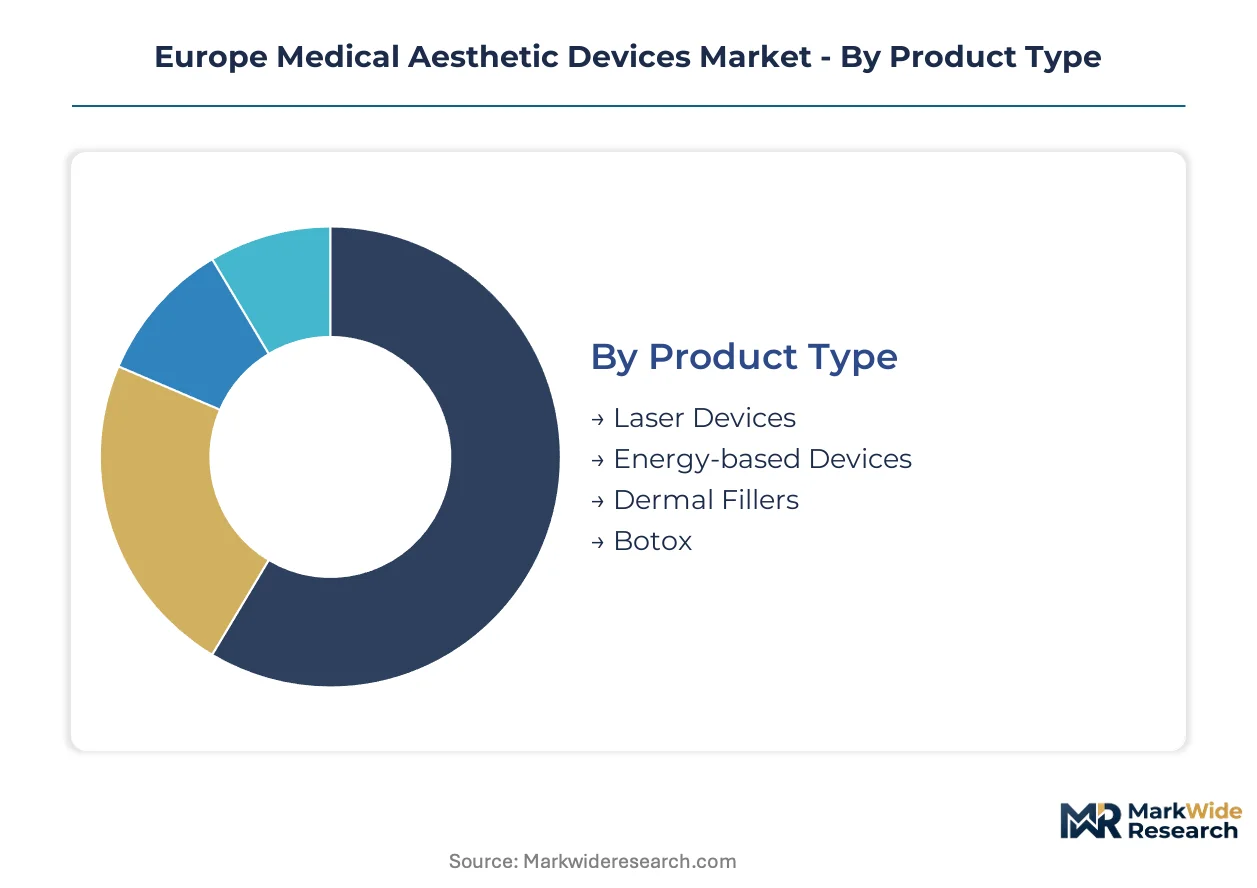
Segmentation clarity determines procurement strategy and vendor qualification pathways across European aesthetic medicine. Technology specifications, end-user channel structures, and application protocols each reshape competitive positioning under tightened MDR compliance frameworks.
Product Type:
Laser wavelength specifications and energy delivery mechanisms differentiate capital equipment economics across European clinic networks.
- Energy-based Devices:Fractional laser and radiofrequency platforms operate between 532 nm and 10,600 nm wavelengths, enabling skin resurfacing with controlled thermal injury zones. German metropolitan dermatology centers prioritize these systems for reduced-downtime protocols, driving accelerated replacement cycles and elevated consumable attach rates for handpieces and cooling cartridges.
- Dermal Fillers:Hyaluronic acid formulations with varying cross-linking densities enable tissue volumization through intradermal and subcutaneous injection. Demand concentrates in French and United Kingdom aesthetic clinics where mid-face volumization and jawline contouring applications are expanding beyond traditional nasolabial fold treatments, though REACH compliance constrains polymer selection.
- Laser Devices:Ablative and non-ablative systems for hair removal and vascular lesion treatment.
- Botox:Botulinum toxin formulations for neuromuscular blockade in wrinkle reduction applications.
Energy-based Devices lead on scale; Dermal Fillers lead on momentum.
End User:
Channel restructuring concentrates purchasing power among independent outpatient facilities.
- Dermatology Centers:Physician-owned multi-site networks in London, Munich, and Paris metropolitan clusters negotiate direct vendor relationships and consolidate procurement through group purchasing organizations, displacing traditional hospital outpatient departments as the dominant channel for elective aesthetic procedures.
- Clinics:Single-specialty aesthetic medicine practices with lower capital deployment thresholds.
- Hospitals:Hospital outpatient departments facing volume erosion to independent providers.
- Medical Spas:Hybrid wellness-aesthetic facilities with variable practitioner credentialing standards.
Dermatology Centers command the steepest procurement concentration; Clinics offer the broadest geographic penetration.
Technology:
Delivery mechanism specifications determine regulatory classification and clinical evidence requirements under MDR frameworks.
- Injectables:Precision delivery systems for hyaluronic acid and botulinum toxin formulations.
- Radiofrequency:Thermal energy delivery for adipose tissue remodeling and skin tightening applications.
- Ultrasound:High-intensity focused ultrasound platforms for non-invasive lifting and fat reduction.
- Light Therapy:Intense pulsed light and LED systems for photorejuvenation and vascular treatment.
Injectables dominate procedure volume; Radiofrequency platforms are climbing the fastest on capital equipment deployment.
Application:
Anatomical treatment zones reshape consumable utilization patterns and practitioner certification requirements.
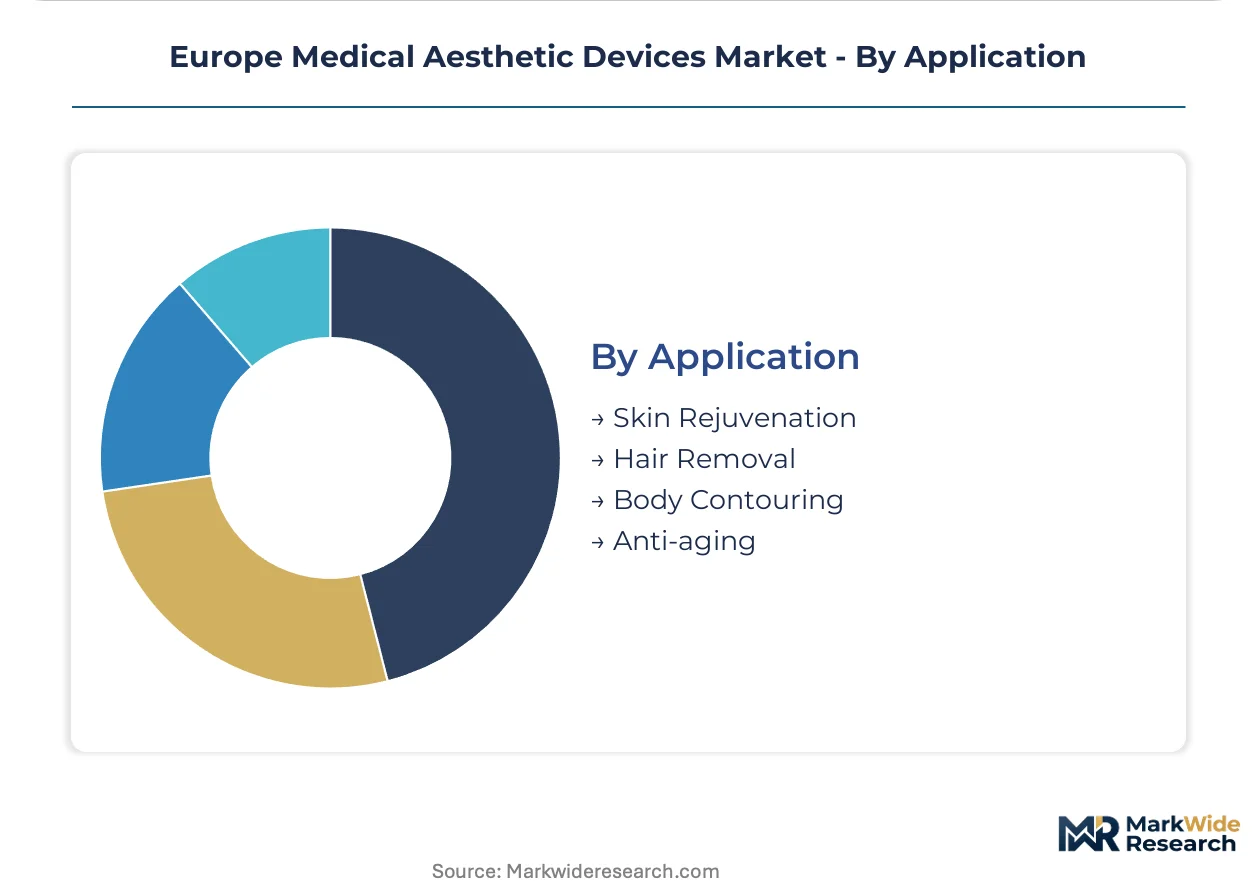
- Skin Rejuvenation:Fractional laser resurfacing, chemical peels, and photorejuvenation protocols addressing photodamage and textural irregularities.
- Hair Removal:Laser and intense pulsed light systems targeting melanin in follicular units.
- Body Contouring:Radiofrequency, ultrasound, and cryolipolysis modalities for non-invasive adipose tissue reduction.
- Anti-aging:Combined neurotoxin and filler protocols for dynamic and static rhytid management.
Skin Rejuvenation anchors procedure frequency; Body Contouring is gaining share fastest on technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing investment toward jurisdictions with streamlined MDR conformity pathways, as notified body capacity constraints in established markets elevate compliance cost differentials across the continent.
Germany
Metropolitan clinic networks in Munich and Berlin are consolidating procurement through group purchasing organizations for fractional laser platforms. The Federal Institute for Drugs and Medical Devices enforces MDR technical documentation standards that extend approval timelines for active implantable devices. The Rhine-Main cluster around Frankfurt anchors energy-based device distribution logistics for Central European markets.
France
Parisian dermatology centers are displacing hospital outpatient departments for hyaluronic acid filler procedures at accelerated rates. ANSM oversight of substance-based device classification creates borderline determination complexity for neurotoxin portfolios. The Île-de-France region concentrates practitioner training infrastructure and notified body engagement for Class III device certifications.
United Kingdom
London multi-site clinic operators are negotiating direct vendor relationships for radiofrequency body contouring systems outside NHS procurement frameworks. The Medicines and Healthcare products Regulatory Agency maintains transitional arrangements for CE-marked devices while aligning with future UKCA requirements. The Southeast England corridor hosts specialized logistics for consumable supply chains serving aesthetic medicine practices.
Italy
Milan and Rome aesthetic clinics are expanding mid-face volumization applications beyond traditional nasolabial fold treatments. The Italian Ministry of Health implements MDR delegated acts that affect laser device classification for dermatological indications. The Lombardy region concentrates private healthcare investment driving capital equipment replacement cycles.
Spain
Barcelona and Madrid dermatology networks are adopting non-ablative fractional systems for reduced-downtime protocols in photorejuvenation. The Spanish Agency for Medicines and Health Products enforces REACH compliance constraints on dermal filler polymer formulations. The Mediterranean corridor is emerging as a clinical trial location for post-market surveillance studies under MDR Article 74.
Europe Medical Aesthetic Devices Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers respond to MDR classification uncertainty by broadening across energy-based and injectable modalities. Market structure exhibits tiered concentration with notified body-qualified incumbents consolidating share while mid-tier vendors face qualification thresholds. Three archetypes prevail: integrated pharmaceutical-device hybrids, pure-play energy platform specialists, and diversified aesthetics portfolios carved from larger healthcare conglomerates. M&A activity and regulatory capacity building constitute the dominant competitive moves as firms acquire notified body relationships and clinical evidence generation capabilities.
Within the pharmaceutical-device hybrid tier, Merz Pharma and AbbVie Inc exemplify archetypes leveraging neurotoxin and filler specialization across German-speaking and Western European markets. Lumenis Inc occupies a position among energy-based platform specialists with fractional laser technology leadership. These three anchors represent distinct strategic postures: substance-based device depth, energy delivery innovation, and conglomerate-backed aesthetic portfolio scale.
| Leading Market Players |
|---|
| Merz Pharma |
| Lumenis Inc |
| AbbVie Inc |
| Cutera Inc |
| Bausch Health Companies Inc |
| Galderma SA |
| Sisram Medical |
| Cynosure LLC |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Notified body certification tiers bifurcate vendor economics between MDR-qualified incumbents and legacy self-certifiers, compressing margins for the latter while embedding premium pricing power in compliant supply chains. This divergence concentrates procurement leverage among German and French dermatology center networks that demand validated technical documentation and traceable post-market surveillance.
Pricing Analysis
Distributor margin layers absorb 15-25 point spreads between factory gate and clinic deployment for energy-based platforms. Three-tier pricing structure across premium, standard, and economy levels stratifies by MDR certification status and handpiece consumable bundling. Pricing pressure stems from REACH compliance elevating dermal filler polymer costs. Hospital outpatient departments exhibit highest price sensitivity; metropolitan multi-site clinic networks prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Regional distribution centers in Frankfurt and Paris anchor hub-and-spoke patterns serving Central and Western European clinic networks. Manufacturing concentrates in Germany, Switzerland, and Israel for laser resonator assemblies and precision injection systems. Cross-linked hyaluronic acid raw materials, fractional laser handpieces, and radiofrequency generator modules constitute critical input dependencies. Single-source vulnerability runs through Swissmedic-certified polymer suppliers. Distribution runs through specialized medical device logistics operators with cold-chain capabilities for toxin formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European medical aesthetic devices constitute a late-cycle quality story as physician-led clinic networks prioritize MDR-validated platforms over price-driven procurement. Demand is concentrating toward premium specifications that bundle consumable attach rates with extended service agreements.
For Market Incumbents: Hedge regulatory exposure by accelerating notified body relationship diversification beyond single-certificate dependencies. Deepen backward integration into hyaluronic acid polymer production to offset REACH-driven cost compression. Prioritize clinical evidence generation capacity as MDR Article 74 post-market surveillance obligations strain mid-tier competitors. For New Entrants and Emerging Players: Begin with Eastern European whitespace in Polish and Romanian dermatology center networks where MDR penetration lags Western adoption curves. Target radiofrequency body contouring applications as the fastest-climbing capital equipment category. Pursue direct procurement relationships with emerging multi-site clinic operators bypassing traditional distribution layers. For Investors and Strategic Acquirers: Consolidation pressure builds where notified body capacity constraints eliminate marginal vendors from qualification pathways. Long-term viability favors pharmaceutical-device hybrids with substance-based device classification clarity and energy platform specialists with fractional laser IP estates. Monitor EMA borderline determination guidance revisions as the critical inflection signal for neurotoxin portfolio reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway Acceleration | Notified body engagement timelines determine market access windows for active implantable laser systems. |
| Consumable Recurring Revenue Model | Handpiece and syringe attach rates shift vendor economics toward annuity-style cash flows. |
| Clinical Evidence Generation Capacity | Post-market surveillance infrastructure separates qualified incumbents from dequalifying mid-tier suppliers. |
| Group Purchasing Organization Partnership | London and Munich clinic networks consolidate procurement leverage through direct vendor negotiations. |
| Substance-Based Device Classification Clarity | EMA borderline determinations dictate whether neurotoxin portfolios require centralized marketing authorization. |
Research Methodology
Bottom-up dermatology center procurement modeling reconciled against top-down energy-based device shipment tracking forms the analytical core of this study. Primary interviews with aesthetic medicine practitioners, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at notified bodies combined with secondary validation against EMA MDR guidance documents, ANSM classification determinations, and hospital procurement database extracts. Triangulation across stakeholder inputs and regulatory filings anchors segmentation-specific demand estimates.
Historical trendline analysis of laser platform replacement cycles and injectable procedure volumes established baseline growth trajectories across the projection horizon. The analytical framework models product type, end-user channel structure, technology delivery mechanism, and anatomical application zone as core segmentation dimensions. CAGRs derive from curve-fitting equipment depreciation schedules and consumable utilization rates against clinic network expansion patterns. Forecast inputs incorporate MDR transition timeline assumptions and REACH compliance cost pass-through coefficients.
Several conditions sit outside the modeled scope, including UKCA implementation divergence from CE marking reciprocity and unforeseen EMA substance-based device reclassification decisions. Forecasts reflect documented assumptions regarding notified body capacity expansion and clinic network consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Medical Aesthetics Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Cosmetic Laser Market
Medical Aesthetics
Australia Laser Hair Removal Market
Medical Aesthetics
Global Energy-Based Non-Invasive Medical Aesthetic Treatment System Market
Medical Aesthetics
North America Laser Tattoo and Striae Removal Market
Medical Aesthetics
Japan Hair Transplant Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market