
 Lip Augmentation Market | 2026-2036
Lip Augmentation Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Augmentation Market Intelligence
South Korea is rewriting the competitive map for aesthetic injectables through its advanced biomanufacturing infrastructure and prolific domestic consumption. Allergan Aesthetics leverages its Juvederm portfolio to dominate premium hyaluronic acid filler segments across North American and European channels. Galderma sustains R&D intensity in next-generation cross-linking technologies that extend product longevity. Merz Pharma anchors its position through specialized training ecosystems that bind practitioners to its Radiesse and Belotero lines.
Lip augmentation encompasses injectable and surgical procedures designed to enhance lip volume, contour, or symmetry through the introduction of biocompatible materials or autologous tissue transfer. Hyaluronic acid fillers, formulated with cross-linked gel matrices of varying particle sizes and G-prime values, constitute the dominant modality due to reversibility with hyaluronidase and tunable duration of six to eighteen months. Collagen fillers retain niche utility in specific reconstructive contexts despite declining commercial share, while fat grafting occupies a specialized tier for patients seeking permanent autologous solutions with higher procedural complexity. The reconstructive surgery application commands premium pricing due to specialized surgical expertise requirements, whereas cosmetic enhancement drives volume through repeat treatment cycles in clinic and dermatology center settings.
The FDA's 510(k) and PMA pathways for dermal fillers mandate biocompatibility testing and post-market surveillance through the MAUDE database, elevating compliance costs for new entrants while reinforcing incumbent quality signals. The EU Medical Device Regulation imposes stricter clinical evidence requirements and unique device identification, reshaping market access timelines for manufacturers targeting European clinics and plastic surgery facilities. Stakeholders must monitor evolving reimbursement policies for reconstructive indications and the convergence of topical anesthetic formulations with injectable platforms as dual-product strategies gain traction.
Market Dynamics
The FDA's premarket approval pathway for dermal fillers compresses product development timelines while elevating compliance thresholds, creating asymmetric barriers that favor incumbents with established quality signals and post-market surveillance infrastructure.
Growth Catalysts
- MFDS fast-track pathways:South Korea's streamlined biologics approval accelerates hyaluronic acid filler launches for domestic manufacturers targeting export markets.
- Minimally invasive modality preference:Cosmetic dermatology clinics report patient demand concentrating on reversible, office-based procedures with minimal downtime versus surgical alternatives.
- Cross-linking technology maturation:Next-generation gel matrices with tunable G-prime values extend duration windows and enable precision contouring for practitioner differentiation.
Market Restraints
- Hyaluronic acid raw material concentration:Fermentation-derived HA supply chains cluster among specialized biomanufacturers in China and South Korea, creating input vulnerability.
- FDA PMA timeline friction:Premarket approval for novel filler formulations requires 24-36 month clinical evidence packages that deter venture-stage entrants.
- Autologous fat grafting substitution:Permanent volume solutions attract price-insensitive patients despite procedural complexity, capping repeat-treatment revenue for temporary fillers.
Strategic Opportunities
- Brazil's underpenetrated clinic network:ANVISA regulatory harmonization with FDA standards opens pathway for premium filler portfolios in Latin America's largest aesthetic market.
- Topical anesthetic convergence:Dual-product strategies combining lidocaine-integrated fillers with pre-treatment numbing protocols capture procedure efficiency premiums.
- Reconstructive indication expansion:Post-oncologic and trauma-related lip restoration applications command reimbursement pathways distinct from cosmetic cash-pay segments.
Industry Challenges
- Injector certification standardization:Disparate training requirements across state medical boards and national nursing councils fragment practitioner credential quality.
- Post-market surveillance integration:MAUDE database reporting obligations impose ongoing pharmacovigilance costs that scale with product portfolio breadth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Augmentation Market |
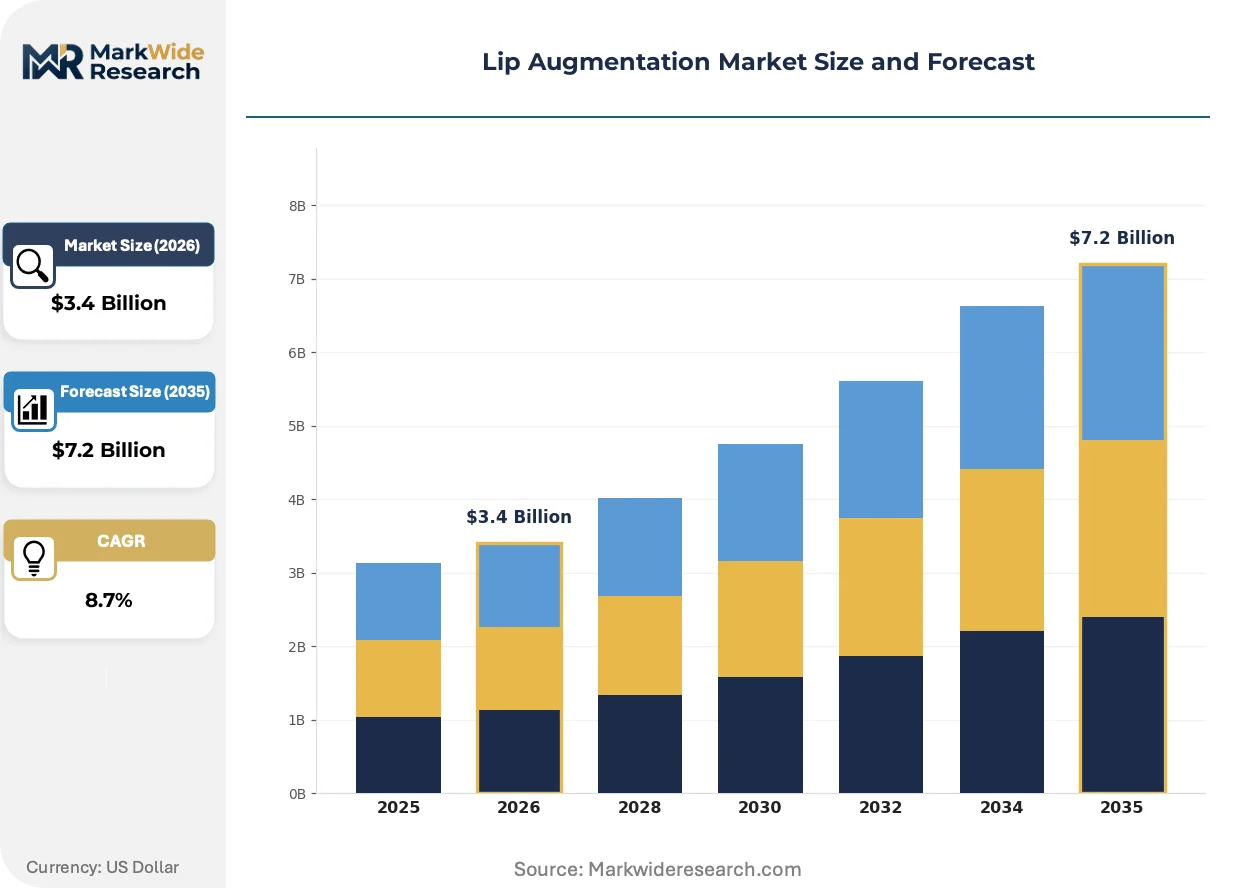
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid Fillers, Collagen Fillers, Fat Grafting, PMMA Fillers Application: Cosmetic Enhancement, Reconstructive Surgery, Scar Correction, Age-Related Volume Loss End User: Clinics, Dermatology Centers, Plastic Surgery Facilities, Home Users Delivery Mode: Injectable Treatments, Topical Anesthetics, Surgical Procedures, Transdermal Delivery |
| Companies Covered | Allergan Aesthetics (AbbVie), Galderma, Merz Pharma, Teoxane Laboratories, Suneva Medical, Sinclair Pharma, Laboratoires Vivacy, Revance Therapeutics, Ipsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Augmentation Market Strategic Shifts & Innovations
Product longevity and reversibility are trading places as the dominant design priority, with formulation science now targeting intermediate-duration solutions that balance patient commitment flexibility with reduced injection frequency.
Viscoelastic filler technology is migrating from high-G-prime structural products toward medium-G-prime options that prioritize natural tissue integration over dramatic projection. High-volume aesthetic chains in the United States and South Korea are adopting these formulations for first-time patients seeking subtle enhancement. The shift compresses average revenue per procedure while expanding addressable patient pools beyond traditional cosmetic surgery demographics.
The EU Medical Device Regulation imposes unique device identification and strengthened clinical evidence requirements that extend market access timelines for manufacturers targeting European clinics. Post-market surveillance obligations now mandate systematic follow-up registries that capture adverse event patterns across diverse practitioner settings. German and French aesthetic medicine facilities are consolidating supplier relationships to reduce compliance verification burden, favoring incumbent portfolios with established MDR technical documentation.
Patient acquisition through social media-driven consultation requests is displacing traditional physician referral networks as the primary channel for aesthetic clinic volume. Instagram and TikTok content creators in Los Angeles, Seoul, and São Paulo now function as de facto distribution intermediaries, compressing the path from awareness to appointment booking. This channel shift elevates importance of before-and-after imagery rights management and influencer partnership structures for clinic marketing operations.
Lip Augmentation Market Segmentation
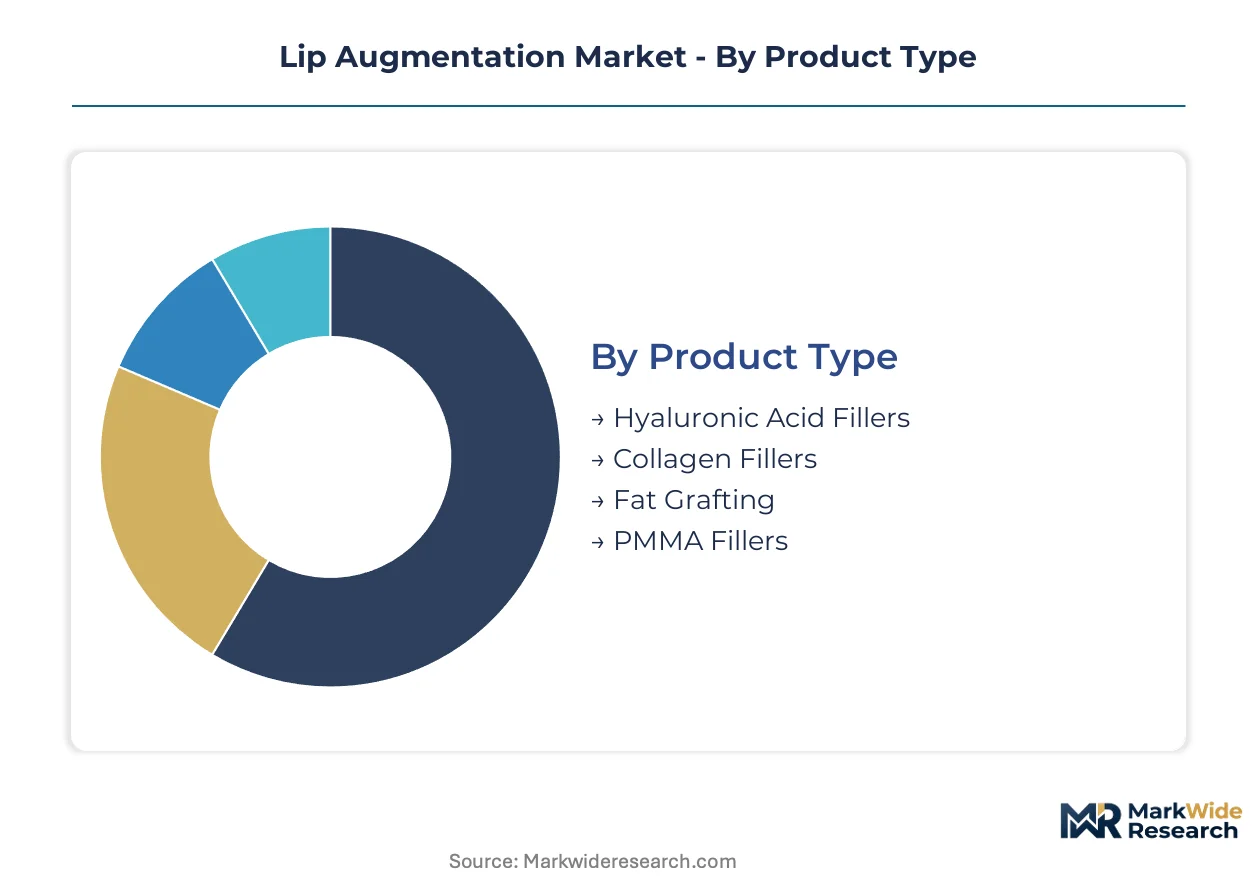
Product differentiation in lip augmentation hinges on reversibility profiles, procedural invasiveness, and practitioner credential requirements. Segmentation reveals how formulation science and delivery mode choices partition patient populations across price points and risk tolerances.
Product Type:
Cost tier structures segment the market from premium reversible solutions to permanent autologous alternatives.
- Hyaluronic Acid Fillers:Cross-linked gel matrices with tunable G-prime values enable duration control from six to eighteen months. Demand concentrates in cosmetic dermatology clinics across the United States and South Korea, where reversibility with hyaluronidase reduces patient hesitation for first-time procedures.
- Collagen Fillers:Bovine and human-derived matrices retain utility in reconstructive contexts requiring structural scaffolding. Volume has migrated toward niche reconstructive applications as hyaluronic acid formulations capture mainstream cosmetic share.
- Fat Grafting:Autologous adipose transfer delivers permanent volume through liposuction harvest and centrifugal purification.
- PMMA Fillers:Polymethyl methacrylate microspheres suspended in collagen carrier provide semi-permanent augmentation.
Hyaluronic Acid Fillers commands the established base. The steepest expansion runs through Fat Grafting.
Application:
Clinical purpose determines reimbursement pathways, with reconstructive indications accessing insurance coverage absent from cosmetic cash-pay segments.
- Cosmetic Enhancement:Elective volume and contour modifications drive repeat treatment cycles in clinic settings. Demand clusters in metropolitan aesthetic hubs including Los Angeles, Seoul, and São Paulo, where social media visibility elevates procedure frequency among younger demographics.
- Reconstructive Surgery:Post-oncologic, trauma, and congenital defect restoration requires specialized surgical expertise. Premium pricing reflects operating room infrastructure and microvascular technique requirements that general dermatology clinics cannot replicate.
- Scar Correction:Tissue revision for traumatic or surgical lip scarring addresses functional and aesthetic sequelae.
- Age-Related Volume Loss:Perioral rejuvenation targets vermillion border definition and philtral column restoration.
Cosmetic Enhancement anchors volume throughput. Reconstructive Surgery captures margin concentration.
End User:
Facility type governs regulatory oversight intensity and product form factor requirements.
- Clinics:Office-based aesthetic medicine practices handle high-frequency injectable workflows with nursing staff support. United States medspa chains and South Korean clinic networks dominate throughput volume through standardized treatment protocols.
- Dermatology Centers:Physician-supervised settings with advanced diagnostic capabilities manage complex cases requiring combination therapy.
- Plastic Surgery Facilities:Operating room infrastructure supports surgical augmentation and fat grafting procedures.
- Home Users:Consumer-directed topical plumping devices and cosmetic preparations occupy the non-prescription tier.
Clinics aggregate the highest procedure density. Dermatology Centers are expanding most quickly through integrated aesthetic service lines.
Delivery Mode:
Invassiveness spectrum segments patients across anesthesia requirements, recovery windows, and outcome permanence.
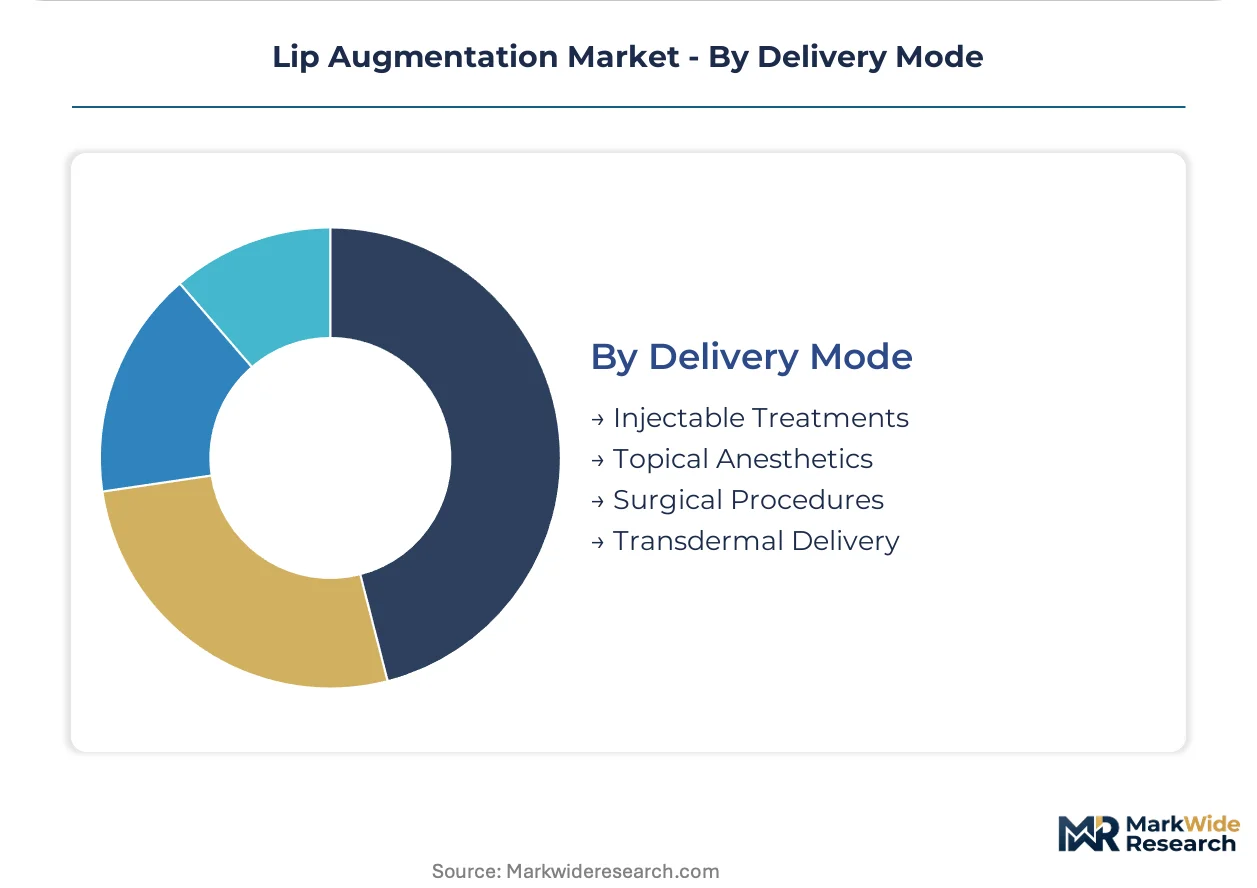
- Injectable Treatments:Cannula and needle-based filler placement under topical or local anesthesia enables same-day resumption of activities. FDA 510(k) clearance pathways and MFDS fast-track mechanisms accelerate product introductions for clinic formulary adoption.
- Topical Anesthetics:Lidocaine-integrated filler formulations and pre-treatment numbing protocols reduce patient discomfort signals.
- Surgical Procedures:Lip implants and vermillion advancement require sterile surgical environments.
- Transdermal Delivery:Microneedle arrays and iontophoretic systems attempt non-invasive augmentation.
Injectable Treatments maintains procedure dominance. Topical Anesthetics show the steepest innovation trajectory through combination product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket approval pathways anchor the United States as the dominant geography, with aesthetic procedure volumes and practitioner density driving premium filler consumption. Demand clusters in metropolitan hubs where social media visibility accelerates patient acquisition cycles.
United States
Cosmetic dermatology clinics in Los Angeles and New York Metro report patient demand concentrating on reversible, office-based procedures with minimal downtime. FDA 510(k) and PMA pathways mandate biocompatibility testing and post-market surveillance through the MAUDE database, elevating compliance costs for new entrants. Aesthetic medicine chains in Miami and Dallas-Fort Worth are consolidating supplier relationships to streamline formulary management.
South Korea
Domestic consumption of aesthetic injectables runs at per-capita rates exceeding most developed markets, with Seoul's Gangnam district hosting dense clinic networks. MFDS fast-track pathways accelerate hyaluronic acid filler launches for domestic manufacturers targeting export markets. Biomanufacturing infrastructure in Incheon and Songdo supports fermentation-derived raw material supply chains.
Germany
EU Medical Device Regulation imposes unique device identification and strengthened clinical evidence requirements that extend market access timelines for manufacturers. Aesthetic medicine facilities in Munich and Hamburg are consolidating supplier relationships to reduce compliance verification burden. German practitioners demonstrate preference for established portfolios with MDR technical documentation.
Brazil
ANVISA regulatory harmonization with FDA standards opens pathway for premium filler portfolios in Latin America's largest aesthetic market. São Paulo and Rio de Janeiro anchor procedure volume through high-density clinic networks and social media-driven patient acquisition. Brazilian consumers demonstrate strong preference for minimally invasive modalities over surgical alternatives.
United Kingdom
Post-Brexit regulatory divergence from EU MDR creates parallel compliance obligations for manufacturers accessing British aesthetic clinics. London's Harley Street medical district maintains concentration of high-end cosmetic dermatology practices. UK nursing councils and medical boards are developing standardized injector certification requirements to address quality fragmentation.
Lip Augmentation Market Key Industry Players
Capability concentration sits with specialized biomanufacturers possessing cross-linking technology expertise; scale advantage sits with diversified pharmaceutical portfolios with established aesthetic medicine channels. The market structure tiers between premium hyaluronic acid specialists and broad-based dermatology portfolios. Three archetypes dominate: fermentation-derived raw material controllers, formulation science specialists with tunable gel matrices, and integrated training-ecosystem operators. Competitive moves concentrate on M&A for biomanufacturing assets and strategic partnerships with high-volume clinic chains.
Within the premium-tier vector, Allergan Aesthetics exemplifies diversified pharmaceutical scale with established North American and European channel presence. Galderma and Merz Pharma occupy positions as formulation science specialists, with the former representing Swiss-based dermatology-focused structure and the latter exemplifying German pharmaceutical heritage. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning in aesthetic injectables.
| Leading Market Players |
|---|
| Allergan Aesthetics (AbbVie) |
| Galderma |
| Merz Pharma |
| Teoxane Laboratories |
| Suneva Medical |
| Sinclair Pharma |
| Laboratoires Vivacy |
| Revance Therapeutics |
| Ipsen |
| Others |
Cost & Logistics Intelligence
Fermentation-derived hyaluronic acid supply chains cluster among specialized biomanufacturers in China and South Korea, concentrating upstream margin capture with raw material controllers while downstream pricing power fragments across formulation specialists and clinic networks.
Pricing Analysis
United States clinic networks command premium pricing over Brazilian and South Korean equivalents, with three-tier pricing structure across premium, standard, and economy levels separating Allergan Aesthetics' Juvederm portfolio from mid-tier Galderma offerings and economy-positioned domestic Asian brands. Price differentiation hinges on FDA PMA certification tier and practitioner training ecosystem depth, with cost compression in economy tiers intensifying because of raw material oversupply from Chinese fermentation capacity. First-time cosmetic patients in São Paulo and Seoul demonstrate highest price sensitivity, whereas reconstructive surgery patients in Los Angeles and New York Metro exhibit lowest sensitivity due to insurance reimbursement pathways.
Supply Chain Analysis
Contract manufacturing concentration sits with Lonza and Samsung Biologics for fermentation-derived HA raw material, with Boehringer Ingelheim and Catalent handling fill-finish for premium filler portfolios. Geographic supply concentration centers on China for bulk HA fermentation, South Korea for cross-linking technology, and Switzerland for precision formulation. Raw material dependencies include microbial fermentation feedstocks, cross-linking agents BDDE and DVS, and pharmaceutical-grade saline carriers. Single-source vulnerability runs through Chinese HA raw material controllers, with distribution running through direct sales forces to high-volume clinic chains and specialty distributors to independent dermatology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent autologous fat grafting presents a substitution threat that temporary filler incumbents must navigate through duration extension and reversibility value proposition reinforcement.
For Market Incumbents: Insulate core hyaluronic acid filler revenue through backward integration into fermentation capacity in South Korea and Switzerland, securing captive supply of high-molecular-weight HA raw material. Deepen practitioner training ecosystem lock-in through exclusive certification programs that bind injectors to proprietary cannula techniques and combination therapy protocols, raising switching costs against emerging entrants with comparable gel matrices. For New Entrants and Emerging Players: Establish a beachhead in Brazil's underpenetrated clinic network outside São Paulo and Rio de Janeiro, where ANVISA regulatory harmonization with FDA standards reduces approval friction for premium portfolios. Target reconstructive indication expansion through hospital system partnerships in Germany and the United Kingdom, accessing reimbursement pathways distinct from saturated cosmetic cash-pay segments through microvascular technique training credentials. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap formulation specialists possessing tunable G-prime cross-linking patents and established MFDS fast-track approval records, with long-term viability contingent on duration extension science outpacing autologous substitution. Watch for inflection in South Korean domestic consumption per-capita rates as early indicator of export market saturation and pricing pressure migration.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Linking Technology Licensing | Galderma's patent portfolio enables duration extension that commands premium clinic formulary placement. |
| Practitioner Training Ecosystem Expansion | Merz Pharma's specialized certification programs bind injectors to Radiesse and Belotero lines through technique exclusivity. |
| MFDS Fast-Track Regulatory Pathway | South Korea's streamlined biologics approval accelerates hyaluronic acid filler launches for domestic manufacturers targeting export markets. |
| Reconstructive Indication Portfolio Buildout | Post-oncologic lip restoration applications command reimbursement pathways distinct from cosmetic cash-pay segments. |
| Raw Material Backward Integration | Fermentation-derived HA supply chain control in Incheon and Songdo secures input cost stability against Chinese price volatility. |
Research Approach
Initial hypotheses were tested against primary input from cosmetic dermatology clinic operators, biomedical engineers at filler manufacturers, regulatory affairs leads at MFDS and FDA, hospital purchasing committee members, and GPO contracts managers, and refined through secondary validation against FDA 510(k) and PMA filings, EMA MDR technical documentation, MFDS biologics approval databases, clinical trial registries for dermal filler studies, and customs trade data for hyaluronic acid raw material flows. Bottom-up procedure volume estimates from clinic networks were triangulated against top-down manufacturer shipment data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, end user, and delivery mode, plus regional regulatory cluster differentiation between FDA, EMA, MFDS, and ANVISA pathways. CAGRs were derived from procedure volume growth trajectories and average revenue per treatment evolution, incorporating hyaluronidase reversal rates and repeat treatment cycle frequency as industry-specific forecast inputs.
Sensitivities concentrate around MFDS approval timeline acceleration, Chinese HA raw material export restrictions, and EU MDR post-market surveillance cost escalation. Forecasts reflect documented assumptions regarding practitioner density growth and social media-driven patient acquisition channel shift. Quarterly review of clinic network consolidation rates, MAUDE adverse event reporting trends, and ANVISA regulatory harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Cosmetic Threads Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Japan Laser Hair Removal Market
Medical Aesthetics
Lip Filler Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Gum Lift Market
Medical Aesthetics
France Hair Transplant Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Cosmetic Laser Market