
 France Hair Transplant Market | 2026-2036
France Hair Transplant Market Size, Share, and Industry Trends Forecast 2026-2036
France Hair Transplant Market Insights
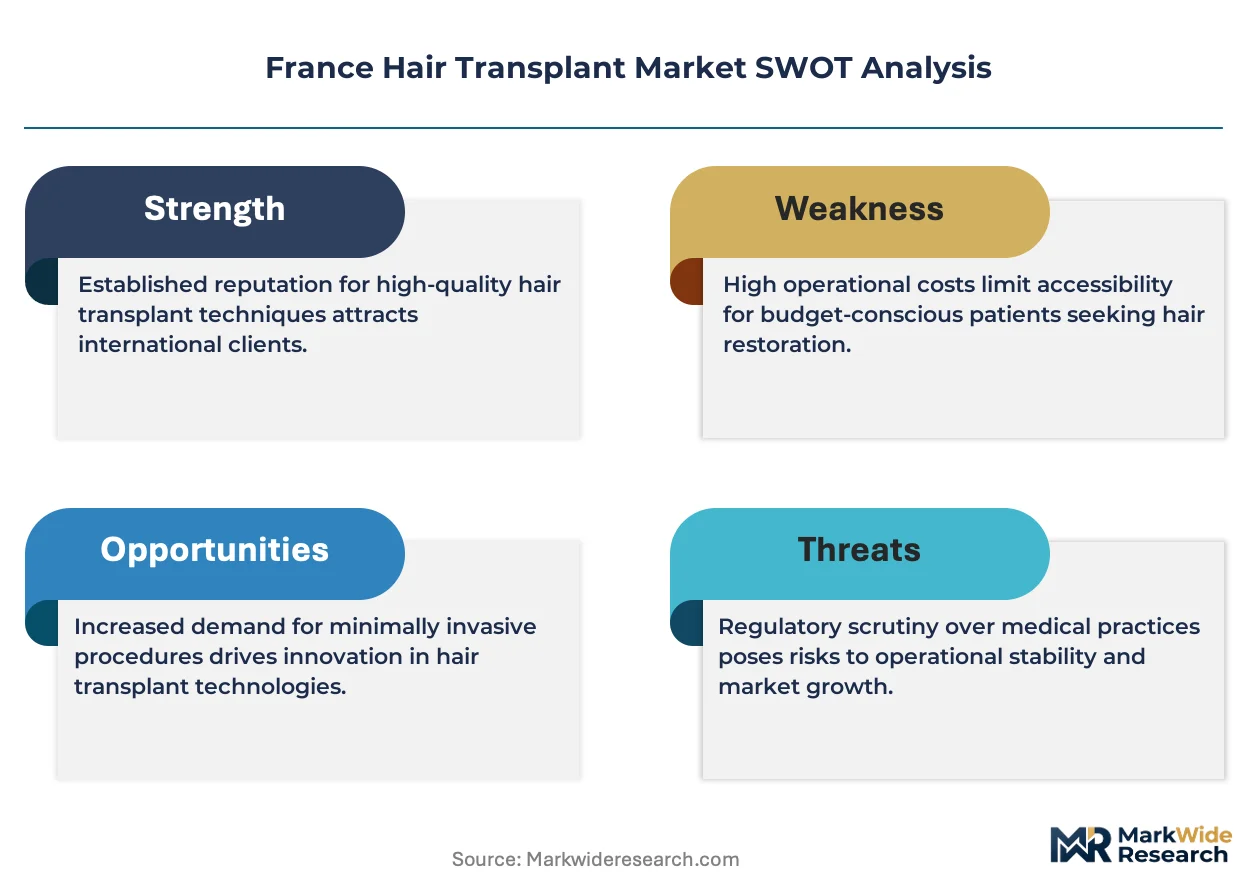
The France hair transplant sector is restructuring around a widening gap between premium concierge clinics and budget-oriented chain operators. Vivant Hair Institute leverages its Paris flagship location to command premium positioning through surgeon-led consultation models. Base Medicale sustains competitive density in Marseille with Mediterranean medical tourism flows. DHI International anchors brand recognition through standardized procedural protocols across multiple French cities.
Hair transplantation encompasses surgical relocation of autologous follicular units from donor zones to recipient scalp areas, typically involving extraction densities of 30-40 grafts per square centimeter for natural pattern restoration. The procedure serves both cosmetic reconstruction for androgenetic alopecia and corrective repair of prior surgical outcomes. FUE procedures now dominate volume flows due to reduced linear scarring and faster recovery trajectories compared with FUT strip harvesting. Robotic systems segment captures concentrated margin pools as capital-intensive installations limit clinic penetration. Premium price tier absorbs disproportionate profit share despite representing smaller patient volumes, reflecting surgeon reputation premiums and bundled aftercare services.
ANSM oversees medical device vigilance for implant instruments and graft preservation solutions, while EU MDR transition imposes stricter clinical evidence requirements on automated extraction devices. French clinic accreditation through the national health agency shapes patient trust and reimbursement-adjacent cosmetic procedure standards. Stakeholders must monitor evolving CE marking timelines for robotic platforms and anticipate ANSM guidance on platelet-rich plasma classification as borderline medical devices.
Market Dynamics
The French hair transplant sector is bifurcating around surgeon reputation premiums versus automated efficiency plays, with ANSM device scrutiny and EU MDR recertification timelines compressing operational margins for mid-tier operators.
Growth Catalysts
- EU MDR Recertification:Stricter clinical evidence requirements for robotic extraction devices are filtering out marginal operators, concentrating volume in accredited Paris and Marseille clinics with compliant quality management systems.
- FUE Technique Maturation:Reduced linear scarring and faster recovery trajectories pull patients aged 35-50 away from pharmaceutical interventions toward surgical restoration.
- Ile-de-France Medical Tourism Infrastructure:Premium clinic density in Paris and surrounding departments captures cross-border patient flows from Belgium, Switzerland, and Luxembourg seeking French surgical standards.
Market Restraints
- Capital Intensity of Robotic Platforms:ARTAS and similar systems require seven-figure euro investments, limiting installation to flagship locations and excluding regional clinic networks from margin-rich automated segments.
- Donor Supply Scarcity:Finite occipital follicular reserves constrain graft yields for advanced Norwood stage patients, capping addressable case complexity regardless of procedural technique.
- ANSM Borderline Classification Uncertainty:Pending determinations on platelet-rich plasma devices as medical versus cosmetic products create compliance ambiguity for clinics bundling adjuvant therapies.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Expansion:Mediterranean medical tourism corridors through Nice and Cannes remain underdeveloped relative to Paris, offering first-mover positioning for premium concierge models.
- Surgeon-Led Subscription Aftercare:Annual maintenance protocols combining PRP sessions, trichoscopic monitoring, and pharmaceutical adjuvants create recurring revenue streams beyond one-time transplantation.
- Teleconsultation Pre-Screening:Remote follicular assessment via high-resolution imaging reduces consultation no-shows and expands geographic catchment without physical clinic footprint.
Industry Challenges
- Trichosurgeon Training Pipeline:France lacks standardized fellowship pathways for follicular unit extraction mastery, forcing clinics to recruit from Turkish or Spanish training centers.
- CE Marking Timeline Compression:EU MDR transition deadlines for Class IIa extraction devices strain regulatory affairs capacity, with notified body backlogs extending certification cycles.
- Graft Viability Logistics:Cold storage and hypothermic preservation protocols require precise temperature chain management, with deviations risking follicular survival rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Hair Transplant Market |
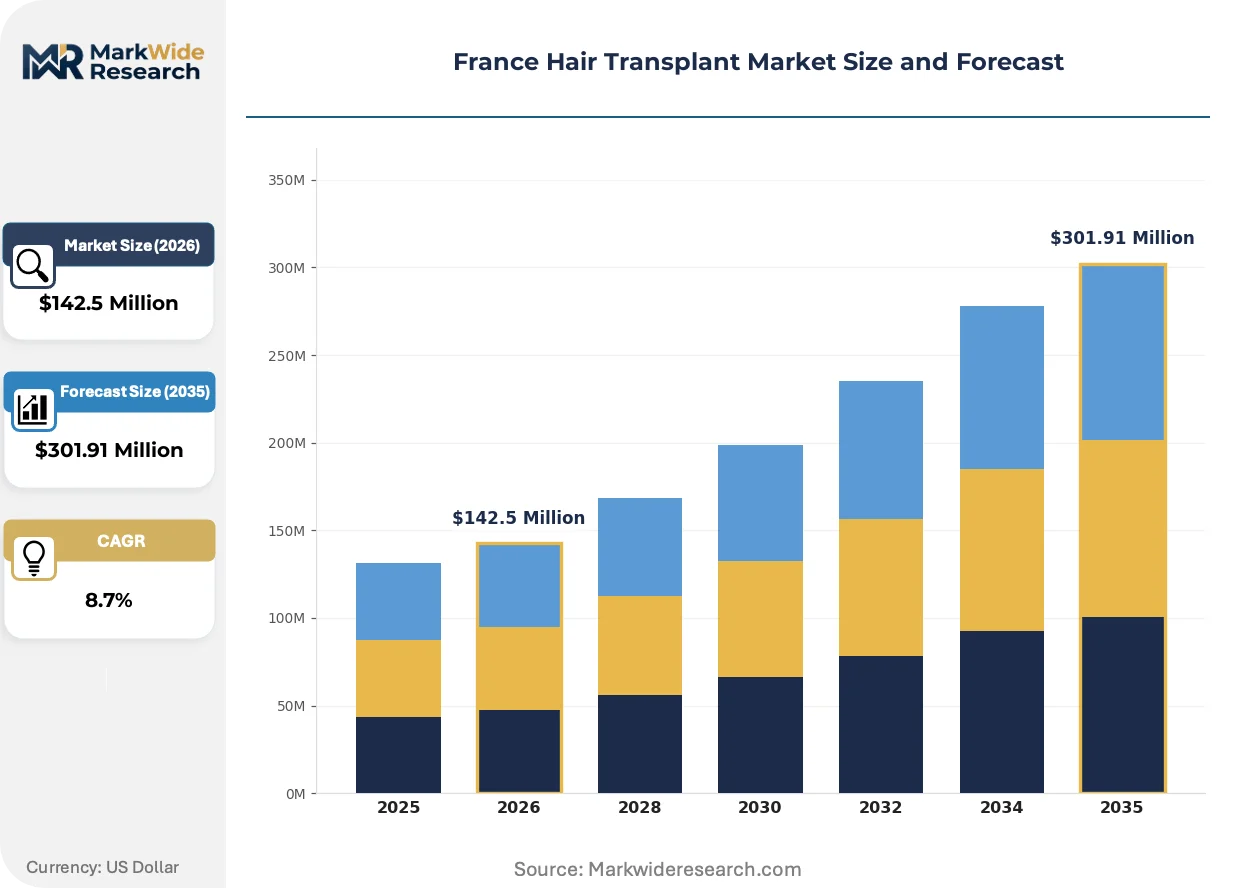
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: FUE, FUT, PRP, Laser Therapy Technology: Robotic Systems, Manual Extraction, Platelet-Rich Plasma, Microneedling End User: Clinics, Hospitals, Private Practices, Medspa Price Tier: Premium, Mid-range, Budget, Others |
| Companies Covered | Vivant Hair Institute, Base Medicale, Clinique du Rond-Point des Champs-Elysées, Marseille Micrograft Clinic, SeineEdge Hair Restoration, Racine², DHI International, Dr. Christelle Santini, Maison Lutétia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Hair Transplant Market Trends and Innovations
Automation, regulatory recalibration, and patient journey digitization are restructuring competitive advantage in French hair restoration, rewarding capital deployment and compliance infrastructure over historical surgeon reputation alone.
Robotic follicular unit extraction is decentralizing procedure volume from celebrity surgeon boutiques toward technology-enabled clinic networks. Mid-sized operators in Lyon and Bordeaux deploy semi-automated extraction platforms to match Parisian graft precision without comparable specialist premiums. This diffusion compresses geographic price differentials and erodes location-based competitive moats.
ANSM is intensifying post-market surveillance obligations for implantable instruments and graft preservation solutions under converging EU MDR frameworks. Clinics must now maintain vigilance databases for adverse events and device malfunctions, with automated platforms facing heightened scrutiny due to software-dependent extraction algorithms. Premium operators absorb these compliance costs through bundled service pricing, while budget chains struggle with documentation overhead.
Patient acquisition is migrating from referral-dependent models toward direct-to-consumer digital channels with transparent outcome documentation. Before-and-after portfolios with standardized trichoscopic imaging replace word-of-mouth trust mechanisms, particularly among the 35-50 male demographic researching procedures independently. This shift is most visible in Paris and Marseille, where clinic groups invest in search visibility and patient education content to capture consideration-stage demand.
France Hair Transplant Market Segmentation
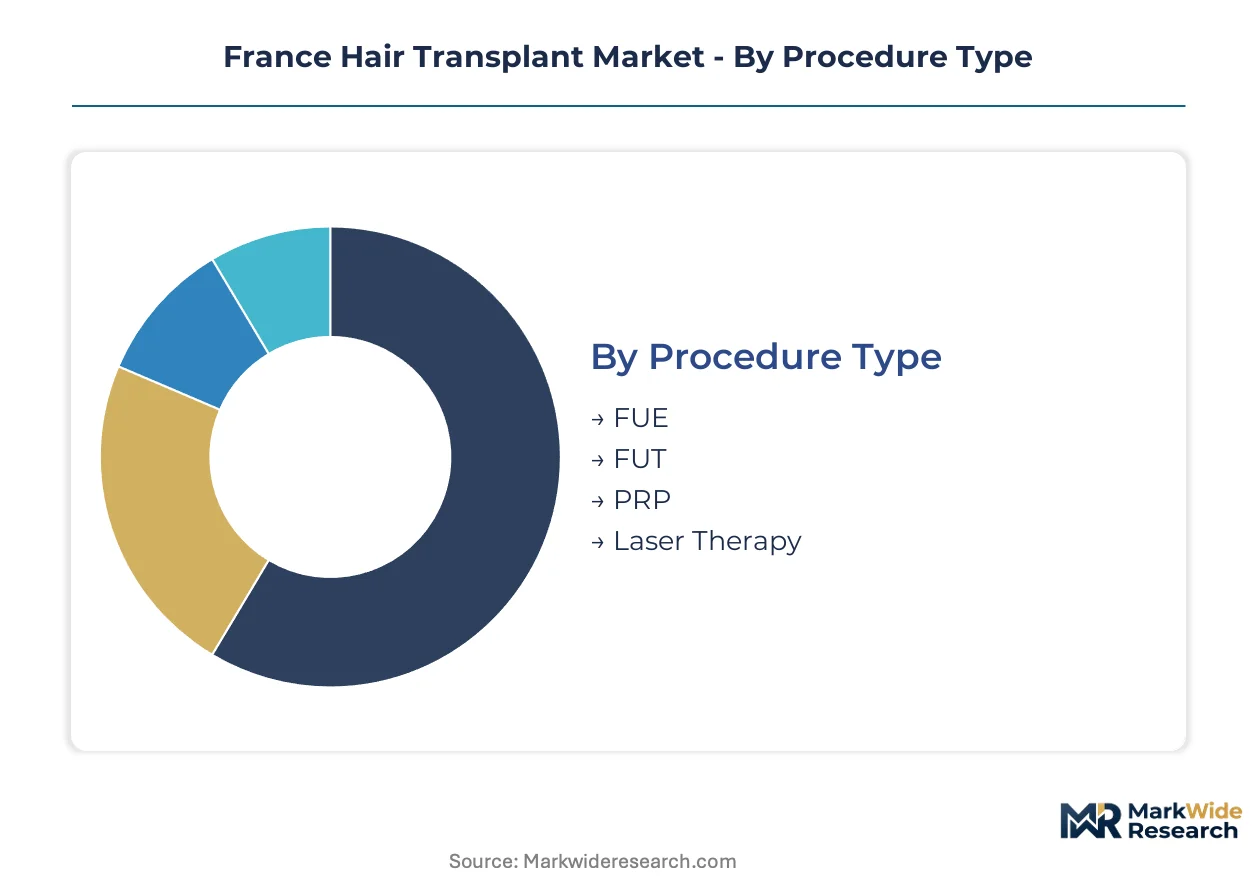
Segmentation in the French hair transplant market reveals how procedural preferences, technology adoption, and price sensitivity fragment demand across distinct buyer profiles. Understanding these divisions exposes where margin pools concentrate and which patient cohorts drive volume expansion.
Procedure Type:
Patient priorities around scarring visibility, recovery speed, and surgical invasiveness differentiate demand across extraction methodologies.
- FUE:Follicular unit extraction harvests individual grafts via micro-punch instruments, eliminating linear donor scars. Paris and Marseille clinics command premium positioning for FUE as the 35-50 male demographic prioritizes discreet recovery and return-to-work timelines.
- FUT:Follicular unit transplantation removes a strip of occipital scalp for dissection into grafts, maximizing yield per session for advanced Norwood stages. Demand concentrates in regional centers where cost sensitivity outweighs scar concealment preferences.
- PRP:Platelet-rich plasma injections serve adjuvant maintenance and early-stage alopecia intervention.
- Laser Therapy:Low-level laser devices target non-surgical candidates seeking pharmaceutical alternatives.
FUE leads volumes today; PRP is gaining share fastest as clinics bundle maintenance protocols.
Technology:
Capital deployment thresholds and precision requirements separate automated platforms from manual techniques.
- Robotic Systems:ARTAS and comparable platforms execute algorithm-guided follicular harvesting with sub-millimeter accuracy. Flagship Paris installations absorb seven-figure euro investments, capturing margin-rich segments as ANSM device scrutiny filters out undercapitalized operators.
- Manual Extraction:Surgeon-controlled punch instruments dominate procedural volume through lower capital barriers and tactile feedback advantages. Lyon and Bordeaux mid-tier clinics deploy semi-automated variants to match graft precision without flagship infrastructure.
- Platelet-Rich Plasma:Centrifuge-based concentration systems face pending ANSM borderline classification between medical devices and cosmetic products.
- Microneedling:Percutaneous collagen induction complements pharmaceutical regimens in medspa channels.
Manual extraction retains volume leadership; robotic systems are climbing the fastest as EU MDR recertification consolidates accredited installations.
End User:
Regulatory compliance capacity and patient acquisition economics determine which facility types capture specific price tiers.
- Clinics:Dedicated hair restoration facilities concentrate FUE and robotic procedure volume. Ile-de-France clinic density outpaces other French metropolitan areas through medical tourism infrastructure serving Belgian and Swiss cross-border flows.
- Hospitals:Academic medical centers handle complex reconstructive cases and corrective repair of prior surgical outcomes. Public hospital dermatology departments anchor patient trust for alopecia areata and scarring alopecia interventions.
- Private Practices:Individual surgeon boutiques compete on reputation premiums and personalized consultation models.
- Medspa:Aesthetic service chains capture PRP and laser therapy demand through lower-threshold entry points.
Clinics dominate current volumes; private practices are expanding most quickly as surgeon-led subscription aftercare models proliferate.
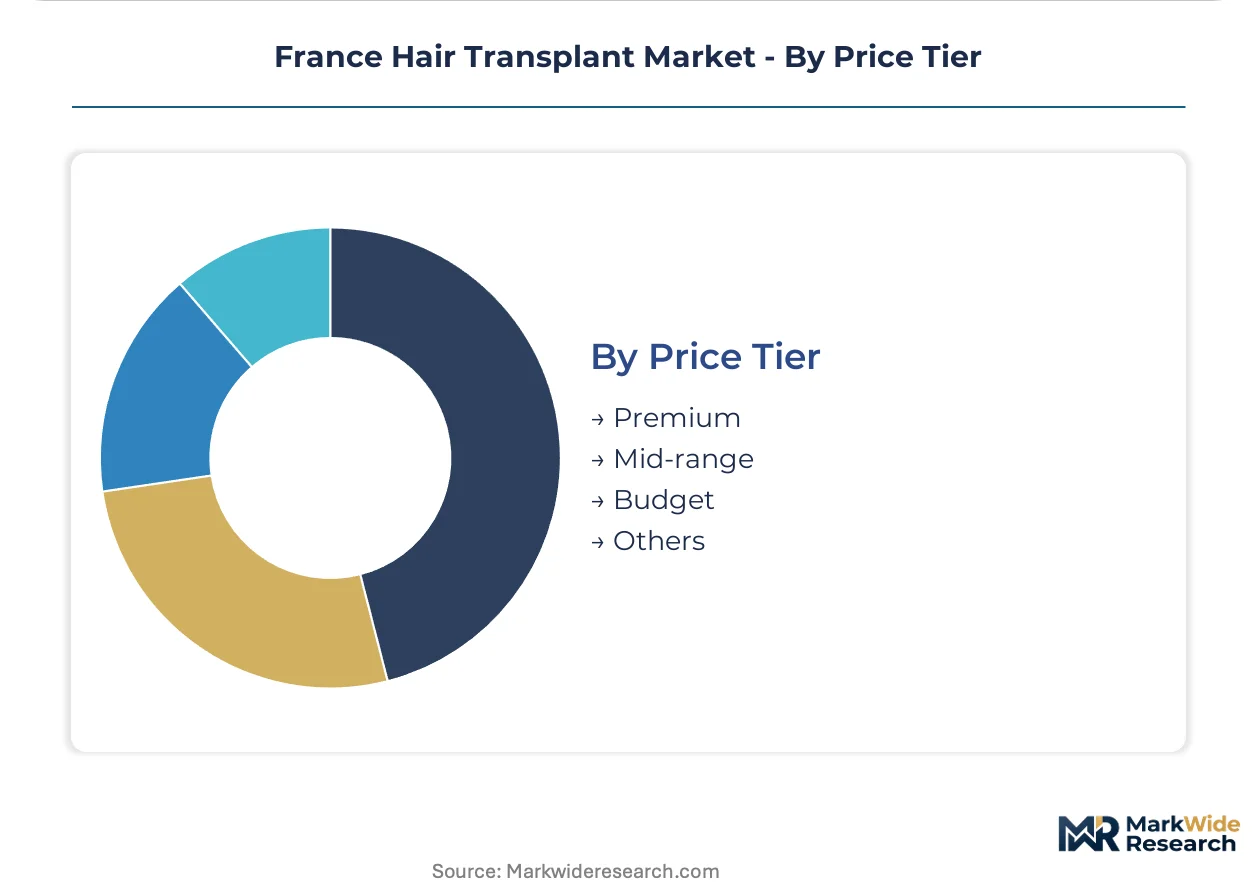
Price Tier:
Service bundling intensity and surgeon reputation premiums stratify accessible entry points from concierge positioning.
- Premium:Surgeon-led consultation, robotic extraction, and bundled aftercare protocols including trichoscopic monitoring and pharmaceutical adjuvants. Paris flagship locations absorb disproportionate profit share through reputation premiums and medical tourism capture.
- Mid-range:Hybrid manual-semi-automated extraction with standardized aftercare packages. Regional operators in Provence-Alpes-Côte d'Azur target Mediterranean medical tourism corridors with competitive positioning against Parisian benchmarks.
- Budget:High-volume chain models with technician-heavy staffing ratios and minimal aftercare bundling.
- Others:Emerging subscription and financing-embedded pricing experiments.
Mid-range pricing holds volume leadership today; premium tiers are gaining share fastest as patient acquisition shifts toward outcome-documented digital channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's medical tourism outflows to French clinics exceed Luxembourg's cross-border volumes, though Swiss patients command higher per-procedure spending in Parisian flagship locations. France's domestic market concentrates in three metropolitan corridors with distinct patient acquisition economics and regulatory compliance capacities.
Île-de-France
Paris and surrounding departments generate the highest procedure density through premium clinic clustering and international patient capture. ANSM oversight of medical device vigilance shapes accreditation standards for robotic extraction platforms. The capital's medical tourism infrastructure serves Belgian, Swiss, and Luxembourg cross-border demand through concierge consultation models.
Provence-Alpes-Côte d'Azur
Mediterranean medical tourism flows through Nice and Cannes remain underdeveloped relative to Paris, offering expansion headroom for premium operators. EU MDR recertification timelines for Class IIa extraction devices strain regulatory affairs capacity in smaller regional clinics. Marseille anchors competitive density through hybrid manual-automated service tiers targeting cost-sensitive international patients.
Auvergne-Rhône-Alpes
Lyon's mid-tier clinic networks deploy semi-automated extraction platforms to match graft precision without capital-intensive robotic installations. The national health agency's clinic accreditation framework shapes patient trust for corrective repair procedures. Regional operators compress price differentials against Parisian benchmarks through standardized procedural protocols.
Nouvelle-Aquitaine
Bordeaux's aesthetic service chains capture adjuvant maintenance demand through PRP and laser therapy entry points. Pending ANSM determinations on platelet-rich plasma classification create compliance ambiguity for bundled therapy providers. The Atlantic corridor lacks dedicated hair restoration infrastructure, forcing patient travel to Toulouse or Paris for complex cases.
Occitanie
Toulouse's academic medical centers handle scarring alopecia interventions and complex reconstructive cases through public hospital dermatology departments. French clinic accreditation through the national health agency anchors patient trust for corrective procedures. The region serves as a secondary catchment for Spanish cross-border demand from Catalonia and the Basque Country.
France Hair Transplant Market Competitive Landscape
Top-tier vendors anchor Parisian flagship positioning, while regional networks compete on accessibility and price-compressed service tiers. The market structures around surgeon reputation premiums versus technology-enabled efficiency plays, with ANSM device scrutiny filtering marginal operators. Three archetypes dominate: celebrity surgeon boutiques, automated platform networks, and high-volume chain operators. Consolidation pressures concentrate around M&A activity targeting accredited clinic assets and strategic partnerships for robotic system distribution.
Within the premium concierge tier, Vivant Hair Institute occupies a position exemplifying surgeon-led consultation models, while DHI International anchors brand recognition through standardized protocols. Base Medicale represents competitive density in secondary metropolitan markets. These three entities collectively illustrate the geographic and service-tier fragmentation shaping patient acquisition economics across French metropolitan corridors.
| Leading Market Players |
|---|
| Vivant Hair Institute |
| Base Medicale |
| Clinique du Rond-Point des Champs-Elysées |
| Marseille Micrograft Clinic |
| SeineEdge Hair Restoration |
| Racine² |
| DHI International |
| Dr. Christelle Santini |
| Maison Lutétia |
| Others |
Pricing and Supply Chain Analysis
Medical-grade titanium alloy pricing indices cascade through French hair transplant supply chains, compressing margins for mid-tier clinics while amplifying surgeon reputation premiums at Paris flagship locations. Raw material volatility in precision micro-punch instruments feeds directly into three-tier pricing stratification across premium concierge, mid-range hybrid, and budget chain operators.
Pricing Analysis
Capacity additions in Lyon and Bordeaux are reshaping price floors for manual extraction procedures, forcing Parisian premium operators to differentiate through bundled aftercare protocols. Pricing stratifies across premium robotic-assisted tiers anchored by ARTAS installations, mid-range hybrid manual-semi-automated service levels, and economy technician-heavy chain models. Cost compression in budget segments intensifies because high-volume operators sacrifice trichoscopic monitoring and pharmaceutical adjuvants. Corporate procurement teams at multinational employers show least price sensitivity, financing employee restoration through supplemental health benefits.
Supply Chain Analysis
Refurbishment flows for robotic extraction platforms concentrate in Germany and Switzerland, where authorized service centers extend ARTAS system lifecycles for secondary French clinic markets. French supply chains draw from Italian precision instrument manufacturers, German optical component specialists, and Belgian graft preservation solution formulators. Single-source vulnerability concentrates in algorithm-dependent extraction software updates controlled by California-based platform developers. Distribution runs through accredited clinic networks with ANSM quality management certification, bypassing unauthorized gray-market device channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's hair transplant market compounds regulatory complexity into competitive advantage, with EU MDR recertification deadlines for Class IIa extraction devices filtering marginal operators and concentrating accredited clinic assets. ANSM medical device vigilance obligations now shape patient trust and pricing power simultaneously.
For Market Incumbents: Anticipate margin compression from semi-automated platform diffusion in Lyon and Bordeaux by securing early CE marking renewal for robotic systems under EU MDR timelines. Consolidate supplier relationships with Italian micro-punch manufacturers before notified body backlogs extend procurement cycles. Channel control through exclusive distribution agreements for graft preservation solutions defends against emerging chain operators. For New Entrants and Emerging Players: Launch via teleconsultation pre-screening models to capture geographic catchment without physical clinic footprint in underdeveloped Provence-Alpes-Côte d'Azur corridors. Target Mediterranean medical tourism flows through Nice and Cannes with hybrid manual-automated service tiers priced against Parisian benchmarks. White-space positioning concentrates in subscription aftercare protocols combining PRP sessions with trichoscopic monitoring. For Investors and Strategic Acquirers: Consolidation pressure builds where ANSM accreditation gaps separate compliant quality management systems from documentation-deficient regional operators. Long-term viability favors acquiring clinic assets with validated EU MDR technical files and established surgeon training pipelines. The signal to watch is notified body queue length for Class IIa extraction device recertification, which will determine which mid-tier operators face forced exit.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Validates robotic platform compliance before notified body backlogs extend certification cycles. |
| Surgeon Training Pipeline Investment | Addresses France's standardized fellowship gap through partnerships with Turkish training centers. |
| Teleconsultation Platform Launch | Expands geographic catchment without physical clinic footprint in underserved regional corridors. |
| Subscription Aftercare Model | Creates recurring revenue streams beyond one-time transplantation through PRP and monitoring bundles. |
| Mediterranean Medical Tourism Partnership | Captures Belgian and Swiss cross-border flows through Nice and Cannes concierge positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with clinic medical directors, ANSM regulatory affairs specialists, biomedical procurement managers at hospital systems, and trichosurgeon training program coordinators. Secondary validation drew from ANSM medical device vigilance databases, EU MDR notified body guidance documents, French national health agency accreditation records, and Ile-de-France medical tourism infrastructure assessments. Bottom-up clinic capacity estimates and top-down procedural volume benchmarks were triangulated against cross-border patient flow data.
Segment-weighting approaches distributed value and volume across procedure type, technology platform, end-user facility category, and price tier dimensions throughout the projection horizon. CAGRs were derived from logarithmic trend fitting against historical procedural volumes and technology adoption curves. Forecast inputs incorporated EU MDR implementation timelines, ANSM borderline classification determinations for PRP devices, and robotic platform installation pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended notified body backlogs or accelerated ANSM enforcement actions. Forecasts reflect documented assumptions regarding surgeon training pipeline expansion and cross-border patient mobility patterns. Practitioners should monitor CE marking suspension announcements and PRP device reclassification determinations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
China Hair Transplant Market
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
North America Dermal Fillers Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Korea Medical Aesthetics Market
Medical Aesthetics
Injectable Anti-Wrinkle Treatment Market
Medical Aesthetics
UK Hair Transplant Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Breast Reconstruction and Augmentation Market
Medical Aesthetics
Facial Injectables Market
Medical Aesthetics
Contouring Implants Market
Medical Aesthetics
Japan Hair Transplant Market