
 Alexandrite Laser Treatment Market | 2026-2036
Alexandrite Laser Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Alexandrite Laser Treatment Market Analysis
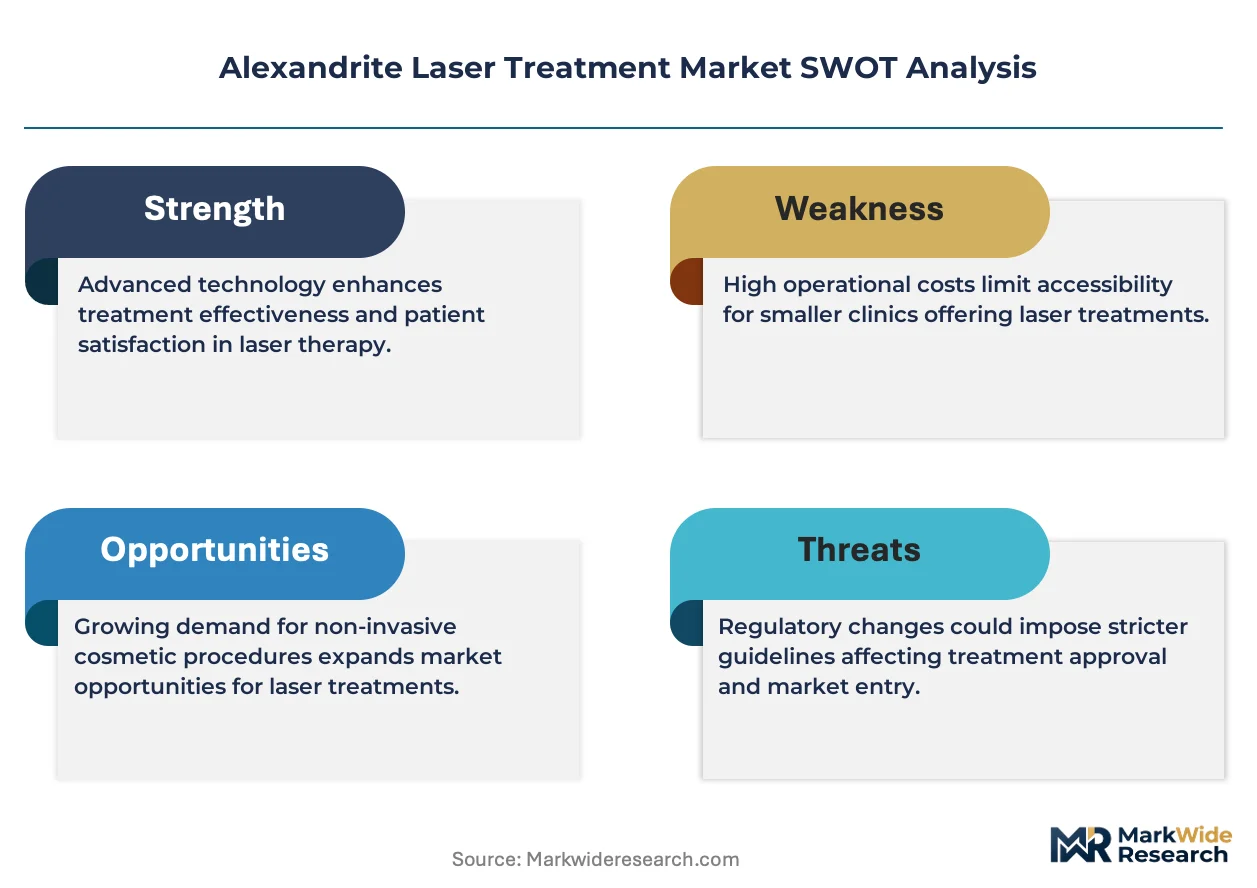
Modular platform configurations that separate laser handpieces from base power units is realigning capital expenditure patterns across buyer segments. Candela leverages interchangeable handpiece architectures to reduce per-clinic equipment replacement cycles. Cynosure sustains competitive positioning through integrated cooling systems that expand treatable patient phenotypes. Alma Lasers anchors its geographic footprint with region-specific service contracts that lower total cost of ownership for dermatology networks.
Alexandrite laser treatment employs a solid-state laser medium of chromium-doped chrysoberyl crystals emitting at 755 nanometers, selectively targeting melanin-rich structures through photothermolysis while sparing adjacent tissue. Hair removal applications dominate procedure volumes due to large addressable patient populations and repeatable treatment protocols. Q-switched technology commands premium positioning in tattoo removal where picosecond pulse durations improve pigment fragmentation. Dermatology clinics represent the fastest-growing end-user channel as physician extenders and nurse practitioners expand service capacity under delegated supervision models.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards govern device safety and clinical performance claims across the two largest commercial jurisdictions. ISO 13485 quality management certification functions as a baseline qualification for Original Equipment Manufacturer partnerships and private-label distribution agreements. Stakeholders must monitor evolving state-level scope-of-practice regulations that determine whether non-physician operators can independently administer Alexandrite procedures, as this directly constrains addressable clinic density and equipment utilization rates.
Market Dynamics
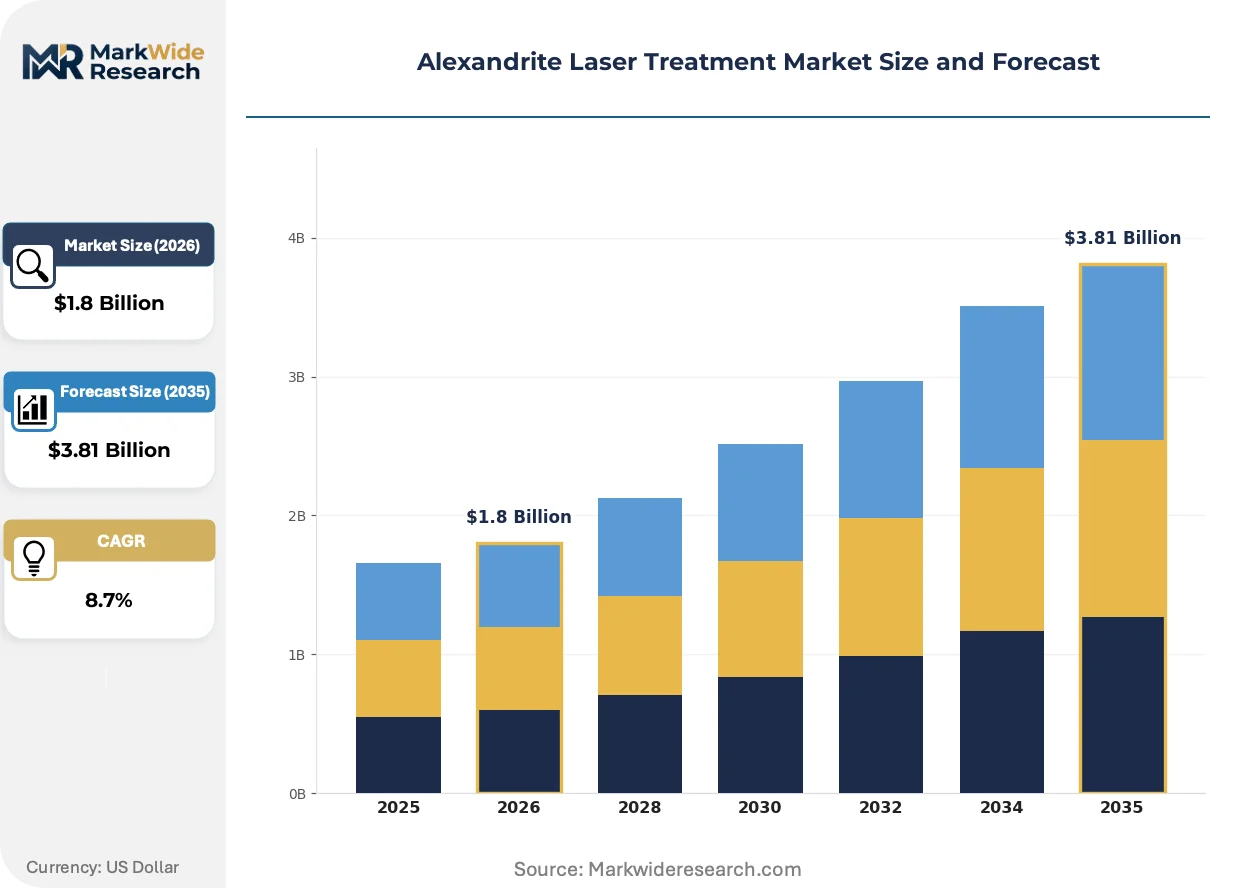
Modular handpiece architectures are compressing equipment replacement cycles and redistributing capital deployment across dermatology networks, forcing manufacturers to restructure service revenue models around consumables and preventive maintenance contracts rather than upfront hardware sales.
Growth Catalysts
- EU MDR technical documentation standards:Harmonized clinical evidence requirements accelerate cross-border device approvals, reducing time-to-market for manufacturers with existing ISO 13485 certification.
- Photothermolysis protocol refinements:Enhanced pulse-width modulation expands treatable skin type ranges, opening procedures to previously excluded patient demographics in Mediterranean and Middle Eastern populations.
- Dermatology clinic consolidation:Private equity-backed platform rollups generate centralized procurement volumes that justify premium device configurations with integrated cooling systems.
Market Restraints
- Chromium-doped chrysoberyl crystal supply:Synthetic crystal growth requires 8-12 week lead times from specialized optical materials suppliers concentrated in Germany and Japan.
- FDA 510(k) predicate device dependencies:Substantial equivalence determinations tether innovation to existing clearance profiles, constraining radical wavelength or pulse-structure modifications.
- Diode laser substitution:Lower-cost 808nm and 1064nm systems capture price-sensitive hair removal volumes in emerging markets with less melanin-selective requirements.
Strategic Opportunities
- Delegated supervision expansion:State-level scope-of-practice liberalization permits nurse practitioner-led procedures in Texas, Florida, and Arizona, multiplying addressable clinic density.
- Picosecond pulse convergence:Q-switched Alexandrite platforms integrate with Nd:YAG sources for multi-wavelength tattoo removal protocols commanding premium pricing.
- Preventive maintenance unbundling:Subscription-based handpiece refurbishment programs generate recurring revenue independent of new equipment sales cycles.
Industry Challenges
- Laser safety officer certification:ANSI Z136.3 compliance training creates bottlenecks in clinic staffing, particularly in markets with limited biomedical technician pipelines.
- Legacy cooling system integration:Air-cooled handpiece retrofits into water-chilled base units require electrical and plumbing modifications that extend installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alexandrite Laser Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Removal, Tattoo Removal, Skin Rejuvenation, Pigmentation Treatment End User: Dermatology Clinics, Cosmetic Surgery Centers, Hospitals, Beauty Salons Technology: Q-Switched, Pulsed, Continuous Wave, Fractional Application: Aesthetic Procedures, Medical Treatments, Scarring, Vascular Lesions |
| Companies Covered | Candela, Cynosure, Lutronic, DEKA, Lumenis, Alma Lasers, Asclepion, Quanta Systems, Fotona, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alexandrite Laser Treatment Market Emerging Trajectories
Real-time skin temperature monitoring and adaptive fluence adjustment are transforming procedure safety profiles while compressing operator training requirements across mid-tier clinic segments.
Picosecond pulse generation technology is converging with traditional nanosecond Alexandrite platforms, enabling dual-mode systems that dermatology clinics deploy across both hair reduction and pigment disorder indications without redundant capital expenditure. Academic medical centers in South Korea and Germany pilot these hybrid configurations for consolidated device footprints. The convergence is compressing standalone Q-switched system demand while elevating service contract complexity.
EU MDR post-market surveillance requirements now mandate systematic clinical follow-up data collection for all Class IIa laser devices, compelling manufacturers to fund registry studies or risk Notified Body withdrawal of certificates. German and French dermatology networks face expanded documentation burdens for adverse event reporting. The regulation is accelerating consolidation among smaller OEMs lacking pharmacovigilance infrastructure.
Leasing arrangements with bundled consumables are displacing outright purchase models among independent dermatology practices facing compressed credit availability. Third-party equipment financiers in the United States structure 36-48 month operating leases with per-pulse pricing tiers that align costs to utilization. The shift is most visible in metropolitan Texas and California markets where private equity clinic rollups dominate competitive dynamics.
Alexandrite Laser Treatment Market Segmentation
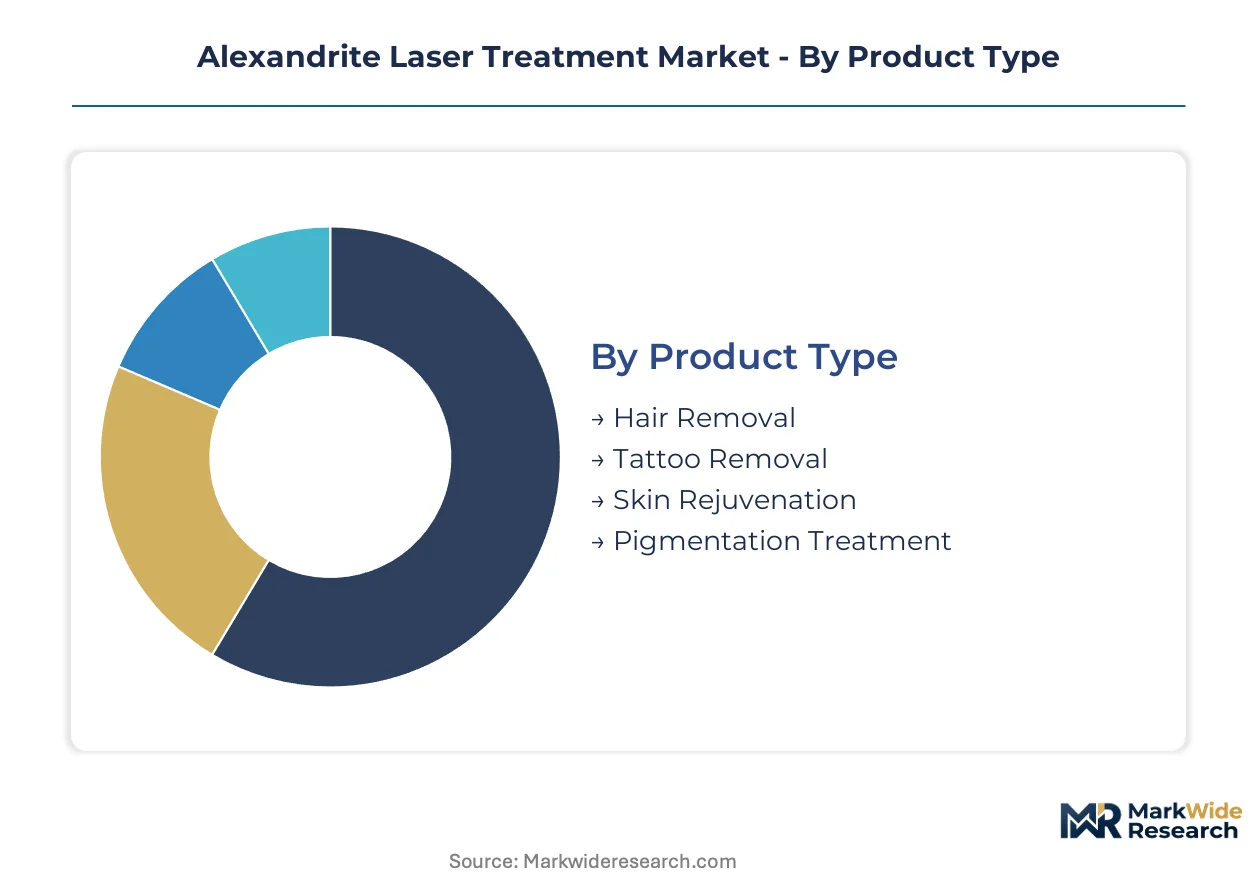
Segmentation reveals how capital deployment patterns diverge across buyer types and procedure categories. Equipment configurations, cooling specifications, and operator certification requirements create distinct purchasing criteria that manufacturers must address through modular platform architectures.
Product Type:
Upgrade cycles compress fastest where procedure volumes justify dedicated device footprints, pushing clinics toward multi-wavelength platforms that amortize capital across indications.
- Hair Removal:755nm wavelength selectively targets melanin in hair follicles through photothermolysis, enabling treatment of darker hair on lighter skin types. Demand concentrates in dermatology networks across Texas and Florida where delegated supervision laws expand nurse practitioner-operated service capacity.
- Tattoo Removal:Q-switched and picosecond pulse durations fragment pigment particles for lymphatic clearance. Premium positioning in South Korean aesthetic medicine clusters drives adoption of dual-mode systems combining Alexandrite with Nd:YAG sources.
- Skin Rejuvenation:Fractional delivery patterns stimulate collagen remodeling through controlled thermal injury.
- Pigmentation Treatment:Melanin-selective absorption addresses solar lentigines and café-au-lait macules.
Hair Removal sits at the top of the volume ranking, with Tattoo Removal climbing the fastest.
End User:
Procurement authority centralizes differently across buyer types, with private equity-backed networks demanding standardized device fleets that simplify training and service logistics.
- Dermatology Clinics:Physician-owned and private equity-platform practices generate the highest equipment utilization rates through dedicated laser service lines. Consolidated procurement across California and Texas metro markets justifies premium configurations with integrated cooling systems.
- Cosmetic Surgery Centers:Combined surgical and non-surgical service menus require versatile platforms spanning multiple wavelengths.
- Hospitals:Academic medical centers in Germany pilot hybrid picosecond-nanosecond systems for consolidated device footprints.
- Beauty Salons:Scope-of-practice limitations restrict this channel to jurisdictions permitting non-physician operators.
Dermatology Clinics command the largest installed base, with Cosmetic Surgery Centers gaining share fastest.
Technology:
Cost tier stratification separates premium pulse-structure innovations from established thermal delivery modes, with reimbursement and out-of-pocket pricing dynamics determining adoption ceilings.
- Q-Switched:Nanosecond pulse durations generate peak power densities for photoacoustic pigment disruption. Tattoo removal protocols in South Korean university hospitals drive validation studies for multi-wavelength sequencing.
- Pulsed:Millisecond pulse widths optimize hair follicle thermal damage while preserving epidermal integrity through epidermal cooling.
- Continuous Wave:Sustained emission patterns suit vascular lesion coagulation with precise thermal control.
- Fractional:Micro-beam arrays create treatment columns surrounded by untreated tissue for rapid re-epithelialization.
Pulsed technology maintains the broadest installed base, with Q-Switched expanding most quickly.
Application:
Volume concentration varies sharply between elective aesthetic procedures and medically indicated treatments, with the latter constrained by prior authorization requirements and narrower addressable populations.
- Aesthetic Procedures:Elective hair reduction and skin rejuvenation generate repeatable revenue streams through multi-session protocols. German dermatology networks leverage EU MDR harmonized standards to deploy consistent device configurations across cross-border clinic platforms.
- Medical Treatments:Physician-directed protocols for benign pigmented lesions and vascular malformations require diagnostic expertise that limits addressable operator pools.
- Scarring:Fractional resurfacing addresses acne and traumatic scar remodeling through collagen neogenesis.
- Vascular Lesions:Hemoglobin-competing absorption at 755nm enables treatment of superficial vascular structures.
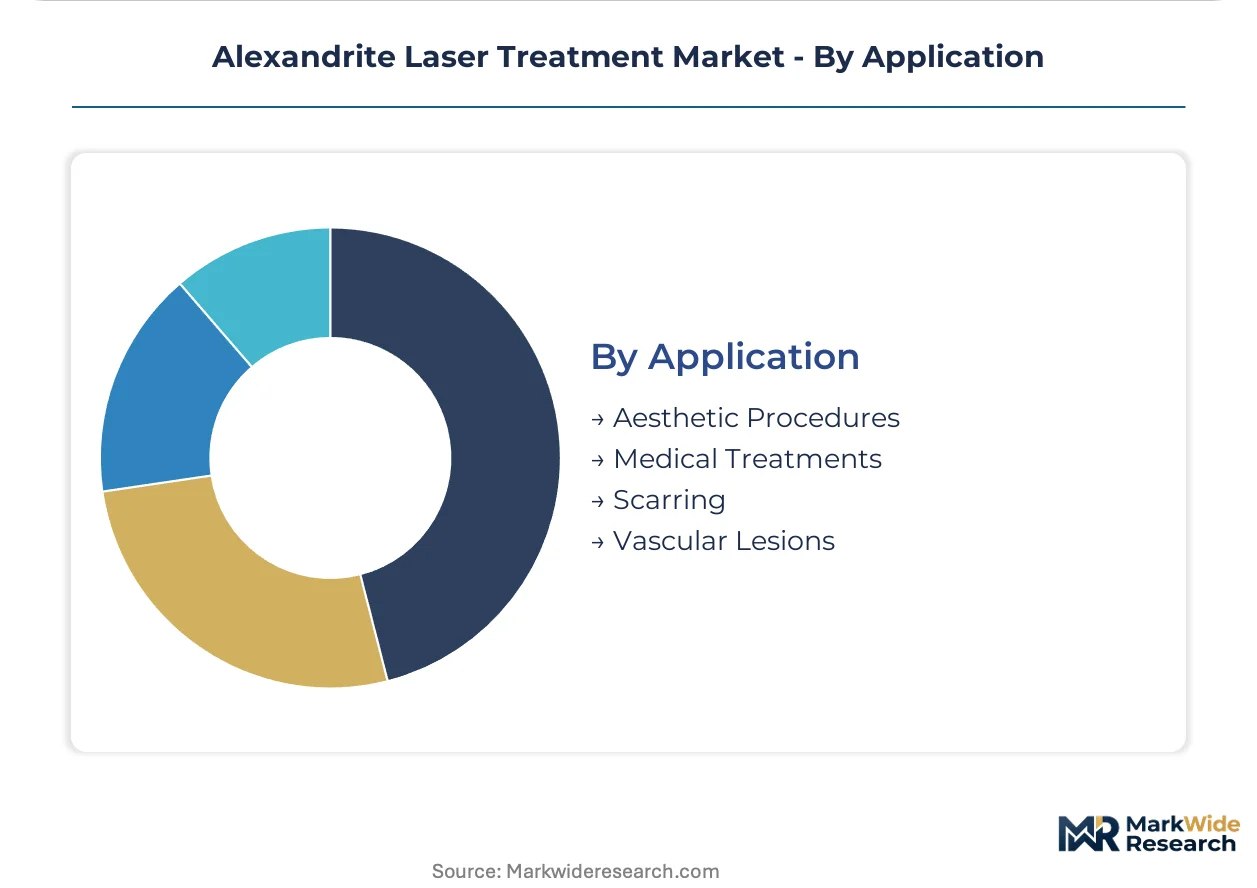
Aesthetic Procedures dominate procedure volumes, with Medical Treatments advancing on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Alexandrite laser treatment industry traces its commercial roots to United States dermatology practices during the 1990s, where 755nm technology first displaced ruby lasers for hair removal protocols. German optical engineering subsequently refined crystal growth and pulse-delivery architectures, establishing cross-Atlantic technology transfer patterns that persist in current supply chains.
United States
Texas and Florida metro markets concentrate demand through private equity-backed dermatology rollups that centralize procurement of multi-wavelength platforms. FDA 510(k) clearance pathways govern device commercialization timelines, with predicate device dependencies shaping innovation boundaries. Dallas and Houston clinic networks drive utilization of delegated supervision models that expand nurse practitioner-operated service capacity.
Germany
Bavarian and Baden-Württemberg manufacturing clusters anchor synthetic chrysoberyl crystal production for laser rod fabrication. EU MDR technical documentation standards and Notified Body oversight govern CE marking timelines, with post-market surveillance mandates compelling registry study investments. Munich university hospitals pilot hybrid picosecond-nanosecond configurations for consolidated device footprints across aesthetic and medical indications.
South Korea
Seoul Capital Area aesthetic medicine districts command premium positioning for Q-switched and picosecond tattoo removal systems. MFDS device licensing requirements align with international standards while enabling accelerated approvals for manufacturers with prior FDA or CE certifications. Gangnam district clinics drive validation studies for multi-wavelength sequencing protocols that combine Alexandrite with Nd:YAG sources.
Japan
Tokyo and Osaka metropolitan markets sustain demand through aging demographics seeking pigmentation and vascular lesion treatments. PMDA pre-market approval processes emphasize clinical evidence standards comparable to FDA requirements, with METI industrial policy supporting domestic optical materials capabilities. Kanto region dermatology networks prioritize integrated cooling systems that expand treatable patient phenotypes across Fitzpatrick skin type ranges.
Brazil
São Paulo and Rio de Janeiro aesthetic service markets absorb lower-cost device configurations amid price-sensitive competitive dynamics. ANVISA medical device registration requirements create documentation burdens that favor established multinational suppliers with regulatory affairs infrastructure. Southeast Brazil clinic networks concentrate hair removal volumes where melanin-selective absorption properties address diverse patient populations.
Alexandrite Laser Treatment Market Vendor Landscape
The competitive structure tilts toward diversified laser platform manufacturers with established service networks. Consolidation patterns favor integrated cooling system architectures and modular handpiece configurations that compress replacement cycles. Three archetypes dominate: full-spectrum aesthetic device conglomerates, specialized dermatology laser pure-plays, and regional OEMs with private-label distribution capabilities. M&A activity concentrates on service contract portfolios and preventive maintenance revenue streams, while geographic expansion targets state-level scope-of-practice liberalization corridors.
Among diversified platform manufacturers, Candela and Cynosure exemplify the full-spectrum archetype with interchangeable handpiece architectures and integrated cooling systems that anchor competitive positioning across North American and European dermatology networks. Alma Lasers occupies a distinct tier through region-specific service contracts that lower total cost of ownership for consolidated clinic platforms. These three entities represent the dominant competitive anchors in current procurement dynamics.
| Leading Market Players |
|---|
| Candela |
| Cynosure |
| Lutronic |
| DEKA |
| Lumenis |
| Alma Lasers |
| Asclepion |
| Quanta Systems |
| Fotona |
| Others |
Supply Flow & Price Mechanics
Captive crystal production in Germany and Japan anchors supply security for premium device tiers while compressing margin structures for manufacturers without in-house optical materials capabilities. This vertical integration choice separates pricing power between conglomerates with controlled rod fabrication and assemblers exposed to spot-market chrysoberyl volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by cooling system sophistication and pulse-width modulation capability. Price differentiation rests on ISO 13485 certification tier and integrated epidermal cooling specifications. Pricing pressure stems from diode laser substitution in emerging markets with less melanin-selective requirements. Independent dermatology practices in Texas and Florida exhibit highest price sensitivity, while private equity-backed clinic networks absorb premium configurations through centralized procurement.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese optical materials suppliers mandate multi-supplier qualification for chrysoberyl crystal rods and xenon flashlamp assemblies. Synthetic crystal growth draws from specialized chemical vapor deposition facilities in Bavaria and Osaka. Single-source vulnerability concentrates in synthetic chrysoberyl feedstock where 8-12 week lead times constrain rapid scaling. Distribution runs through authorized service distributors with preventive maintenance bundling in North American and European dermatology networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on preventive maintenance unbundling and consumables-based revenue models that decouple growth from hardware replacement cycles.
For Market Incumbents: Cement service contract dominance through region-specific preventive maintenance programs that lower total cost of ownership for consolidated dermatology networks. Backward integration into synthetic chrysoberyl crystal production insulates against Japanese and German supply bottlenecks. Counter diode laser substitution by expanding treatable skin type ranges through adaptive fluence technologies.
For New Entrants and Emerging Players: Nurse practitioner-operated clinics in scope-of-practice liberalization corridors represent the most penetrable buyer archetype. Target delegated supervision markets in Arizona and metropolitan Texas with leasing arrangements that displace outright purchase models. Enter through third-party equipment financiers structuring per-pulse pricing tiers that align costs to utilization.
For Investors and Strategic Acquirers: Consolidation pressure builds where pharmacovigilance infrastructure gaps expose smaller OEMs to EU MDR post-market surveillance withdrawal. Long-term viability favors targets with installed base density sufficient to support subscription-based handpiece refurbishment programs. Monitor state-level scope-of-practice legislation as the primary inflection signal for addressable clinic density expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Unbundling | Subscription-based handpiece refurbishment generates recurring revenue independent of new equipment sales cycles. |
| EU MDR Technical Documentation Pathway | Harmonized clinical evidence requirements accelerate cross-border approvals for ISO 13485-certified manufacturers. |
| Delegated Supervision Expansion | State-level scope-of-practice liberalization in Texas and Florida multiplies addressable clinic density for nurse practitioner-led procedures. |
| Picosecond Pulse Convergence | Dual-mode Alexandrite-Nd:YAG systems command premium pricing in South Korean tattoo removal protocols. |
| Region-Specific Service Contracts | Localized maintenance agreements lower total cost of ownership for private equity-backed dermatology rollups. |
Methodological Framework
Direct dialogue with dermatology clinic operators, biomedical equipment procurement managers, laser safety officers, and GPO contracts administrators grounded the qualitative foundation. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR Notified Body technical documentation filings, hospital procurement contract registries, and ISO 13485 certification records. Bottom-up and top-down triangulation reconciled equipment shipment data with procedure volume estimates across the analysis window.
Bottom-up modeling aggregated individual country-level demand trajectories while top-down cross-checks validated aggregate market sizing against capital expenditure patterns in consolidated dermatology networks. Segmentation dimensions spanned product type, end-user channel, pulse-structure technology, and application indication. CAGRs were derived from fitted growth curves anchored to historical equipment replacement cycles and projected clinic density expansion. Industry-specific inputs included synthetic chrysoberyl crystal supply lead times and state-level scope-of-practice regulatory status.
Underlying measurement precision varies by segment; hair removal and dermatology clinic channels carry tighter precision than tattoo removal and hospital segments due to more transparent procurement patterns. Forecasts reflect assumptions regarding EU MDR enforcement consistency, delegated supervision legislative trajectories, and diode laser substitution elasticity. Deviation in synthetic chrysoberyl supply disruption or FDA predicate device pathway modification would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aesthetic Medicine
Skin Tightening Market
Aesthetic Medicine
Aesthetic Laser Market
Aesthetic Medicine
Asia Pacific Aesthetics Market
Aesthetic Medicine
Spa Market
Aesthetic Medicine
Saudi Arabia Facial Aesthetics Market
Aesthetic Medicine
Aesthetic Lasers and Energy Devices Market
Aesthetic Medicine
Non-Invasive Aesthetic Treatment Market
Aesthetic Medicine
Body Contouring Market
Aesthetic Medicine
North America Medical Aesthetic Devices Market
Aesthetic Medicine
Asia-Pacific Dermal Fillers Market
Aesthetic Medicine
Aesthetics Combination Therapy Market
Aesthetic Medicine
Customized China Aesthetics Equipment Market
Aesthetic Medicine
Asia-Pacific Facial Aesthetics Market
Aesthetic Medicine
Carboxy Therapy Market
Aesthetic Medicine
Phototherapy Lamps and Units for Aesthetic Medicine Market
Aesthetic Medicine
Middle East and Africa Dermal Fillers Market