
 Australia Endoscopy Devices Market | 2026-2036
Australia Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Endoscopy Devices Market Outlook
Single-use endoscope technology is tilting procurement patterns away from capital-intensive reusable systems toward per-procedure consumption models. Medtronic Plc leverages its broad therapeutic portfolio to anchor hospital supply contracts across Australia's major health networks. Olympus Corporation sustains dominance in flexible gastrointestinal platforms through deep service infrastructure and technician training programs. Ambu A/S differentiates with fully disposable bronchoscope and cystoscope lines that eliminate reprocessing compliance burdens for smaller facilities.
Endoscopy devices are instruments comprising insertion tubes with integrated optical or digital imaging channels, illumination systems, and instrument channels for biopsy or therapeutic intervention, manufactured with medical-grade polymers and stainless steel alloys to withstand repeated sterilization or designed for single-use disposal. Flexible endoscopes lead procedural volume in gastroenterology and pulmonology applications where anatomical navigation demands steerable distal tips, while robot-assisted endoscopes represent the fastest-expanding category as hospitals seek precision in complex interventions. Capsule endoscopes occupy a specialized niche for small-bowel visualization where conventional scope insertion proves technically difficult.
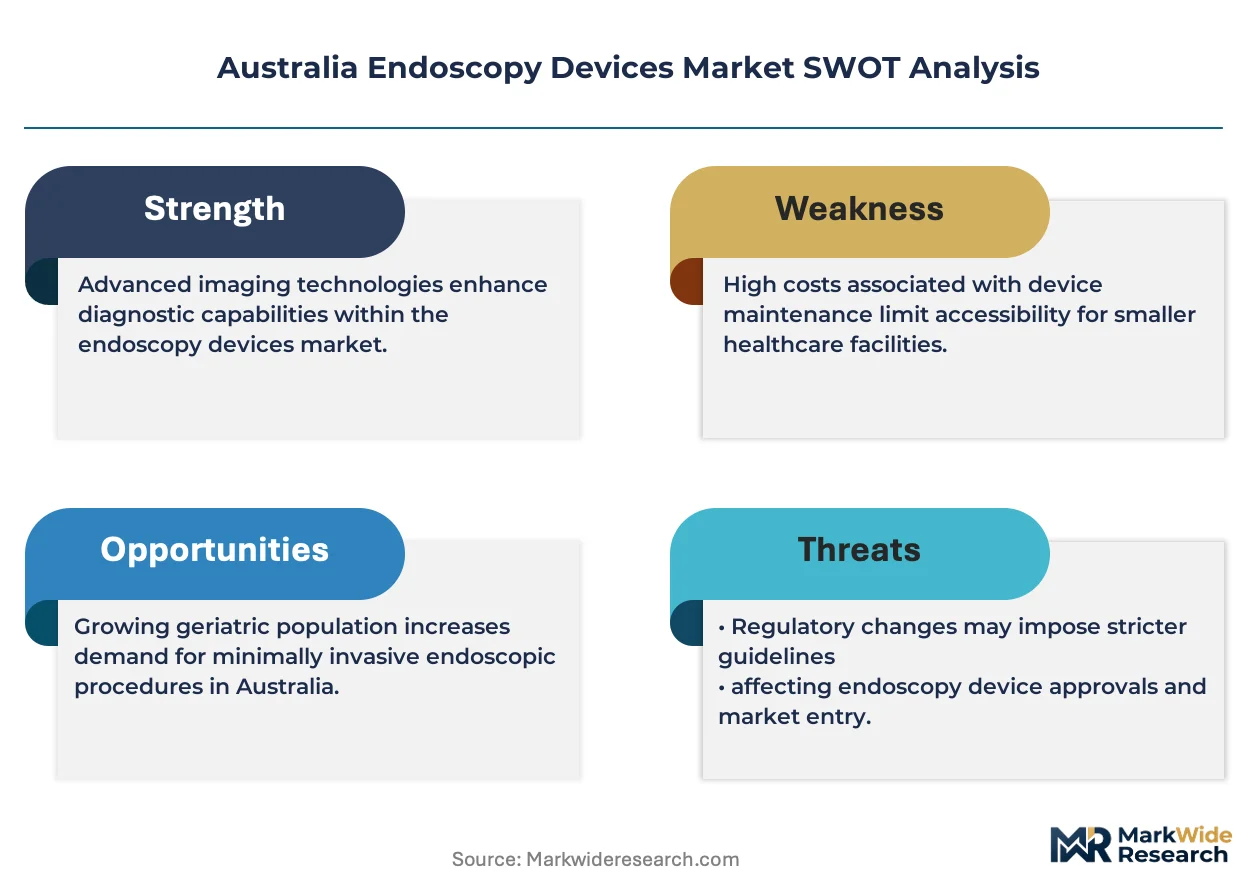
TGA governs device registration and post-market surveillance under the Therapeutic Goods Act, while the Australian Commission on Safety and Quality in Health Care enforces endoscope reprocessing standards that directly influence purchasing decisions between reusable and disposable platforms. Health facilities must reconcile TGA requirements with state-level infection control protocols administered by New South Wales Health and Queensland Health. Stakeholders should monitor how TGA's evolving guidance on single-use device equivalence compares against reusable instrument lifecycle economics.
Market Dynamics
Single-use endoscope technology is compressing capital expenditure cycles across Australian hospital networks, converting fixed asset investments into variable per-procedure costs that align with episodic funding models.
Growth Catalysts
- Colorectal screening expansion:Australia's National Bowel Cancer Screening Program drives procedural volume growth in New South Wales and Victoria hospital networks, requiring expanded endoscopy suite capacity.
- TGA reprocessing standards:Updated Therapeutic Goods Administration guidelines on reusable device sterilization accelerate facility-level evaluation of disposable alternatives.
- Metropolitan hospital consolidation:Networked procurement across Sydney, Melbourne, and Brisbane creates volume concentration that favors standardized platform deployments.
Market Restraints
- Polymer supply concentration:Medical-grade polymer feedstocks for single-use scope housings concentrate among Asian specialty chemical suppliers, exposing Australian manufacturers to input cost volatility.
- Service infrastructure lock-in:Deep technician training programs and proprietary maintenance networks for flexible platforms create switching friction for incumbent reusable systems.
- Reimbursement compression:Medicare Benefits Schedule adjustments constrain per-procedure revenue, limiting hospitals' appetite for premium disposable technologies.
Strategic Opportunities
- Regional hospital penetration:Queensland and Western Australia regional facilities remain underpenetrated by disposable bronchoscope and cystoscope platforms, presenting expansion whitespace.
- Robot-assisted integration:Convergence of flexible endoscopy with robotic articulation systems enables precision interventions in complex gastrointestinal procedures.
- State infection control mandates:Queensland Health and New South Wales Health protocols create procurement preference for single-use devices in outbreak-sensitive settings.
Industry Challenges
- Specialized technician shortage:Gastroenterology nursing and scope reprocessing certification programs face enrollment gaps that delay facility expansion timelines.
- Legacy platform integration:Hybrid workflows combining reusable and disposable systems require IT infrastructure reconfiguration and staff retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Endoscopy Devices Market |
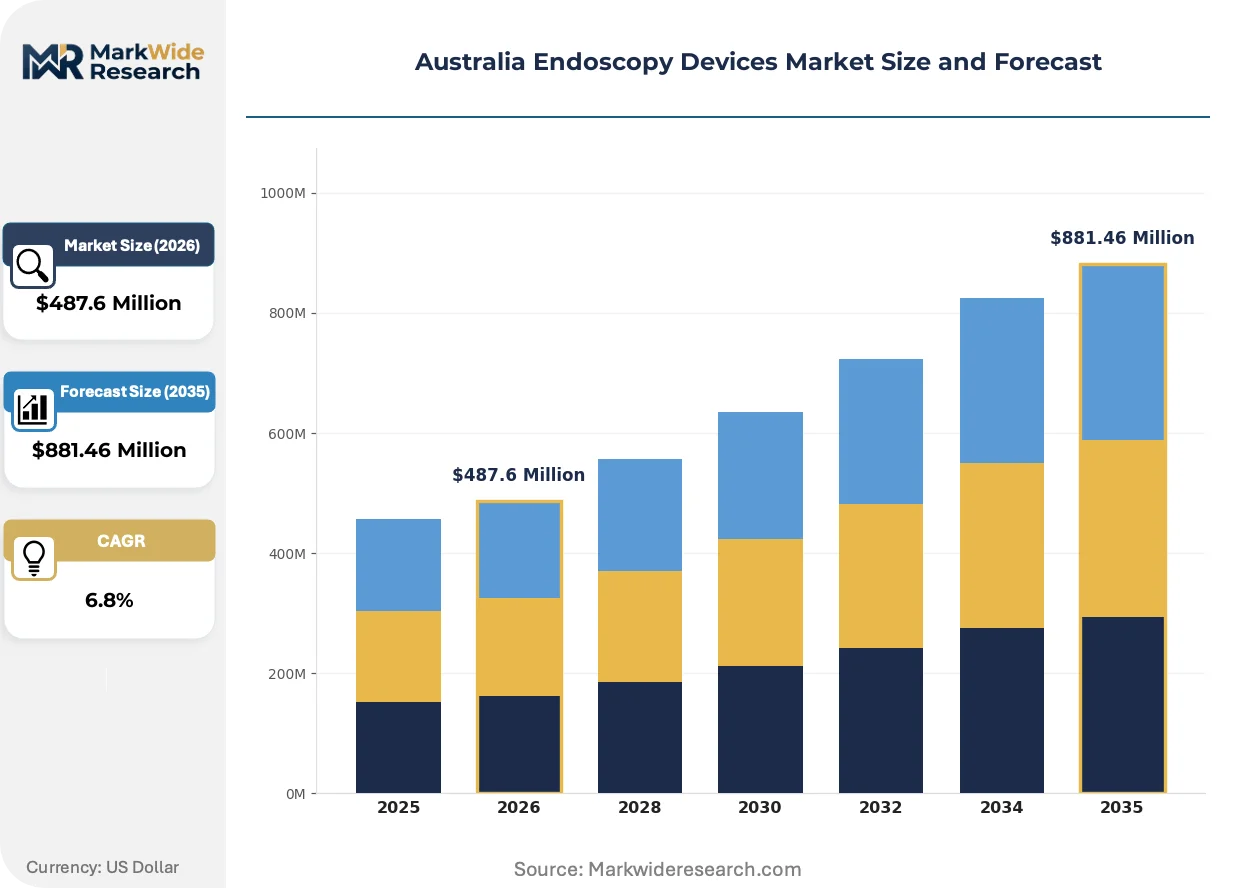
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Capsule Endoscopes, Robot-Assisted Endoscopes Technology: Optical, Video, Wireless, Hybrid End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialty Clinics Application: Gastroenterology, Pulmonology, Urology, Gynecology |
| Companies Covered | Medtronic Plc, STERIS PLC, Olympus Corporation, Johnson & Johnson (Ethicon), Ambu A/S, Stryker Corporation, Hoya Group (PENTAX Medical), Karl Storz GmbH & Co KG, FUJIFILM Holdings Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Endoscopy Devices Market Strategic Shifts
Digital imaging and disposable materials are restructuring how Australian hospitals acquire, deploy, and retire endoscopy equipment across procedural workflows.
CMOS sensor technology is digitizing image capture at the distal tip of flexible endoscopes, eliminating fiber optic bundles that degrade with repeated sterilization. Metropolitan hospital networks in Sydney and Melbourne are adopting these platforms for high-volume gastroenterology suites. The shift is digitizing maintenance economics by reducing scope damage rates and extending functional lifecycles for capital equipment.
TGA guidance on single-use device equivalence is tightening documentation requirements for manufacturers seeking reusable instrument substitutions. The regulatory friction is compressing approval timelines for novel disposable platforms while grandfathering established reusable systems. Smaller facilities in Brisbane and Perth are responding by accelerating pilot programs for fully disposable lines that bypass reprocessing compliance entirely.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, negotiating standalone maintenance agreements or third-party technical support. This behavioral shift disrupts manufacturer-captive service networks that historically anchored long-term supply relationships. The pattern is most visible in Victoria's consolidated health networks, where centralized procurement functions extract service pricing transparency through competitive tendering.
Australia Endoscopy Devices Market Segmentation
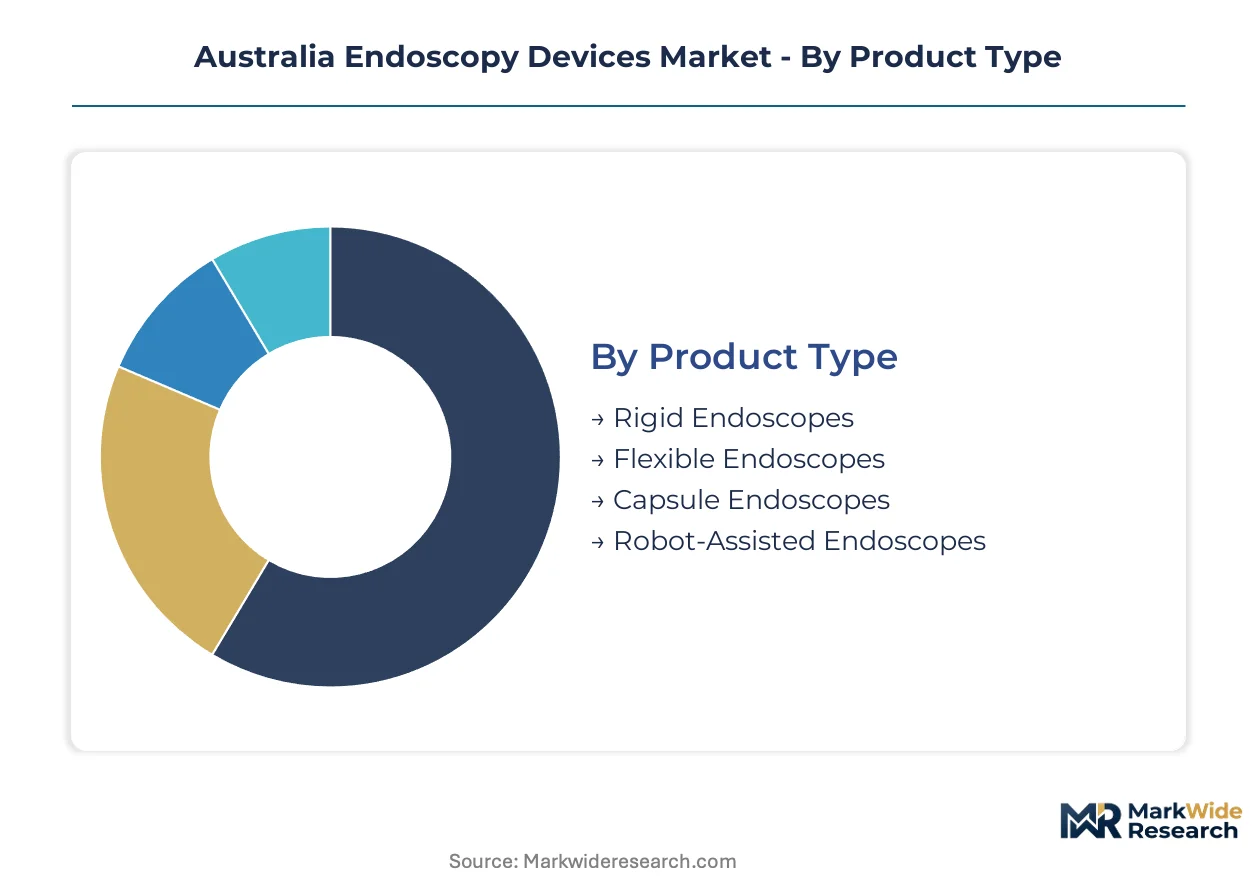
Endoscopy device procurement in Australia stratifies across product lifecycles spanning capital-intensive reusable platforms to single-use disposables, with each segment carrying distinct reprocessing compliance obligations and capital allocation profiles. Understanding these structural divides clarifies how metropolitan hospital networks balance infection control mandates against equipment turnover economics.
Product Type:
Flexible endoscopes turn over every 3-5 years under heavy sterilization cycles, while rigid platforms endure 7-10 year lifespans and disposable lines rotate per-procedure.
- Flexible Endoscopes:These instruments incorporate steerable distal tips with fiber optic or CMOS imaging channels, instrument channels for biopsy forceps, and irrigation ports. Demand concentrates in Sydney and Melbourne gastroenterology suites where high procedural volumes from the National Bowel Cancer Screening Program strain sterilization capacity and accelerate replacement schedules.
- Robot-Assisted Endoscopes:Systems integrate robotic articulation with flexible platforms to enable precision intervention in complex anatomical navigation. Queensland Health networks in Brisbane are piloting these platforms for advanced therapeutic endoscopy where manual dexterity limits constrain conventional scope performance.
- Rigid Endoscopes:Stainless steel laparoscopes and arthroscopes with rod-lens optical systems serve urological and orthopedic applications across Victorian hospital networks.
- Capsule Endoscopes:Ingestible wireless imaging devices with CMOS sensors and LED illumination target small-bowel visualization in Perth diagnostic centers where conventional insertion proves technically prohibitive.
Flexible endoscopes anchor the volume base while robot-assisted platforms gain share at the steepest rate.
Technology:
Cost tiers separate legacy fiber optic systems from premium digital platforms, with hybrid configurations emerging as a mid-market bridge for budget-constrained facilities.
- Video:Digital CMOS sensor technology at the distal tip eliminates fiber degradation from repeated sterilization. New South Wales Health procurement tenders increasingly specify video platforms for high-volume suites in Sydney metropolitan hospitals.
- Wireless:Radio-frequency transmission from capsule devices enables real-time small-bowel imaging without tethered connections. Western Australia regional facilities deploy these for outpatient diagnostics where endoscopy suite infrastructure remains limited.
- Optical:Conventional fiber optic bundles persist in budget-tier rigid platforms across Queensland regional hospitals.
- Hybrid:Combined optical-digital architectures allow staged upgrades without full platform replacement in Victorian consolidated health networks.
Video technology commands the installed base while wireless platforms are climbing the fastest among new procurements.
End User:
Customer type determines procurement authority concentration, with networked hospital systems exercising centralized purchasing power against fragmented clinic decision-making.
- Hospitals:Tertiary facilities in Sydney, Melbourne, and Brisbane maintain dedicated endoscopy suites with dedicated reprocessing departments. These sites drive volume for both capital equipment and high-throughput disposable consumption under centralized procurement frameworks.
- Ambulatory Surgery Centers:Standalone facilities in Victoria and Queensland favor single-use bronchoscope and cystoscope platforms to eliminate on-site sterilization infrastructure and TGA compliance staffing requirements.
- Diagnostic Laboratories:Pathology-integrated endoscopy services in New South Wales concentrate on capsule-based small-bowel diagnostics.
- Specialty Clinics:Gastroenterology and pulmonology practices in Perth and Adelaide operate flexible platforms with outsourced reprocessing contracts.
Hospitals anchor the volume base while ambulatory surgery centers gain share at the steepest rate.
Application:
Procedure volume distribution across medical specialties shapes platform standardization decisions within consolidated health networks.
- Gastroenterology:Colonoscopy and esophagogastroduodenoscopy procedures dominate procedural schedules. The National Bowel Cancer Screening Program drives demand concentration across New South Wales and Victoria hospital networks where screening compliance targets strain existing suite capacity.
- Pulmonology:Bronchoscopy for lung cancer staging and interventional procedures requires sterile access to distal airways. Queensland Health infection control protocols increasingly specify single-use bronchoscopes in outbreak-sensitive respiratory settings.
- Urology:Cystoscopy and ureteroscopy procedures concentrate in metropolitan urology centers across Sydney and Melbourne.
- Gynecology:Hysteroscopy and laparoscopy applications serve fertility and oncology services in specialized women's health facilities.
Gastroenterology anchors the volume base while pulmonology gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan hospital networks in New South Wales and Victoria concentrate procurement authority for endoscopy devices, while regional facilities in Queensland and Western Australia present expansion opportunities for single-use platforms.
New South Wales
Sydney's tertiary hospitals drive demand for flexible gastrointestinal platforms under the National Bowel Cancer Screening Program. TGA registration requirements shape vendor selection for high-volume endoscopy suites. Centralized procurement across NSW Health networks favors standardized video platform deployments with bundled service contracts.
Victoria
Melbourne's consolidated health networks are unbundling after-sales service from capital equipment purchases through competitive tendering. State-level infection control protocols administered by Victorian health authorities accelerate evaluation of disposable bronchoscope alternatives. The city's gastroenterology clusters strain sterilization capacity, compressing replacement cycles for fiber optic systems.
Queensland
Brisbane's metropolitan hospitals pilot robot-assisted platforms for complex therapeutic procedures, while regional facilities remain underpenetrated by single-use cystoscope lines. Queensland Health mandates on outbreak-sensitive respiratory settings specify disposable bronchoscopes. Procurement concentration across the state's networked health system creates volume leverage for standardized deployments.
Western Australia
Perth diagnostic centers specialize in capsule-based small-bowel visualization where conventional scope insertion proves technically prohibitive. The state's geographic isolation elevates logistics costs for reusable device reprocessing infrastructure. Regional facilities favor wireless platforms that eliminate on-site sterilization staffing requirements.
South Australia
Adelaide's specialty clinics operate flexible platforms with outsourced reprocessing contracts to manage compliance burdens. Smaller procedural volumes relative to eastern states limit capital expenditure appetite for premium robotic systems. The state's health procurement framework emphasizes lifecycle cost analysis over upfront equipment pricing.
Australia Endoscopy Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across Australia's endoscopy device market, creating a tiered structure where scale advantages clash with niche differentiation. Multinational manufacturers with broad therapeutic portfolios anchor supply contracts through integrated service networks. Three archetypes dominate: diversified medical technology conglomerates with captive distribution, pure-play endoscopy specialists with deep technical expertise, and disposable-platform innovators attacking reprocessing compliance costs. Competitive moves concentrate on strategic partnerships with hospital procurement consortia and portfolio diversification into single-use alternatives.
Among the diversified technology conglomerates, Medtronic Plc and Stryker Corporation exemplify channel-controlling archetypes that leverage broad product portfolios to secure multi-year supply agreements. Olympus Corporation and FUJIFILM Holdings Corporation occupy positions as imaging-technology anchors with established service infrastructure. Ambu A/S represents the disposable-platform specialist tier that eliminates reprocessing burdens for smaller facilities. Karl Storz GmbH & Co KG anchors the rigid endoscopy segment with German-engineered optical systems.
| Leading Market Players |
|---|
| Medtronic Plc |
| STERIS PLC |
| Olympus Corporation |
| Johnson & Johnson (Ethicon) |
| Ambu A/S |
| Stryker Corporation |
| Hoya Group (PENTAX Medical) |
| Karl Storz GmbH & Co KG |
| FUJIFILM Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Asian medical-grade polymer production is compressing input costs for single-use endoscope manufacturers while simultaneously eroding pricing power for reusable platform vendors locked into fixed depreciation schedules. This utilization asymmetry rewards disposable-platform innovators with margin flexibility while straining capital-equipment incumbents tethered to long-cycle amortization.
Pricing Analysis
Cost-plus contracts with quarterly polymer indexation dominate procurement agreements between Australian hospital networks and disposable endoscope suppliers. Pricing stratifies across premium CMOS-video platforms, standard fiber-optic systems, and economy-tier rigid scopes based on imaging resolution and TGA registration tier. Pricing pressure stems from Medicare Benefits Schedule compression constraining per-procedure hospital revenue. Ambulatory surgery centers exhibit highest price sensitivity due to episodic cash flows, while tertiary hospital networks in Sydney and Melbourne prioritize lifecycle cost certainty over upfront expenditure.
Supply Chain Analysis
Tariff exposure between China and Australia dominates supply chain risk planning for medical-grade polymer feedstocks and CMOS sensor components. Manufacturing concentrates in China, South Korea, and Germany for optical assemblies, distal tip electronics, and stainless steel instrument channels. Raw material dependencies rest on medical-grade polycarbonate housings, platinum-iridium electrode alloys, and LED illumination modules. Single-source vulnerability concentrates in specialty polymer extrusion for flexible scope sheaths. Distribution runs through manufacturer-direct field service organizations and third-party medical device distributors serving regional Queensland and Western Australia facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-use endoscope substitution threatens reusable platform incumbents with accelerated capital obsolescence as TGA reprocessing standards tighten and Queensland Health mandates expand. Incumbents must navigate this displacement by repositioning service infrastructure as a retention anchor.
For Market Incumbents: Pre-empt disposable-platform encroachment by bundling predictive maintenance analytics with reusable system leases, converting capital sales into recurring service revenue. Deepen backward integration into reprocessing consumables to capture margin pools otherwise lost to third-party sterilization vendors. Anchor hospital supply contracts through integrated technician training programs that elevate switching costs for Queensland Health and New South Wales Health networks evaluating platform migration.
For New Entrants and Emerging Players: Build out regional penetration in Western Australia and Queensland rural facilities where reusable infrastructure gaps create immediate single-use addressability. Target ambulatory surgery centers in Victoria with disposable bronchoscope platforms that eliminate on-site sterilization staffing entirely. Pursue GPO contracting through centralized procurement consortia rather than fragmented clinic direct sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among disposable-platform specialists with per-procedure consumption models and hospital system subscription contracts. Long-term viability favors manufacturers with polymer supply agreements decoupled from commodity volatility and TGA equivalence documentation accelerating reusable substitution approvals. Monitor Queensland Health mandate expansion as inflection signal for disposable platform adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Centralized procurement across NSW Health networks standardizes platform deployment and locks multi-year supply commitments. |
| Reimbursement Strategy | Medicare Benefits Schedule alignment determines hospital budget availability for premium disposable technology adoption. |
| CE Marking Pathway | TGA mutual recognition agreements accelerate registration timelines for European-manufactured video platforms. |
| Software Companion Development | AI-assisted polyp detection modules differentiate CMOS-video platforms in high-volume Sydney gastroenterology suites. |
| Backward Integration | In-house polymer compounding insulates disposable manufacturers from Asian specialty chemical supplier concentration. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and sterile processing department heads. Secondary validation drew from TGA device registration databases, Medicare Benefits Schedule procedure volume data, state health department infection control protocols, and hospital capital expenditure disclosures. Bottom-up procedural volume estimates triangulated against top-down manufacturer shipment data across the analysis window.
Calibration against historical replacement cycles and sterilization capacity constraints anchored the analytical framework. Segmentation dimensions modeled include product lifecycle type, imaging technology tier, end-user facility scale, and procedural application specialty. CAGRs were derived from fitted growth curves applied to metropolitan hospital expansion pipelines and regional screening program compliance targets. Forecast inputs incorporated TGA guidance evolution timelines and Queensland Health mandate propagation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian disposable-platform specialists or accelerated TGA equivalence approvals would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
US Colonic Stents Market
Endoscopy
Asia Pacific Endoscopy Devices Market
Endoscopy
Bronchoscopy Market
Endoscopy
Europe Disposable Endoscopes Market
Endoscopy
Gastrointestinal Endoscopy Devices Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Functional Endoscopic Sinus Surgery Systems Market
Endoscopy
Esophageal Stents Market
Endoscopy
Global Mobile Endoscopic Workstations Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Endoscope Tracking Solutions Market
Endoscopy
Dermatology Endoscopy Devices Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Endobronchial Ultrasound Biopsy Market