
 Contouring Implants Market | 2026-2036
Contouring Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Contouring Implants Market Outlook
European polymer suppliers is restructuring their medical-grade silicone output to align with ECHA REACH compliance timelines and shifting volume toward certified biocompatible grades. Stryker leverages its orthopedic manufacturing scale to cross-pollinate precision milling capabilities into facial implant production. Allergan Inc. anchors its contouring portfolio through decades of clinical data accumulation and surgeon training program density. GC Aesthetics competes aggressively on cost structure while sustaining European quality certifications across its Turkish and Irish production nodes.
Contouring implants are patient-matched or off-the-shelf devices manufactured from silicone elastomers, titanium alloys, or polymethyl methacrylate composites, designed to restore or augment craniofacial and body topography through subcutaneous or subperiosteal placement. Manufacturing requires cleanroom molding, surface texturing for tissue integration control, and sterility assurance to ISO 13485 protocols, with dimensional tolerances typically held within fractions of a millimeter to prevent palpability or migration. Facial implants lead current revenue contribution due to shorter procedure times and lower reimbursement friction in private-pay settings, while body implants capture faster growth trajectories driven by gluteal and pectoral augmentation demand in Latin American and Middle Eastern surgical centers. Silicone material formulations dominate unit economics through decades of safety databases and established supplier ecosystems, though polymethyl methacrylate variants occupy premium positioning for permanent structural applications requiring osseointegration resistance.
FDA premarket notification and PMA pathways govern US market access, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements and notified body oversight that elongates certification cycles for new entrants. Brazil's ANVISA maintains parallel but distinct silicone implant registration standards that create separate compliance burdens for multinational manufacturers. Stakeholders must monitor evolving post-market surveillance mandates and reimbursement coding granularity as health technology assessment bodies tighten evidentiary thresholds for cosmetic versus reconstructive indication distinctions.
Market Dynamics
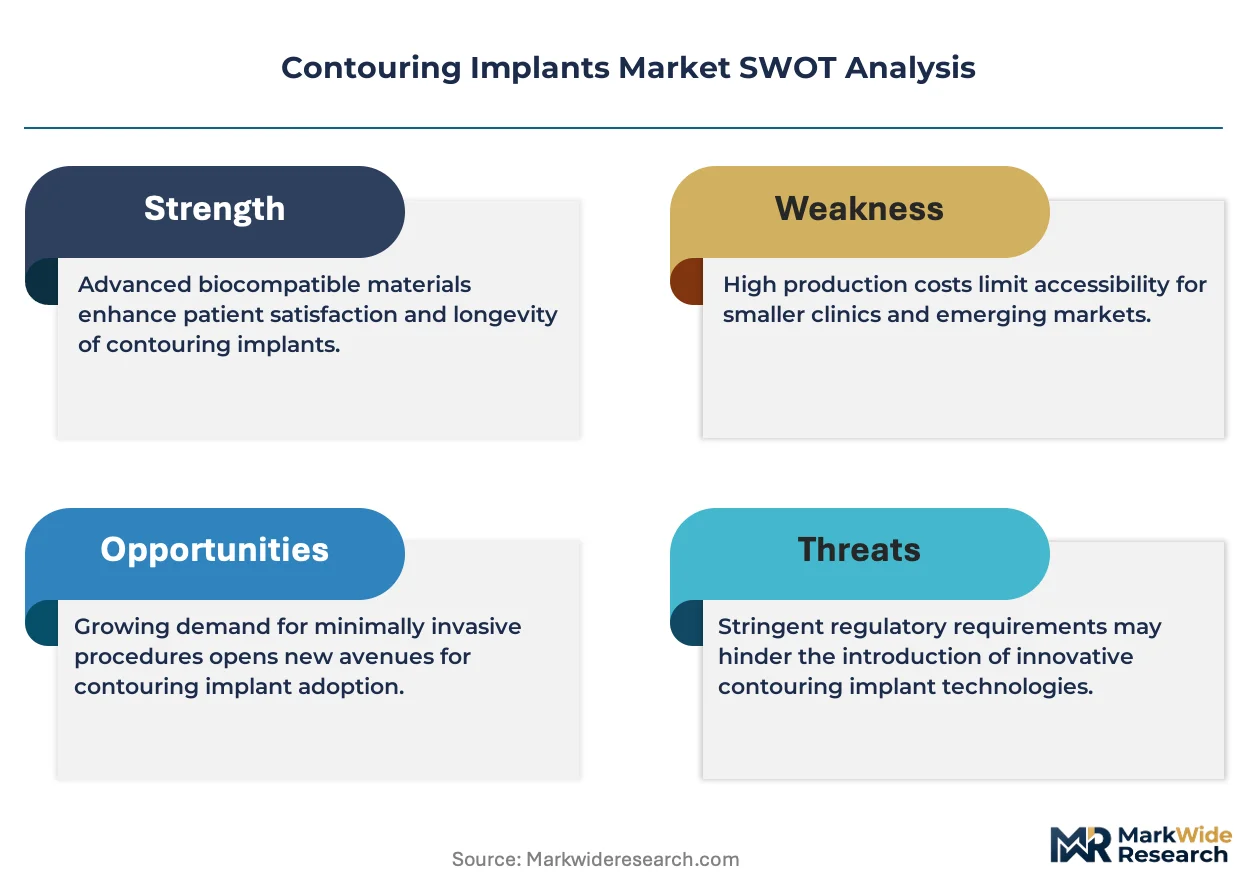
Patient-matched 3D-printed titanium implants are compressing production lead times and eroding the cost advantage of off-the-shelf silicone inventories across high-volume aesthetic centers.
Growth Catalysts
- Minimally invasive placement protocols:Percutaneous insertion techniques reduce operative time and expand procedure accessibility in outpatient settings. Aesthetic clinics in Brazil and Mexico are retrofitting surgical suites to accommodate these workflows.
- EU Medical Device Regulation (MDR) harmonization:Strengthened clinical evidence requirements accelerate consolidation toward manufacturers with established notified body relationships. Mid-sized suppliers face capital barriers that cede share to certified incumbents.
- Gluteal augmentation demand:Body contouring procedures in Latin American surgical centers drive polymethyl methacrylate composite consumption. Patient preference for permanent structural outcomes sustains premium pricing against silicone alternatives.
Market Restraints
- Medical-grade silicone supply concentration:European polymer suppliers control certified biocompatible output, exposing manufacturers to REACH compliance cost pass-throughs and batch allocation constraints.
- FDA premarket approval pathway:Silicone-based facial implants face 18-36 month PMA timelines that freeze product iteration cycles and deter venture-backed entrants.
- Autologous fat grafting substitution:Liposuction-derived adipose transfer offers donor-site morbidity trade-offs that capture revision-seeking patients and compress re-implantation rates.
Strategic Opportunities
- Sub-regional expansion in the Middle East:Dubai and Riyadh surgical centers lack domestic implant manufacturing, creating import substitution openings for Turkish and European producers with MDR certification.
- Digital surgical planning integration:Convergence of cone-beam CT segmentation with CNC milling enables same-week implant delivery. Aesthetic chains are contracting directly with milling service bureaus to bypass distributor markups.
- Brazilian ANVISA mutual recognition pathways:Bilateral agreements with Mercosur neighbors streamline registration portability. Manufacturers with São Paulo-based quality management systems can access Argentine and Colombian markets with reduced documentation burdens.
Industry Challenges
- Cleanroom molding technician scarcity:ISO 13485-certified operators command wage premiums that inflate production costs at contract manufacturers in Eastern Europe and Southeast Asia.
- Surface texturing IP fragmentation:Patent thickets around porous architecture designs force licensing negotiations or design-around expenditures that delay product launches by 8-14 months.
- Sterility assurance validation:Ethylene oxide residual testing protocols require dedicated analytical chemistry capacity that smaller manufacturers outsource at margin-eroding rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contouring Implants Market |
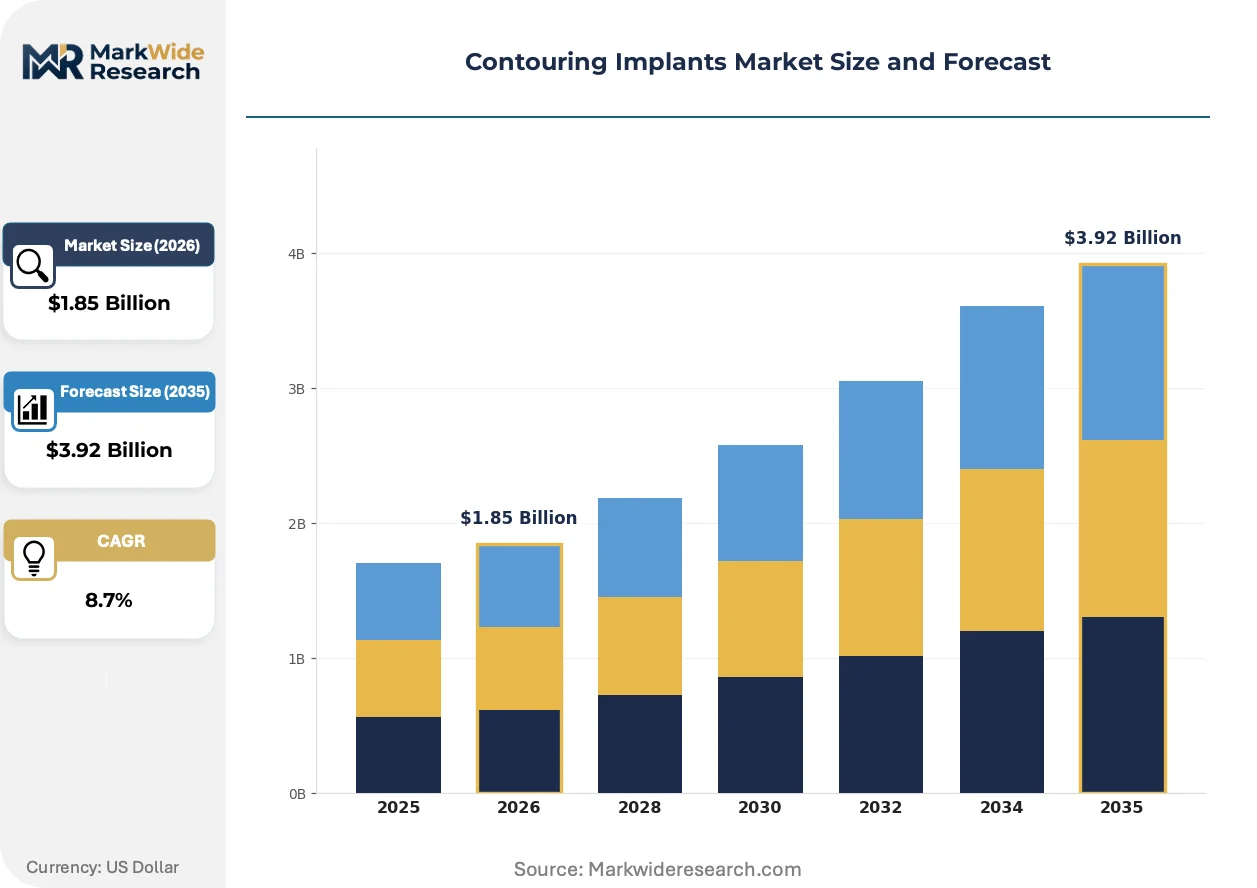
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Implants, Body Implants, Silicone Implants, Titanium Implants End User: Aesthetic Clinics, Hospitals, Surgical Centers, Dermatology Practices Material: Silicone, Polypropylene, Polymethyl Methacrylate, Polyurethane Application: Reconstructive Surgery, Cosmetic Enhancements, Trauma Repair, Oncology Related |
| Companies Covered | Stryker, Allergan Inc., GC Aesthetics, DePuy Synthes, Mentor Worldwide LLC, Sientra Inc., Silimed, ALPHA-HEALTH (ASIA) PTE Ltd., Hansbiomed Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contouring Implants Market Strategic Shifts
Computational design tools and biomaterial science advances are collapsing the traditional separation between reconstructive precision and aesthetic scalability in implant manufacturing.
Patient-specific titanium lattice structures fabricated through electron beam melting are overtaking solid silicone mandibular implants in academic medical center craniomaxillofacial units. Reconstructive surgeons prioritize osseointegration predictability over material cost differentials. The shift compresses average selling prices for premium silicone facial lines while expanding service revenue from surgical planning software subscriptions.
ECHA REACH substance restriction proposals targeting cyclic siloxanes are forcing reformulation of medical-grade elastomers ahead of 2027 sunset dates. German and French notified bodies are rejecting legacy silicone dossiers that lack updated toxicological profiles. Manufacturers with captive polymer development capabilities are securing preferred supplier status with implant OEMs scrambling to qualify alternative grades.
Direct-to-surgeon digital platforms are disintermediating traditional aesthetic device distributors in Brazil and South Korea. Specialist surgeons purchase off-the-shelf implants through proprietary mobile applications that bundle training credits and revision insurance. The channel shift concentrates procurement influence among high-volume individual practitioners and erodes regional distributor margin pools that historically captured 35-50 percent of landed cost.
Contouring Implants Market Segmentation
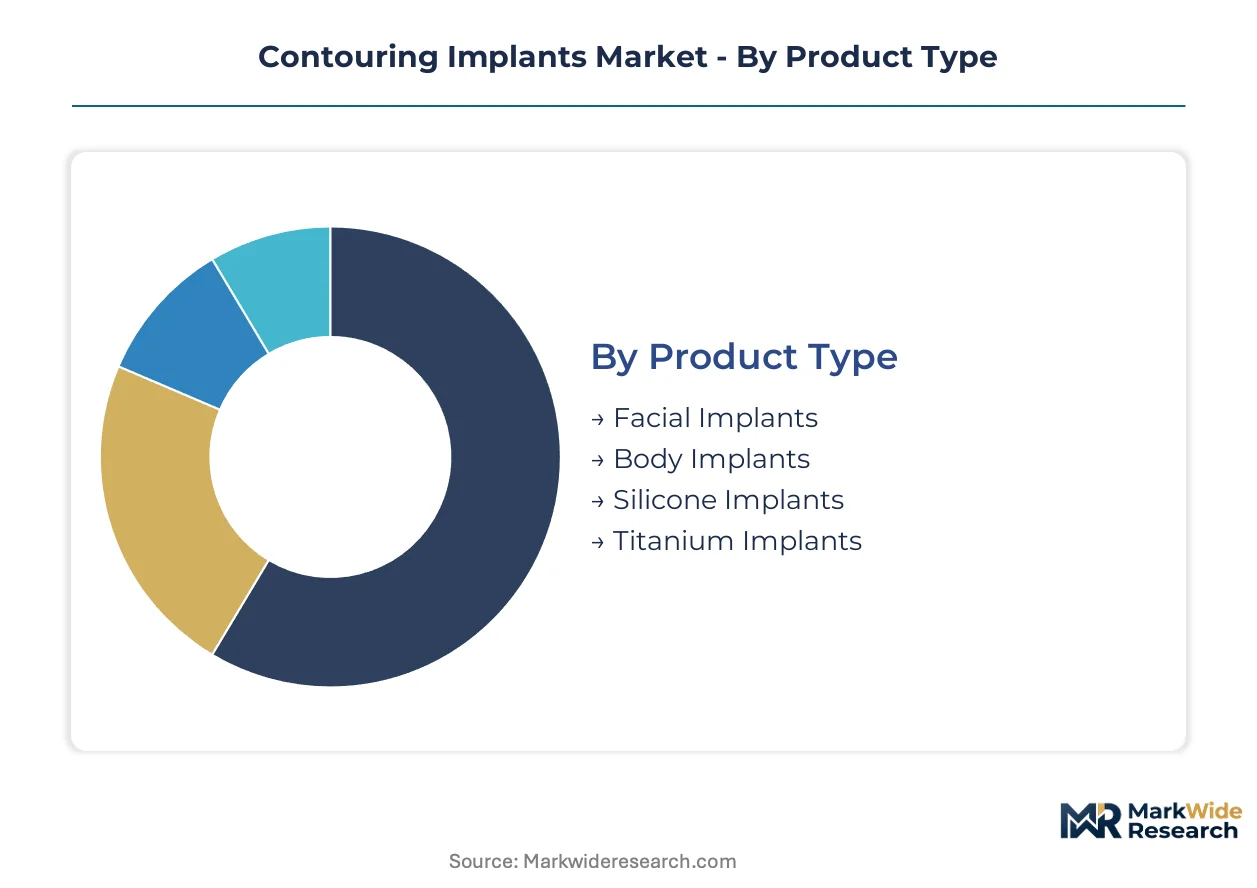
Implant selection cascades through material compatibility, anatomical target, and procedural setting, with each dimension carrying distinct regulatory and reimbursement implications. Manufacturers configure product portfolios across these axes to capture volume in high-throughput aesthetic chains while defending margin in complex reconstructive workflows.
Product Type:
Replacement cycles diverge sharply between facial and body applications, with revision rates and material fatigue driving upgrade timing rather than device obsolescence.
- Facial Implants:Silicone elastomer and porous polyethylene constructs address malar, chin, and mandibular augmentation. Aesthetic clinics in São Paulo and Seoul concentrate demand for off-the-shelf anatomical shapes with textured surfaces that reduce capsular contracture incidence.
- Body Implants:Pectoral, gluteal, and calf applications require larger-volume devices with reinforced shell architecture. Latin American surgical centers drive consumption of cohesive gel and solid silicone variants as permanent structural alternatives to autologous grafting.
- Silicone Implants:Medical-grade elastomer formulations with platinum-cured crosslinking dominate unit economics through established supplier ecosystems and decades of safety databases.
- Titanium Implants:Electron-beam-melted lattice structures fabricated from Ti-6Al-4V ELI enable patient-matched craniomaxillofacial reconstruction with osseointegration timelines measured in weeks rather than months.
Facial implants sit at the top of the volume ranking, with titanium lattice variants climbing the fastest as academic medical centers prioritize integration predictability over material cost.
End User:
Procurement authority concentrates differently across settings, with individual surgeon influence highest in specialized aesthetic chains and institutional committees governing hospital purchasing.
- Aesthetic Clinics:Outpatient facilities in Brazil and Mexico retrofit surgical suites for percutaneous insertion protocols. Direct-to-surgeon digital platforms are disintermediating traditional distributors, concentrating procurement influence among high-volume individual practitioners.
- Hospitals:Academic medical centers prioritize titanium lattice implants for craniomaxillofacial reconstruction, with purchasing committees requiring extensive clinical evidence packages and long-term follow-up data.
- Surgical Centers:Ambulatory facilities balance procedure throughput against infection control protocols, favoring pre-sterilized single-use implants with streamlined inventory management.
- Dermatology Practices:Non-surgical aesthetic providers expand into minimally invasive implant placement, creating demand for smaller-diameter devices with simplified insertion instrumentation.
Aesthetic clinics command the highest procedure volume, though hospital purchasing value is expanding most quickly as reconstructive titanium applications penetrate academic networks.
Material:
Cost tiers stratify around biocompatibility certification depth, with ECHA REACH compliance timelines forcing qualification of alternative grades ahead of sunset dates.
- Silicone:Platinum-cured elastomers with established ISO 10993 biocompatibility profiles anchor mid-market pricing. German and French notified bodies are rejecting legacy dossiers lacking updated toxicological profiles.
- Polypropylene:Mesh-reinforced constructs provide permanent structural support in body wall and facial applications where tissue ingrowth stability outweighs explantation flexibility.
- Polymethyl Methacrylate:PMMA composites occupy premium positioning for permanent structural applications requiring osseointegration resistance, with Latin American surgical centers driving consumption for gluteal augmentation.
- Polyurethane:Foam-coated implants offer enhanced tissue integration with reduced capsular contracture rates, though manufacturing complexity limits supplier diversity.
Silicone leads absolute volume, with polymethyl methacrylate gaining share fastest among patients prioritizing permanent outcomes over revision flexibility.
Application:
Reimbursement coding granularity separates cosmetic from reconstructive indications, with health technology assessment bodies tightening evidentiary thresholds for each category.
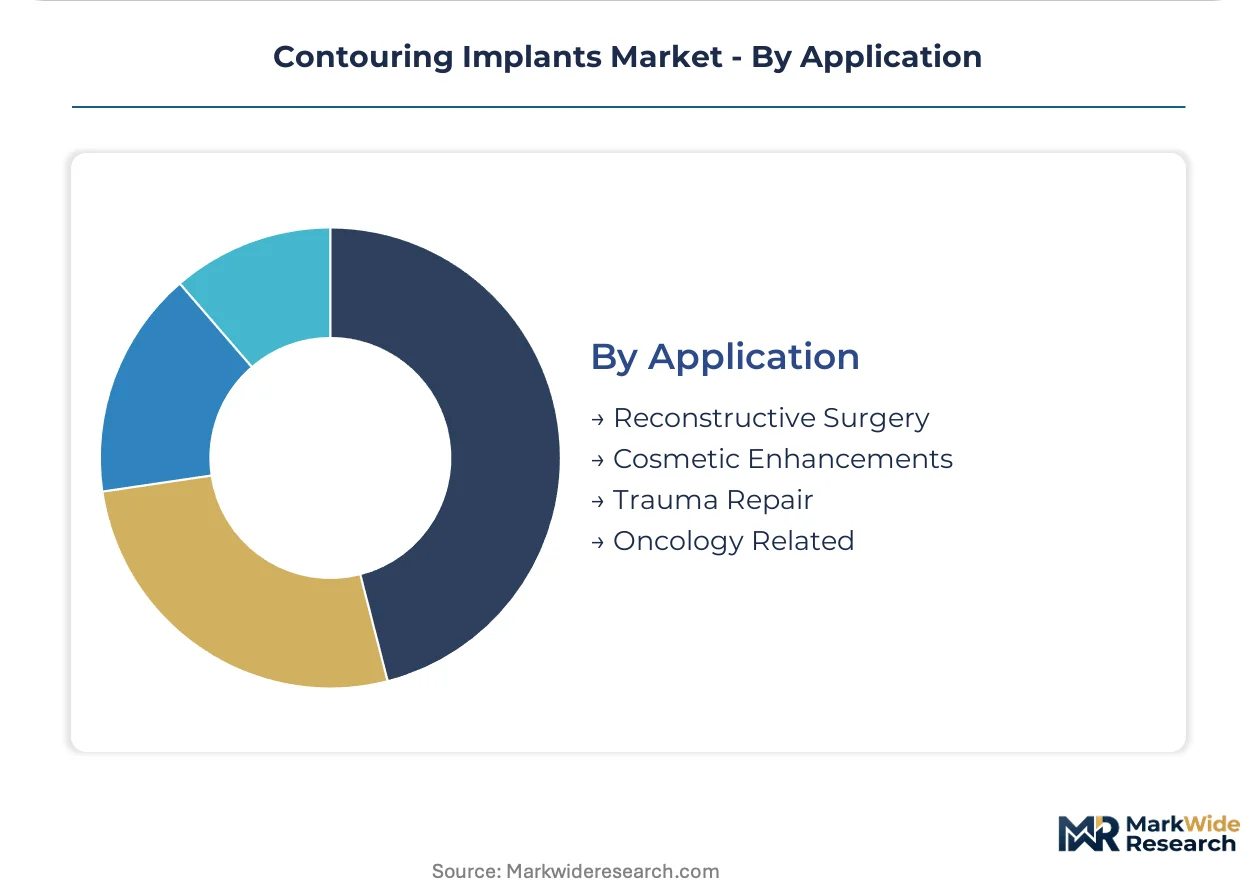
- Reconstructive Surgery:Congenital deformity and post-traumatic correction drive demand for patient-matched titanium implants with dimensional tolerances held within fractions of a millimeter.
- Cosmetic Enhancements:Elective augmentation procedures in private-pay settings favor off-the-shelf silicone devices with shorter procedure times and lower capital equipment requirements.
- Trauma Repair:Acute craniomaxillofacial injury management requires rapid-turnaround custom implants, with cone-beam CT segmentation enabling same-week delivery from milling service bureaus.
- Oncology Related:Post-resection reconstruction combines aesthetic outcome requirements with radiation therapy compatibility, favoring materials with minimal artifact generation in follow-up imaging.
Cosmetic enhancements generate the highest procedure count, with trauma repair applications expanding most steeply as digital surgical planning compresses production lead times.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting production investment toward jurisdictions where REACH compliance costs and FDA premarket timelines create divergent cost-of-market-access structures. Manufacturers with dual-certification capabilities capture margin advantages across both pathways.
United States
FDA premarket approval pathways for silicone-based facial implants impose 18-36 month timelines that freeze product iteration cycles. Venture-backed entrants face capital barriers that cede share to established incumbents with accumulated clinical data packages. Academic medical centers in Boston and Los Angeles prioritize titanium lattice implants for craniomaxillofacial reconstruction.
Brazil
ANVISA maintains parallel but distinct silicone implant registration standards that create separate compliance burdens for multinational manufacturers. São Paulo-based quality management systems enable Mercosur registration portability into Argentine and Colombian markets. Aesthetic procedure density and surgeon training infrastructure in Rio de Janeiro and São Paulo outpace most other national markets.
Germany
ECHA REACH substance restriction proposals targeting cyclic siloxanes are forcing reformulation of medical-grade elastomers ahead of 2027 sunset dates. German notified bodies are rejecting legacy silicone dossiers that lack updated toxicological profiles. Polymer development capabilities in the Ruhr industrial cluster secure preferred supplier status with implant OEMs scrambling to qualify alternative grades.
South Korea
MFDS oversees medical device registration with strengthened clinical evidence requirements that elongate certification cycles for new entrants. Direct-to-surgeon digital platforms are disintermediating traditional aesthetic device distributors in Seoul. High-volume individual practitioners concentrate procurement influence through proprietary mobile applications bundling training credits.
Turkey
Domestic implant manufacturing creates import substitution openings for MDR-certified producers targeting Dubai and Riyadh surgical centers. Turkish production nodes sustain European quality certifications while competing aggressively on cost structure. Istanbul-based contract manufacturers serve Middle Eastern markets lacking domestic manufacturing infrastructure.
Contouring Implants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue patient-matched titanium fabrication and digital surgical planning integration. The vendor base stratifies across three maturity tiers: multinational orthopedic conglomerates with cross-pollinated precision milling capabilities; mid-sized aesthetic specialists with decades of clinical data accumulation; and regional cost competitors with certified biocompatible production nodes. Consolidation pressures favor manufacturers with established notified body relationships and captive polymer development capabilities. Dominant competitive moves include strategic partnerships with cone-beam CT segmentation platforms and geographic expansion through bilateral mutual recognition agreements.
Among orthopedic-derived fabricators, Stryker leverages manufacturing scale to cross-pollinate precision milling capabilities into facial implant production. Allergan Inc. anchors the data-rich tier through accumulated clinical evidence and surgeon training program density. GC Aesthetics exemplifies the cost-competitive archetype, sustaining European quality certifications across Turkish and Irish production nodes while competing on structural efficiency.
| Leading Market Players |
|---|
| Stryker |
| Allergan Inc. |
| GC Aesthetics |
| DePuy Synthes |
| Mentor Worldwide LLC |
| Sientra Inc. |
| Silimed |
| ALPHA-HEALTH (ASIA) PTE Ltd. |
| Hansbiomed Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Patient-matched 3D-printed titanium procurement preferences in São Paulo and Seoul surgical centers are forcing contract manufacturers to reconfigure cleanroom capacity toward low-volume, high-mix production, compressing margins on standardized silicone inventories while elevating pricing power for certified biocompatible polymer suppliers.
Pricing Analysis
Distributor margin layers in Brazil and Mexico historically captured 35-50 percent of landed cost, though direct-to-surgeon digital platforms are disintermediating this tier and concentrating procurement influence among high-volume individual practitioners. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and customization level, with FDA PMA-certified silicone facial implants commanding substantial premiums over ANVISA-registered alternatives. Pricing pressure stems from autologous fat grafting substitution and patient-matched titanium fabrication, which erodes re-implantation rates and off-the-shelf silicone volumes. Aesthetic clinic chains exhibit highest price sensitivity due to percutaneous insertion protocol investments, while academic medical centers prioritize osseointegration predictability over material cost differentials.
Supply Chain Analysis
Regional distribution centers in Germany, Turkey, and Brazil anchor hub-and-spoke patterns serving aesthetic chains and hospital purchasing committees across Latin America, the Middle East, and Western Europe. Medical-grade silicone elastomer production concentrates in German and French polymer facilities, with titanium powder feedstocks drawing from aerospace-qualified suppliers in the United States and United Kingdom. Supply chain risk centers on ECHA REACH substance restriction timelines targeting cyclic siloxanes, which threatens batch allocation constraints and reformulation costs ahead of sunset dates. Distribution runs through notified body-certified contract manufacturers with ISO 13485 quality management systems, with Istanbul and São Paulo nodes gaining share for Mercosur and Middle Eastern market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market rest on captive polymer development capabilities and patient-matched fabrication service revenue, as digital surgical planning subscriptions offset compression in premium silicone average selling prices.
For Market Incumbents: Deploy cone-beam CT segmentation partnerships to capture surgical planning software recurring revenue and defend against milling service bureau disintermediation. Consolidate notified body relationships ahead of EU MDR harmonization, which will cede share from mid-sized suppliers facing capital barriers. Capacity addition in Turkish production nodes secures cost-competitive positioning for Middle Eastern import substitution while sustaining MDR certification portability. For New Entrants and Emerging Players: High-volume aesthetic practitioners in Dubai and Riyadh surgical centers represent an underserved buyer archetype lacking domestic implant manufacturing and receptive to direct procurement platforms. Same-week titanium implant delivery from CNC milling service bureaus offers the most penetrable application segment, with trauma repair workflows compressing traditional production lead times. Go-to-market execution should bundle revision insurance and training credits through proprietary mobile applications, mirroring successful channel shifts in Brazil and South Korea. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized aesthetic specialists possessing decades of clinical data accumulation and established surgeon training program density, as FDA PMA pathway timelines deter venture-backed entrants and accelerate consolidation toward certified incumbents. Long-term viability over the projection horizon favors manufacturers with backward integration into polymer development and dual-certification capabilities across FDA and EU MDR pathways. The signal to watch is bilateral mutual recognition agreement momentum between ANVISA and Mercosur neighbors, which would streamline registration portability and reward São Paulo-based quality management systems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR harmonization elongates certification cycles and accelerates consolidation toward established notified body relationships. |
| Hospital System Partnership | Academic medical center purchasing committees require extensive clinical evidence packages for titanium lattice adoption. |
| Software Companion Development | Cone-beam CT segmentation integration enables same-week implant delivery and recurring subscription revenue capture. |
| Backward Integration | Captive polymer development capabilities secure preferred supplier status amid ECHA REACH reformulation mandates. |
| Reimbursement Strategy | Health technology assessment body evidentiary thresholds tighten distinctions between cosmetic and reconstructive indication coding. |
Study Parameters
Bottom-up aesthetic clinic and hospital purchasing modeling reconciled against top-down medical-grade silicone and titanium powder supply tracking forms the analytical core of this study. Primary interviews with craniofacial surgeons, biomedical engineers, GPO contracts managers, and implant OEM procurement leads combined with secondary validation from FDA PMA filings, ANVISA registration databases, ECHA REACH substance restriction proposals, and EU MDR notified body guidance documents. Triangulation across stakeholder inputs and regulatory dossiers ensures segmentation integrity across material, application, and end-user dimensions.
Input-output matrix framing connects procedure volume assumptions to implant unit economics, with value outputs derived from pricing stratification across premium, standard, and economy certification tiers. Segmentation dimensions modeled include material formulation, anatomical target, procedural setting, and regional regulatory cluster, with CAGRs calibrated against historical procedural growth trajectories and surgeon training program expansion rates. Forecast inputs incorporate ECHA REACH compliance timelines, FDA premarket approval pathway duration estimates, and digital surgical planning adoption curves across academic and aesthetic settings.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in private-pay aesthetic clinic transaction data introduce uncertainty bands around cosmetic procedure volume assumptions. Forecasts reflect documented assumptions regarding regulatory pathway durations, polymer reformulation timelines, and bilateral mutual recognition agreement momentum. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Aesthetics
Europe Non-Surgical Procedures Market
Medical Aesthetics
Oculoplastic Surgery Market
Medical Aesthetics
Scar Revision Market
Medical Aesthetics
Collagen Fillers Market
Medical Aesthetics
Global Medical Aesthetic Devices Market
Medical Aesthetics
Facial Aesthetics Market
Medical Aesthetics
Tattoo Removal Patch Market
Medical Aesthetics
China Laser Hair Removal Market
Medical Aesthetics
Europe Medical Aesthetic Devices Market
Medical Aesthetics
Facial Bone Contouring Market
Medical Aesthetics
Italy Hair Transplant Market
Medical Aesthetics
Europe Facial Injectable Market
Medical Aesthetics
Facial Injector Market
Medical Aesthetics
Photoelectric Medical Beauty Equipment Market
Medical Aesthetics
Laser Hair Removal Market
Medical Aesthetics
Non-Hyaluronic Acid Dermal Filler Market