
 Italy Hand Sanitizer Market | 2026-2036
Italy Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Hand Sanitizer Market Intelligence
Ethanol-to-isopropanol substitution in active ingredient blends is narrowing formulation flexibility for Italian manufacturers. Henkel AG & Co. KGaA leverages its Düsseldorf-based R&D pipeline to sustain premium positioning in gel formats across Italian retail channels. Reckitt Benckiser Group PLC anchors hospital procurement contracts through Ecolab Inc.'s infection control distribution network, while GOJO Industries Inc. competes on touch-free dispenser technology in Lombardy healthcare clusters.
Hand sanitizer comprises alcohol-based antiseptic solutions, typically formulated with 60-95% ethanol or isopropanol combined with emollients and thickeners, manufactured through compounding and sterile filling processes designed to reduce transient microbial flora on intact skin. Gel formulations dominate Italian pharmacy shelves due to consumer familiarity and spill control, while foam formats are gaining traction in hospital settings where rapid coverage and reduced residue support clinical workflow efficiency. Dispensers as a packaging category command higher margin pools through recurring cartridge sales, whereas sachet demand concentrates in travel and foodservice segments.
Italy's Ministry of Health enforces biocidal product registration under EU BPR transposition, while ECHA manages REACH substance evaluation for ethanol impurities and residual acetaldehyde limits. These frameworks shape demand by mandating clinical efficacy documentation and environmental risk assessments that elevate compliance costs for smaller domestic blenders. Stakeholders must monitor pending EU Green Deal amendments to biocidal carbon intensity thresholds, as these will determine whether Italian producers source fermentation ethanol domestically or import lower-carbon Brazilian supply.
Market Dynamics
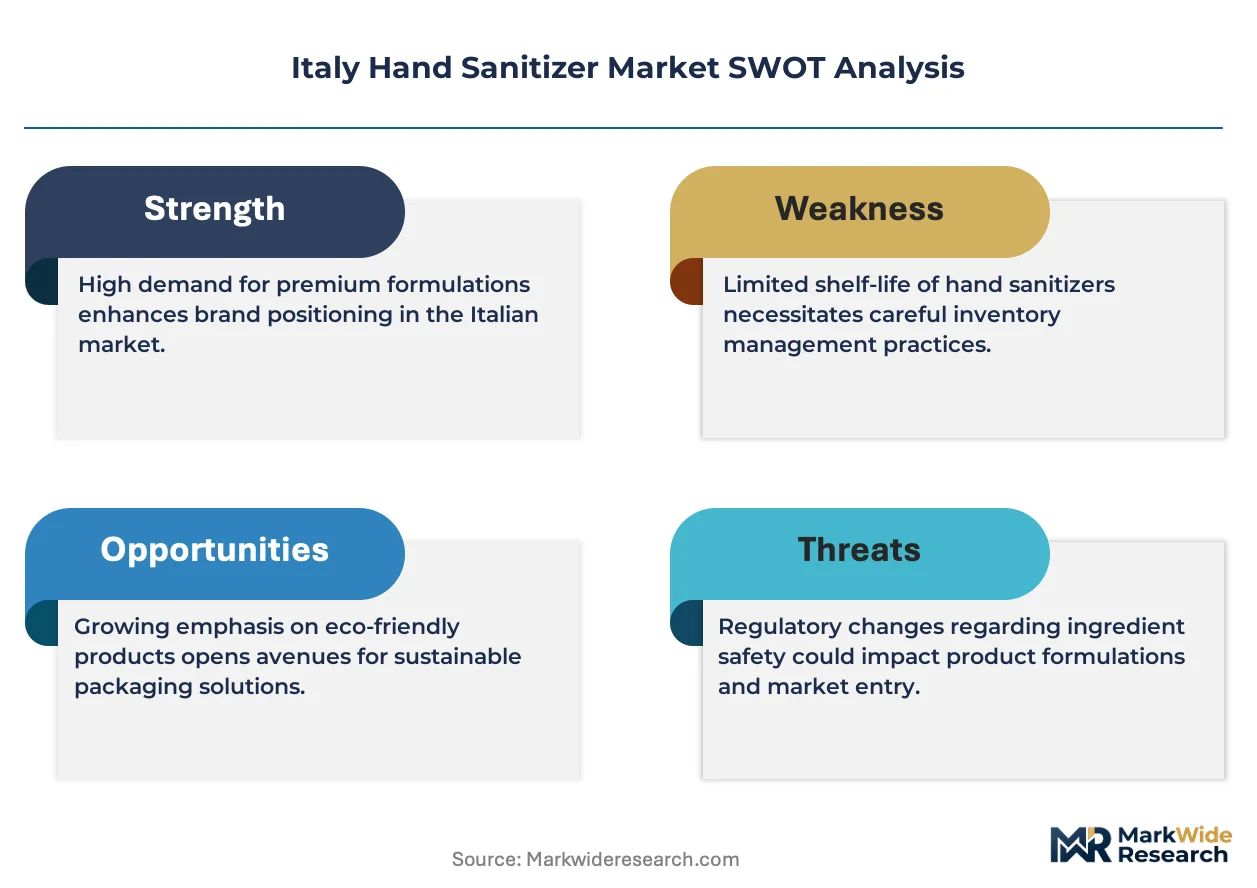
Italian hand sanitizer procurement is consolidating around hospital system central purchasing, compressing margins for regional blenders while favoring scaled suppliers with dedicated ECHA compliance teams and REACH dossier completion.
Growth Catalysts
- EU Biocidal Products Regulation institutionalization:Post-pandemic healthcare networks now mandate alcohol-based antiseptic protocols as permanent infrastructure, locking in recurring hospital demand across Lombardy and Veneto clinical clusters.
- Milan-Turin pharmaceutical corridor density:Northern Italy's overlapping manufacturing and hospital infrastructure creates localized supply-demand matching that reduces logistics costs for gel and foam format distribution.
- Fermentation ethanol technology maturation:Domestic biorefinery capacity expansion is enabling shorter supply chains for active ingredient sourcing, reducing import dependency for REACH-compliant formulations.
Market Restraints
- Ethanol-isopropanol substitution rigidity:REACH substance evaluation for residual acetaldehyde limits is narrowing approved active ingredient blends, forcing expensive reformulation cycles for mid-sized domestic manufacturers.
- Raw material supply concentration:Pharmaceutical-grade ethanol sourcing clusters in Po Valley agricultural processing zones, creating geographic single-point vulnerability for northern Italian production facilities.
- Carbon intensity disclosure mandates:Pending EU Green Deal amendments to biocidal product carbon thresholds threaten to disqualify conventional fermentation routes without verified low-carbon certification.
Strategic Opportunities
- Central and southern Italy hospital network penetration:Lazio and Campania healthcare procurement remains fragmented, offering white space for suppliers with ECHA-registered formulations and regional logistics partnerships.
- Touch-free dispenser cartridge ecosystems:Lombardy healthcare clusters are standardizing on automated dispensing infrastructure, creating recurring revenue streams through proprietary cartridge compatibility requirements.
- Sustainable ethanol sourcing arbitrage:Brazilian sugarcane ethanol's lower carbon intensity profile positions importers to capture advantage if EU Green Deal biocidal thresholds tighten as anticipated.
Industry Challenges
- ECHA dossier preparation expertise scarcity:Smaller domestic blenders face 12-18 month registration timelines for new formulations, delaying product launches against larger competitors with dedicated regulatory affairs functions.
- Sterile filling capacity capex requirements:Hospital-grade gel and foam production demands ISO 14644 cleanroom investment that strains mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Hand Sanitizer Market |
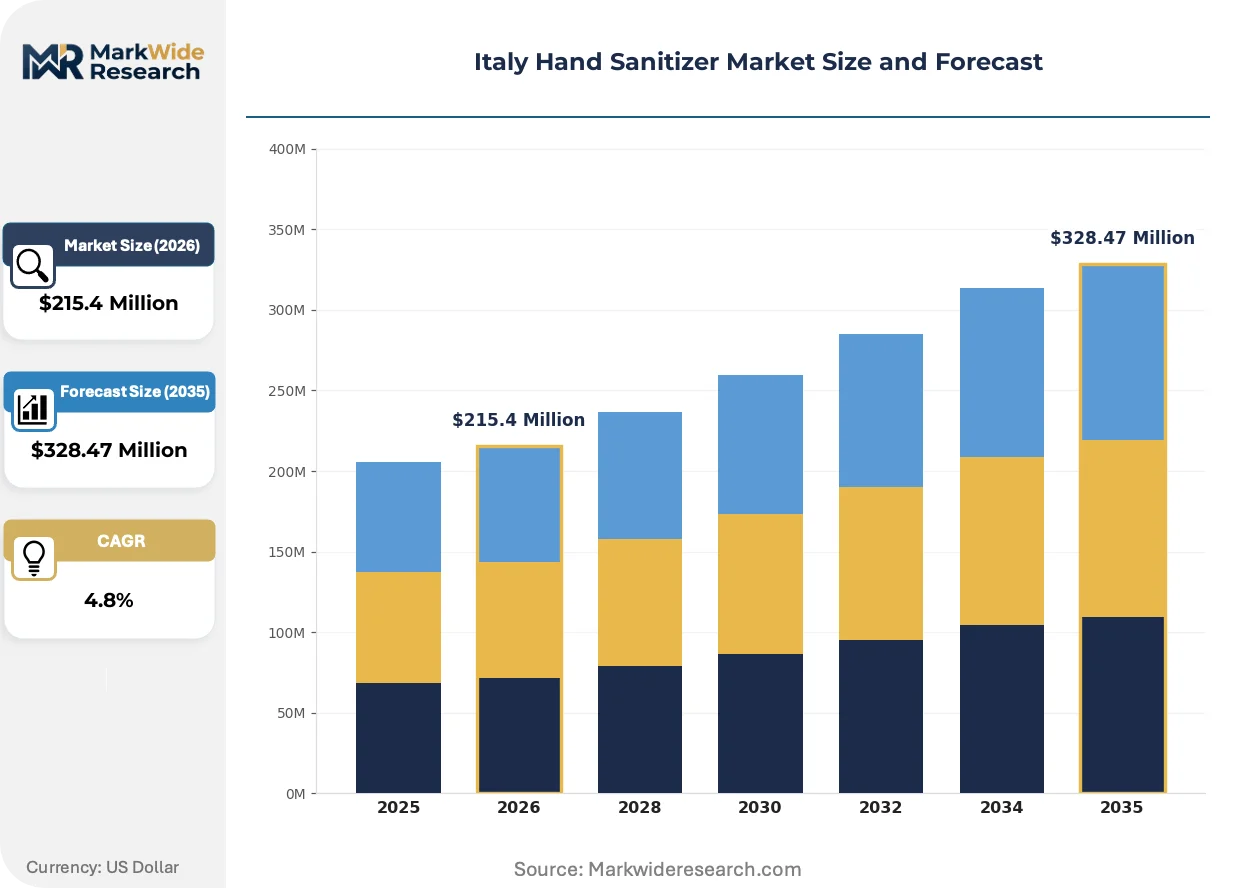
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $328.47 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Liquid, Spray End User: Hospitals, Schools, Restaurants, Individuals Packaging Type: Bottles, Sachets, Dispensers, Tubs Distribution Channel: Pharmacies, Online Retail, Supermarkets, Convenience Stores |
| Companies Covered | Reckitt Benckiser Group PLC, Unilever PLC, Procter & Gamble Company, 3M Company, GOJO Industries Inc., Henkel AG & Co. KGaA, Ecolab Inc., Himalaya Global Holdings Ltd., Colgate-Palmolive Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Hand Sanitizer Market Strategic Shifts & Innovations
Digital compliance infrastructure is virtualizing how Italian manufacturers manage biocidal product registration, with cloud-based REACH dossier platforms compressing regulatory timelines and reducing ECHA submission error rates.
Touch-free dispensing hardware is virtualizing infection control workflows in Lombardy hospital clusters, with sensor-activated systems replacing manual pump bottles in surgical wards and intensive care units. Procurement managers at ASST and IRCCS networks are specifying cartridge-compatible infrastructure to lock in supply relationships. This virtualization of dispensing interaction is compressing the addressable market for conventional bottle formats in clinical settings.
ECHA's evolving REACH substance evaluation protocols for ethanol impurities are forcing active ingredient disclosure granularity that exceeds current testing infrastructure at smaller Italian blenders. The industrial consequence is accelerated consolidation, with mid-sized manufacturers outsourcing dossier preparation to specialized regulatory consultancies. Gel format producers serving pharmacy retail channels face the steepest compliance cost escalation, as their product portfolios require the most extensive reformulation documentation.
Hospital procurement centralization is consolidating purchasing authority from individual clinical units to regional health authority supply chains across Italy's 20 regions. This concentration is displacing fragmented distributor networks with direct manufacturer contracts and tender-based volume commitments. The shift is most visible in Emilia-Romagna and Tuscany, where Azienda Sanitaria Locale structures are standardizing on multi-year supply agreements with ECHA-registered suppliers offering transparent carbon footprint documentation.
Italy Hand Sanitizer Market Segmentation
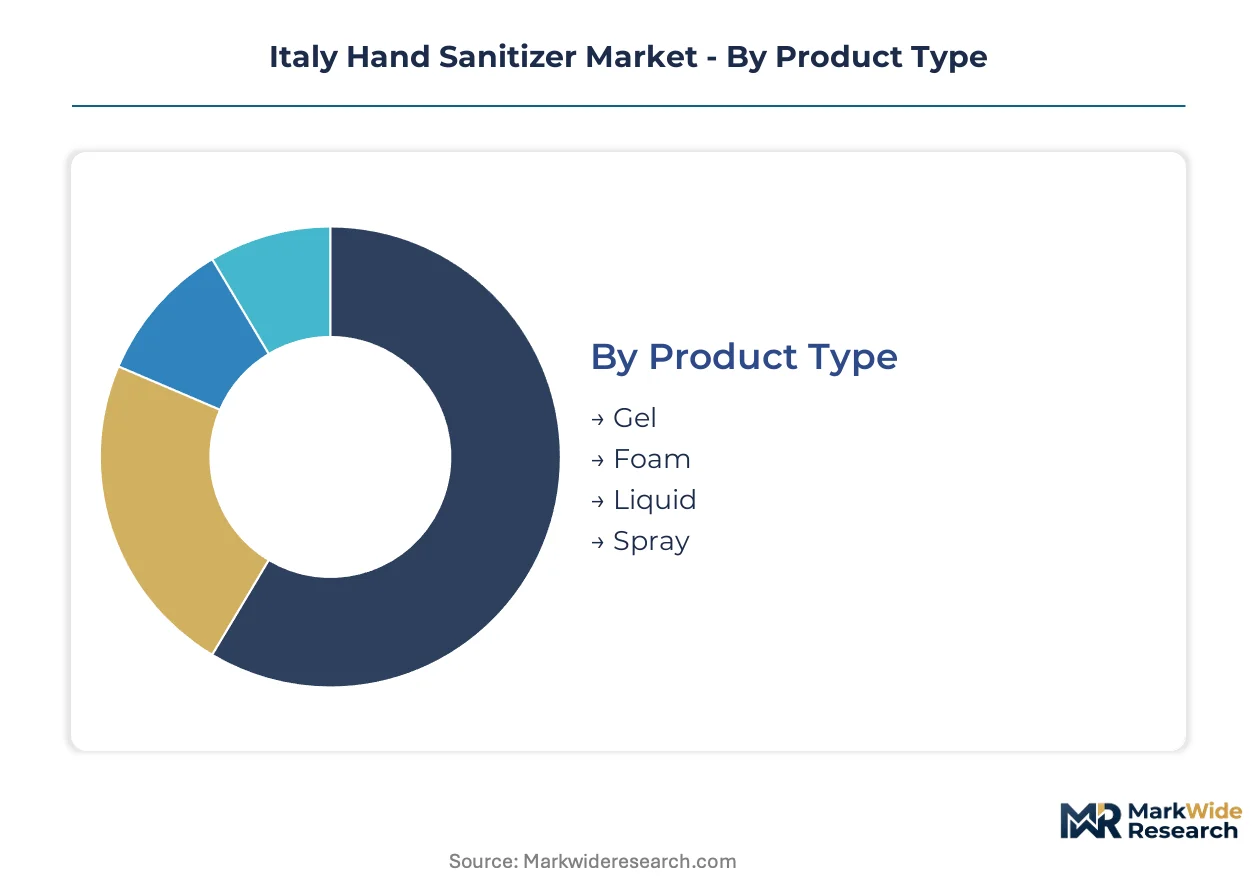
Segmentation in the Italian hand sanitizer market reveals how procurement patterns diverge across clinical, institutional, and consumer channels. Each dimension carries distinct margin profiles and regulatory burdens that shape supplier strategy.
Product Type:
After-sales service intensity varies sharply across formats, with dispenser-linked systems demanding technical support contracts while portable formats require minimal ongoing engagement.
- Gel:Viscous formulations incorporating 60-95% ethanol with carbomer or cellulose thickeners provide controlled dosing and minimal drip. Pharmacy retail across Lombardy and Veneto concentrates demand here, driven by consumer familiarity and spill containment preferences in home and office settings.
- Foam:Air-entrained formulations expand on dispensing to cover larger skin surface area with less product volume. Hospital procurement in Milan-Turin clinical clusters favors this format for rapid surgical hand preparation and reduced residue that supports glove donning workflows.
- Liquid:Low-viscosity solutions offer rapid evaporation and compatibility with spray pump mechanisms. Demand concentrates in foodservice and industrial hygiene applications across Emilia-Romagna manufacturing zones.
- Spray:Atomized delivery systems enable coverage of both hands and environmental surfaces. Institutional purchasers in school and transit settings specify spray formats for shared space disinfection protocols.
Gel holds the largest share; momentum sits with foam as hospital procurement standardizes on clinical workflow efficiency.
End User:
Volume concentration and margin structure diverge substantially across customer types, with institutional buyers leveraging tender processes while individual consumers pay shelf-price premiums.
- Hospitals:ASST and IRCCS networks across Italy's 20 regions drive the highest volume procurement through centralized purchasing authorities. ECHA-registered formulations with documented clinical efficacy against EN 1500 standards are mandatory for surgical ward supply contracts.
- Schools:Regional education ministries specify alcohol-based protocols for classroom and cafeteria deployment. Procurement fragments across municipal purchasing cooperatives with varying technical specifications.
- Restaurants:HACCP compliance mandates hand hygiene infrastructure for food handling zones. Demand concentrates in sachet and small-format bottle purchases through foodservice distributors.
- Individuals:Pharmacy and supermarket channels serve household stockpiling and personal carry needs. Brand loyalty remains low, with purchasing decisions driven by price visibility and packaging convenience.
Hospitals command the volume concentration; schools represent the steepest expansion trajectory as post-pandemic hygiene protocols institutionalize across education infrastructure.
Packaging Type:
Supply chain configuration and margin capture potential vary with packaging investment, from disposable sachets to capital-intensive dispenser hardware ecosystems.
- Bottles:Polyethylene or polyethylene terephthalate containers ranging from 50ml pocket formats to 5 liter institutional sizes dominate pharmacy and retail distribution. Northern Italian blow-molding capacity supports domestic sourcing for standard formats.
- Sachets:Single-use laminated film pouches concentrate demand in travel, hospitality, and foodservice segments where portion control and waste minimization are prioritized.
- Dispensers:Wall-mounted or free-standing units with proprietary cartridge interfaces generate recurring revenue through locked supply relationships. Lombardy hospital clusters are standardizing on touch-free sensor-activated systems from specified manufacturers.
- Tubs:Wide-mouth containers for high-frequency access points in industrial and institutional settings. Refill economics favor bulk purchasing by facility management contractors.
Bottles retain the broadest penetration; dispensers are climbing the fastest as healthcare procurement shifts toward automated infrastructure with cartridge compatibility requirements.
Distribution Channel:
Channel selection determines regulatory exposure and customer access costs, with pharmacy networks enforcing strict biocidal registration verification.
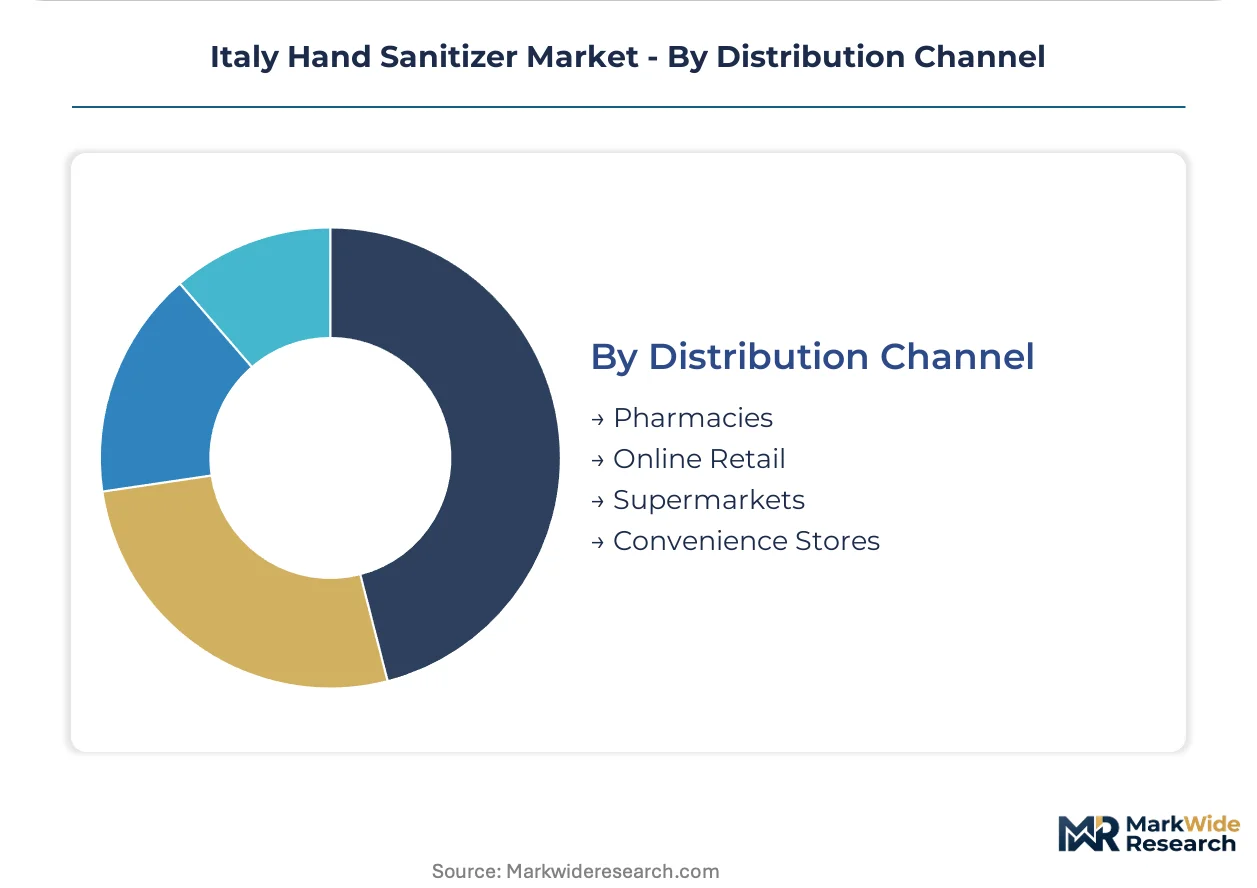
- Pharmacies:Federfarma and Assofarm member networks require EU BPR-compliant product registration and Italian Ministry of Health authorization for shelf placement. This channel captures premium pricing for clinically positioned formulations.
- Online Retail:Amazon.it and specialized medical supply platforms enable direct-to-consumer and institutional purchasing with reduced geographic constraint. ECHA dossier transparency becomes a competitive differentiator in digital search environments.
- Supermarkets:Coop, Conad, and Esselunga chains drive volume through promotional pricing and private label programs. Shelf space allocation favors suppliers with national logistics coverage.
- Convenience Stores:Small-format urban retail captures impulse and emergency replenishment demand. Product turnover favors compact, high-margin SKUs with extended shelf stability.
Pharmacies anchor the premium tier; online retail is gaining share fastest as procurement digitization accelerates across institutional buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ethanol exports flow into northern Italian pharmaceutical corridors, supplying active ingredient feedstock for REACH-compliant formulation plants clustered around Milan and Turin.
Lombardy
ASST hospital networks and IRCCS research hospitals drive concentrated procurement demand across Milan, Bergamo, and Brescia. Regional health authority tender processes now mandate ECHA-registered biocidal formulations with documented EN 1500 efficacy. The Milan metropolitan corridor anchors Italy's densest dispenser infrastructure deployment, with touch-free sensor systems standardizing in surgical wards.
Piedmont
Turin's pharmaceutical manufacturing heritage supports fermentation ethanol production for domestic active ingredient sourcing. The region's biorefinery capacity expansion aligns with EU Green Deal carbon intensity disclosure requirements anticipated for biocidal products. Industrial zones around Novara and Alessandria concentrate sterile filling operations serving hospital supply chains.
Veneto
Verona and Padua hospital clusters institutionalized post-pandemic hygiene protocols ahead of national averages. Regional purchasing authorities specify alcohol-based antiseptic formats for surgical hand preparation. The Veneto pharmaceutical corridor connects to Lombardy distribution networks through established logistics channels.
Emilia-Romagna
Bologna-based Azienda Sanitaria Locale structures pioneered multi-year supply agreements with transparent carbon footprint documentation. The region's food processing industry generates parallel demand for HACCP-compliant hand hygiene infrastructure. Parma and Modena manufacturing zones support packaging material supply for bottle and dispenser production.
Lazio
Rome's fragmented hospital procurement landscape offers expansion opportunity for ECHA-registered suppliers with regional logistics partnerships. The Ministry of Health's biocidal product registration enforcement creates compliance barriers that favor established players over emerging domestic blenders. Central Italy's underpenetrated clinical infrastructure contrasts with northern concentration patterns.
Italy Hand Sanitizer Market Key Industry Players
Channel-controlling players compete with product-specialist players across pharmacy, hospital, and institutional procurement segments. Market structure tilts toward consolidation as central purchasing authorities compress supplier lists to ECHA-registered manufacturers with dedicated regulatory affairs functions. Three archetypes dominate: multinational hygiene conglomerates with integrated dispenser hardware, pharmaceutical-grade blenders with sterile filling certification, and regional distributors with local logistics relationships. Competitive moves concentrate on strategic partnerships with hospital procurement networks and portfolio diversification into sustainable ethanol sourcing.
Among Germany-based hygiene conglomerates, Henkel AG & Co. KGaA and Reckitt Benckiser Group PLC occupy positions anchoring premium gel format distribution through pharmacy retail channels. US-based infection control specialists Ecolab Inc. and GOJO Industries Inc. exemplify the dispenser-integrated archetype, with the latter representing automated dispensing technology deployment in Lombardy healthcare clusters. These named entities sit within broader competitive dynamics where regulatory compliance capacity separates scalable suppliers from mid-tier blenders facing ECHA dossier preparation delays.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| Unilever PLC |
| Procter & Gamble Company |
| 3M Company |
| GOJO Industries Inc. |
| Henkel AG & Co. KGaA |
| Ecolab Inc. |
| Himalaya Global Holdings Ltd. |
| Colgate-Palmolive Company |
| Others |
Cost & Logistics Intelligence
Milan-Turin pharmaceutical corridor freight economics compress logistics costs for northern Italian manufacturers while amplifying price differentiation between REACH-certified hospital-grade formulations and uncertified retail alternatives. This corridor density enables scaled suppliers to absorb ECHA compliance overhead into premium pricing, leaving mid-tier blenders exposed to margin erosion.
Pricing Analysis
Sensor-activated dispenser systems command substantial premiums over manual pump formats, while gel formulations price below foam alternatives due to mature manufacturing scale. Three-tier pricing structure across premium, standard, and economy levels separates ECHA-registered hospital supply from pharmacy retail and private-label supermarket tiers. Pricing pressure stems from central purchasing authority consolidation across ASST networks, which leverages volume tender processes to extract supplier concessions. Hospital procurement committees exhibit lowest price sensitivity due to protocol-driven specification mandates, whereas individual consumers through supermarket channels demonstrate highest elasticity.
Supply Chain Analysis
Pharmaceutical-grade ethanol feedstock draws from German biorefinery exports, Brazilian sugarcane fermentation capacity, and domestic Po Valley agricultural processing zones. Active ingredient sourcing hinges on REACH-compliant acetaldehyde limits, carbomer thickener availability, and sterile-grade water treatment infrastructure. Single-source vulnerability concentrates in northern Italian sterile filling facilities certified to ISO 14644 cleanroom standards. Distribution runs through Ecolab Inc.'s infection control network for hospital contracts, Federfarma pharmacy cooperatives for retail, and Amazon.it for direct institutional purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA dossier preparation expertise functions as the critical constraining asset, with 12-18 month registration timelines creating defensive moats for incumbents and barriers for aspirants. This capability scarcity shapes competitive dynamics across all strategic postures.
For Market Incumbents: Harden regulatory affairs infrastructure through dedicated REACH compliance teams and accelerated sterile filling capacity expansion in Piedmont industrial zones. Ecolab Inc.'s hospital distribution network represents the primary substitution threat for direct manufacturer relationships. Backward integration into fermentation ethanol production secures supply chain resilience against pending EU Green Deal carbon intensity thresholds. For New Entrants and Emerging Players: Build out regional logistics partnerships targeting Lazio and Campania hospital networks where procurement fragmentation persists. Central and southern Italy healthcare infrastructure offers the most penetrable geographic white space. Go-to-market execution should emphasize ECHA-registered formulation transparency and carbon footprint documentation to satisfy emerging tender requirements. For Investors and Strategic Acquirers: Pharmaceutical-grade blenders with sterile filling certification and established ECHA registration portfolios represent the priority acquisition archetype. Long-term viability hinges on EU Green Deal biocidal carbon threshold implementation trajectories. The signal to monitor is Ministry of Health enforcement intensity for BPR transposition compliance across regional health authorities.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | ECHA registration accelerates hospital tender eligibility and compresses competitor launch timelines. |
| Sterile Filling Capacity Expansion | ISO 14644 cleanroom investment captures ASST central purchasing contract migration. |
| Sustainable Ethanol Sourcing Transition | Brazilian sugarcane supply positions ahead of EU Green Deal carbon intensity mandates. |
| Touch-Free Dispenser Ecosystem Lock-In | Cartridge-compatible hardware secures recurring revenue through proprietary supply relationships. |
| Regional Logistics Partnership Development | Lazio and Campania distribution networks exploit procurement fragmentation in central-southern Italy. |
Research Approach
Cross-validation between primary interviews with hospital procurement managers, ECHA regulatory consultants, and sterile filling plant operators anchors the qualitative findings against secondary validation from EU BPR registration databases, REACH dossier filings, and Italian Ministry of Health authorization records. Bottom-up volume estimates from regional ASST tender disclosures triangulate with top-down market sizing derived from Federfarma pharmacy sales audits and customs ethanol import data.
Calibration against historical CAGRs from adjacent European hygiene markets informs the projection framework across the analysis window. Segmentation dimensions span product format, end-user category, packaging type, and distribution channel, with hospital procurement centralization patterns and ECHA registration velocity serving as industry-specific forecast inputs. Growth trajectories reflect compounding assumptions around post-pandemic protocol institutionalization and EU regulatory enforcement intensity.
Sensitivities concentrate around EU Green Deal biocidal carbon threshold amendments, ECHA substance evaluation timeline extensions, and regional health authority tender process standardization. Forecasts embed assumptions regarding REACH compliance cost trajectories and sterile filling capacity expansion rates. Cross-checking against ECHA's published biocidal product registration statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Medical Scrubs Market
Healthcare Products
GCC Healthcare Packaging Market
Healthcare Products
Automatic Hand Sanitizer Dispenser Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Global Consumer Healthcare Products Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Nursing Products Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Pressure Ulcer Prevention Market