
 Peptide-Based Infection Therapeutics Market | 2026-2036
Peptide-Based Infection Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide-Based Infection Therapeutics Market Analytics
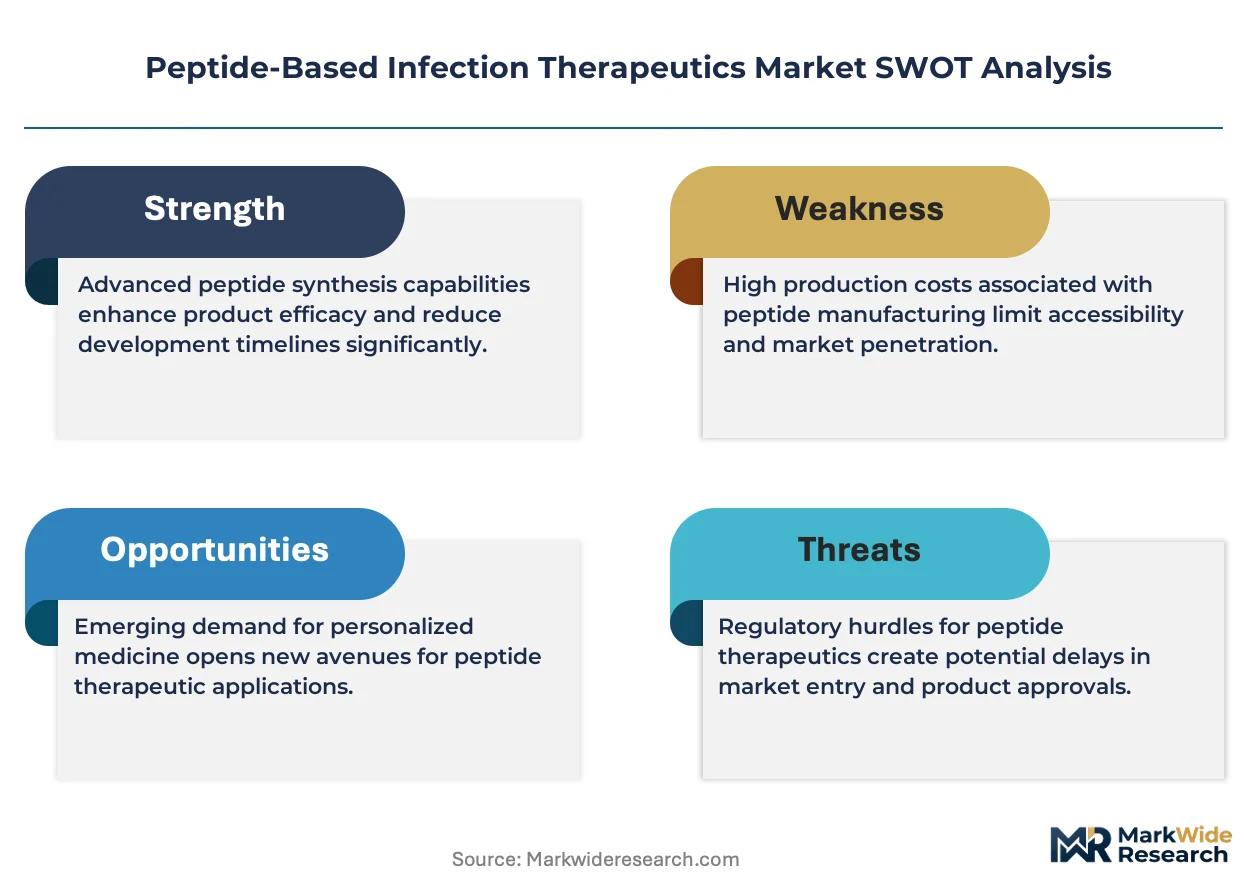
A shortage of peptide chemists and formulation scientists is unwinding development timelines across the sector. Pfizer leverages its antibiotic infrastructure to sustain manufacturing scale for late-stage candidates. Merck & Co. anchors its position through specialized bacterial infection programs. Polyphor competes in Gram-negative resistance with differentiated cyclic peptide architectures.
Peptide-based infection therapeutics comprise short amino acid sequences, typically 12–50 residues, engineered to disrupt microbial membranes or modulate host immune responses through defined secondary structures such as alpha-helices or beta-sheets. These agents serve primarily as targeted anti-infectives against drug-resistant pathogens where conventional small molecules fail. Antimicrobial peptides command the largest current revenue share due to established proof-of-mechanism in cystic fibrosis and wound infections. Immunomodulatory peptides represent the fastest-expanding category as developers pair pathogen killing with inflammation control. Injectable delivery dominates hospital settings, though oral bioavailability programs are gaining funding intensity.
FDA's Qualified Infectious Disease Product designation and EMA's PRIME scheme together shape clinical development priorities and market exclusivity timelines for peptide developers. The EPA and national antimicrobial stewardship programs in Germany and Japan further constrain prescribing patterns, directing demand toward resistance-sparing modalities. Stakeholders must monitor regulatory shifts in China and India where domestic peptide manufacturing scale is rising and local approval pathways are tightening quality benchmarks.
Market Dynamics
Antimicrobial resistance intensity is compressing development timelines and forcing hospital procurement toward resistance-sparing modalities, while peptide chemist shortages throttle manufacturing scale-up across the value chain.
Growth Catalysts
- FDA Qualified Infectious Disease Product designation:Accelerated clinical pathways and extended market exclusivity timelines incentivize peptide developers to prioritize novel mechanisms over reformulations.
- Cystic fibrosis and chronic wound care centers:Hospital networks in the United States and Germany are expanding formulary access for membrane-disrupting antimicrobial peptides with established proof-of-mechanism.
- Gram-negative resistance targeting:Cyclic peptide architectures addressing carbapenem-resistant Enterobacterales are capturing priority funding as last-resort small molecules fail.
Market Restraints
- Peptide synthesis input costs:Solid-phase synthesis resins and protected amino acid derivatives face supply volatility from concentrated Chinese specialty chemical manufacturers.
- Formulation scientist scarcity:The talent pipeline for injectable-to-oral bioavailability translation remains structurally thin across European contract development organizations.
- EPA antimicrobial stewardship constraints:Environmental discharge regulations complicate manufacturing scale-up for membrane-active peptides with aquatic toxicity profiles.
Strategic Opportunities
- Japan's reimbursement innovation corridor:PMDA's Sakigake designation offers priority review for immunomodulatory peptides combining pathogen killing with inflammation control.
- Oral bioavailability technology convergence:Cyclization chemistry paired with permeation enhancers opens ambulatory care markets currently captive to hospital infusion.
- India's domestic manufacturing scale:CDSCO tightening of peptide quality benchmarks creates first-mover advantage for compliant contract manufacturers serving export markets.
Industry Challenges
- Peptide chemist recruitment bottlenecks:Synthetic organic chemistry programs at German and Swiss universities produce insufficient graduates for industrial demand.
- cGMP facility certification timelines:EMA inspections for multi-product peptide suites extend validation cycles by 12-18 months versus small molecule equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide-Based Infection Therapeutics Market |
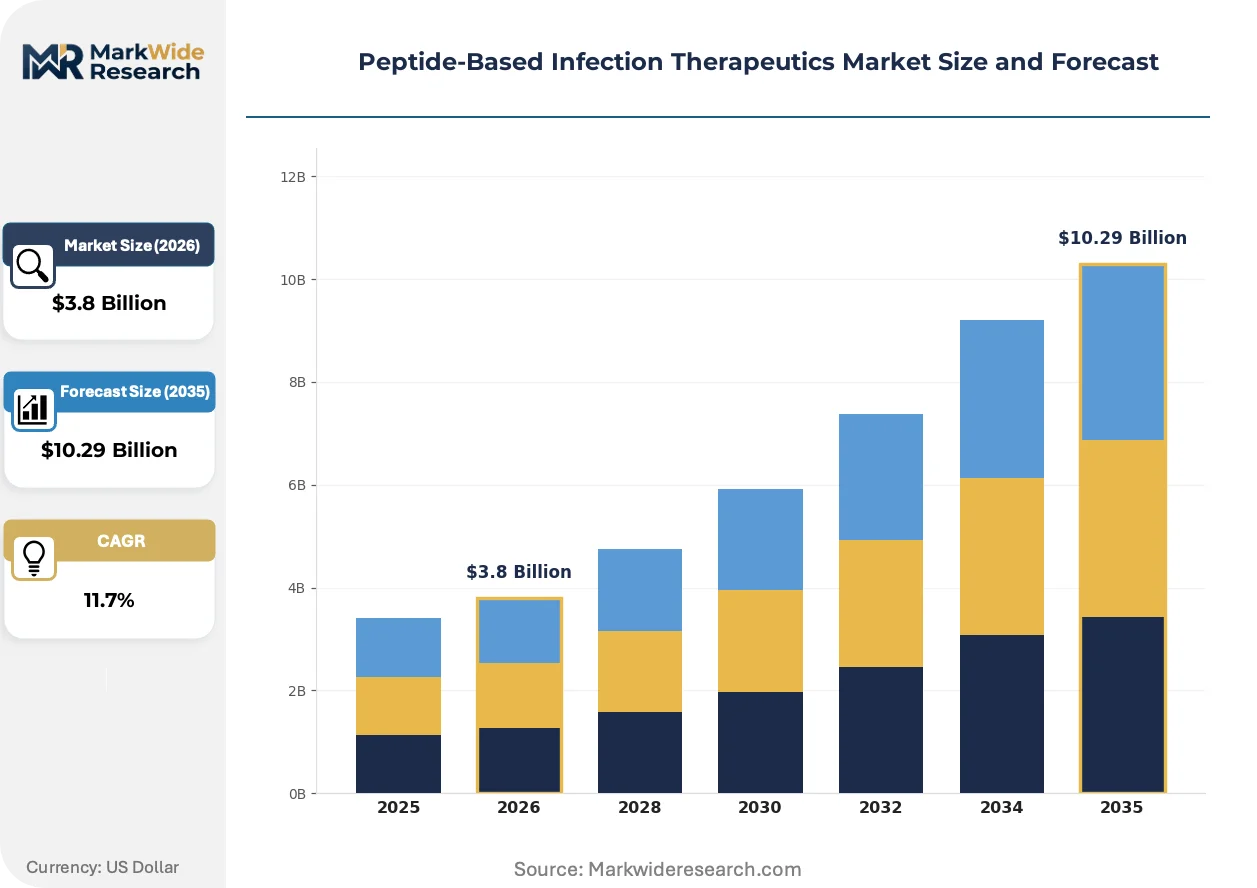
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial Peptides, Immunomodulatory Peptides, Antiviral Peptides, Cytotoxic Peptides Therapy Area: Bacterial Infections, Viral Infections, Fungal Infections, Parasitic Infections End User: Pharmaceutical Companies, Research Institutions, Hospitals, Contract Research Organizations Delivery Method: Injectable, Oral, Topical, Intranasal |
| Companies Covered | Melinta Therapeutics, Pfizer, Merck & Co., Roche Holding AG, Polyphor, Spero Therapeutics, Destiny Pharma, Summit Therapeutics, ContraFect Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide-Based Infection Therapeutics Market Evolving Landscape
Peptide engineering is splitting between hospital-critical injectables and outpatient oral programs, with regulatory incentives and manufacturing constraints pulling development in opposing directions simultaneously.
Alpha-helical antimicrobial peptides are bifurcating development priorities between cystic fibrosis lung delivery and systemic sepsis applications. Hospital pharmacies in the United States are stockpiling inhaled formulations for resistant Pseudomonas infections while venture funding concentrates on intravenous candidates for bloodstream infections. This technology split is compressing platform economics as developers must choose between validated delivery routes and unproven systemic expansion.
EMA's PRIME scheme for priority medicines is redirecting clinical trial investment toward combination therapies pairing membrane disruptors with conventional antibiotics. European developers are restructuring Phase II protocols to demonstrate resistance-sparing properties alongside efficacy endpoints. Immunomodulatory peptide programs targeting sepsis-related inflammation are capturing the bulk of accelerated assessment requests.
Hospital procurement committees are consolidating supplier relationships around integrated anti-infective stewardship contracts. United States health systems are bundling peptide therapeutics with resistance surveillance diagnostics, displacing standalone pharmaceutical purchasing. Academic medical centers in Germany and Japan are piloting this model most aggressively, pressuring manufacturers to demonstrate real-world resistance outcome data beyond registration trials.
Peptide-Based Infection Therapeutics Market Segmentation
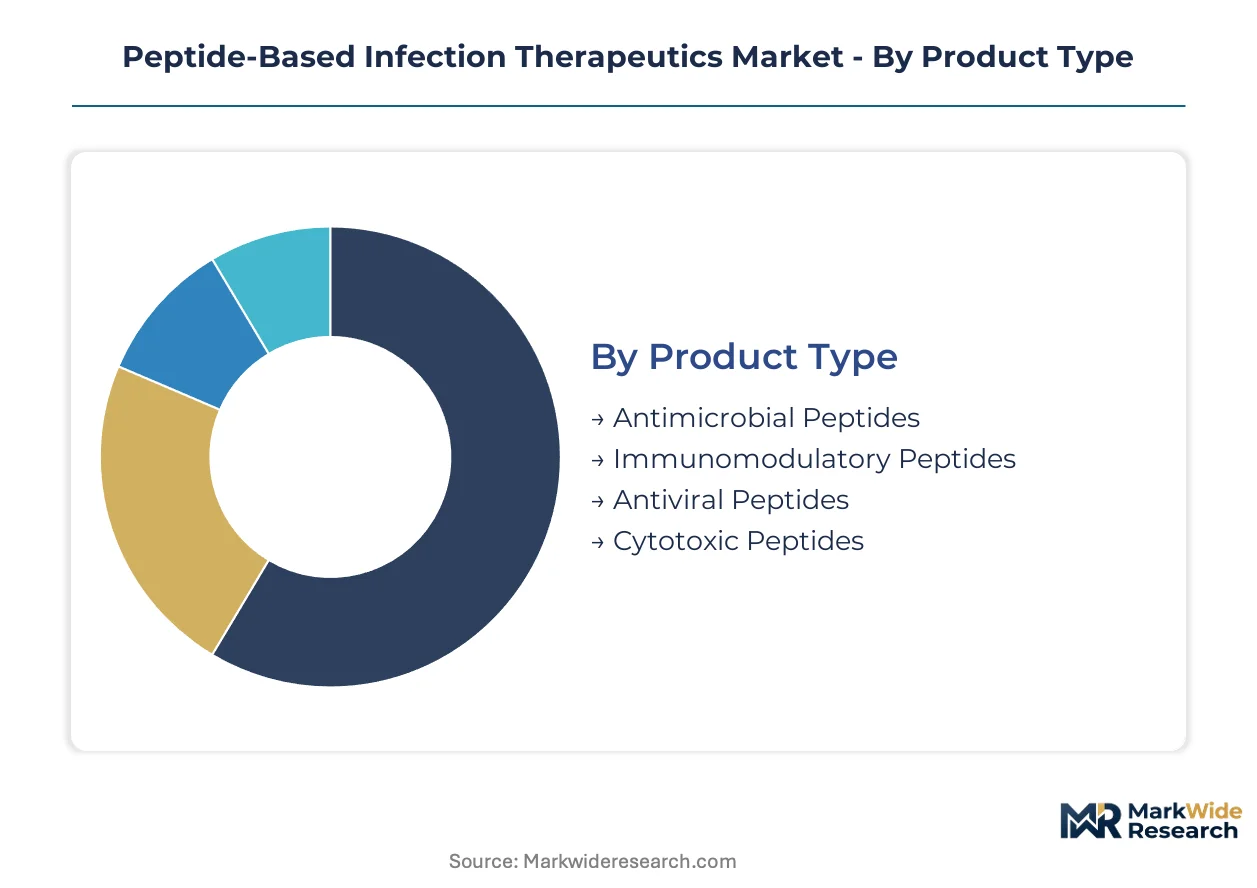
Segmentation in peptide-based infection therapeutics reveals distinct regulatory pathways and manufacturing requirements across product architectures. Each category carries specific FDA Qualified Infectious Disease Product and EMA PRIME eligibility criteria that shape development economics and market access timelines.
Product Type:
FDA's QIDP designation and EMA's PRIME scheme apply differentially across peptide functional classes, with antimicrobial and immunomodulatory categories commanding priority review resources.
- Antimicrobial Peptides:These membrane-disrupting agents, typically alpha-helical or cyclic structures of 12-50 residues, target drug-resistant bacterial membranes through physical permeabilization. Hospital procurement in the United States and Germany concentrates on inhaled formulations for cystic fibrosis Pseudomonas infections, driven by antimicrobial stewardship mandates that favor resistance-sparing modalities over conventional antibiotics.
- Immunomodulatory Peptides:Engineered sequences that combine pathogen killing with inflammation control, modulating host immune responses through defined secondary structures. Japan's PMDA Sakigake designation is accelerating clinical timelines for sepsis-related candidates, as reimbursement frameworks in Tokyo and Osaka prioritize therapies reducing intensive care duration.
- Antiviral Peptides:Entry inhibitor and fusion-disrupting sequences targeting viral envelope proteins.
- Cytotoxic Peptides:Cell-penetrating sequences engineered for targeted pathogen elimination with mammalian cell selectivity.
Antimicrobial Peptides handles the majority of throughput; Immunomodulatory Peptides is the fastest mover on share.
Therapy Area:
Clinical trial investment correlates directly with resistance surveillance data from CDC and ECDC priority pathogen lists, concentrating development in bacterial targets where small-molecule pipelines have failed.
- Bacterial Infections:Carbapenem-resistant Enterobacterales and Pseudomonas aeruginosa dominate hospital-critical development. Cyclic peptide architectures from European developers are capturing priority funding as last-resort antibiotics lose efficacy in United States academic medical centers and German university hospitals.
- Viral Infections:Respiratory syncytial virus and influenza entry inhibitors represent expanding programs. Pandemic preparedness funding from BARDA and CEPI is accelerating intranasal delivery development, with formulation scientists scarce across Swiss and German contract manufacturing organizations.
- Fungal Infections:Candida auris and azole-resistant Aspergillus targets for immunocompromised patients.
- Parasitic Infections:Malaria and leishmaniasis applications primarily in nonprofit-sponsored development pipelines.
Bacterial Infections commands the largest development spend; Viral Infections is climbing the fastest on trial initiations.
End User:
Procurement authority and quality benchmark enforcement vary sharply across customer types, with hospital pharmacy committees and pharmaceutical companies operating under divergent cGMP and stewardship requirements.
- Pharmaceutical Companies:Integrated developers with captive peptide synthesis capabilities and antibiotic infrastructure, such as those leveraging existing manufacturing scale for late-stage candidates. These organizations navigate FDA pre-approval inspections and EMA multi-product suite certifications that extend validation cycles 12-18 months beyond small-molecule equivalents.
- Hospitals:Academic medical centers and health systems in the United States, Germany, and Japan are consolidating supplier relationships around bundled anti-infective stewardship contracts. Procurement committees demand real-world resistance outcome data beyond registration trials, pressuring manufacturers to integrate surveillance diagnostics with therapeutic purchasing.
- Research Institutions:Early-stage discovery programs and NIH-funded academic collaborations.
- Contract Research Organizations:European CDMOs with peptide formulation expertise, concentrated in Switzerland and Germany.
Pharmaceutical Companies retains the dominant procurement volume; Hospitals is gaining share fastest on integrated contract expansion.
Delivery Method:
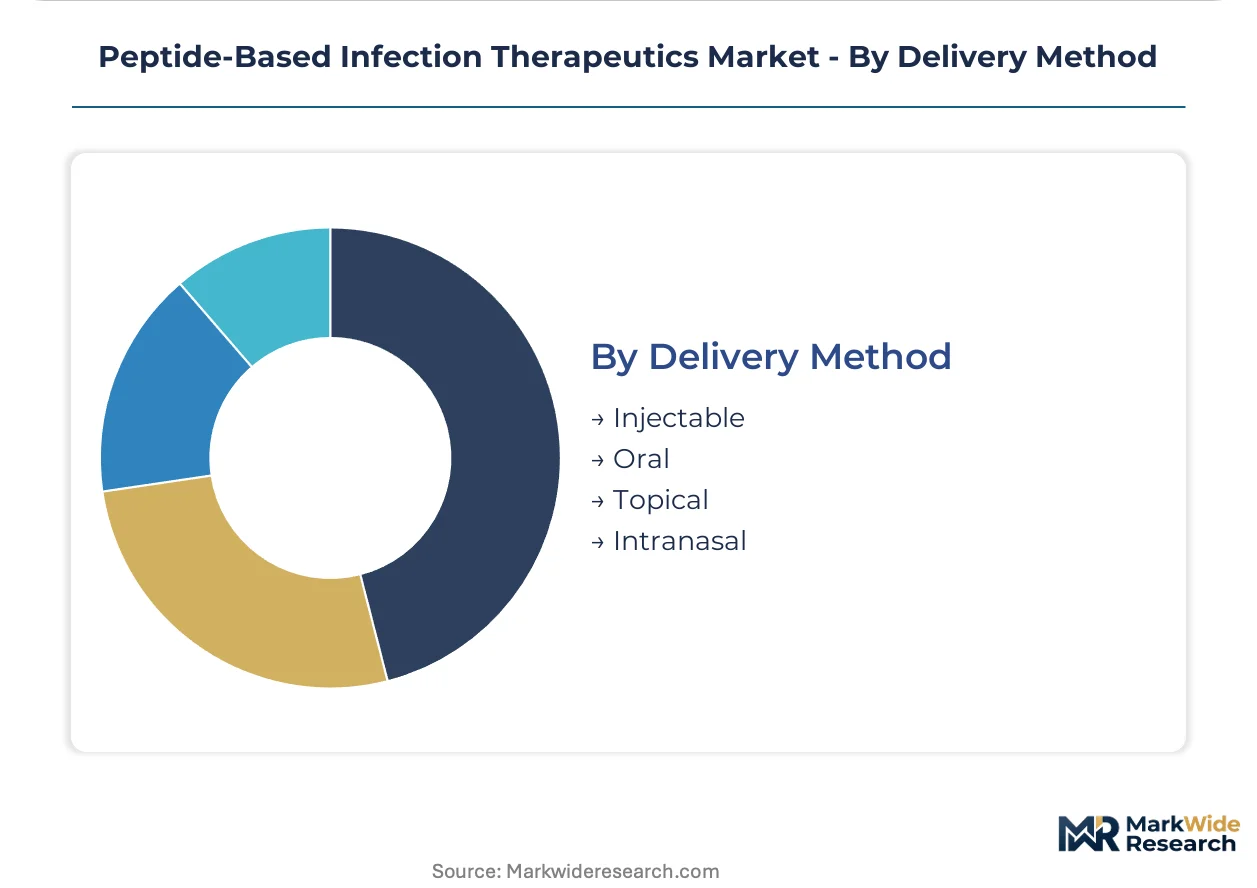
Route of administration determines manufacturing complexity, regulatory pathway, and reimbursement setting, with injectable dominance in hospital-critical applications and oral programs targeting ambulatory market expansion.
- Injectable:Intravenous and inhaled formulations dominate current revenue, serving hospital-critical bloodstream and lung infections. United States cystic fibrosis centers and German chronic wound care networks stockpile membrane-disrupting peptides, while EPA discharge regulations complicate manufacturing scale-up for aquatic-toxicity profiles.
- Oral:Bioavailability programs pairing cyclization chemistry with permeation enhancers are attracting venture funding intensity. Developers target ambulatory care markets currently captive to hospital infusion, with formulation scientist scarcity across European contract development organizations throttling translation timelines.
- Topical:Wound and skin infection applications with localized delivery advantages.
- Intranasal:Respiratory viral prophylaxis and upper airway infection targeting.
Injectable carries the current volume base; Oral is expanding most quickly on bioavailability technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Qualified Infectious Disease Product designation anchors United States market incentives, while EMA's PRIME scheme and Japan's PMDA Sakigake designation create parallel accelerated pathways across the Atlantic and Pacific.
United States
Academic medical centers in Boston and Baltimore are stockpiling inhaled antimicrobial peptides for cystic fibrosis Pseudomonas infections. BARDA pandemic preparedness funding accelerates intranasal delivery development for respiratory viral prophylaxis. The Research Triangle Park cluster in North Carolina concentrates contract manufacturing organizations serving late-stage peptide developers.
Germany
University hospitals in Munich and Heidelberg are piloting bundled anti-infective stewardship contracts that integrate peptide therapeutics with resistance surveillance diagnostics. EMA multi-product suite certifications for cGMP peptide facilities extend validation cycles 12-18 months beyond small-molecule equivalents. The Basel-Zurich corridor spills specialized formulation expertise across the Swiss-German border.
Japan
Tokyo and Osaka health systems prioritize immunomodulatory peptides that reduce intensive care duration through combined pathogen killing and inflammation control. PMDA's Sakigake designation offers priority review timelines that compress market access by 6-12 months versus standard pathways. The Kansai region hosts concentrated contract research organizations with peptide cyclization chemistry capabilities.
Switzerland
Swissmedic's alignment with EMA quality benchmarks positions Basel and Zurich as peptide manufacturing hubs for European export markets. Polyphor's cyclic peptide architectures for Gram-negative resistance anchor local specialized bacterial infection programs. The country's protected amino acid derivative suppliers face supply volatility from concentrated Chinese specialty chemical manufacturers.
India
CDSCO tightening of peptide quality benchmarks creates first-mover advantage for compliant contract manufacturers in Hyderabad and Bangalore serving export markets. Domestic peptide synthesis scale is rising as local approval pathways enforce documentation standards matching FDA and EMA precedents. The country's solid-phase synthesis resin suppliers compete with concentrated Chinese specialty chemical manufacturers for global market share.
Peptide-Based Infection Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with antibiotic infrastructure holders leveraging captive manufacturing scale against pure-play peptide developers dependent on contract synthesis networks. Pfizer and Merck & Co. anchor the upper tier through existing FDA pre-approval inspection relationships and multi-product cGMP suite certifications. The specialist tier fragments across cyclic peptide architects, immunomodulatory sequence engineers, and formulation-focused developers. Competitive moves concentrate on backward integration into protected amino acid supply and strategic partnerships with European contract development organizations to offset formulation scientist scarcity.
Within the integrated pharmaceutical tier, Pfizer and Merck & Co. represent archetypal infrastructure leverage, while Polyphor occupies a distinct position among cyclic peptide specialists targeting carbapenem-resistant Enterobacterales. These three anchors exemplify the strategic split between manufacturing-scale incumbents and mechanism-differentiated challengers.
| Leading Market Players |
|---|
| Melinta Therapeutics |
| Pfizer |
| Merck & Co. |
| Roche Holding AG |
| Polyphor |
| Spero Therapeutics |
| Destiny Pharma |
| Summit Therapeutics |
| ContraFect Corporation |
| Others |
Value Network & Pricing Analysis
Solid-phase synthesis resin substitution from European to Chinese specialty chemical manufacturers simultaneously compresses input costs and concentrates supply geography, redistributing pricing power toward concentrated raw material suppliers while fragmenting downstream formulation margins.
Pricing Analysis
Geographic price spreads between United States hospital procurement contracts and Indian export manufacturing widen as EPA discharge regulations inflate domestic production costs. Pricing stratifies across cGMP-certified premium, validated standard, and preclinical economy tiers based on FDA pre-approval inspection status and batch documentation depth. Cost compression in the economy tier intensifies because CDSCO quality benchmark tightening forces documentation upgrades. Academic medical centers in Boston and Baltimore exhibit lowest price sensitivity due to bundled stewardship contract structures, while European contract development organizations face acute margin pressure from formulation scientist scarcity.
Supply Chain Analysis
Inbound logistics costs from Shanghai Port congestion and trans-Pacific container availability constraints delay protected amino acid derivative deliveries to Basel and Zurich manufacturing hubs. Supply concentrates in China for solid-phase synthesis resins, Switzerland for cyclic peptide finishing, and India for generic API intermediates. The value chain rests on Chinese specialty chemical manufacturers for protected amino acids, European contract development organizations for formulation science, and United States hospital networks for demand absorption. Single-source vulnerability in Chinese resin supply creates structural exposure. Distribution runs through pharmaceutical company captive synthesis facilities and specialized European CDMOs serving late-stage developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement committees in the United States and Germany, with bundled anti-infective stewardship contracts displacing standalone pharmaceutical purchasing and demanding real-world resistance outcome data beyond registration trials.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into protected amino acid supply chains, securing captive resin production against Chinese supplier concentration risk. Expand cGMP multi-product suite certifications in the Research Triangle Park cluster to compress EMA validation cycles. Prioritize FDA Qualified Infectious Disease Product designation maintenance as generic peptide manufacturers threaten formulation margins through cost-competitive positioning. For New Entrants and Emerging Players: FDA's priority review voucher fast-track offers compressed clinical timelines for immunomodulatory peptides combining pathogen killing with inflammation control. White-space exists in oral bioavailability programs pairing cyclization chemistry with permeation enhancers for ambulatory care markets currently captive to hospital infusion. Target Japan's PMDA Sakigake designation corridor for reimbursement innovation advantages in sepsis applications. Go-to-market leverage rests on European contract development organization partnerships offsetting formulation scientist scarcity. For Investors and Strategic Acquirers: Capital is best deployed toward cyclic peptide architecture specialists with differentiated Gram-negative resistance mechanisms and established EMA PRIME scheme relationships. Long-term viability hinges on regulatory exclusivity duration rather than manufacturing scale alone. Watch FDA QIDP designation velocity as inflection indicator for portfolio prioritization shifts among integrated pharmaceutical developers.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA PRIME scheme access compresses European market access timelines for sepsis candidates. |
| Regulatory Approval Pathway | FDA QIDP designation extends market exclusivity and accelerates priority review for novel mechanisms. |
| Backward Integration | Captive protected amino acid supply insulates against Chinese specialty chemical manufacturer concentration. |
| Manufacturing Scale-Up | Research Triangle Park cGMP expansion serves late-stage peptide developers with FDA pre-approval inspection readiness. |
| Hospital System Partnership | Bundled stewardship contracts with academic medical centers integrate resistance surveillance with therapeutic purchasing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Primary interviews engaged drug development executives at integrated pharmaceutical companies, regulatory affairs leads navigating QIDP and PRIME pathways, hospital procurement managers in Boston and Baltimore academic medical centers, and payer access specialists in Tokyo and Osaka health systems. Secondary validation drew from SEC 10-K disclosures, Swissmedic quality benchmark documentation, and CDSCO regulatory circulars. Bottom-up patient-flow modeling and top-down market sizing triangulate volume and value estimates.
Segmentation dimensions modeled include peptide functional class, therapy area, delivery method, and regional regulatory cluster across the projection horizon. Treatment line positioning, administration route economics, and hospital versus ambulatory care setting further stratify demand. CAGRs derive from epidemiological trend analysis, resistance surveillance data from CDC and ECDC priority pathogen lists, and reimbursement framework evolution in United States, German, and Japanese markets. Forecast inputs incorporate antimicrobial stewardship mandate intensity and peptide chemist pipeline constraints from German and Swiss university programs.
Decision-makers should treat outputs as directional under base assumptions of sustained antimicrobial resistance intensification and stable FDA QIDP incentive structures; material deviation in regulatory exclusivity duration or hospital procurement consolidation velocity would warrant model refresh. Specific risk factors include EPA discharge regulation tightening for membrane-active peptides, Chinese specialty chemical export restriction implementation, and EMA multi-product suite certification timeline extension. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global Disinfection Robots Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Ear Infection Treatment Market
Infection Control
Hand Hygiene Products Market
Infection Control
Global Viral Inactivation Market
Infection Control
South Africa Antibacterial Soap Market
Infection Control
Botulism Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Infection Control Supplies Market
Infection Control
Global Hospital Infection Therapeutics Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Alcohol Wipes Market
Infection Control
Infection Control Market
Infection Control
Pertussis Infection Testing Market