
 Hand Sanitizer Market | 2026-2036
Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Sanitizer Market Analysis
Single-use sachet unbundling is shifting buyer choice toward portable, pocket-sized formats across travel and workplace segments. Reckitt Benckiser Group Plc leverages its Lysol brand equity to dominate retail shelf positioning in North American pharmacy chains. GOJO Industries, Inc. anchors the institutional channel through its Purell dispensing systems embedded in hospital and airport infrastructure. Unilever Plc competes across price tiers with Lifebuoy variants tailored to emerging-market consumers.
Hand sanitizer denotes a topical antiseptic preparation containing ethanol, isopropanol, or benzalkonium chloride formulated to reduce microbial load on intact skin, typically manufactured through batch compounding in stainless-steel vessels followed by automated filling and capping. Its primary commercial purpose spans healthcare infection control, food-service hygiene compliance, and consumer convenience in settings lacking soap and water access. Gel formulations sustain the largest revenue share due to viscosity-controlled dosing and reduced spillage in clinical environments. Alcohol-based formulations lead volume given WHO and CDC endorsement of minimum sixty percent ethanol content for pathogen inactivation. Spray configurations represent the fastest-growing product type, driven by surface-and-hand dual-use positioning and finer particle dispersion.
The FDA governs active ingredient safety and efficacy through its ongoing OTC monograph reform, while the EPA regulates sanitizer claims against specific viral pathogens under FIFRA standards. OSHA workplace sanitation mandates compel employers across manufacturing and logistics to maintain accessible sanitizer stations, embedding recurring institutional demand. REACH compliance in Europe restricts certain preservative chemistries, redirecting formulation R&D toward biobased alternatives. Stakeholders must monitor evolving monograph finalization timelines and antimicrobial resistance scrutiny to align portfolio investments with compliance-bound market access.
Market Dynamics
Healthcare procurement departments are consolidating vendor relationships around bulk refill systems that reduce per-unit cost while satisfying Joint Commission audit requirements. This institutional purchasing compression is redistributing margin from branded dispensers to formulation suppliers capable of certifying alcohol content stability across extended shelf lives.
Growth Catalysts
- OSHA workplace mandates:Manufacturing and logistics employers must maintain accessible sanitizer stations under federal workplace sanitation rules, embedding recurring institutional volume.
- India:School district hygiene programs and urban transit authority procurement are expanding accessible distribution points in high-density corridors.
- Surface-and-hand dual-use sprays:Finer particle dispersion technology is capturing travel and hospitality segments seeking versatile application formats.
Market Restraints
- Ethanol feedstock volatility:Corn and sugarcane-derived alcohol prices fluctuate with agricultural commodity cycles, compressing margin on economy-tier formulations.
- China:Concentrated production of pump mechanisms and PET containers creates single-source vulnerability for Western contract manufacturers.
- Benzalkonium chloride efficacy ceiling:This non-alcohol active demonstrates inferior viral inactivation against enveloped pathogens per CDC guidance, limiting clinical adoption.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization with FDA standards is accelerating market access for alcohol-based formulations previously restricted by preservative rules.
- Biobased emollients:Glycerin derived from waste vegetable oil streams is converging with carbon accounting requirements to differentiate premium positioning.
- Direct-to-institution e-procurement:Hospital network purchasing cooperatives are bypassing traditional distribution tiers through centralized digital platforms.
Industry Challenges
- OTC monograph compliance timelines:FDA finalization of alcohol-based sanitizer standards creates formulation uncertainty requiring dual-track R&D investment.
- Automated filling line reconfiguration:Transitioning between gel and spray viscosities demands capital-intensive changeover protocols that constrain batch flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Sanitizer Market |
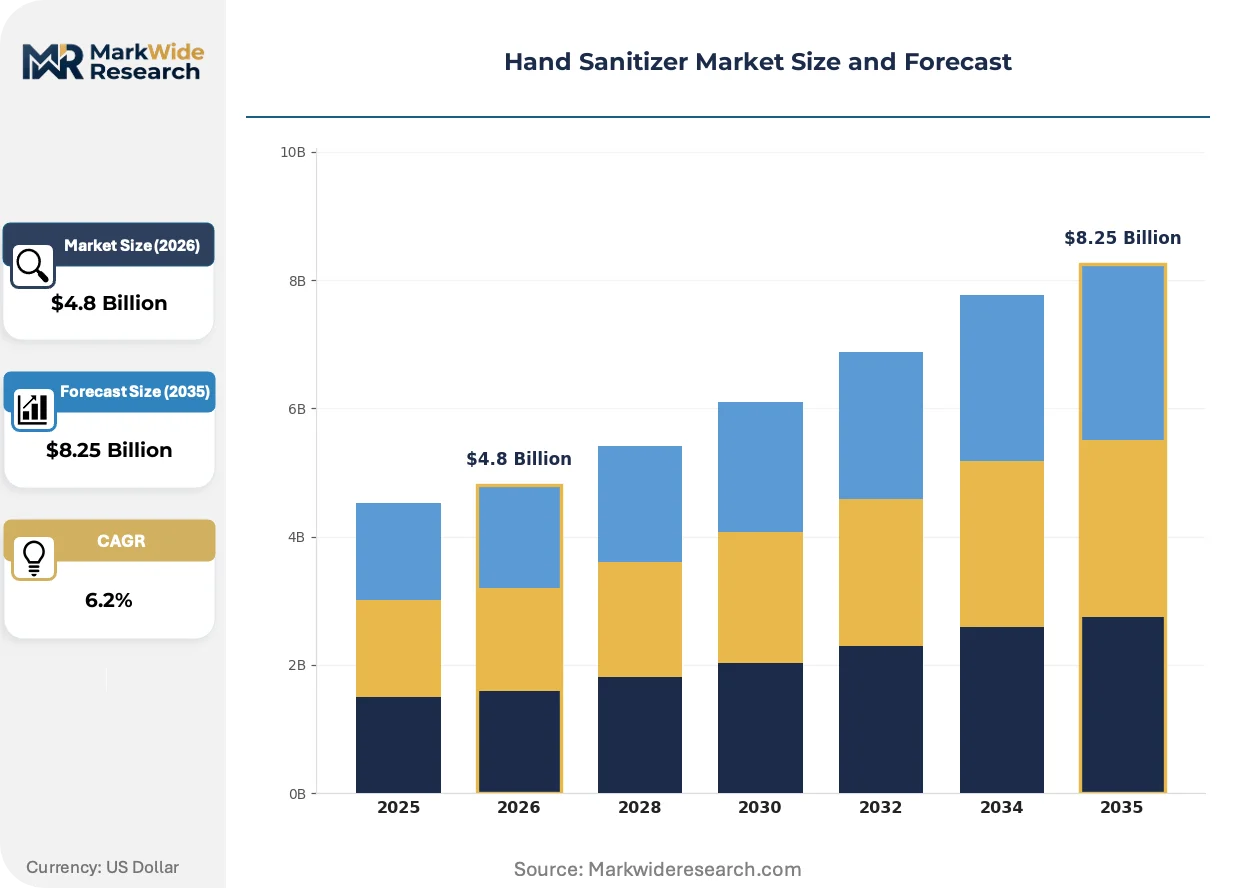
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Spray, Liquid Formulation: Alcohol-based, Alcohol-free, Antibacterial, Herbal Packaging Type: Tube, Bottle, Refill, Pump Distribution Channel: Retail, Online, Wholesale, Institutional |
| Companies Covered | Reckitt Benckiser Group Plc, Procter & Gamble Company, Unilever Plc, GOJO Industries, Inc., Henkel AG & Co. KGaA, 3M Company, The Clorox Company, Ecolab Inc., Chattem, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Sanitizer Market Emerging Trajectories
Formulation chemistry and dispensing hardware are converging to deliver measurable dosing precision while reducing packaging waste. This convergence is compressing the traditional separation between clinical efficacy claims and consumer convenience expectations.
Encapsulated alcohol microspheres are unifying controlled release with skin-moisturizing functionality in a single active delivery system. Hospital infection control departments are piloting these formulations to reduce dermatitis incidence among nursing staff with frequent hand hygiene protocols. This technology is unifying therapeutic and cosmetic benefits that previously required separate product applications.
REACH compliance deadlines in Europe are restricting benzalkonium chloride concentrations and certain synthetic preservatives, redirecting R&D toward plant-derived antimicrobial alternatives. Formulators must resubmit safety dossiers for existing product lines, compressing time-to-market for portfolio refreshes. German and French cosmetic ingredient suppliers are accelerating biobased preservative development to capture reformulation contracts.
Subscription-based replenishment programs are displacing spot purchasing in corporate wellness and educational institution channels. Facility managers are consolidating vendor relationships around automated inventory monitoring systems that trigger refill shipments. This pattern is most visible in United States school districts and airport concession networks seeking to eliminate stockout risk during peak travel seasons.
Hand Sanitizer Market Segmentation
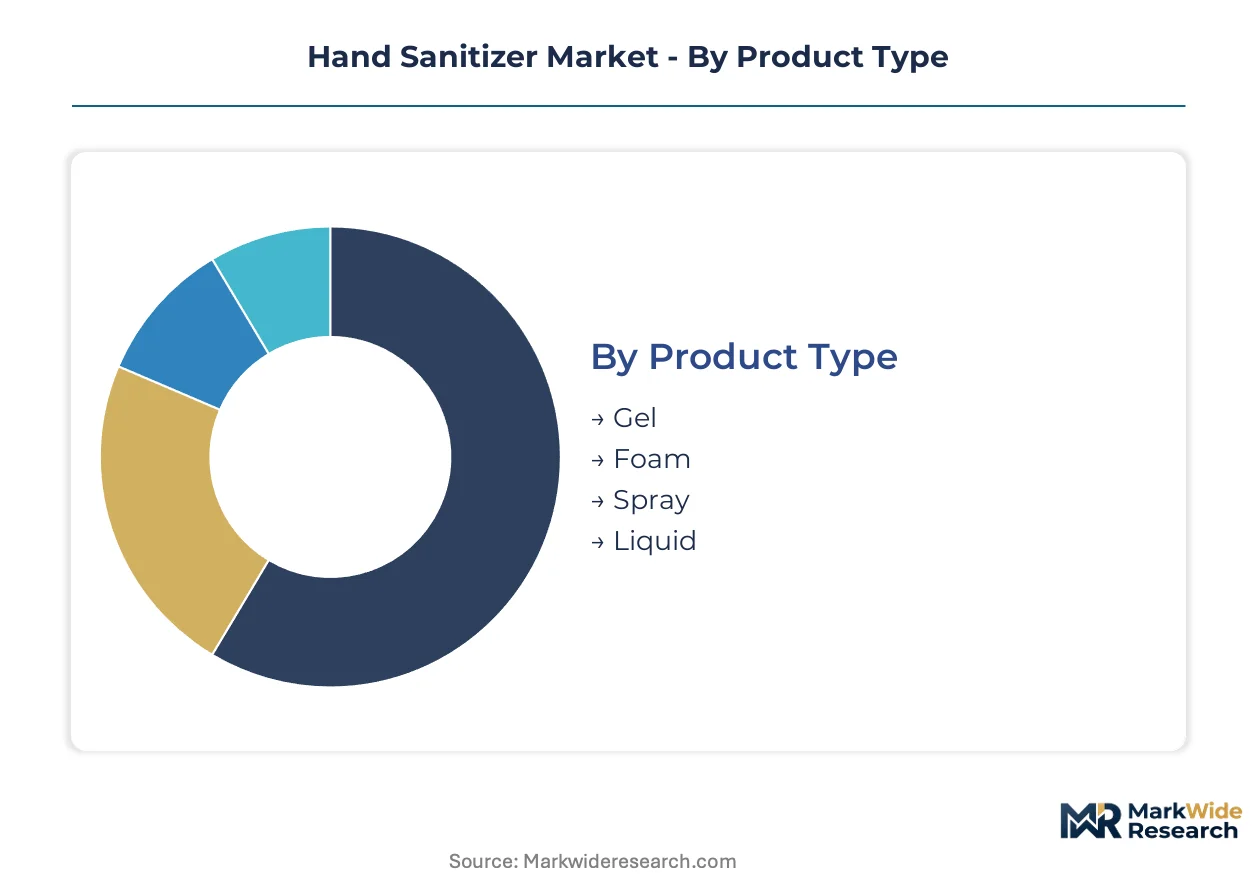
Hand sanitizer purchasing decisions diverge sharply across clinical, institutional, and consumer contexts, with viscosity, active chemistry, and dispensing format each governing access to distinct contract tiers. Procurement specifications from hospital networks, school districts, and retail chains create non-overlapping demand profiles that reshape manufacturing priorities.
Product Type:
Upgrade cycles in healthcare and hospitality infrastructure are replacing legacy dispensers with multi-format systems that accommodate gel, foam, and spray from a single mounting unit.
- Gel:Viscosity-controlled dosing reduces spillage in high-throughput clinical environments. Hospital infection control departments specify gel for its dwell time on skin surfaces, with United States hospital networks driving bulk procurement through Joint Commission-compliant refill contracts.
- Spray:Finer particle dispersion enables dual-use surface-and-hand application, capturing demand from travel and hospitality segments. United States airport concessions and hotel chains are standardizing spray formats for guest-facing amenity programs.
- Foam:Air-entrained formulations expand volume per dose, lowering per-use cost in institutional settings with high-frequency hand hygiene protocols.
- Liquid:Thin-consistency products dominate manual pump and pour applications in food service and manufacturing floor stations where rapid absorption matters.
Gel sits at the top of the volume ranking, with Spray climbing the fastest.
Formulation:
Cost tier differentiation separates clinical-grade alcohol-based products from economy-positioned alternatives, with active chemistry determining reimbursement eligibility and regulatory pathway.
- Alcohol-based:Ethanol or isopropanol concentrations above sixty percent meet WHO and CDC efficacy thresholds for enveloped pathogen inactivation. United States healthcare procurement mandates alcohol-based formulations for clinical settings, embedding recurring volume through GPO contracts.
- Herbal:Plant-derived antimicrobial blends target consumers seeking preservative-free positioning, with German and French cosmetic ingredient suppliers accelerating biobased development under REACH compliance deadlines.
- Alcohol-free:Benzalkonium chloride formulations serve segments with flammability restrictions, though CDC guidance limits clinical adoption due to inferior viral inactivation profiles.
- Antibacterial:Triclosan and alternative actives occupy niche regulatory spaces outside FDA OTC monograph coverage, primarily in industrial hygiene applications.
Alcohol-based commands the dominant share by procurement value, with Herbal expanding most quickly in premium consumer channels.
Packaging Type:
Volume scale and customer type reshape packaging economics, with institutional buyers compressing per-unit cost through bulk refill systems while retail channels prioritize shelf differentiation.
- Refill:Bulk reservoir systems reduce packaging waste and per-dose cost for hospital networks and school districts. United States educational institutions are consolidating vendor relationships around automated inventory monitoring that triggers refill shipments.
- Pump:Metered-dose mechanisms dominate food service and manufacturing floor stations under OSHA workplace sanitation mandates.
- Bottle:Standard containers serve retail pharmacy and grocery channels with branding surface for shelf competition.
- Tube:Collapsible formats capture travel and personal carry segments seeking portable, pocket-sized convenience.
Refill leads institutional procurement volume, with Tube gaining share fastest in travel and workplace segments.
Distribution Channel:
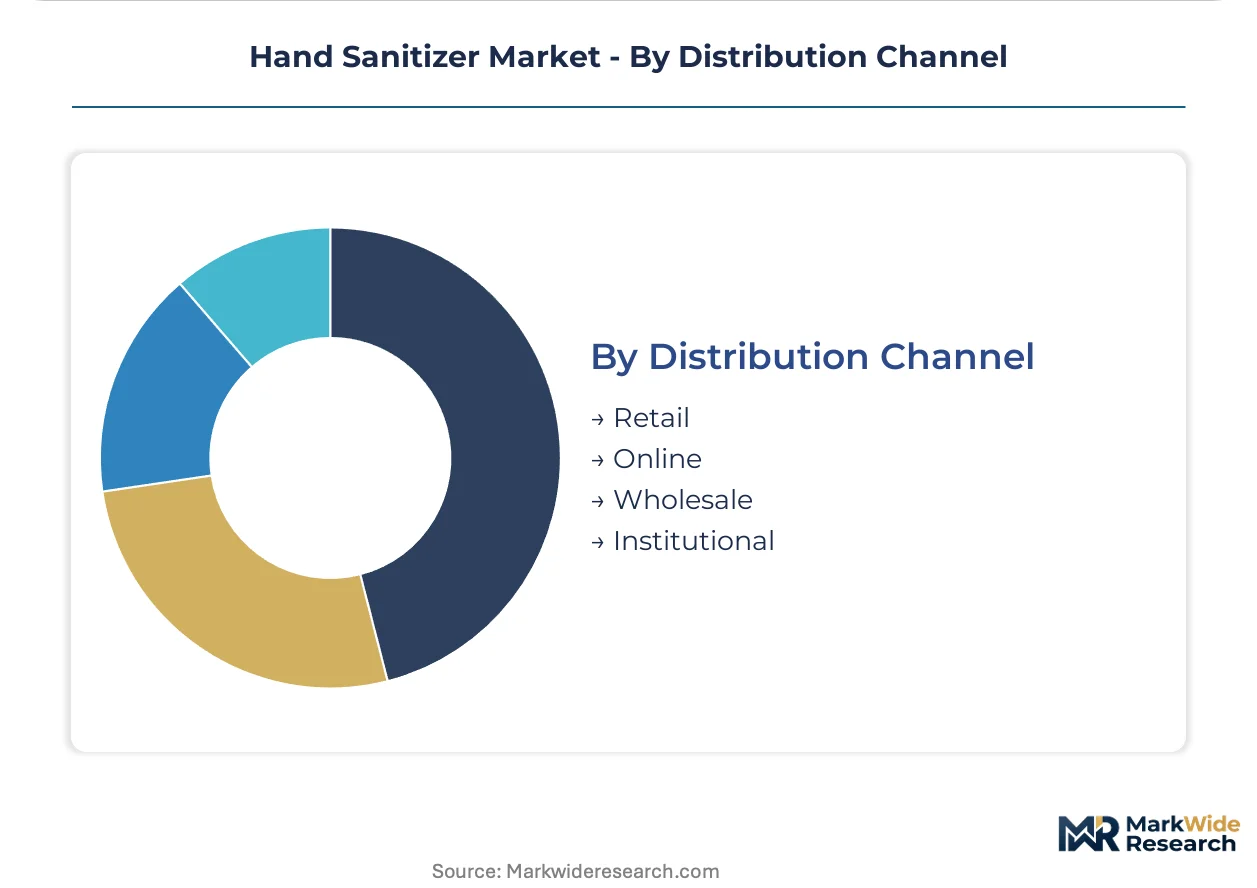
Supply concentration and margin structure separate direct-to-institution platforms from tiered wholesale networks, with digital procurement bypassing traditional distribution layers.
- Institutional:Hospital network purchasing cooperatives and school district contracts embed recurring demand through multi-year supply agreements. United States GPOs consolidate vendor relationships around bulk refill certification and alcohol stability documentation.
- Online:Direct-to-consumer and direct-to-institution e-procurement platforms are displacing spot purchasing, with subscription-based replenishment programs capturing corporate wellness and educational channels.
- Retail:Pharmacy chains and mass merchants compete on shelf positioning and brand equity, with North American pharmacy chains driving volume through seasonal promotional cycles.
- Wholesale:Distributor networks serve fragmented food service, manufacturing, and small healthcare accounts lacking direct contract scale.
Institutional channels anchor procurement value, with Online expanding most quickly through centralized digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hand sanitizer industry traces its modern commercial lineage to institutional healthcare procurement in the United States during the 1990s, when hospital infection control protocols first mandated alcohol-based formulations at point-of-care stations. This clinical origin shaped subsequent regulatory frameworks and manufacturing standards that now govern regional market development.
United States
Hospital network purchasing cooperatives and school district supply agreements embed recurring demand through multi-year contracts. FDA OTC monograph reform continues reshaping formulation standards for alcohol-based products. Cincinnati anchors institutional channel distribution, with GOJO Industries maintaining embedded infrastructure across hospital and airport networks.
Germany
REACH compliance deadlines restrict benzalkonium chloride concentrations and synthetic preservatives, redirecting R&D toward plant-derived alternatives. ECHA regulatory oversight compresses time-to-market for portfolio refreshes requiring safety dossier resubmission. Frankfurt and Hamburg cosmetic ingredient suppliers accelerate biobased preservative development to capture reformulation contracts.
India
School district hygiene programs and urban transit authority procurement expand accessible distribution points in high-density corridors. CDSCO regulatory harmonization with FDA standards accelerates market access for alcohol-based formulations. Mumbai and Delhi manufacturing clusters scale production to meet institutional tender requirements from state education departments.
Brazil
ANVISA regulatory harmonization with FDA standards accelerates market access for alcohol-based formulations previously restricted by preservative rules. Federal hygiene mandates in food processing and healthcare facilities drive institutional procurement volume. São Paulo state manufacturers expand capacity to serve Mercosur regional distribution networks.
China
Concentrated production of pump mechanisms and PET containers creates supply chain positioning for Western contract manufacturers. NMPA oversight of cosmetic and disinfectant classifications shapes import registration pathways. Guangdong and Zhejiang manufacturing clusters dominate component fabrication for global brand packaging requirements.
Hand Sanitizer Market Vendor Landscape
The competitive structure tilts toward brand-holding conglomerates with cross-category hygiene portfolios. Market concentration reflects dual-channel dominance requirements: retail shelf positioning in pharmacy chains alongside institutional procurement certification for healthcare networks. Three archetypes prevail: multinational consumer goods conglomerates leveraging brand equity, institutional specialists with embedded dispensing infrastructure, and private-label manufacturers serving price-sensitive bulk procurement. Geographic expansion through distributor partnerships and portfolio diversification into adjacent surface disinfectant categories represent the dominant competitive moves.
Within the multinational tier, Reckitt Benckiser Group Plc and Unilever Plc exemplify brand-holding conglomerates with cross-category hygiene portfolios. GOJO Industries, Inc. occupies a position as the institutional specialist archetype. These three companies represent the spectrum of competitive positioning from retail brand equity to embedded infrastructure deployment.
| Leading Market Players |
|---|
| Reckitt Benckiser Group Plc |
| Procter & Gamble Company |
| Unilever Plc |
| GOJO Industries, Inc. |
| Henkel AG & Co. KGaA |
| 3M Company |
| The Clorox Company |
| Ecolab Inc. |
| Chattem, Inc. |
| Others |
Supply Flow & Price Mechanics
REACH compliance deadlines in Europe gate qualified supply and premium-tier pricing access, as formulators must resubmit safety dossiers for biobased preservative alternatives. This regulatory filtration compresses time-to-market for portfolio refreshes while concentrating margin capture among suppliers with certified alcohol stability documentation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade alcohol-based formulations from private-label institutional contracts and commodity spot purchases. Price differentiation hinges on FDA OTC monograph certification status and volume-scale procurement through GPO contracts. Pricing pressure stems from ethanol feedstock volatility tied to agricultural commodity cycles, compressing margins on economy-tier formulations. Hospital networks exhibit lowest price sensitivity due to Joint Commission audit requirements, while food service distributors face acute cost compression from OSHA mandate compliance without reimbursement mechanisms.
Supply Chain Analysis
Workforce availability in Guangdong and Zhejiang manufacturing clusters anchors global pump mechanism and PET container fabrication for Western contract manufacturers. Raw material dependencies center on corn and sugarcane-derived ethanol, benzalkonium chloride active ingredients, and biobased glycerin emollients. Single-source vulnerability concentrates in Chinese component production, creating tariff exposure and logistics chokepoint risk. Distribution runs through hospital network purchasing cooperatives and direct-to-institution e-procurement platforms that bypass traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hand sanitizer market reads as a late-cycle quality story, as procurement departments shift specifications toward encapsulated alcohol microsphere formulations that unify therapeutic efficacy with dermatitis prevention.
For Market Incumbents: Anchor institutional channel position through embedded dispensing infrastructure upgrades that accommodate gel, foam, and spray formats from single mounting units. Threats from private-label manufacturers serving price-sensitive bulk procurement require certification investment in alcohol content stability across extended shelf lives. Backward integration into biobased emollient sourcing secures margin against REACH-driven reformulation cycles. For New Entrants and Emerging Players: Direct-to-institution e-procurement routes offer white-space access through subscription-based replenishment programs displacing spot purchasing in United States school districts. The travel and hospitality segment presents the most penetrable geography, with airport concessions standardizing spray formats for guest-facing amenity programs. A sustainability-forward positioning leveraging waste vegetable oil-derived glycerin captures premium-tier procurement from carbon-accounting-conscious facility managers. For Investors and Strategic Acquirers: Roll-up economics work for regional formulation specialists with FDA OTC monograph compliance infrastructure because regulatory barriers to entry are rising under ongoing monograph reform. Long-term viability favors acquisition targets with embedded hospital network contracts and automated inventory monitoring capabilities. The signal to watch is ANVISA harmonization progress in Brazil, which would accelerate market access for alcohol-based formulations and trigger regional consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Preservative Development | REACH compliance deadlines in Europe redirect R&D contracts toward German and French cosmetic ingredient suppliers. |
| Multi-Format Dispensing Infrastructure | Healthcare upgrade cycles replace legacy units with systems accommodating gel, foam, and spray from single mounts. |
| Direct-to-Institution E-Procurement | Hospital network purchasing cooperatives bypass traditional distribution tiers through centralized digital platforms. |
| Encapsulated Alcohol Microsphere Launch | Hospital infection control departments pilot controlled-release formulations to reduce nursing staff dermatitis incidence. |
| Subscription-Based Replenishment Program | United States school districts and airport concessions eliminate stockout risk through automated inventory monitoring. |
Methodological Framework
Multiple input streams — procurement director interviews, regulatory filing analysis, and trade flow reconciliation — were reconciled to construct demand estimates. Primary fieldwork engaged hospital infection control officers, GPO contracts managers, formulation chemists at manufacturing clusters, and facility managers at school districts. Secondary validation drew from FDA OTC monograph dockets, EPA FIFRA registration databases, ECHA REACH substance dossiers, and customs records of ethanol and packaging component trade. Bottom-up volume builds triangulated against top-down addressable market sizing.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product viscosity tier, active chemistry classification, dispensing format, end-use institutional context, and regional regulatory cluster. CAGRs were derived from trajectory fitting to procurement volume trends and price-point evolution. Industry-specific forecast inputs encompassed Joint Commission audit schedule impacts and OSHA workplace mandate enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for encapsulated alcohol microsphere dispensing would alter the outlook. Forecasts reflect embedded assumptions regarding FDA monograph finalization timelines and agricultural commodity cycle stability. Material deviation in ethanol feedstock volatility or antimicrobial resistance scrutiny warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
Elderly Walker Market
Healthcare Products
Organ Care Products Market
Healthcare Products
Europe Hand Sanitizer Market
Healthcare Products
Australia Hair Transplant Market
Healthcare Products
Medical Scrubs Market
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Contraceptive Sponges Market
Healthcare Products
Incontinence Products Market
Healthcare Products
United States Infrared Sauna Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Isolation Gowns Market
Healthcare Products
Pressure Ulcer Prevention Market