
 Atopic Dermatitis Clinical Trials Market | 2026-2036
Atopic Dermatitis Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Atopic Dermatitis Clinical Trials Market Analytics
Adaptive trial design software is repositioning how contract research organizations package clinical development services, shifting revenue from per-patient fees toward platform subscriptions and data analytics retainers. Pfizer Inc. leverages its global site network to sustain recruitment velocity across multiple concurrent Phase II and Phase III programs. Sanofi SA anchors its dermatology franchise through deep investigator relationships in European academic hospitals. Regeneron Pharmaceuticals, Inc. differentiates by controlling biologic supply chain endpoints for its IL-4Rα inhibitor trials.
Atopic dermatitis clinical trials constitute structured research protocols evaluating therapeutic interventions for a chronic inflammatory skin disease characterized by epidermal barrier dysfunction, T-helper 2 immune skewing, and pruritus severity measured via EASI and SCORAD indices; these studies generate evidence for regulatory approval and payer reimbursement decisions. Biologics segments command premium investigator fees and complex biomarker stratification, while systemic JAK inhibitor trials face elevated safety monitoring costs that compress per-study margins. Pediatric patient recruitment pools remain structurally constrained, creating bottlenecks that extend trial timelines and inflate per-enrolled-subject expenditures.
FDA, EMA, and ICH-GCP frameworks govern protocol design, adverse event reporting thresholds, and multi-regional inspection readiness, with pediatric investigation plans mandated under the EU Paediatric Regulation and FDA Pediatric Research Equity Act. The FDA's evolving dermatology guidance on placebo-controlled trial ethics shapes comparator arm selection and influences institutional review board approval timelines. Sponsors must monitor how regulator alignment on JAK class safety labeling affects investigator willingness to randomize patients into active-comparator studies.
Market Dynamics
EMA and FDA safety frameworks are intensifying scrutiny of JAK inhibitor trials, forcing sponsors to reallocate capital toward adaptive trial designs and pediatric investigation plans while compressing margins on legacy protocols.
Growth Catalysts
- EU Paediatric Regulation mandates:Pediatric investigation plans create guaranteed trial volumes for sponsors with established juvenile patient networks.
- Adaptive trial design software:CROs are capturing recurring revenue through platform subscriptions rather than transactional per-patient fees.
- Biomarker stratification protocols:IL-4Rα and IL-13 pathway targeting enables precision patient selection that accelerates regulatory approval timelines.
Market Restraints
- JAK class safety monitoring:Elevated adverse event reporting thresholds under FDA dermatology guidance inflate per-study operational costs.
- Pediatric recruitment pool scarcity:Structural constraints in qualified juvenile dermatology centers extend enrollment timelines by 40-60% versus adult equivalents.
- Biologic cold chain logistics:Temperature-controlled distribution requirements for monoclonal antibody trials limit site selection to urban academic medical centers.
Strategic Opportunities
- Real-world evidence integration:FDA's 21st Century Cures Act framework permits supplemental safety data from post-market registries to support label expansion.
- Decentralized trial models:Tele-dermatology platforms enable home-based SCORAD assessments that unlock rural and suburban patient pools.
- Asia-Pacific regulatory alignment:PMDA and MFDS are harmonizing ICH-GCP inspection standards, reducing redundant protocol amendments for multi-regional studies.
Industry Challenges
- Principal investigator scarcity:Board-certified pediatric dermatologists with IND experience concentrate in fifteen US academic medical centers, creating bidding wars for site contracts.
- Legacy EDC system integration:Sponsors face data reconciliation friction when merging adaptive platform outputs with established clinical databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atopic Dermatitis Clinical Trials Market |
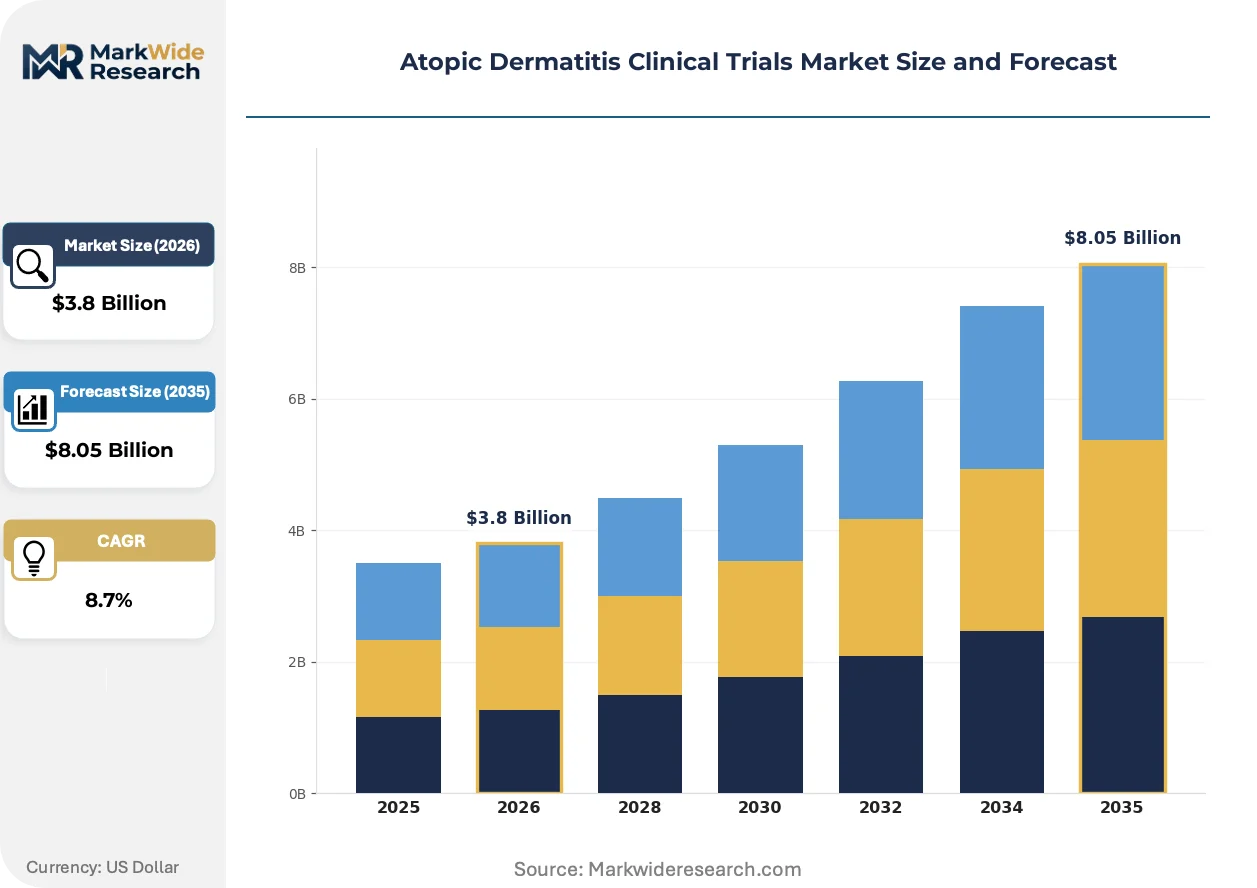
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Topical, Systemic, Biologics, Immunomodulators Study Phase: Phase I, Phase II, Phase III, Phase IV Patient Type: Pediatric, Adult, Geriatric, Mixed Trial Design: Randomized, Open-label, Double-blind, Controlled |
| Companies Covered | Pfizer Inc., Sanofi SA, Regeneron Pharmaceuticals, Inc., AbbVie Inc., Novartis International AG, Eli Lilly and Company, GlaxoSmithKline plc, Johnson & Johnson, LEO Pharma A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atopic Dermatitis Clinical Trials Market Evolving Landscape
Clinical trial execution is pivoting from site-centric to patient-centric models, with technology vendors and regulators co-evolving standards that reward adaptive protocols and compress traditional development timelines.
Electronic clinical outcome assessment platforms is unifying patient-reported pruritus severity capture with clinician EASI scoring in single workflows. Mid-tier CROs are deploying these systems across dermatology networks to differentiate from legacy paper-based competitors. This convergence is unifying data capture standards that previously fragmented between academic and community site tiers.
REACH and RoHS compliance requirements for investigational medicinal product packaging are forcing sponsors to reformulate primary container materials and document supply chain chemical footprints. European contract manufacturers are absorbing these costs to maintain EMA-qualified site status. Biologic sponsors with EU manufacturing footprints face the steepest revalidation burdens.
Site selection criteria now weight patient travel burden and parking accessibility as heavily as investigator publication history. Large dermatology networks are consolidating preferred site lists to twenty to thirty high-recruitment locations with embedded pharmacy and laboratory infrastructure. This consolidation is most pronounced in the United States, where patient dropout rates correlate directly with one-way commute times exceeding ninety minutes.
Atopic Dermatitis Clinical Trials Market Segmentation
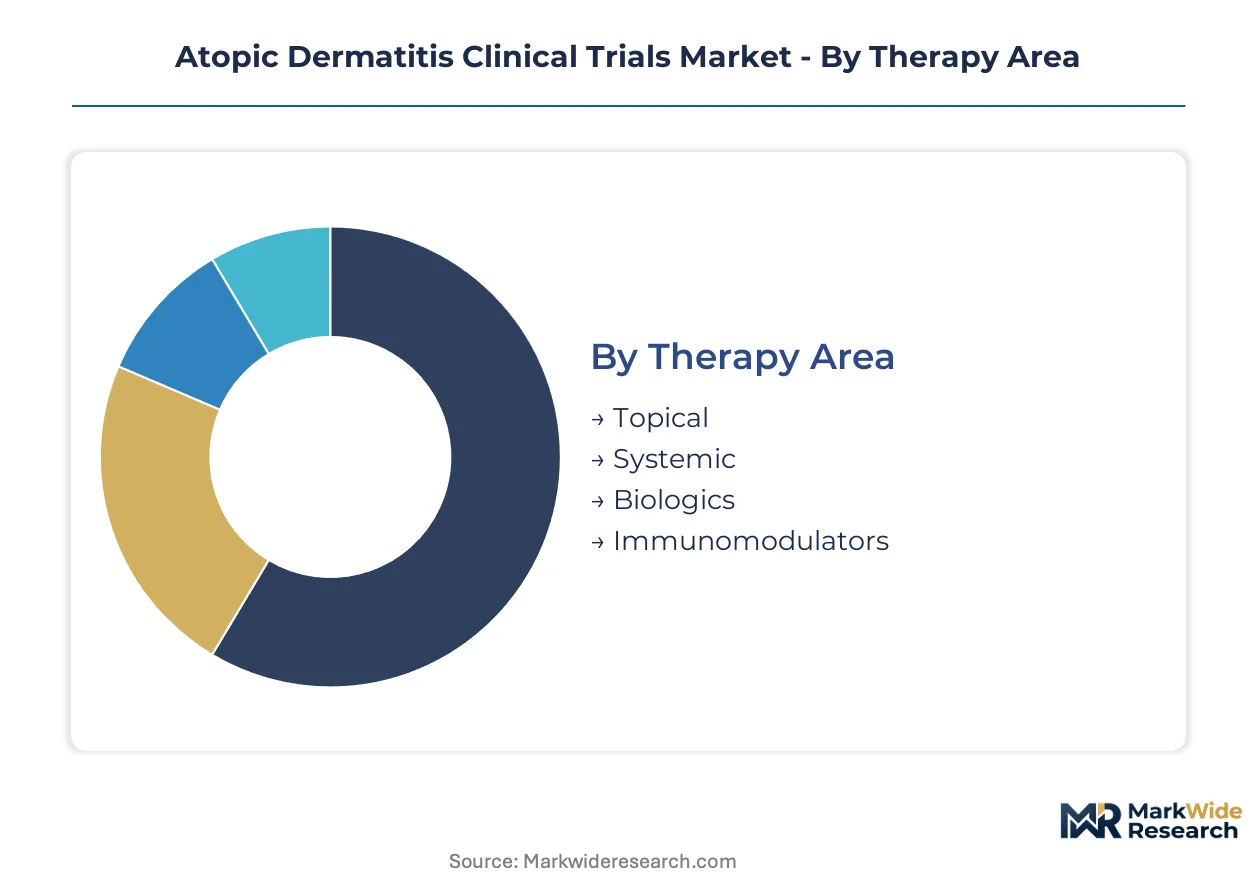
Atopic dermatitis clinical trials segment across therapeutic modality, development stage, patient population, and methodological rigor. Each dimension shapes site selection criteria, investigator fees, and regulatory submission pathways.
Therapy Area:
The customization-vs-standardization spectrum spans from commodity topical formulations to precision biologic constructs requiring cold chain stewardship and biomarker stratification.
- Topical:Corticosteroid and calcineurin inhibitor formulations dominate early-phase screening protocols. Demand concentrates in community dermatology practices across the United States and Germany where patient access costs remain minimal.
- Systemic:Oral JAK inhibitors and conventional immunosuppressants require intensive safety monitoring infrastructure. European academic medical centers absorb elevated per-patient costs under EMA pharmacovigilance frameworks.
- Biologics:Monoclonal antibodies targeting IL-4Rα and IL-13 pathways command premium investigator fees.
- Immunomodulators:Small-molecule and biologic combinations test novel mechanism synergies.
Most installed capacity flows through Topical. Expansion is steepest in Biologics.
Study Phase:
Cost tiers stratify sharply across the development continuum, with Phase I absorbing exploratory risk and Phase III carrying registration-grade validation burdens.
- Phase I:First-in-human and dose-escalation studies in healthy volunteers establish safety pharmacology. Specialized units in the United Kingdom and Australia concentrate early-phase demand due to streamlined ethics review timelines.
- Phase II:Proof-of-concept trials in moderate-to-severe patients generate efficacy signals. United States academic centers with established EASI-trained investigator networks capture dominant sponsor allocation.
- Phase III:Pivotal registration studies require multi-thousand-patient recruitment across dispersed geographies.
- Phase IV:Post-market commitment studies fulfill regulatory label expansion and pediatric investigation plan obligations.
Phase III commands the largest absolute expenditure. Phase II is gaining share fastest as adaptive designs compress traditional timelines.
Patient Type:
Application requirements diverge across age strata, with pediatric protocols mandating distinct endpoint instruments and caregiver-reported outcomes.
- Pediatric:Trials in patients aged 6 months to 17 years require SCORAD adaptation and school-schedule accommodation. Fifteen United States academic medical centers with board-certified pediatric dermatologists concentrate qualified investigator supply.
- Adult:The largest recruitment pool supports placebo-controlled designs with EASI-75 primary endpoints. Community and academic site networks across the United States, Germany, and Japan absorb volume demand.
- Geriatric:Comorbidity-heavy populations test drug-drug interaction profiles.
- Mixed:Age-spanning protocols enable label breadth but complicate statistical powering.
Adult studies carry the heaviest enrollment volume. Pediatric is expanding most quickly under EU Paediatric Regulation and FDA Pediatric Research Equity Act mandates.
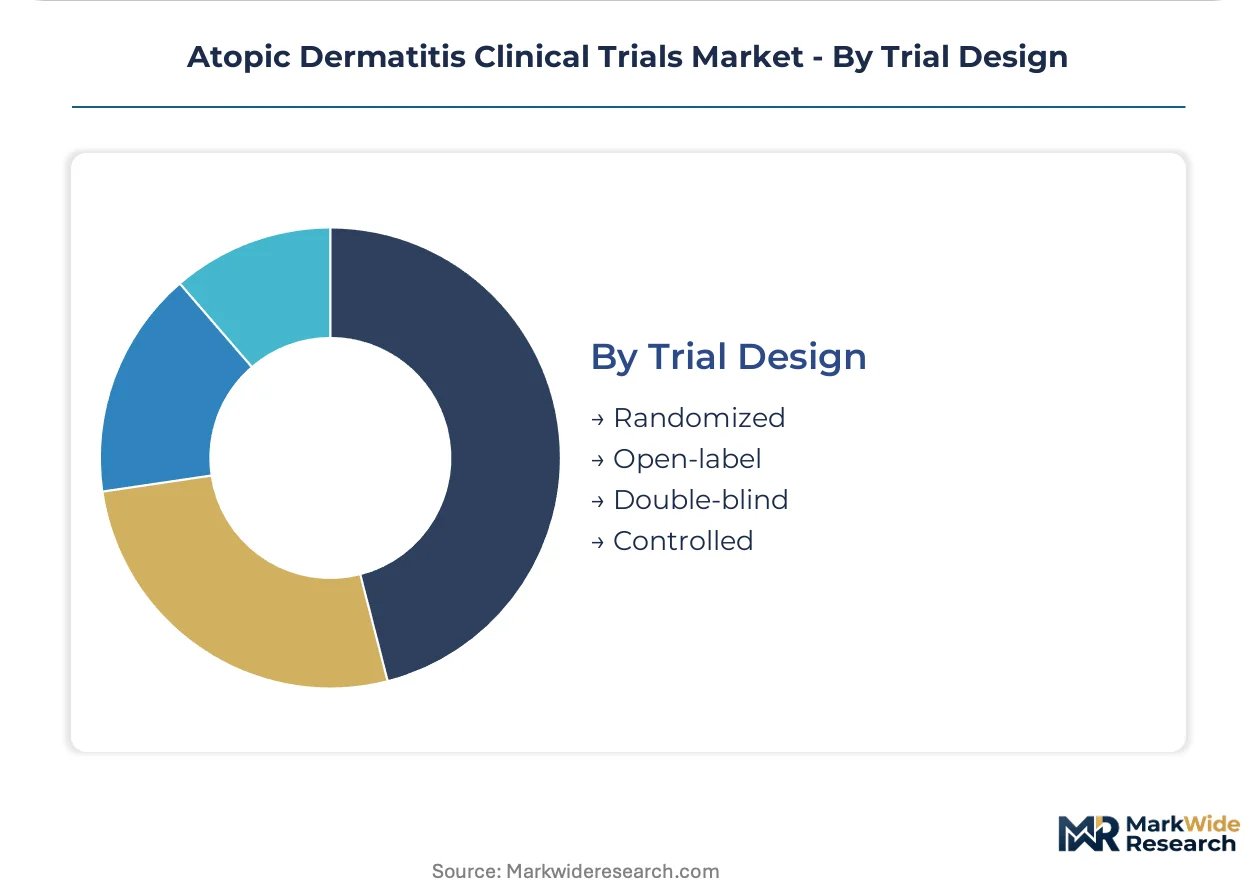
Trial Design:
Methodological rigor maps directly to regulatory acceptability, with double-blind controlled structures remaining the gold standard for marketing authorization.
- Randomized:Computer-generated allocation sequences minimize selection bias. EMA and FDA both mandate randomization for pivotal atopic dermatitis efficacy claims.
- Open-label:Unmasked designs suit long-term extension studies and compassionate access programs. Patient retention in open-label extensions runs higher than in placebo-controlled periods.
- Double-blind:Investigator and patient masking eliminates assessment bias. United States sites with dedicated pharmacy unblinding infrastructure command premium contracts.
- Controlled:Active comparator or placebo arms provide interpretable efficacy benchmarks.
Double-blind controlled studies represent the dominant installed base. Open-label designs are climbing the fastest as sponsors prioritize real-world persistence data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting trial execution toward jurisdictions with streamlined pediatric investigation pathways and harmonized ICH-GCP inspection standards. Sponsors now weigh EMA pediatric mandates against FDA Pediatric Research Equity Act obligations when siting Phase III programs. Cost-of-compliance gaps between European academic centers and United States community networks are redrawing site selection maps.
United States
Fifteen academic medical centers with board-certified pediatric dermatologists concentrate qualified investigator supply for juvenile protocols. FDA dermatology guidance on placebo-controlled trial ethics shapes comparator arm selection across pivotal studies. The Greater Boston and New York Metro corridors host dense clusters of Phase II and Phase III recruitment infrastructure with embedded pharmacy unblinding capabilities.
Germany
European academic hospitals absorb elevated per-patient costs under EMA pharmacovigilance frameworks for JAK inhibitor safety monitoring. REACH and RoHS compliance requirements for investigational medicinal product packaging force sponsors to reformulate primary container materials. The Munich and Heidelberg university hospital networks anchor biologic cold chain logistics for monoclonal antibody trials.
United Kingdom
Specialized Phase I units in London and Manchester concentrate early-phase demand due to streamlined Health Research Authority ethics review timelines. MHRA alignment with FDA pediatric investigation plan standards reduces redundant protocol amendments for transatlantic programs. The Oxford-Cambridge-London golden triangle maintains dense investigator networks for EASI-trained clinician recruitment.
Japan
PMDA harmonization with ICH-GCP inspection standards is reducing redundant protocol amendments for multi-regional studies involving Asian patient populations. Tokyo and Osaka academic centers with established SCORAD adaptation expertise capture sponsor allocation for pediatric bridging studies. METI funding for decentralized trial infrastructure is enabling tele-dermatology platforms for home-based outcome assessment.
Australia
TGA streamlined clinical trial notification pathways attract early-phase sponsor allocation for first-in-human and dose-escalation studies in healthy volunteers. Sydney and Melbourne specialized units offer rapid ethics turnaround for adaptive trial designs. The country's seasonal recruitment advantages enable counter-cyclical enrollment against Northern Hemisphere site networks.
Atopic Dermatitis Clinical Trials Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with biopharmaceutical sponsors retaining direct control over Phase III execution while outsourcing early-phase and pediatric protocols. The vendor base concentrates around three strategic archetypes: global site networks with embedded recruitment infrastructure, precision biomarker laboratories with IL-4Rα pathway expertise, and adaptive platform vendors capturing recurring subscription revenue. Competitive positioning hardens through investigator relationship depth and pediatric site exclusivity arrangements rather than price competition.
Among established biopharmaceutical developers, Pfizer Inc., Sanofi SA, and Regeneron Pharmaceuticals, Inc. occupy positions exemplifying distinct strategic archetypes. Pfizer represents the global site network model with concurrent multi-phase program execution. Sanofi exemplifies European academic hospital anchoring through deep investigator relationships. Regeneron sits within the supply chain control archetype through biologic manufacturing endpoint stewardship. These three entities illustrate how competitive differentiation in this market derives from operational infrastructure rather than therapeutic modality alone.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi SA |
| Regeneron Pharmaceuticals, Inc. |
| AbbVie Inc. |
| Novartis International AG |
| Eli Lilly and Company |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| LEO Pharma A/S |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract research organizations have consolidated site networks across the United States and Western Europe, creating pricing discipline through preferred-site exclusivity arrangements while compressing per-patient margins for legacy paper-based competitors. This ownership pattern concentrates supply-side leverage among three to four platform players capable of bundling adaptive trial software with investigator access, directly shaping how sponsors negotiate fee structures across Phase II and Phase III programs.
Pricing Analysis
Capacity additions in Germany and the United Kingdom are reshaping price floors for EASI-trained investigator services, intensifying competition among academic medical centers vying for biologic trial contracts. Three-tier pricing structure across premium, standard, and economy levels separates full-service CRO packages with embedded biomarker laboratories from mid-tier vendors offering modular recruitment support and regional specialists handling single-site management. Pricing pressure stems from EMA-mandated pediatric investigation plans that extend trial timelines without proportional fee increases. Small-molecule sponsors exhibit highest price sensitivity due to compressed R&D budgets, while biopharmaceutical developers with IL-4Rα inhibitor portfolios absorb premium investigator fees without volume negotiation.
Supply Chain Analysis
Freight costs for temperature-controlled biologic distribution have climbed sharply, forcing sponsors to consolidate cold chain logistics around manufacturing hubs in the United States, Germany, and Switzerland. Investigational medicinal product supply draws from active pharmaceutical ingredient producers in India and China, with formulation and fill-finish operations concentrated in FDA- and EMA-qualified facilities near trial recruitment clusters. Single-source vulnerability runs through specialized pediatric dermatology sites in fifteen United States academic medical centers, where principal investigator scarcity creates bidding wars that extend procurement cycles. Distribution runs through centralized depot networks with regional pharmacy hubs maintaining unblinding capabilities for double-blind controlled studies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where sponsor procurement committees now weight patient retention metrics and regulatory inspection history above per-patient cost minimization, reflecting demand-shift toward premium trial execution standards with embedded adaptive design capabilities.
For Market Incumbents: To counter adaptive platform vendors capturing recurring subscription revenue, global CROs must deepen investigator exclusivity arrangements with European academic hospitals and deploy proprietary electronic clinical outcome assessment systems across dermatology networks. Backward integration into biomarker stratification laboratories offers margin defense against mid-tier competitors lacking IL-4Rα pathway expertise. For New Entrants and Emerging Players: Tele-dermatology platforms represent the most penetrable white-space channel, enabling home-based SCORAD assessments that unlock rural patient pools outside traditional academic site networks. Targeting Japan and Australia with decentralized trial infrastructure sidesteps principal investigator scarcity in United States pediatric centers while leveraging PMDA and TGA regulatory alignment for multi-regional study participation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier CROs with dermatology site networks but lacking adaptive software platforms, presenting consolidation targets for private equity seeking to assemble full-service capabilities. Long-term viability hinges on five-to-ten-year regulatory trajectory for JAK inhibitor safety frameworks and pediatric mandate expansion under FDA and EMA pediatric investigation plans. Watch for EMA pediatric investigation plan volume commitments as inflection signal for contracted revenue visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Platform Deployment | CROs capture recurring SaaS revenue from sponsors seeking protocol flexibility under FDA dermatology guidance. |
| Pediatric Investigation Plan Execution | EU Paediatric Regulation mandates create guaranteed trial volumes for sponsors with juvenile patient networks. |
| Biomarker Stratification Laboratory Investment | IL-4Rα pathway expertise accelerates patient selection and compresses regulatory approval timelines. |
| Tele-Dermatology Platform Integration | METI-funded decentralized infrastructure in Japan enables home-based outcome assessment beyond urban academic centers. |
| European Academic Hospital Network Consolidation | REACH and RoHS compliance burdens favor scaled operators with EMA-qualified manufacturing footprints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads at major sponsors, principal investigators at United States academic medical centers, and formulary directors at European payer organizations with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up trial volume estimates triangulated against top-down sponsor R&D expenditure allocations across therapeutic modality segments.
Segment-weighting approaches modeled therapy area, study phase, patient type, and trial design dimensions across the analysis window, with CAGRs derived from sponsor pipeline disclosures and CRO contract announcement tracking. Forecast inputs incorporated EMA pediatric investigation plan mandate schedules, FDA dermatology guidance evolution, and adaptive trial design software adoption curves among mid-tier CROs competing against legacy paper-based service providers.
Regulatory timeline delays, JAK inhibitor safety framework revisions, and pediatric recruitment pool access constraints are the dominant revision risks that could alter sponsor site selection patterns and per-patient cost assumptions. Stakeholders should weight assumptions against their own operating context and pipeline exposure to biologic versus small-molecule development portfolios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Synthetic Clinical Trial Data Market
Clinical Research
Clinical Trial Management Services Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
Esource and Clinical Trials Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
AI in Clinical Trials Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market
Clinical Research
Global in Silico Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
India CRO Market
Clinical Research
Global Virtual Clinical Trials Market
Clinical Research
Ecoa, Esource & Clinical Trials Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Clinical Trials Site Management Organizations Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market