
 Global Healthcare Wipes Market | 2026-2036
Global Healthcare Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Wipes Market Foresight
Multi-source procurement for nonwoven substrates is broadening as manufacturers reduce reliance on single fiber suppliers. Kimberly-Clark Corporation anchors North American production through integrated pulp-to-wipe operations. Essity AB leverages European sustainability certifications to differentiate its hospital-grade offerings. Procter and Gamble competes on consumer-to-professional channel crossover, extending brand equity into clinical settings.
Healthcare wipes are nonwoven fabric substrates impregnated with antimicrobial, antiseptic, or detergent solutions, typically composed of spunlace viscose-polyester blends at 40-80 gsm basis weight, manufactured through hydroentanglement and validated for bioburden control. Their primary purpose is to reduce nosocomial infection risk while replacing reusable linens in acute care environments. Antiseptic wipes and disinfectant wipes command the largest revenue pools, reflecting perioperative protocol standardization across OECD health systems. Surface cleaning wipes represent the fastest-growing application segment as outpatient facilities adopt terminal disinfection routines previously confined to inpatient wards.
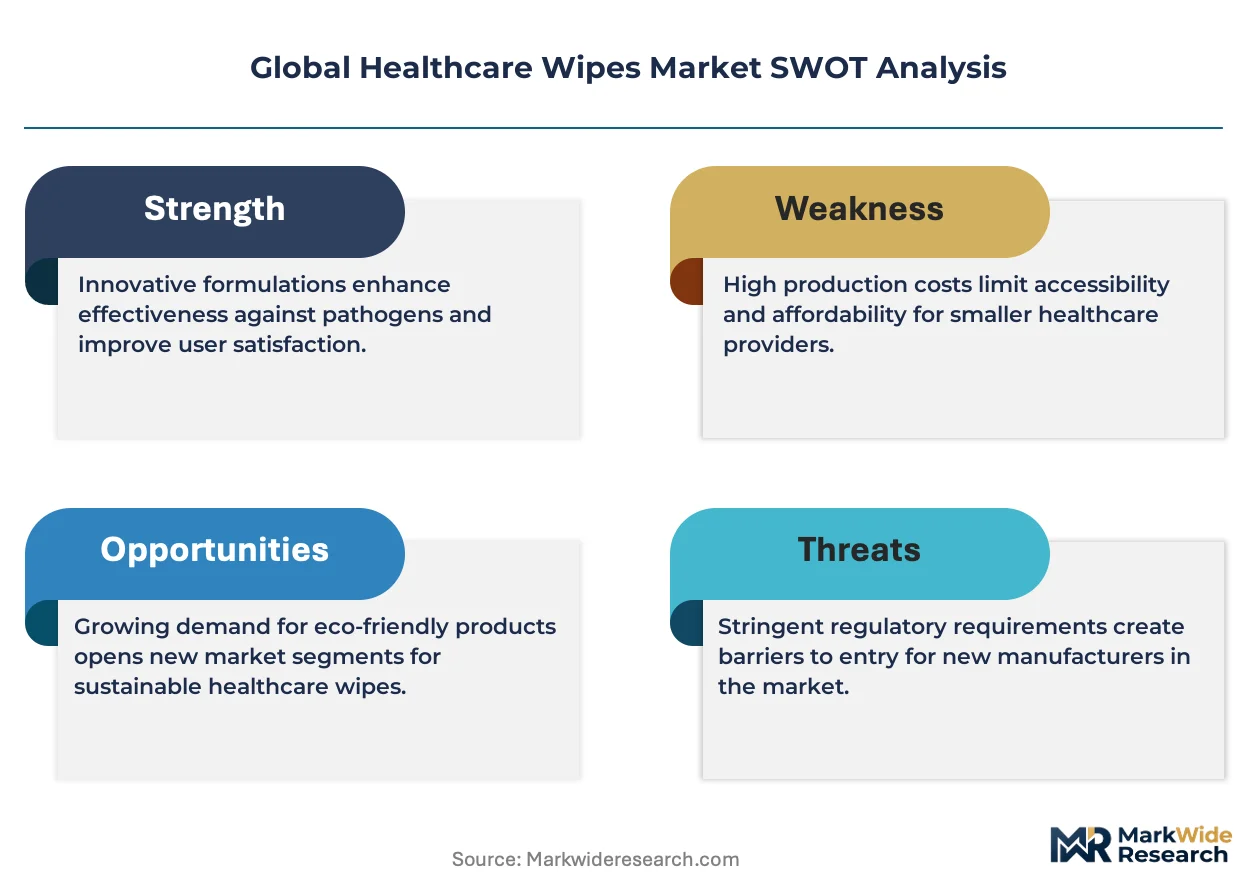
The EPA regulates disinfectant wipe efficacy claims through List N designation requirements, while the FDA oversees antiseptic wipe monograph compliance under 21 CFR 333, and ISO 13485 certification governs sterile wipe quality management systems for surgical instrument applications. These frameworks elevate barrier costs for new entrants and reward incumbent documentation capabilities. Stakeholders must monitor evolving EPA active ingredient restrictions and EU MDR spillover effects on wipe classification as medical devices.
Market Dynamics
The EPA's tightening List N designation requirements for disinfectant efficacy claims are compressing formulation flexibility while elevating documentation burdens across North American supply chains.
Growth Catalysts
- Preoperative Protocol Standardization:OECD health systems mandate antiseptic wipe use for surgical site preparation, embedding consumption into reimbursement frameworks.
- ISO 13485 Certification Expansion:Sterile wipe quality management systems are becoming mandatory for surgical instrument applications, creating captive demand for validated manufacturers.
- Outpatient Terminal Disinfection:Ambulatory surgical centers in the United States and Germany adopt inpatient-grade surface cleaning protocols previously confined to hospital wards.
Market Restraints
- Viscose-Polyester Input Volatility:Spunlace nonwoven substrate costs fluctuate with pulp and petrochemical feedstock pricing, compressing blended margins for mid-tier producers.
- Active Ingredient Concentration Risk:EPA restrictions on quaternary ammonium compounds and bleach alternatives limit formulation options for disinfectant wipe manufacturers.
- Single-Use Plastic Substitution Pressure:EU Green Deal spillover effects and state-level bag bans in California and New York threaten conventional wipe packaging formats.
Strategic Opportunities
- Japanese Elder Care Facility Penetration:Aging demographics and METI infection control guidelines create unmet demand for antiseptic wipes in long-term care settings outside acute hospitals.
- Biodegradable Substrate Convergence:Lenzing's Tencel and Bacterial Cellulose integration with existing hydroentanglement lines enables premium positioning for sustainability-credentialed buyers.
- EU MDR Medical Device Reclassification:Wipes with therapeutic claims face stricter conformity assessment, rewarding early movers with notified body relationships and technical file capabilities.
Industry Challenges
- Formulation Chemist Scarcity:The intersection of antimicrobial efficacy testing, EPA registration timelines, and biocompatibility validation requires specialized talent pools concentrated at incumbent competitors.
- Dual Certification Timeline Compression:Simultaneous FDA antiseptic monograph compliance and EPA List N designation extend product launch cycles by 18-24 months.
- Legacy Linen Contract Integration:Hospital purchasing departments resist unbundling reusable textile services from wipe-based disposable protocols, requiring change management investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Wipes Market |
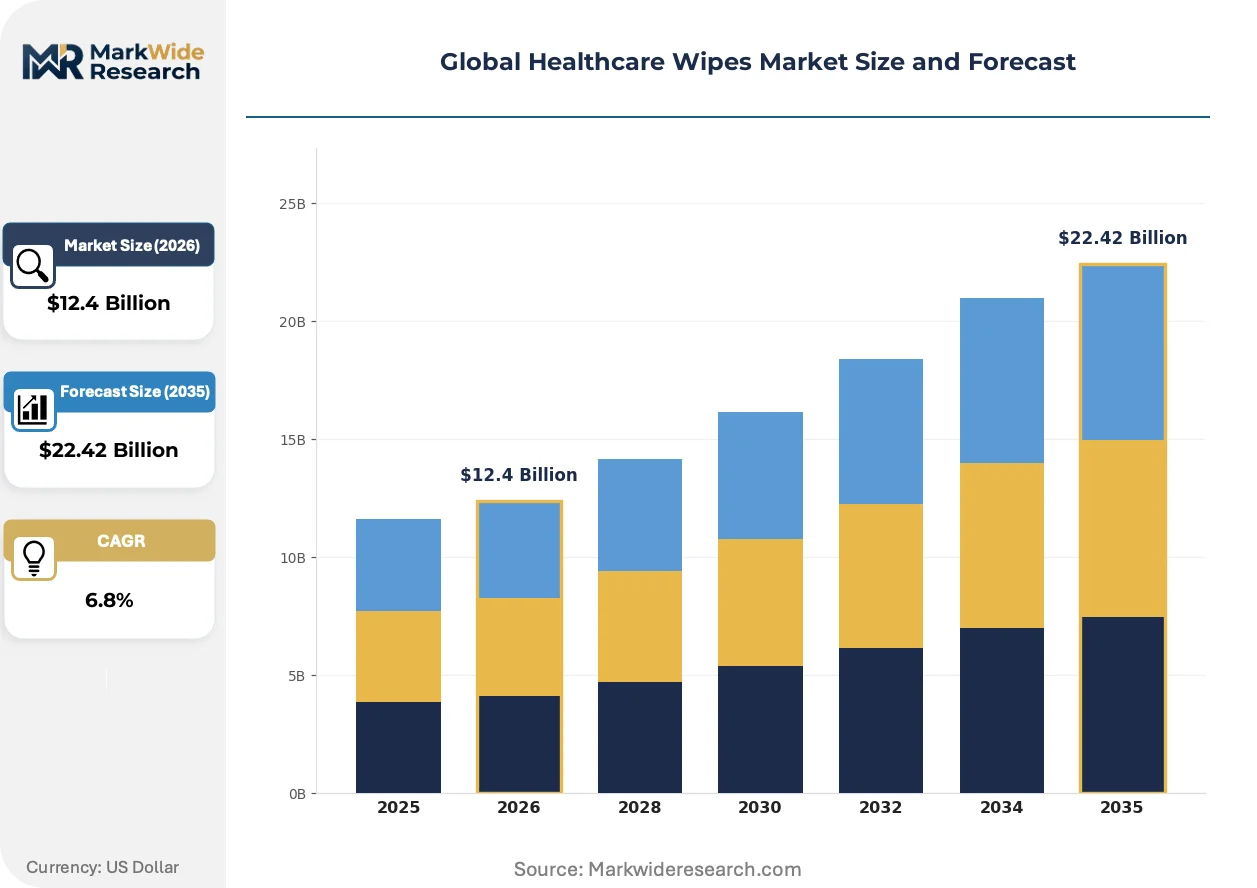
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptic Wipes, Disinfectant Wipes, Baby Care Wipes, Surface Cleaning Wipes, Sterile Wipes Application: Preoperative Cleaning, Patient Care, Medical Device Cleaning, Surgical Instrument Sterilization, Hygiene Maintenance End User: Hospitals, Diagnostic Centers, Outpatient Facilities, Home Healthcare, Ambulatory Surgical Centers Packaging Type: Foil Packs, Refillable Containers, Individually Wrapped, Tubes, Canisters |
| Companies Covered | Essity AB, The Clorox Company, Procter and Gamble, Unilever PLC, Reckitt Benckiser Group PLC, Kimberly-Clark Corporation, Diamond Wipes International, Inc., Ecolab, Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Wipes Market Shifts & Advancements
Active ingredient disclosure mandates and substrate sustainability pressures are converging to reshape product architecture, manufacturing investment, and channel access requirements across the value chain.
Bamboo-derived viscose is expanding into spunlace nonwoven production for healthcare wipe substrates. German hospital procurement coalitions specify minimum renewable content thresholds in tender documents. This fiber transition is expanding into premium product tiers as manufacturers seek differentiation against petroleum-based polyester blends.
REACH authorization requirements for biocidal active substances are forcing reformulation of European-market disinfectant wipes ahead of 2025 compliance deadlines. The ECHA review of quaternary ammonium compound safety profiles elevates phenolic alternative development. Hospital-grade wipe producers with existing PT1-PT4 biocidal product authorizations capture shelf space as competitors exit.
Consolidated purchasing by United States hospital networks compresses supplier rosters to vendors with documented EPA registration, ISO 13485 certification, and GPO contract eligibility. Independent distributors lose access to integrated delivery networks as procurement centralizes. This concentration is most visible in the southeastern United States where HCA and Tenet facility clusters dominate acute care capacity.
Global Healthcare Wipes Market Segmentation
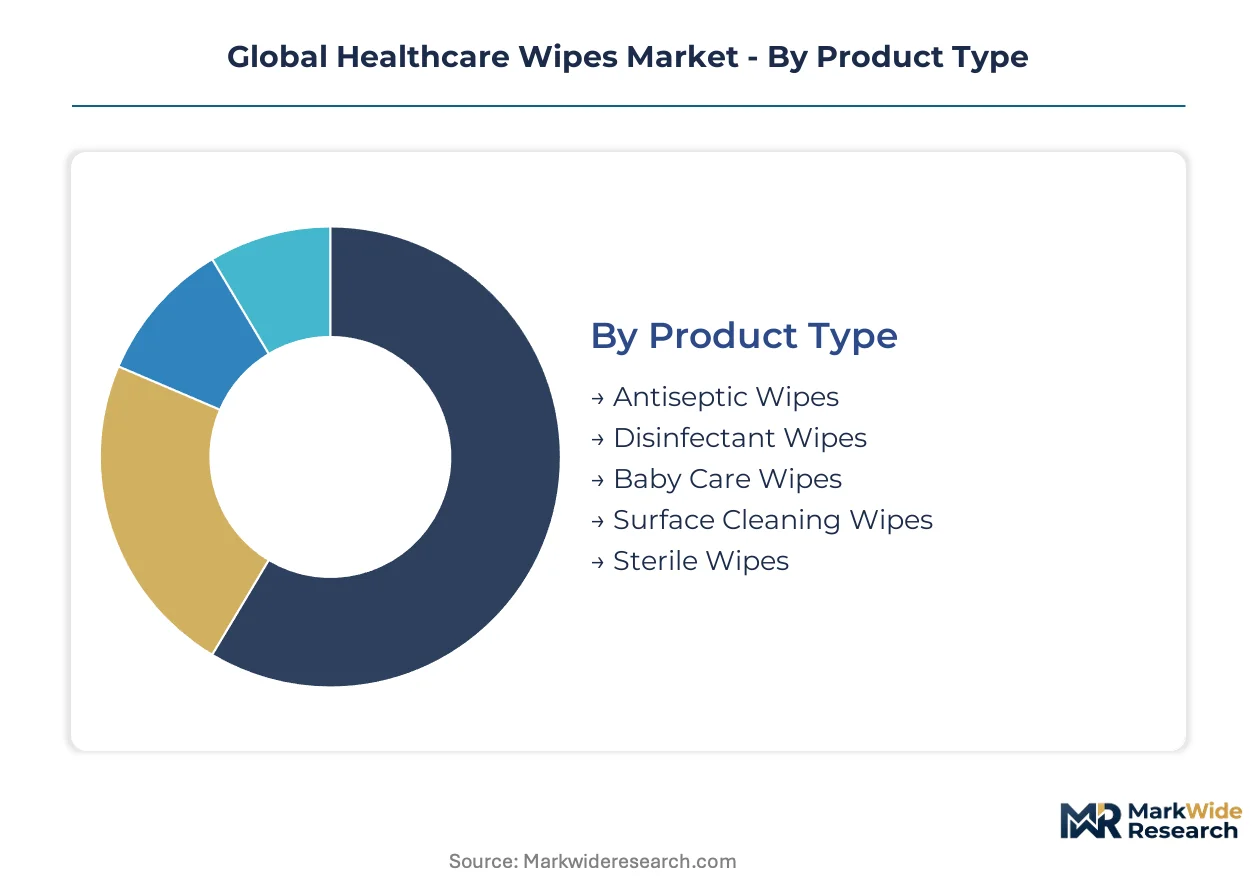
Healthcare wipes segmentation reflects divergent certification burdens across use cases. Product type determines whether EPA List N designation, FDA antiseptic monograph compliance, or ISO 13485 certification applies. Application context further stratifies procurement channels and reimbursement eligibility.
Product Type:
Antiseptic wipes require FDA 21 CFR 333 monograph adherence. Disinfectant wipes face EPA List N efficacy documentation. Sterile wipes demand ISO 13485 quality management systems for surgical instrument applications.
- Antiseptic Wipes:Spunlace viscose-polyester substrates impregnated with chlorhexidine or alcohol solutions at 40-60 gsm. Surgical site preparation protocols in United States and German hospitals embed consumption into bundled reimbursement, creating captive demand for validated suppliers.
- Disinfectant Wipes:Quaternary ammonium or bleach-based formulations on 50-80 gsm nonwoven substrates for surface decontamination. Outpatient facilities in Japan and the United States adopt terminal disinfection routines, expanding addressable volume beyond acute care wards.
- Baby Care Wipes:Gentle detergent formulations for neonatal skin cleansing in maternity wards.
- Surface Cleaning Wipes:Detergent-based substrates for general environmental hygiene without antimicrobial claims.
- Sterile Wipes:Gamma-irradiated or ethylene oxide-sterilized products for surgical instrument preparation.
Leading the category by volume: Disinfectant Wipes. Expanding most quickly: Antiseptic Wipes.
Application:
Preoperative cleaning commands premium pricing through reimbursement integration. Patient care applications compete on cost per use against reusable textile alternatives.
- Preoperative Cleaning:Surgical site preparation with antiseptic wipes before incision. United States hospital networks mandate standardized protocols, embedding consumption into quality metrics and infection rate reporting.
- Patient Care:Perineal cleansing, bathing, and general hygiene for bedbound patients. German and Japanese long-term care facilities drive substitution of washcloths with disposable alternatives.
- Medical Device Cleaning:Non-sterile wipes for equipment surface decontamination between uses.
- Surgical Instrument Sterilization:Sterile wipes for final preparation before autoclave or immediate use.
- Hygiene Maintenance:Routine environmental and hand hygiene in non-critical care zones.
Dominant by procurement value: Preoperative Cleaning. Gaining share fastest: Patient Care.
End User:
Hospital procurement centralization favors vendors with GPO contracts and multi-certification portfolios. Home healthcare channels prioritize retail accessibility over clinical documentation.
- Hospitals:Integrated delivery networks in the southeastern United States consolidate purchasing through HCA and Tenet supply agreements. ISO 13485 certification and EPA registration are mandatory for vendor qualification.
- Outpatient Facilities:Ambulatory surgical centers in Germany and the United States adopt inpatient-grade protocols. METI guidelines in Japan extend infection control standards to clinic settings.
- Diagnostic Centers:Imaging and laboratory environments requiring surface disinfection between patients.
- Home Healthcare:Post-acute and palliative care settings with caregiver-administered protocols.
- Ambulatory Surgical Centers:Same-day procedure facilities with compressed turnaround requirements.
Concentrating procurement spend: Hospitals. Expanding addressable base: Outpatient Facilities.
Packaging Type:
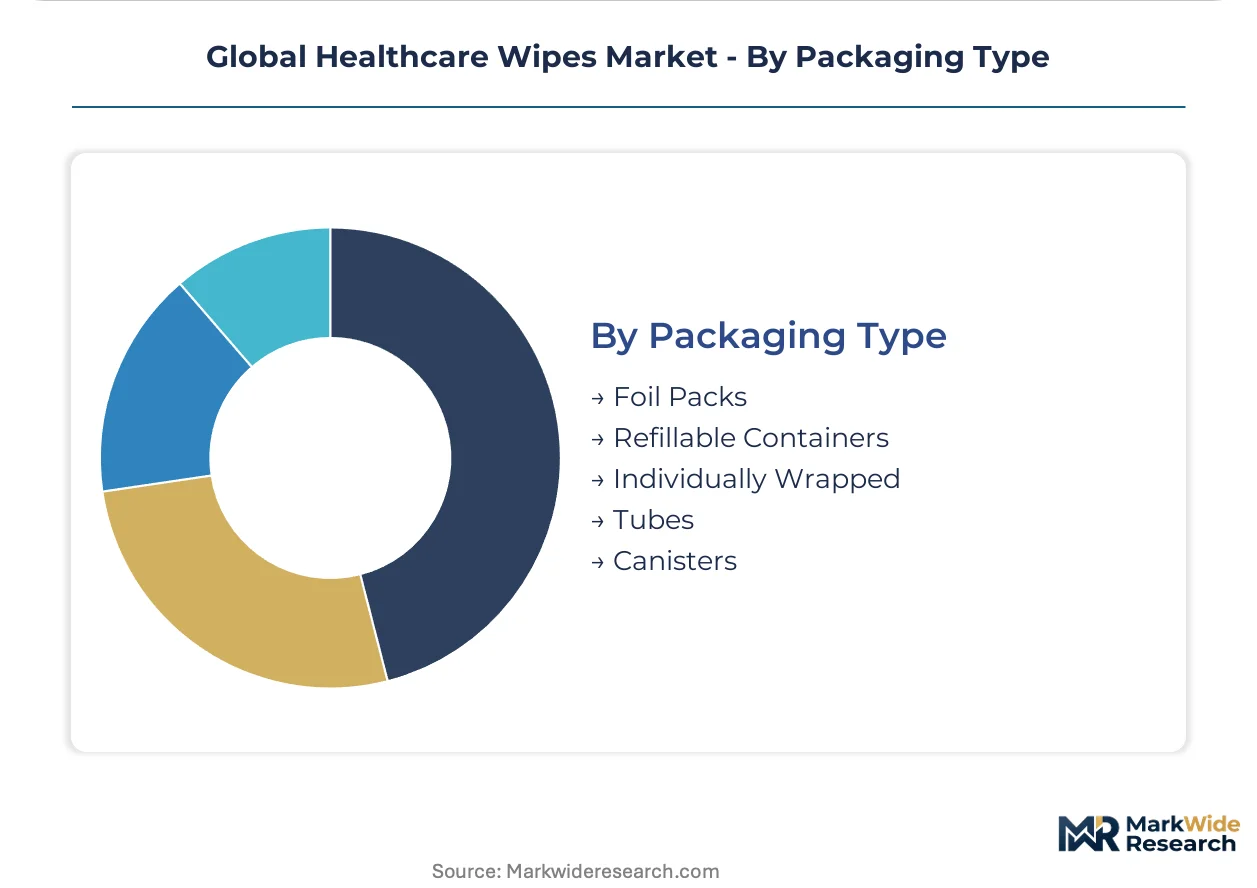
Packaging format determines shelf stability, dispensing ergonomics, and compliance with single-use plastic regulations. EU Green Deal spillover pressures conventional formats.
- Individually Wrapped:Single-unit foil or polymer pouches ensuring sterility and portability. Surgical kits and emergency medical services in the United States and Japan specify unit-dose formats for contamination control.
- Canisters:Rigid plastic containers with dispensing lids for high-frequency surface cleaning. California and New York state regulations threaten conventional formats, accelerating biodegradable substrate and recyclable packaging development.
- Foil Packs:Multi-count flexible pouches for institutional bulk purchasing.
- Refillable Containers:Hard-shell dispensers with replaceable wipe cartridges to reduce plastic waste.
- Tubes:Flexible packaging for compact storage and controlled dispensing.
Highest institutional volume: Canisters. Steepest expansion trajectory: Individually Wrapped.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan as these markets enforce stringent healthcare hygiene standards. OECD health systems mandate antiseptic wipe use for surgical site preparation, embedding consumption into reimbursement frameworks. Regulatory divergence across geographies creates distinct compliance architectures for multinational suppliers.
United States
Hospital networks in the southeastern United States consolidate purchasing through HCA and Tenet supply agreements. The EPA regulates disinfectant wipe efficacy claims through List N designation requirements. Greater Boston anchors sterile wipe quality management systems for surgical instrument applications, with ISO 13485 certification serving as mandatory vendor qualification criteria.
Germany
Hospital procurement coalitions specify minimum renewable content thresholds in tender documents. REACH authorization requirements for biocidal active substances force reformulation of disinfectant wipes ahead of compliance deadlines. Bavaria exemplifies premium positioning for sustainability-credentialed buyers through bamboo-derived viscose integration into spunlace nonwoven production.
Japan
Aging demographics and METI infection control guidelines create unmet demand for antiseptic wipes in long-term care settings outside acute hospitals. The country's national pharmaceutical regulator oversees antiseptic wipe monograph compliance. Kanto region procurement centralization favors vendors with documented EPA registration equivalents and multi-certification portfolios.
United Kingdom
Ambulatory surgical centers adopt inpatient-grade surface cleaning protocols previously confined to hospital wards. EU MDR spillover effects influence wipe classification as medical devices with therapeutic claims. London-Southeast hospital clusters drive substitution of washcloths with disposable alternatives in perineal cleansing applications.
India
Post-acute and palliative care settings expand addressable volume beyond acute care wards. The country's national pharmaceutical regulator and BIS standards govern product quality. Maharashtra-based distributors lose access to integrated delivery networks as procurement centralizes toward GPO contract eligibility requirements.
Global Healthcare Wipes Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reduce reliance on single fiber suppliers. The vendor base stratifies across three tiers: integrated pulp-to-wipe operators with captive substrate supply, sustainability-certified specialists leveraging European certifications, and consumer-to-professional crossover brands extending retail equity into clinical channels. Strategic archetypes include backward-integrated substrate controllers, premium sustainability differentiators, and volume-scale consumer hybrids. M&A activity and geographic expansion represent the dominant competitive moves as firms secure multi-region EPA and FDA registration portfolios.
Among North American integrated operators, Kimberly-Clark Corporation anchors production through pulp-to-wipe operations. Essity AB exemplifies the European sustainability-certified tier, while Procter and Gamble occupies the consumer-to-professional crossover position. These three entities represent distinct strategic archetypes: captive supply chain control, renewable content premium positioning, and brand equity migration from retail shelves into hospital procurement systems.
| Leading Market Players |
|---|
| Essity AB |
| The Clorox Company |
| Procter and Gamble |
| Unilever PLC |
| Reckitt Benckiser Group PLC |
| Kimberly-Clark Corporation |
| Diamond Wipes International, Inc. |
| Ecolab |
| Johnson & Johnson Services, Inc. |
| Others |
Supply & Pricing Matrix
Captive pulp-to-wipe integration anchors both supply security and pricing power for North American producers, while European sustainability mandates force substrate diversification that compresses mid-tier margins. This structural divergence between integrated operators and fiber-dependent competitors concentrates pricing leverage with backward-integrated manufacturers who control viscose-polyester blend costs.
Pricing Analysis
Warranty-backed EPA registration and ISO 13485 certification bundling separate premium-tier suppliers from unvalidated competitors in hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects documentation depth, with GPO-contracted incumbents commanding 15-20% premiums over independent distributors. Cost compression in standard tiers is intensifying because viscose-polyester input volatility squeezes converters without captive fiber supply. Ambulatory surgical centers exhibit highest price sensitivity as they lack bundled reimbursement integration.
Supply Chain Analysis
Domestic-content thresholds in German hospital procurement coalitions and proposed EU Green Deal local sourcing rules are reshaping substrate sourcing toward European viscose producers. Manufacturing concentrates in the United States, Germany, and China, with spunlace nonwoven production drawing from pulp, petrochemical, and regenerated cellulose feedstocks. Single-source vulnerability in quaternary ammonium compound supply threatens disinfectant wipe formulation continuity. Distribution runs through GPO-integrated delivery networks and specialized medical distributors serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Healthcare Wipes Market operates as a cost-of-compliance arena where EPA List N designation and FDA antiseptic monograph requirements erect documentation barriers that reward incumbent investment in regulatory infrastructure.
For Market Incumbents: Hedge formulation exposure by diversifying active ingredient portfolios ahead of EPA quaternary ammonium restrictions, while securing bamboo-derived viscose supply agreements to meet German renewable content mandates. Capacity expansion in the southeastern United States captures HCA and Tenet procurement concentration. Certification depth serves as the priority defensive lever against private-label erosion.
For New Entrants and Emerging Players: Direct-to-clinic digital platforms bypass GPO entry barriers for outpatient surgical centers in Japan and Germany seeking alternative suppliers. Japanese elder care facilities represent the most penetrable white-space target given METI guideline expansion and limited incumbent focus. Specialist positioning in biodegradable substrates enables premium pricing before scale players reorient.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to consumer health conglomerates seeking clinical channel access, with IPO viability tethered to multi-region EPA-FDA registration completion. Acquisition targets should display ISO 13485 certification, GPO contract eligibility, and established notified body relationships for EU MDR navigation. Watch EPA active ingredient restriction timelines as inflection signals for formulation-dependent valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| EPA List N Registration Expansion | Multi-state efficacy documentation unlocks integrated delivery network procurement access. |
| ISO 13485 Certification Investment | Quality management validation becomes mandatory for surgical instrument wipe suppliers. |
| Biodegradable Substrate Integration | Tencel and bacterial cellulose conversion enables EU Green Deal compliance positioning. |
| GPO Contract Eligibility Pursuit | Hospital procurement centralization in the United States favors contracted vendor rosters. |
| Japanese Elder Care Channel Development | METI infection control guidelines create unmet demand outside acute hospital settings. |
Research Methodology
Independent corroboration across hospital procurement managers, GPO contracts specialists, formulation chemists, and nonwoven substrate manufacturers underwrites the qualitative findings in this study. Primary interviews with biomedical engineers and EPA registration consultants combined with secondary validation from FDA 510(k) filings, EPA List N databases, hospital procurement records, and spunlace nonwoven trade data established demand and supply parameters. Bottom-up patient protocol volume estimates and top-down healthcare expenditure allocation triangulate market sizing.
Rate-of-change decomposition across product type, application context, end-user channel, and certification tier generates segment-level growth trajectories over the projection horizon. CAGRs derive from protocol penetration modeling, reimbursement framework evolution, and regulatory compliance timeline analysis. Forecast inputs incorporate EPA registration backlog durations, EU MDR reclassification uncertainty, and viscose-polyester feedstock price elasticity assumptions.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time antiseptic wipe consumption telemetry introduce uncertainty bands around outpatient facility estimates. Forecasts reflect documented assumptions regarding regulatory timeline adherence and fiber substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Europe Functional Cosmetics Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Skin Care Supplements Market
Skincare
Self-Tanning Care Market
Skincare
Medicine Skin Care Market
Skincare
Dermal Regeneration Market
Skincare
Global Physician Dispensed Cosmeceuticals Market
Skincare
Skin Bioactive Market
Skincare
Peel Off Face Mask Market
Skincare
Incontinence Skin Care Products Market
Skincare
Exfoliators and Scrubs Market
Skincare
Asia-Pacific Cosmeceutical Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Skincare Ingredients Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Moisturizing Cream Market