
 Antimicrobial Wipes Market | 2026-2036
Antimicrobial Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Wipes Market Analysis
The antimicrobial wipes market is shifting between premium clinical-grade formulations and commodity household tiers. Procter & Gamble leverages its retail distribution network to dominate mass-market channels. Kimberly-Clark specializes in healthcare-specific portfolios that sustain higher margin positions. Ecolab anchors its competitive stance through institutional supply contracts with hospital networks.
Antimicrobial wipes are non-woven substrates impregnated with biocidal agents such as quaternary ammonium compounds, alcohol blends, or hydrogen peroxide solutions, engineered to reduce microbial load on surfaces and skin within specified contact times. Disposable product types lead volume due to infection control protocols, while spunlace material segments capture expanding share from cotton alternatives driven by fiber strength and liquid retention requirements. Healthcare facilities represent the most concentrated end-user margin pool, whereas food service applications show accelerated regulatory-driven replacement of reusable cloth systems.
EPA registration requirements govern surface disinfectant claims in the United States, while the EU Biocidal Products Regulation (BPR) mandates active substance approval across European member states. FDA oversight applies to antimicrobial wipes classified as medical devices or skin antiseptics, creating compliance thresholds that filter commodity entrants. Stakeholders must monitor evolving state-level chemical disclosure laws and hospital procurement standards that increasingly specify validated kill-log documentation against multidrug-resistant organisms.
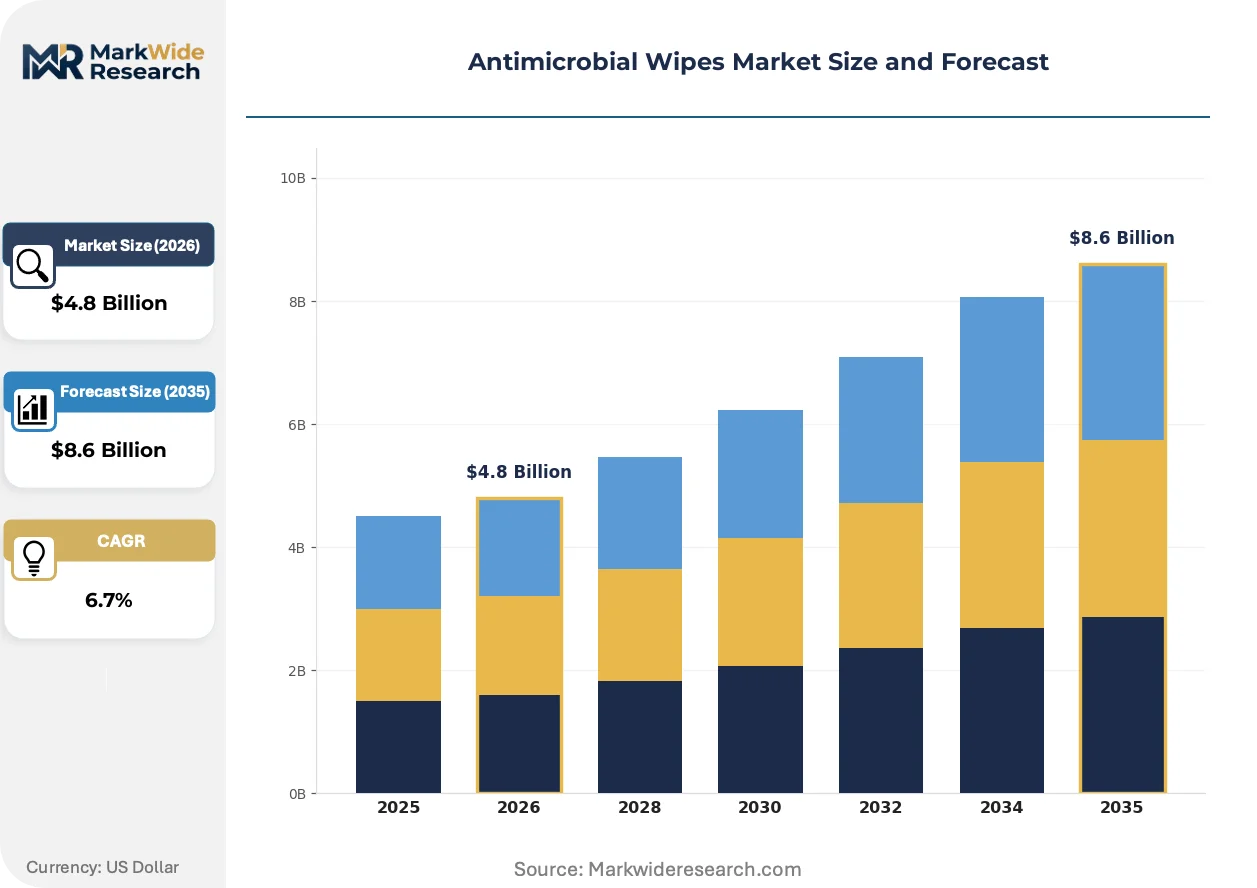
Market Dynamics
Hospital infection control protocols are forcing rapid substitution of reusable cleaning systems with single-use disinfectant wipes, compressing procurement cycles and elevating kill-log documentation requirements above price sensitivity in institutional purchasing.
Growth Catalysts
- EPA-registered quaternary ammonium formulations:Healthcare facilities in the United States now mandate EPA-validated surface disinfectants for Joint Commission accreditation, eliminating non-compliant suppliers from hospital procurement lists.
- Food service regulatory mandates:FDA Food Code updates require commercial kitchens to replace reusable cloths with single-use sanitizing wipes for food-contact surface compliance, opening institutional volume channels.
- Spunlace non-woven material substitution:Spunlace manufacturing lines in Germany and Italy are displacing cotton-based substrates due to superior liquid retention and fiber strength under saturated biocidal loading.
Market Restraints
- Isopropyl alcohol feedstock volatility:Antimicrobial wipes depend on petrochemical-derived alcohol blends, exposing margin structures to crude oil price swings and refinery capacity constraints.
- EU Biocidal Products Regulation active substance review:ECHA's ongoing reassessment of quaternary ammonium compounds creates registration uncertainty, delaying new product launches and reformulation investments.
- Electrostatic sprayer systems:Fogging and electrostatic application technologies offer surface coverage advantages over manual wipe protocols in large-scale disinfection contracts.
Strategic Opportunities
- India pharmaceutical manufacturing corridors:CDSCO-aligned cleanroom standards in Hyderabad and Bangalore are mandating validated surface disinfection protocols, creating demand for imported clinical-grade wipe formulations.
- Sustainable substrate innovation:Cellulose-based biodegradable non-wovens combined with peracetic acid biocides address EU Single-Use Plastics Directive pressure without sacrificing kill efficacy.
- Direct-to-facility e-procurement platforms:Amazon Business and specialized healthcare supply marketplaces are disintermediating traditional distributor networks for mid-size clinic and dental practice segments.
Industry Challenges
- Microbiological validation laboratory capacity:EPA and FDA require time-kill studies against specific pathogen panels, and qualified third-party testing facilities face 12-18 month backlogs for new product submissions.
- Legacy equipment incompatibility:Automated wipe dispensing systems in older hospital infrastructure require retrofitting to accommodate larger-format or pre-saturated wipe formats, slowing facility-wide rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Wipes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Antibacterial, Sterilizing End User: Healthcare Facilities, Households, Food Service, Industrial Material: Non-woven Fabric, Spunlace, Cotton, Plastic Packaging Type: Flip-top Packs, Wipes Canisters, Sachets, Tubes |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Reckitt Benckiser Group plc, The Clorox Company, 3M, Johnson & Johnson, Ecolab, Edgewell Personal Care, Nice-Pak Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Wipes Market Emerging Trajectories
Biocidal chemistry and substrate engineering are converging to extend contact time efficacy while reducing environmental persistence, reshaping how manufacturers differentiate formulations beyond basic EPA registration claims.
Peracetic acid-hydrogen peroxide blended formulations are expanding into surgical suite and pharmaceutical cleanroom applications previously dominated by quaternary ammonium compounds. Spunlace substrate producers in Italy report 40% capacity allocation shifts toward these high-performance segments. The technology is expanding into premium pricing tiers where validated sporicidal claims command 3x commodity wipe margins.
ECHA's 2024 update to the EU Biocidal Products Regulation reclassification timeline is compressing active substance approval windows for legacy quaternary ammonium compounds. German and French formulators are accelerating peracetic acid and alcohol-based alternative registrations to maintain market access. Healthcare procurement consortia in the Netherlands and Belgium are now specifying BPR-compliant documentation as a mandatory bid qualification.
Hospital supply chain managers are consolidating vendor relationships from 15-20 suppliers to 3-5 strategic partners with validated manufacturing and quality systems. Group purchasing organizations in the United States are embedding kill-log documentation requirements into master service agreements, displacing spot-buy commodity purchasing. This consolidation is most visible in integrated delivery networks across Texas and Florida, where standardization mandates now cover 80% of affiliated facilities.
Antimicrobial Wipes Market Segmentation
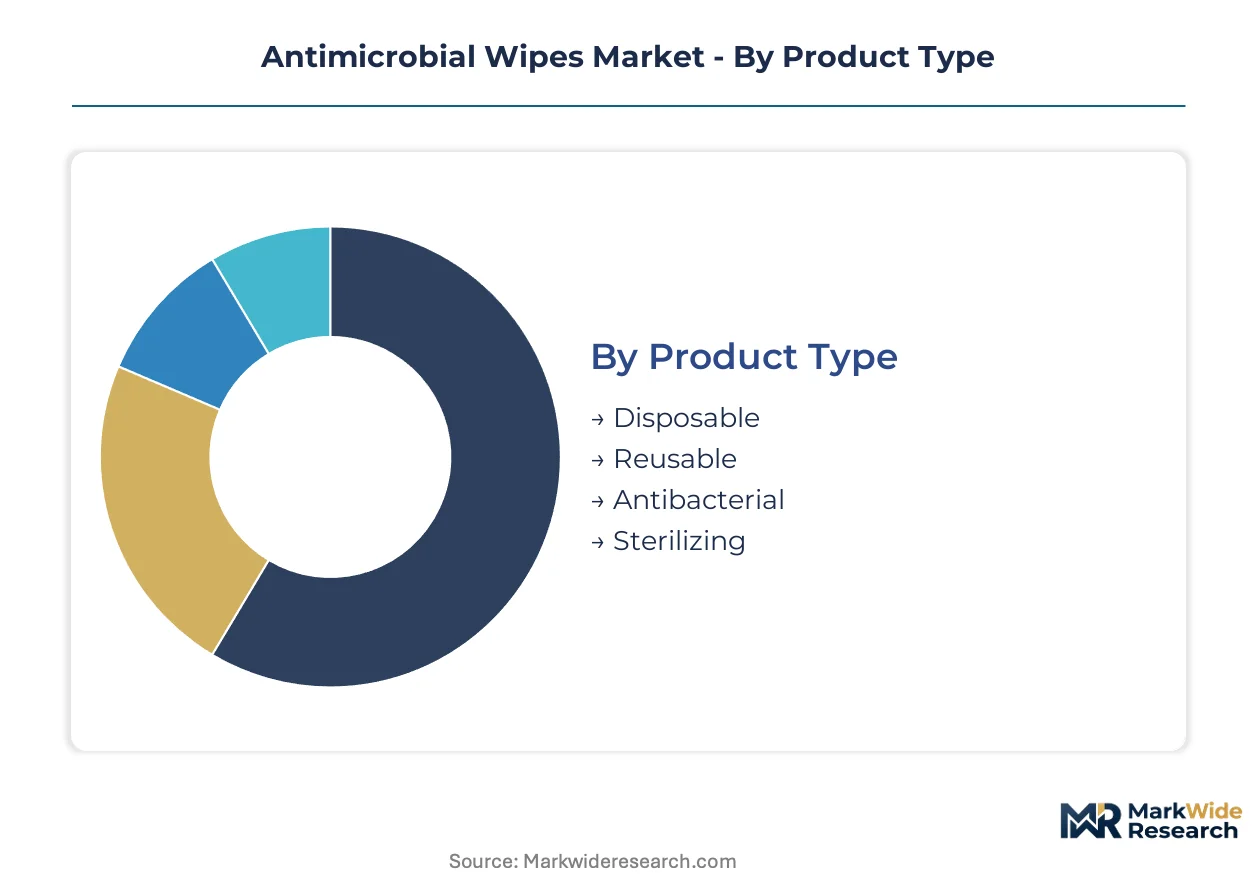
Antimicrobial wipe manufacturers configure production assets around substrate chemistry, packaging automation, and end-use compliance tiers. Segmentation discipline separates commodity household volumes from premium clinical-grade margins where EPA registration and kill-log documentation create defensible pricing power.
Product Type:
Capital intensity peaks in pre-saturated disposable lines requiring automated filling, biocidal stability testing chambers, and EPA-compliant validation infrastructure. Reusable systems demand lower upfront equipment spend but incur higher lifecycle quality assurance costs.
- Disposable:Single-use non-woven substrates pre-saturated with quaternary ammonium compounds or alcohol blends dominate hospital procurement under Joint Commission infection control mandates. United States healthcare facilities now specify disposable formats for 90% of surface disinfection protocols, compressing reusable alternatives to niche maintenance applications.
- Antibacterial:Consumer-grade formulations targeting staphylococcal and salmonella reduction command mass-market shelf space through retail distribution networks. German and Italian spunlace producers supply substrate rolls to private-label converters serving European supermarket chains where price-per-wipe sensitivity constrains premium positioning.
- Reusable:Launderable microfiber systems persist in industrial maintenance and food service equipment cleaning where surface abrasion requirements exceed disposable material durability.
- Sterilizing:Sporicidal-grade wipes validated against C. difficile and Bacillus spores serve surgical suites and pharmaceutical cleanrooms under FDA device regulations.
Most installed capacity flows through Disposable. Expansion is steepest in Sterilizing.
End User:
Customer concentration determines contract structure — healthcare procurement consortia negotiate multi-year master service agreements while household channels rely on trade promotion and retail slotting fees.
- Healthcare Facilities:United States hospital systems and integrated delivery networks in Texas and Florida mandate EPA-registered surface disinfectants with validated kill-log documentation against multidrug-resistant organisms. Group purchasing organizations embed compliance requirements into strategic vendor agreements covering 80% of affiliated facilities.
- Food Service:FDA Food Code updates require commercial kitchens to replace reusable cloths with single-use sanitizing wipes for food-contact surface compliance, opening institutional volume channels previously served by chemical spray-and-wipe protocols.
- Households:Mass-market retail placement in United States drugstore and grocery channels depends on seasonal promotion cycles and private-label conversion pressure.
- Industrial:Manufacturing maintenance and cleanroom operations specify substrate durability and chemical compatibility over biocidal spectrum breadth.
Healthcare Facilities concentrate margin capture. Food Service is climbing the fastest.
Material:
Substrate selection governs liquid retention capacity, fiber release during abrasion, and compatibility with active biocidal chemistries.
- Spunlace:Hydroentangled polyester-viscose blends manufactured on German and Italian production lines deliver superior tensile strength under saturated quaternary ammonium loading. European healthcare procurement consortia in the Netherlands and Belgium now specify spunlace documentation as mandatory bid qualification under EU Biocidal Products Regulation alignment.
- Non-woven Fabric:Thermal-bonded polypropylene substrates serve cost-sensitive household and industrial segments where fiber shedding tolerance exceeds clinical hygiene requirements.
- Cotton:Natural fiber alternatives face displacement from cellulose-based biodegradable non-wovens addressing EU Single-Use Plastics Directive pressure.
- Plastic:Synthetic film-based wipes persist in specialized industrial solvent applications where chemical resistance trumps absorbency.
Spunlace commands premium positioning. Cotton faces regulatory headwinds.
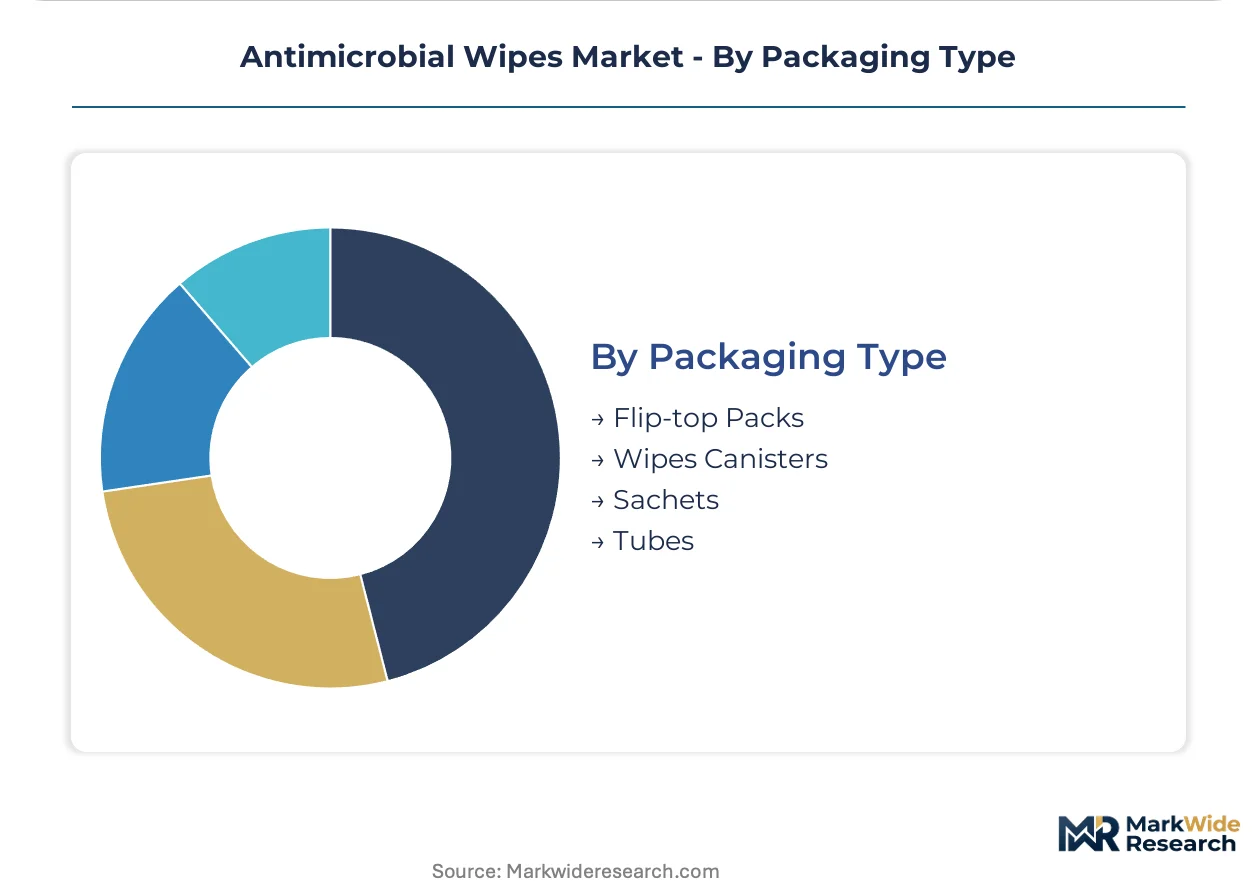
Packaging Type:
Packaging automation investment separates high-volume institutional supply from retail-format flexibility.
- Flip-top Packs:Flexible film pouches with resealable lids dominate United States retail household channels where shelf-ready presentation and portability drive placement decisions.
- Wipes Canisters:Rigid plastic containers with threaded lids serve healthcare and food service institutional contracts requiring moisture retention over extended use cycles and compliance with OSHA workplace safety labeling.
- Sachets:Single-unit foil packets address travel, hospitality, and field service applications where contamination control requires point-of-use opening.
- Tubes:Cylindrical dispensers occupy specialty personal care and veterinary segments with differentiated dispensing mechanics.
Canisters anchor institutional procurement. Flip-top Packs expand through e-commerce fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's spunlace manufacturing lines supply premium healthcare substrates, while the United States concentrates EPA-registered disinfectant demand through hospital procurement networks.
United States
Texas and Florida integrated delivery networks mandate EPA-validated surface disinfectants for Joint Commission accreditation. The EPA registration requirement filters non-compliant suppliers from hospital procurement lists. Spunlace substrate imports from European manufacturers serve cleanroom operations in Boston and San Francisco pharmaceutical corridors.
Germany
German healthcare procurement consortia specify BPR-compliant documentation as mandatory bid qualification. ECHA's ongoing reassessment of quaternary ammonium compounds creates registration uncertainty for formulators. Spunlace production lines in Baden-Württemberg displace cotton-based substrates for superior liquid retention under saturated biocidal loading.
India
CDSCO-aligned cleanroom standards in Hyderabad and Bangalore pharmaceutical manufacturing corridors mandate validated surface disinfection protocols. The country's national pharmaceutical regulator enforces contamination control documentation for active pharmaceutical ingredient facilities. Imported clinical-grade wipe formulations penetrate production facilities in Maharashtra and Gujarat export zones.
Netherlands
Dutch hospital supply chain managers consolidate vendor relationships from 15-20 suppliers to 3-5 strategic partners with validated manufacturing systems. The EU Biocidal Products Regulation reclassification timeline compresses active substance approval windows. Healthcare procurement consortia in Amsterdam and Rotterdam embed kill-log documentation requirements into master service agreements.
Italy
Italian spunlace substrate producers report 40% capacity allocation shifts toward high-performance surgical suite and pharmaceutical cleanroom segments. The EU Single-Use Plastics Directive pressure accelerates cellulose-based biodegradable non-woven development. Manufacturing clusters in Lombardy and Piedmont supply premium substrate rolls to European healthcare formulators.
Antimicrobial Wipes Market Vendor Landscape
Top-tier vendors anchor institutional healthcare contracts, while mid-tier specialists occupy private-label retail channels. The market structure separates EPA-registered clinical-grade formulators from commodity household-tier suppliers. Three archetypes dominate: diversified consumer goods conglomerates with retail distribution networks, healthcare-focused specialists with institutional supply relationships, and private-label converters serving price-sensitive mass-market channels. Competitive moves concentrate on M&A for regulatory asset acquisition and spunlace manufacturing capacity expansion.
Among diversified consumer goods conglomerates, Procter & Gamble and Kimberly-Clark exemplify contrasting strategic positions. Procter & Gamble represents the retail-distribution archetype with mass-market channel dominance through drugstore and grocery placement. Kimberly-Clark occupies the healthcare-specialist position with institutional supply contracts sustaining higher margin positions. Both companies sit within the top-tier vendor category where regulatory compliance infrastructure creates defensible pricing power against commodity entrants.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark |
| Reckitt Benckiser Group plc |
| The Clorox Company |
| 3M |
| Johnson & Johnson |
| Ecolab |
| Edgewell Personal Care |
| Nice-Pak Products |
| Others |
Supply Flow & Price Mechanics
Joint Commission accreditation mandates for EPA-registered surface disinfectants are compressing hospital procurement cycles and forcing supply chain reconfiguration toward validated manufacturing partners with kill-log documentation infrastructure, elevating price floors for compliant suppliers while squeezing commodity converters from institutional channels.
Pricing Analysis
Capacity additions in Germany and Italy are reshaping price floors for spunlace substrates used in clinical-grade formulations. Pricing stratifies across premium sterilizing tiers with sporicidal validation, standard EPA-registered hospital grades, and economy household segments without regulatory claims. Price differentiation rests on kill-log documentation depth and substrate tensile performance under saturated biocidal loading. Cost compression in standard hospital tiers is intensifying as group purchasing organizations consolidate vendor panels. Household channels exhibit highest price sensitivity, while surgical suite applications show minimal elasticity due to liability exposure.
Supply Chain Analysis
Direct-to-facility e-procurement platforms handle mid-size clinic and dental practice demand, bypassing traditional distributor markups. Raw material supply draws from German and Italian spunlace manufacturing clusters, United States petrochemical feedstocks for alcohol blends, and Indian cotton alternatives facing displacement. Distribution runs through institutional supply contracts with integrated delivery networks, retail mass-market channels, and specialized healthcare marketplaces. Single-source vulnerability concentrates in European substrate production, where 40% capacity allocation shifts toward high-performance segments create allocation risk for standard-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
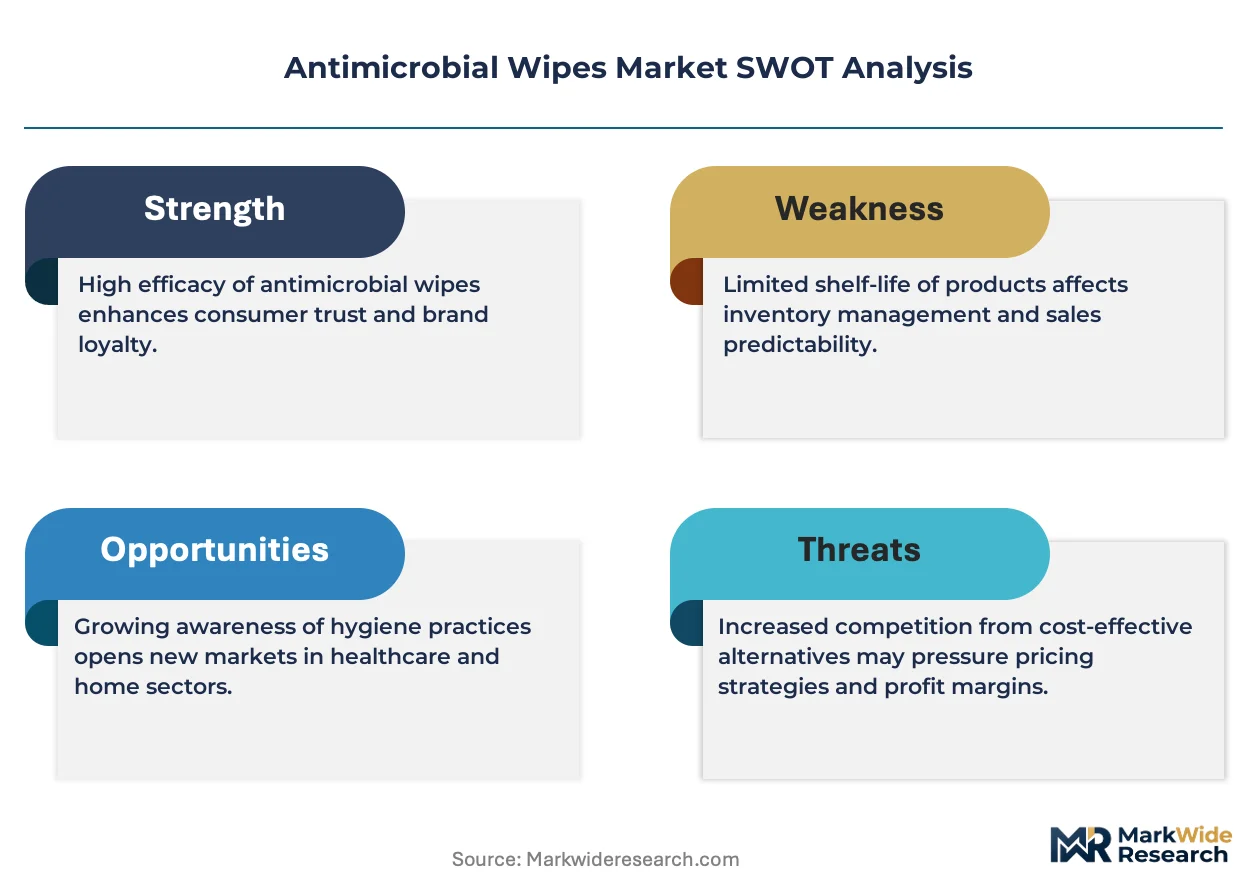
The antimicrobial wipes market functions as a regulatory compounder where EPA registration requirements and evolving EU Biocidal Products Regulation timelines continuously filter supplier bases and create replacement demand from displaced non-compliant products.
For Market Incumbents: Deepen backward integration into spunlace substrate production to secure allocation priority during capacity crunches, while accelerating peracetic acid alternative registrations ahead of ECHA quaternary ammonium reassessment completion. Lock in multi-year master service agreements with consolidated integrated delivery networks before procurement standardization fully matures. For New Entrants and Emerging Players: Launch via direct-to-facility e-procurement platforms targeting mid-size dental practices and ambulatory surgery centers underserved by legacy distributor networks. Penetrate India's CDSCO-aligned pharmaceutical manufacturing corridors with imported clinical-grade formulations before domestic production scales. White-space concentration sits in sustainable substrate innovation combining cellulose biodegradability with validated sporicidal claims. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier formulators possessing EPA registration infrastructure but lacking spunlace manufacturing captive supply, making them acquisition targets for diversified substrate producers seeking downstream integration. Long-term viability hinges on regulatory asset durability across multiple jurisdiction approvals. Watch ECHA's quaternary ammonium compound reclassification timeline as inflection indicator for alternative chemistry demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spunlace Manufacturing | Captive substrate supply secures allocation priority during European capacity crunches. |
| Alternative Biocide Registration Acceleration | Peracetic acid approvals ahead of ECHA quaternary ammonium reassessment preserve EU market access. |
| Direct-to-Facility E-Procurement Platform Launch | Amazon Business and specialized healthcare marketplaces disintermediate traditional distributor networks. |
| Sustainable Substrate R&D Investment | Cellulose-based biodegradable non-wovens address EU Single-Use Plastics Directive compliance pressure. |
| Multi-Year Master Service Agreement Consolidation | Integrated delivery networks in Texas and Florida standardize 80% of affiliated facilities under strategic vendor panels. |
Methodological Framework
Multiple input streams — structured interviews with hospital procurement managers and GPO contracts directors, technical discussions with spunlace manufacturing engineers and biocidal formulation chemists, and validation sessions with regulatory affairs specialists — were reconciled against EPA registration databases, FDA device classification filings, ECHA biocidal active substance review documentation, and hospital supply chain procurement records. Bottom-up demand modeling across end-user segments was cross-referenced with top-down capacity assessments from substrate production line disclosures.
Historical volume trajectories were cross-referenced against expert panel assessments of regulatory timeline impacts and procurement consolidation patterns across the analysis window. Segmentation dimensions modeled include product type tiers, material substrate chemistry, packaging automation levels, end-use compliance requirements, and regional regulatory cluster alignment. CAGRs were derived from slope consensus across input methodologies, incorporating kill-log documentation adoption curves and spunlace capacity expansion schedules as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA accelerated quaternary ammonium reclassification or Joint Commission mandate expansion scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Hand Hygiene Products Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Hygiene Stations Market
Infection Control
Disinfection Equipment Market
Infection Control
Global Hospital Infection Therapeutics Market
Infection Control
Denture Disinfectants Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Botulism Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Sterilization Tunnel Market
Infection Control
Surgical Site Infections Market
Infection Control
North America Bloodstream Infection Testing Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
Sterilization Monitoring Market