
 Global Pseudomonas Aeruginosa Infection Treatment Market | 2026-2036
Global Pseudomonas Aeruginosa Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pseudomonas Aeruginosa Infection Treatment Market Foresight
Intensive care unit admission thresholds for multidrug-resistant Gram-negative infections is hardening across tertiary hospitals worldwide. Pfizer Inc. leverages its established anti-pseudomonal cephalosporin pipeline to sustain positions in complicated intra-abdominal infection protocols. Merck & Co., Inc. anchors critical care formularies through in-house production of carbapenem-class therapies. Novartis AG differentiates through geographic dominance in European hospital tender systems for resistant pathogen coverage.
Pseudomonas aeruginosa infection treatment encompasses antimicrobial and adjunctive therapies targeting the oxidase-positive, non-fermenting Gram-negative bacillus, with minimum inhibitory concentration breakpoints guiding agent selection against its intrinsic efflux pumps and porin channel mutations. The primary purpose centers on reducing mortality in ventilator-associated pneumonia, cystic fibrosis exacerbations, and neutropenic sepsis where biofilm formation complicates eradication. Antibiotics occupy the largest value pool due to entrenched formulary placement, though phage therapy represents the fastest-growing category as compassionate-use frameworks expand for pan-resistant isolates. Combination therapy captures concentrated margin pools where hospitals seek insurance against resistance escalation through dual-mechanism coverage.
The FDA's Qualified Infectious Disease Product program shapes demand by granting extended exclusivity for novel anti-pseudomonal agents, while the EMA's antibacterial stewardship frameworks restrict empirical broad-spectrum use to documented resistance profiles. WHO priority pathogen listings directly influence national reimbursement tiers and hospital procurement mandates across multiple jurisdictions. Stakeholders must monitor phage therapy regulatory harmonization between FDA and EMA pathways to time manufacturing investments ahead of formal guidance publication.
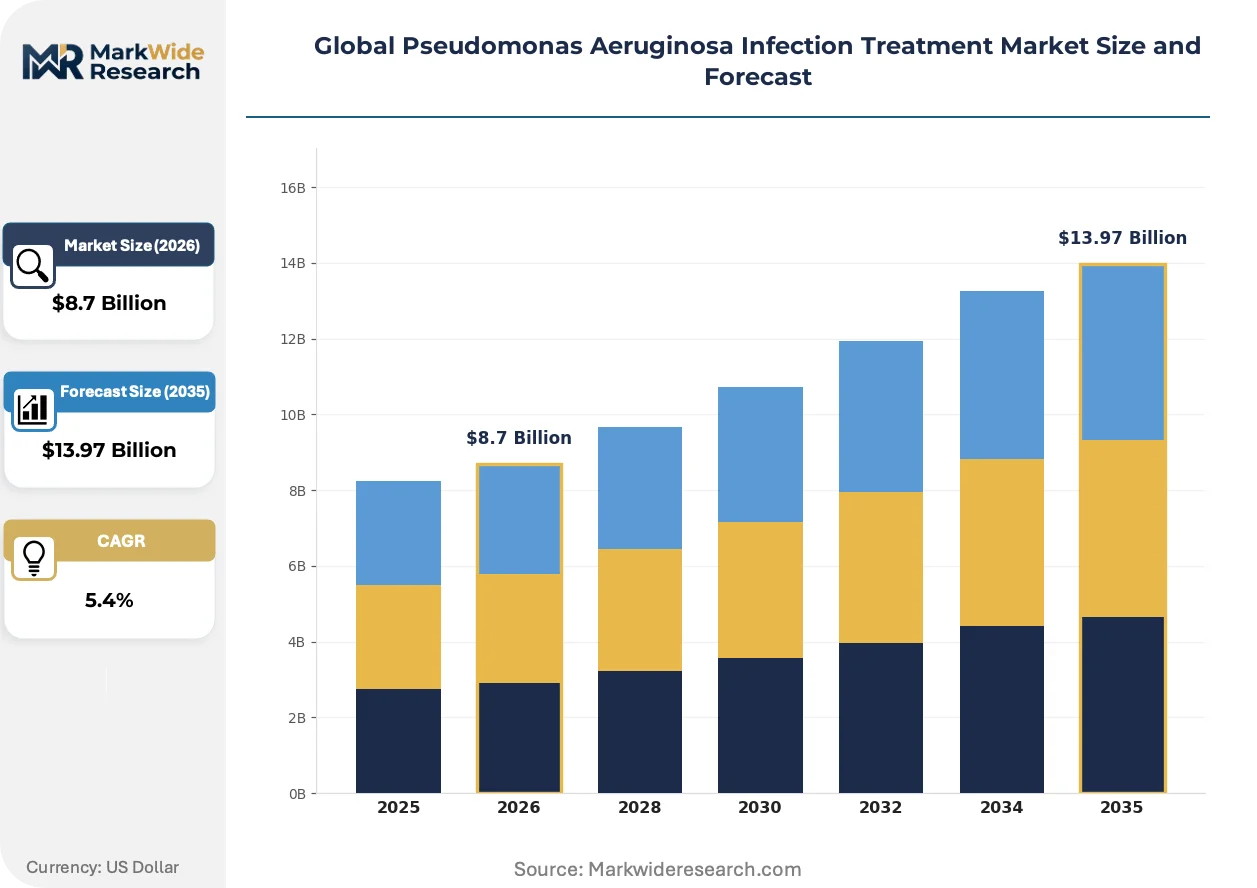
Market Dynamics
Phage therapy manufacturing scale-up is compressing development timelines for pan-resistant Pseudomonas aeruginosa coverage, forcing incumbent antibiotic developers to accelerate novel mechanism programs before regulatory harmonization locks in first-mover advantages.
Growth Catalysts
- Compassionate-use frameworks:FDA's expanded access protocols for bacteriophage cocktails are accelerating clinical validation timelines for refractory cystic fibrosis cases in the United States.
- Hospital tender centralization:Germany's federal procurement consortiums for anti-pseudomonal agents are consolidating volume commitments, reducing supplier fragmentation in critical care formularies.
- Cystic fibrosis population expansion:Expanded newborn screening programs across Japan are identifying Pseudomonas colonization earlier, extending chronic suppressive therapy demand curves.
Market Restraints
- Active pharmaceutical ingredient concentration:Carbapenem API production clusters in China create single-source vulnerability for European and North American finished-dose manufacturers.
- Extended exclusivity erosion:FDA Qualified Infectious Disease Product benefits expire for early-generation anti-pseudomonal agents, compressing margin pools for legacy pipeline holders.
- Phage stability limitations:Cold-chain requirements for bacteriophage formulations restrict outpatient deployment, tethering growth to hospital-based infusion centers.
Strategic Opportunities
- Indian hospital system buildout:Greenfield tertiary care construction in Maharashtra and Karnataka is creating first-mover slots for resistant-pathogen coverage protocols.
- Inhaled phage delivery convergence:Nebulizer-compatible bacteriophage formulations paired with cystic fibrosis maintenance devices are opening home-administration channels.
- WHO priority pathogen tiering:National reimbursement mandates in Brazil and Saudi Arabia are carving dedicated procurement budgets for carbapenem-resistant Gram-negative therapies.
Industry Challenges
- Phage-host range matching:Strain-specific bacteriophage cocktails require real-time susceptibility testing infrastructure that most clinical microbiology laboratories lack.
- Combination therapy evidence generation:Dual-agent randomized controlled trials for ventilator-associated pneumonia demand enrollment scales that strain sponsor budgets and site activation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pseudomonas Aeruginosa Infection Treatment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Antibiotics, Combination Therapy, Phage Therapy, Immunotherapy, Antiseptics Application: Pneumonia Therapy, Urinary Tract Infection Management, Burn Wound Care, Bloodstream Infection Control, Surgical Site Infection Prevention End User: Hospitals, Clinics, Long-term Care Facilities, Diagnostic Laboratories, Outpatient Centers Delivery Mode: Oral, Intravenous, Topical, Aerosolized, Intramuscular |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Johnson & Johnson, Novartis AG, AstraZeneca PLC, AbbVie Inc., Teva Pharmaceutical Industries Ltd., Gilead Sciences, Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pseudomonas Aeruginosa Infection Treatment Market Shifts & Advancements
Engineered bacteriophage platforms are displacing empirical broad-spectrum protocols in tertiary care settings, compressing the window for conventional antibiotic developers to demonstrate superior outcomes in biofilm-associated infections.
CRISPR-modified phage lysins are expanding into cystic fibrosis exacerbation protocols as nebulized formulations bypass biofilm penetration limits of systemic antibiotics. Academic medical centers in the United States are piloting bedside phage susceptibility panels, compressing the 72-hour empirical therapy window that drives resistance selection. This technology is expanding into outpatient pulmonary clinics, enabling chronic suppressive regimens that reduce hospitalization frequency.
EMA's antibacterial stewardship frameworks are restricting empirical carbapenem use to documented resistance profiles, forcing formulary committees to tier anti-pseudomonal agents by mechanism novelty. German and French hospital networks are deploying rapid molecular diagnostics to satisfy pre-authorization requirements, compressing time-to-appropriate-therapy metrics. Intensive care units in these jurisdictions are reallocating pharmacy budgets toward combination therapy slots that satisfy stewardship committees.
Outcome-based tendering is displacing volume-discount procurement in European hospital systems, with payment tied to 30-day mortality reduction in ventilator-associated pneumonia cohorts. Group purchasing organizations in the United Kingdom are unbundling antibiotic supply from diagnostic service contracts, creating separate vendor relationships for susceptibility testing platforms. This shift is most visible in NHS England procurement zones, where integrated care systems negotiate population-level coverage guarantees.
Global Pseudomonas Aeruginosa Infection Treatment Market Segmentation
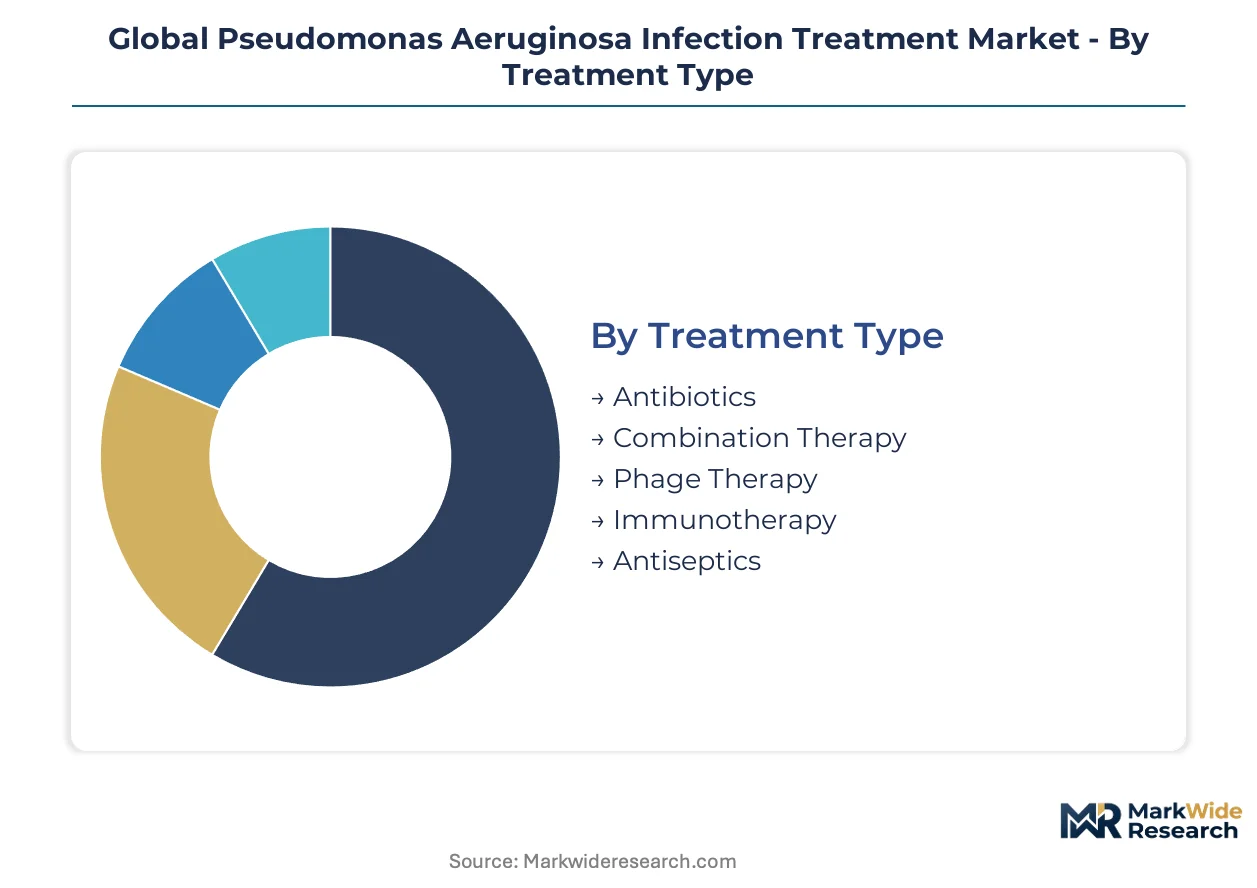
Treatment selection for Pseudomonas aeruginosa hinges on resistance profiles, infection site, and patient acuity. Formulary committees tier options by mechanism novelty and stewardship compliance, creating distinct procurement channels across acute and chronic care settings.
Treatment Type:
Hospital procurement teams prioritize coverage breadth against documented resistance patterns when selecting therapeutic categories.
- Antibiotics:Beta-lactam and fluoroquinolone formulations dominate intensive care unit formularies due to entrenched clinical familiarity and rapid bactericidal activity. Demand concentrates in tertiary hospitals across the United States, Germany, and Japan where ventilator-associated pneumonia protocols mandate immediate empirical coverage.
- Combination Therapy:Dual-agent regimens pair beta-lactams with aminoglycosides or polymyxins to suppress resistance emergence in neutropenic sepsis. German federal procurement consortiums are consolidating volume commitments for these protocols, reducing supplier fragmentation in critical care settings.
- Phage Therapy:Bacteriophage cocktails target pan-resistant isolates through strain-specific lytic action. FDA expanded access protocols are accelerating clinical validation for refractory cystic fibrosis cases.
- Immunotherapy:Monoclonal antibodies and vaccine candidates modulate host immune response against biofilm-encased pathogens. Development pipelines focus on chronic colonization scenarios.
- Antiseptics:Topical formulations including silver sulfadiazine and chlorhexidine provide adjunctive decolonization in burn units and surgical preparation protocols.
Antibiotics lead on scale; phage therapy leads on momentum.
Application:
Infection site determines route selection, dosing intensity, and duration economics for payers and providers.
- Pneumonia Therapy:Ventilator-associated and hospital-acquired pneumonia drive intravenous antibiotic consumption in intensive care units. Japanese tertiary hospitals are hardening admission thresholds for multidrug-resistant Gram-negative coverage, extending therapy duration curves.
- Urinary Tract Infection Management:Catheter-associated infections in long-term care facilities require oral step-down protocols after initial parenteral therapy. Resistance surveillance in French hospital networks guides empirical agent selection.
- Burn Wound Care:Topical and systemic regimens address colonization in partial-thickness and full-thickness injuries. Biofilm penetration challenges favor combination approaches.
- Bloodstream Infection Control:Neutropenic sepsis protocols demand rapid empirical coverage with carbapenem-class agents. Outcome-based tendering in NHS England ties payment to mortality reduction metrics.
- Surgical Site Infection Prevention:Preoperative antiseptic preparation and perioperative antibiotic prophylaxis target orthopedic and abdominal procedures.
Pneumonia therapy commands the largest addressable patient volume; bloodstream infection control carries the highest per-case economic burden.
End User:
Facility type shapes formulary depth, diagnostic capability, and reimbursement pathway for anti-pseudomonal agents.
- Hospitals:Tertiary acute care centers maintain broad-spectrum formularies with rapid molecular diagnostics for resistance profiling. EMA antibacterial stewardship frameworks restrict empirical carbapenem use to documented resistance profiles.
- Long-term Care Facilities:Skilled nursing and rehabilitation centers manage chronic colonization with oral suppressive regimens. Urinary catheter management protocols drive recurrent infection treatment demand.
- Clinics:Outpatient pulmonary and infectious disease practices coordinate cystic fibrosis maintenance therapy. Nebulizer-compatible phage formulations are opening home-administration channels.
- Diagnostic Laboratories:Clinical microbiology services provide susceptibility testing infrastructure for phage-host range matching and resistance surveillance.
- Outpatient Centers:Ambulatory infusion suites deliver prolonged intravenous courses for complex infections, tethering growth to hospital-based networks.
Hospitals anchor procurement volume; long-term care facilities are expanding most quickly as population aging extends chronic suppressive therapy demand.
Delivery Mode:
Route selection balances biofilm penetration, systemic exposure, and outpatient viability against cold-chain and compounding constraints.
- Intravenous:Continuous or intermittent infusion delivers peak concentrations for severe infections in intensive care settings. API production concentration in China creates supply vulnerability for carbapenem-class formulations.
- Aerosolized:Nebulized antibiotics and phage lysins target pulmonary biofilms in cystic fibrosis patients. CRISPR-modified formulations bypass systemic toxicity limits.
- Oral:Fluoroquinolone and fosfomycin formulations enable step-down therapy and chronic suppression. Bioavailability constraints limit application to uncomplicated infections.
- Topical:Creams, solutions, and wound dressings deliver localized concentrations in burn and surgical site protocols.
- Intramuscular:Depot formulations provide sustained release for outpatient compliance in resource-limited settings.
Intravenous delivery retains the steepest revenue concentration; aerosolized administration is gaining share fastest through nebulizer-phage convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping active pharmaceutical ingredient sourcing for anti-pseudomonal agents, with manufacturers relocating carbapenem intermediate production to jurisdictions offering streamlined environmental compliance pathways.
United States
FDA expanded access protocols for bacteriophage cocktails are accelerating clinical validation timelines for refractory cystic fibrosis cases. The Qualified Infectious Disease Product program grants extended exclusivity for novel anti-pseudomonal agents, incentivizing domestic manufacturing investment. Boston and San Francisco anchor phage therapy development clusters where academic medical centers pilot bedside susceptibility panels.
Germany
Federal procurement consortiums for anti-pseudomonal agents are consolidating volume commitments across tertiary hospital networks. EMA antibacterial stewardship frameworks restrict empirical carbapenem use to documented resistance profiles, forcing rapid molecular diagnostic deployment. The Rhine-Ruhr metropolitan region concentrates finished-dose formulation capacity for European distribution.
Japan
Expanded newborn screening programs are identifying Pseudomonas colonization earlier, extending chronic suppressive therapy demand curves. PMDA accelerated review pathways for combination anti-pseudomonal regimens align with METI industrial policy for pharmaceutical manufacturing. The Kansai region around Osaka maintains specialized fermentation capacity for beta-lactam antibiotic production.
India
Greenfield tertiary care construction in Maharashtra and Karnataka is creating first-mover slots for resistant-pathogen coverage protocols. CDSCO streamlined approval frameworks for fixed-dose combination anti-pseudomonal products support domestic formulation growth. The Hyderabad-Visakhapatnam corridor concentrates API synthesis capability for carbapenem-class intermediates.
China
Carbapenem API production clusters create single-source vulnerability for European and North American finished-dose manufacturers. NMPA environmental compliance enforcement is consolidating fermentation capacity among state-affiliated pharmaceutical groups. The Shandong Peninsula anchors cephalosporin intermediate manufacturing for export markets.
Global Pseudomonas Aeruginosa Infection Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent antibiotic developers accelerate novel mechanism programs ahead of phage therapy regulatory harmonization. The market exhibits consolidated structure among multinational pharmaceutical conglomerates with established anti-pseudomonal pipelines, while emerging bacteriophage specialists occupy pre-commercial niches. Three strategic archetypes define competitive positioning: legacy beta-lactam developers stewarding entrenched hospital formularies, phage therapy platforms pursuing compassionate-use validation, and combination therapy sponsors generating dual-agent evidence. Dominant competitive moves include geographic expansion into Indian hospital system buildouts and technology licensing for nebulizer-compatible phage delivery systems.
Within the legacy pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. occupy positions reflecting decades of cephalosporin and carbapenem development heritage. Novartis AG exemplifies geographic dominance strategies through European hospital tender system penetration. These entities represent the incumbent archetype confronting displacement pressure from engineered bacteriophage platforms.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Novartis AG |
| AstraZeneca PLC |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Gilead Sciences, Inc. |
| Bayer AG |
| Others |
Supply & Pricing Matrix
EMA environmental compliance enforcement for fermentation effluent discharge gates qualified supply access and premium-tier pricing for carbapenem-class formulations in European hospital networks. Finished-dose manufacturers face dual qualification hurdles: proving green chemistry credentials while meeting stewardship committee efficacy thresholds.
Pricing Analysis
Distributor margins for anti-pseudomonal agents compress as hospital group purchasing organizations consolidate volume commitments across tertiary networks. Pricing stratifies across premium, standard, and economy tiers based on mechanism novelty and documented resistance coverage breadth. Cost compression in standard-tier beta-lactams intensifies because API oversupply from Chinese fermentation clusters erodes margin pools. Long-term care facilities exhibit highest price sensitivity due to fixed reimbursement rates, while intensive care units prioritize coverage certainty over unit cost.
Supply Chain Analysis
India's domestic-content mandates for pharmaceutical manufacturing under the PLI scheme are reshaping sourcing patterns for beta-lactam intermediates. Carbapenem API production draws from China, India, and Italy, with penem-ring synthesis feeding from Shandong and Hyderabad-Visakhapatnam corridors. Single-source vulnerability concentrates in Chinese fermentation capacity for 4-AA intermediates. Distribution runs through federal procurement consortiums in Germany and group purchasing organizations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Pseudomonas Aeruginosa Infection Treatment Market functions as a stable compounder anchored by irreversible resistance escalation that perpetually refreshes demand for next-generation coverage.
For Market Incumbents: Anchor hospital formulary positions through backward integration into carbapenem API production, eliminating single-source exposure that disrupts tender fulfillment. Accelerate nebulizer-compatible phage lysin development before compassionate-use frameworks mature, as engineered bacteriophage platforms threaten displacement of empirical beta-lactam protocols in tertiary care settings. For New Entrants and Emerging Players: Specialty distributors serving cystic fibrosis outpatient clinics offer the most penetrable channel for nebulized phage formulations bypassing hospital pharmacy gatekeepers. Target Maharashtra and Karnataka greenfield hospital systems where first-mover slots for resistant-pathogen coverage protocols remain uncommitted. Pursue licensing arrangements with academic medical centers holding engineered phage patent estates. For Investors and Strategic Acquirers: Roll-up economics work for clinical microbiology diagnostic platforms because phage-host range matching demands real-time susceptibility testing infrastructure that most laboratories currently lack. The 5-10 year viability window favors platforms combining rapid molecular diagnostics with therapeutic decision support. Watch for FDA-EMA regulatory harmonization on bacteriophage manufacturing standards as the inflection signal triggering manufacturing investment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Phage therapy production capacity expansion ahead of FDA harmonization guidance secures first-mover positioning in compassionate-use networks. |
| Regulatory Approval Pathway | Qualified Infectious Disease Product designation through FDA extends exclusivity periods for novel anti-pseudomonal mechanisms. |
| Hospital System Partnership | Integrated care system contracts in NHS England zones tie payment to mortality reduction metrics in ventilator-associated pneumonia cohorts. |
| Pipeline Diversification | CRISPR-modified phage lysin development addresses biofilm penetration limits that constrain systemic antibiotic efficacy in cystic fibrosis. |
| Geographic Expansion | Greenfield tertiary care construction in Indian states creates procurement slots for resistant-pathogen coverage protocols before incumbent lock-in. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with formulary directors, hospital pharmacy managers, regulatory affairs leads, and infectious disease clinicians combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Top-down supply-side analysis triangulates customs data, fermentation capacity disclosures, and API trade flows against bottom-up demand estimates.
Input-output matrices map treatment type, application site, end-user facility, and delivery mode dimensions across the projection horizon. CAGRs derive from segment-level demand elasticity modeling against resistance surveillance trends and regulatory framework evolution. Forecast inputs incorporate PMDA accelerated review pathway utilization rates and EMA stewardship compliance thresholds.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to phage therapy regulatory harmonization timing and carbapenem API supply disruption events. Analytical boundaries exclude veterinary applications and environmental decontamination protocols. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Alcohol Wipes Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Infection Prevention Market
Infection Control
Ultraviolet Germicidal Irradiation Market
Infection Control
Ear Infection Treatment Market
Infection Control
Sterilization Market
Infection Control
Global Hospital Infection Therapeutics Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Hygiene Stations Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
North America Bloodstream Infection Testing Market