
 Antimicrobial Catheters Market | 2026-2036
Antimicrobial Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Catheters Market Analysis
Asset-light leasing models for high-volume catheter procurement is reconfiguring competitive dynamics, allowing mid-tier hospitals to access premium antimicrobial portfolios without capital outlay. BD leverages its vertical integration across polymer sourcing and coating application to sustain margin control. Teleflex Incorporated anchors its position through specialized central venous catheter lines with integrated antiseptic barriers. Medtronic competes by dominating electromechanical infusion systems that pair with antimicrobial intravascular sets.
Antimicrobial catheters are polymer-based medical tubes impregnated with silver ions, antibiotic coatings, or antiseptic surfaces that inhibit biofilm formation during indwelling use, typically manufactured via extrusion followed by dip-coating or vapor-deposition of active agents. Foley catheters occupy the largest volume share due to standardized urinary drainage protocols, while central venous catheters command premium pricing driven by bloodstream infection liability costs. Peripheral catheters represent a maturing segment where commodity pricing pressures manufacturers toward coating differentiation.
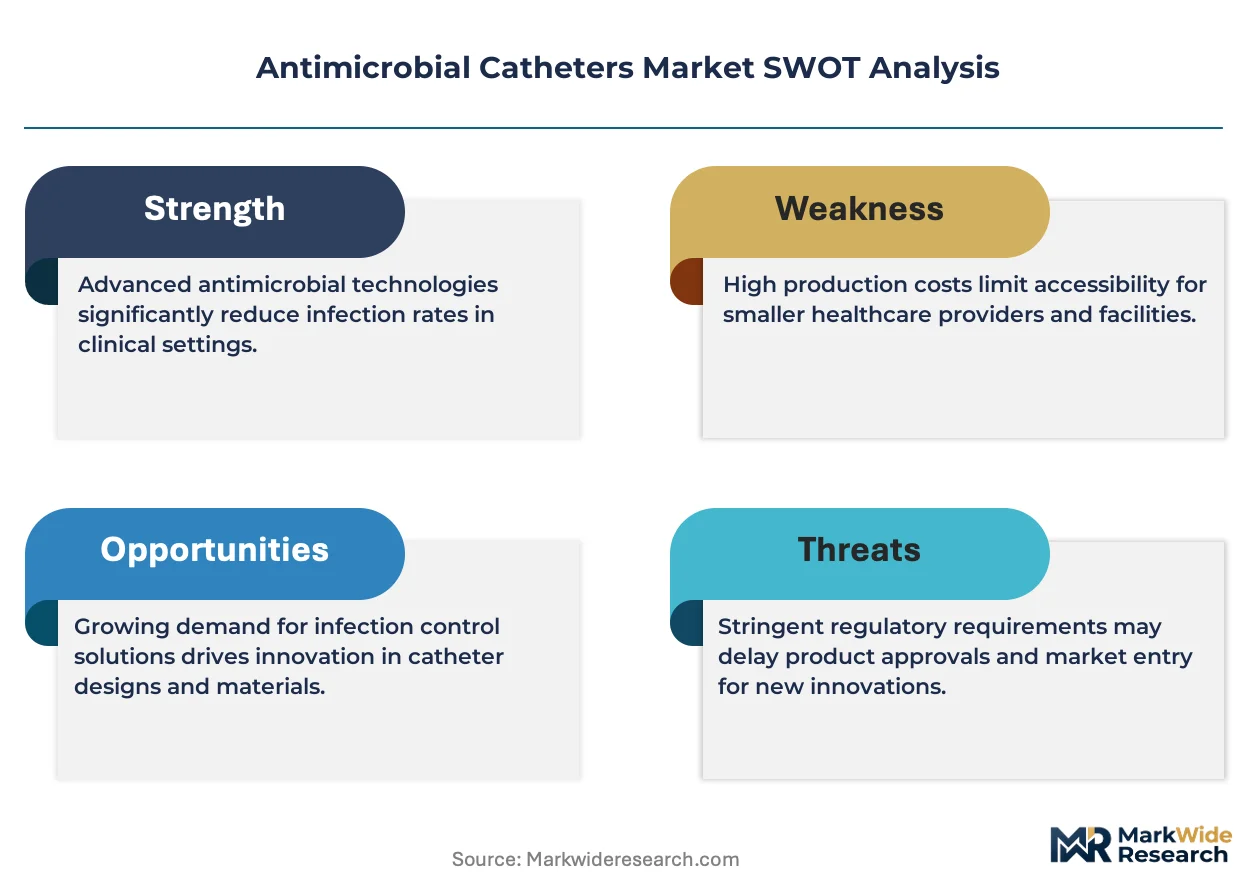
FDA premarket notification pathways and EPA antimicrobial product registrations jointly determine which coating chemistries reach clinical use, with the former assessing biocompatibility and the latter regulating residual silver release claims. The EU MDR's heightened clinical evidence requirements for implantable devices are extending approval timelines for European market entrants. Stakeholders must monitor evolving biofilm resistance patterns against established coating chemistries to anticipate next-generation material investments.
Market Dynamics
FDA's updated premarket notification requirements for antimicrobial devices are accelerating validation investments across the supply chain, forcing manufacturers to front-load clinical evidence generation before coating chemistry selection finalizes.
Growth Catalysts
- Catheter-associated infection reduction mandates:United States hospitals face reimbursement penalties tied to preventable bloodstream infections, compressing replacement cycles for standard catheters.
- Silver-ion coating advances:Vapor-deposition techniques now achieve sustained elution profiles that satisfy EPA residual release thresholds without compromising polymer integrity.
- China:NMPA fast-track pathways for breakthrough antimicrobial devices are attracting coating technology transfers from Western suppliers seeking volume scale.
Market Restraints
- Polymer resin concentration:Medical-grade polyurethane supply concentrates among three European chemical conglomerates, exposing converters to input cost volatility.
- EU MDR clinical evidence requirements:Extended approval timelines for implantable devices delay European market entry for novel coating formulations.
- Antiseptic-impregnated dressings:These adjunct products substitute for premium catheter upgrades in cost-constrained acute care settings.
Strategic Opportunities
- India:CDSCO's phased implementation of medical device rules creates first-mover advantage for silver-alloy Foley catheter registrations ahead of domestic manufacturing scale-up.
- Home infusion therapy:Ambulatory antimicrobial central venous catheter demand is outpacing hospital procurement as oncology shifts to outpatient administration.
- Leasing-based procurement:Asset-light models allow mid-tier hospitals to access premium antimicrobial portfolios without capital outlay, reconfiguring competitive dynamics.
Industry Challenges
- Biofilm resistance surveillance:Clinical microbiology laboratories lack standardized protocols for tracking coating chemistry failure patterns, complicating next-generation material roadmaps.
- Coating-application equipment:Precision dip-coating and vapor-deposition systems require seven-figure capital commitments that strain mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Catheters Market |
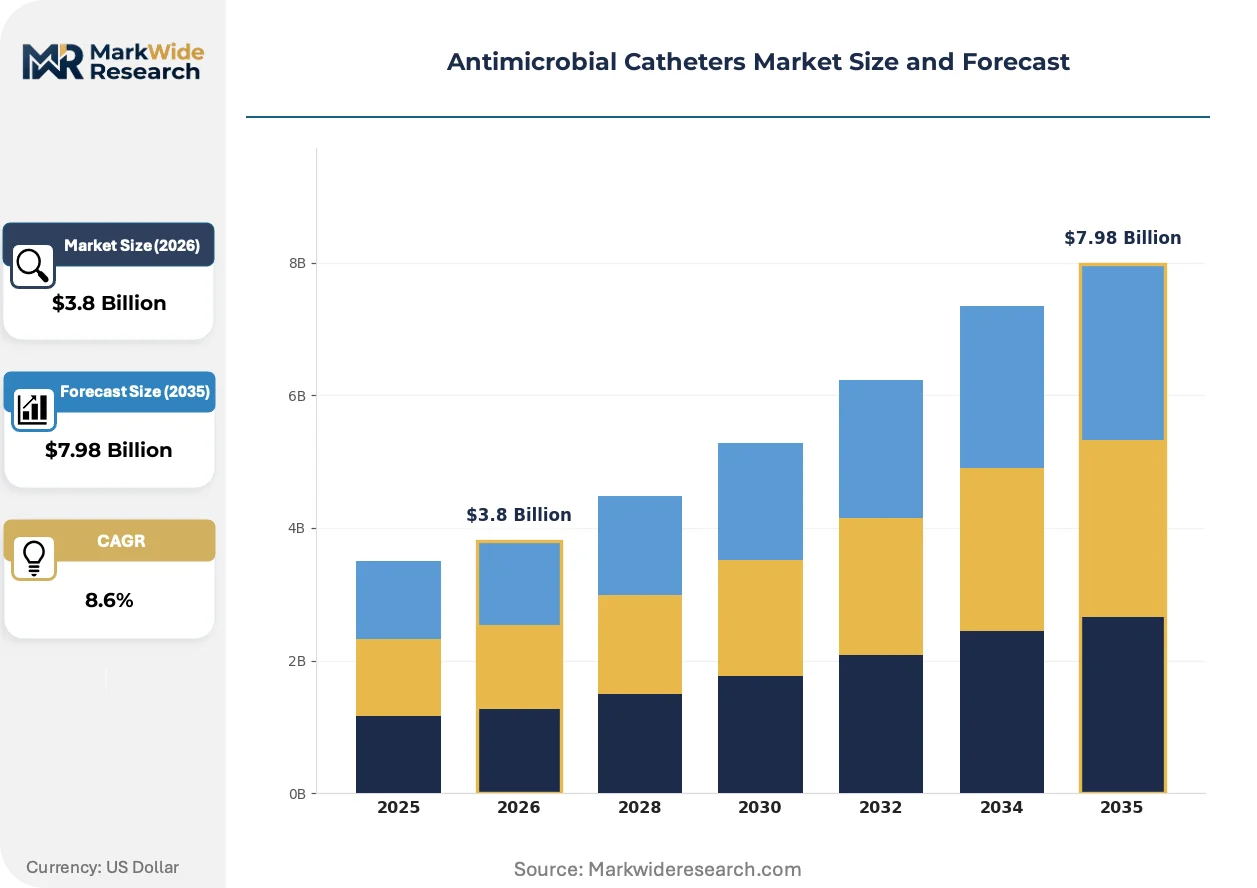
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foley Catheters, Central Venous Catheters, Peripheral Catheters, Urethral Catheters Delivery Mode: Intravascular, Urethral, Surgical, Enteral End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Application: Infection Prevention, Drug Delivery, Fluid Management, Biopsy |
| Companies Covered | B. Braun SE, Teleflex Incorporated, BD, Medtronic, ConvaTec Group PLC, Cook Medical, Medline, Vygon, Silq Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Catheters Market Emerging Trajectories
Coating chemistry innovation and procurement model experimentation are compressing traditional product lifecycles while regulatory evidence requirements extend development timelines.
Photocatalytic titanium dioxide coatings activated by ambient light exposure are rendering obsolete conventional silver-ion formulations in outpatient settings. Home health agencies in Germany and Japan are piloting these catheters for long-term urinary drainage. The technology is rendering obsolete the assumption that antimicrobial efficacy requires sustained pharmaceutical elution.
EPA's updated antimicrobial product registration framework now mandates quantitative biofilm inhibition assays for residual silver release claims. Coating manufacturers must retest legacy formulations under revised protocols, extending re-registration timelines by 18-24 months. Central venous catheter suppliers with diversified chemistry portfolios are accelerating non-silver alternatives to circumvent approval bottlenecks.
Hospital supply chain consolidation is compressing vendor panels and unbundling catheter procurement from bundled payment contracts. Integrated delivery networks in Texas and Florida are centralizing antimicrobial catheter selection at the system level, displacing individual hospital autonomy. This concentration is most visible in multi-hospital systems pursuing bloodstream infection rate guarantees with payers.
Antimicrobial Catheters Market Segmentation
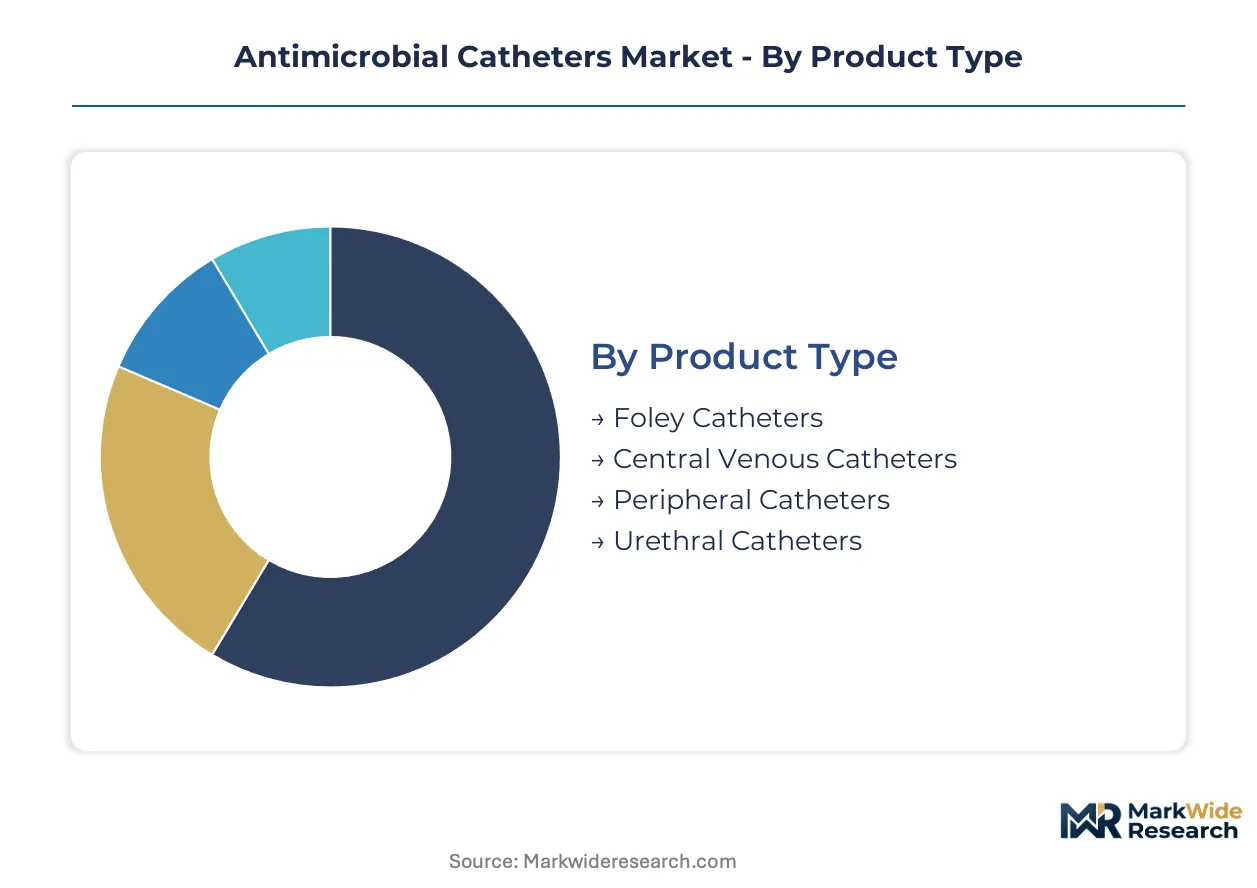
Antimicrobial catheter purchasing decisions fragment across clinical workflow requirements, reimbursement structures, and infection liability exposure. Each segmentation dimension captures distinct procurement authority patterns and technology performance thresholds that reshape vendor competitive positioning.
Product Type:
Cost tier stratification determines polymer specification, coating chemistry investment, and replacement cycle economics across catheter categories.
- Foley Catheters:Polymer tubes with silver-alloy or hydrogel coatings inserted transurethrally for urinary drainage, manufactured via extrusion with dip-coating antimicrobial application. Demand concentrates in United States acute care hospitals where CMS non-payment policies for catheter-associated urinary tract infections compress replacement cycles to 72-hour maximums.
- Central Venous Catheters:Multi-lumen polyurethane devices with integrated antiseptic barriers or impregnated cuffs, requiring vapor-deposition coating systems for sustained elution profiles. High bloodstream infection liability costs in tertiary referral centers in Texas and Florida drive premium pricing acceptance for antiseptic-impregnated variants.
- Peripheral Catheters:Short-term intravenous access devices with surface-modified polymer interfaces, manufactured at commodity scale with thinner coating layers. Mid-tier hospitals in cost-constrained markets substitute standard variants with antiseptic dressings rather than upgrading to coated catheters.
- Urethral Catheters:Intermittent or indwelling drainage devices with lubricious antimicrobial surfaces, typically single-use disposable format. Home care agencies in Germany and Japan pilot photocatalytic titanium dioxide variants activated by ambient light exposure.
Foley catheters command the established base. The steepest expansion runs through central venous catheters as oncology shifts to outpatient infusion protocols.
Delivery Mode:
Application site determines regulatory pathway complexity, sterility assurance requirements, and coating durability specifications.
- Intravascular:Catheters entering venous or arterial circulation with endothelial contact, subject to FDA premarket notification for antimicrobial claims and EPA residual silver release registration. Bloodstream infection reduction mandates in United States hospitals accelerate validation investments for coating chemistries.
- Urethral:Transurethral insertion devices with mucosal membrane exposure, requiring biocompatibility testing under ISO 10993 standards for prolonged indwelling use. European urology clinics favor hydrogel-coated variants with lower friction coefficients than silver-ion alternatives.
- Surgical:Intraoperative placement catheters with temporary antimicrobial protection during high-contamination procedures. Operating room supply chains in India prioritize cost-minimized standard variants over premium coated options.
- Enteral:Gastrointestinal access devices with antimicrobial luminal surfaces to prevent biofilm accumulation in feeding tubes. Long-term care facilities in Japan represent concentrated demand for silicone-based enteral catheters with silver-ion impregnation.
Intravascular delivery anchors revenue concentration. The fastest volume gains are occurring in enteral applications as home nutrition support expands.
End User:
Customer type shapes procurement centralization, budget authority, and technology specification stringency.
- Hospitals:Integrated delivery networks with system-level vendor consolidation and bloodstream infection rate guarantees with payers. Texas and Florida multi-hospital systems centralize antimicrobial catheter selection, displacing individual facility autonomy.
- Clinics:Outpatient settings with limited capital budgets and preference for leasing-based procurement models. Asset-light arrangements allow mid-tier clinics access to premium antimicrobial portfolios without upfront outlay.
- Home Care:Ambulatory settings where patients or caregivers perform catheter maintenance, driving demand for simplified handling and extended wear intervals. German home health agencies pilot photocatalytic coatings activated by ambient light.
- Long-term Care Facilities:Skilled nursing environments with high catheter utilization rates and pressure to minimize infection-related transfer costs. Silver-alloy Foley catheters represent standard of care in United States nursing homes facing state inspection scrutiny.
Hospitals retain procurement volume leadership. Home care is climbing the fastest as oncology administration shifts to outpatient settings.
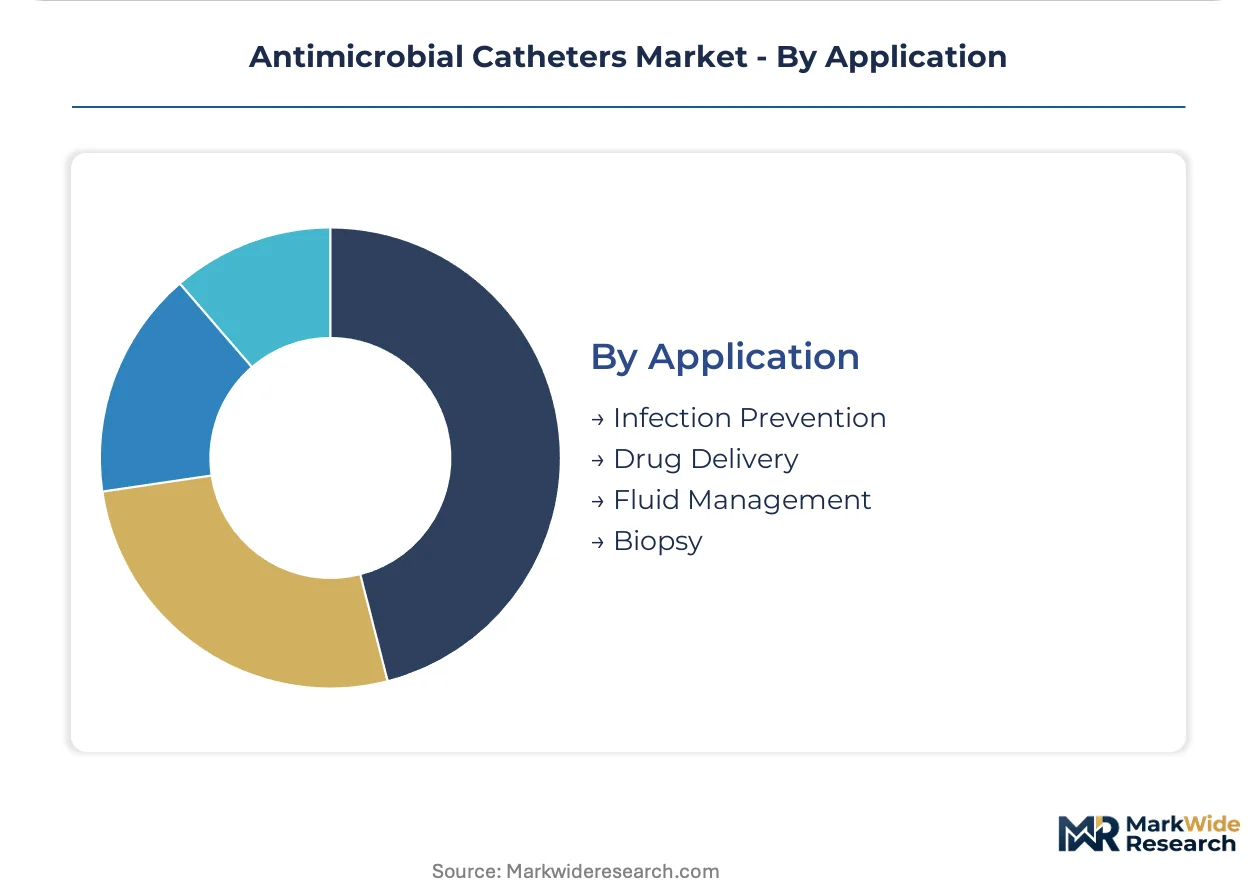
Application:
Functional use case determines performance threshold, regulatory evidence requirements, and pricing tolerance.
- Infection Prevention:Primary antimicrobial indication with EPA registration mandates for residual silver release claims and quantitative biofilm inhibition assays. Coating manufacturers must retest legacy formulations under revised protocols, extending re-registration timelines.
- Drug Delivery:Chemotherapy and antimicrobial administration requiring chemical compatibility between coating agents and infused pharmaceuticals. Oncology clinics demand central venous catheters with non-reactive polymer surfaces.
- Fluid Management:Drainage and irrigation applications where antimicrobial protection prevents luminal occlusion. Surgical suites prioritize standard variants with adjunct antiseptic protocols over coated premiums.
- Biopsy:Tissue sampling procedures with temporary catheter placement and minimal indwelling duration. Cost constraints in diagnostic imaging centers limit antimicrobial coating adoption.
Infection prevention commands the established base. Drug delivery is gaining share fastest as precision oncology expands infusion therapy volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy European polymer suppliers dominate medical-grade polyurethane feedstock, while import-dependent Asian converters absorb coating technology transfers to build domestic catheter manufacturing. The United States runs a structural deficit in antimicrobial device components, sourcing specialty coatings from German and Swiss chemical firms. China and India are narrowing this gap through regulatory fast-tracks and localized production incentives.
United States
CMS non-payment policies for catheter-associated urinary tract infections compress replacement cycles to 72-hour maximums in acute care hospitals. FDA premarket notification pathways for antimicrobial claims require extensive clinical evidence generation before coating chemistry finalization. Texas and Florida multi-hospital systems centralize procurement decisions, displacing individual facility autonomy in antimicrobial catheter selection.
Germany
Home health agencies pilot photocatalytic titanium dioxide catheters activated by ambient light exposure for long-term urinary drainage. ECHA REACH compliance mandates rigorous substance registration for silver-ion coating chemistries entering clinical use. The Rhine-Ruhr industrial corridor concentrates polymer sourcing and precision coating equipment manufacturing for European catheter supply chains.
China
NMPA fast-track pathways for breakthrough antimicrobial devices attract Western coating technology transfers seeking volume scale. Domestic manufacturers expand silver-alloy Foley catheter production to reduce import dependence for hospital procurement. The Yangtze River Delta cluster anchors catheter extrusion and dip-coating capacity serving Asia-Pacific demand.
India
CDSCO's phased medical device rules implementation creates first-mover advantage for silver-alloy Foley catheter registrations ahead of domestic manufacturing scale-up. Cost constraints in operating room supply chains prioritize standard variants over premium coated options in surgical applications. Maharashtra and Gujarat industrial zones attract contract manufacturing investments from multinational catheter suppliers.
Japan
Long-term care facilities drive concentrated demand for silicone-based enteral catheters with silver-ion impregnation. METI standards for medical device quality management extend approval timelines for novel coating formulations seeking market entry. The Kanto region around Tokyo hosts specialized central venous catheter distribution serving home infusion therapy expansion.
Antimicrobial Catheters Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream controlling polymer specification and coating application. Market structure tilts toward consolidated procurement authority as hospital supply chain consolidation compresses vendor panels and unbundles catheter selection from bundled payment contracts. Three archetypes dominate: diversified medical technology conglomerates with captive polymer sourcing, specialized catheter manufacturers with coating chemistry expertise, and contract converters serving private-label demand. Competitive dynamics center on backward integration into polymer resin supply and strategic partnerships with antimicrobial coating technology licensors.
Among diversified platform operators, BD exemplifies vertical control across polymer sourcing and coating application. Teleflex Incorporated occupies a position within the specialized catheter tier through central venous catheter lines with integrated antiseptic barriers. Medtronic anchors the electromechanical systems segment where infusion platforms pair with antimicrobial intravascular sets. These three represent distinct competitive vectors: supply chain control, clinical specialization, and system integration.
| Leading Market Players |
|---|
| B. Braun SE |
| Teleflex Incorporated |
| BD |
| Medtronic |
| ConvaTec Group PLC |
| Cook Medical |
| Medline |
| Vygon |
| Silq Technologies |
| Others |
Supply Flow & Price Mechanics
Medical-grade polyurethane feedstock concentrates among three European chemical conglomerates, anchoring margin capture upstream while catheter converters downstream absorb volatile input costs through contract pass-through clauses. This concentration forces manufacturers to front-load coating chemistry investments before polymer price negotiations finalize.
Pricing Analysis
Integrated delivery networks anchor antimicrobial catheter pricing through system-level vendor consolidation and bloodstream infection rate guarantees with payers. Three-tier pricing structure across premium antiseptic-impregnated, standard silver-ion, and economy uncoated tiers separates tertiary referral centers from mid-tier hospitals and cost-constrained surgical suites. Cost compression in the peripheral catheter segment is intensifying because antiseptic-impregnated dressings substitute for coated premiums. Mid-tier hospitals exhibit highest price sensitivity, while Texas and Florida multi-hospital systems accept premium tiers for liability reduction.
Supply Chain Analysis
Extended payment terms from European polymer suppliers strain working capital for Asian contract manufacturers expanding coating-application capacity. Raw material sourcing draws from Germany and Switzerland for specialty coatings, China and South Korea for extrusion equipment, and India for labor-intensive assembly. Single-source vulnerability concentrates in vapor-deposition coating systems requiring seven-figure capital commitments. Distribution runs through group purchasing organizations consolidating hospital procurement panels and unbundling catheter selection from bundled payment contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial catheter adoption sits in early-cycle expansion as outpatient oncology infusion protocols accelerate central venous catheter demand beyond traditional hospital procurement. Photocatalytic coating advances and home health agency pilot programs signal penetration tailwinds in ambulatory settings.
For Market Incumbents: Pre-empt coating chemistry obsolescence by accelerating non-silver alternatives through FDA premarket notification pathways before EPA re-registration bottlenecks harden. Backward integration into polymer resin supply and captive vapor-deposition capacity defend margin pools against mid-tier converters gaining coating technology transfers from Western suppliers. For New Entrants and Emerging Players: Establish a beachhead in India's silver-alloy Foley catheter segment ahead of CDSCO's full medical device rules implementation, leveraging contract manufacturing investments in Maharashtra and Gujarat industrial zones. Home infusion therapy for oncology represents the most penetrable white-space target, with direct-to-home-health-agency distribution bypassing consolidated hospital supply chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed coating technology specialists holding EPA antimicrobial product registrations and vapor-deposition equipment fleets. Long-term viability hinges on diversified chemistry portfolios resilient to biofilm resistance surveillance gaps. The signal to watch is NMPA fast-track approval velocity for breakthrough antimicrobial devices, indicating technology transfer momentum into domestic Chinese manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Accelerates antimicrobial coating validation before chemistry selection finalizes for US market entry. |
| Hospital System Partnership | Texas and Florida integrated delivery networks centralize procurement decisions displacing facility autonomy. |
| Backward Integration into Polymer Supply | BD's vertical control across medical-grade polyurethane sourcing sustains margin compression resistance. |
| Reimbursement Strategy | CMS non-payment policies for catheter-associated infections compress replacement cycles to 72-hour maximums. |
| Software Companion Development | Biofilm resistance surveillance platforms address clinical microbiology laboratories' standardized protocol gaps. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and coating chemistry R&D directors. Secondary validation drew from FDA 510(k) filings, EPA antimicrobial product registration databases, CMS Medicare reimbursement data, and hospital procurement contract disclosures. Bottom-up catheter unit demand estimates and top-down market sizing triangulated across the analysis window.
Calibration against historical replacement cycle data and regulatory approval timelines anchored the analytical framework. Segmentation dimensions modeled include product type, delivery mode, end user, and application across the projection horizon. CAGRs derived from infection reduction mandate penetration curves and outpatient oncology shift trajectories. Coating chemistry innovation cycles and biofilm resistance surveillance adoption patterns served as industry-specific forecast inputs.
Sensitivities concentrate around EPA re-registration timeline extensions, EU MDR clinical evidence requirement evolution, and NMPA fast-track pathway velocity for breakthrough devices. Forecasts reflect documented assumptions on antimicrobial resistance pattern trajectories and hospital supply chain consolidation momentum. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Surgical Site Infection Control Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Disinfection Cupboard Market
Infection Control
Salivary Gland Infection Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Sterilization Tunnel Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Alcohol Wipes Market
Infection Control
Yeast Infection Market
Infection Control
Air Sanitizer Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Hospital Acquired Infections Therapeutic Market