
 Cough Assist Devices Market | 2026-2036
Cough Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cough Assist Devices Market Analysis
Buyer concentration among home care providers and long-term respiratory service networks is realigning procurement patterns across the cough assist devices landscape. Hill-Rom Holdings sustains its institutional channel dominance through durable equipment leasing programs that lock in hospital system loyalty. Koninklijke Philips N.V. leverages integrated ventilator-to-cough-assist platforms that reduce clinician training burdens across multi-site deployments. Dima Italia Srl specializes in portable electromechanical units that navigate reimbursement constraints in European home care markets.
Cough assist devices are mechanical or electromechanical systems that apply positive insufflation followed by rapid negative exsufflation to simulate natural cough mechanics, typically generating peak expiratory flows exceeding 160 liters per minute to clear retained airway secretions in patients with compromised respiratory muscle function. Electromechanical devices lead unit shipments due to programmable pressure cycling and patient compliance monitoring, while mechanical cough stimulators occupy the value tier serving price-sensitive institutional buyers in emerging markets. The neuromuscular disorders application segment captures concentrated margin pools as amyotrophic lateral sclerosis and muscular dystrophy patient cohorts require prolonged device utilization with recurring disposable component purchases.
The FDA's Class II 510(k) clearance framework and the EU Medical Device Regulation's clinical evidence requirements shape product development timelines and market access costs for manufacturers on both sides of the Atlantic. Japan's PMDA enforces stringent electrical safety and biocompatibility testing under JIS standards that filter out lower-capability entrants from the Asia-Pacific supply base. Stakeholders must monitor evolving home care reimbursement codes and pressure from respiratory therapist professional societies to demonstrate comparative effectiveness against manual airway clearance techniques.
Market Dynamics
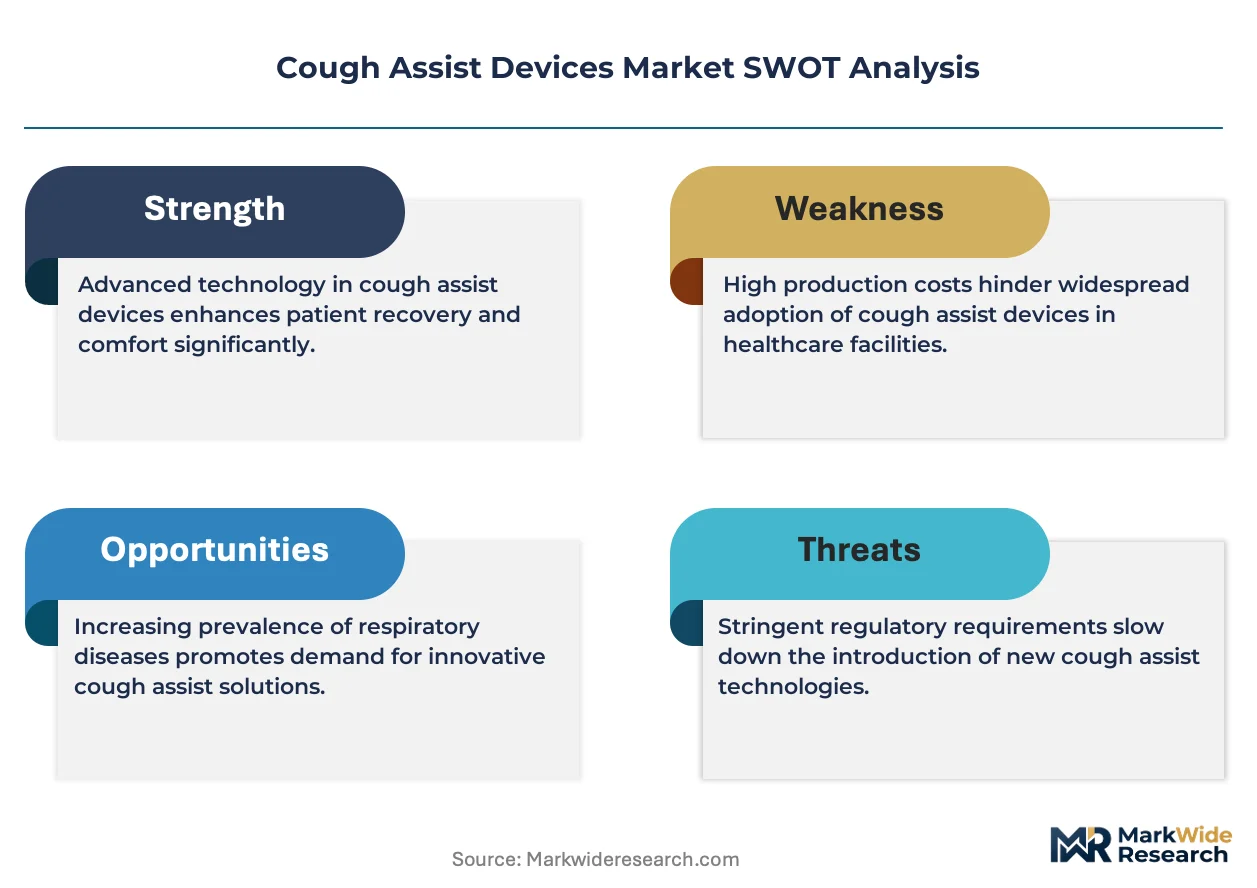
Home care reimbursement expansion is compressing hospital procurement cycles and forcing manufacturers to reconfigure distribution networks around durable medical equipment suppliers serving decentralized patient populations.
Growth Catalysts
- Aging demographics:Germany, Japan, and the United States exhibit elevated neuromuscular disease prevalence that sustains recurring demand for secretion management interventions.
- FDA Class II 510(k) pathway:The streamlined premarket notification framework accelerates electromechanical device introductions relative to Class III PMA timelines.
- Portable electromechanical platforms:Programmable pressure cycling with compliance monitoring enables longitudinal respiratory therapist oversight without institutional admission.
Market Restraints
- EU MDR clinical evidence requirements:The expanded post-market surveillance obligations extend product development timelines and inflate regulatory consulting expenditures for European market access.
- Biocompatibility testing under JIS standards:Japan's electrical safety mandates filter lower-capability entrants from the Asia-Pacific supply base, concentrating sourcing options.
- Manual airway clearance substitution:Chest physiotherapy and percussion vest alternatives retain institutional preference in price-sensitive emerging markets.
Strategic Opportunities
- Underpenetrated home care segments:Rural United States markets exhibit significant coverage gaps where telehealth-integrated cough assist platforms could displace episodic emergency department visits.
- Reimbursement code expansion:Evolving HCPCS and CPT classifications for mechanical insufflation-exsufflation create billing clarity that reduces patient out-of-pocket exposure.
- Ventilator-to-cough-assist convergence:Integrated respiratory platforms that share power supplies and patient circuits reduce capital duplication for long-term care facilities.
Industry Challenges
- Respiratory therapist certification gaps:Specialized training for mechanical insufflation-exsufflation titration remains unevenly distributed across home health agencies, limiting device utilization optimization.
- Legacy EMR integration friction:Disconnected data architectures between cough assist devices and electronic health records impede remote monitoring scalability for multi-site deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cough Assist Devices Market |
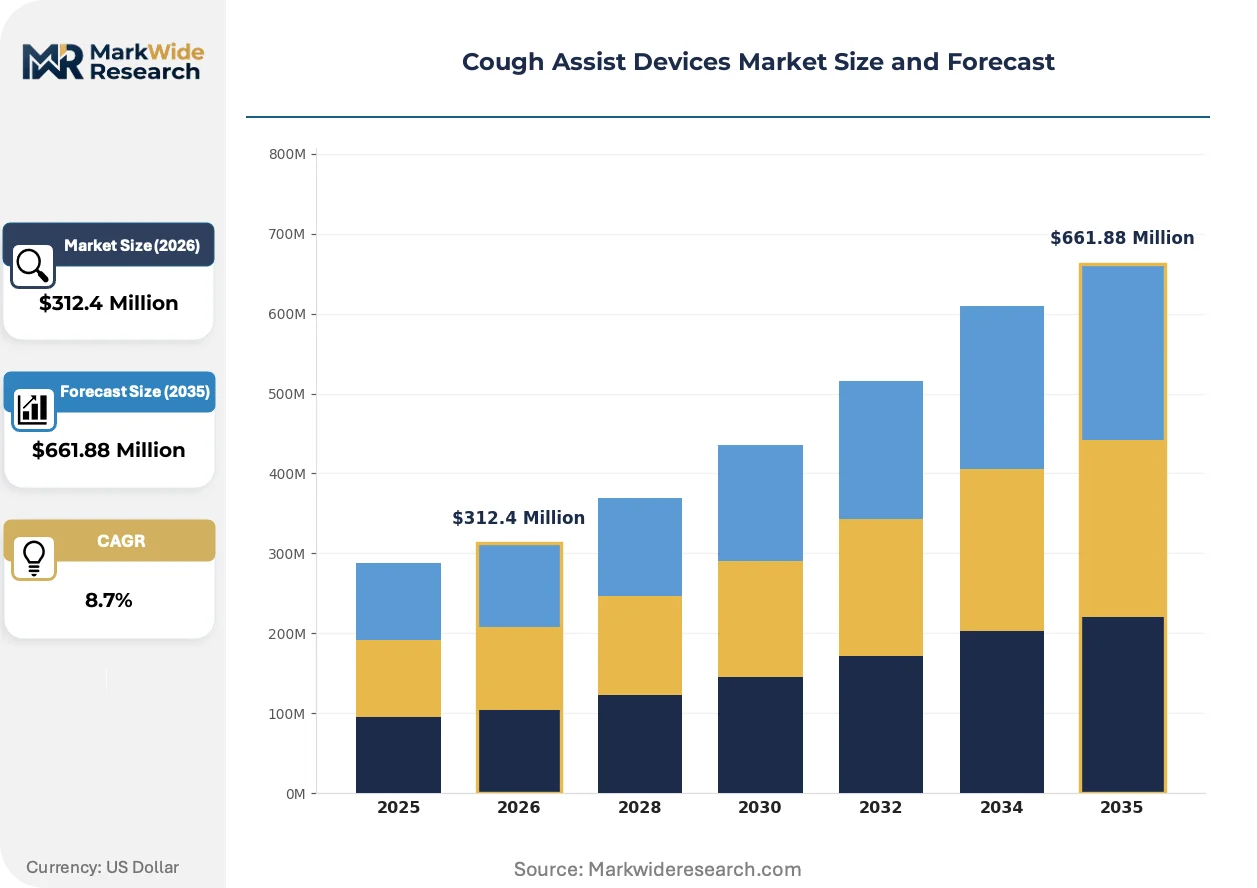
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Cough Stimulators, Manual Cough Assist Devices, Electromechanical Devices, Disposable Cough Aids End User: Hospitals, Home Care Settings, Rehabilitation Centers, Nursing Facilities Application: Chronic Respiratory Conditions, Neuromuscular Disorders, Post-Surgical Recovery, Pediatric Use Technology: Positive Airway Pressure, Oscillating Positive Expiratory Pressure, High-Frequency Chest Wall Oscillation, Others |
| Companies Covered | Koninklijke Philips N.V., Hill-Rom Holdings, Inc., Percussionaire Corp., Ventec Life Systems, Air Liquide Medical Systems, Dima Italia Srl, Baxter International Inc., West Care Medical, PARI GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cough Assist Devices Market Emerging Trajectories
Digital connectivity and algorithmic pressure modulation are transforming cough assist devices from isolated mechanical units into networked respiratory management nodes that feed longitudinal patient data into integrated care pathways.
Electromechanical cough assist platforms with programmable inspiratory-expiratory pressure ratios and real-time flow monitoring are overtaking purely mechanical devices in institutional procurement specifications. Hospital systems and long-term care networks prioritize units that capture treatment adherence metrics and automate pressure titration protocols. This capability compression is marginalizing mechanical stimulators to emergency backup roles and price-tiered emerging market segments.
The EU Medical Device Regulation's strengthened clinical evidence and post-market surveillance obligations are extending certification timelines for manufacturers seeking CE marking. Device sponsors must now compile systematic literature reviews and proactive vigilance systems that earlier directives did not mandate. Electromechanical platform developers with established quality management systems are absorbing these compliance costs more readily than mechanical device specialists with narrower regulatory footprints.
Home care providers are consolidating procurement authority through durable medical equipment leasing networks that bundle device placement with disposable component replenishment. Multi-state respiratory service organizations negotiate volume commitments that displace fragmented individual facility purchasing. This channel concentration is most visible across the United States, where Medicare reimbursement restructuring favors contracted supplier relationships over transactional equipment acquisition.
Cough Assist Devices Market Segmentation
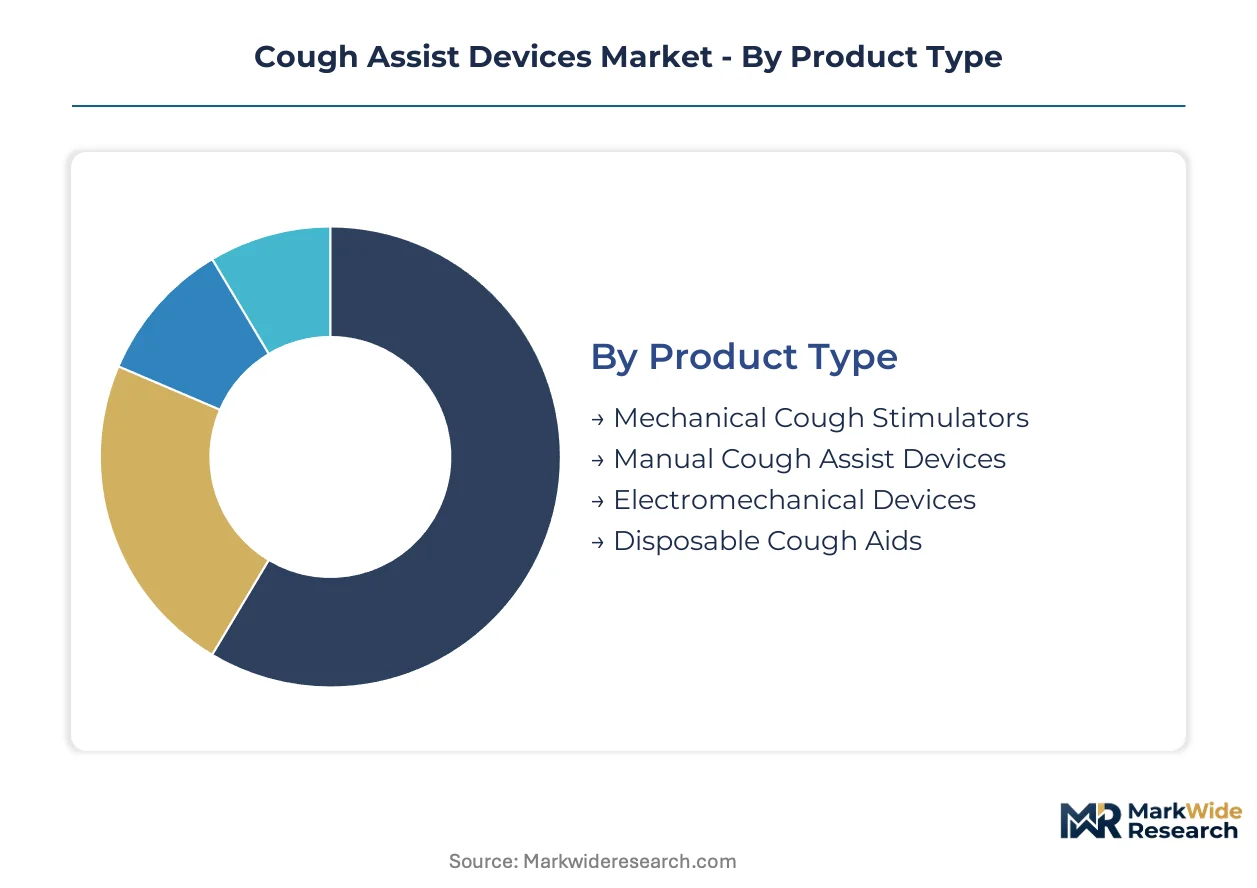
Cough assist devices fragment across four distinct taxonomies that reshape procurement priorities and regulatory pathways. Product type determines FDA clearance complexity, while end-user concentration shifts reimbursement leverage between institutional buyers and home care networks.
Product Type:
Electromechanical devices navigate FDA Class II 510(k) pathways with moderate clinical evidence burdens, while mechanical stimulators face lighter documentation requirements that accelerate emerging market entry.
- Electromechanical Devices:Programmable pressure cycling systems generate peak expiratory flows exceeding 160 liters per minute through automated insufflation-exsufflation sequences. Demand concentrates in United States hospital systems and German home care networks where respiratory therapist oversight enables longitudinal titration protocols.
- Mechanical Cough Stimulators:Pneumatic or spring-loaded devices deliver fixed-pressure cough simulation without electronic control modules. Price-sensitive institutional buyers in India and Brazil favor these units where reimbursement constraints limit capital equipment budgets.
- Manual Cough Assist Devices:Hand-operated bag-valve systems requiring caregiver compression for insufflation phase.
- Disposable Cough Aids:Single-use components including mouthpieces, tubing sets, and bacterial filters.
Electromechanical devices sit at the top of the volume ranking, with disposable cough aids climbing the fastest as recurring consumable purchases lock in manufacturer revenue streams.
End User:
Procurement authority concentrates differently across settings—hospitals leverage capital equipment budgets while home care providers negotiate bundled leasing arrangements with durable medical equipment suppliers.
- Home Care Settings:Decentralized patient management drives demand for portable units with compliance monitoring and telehealth integration. United States Medicare reimbursement restructuring favors contracted supplier relationships that displace fragmented facility purchasing.
- Hospitals:Acute care units require high-duty-cycle devices with rapid pressure modulation for intensive secretion management. German university hospitals and Japanese tertiary centers specify integrated ventilator-to-cough-assist platforms that reduce training burdens.
- Rehabilitation Centers:Post-acute respiratory therapy programs utilize mid-tier electromechanical units for weaning protocols.
- Nursing Facilities:Long-term care operators prioritize mechanical stimulators for cost containment in extended-stay populations.
Home care settings command the dominant procurement volume position, with rehabilitation centers gaining share fastest as post-acute care networks consolidate across the United States.
Application:
Clinical indication determines device specification intensity—neuromuscular disorders require sustained high-performance cycling while post-surgical applications tolerate shorter utilization windows.
- Neuromuscular Disorders:Amyotrophic lateral sclerosis and muscular dystrophy patient cohorts demand prolonged device utilization with recurring disposable component purchases. United States and Japan exhibit concentrated prevalence that sustains premium electromechanical platform adoption.
- Chronic Respiratory Conditions:Chronic obstructive pulmonary disease and bronchiectasis populations utilize cough assist adjunctively with standard bronchodilator therapy. German disease management programs integrate these devices into bundled respiratory care pathways.
- Post-Surgical Recovery:Thoracic and abdominal surgery patients require temporary secretion management during convalescence.
- Pediatric Use:Neonatal and juvenile patients need pressure-calibrated systems with adapted patient interfaces.
Neuromuscular disorders anchor the highest-margin application tier, with pediatric use expanding most quickly as congenital myopathy diagnosis improves.
Technology:
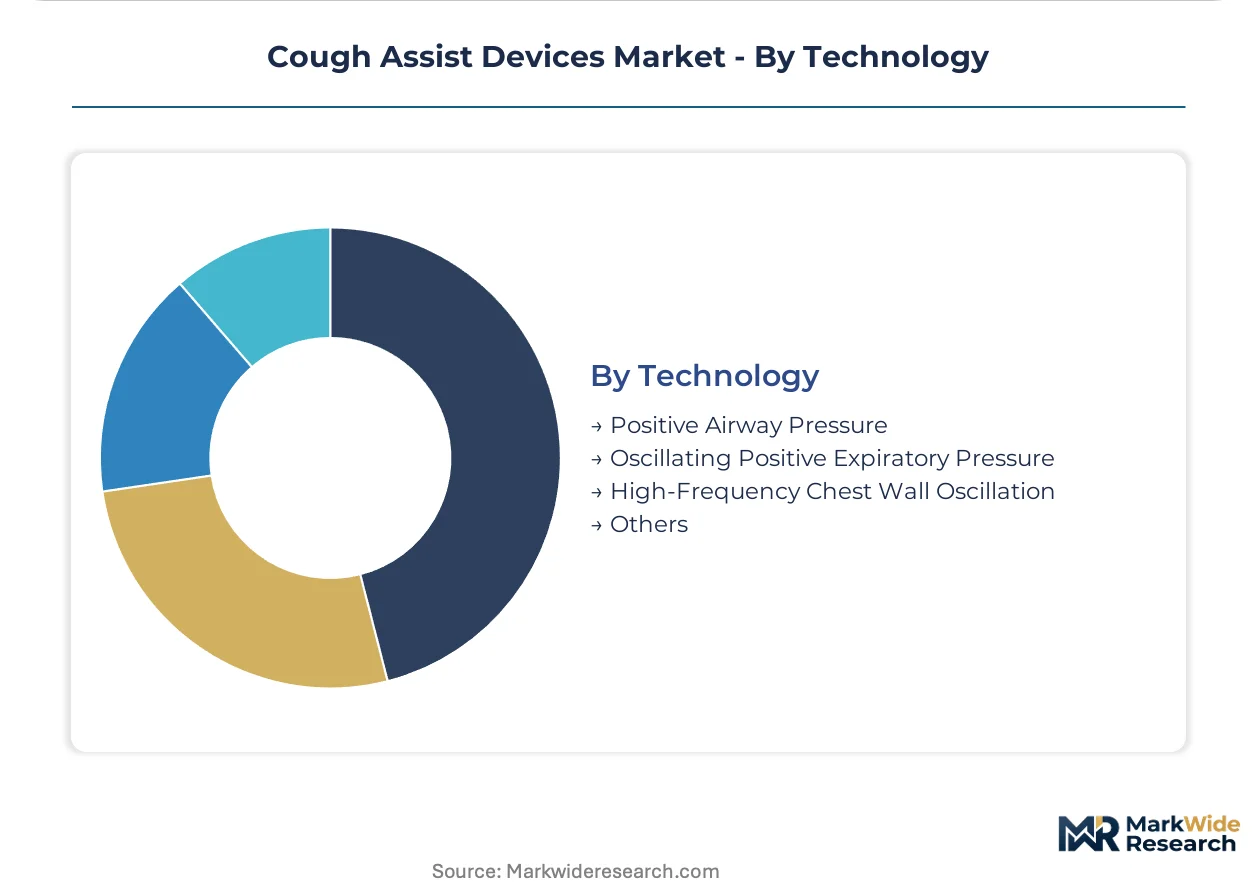
Technical modality selection reflects therapeutic objective—positive airway pressure dominates mechanical insufflation-exsufflation while oscillating alternatives compete for mucus mobilization indications.
- Positive Airway Pressure:Delivers preset inspiratory pressure followed by rapid negative pressure exsufflation to simulate natural cough mechanics. Institutional procurement specifications in the United States and Germany prioritize these systems for amyotrophic lateral sclerosis management.
- Oscillating Positive Expiratory Pressure:Generates airflow oscillations during exhalation to reduce mucus viscosity and promote peripheral airway clearance. Home care providers in Japan favor portable OPEP devices for cystic fibrosis patient self-management.
- High-Frequency Chest Wall Oscillation:External compression garment systems that mobilize secretions through chest wall vibration.
- Others:Intrapulmonary percussive ventilation and hybrid mechanical modalities.
Positive airway pressure technology holds the installed base leadership, with oscillating positive expiratory pressure gaining traction fastest in European home care markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany sustains more mature home care infrastructure for neuromuscular disease management than Japan, where tertiary hospital networks still dominate device procurement despite accelerating reimbursement reform.
United States
Medicare reimbursement restructuring and ALS patient advocacy networks drive home care adoption across the Midwest and Southeast corridors. The FDA's Class II 510(k) clearance pathway enables faster electromechanical device introductions than European alternatives. The Boston-Cambridge medical device cluster anchors respiratory technology development with established quality management systems.
Germany
Disease management programs for muscular dystrophy and bundled respiratory care pathways sustain institutional procurement volumes. The EU Medical Device Regulation's clinical evidence requirements extend certification timelines for CE-marked products. The Baden-Württemberg region concentrates precision electromechanical manufacturing capabilities serving domestic and export markets.
Japan
Aging demographics and concentrated ALS prevalence create sustained demand for high-performance secretion management systems. PMDA enforces stringent JIS electrical safety and biocompatibility testing that filters lower-capability entrants. The Kanto region around Tokyo hosts tertiary respiratory centers specifying integrated ventilator-to-cough-assist platforms.
United Kingdom
NHS long-term care commissioning frameworks are shifting procurement authority toward durable medical equipment leasing networks. MHRA post-Brexit regulatory alignment with EU MDR creates transitional compliance burdens for device sponsors. The Greater Manchester health innovation cluster pilots telehealth-integrated respiratory management programs.
India
Price-sensitive institutional buyers in thoracic surgery and post-ICU recovery favor mechanical stimulators over programmable electromechanical units. CDSCO medical device rules mandate import licensing and local testing for foreign-manufactured respiratory equipment. The Delhi-NCR corridor aggregates hospital procurement authority for multi-site respiratory service networks.
Cough Assist Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base fragments across three strategic layers: integrated respiratory platform developers, portable electromechanical specialists, and mechanical stimulator fabricators serving emerging markets. Dominant competitive moves include portfolio diversification into adjacent ventilation modalities and geographic expansion through durable medical equipment leasing partnerships.
Within the integrated platform tier, Koninklijke Philips N.V. and Hill-Rom Holdings, Inc. exemplify diversified medical technology conglomerates leveraging institutional channel relationships. Dima Italia Srl represents focused specialists navigating European home care reimbursement constraints. These three anchors demonstrate how scale advantages and geographic concentration shape competitive positioning across divergent regulatory environments.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Hill-Rom Holdings, Inc. |
| Percussionaire Corp. |
| Ventec Life Systems |
| Air Liquide Medical Systems |
| Dima Italia Srl |
| Baxter International Inc. |
| West Care Medical |
| PARI GmbH |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up durable medical equipment suppliers in the United States and Germany control leasing networks that compress manufacturer margins while locking in multi-year service contracts. This ownership concentration enables volume-based price negotiations that favor electromechanical platform bundling over standalone mechanical stimulator procurement.
Pricing Analysis
Capacity additions in China's precision electromechanical component sector are reshaping price floors for programmable cough assist platforms. Three-tier pricing structure across premium electromechanical, standard mechanical, and economy manual devices dominates procurement specifications. Price differentiation rests on FDA Class II 510(k) certification tier and respiratory therapist training bundling. Cost compression in mechanical stimulators is intensifying because CDSCO import licensing requirements in India favor domestic fabricators. Home care networks exhibit highest price sensitivity; Japanese tertiary hospitals show lowest.
Supply Chain Analysis
Refurbishment flows for electromechanical devices concentrate in Germany's Baden-Württemberg region and the United States' Boston-Cambridge corridor, where original manufacturers recapture patient circuits and control modules. Supply chains draw from Taiwan for pressure sensors, Germany for precision pneumatics, and Japan for biocompatible polymers. Single-source vulnerability sits with Taiwanese semiconductor components for flow-monitoring chipsets. Distribution runs through durable medical equipment leasing networks that bundle device placement with disposable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cough assist devices market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations requiring prolonged neuromuscular respiratory management.
For Market Incumbents: Hedge against manual airway clearance substitution in emerging markets by deepening backward integration into pressure sensor manufacturing and securing exclusive GPO contracts with United States hospital systems. Certification investment in Japan's PMDA JIS electrical safety tier protects premium positioning against lower-cost Asian entrants. Channel control through respiratory therapist training academies locks in titration protocol loyalty. For New Entrants and Emerging Players: Capture underpenetrated rural United States home care segments where telehealth-integrated platforms displace episodic emergency department visits. Pediatric congenital myopathy applications offer the most penetrable clinical entry point given improving diagnostic rates. A reimbursement-first go-to-market angle targeting evolving HCPCS billing code clarity reduces patient out-of-pocket friction. For Investors and Strategic Acquirers: Valuations sit cheapest among European portable electromechanical specialists navigating EU MDR clinical evidence cost absorption. Long-term viability over a 5-10 year window rests on ventilator-to-cough-assist convergence platforms that reduce capital duplication for long-term care facilities. Monitor FDA 510(k) clearance velocity for electromechanical devices as inflection indicator for competitive entry dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined Class II clearance accelerates electromechanical platform introductions versus PMA timelines. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend certification timelines but filter lower-capability competitors. |
| Hospital System Partnership | Integrated ventilator-to-cough-assist platforms reduce training burdens across German university hospital networks. |
| Software Companion Development | Telehealth-integrated compliance monitoring enables longitudinal respiratory therapist oversight without institutional admission. |
| Reimbursement Strategy | HCPCS and CPT code expansion creates billing clarity that reduces patient out-of-pocket exposure in United States home care. |
Methodological Framework
Multiple input streams — regulatory filing databases, hospital procurement contract registries, and durable medical equipment leasing records — were reconciled through primary interviews with respiratory therapists, biomedical engineers, GPO contracts managers, and home care network procurement directors. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body certification records, CMS Medicare reimbursement data, and Japanese PMDA approval filings. Bottom-up unit shipment modeling and top-down market sizing triangulated volume estimates.
Historical shipment trajectories were cross-referenced against expert panel assessments to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, end-user setting, clinical application, and regional regulatory cluster. CAGRs were derived from iterative convergence between epidemiological disease prevalence projections and device replacement cycle analysis. Forecast inputs incorporated ALS patient cohort survival curves and Medicare reimbursement restructuring timelines.
Underlying measurement precision varies by segment; electromechanical device unit shipments carry tighter precision than mechanical stimulator estimates due to consolidated manufacturer reporting. Forecasts reflect documented assumptions about regulatory clearance velocity and home care reimbursement code evolution. Practitioners should monitor FDA 510(k) submission backlogs and EU MDR notified body capacity constraints for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Bionic Implant Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Embolic Protection Systems Market
Medical Devices
Cervical Retractors Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Quadripodal Implants Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Injectable Bone Graft Substitutes Market
Medical Devices
Electroencephalography Devices Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market