
 UK Artificial Organs and Bionic Implants Market | 2026-2036
UK Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
UK Artificial Organs and Bionic Implants Market Analytics
Project finance partnerships between NHS trusts and device manufacturers is tilting procurement toward long-term service contracts rather than capital-intensive ownership models. Edwards Lifesciences Corporation leverages its transcatheter heart valve expertise to anchor premium positioning within NHS cardiac pathways. Medtronic competes through vertically integrated manufacturing that sustains cost advantages across its neuromodulation portfolio. Cochlear Ltd specializes in auditory implant systems that dominate paediatric referral networks across UK cochlear implant programmes.
Artificial organs and bionic implants encompass electromechanical and biological systems designed to replace or augment native physiological functions, typically incorporating biocompatible alloys, polymer matrices, and integrated sensor arrays manufactured through precision machining and additive layer techniques. These devices restore motor, sensory, or organ-level performance in patients with irreversible tissue damage or congenital deficits. Cardiac devices occupy the largest value pool given the procedural complexity and reimbursement weighting of ventricular assist systems and total artificial hearts within NHS tariff structures. Neuroprosthetics represent the fastest-expanding category as peripheral nerve interfaces and brain-computer interface technologies migrate from research institutions into outpatient clinic settings. Biocompatible polymers command margin premiums over metals and ceramics due to their tunable degradation profiles and reduced fibrotic encapsulation in chronic implantation scenarios.
The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements that dictate clinical evidence standards for permanent implantable devices, while NHS England's specialised commissioning frameworks determine which procedures receive national funding and which remain locally negotiated. MHRA alignment with EU MDR transitional provisions maintains continuity for manufacturers previously certified under notified body routes, though divergence timelines create planning uncertainty for quality system investments. Stakeholders must monitor how MHRA's future recognition agreements with FDA and Health Canada reshape competitive access for US and Canadian device firms seeking UK market entry.
Market Dynamics
NHS England's specialised commissioning frameworks are compressing procurement cycles for high-value implantable devices while simultaneously fragmenting purchasing authority across integrated care boards. This structural tension between centralised funding eligibility and distributed procurement decision-making is reshaping how manufacturers access the UK market.
Growth Catalysts
- MHRA Streamlined Pathways:The Medicines and Healthcare products Regulatory Agency's accelerated access pathways for breakthrough devices reduce time-to-market for novel cardiac and neuroprosthetic technologies. Manufacturers gain earlier revenue recognition on ventricular assist systems and cochlear implants.
- Expanded NHS Coverage:NHS England's revised specialised services contracts now fund advanced prosthetic procedures previously restricted to trauma and cancer patients. This broadens addressable patient populations for bionic limb and auditory implant providers.
- Greater London Cluster Density:Tertiary cardiac centres in Greater London concentrate complex ventricular assist device implantation volumes that generate referral network effects. Teaching hospitals in this cluster train specialists who diffuse techniques to regional centres.
Market Restraints
- Biocompatible Polymer Supply Concentration:Medical-grade polymer feedstocks for chronic implantation applications concentrate among a limited set of European and North American chemical suppliers. Price volatility in fluoropolymers and silicone matrices compresses device margins.
- MHRA-MDR Divergence Timeline:Uncertainty around future UKCA marking recognition agreements with EU notified bodies creates compliance planning risk. Manufacturers face duplicated quality system investments pending clarity on mutual recognition.
- Chronic Fibrotic Encapsulation:Long-term implant performance degrades due to immune-mediated fibrotic responses that remain incompletely addressed by current surface engineering. This technical limitation necessitates costly revision surgeries and dampens patient lifetime value.
Strategic Opportunities
- Paediatric Cochlear Expansion:Underpenetrated referral pathways in Northern England and Scotland present volume growth for auditory implant programmes. NHS Scotland's distinct commissioning structures offer faster adoption curves for bilateral implantation protocols.
- Brain-Computer Interface Migration:Convergence of neural signal processing hardware with minimally invasive electrode arrays enables outpatient clinic deployment of motor neuroprosthetics. This technology pairing reduces infrastructure requirements for peripheral nerve interface procedures.
- Long-Term Service Contracts:Project finance partnerships between NHS trusts and device manufacturers displace capital purchase models with performance-based agreements. This channel innovation aligns manufacturer incentives with patient outcome metrics.
Industry Challenges
- Bioelectronics Manufacturing Talent Scarcity:Precision machining and additive layer fabrication of integrated sensor arrays requires specialised cleanroom technicians. UK training pipelines for microfabrication skills lag device development timelines.
- UKCA Transition Certification Burden:Legacy devices previously CE-marked under EU MDR require renewed clinical evidence packages for MHRA approval. This recertification timeline compresses revenue continuity for established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Artificial Organs and Bionic Implants Market |
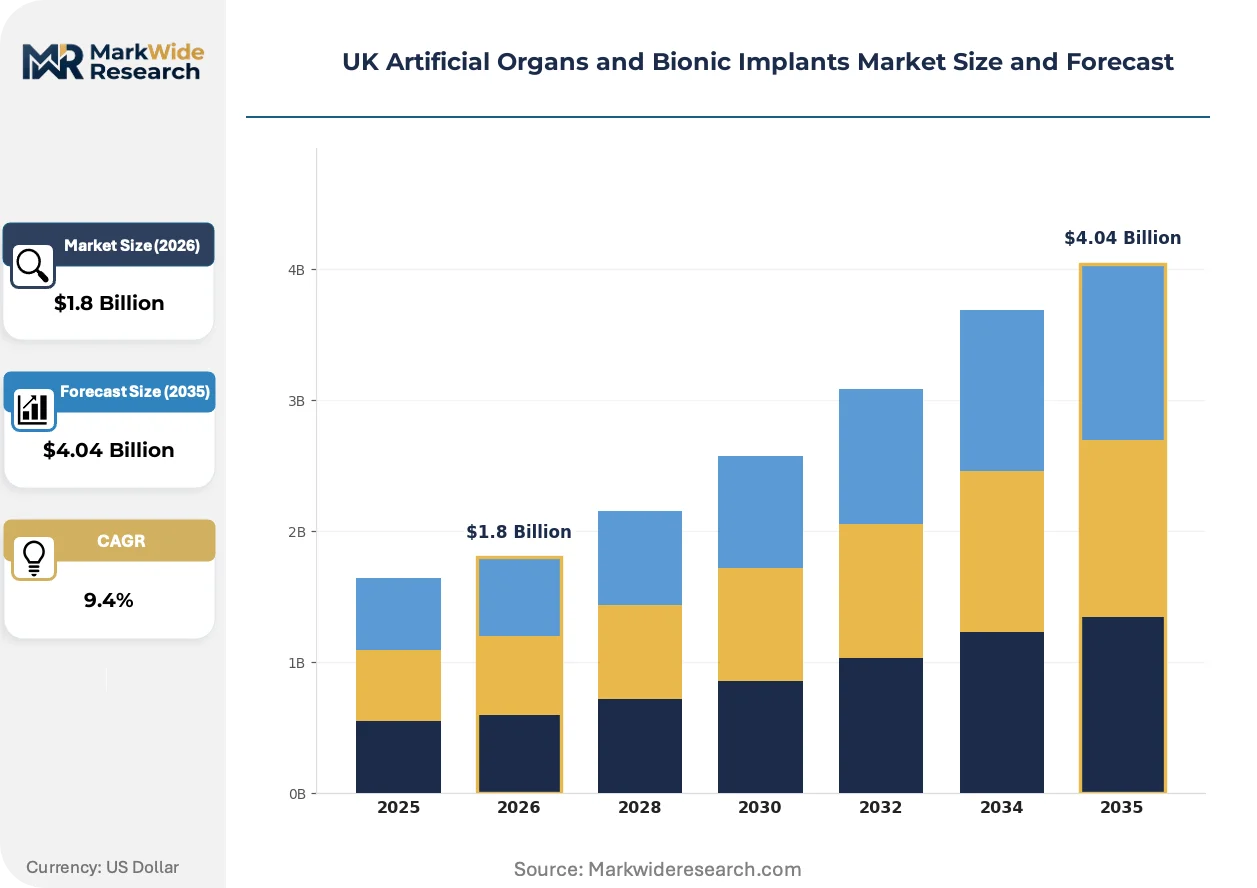
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Devices, Renal Devices, Neuroprosthetics, Vision Implants Material: Biocompatible Polymers, Metals, Ceramics, Composite Materials End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Research Institutions Technology: Artificial Intelligence, Robotics, Biosensors, 3D Printing |
| Companies Covered | Edwards Lifesciences Corporation, Abiomed Inc, Medtronic, Berlin Heart, Jarvik Heart Inc, Ekso Bionics, Abbott, Cochlear Ltd, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Artificial Organs and Bionic Implants Market Evolving Landscape
Sensor-integrated implantable systems are displacing passive mechanical devices across cardiac and neurological applications. This instrumentation shift generates continuous physiological data streams that enable predictive intervention models.
Additive manufacturing of patient-specific titanium lattice structures is digitizing orthopaedic and craniofacial implant production. NHS trusts in Greater Manchester and Birmingham are adopting point-of-care printing for complex reconstructive cases. This distributed fabrication model compresses supply chains from months to days while enabling anatomical matching previously unattainable with standard inventory.
MHRA alignment with EU MDR transitional provisions maintains temporary market access for devices certified under notified body routes. Manufacturers are dual-running quality systems pending definitive divergence timelines. Cardiac device categories face the most acute compliance uncertainty given their reliance on pan-European clinical trial networks.
Integrated care boards are consolidating procurement authority previously dispersed across individual NHS trusts. This buyer concentration forces manufacturers to reconfigure sales organisations around regional account structures. The shift is most visible in neurostimulator purchasing, where Thames Valley and Wessex ICBs have pioneered multi-year framework agreements.
UK Artificial Organs and Bionic Implants Market Segmentation
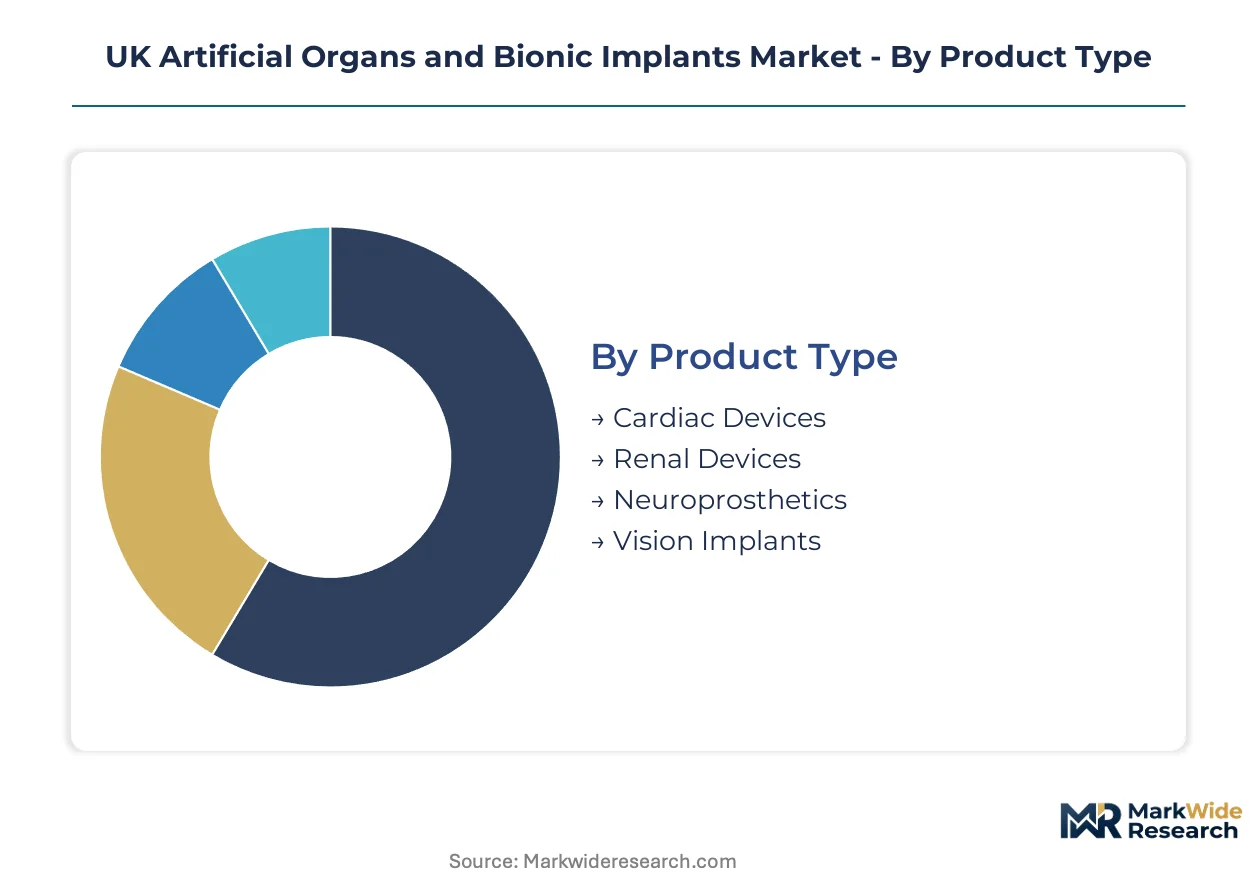
Segmentation reveals how NHS procurement patterns and MHRA regulatory pathways create distinct commercial corridors across implantable technologies. Manufacturers must align product portfolios with the specific reimbursement weights and clinical evidence requirements governing each category.
Product Type:
Mature ventricular assist systems anchor procurement volumes while emerging neuroprosthetic platforms reshape referral pathways across UK specialised commissioning networks.
- Cardiac Devices:Ventricular assist devices and total artificial hearts incorporate biocompatible alloys and integrated sensor arrays for haemodynamic monitoring. Greater London's tertiary cardiac centres concentrate implantation volumes that generate surgeon training network effects and influence NHS tariff negotiations.
- Neuroprosthetics:Peripheral nerve interfaces and brain-computer interface systems restore motor and sensory function through implanted electrode arrays. Outpatient clinic deployment in Thames Valley and Wessex ICBs accelerates as minimally invasive insertion techniques reduce infrastructure requirements.
- Renal Devices:Wearable and implantable artificial kidney systems address end-stage renal failure through continuous filtration membranes. NHS England's specialised services contracts currently limit coverage to haemodialysis-dependent populations in specific integrated care board catchments.
- Vision Implants:Retinal prosthesis systems and cortical visual implants translate camera inputs into neural stimulation patterns. Moorfields Eye Hospital and Oxford University Hospitals anchor the limited UK referral networks for these experimental procedures.
Cardiac devices handle the majority of throughput; neuroprosthetics is climbing the fastest on share.
Material:
Cost tier stratification separates premium polymer formulations from commodity metal feedstocks, with margin compression most acute in standard-grade titanium and cobalt-chrome alloys.
- Biocompatible Polymers:Silicone matrices and fluoropolymer coatings enable tunable degradation profiles that reduce fibrotic encapsulation in chronic implantation scenarios. Paediatric cochlear implant programmes in NHS Scotland prioritise these materials for bilateral implantation protocols given their reduced inflammatory response.
- Metals:Titanium and cobalt-chrome alloys provide structural integrity for orthopaedic and craniofacial implants through precision machining and additive layer fabrication. Greater Manchester NHS trusts have adopted point-of-care printing of patient-specific titanium lattice structures for complex reconstructive cases.
- Ceramics:Alumina and zirconia compositions offer wear resistance in load-bearing articulating surfaces. Supply concentration among European chemical suppliers creates procurement vulnerability for UK device manufacturers.
- Composite Materials:Polymer-ceramic and metal-polymer hybrids combine mechanical properties across application requirements. These formulations command development investment from manufacturers seeking differentiation in revision surgery markets.
Biocompatible polymers capture the premium pricing tier; composite materials are expanding most quickly as formulation science advances.
End User:
Customer type concentration in NHS hospital trusts contrasts with emerging volume migration toward outpatient clinics as minimally invasive techniques reduce procedural infrastructure requirements.
- Hospitals:Tertiary cardiac centres and teaching hospitals perform complex ventricular assist device implantations and multi-stage reconstructive procedures. These institutions anchor NHS England's specialised commissioning frameworks and determine national funding eligibility.
- Outpatient Clinics:Peripheral nerve interface procedures and cochlear implant programming increasingly occur outside inpatient settings. Thames Valley and Wessex ICBs have pioneered multi-year framework agreements for neurostimulator purchasing through consolidated procurement authority.
- Rehabilitation Centers:Post-implant physiotherapy and device calibration services support functional recovery for bionic limb and auditory implant recipients. Northern England referral pathways remain underpenetrated relative to Greater London and South East clusters.
- Research Institutions:University hospitals and academic medical centres host clinical trials for breakthrough devices accessing MHRA accelerated approval pathways. These sites generate the clinical evidence packages required for UKCA marking of novel implantable technologies.
Hospitals handle the majority of throughput; outpatient clinics are gaining share fastest as procedure complexity migrates downstream.
Technology:
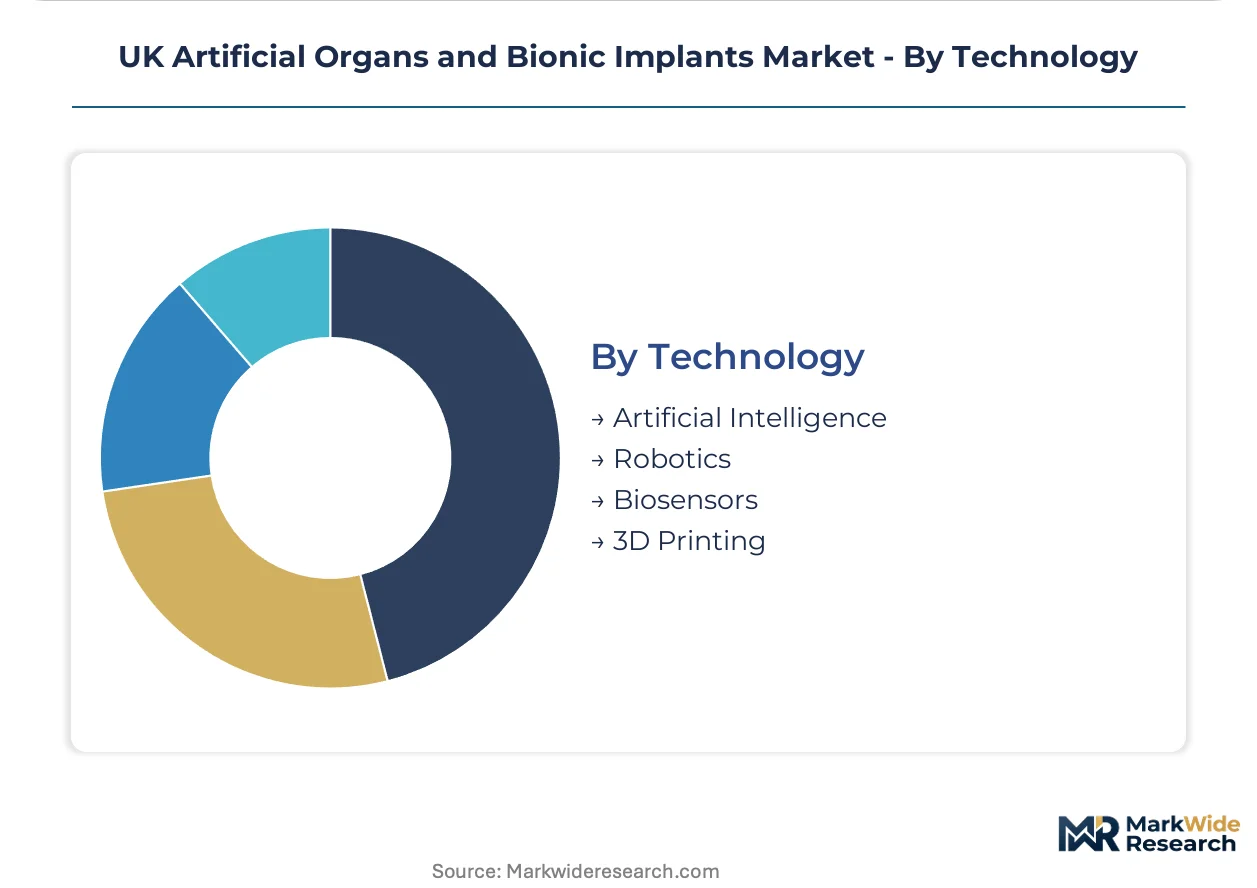
Application focus separates continuous monitoring platforms from fabrication methods, with integration across these technology layers determining competitive positioning.
- Artificial Intelligence:Neural signal processing algorithms interpret physiological data streams from implanted sensor arrays. These systems enable predictive intervention models that reduce emergency revision surgery rates.
- Robotics:Surgical robot platforms enhance precision in electrode array placement and microvascular anastomosis for artificial organ implantation.
- Biosensors:Integrated glucose, oxygen, and pressure sensors generate real-time physiological feedback from chronic implants. MHRA clinical evidence standards for permanent implantable devices mandate specific performance thresholds for these components.
- 3D Printing:Additive manufacturing of patient-specific anatomical models and implantable lattice structures compresses supply chains from months to days. Birmingham NHS trusts have adopted distributed fabrication for craniofacial reconstruction cases.
Biosensors handle the majority of integration requirements; artificial intelligence is climbing the fastest on development investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHS England's specialised commissioning frameworks determine funding eligibility and procurement authority across UK regions, creating distinct commercial corridors for implantable device manufacturers.
Greater London
Tertiary cardiac centres in this cluster concentrate complex ventricular assist device implantation volumes that generate surgeon training network effects. Guy's and St Thomas' NHS Foundation Trust anchors national referral pathways for total artificial heart procedures. The concentration of teaching hospitals here diffuses techniques to regional centres across England.
Scotland
NHS Scotland's distinct commissioning structures offer faster adoption curves for bilateral cochlear implantation protocols in paediatric populations. The Scottish Health Technologies Group accelerates health technology assessment timelines relative to England. Edinburgh and Glasgow host the principal auditory implant programmes serving Northern England overflow demand.
Midlands
Birmingham NHS trusts have pioneered point-of-care additive manufacturing of patient-specific titanium lattice structures for craniofacial reconstruction. University Hospitals Birmingham NHS Foundation Trust hosts one of three UK centres for ventricular assist device implantation. The region's medical device manufacturing heritage supports local supply chain integration.
Wales
Health Technology Wales operates distinct reimbursement assessment pathways that diverge from NICE processes in England. Cardiff and Vale University Health Board anchors specialised cardiac services for South Wales populations. The Welsh Government's life sciences investment strategy targets neuroprosthetic research commercialisation.
Northern England
Underpenetrated cochlear implant referral pathways in this region present volume growth opportunities for auditory implant programmes. Newcastle upon Tyne Hospitals NHS Foundation Trust leads Northern specialised commissioning for complex cardiac devices. Manchester University NHS Foundation Trust is consolidating procurement authority previously dispersed across individual trusts.
UK Artificial Organs and Bionic Implants Market Competitive Landscape
On the supply side, the industry is consolidating around cardiac device specialists with established NHS procurement relationships and emerging neuroprosthetic entrants accessing MHRA accelerated pathways. Three archetypes dominate: multinational cardiovascular conglomerates with vertically integrated manufacturing, auditory implant specialists with paediatric referral network dominance, and bionic limb innovators transitioning from research to outpatient deployment. Competitive moves centre on long-term service contract negotiations with integrated care boards and additive manufacturing partnerships with NHS trusts for patient-specific implant production.
Among cardiovascular device manufacturers, Edwards Lifesciences Corporation and Medtronic occupy positions reflecting distinct strategic emphases. Edwards Lifesciences Corporation exemplifies premium-tier positioning anchored in transcatheter heart valve expertise within NHS cardiac pathways. Medtronic represents scale-driven manufacturing integration sustaining cost advantages across implantable portfolios. Cochlear Ltd sits within the auditory implant specialist archetype, with its dominance of UK paediatric cochlear implant programmes reflecting concentrated referral network control.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Abiomed Inc |
| Medtronic |
| Berlin Heart |
| Jarvik Heart Inc |
| Ekso Bionics |
| Abbott |
| Cochlear Ltd |
| Boston Scientific Corporation |
| Others |
Value Network & Pricing Analysis
Greater Manchester's additive manufacturing cluster concentrates point-of-care titanium printing capacity that compresses craniofacial implant lead times from months to days, granting NHS trusts procurement leverage over traditional inventory-based suppliers. This geographic production density reshapes pricing power across patient-specific orthopaedic segments.
Pricing Analysis
Certification level (UKCA/CE/FDA-grade) creates the primary spread between premium cardiac devices and standard-tier alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by biocompatible polymer grade and integrated sensor sophistication. Cost compression in standard-grade titanium alloys is intensifying because Greater London ICBs consolidate neurostimulator purchasing into multi-year frameworks. NHS specialised commissioning committees exhibit highest price sensitivity; private referral networks in Harley Street clusters show lowest.
Supply Chain Analysis
Export-control regimes restricting dual-use bioelectronics technology limit flows of neural signal processing hardware from US and Japanese suppliers into UK manufacturing. Medical-grade fluoropolymer feedstocks draw from German and US chemical producers; titanium sponge sources from Chinese and Russian smelters. Single-source vulnerability concentrates in silicone matrices for paediatric cochlear implants. Distribution runs through NHS Supply Chain national frameworks with regional ICB deviation for specialised cardiac devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across integrated care board procurement authority creates niches for differentiated positioning, as NHS England's specialised commissioning reforms devolve purchasing decisions to 42 distinct ICB structures.
For Market Incumbents: Insulate cardiac device margins through captive supply of biocompatible polymers and exclusive surgeon training networks at Guy's and St Thomas' NHS Foundation Trust. Secure UKCA marking ahead of MHRA-EU MDR divergence timelines. Lock in long-term service contracts with Thames Valley and Wessex ICBs before competitor replication. For New Entrants and Emerging Players: Northern England's underpenetrated cochlear implant referral pathways offer volume entry with lower competitive density than Greater London clusters. Target NHS Scotland's faster health technology assessment timelines for bilateral paediatric protocols. Lead with brain-computer interface outpatient deployment to bypass capital-intensive hospital infrastructure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement authority concentration across ICBs will favour scaled service-contract negotiators over point-product vendors. Target mid-cap auditory implant specialists with established NHS Scotland relationships. Monitor MHRA recognition agreement announcements with FDA and Health Canada as inflection signals for US market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Accelerated Access Pathway Submission | Compresses time-to-market for novel ventricular assist systems ahead of tariff negotiations. |
| ICB Long-Term Service Contract Negotiation | Aligns manufacturer incentives with NHS outcome metrics across neuroprosthetic portfolios. |
| Point-of-Care Additive Manufacturing Partnership | Enables patient-specific titanium lattice production at Birmingham and Manchester trusts. |
| Paediatric Cochlear Bilateral Implantation Protocol | Captures NHS Scotland's faster adoption curves relative to England commissioning. |
| Brain-Computer Interface Outpatient Deployment | Reduces infrastructure barriers for peripheral nerve interface procedures in Thames Valley. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across NHS specialised commissioning leads, cardiac surgeons at tertiary centres, biomedical engineers, GPO contracts managers, and MHRA regulatory affairs specialists. Secondary validation drew from NHS England specialised services contracts, MHRA UKCA marking databases, hospital procurement records, and integrated care board framework agreements. Bottom-up implant volume estimates triangulated against top-down NHS tariff expenditure analysis.
Calibration against historical NHS procurement cycles and MHRA approval timelines anchored projections across the analysis window. Segmentation modeling spanned product type, material grade, end-user setting, and technology layer with regional ICB clustering. CAGRs derived from procedure volume trajectories, reimbursement weighting shifts, and technology substitution curves. Neural signal processing hardware cost declines and biocompatible polymer supply constraints fed sensitivity scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by US cardiovascular conglomerates or Chinese additive manufacturing entrants would shift outcomes. Cross-checking against NHS England's annual specialised services commissioning intentions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
EEG Amplifiers Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Global Medical Loupes Market
Medical Devices
Medical Polyetheretherketone Market
Medical Devices
Transport Chairs Market
Medical Devices
Germany Artificial Organs and Bionics Market
Medical Devices
Ambulatory Aids Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Global Medical Composite Market
Medical Devices
Europe Implantable Medical Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
US Orthopedic Spine Navigation Systems Market
Medical Devices
Male Artificial Urinary Sphincter Market
Medical Devices
Global Implantable Loop Recorder Market
Medical Devices
Digital X-Ray Devices Market
Medical Devices
North America Wearable Medical Devices Market