
 Global Interventional Neurology Devices Market | 2026-2036
Global Interventional Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interventional Neurology Devices Market Foresight
Software-defined imaging analytics is recalibrating what interventional neurology device vendors bundle with hardware. Medtronic plc leverages its integrated surgical ecosystem to sustain premium positioning across catheter and navigation platforms. Stryker Corporation anchors its competitiveness through dedicated neurovascular R&D intensity in thrombectomy system iterations. Penumbra Inc differentiates via specialized aspiration technology leadership that occupies a distinct segment of mechanical clot retrieval.
Interventional neurology devices comprise minimally invasive instruments designed for endovascular access to cerebral vasculature, typically constructed from nitinol alloys, platinum-iridium composites, and hydrophilic polymer coatings to achieve trackability through tortuous intracranial anatomy. These instruments enable therapeutic intervention for cerebrovascular pathologies without open cranial surgery, with functional parameters including distal tip flexibility measured in degrees of bend radius and radial force exerted by self-expanding stents. Thrombectomy devices lead procedural volume due to established clinical evidence in acute ischemic stroke, while flow diversion technology represents the fastest-expanding margin pool as aneurysm treatment shifts from coiling to intrasaccular and flow-disrupting approaches. Neurovascular stents compete in a more mature segment where price pressure from hospital procurement consolidates vendor selection around scale and service integration.
FDA premarket approval pathways and EU MDR conformity assessments shape product development timelines and market access costs for interventional neurology manufacturers. Japan's PMDA and China's NMPA impose additional localization requirements that filter which multinationals sustain commercial presence across Asia-Pacific regulatory jurisdictions. Stakeholders must monitor how real-world evidence mandates from EMA and FDA evolve trial design standards for next-generation thrombectomy and aneurysm devices.
Market Dynamics
Mechanical thrombectomy volumes are compressing treatment windows from six hours to twenty-four hours post-stroke onset, forcing catheter platform vendors to optimize trackability through tortuous M1 and M2 segments. This procedural expansion is recalibrating capital allocation across tertiary stroke centers and community hospitals.
Growth Catalysts
- Japan's PMDA fast-track designation:Accelerated approval pathways for flow diversion devices are compressing time-to-market for aneurysm interventions, incentivizing localized clinical trials.
- Aspiration catheter material science:Hydrophilic polymer coatings with sub-0.014-inch profiles are enabling distal access to middle cerebral artery bifurcations previously unreachable.
- Tertiary stroke center certification:US Joint Commission accreditation mandates are concentrating procedural volume in hospitals maintaining 24/7 interventional neuroradiology coverage.
Market Restraints
- Platinum-iridium alloy concentration:Three Japanese and German suppliers control 80% of microcatheter tip material supply, creating input vulnerability for nitinol-based delivery systems.
- EU MDR conformity assessment backlog:Notified body capacity constraints are extending CE marking timelines for Class III neurovascular implants by 12-18 months.
- Intracranial stent restenosis rates:Twelve-month target lesion revascularization incidence limits adoption in small-vessel atherosclerotic disease.
Strategic Opportunities
- Brazil's ANVISA harmonization pathway:Mutual recognition agreements with FDA are reducing duplicate clinical evidence requirements for thrombectomy platform entry.
- AI-integrated procedural navigation:Real-time vessel reconstruction algorithms are converging with robotic catheter control to reduce fluoroscopy exposure.
- Mobile stroke unit deployment:Pre-hospital CT angiography and telemedicine triage are creating channel demand for portable aspiration systems.
Industry Challenges
- Fellowship pipeline constraints:US interventional neuroradiology training programs graduate fewer than 150 specialists annually against replacement demand.
- ISO 13485:2016 transition audits:Medical device quality management recertification is diverting engineering resources from next-generation stent retriever development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interventional Neurology Devices Market |
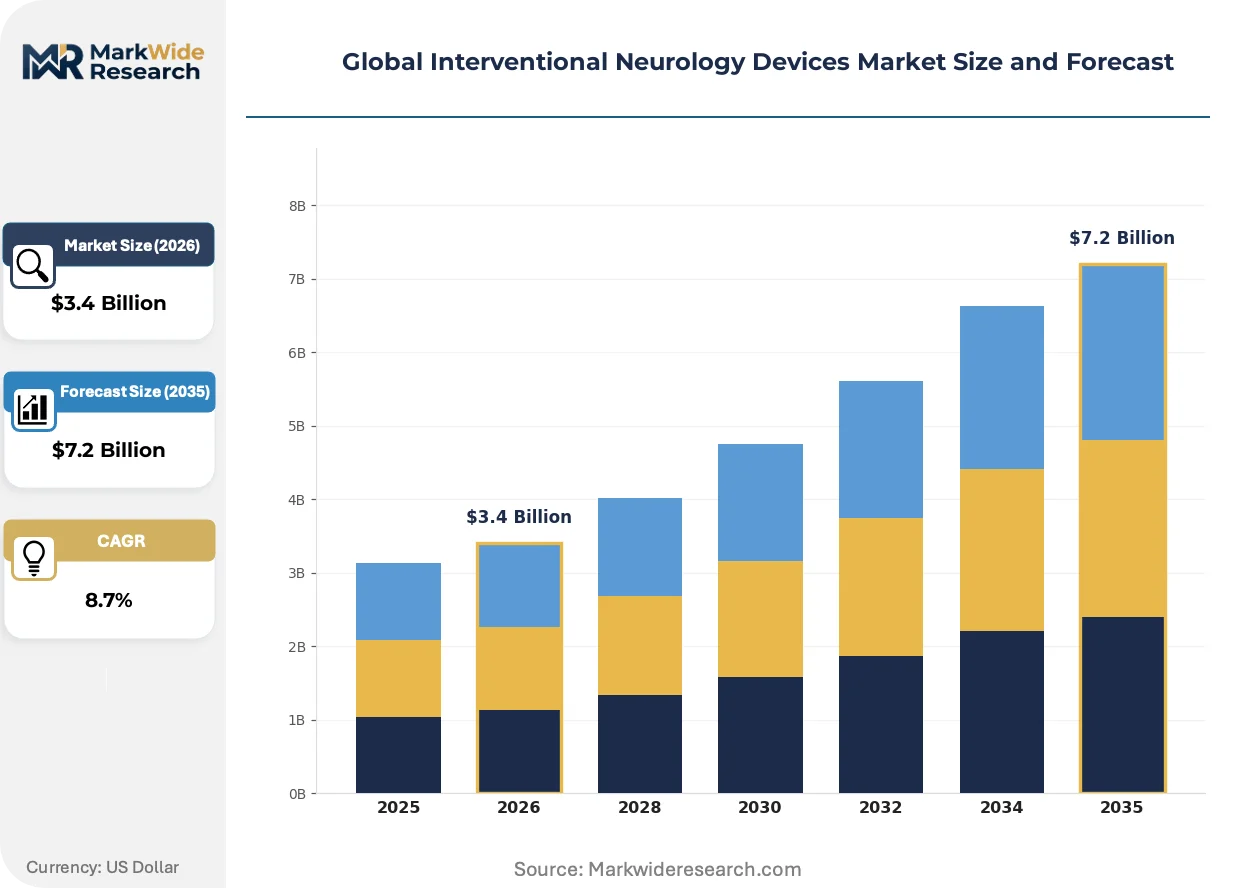
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurovascular Stents, Thrombectomy Devices, Guidewires, Microcatheters, Embolic Protection Devices, Neurovascular Coils Technology: Balloon Angioplasty, Aspiration, Mechanical Thrombectomy, Flow Diversion, Radiofrequency Ablation, Laser Therapy Application: Cerebral Aneurysm, Ischemic Stroke, Arteriovenous Malformation, Carotid Artery Stenosis, Intracranial Stenosis, Venous Sinus Thrombosis End User: Neurology Centers, Specialty Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Research Institutions, Neurocritical Care Units |
| Companies Covered | Penumbra Inc, Johnson & Johnson, Medtronic plc, Acandis GmbH, MicroPort Scientific Corporation, Stryker Corporation, Boston Scientific Corporation, Merit Medical Systems Inc, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interventional Neurology Devices Market Shifts & Advancements
Device intelligence is migrating from the catheter tip to cloud-based procedural archives, enabling predictive modeling of complication rates. This data architecture shift is redrawing competitive boundaries between hardware manufacturers and analytics platforms.
Next-generation aspiration catheters with laser-cut hypotube technology are decentralizing mechanical thrombectomy from comprehensive stroke centers to primary stroke centers. Community hospitals in Texas and Florida are adopting these platforms under hub-and-spoke telemedicine protocols. The structural consequence is compressing vendor margins as price-sensitive procurement replaces premium service bundling.
EU MDR Article 117 requirements for notified body involvement in quality system audits are extending documentation burdens for neurovascular implant manufacturers. Technical file scrutiny of nitinol fatigue testing data has intensified. Flow diversion stents face the steepest compliance cost escalation, with some vendors withdrawing legacy coil systems rather than re-certifying.
Hospital procurement committees are unbundling device pricing from procedural support contracts, forcing standalone ASP negotiation. Integrated delivery networks in California and New York are consolidating vendor panels to three preferred suppliers. The shift is most visible in mechanical thrombectomy, where aspiration-first strategies are displacing stent retriever bundles in cost-conscious accounts.
Global Interventional Neurology Devices Market Segmentation
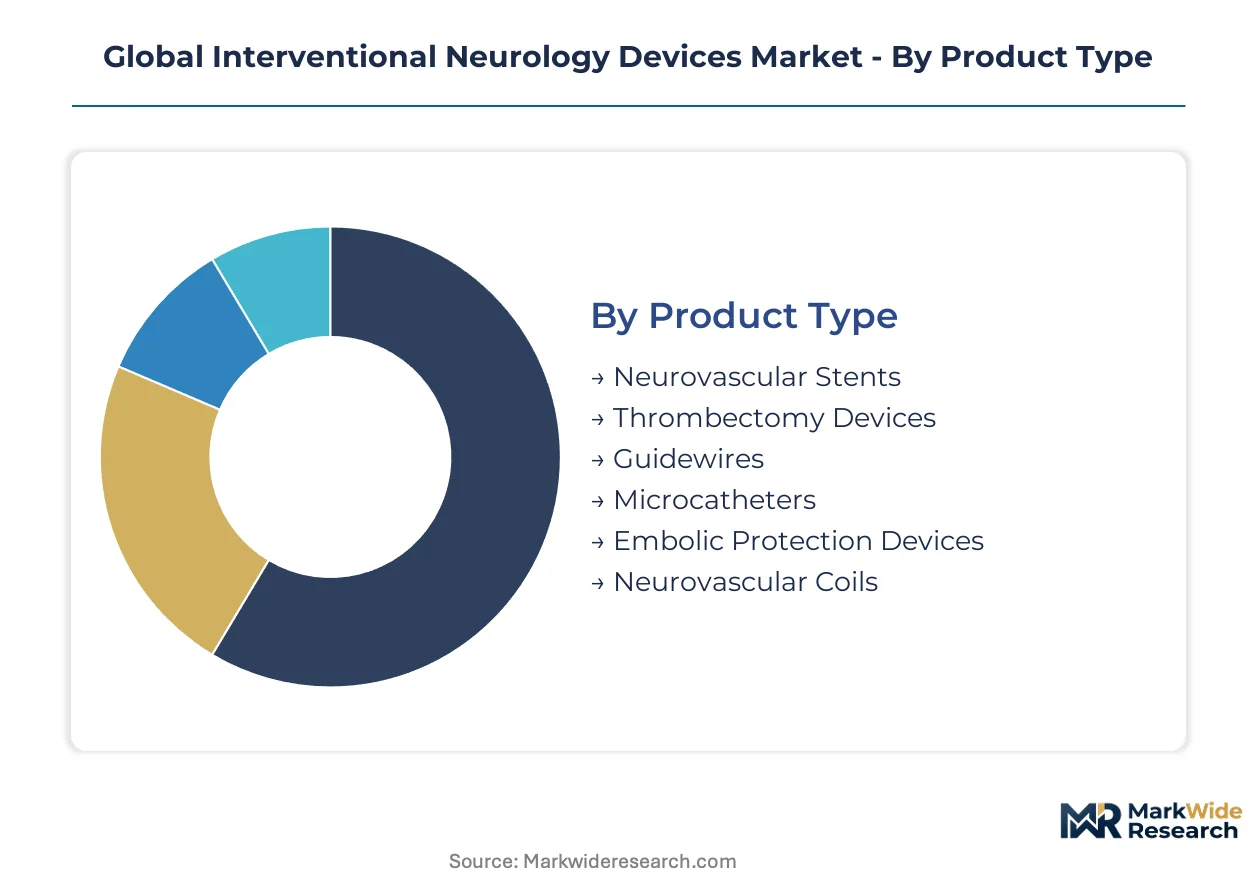
Segmentation in interventional neurology devices reveals how supply-side capabilities and clinical evidence concentrations reshape procurement decisions across stroke centers and aneurysm treatment pathways. Understanding these divisions exposes where vendor bundling strategies succeed or fracture.
Product Type:
Supply concentration among nitinol alloy processors and hydrophilic coating specialists directly determines which device categories sustain premium positioning versus commodity pressure.
- Thrombectomy Devices:Stent retrievers and aspiration catheters constructed from laser-cut nitinol hypotubes with distal flexibility below 3mm bend radius. Demand clusters in US tertiary stroke centers certified for 24/7 mechanical thrombectomy, driven by Joint Commission mandates expanding treatment windows to 24 hours post-onset.
- Neurovascular Stents:Self-expanding braided constructs with platinum-iridium radiopaque markers delivering radial force against intracranial vessel walls. German and Japanese stroke centers concentrate adoption, constrained by twelve-month restenosis rates limiting small-vessel atherosclerotic applications.
- Neurovascular Coils:Platinum-tungsten filament bundles for aneurysm sac filling, facing EU MDR recertification withdrawals among legacy system vendors.
- Microcatheters:Sub-0.014-inch hydrophilic polymer delivery platforms, with tip material supply controlled by three Japanese and German suppliers creating input bottlenecks.
- Guidewires:Torque-responsive stainless steel or nitinol cores with distal coil springs, standardizing across aspiration and stent delivery procedures.
- Embolic Protection Devices:Filter and occlusion balloon systems for carotid interventions, competing in a maturing segment with consolidated hospital procurement panels.
Today's leader: Thrombectomy Devices. Tomorrow's challenger: Neurovascular Stents.
Technology:
Cost tier stratification separates capital-intensive robotic navigation from disposable catheter platforms, with reimbursement rates determining hospital adoption thresholds.
- Mechanical Thrombectomy:Stent retriever deployment with integrated aspiration for acute ischemic stroke revascularization. US and German comprehensive stroke centers drive volume, with hub-and-spoke protocols extending into Texas and Florida community hospitals.
- Flow Diversion:Pipeline embolization devices redirecting blood flow from aneurysm sacs using braided nitinol mesh. Japan's PMDA fast-track designations accelerate time-to-market, while EU MDR technical file scrutiny intensifies fatigue testing documentation burdens.
- Aspiration:Large-bore catheter systems for first-pass clot retrieval, gaining share in cost-conscious accounts unbundling from stent retriever packages.
- Balloon Angioplasty:Inflation platforms for intracranial stenosis, limited by restenosis rates in small-vessel disease.
- Radiofrequency Ablation:Thermal energy delivery for arteriovenous malformation nidus reduction, occupying niche applications in specialized centers.
- Laser Therapy:Photocoagulation systems for venous sinus thrombosis, with constrained reimbursement constraining hospital capital allocation.
Flow Diversion is climbing the fastest as aneurysm treatment shifts from coiling to intrasaccular and flow-disrupting approaches.
Application:
Volume concentration in acute stroke intervention compresses margins, while complex aneurysm pathways preserve pricing power for specialized device configurations.
- Ischemic Stroke:Mechanical thrombectomy for large vessel occlusion represents the dominant procedural volume globally. Tertiary center certification requirements in the US, Germany, and Japan concentrate demand in 24/7 interventional neuroradiology facilities.
- Cerebral Aneurysm:Endovascular coiling, flow diversion, and intrasaccular device deployment. Japanese and German centers lead adoption of next-generation flow diverters, with PMDA accelerated pathways compressing regulatory timelines.
- Arteriovenous Malformation:Embolization and stereotactic radiosurgery adjuncts, requiring specialized neurovascular surgeon availability limiting addressable centers.
- Carotid Artery Stenosis:Stenting with embolic protection, competing against surgical endarterectomy in established stroke prevention pathways.
- Intracranial Stenosis:Angioplasty and stenting for intracranial atherosclerosis, constrained by target lesion revascularization incidence.
- Venous Sinus Thrombosis:Mechanical thrombectomy and local thrombolysis, with mobile stroke unit deployment creating emerging channel demand.
The steepest expansion trajectory belongs to cerebral aneurysm interventions as flow diversion technology matures.
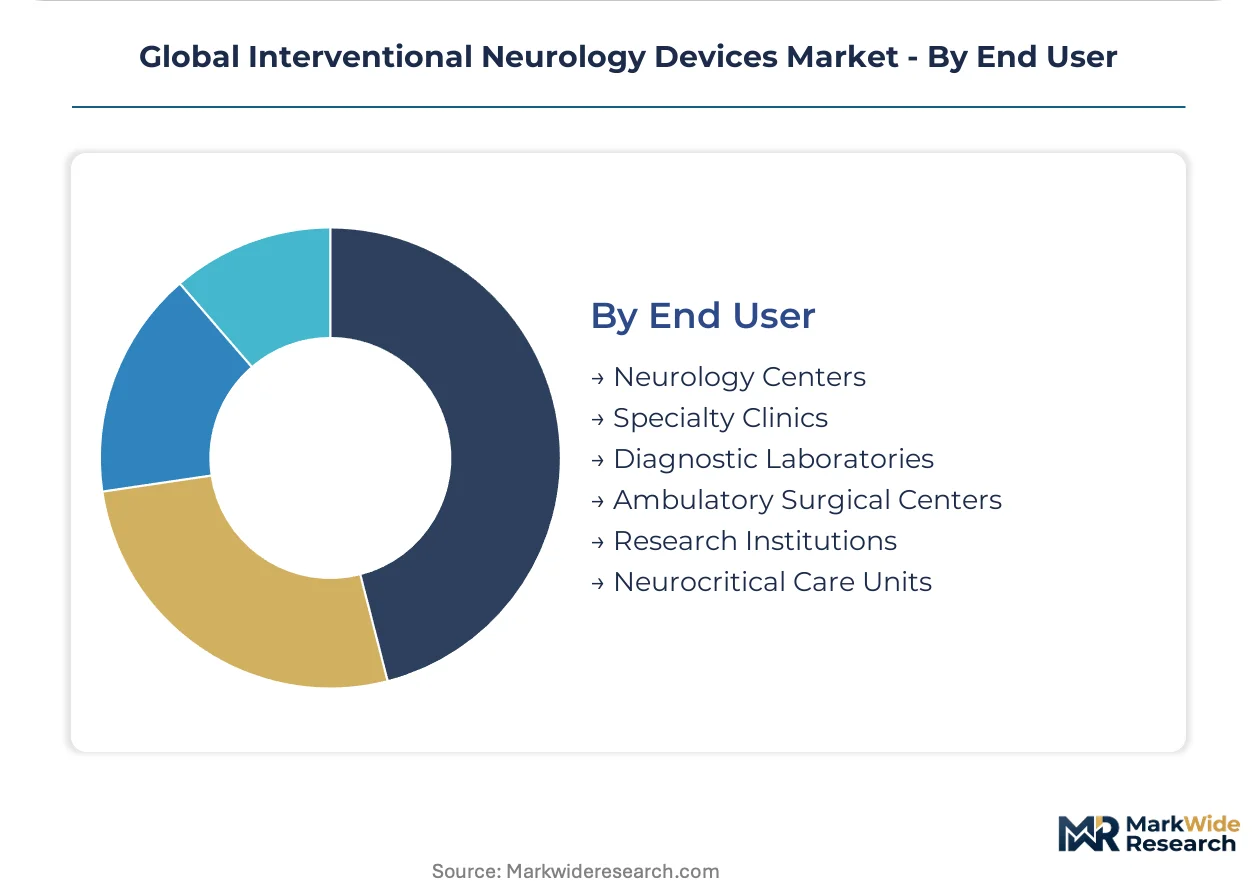
End User:
Customer type fragmentation across certification tiers determines whether vendors bundle procedural support or compete on standalone device pricing.
- Neurology Centers:Comprehensive stroke centers with 24/7 interventional neuroradiology coverage. US Joint Commission accreditation mandates concentrate high-complexity procedures, sustaining premium service bundling from major device vendors.
- Neurocritical Care Units:ICU-integrated interventional capabilities for stroke and hemorrhage management. German and Japanese hospital systems invest in embedded angiography suites, driving capital equipment and disposable catheter demand.
- Specialty Clinics:Outpatient diagnostic and minor intervention facilities, excluded from mechanical thrombectomy reimbursement tiers.
- Ambulatory Surgical Centers:Limited to diagnostic angiography and elective aneurysm follow-up, constrained by emergency stroke intervention requirements.
- Diagnostic Laboratories:Imaging and non-interventional assessment, serving referral networks to comprehensive centers.
- Research Institutions:Clinical trial sites for next-generation thrombectomy and flow diversion devices, with FDA and EMA real-world evidence mandates reshaping study design standards.
Neurology Centers command current procurement volume. Neurocritical Care Units are gaining share fastest as embedded interventional capabilities expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's tertiary stroke centers process mechanical thrombectomy volumes that outpace Japan's national procedural count, yet Tokyo's flow diversion adoption rates exceed Berlin's by a measurable margin in aneurysm interventions.
United States
Joint Commission certification mandates for comprehensive stroke centers concentrate 24/7 interventional neuroradiology coverage in urban hospital systems. FDA premarket approval pathways shape device development timelines for thrombectomy platforms. The Texas Medical Center in Houston anchors one of the highest procedural volumes globally, with hub-and-spoke protocols extending into Florida community hospitals.
Germany
Baden-Württemberg and Bavaria host the densest clusters of certified stroke units in Europe, driving catheter platform procurement. EU MDR conformity assessments from notified bodies extend CE marking timelines for Class III neurovascular implants. The Heidelberg University Hospital corridor represents a concentration of flow diversion clinical trial activity and aneurysm intervention volume.
Japan
PMDA fast-track designations for flow diversion devices compress regulatory timelines below EMA and FDA benchmarks. METI industrial policy supports domestic nitinol processing capabilities for microcatheter manufacturing. The Tokyo-Osaka medical corridor concentrates demand for next-generation aspiration catheters with sub-0.014-inch distal profiles.
China
NMPA localization requirements filter multinational commercial presence, favoring joint ventures with domestic device manufacturers. The Yangtze River Delta around Shanghai hosts expanding tertiary neurology centers adopting mechanical thrombectomy. Beijing's military hospital systems drive early adoption of AI-integrated procedural navigation platforms.
Brazil
ANVISA harmonization pathways with FDA reduce duplicate clinical evidence requirements for thrombectomy platform market entry. São Paulo's Albert Einstein Hospital and Hospital das Clínicas anchor interventional neurology training and procedural volume. The Southeast region concentrates device procurement as reimbursement frameworks shift toward value-based care models.
Global Interventional Neurology Devices Market Competitive Landscape
Top-tier vendors anchor integrated surgical ecosystems, while mid-scale specialists occupy distinct technology segments. The vendor base stratifies across three tiers: multinational conglomerates with navigation platform bundling, dedicated neurovascular R&D houses, and regional catheter fabricators. Two strategic archetypes dominate—ecosystem integrators competing through service bundling, and aspiration technology specialists defending segment position through material science differentiation. Competitive moves concentrate on M&A for catheter platform capabilities and strategic partnerships for AI-integrated navigation.
Among the named participants, Medtronic plc and Stryker Corporation exemplify ecosystem integrators with broad navigation and thrombectomy platform portfolios. Penumbra Inc occupies a distinct position as an aspiration technology specialist. Acandis GmbH represents the mid-scale European specialist archetype. Johnson & Johnson, Boston Scientific Corporation, and Terumo Corporation sit within the diversified multinational tier, each with neurovascular divisions competing across multiple device categories. MicroPort Scientific Corporation and Merit Medical Systems Inc exemplify regional-scale competitors with targeted interventional portfolios.
| Leading Market Players |
|---|
| Penumbra Inc |
| Johnson & Johnson |
| Medtronic plc |
| Acandis GmbH |
| MicroPort Scientific Corporation |
| Stryker Corporation |
| Boston Scientific Corporation |
| Merit Medical Systems Inc |
| Terumo Corporation |
| Others |
Supply & Pricing Matrix
Laser-cut hypotube manufacturing migration from Swiss precision shops to Japanese and German nitinol processors is compressing unit economics for aspiration catheter platforms while simultaneously locking in supply concentration among three alloy specialists. This dual restructuring forces device vendors to absorb margin compression or surrender pricing autonomy to upstream material gatekeepers.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for nitinol-based delivery systems as new hypotube fabrication lines come online. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive stroke center bundles from community hospital standalone procurement, with FDA breakthrough-designation premiums commanding the top tier. Cost compression in standard-tier mechanical thrombectomy devices is intensifying because hub-and-spoke protocols extend procedural volume to price-sensitive primary stroke centers. Community hospitals in Texas and Florida exhibit the highest price sensitivity, while Joint Commission-certified tertiary centers in the US and German university hospitals remain least sensitive due to bundled service contracts.
Supply Chain Analysis
ISO 13485:2016 and EU MDR Article 117 certification requirements filter viable suppliers to a narrow tier of notified body-audited nitinol processors and hydrophilic coating specialists. Manufacturing gravity centers on Japan, Germany, and Switzerland for microcatheter tip fabrication, with platinum-iridium alloy supply resting on three Japanese and German suppliers. Raw material dependencies include nitinol shape-memory alloys, hydrophilic polymer coatings, and platinum-iridium radiopaque markers. Single-source vulnerability concentrates in sub-0.014-inch hypotube supply for distal access platforms. Distribution runs through integrated delivery networks in California and New York that consolidate vendor panels to three preferred suppliers per category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japan's PMDA fast-track pathways compressing regulatory timelines and the EU MDR conformity assessment backlog extending CE marking by 12-18 months for identical device platforms.
For Market Incumbents: Deploy backward integration into nitinol alloy processing to secure hypotube supply against Japanese and German supplier concentration. Lock in multi-year offtake agreements with platinum-iridium specialists before capacity constraints tighten. Defend against aspiration-first pricing erosion by bundling AI-integrated navigation software with catheter platforms, creating switching costs for cost-conscious community hospitals. For New Entrants and Emerging Players: Enter via Brazil's ANVISA harmonization pathway to leverage FDA mutual recognition and avoid duplicate clinical evidence generation. Target mobile stroke unit deployment channels in the US Southeast and pre-hospital aspiration systems as the most penetrable white-space segment. Pursue telemedicine-integrated go-to-market partnerships with hub-and-spoke network operators rather than direct hospital sales. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale aspiration technology specialists because hospital procurement consolidation favors vendors with full catheter-platform portfolios over single-product lines. Five-to-ten year viability hinges on capturing flow diversion device share as aneurysm treatment shifts from coiling. Watch for PMDA accelerated approval announcements as the inflection signal indicating which platforms will compress time-to-market in Japan's high-adoption corridor.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Fast-Track Designation Pursuit | Japan's accelerated pathway compresses regulatory timelines below FDA and EMA benchmarks for flow diversion devices. |
| CE Marking Pathway Navigation | EU MDR Article 117 notified body involvement extends documentation burdens for nitinol fatigue testing data. |
| Hospital System Partnership | Integrated delivery networks in California consolidate vendor panels to three preferred suppliers per device category. |
| Software Companion Development | AI-integrated procedural navigation converges with robotic catheter control to reduce fluoroscopy exposure in stroke centers. |
| Reimbursement Strategy | US Joint Commission certification mandates concentrate 24/7 interventional neuroradiology coverage in urban hospital systems. |
Research Methodology
Multiple input streams — primary interviews with interventional neuroradiologists and hospital purchasing committees, secondary validation against FDA 510(k) and PMA filings, and GPO contract database analysis — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included stroke center medical directors, biomedical engineers, GPO contracts managers, and neurovascular device R&D heads. Secondary sources encompassed EMA public assessment reports, PMDA approval summaries, hospital procurement databases, and CMS Medicare reimbursement schedules.
Historical procedural volume trajectories were cross-referenced against panel-based specialist input to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application pathway, and end-user certification tier. CAGRs were derived from procedure volume elasticity to treatment window expansion and flow diversion adoption curves. Industry-specific forecast inputs incorporated PMDA fast-track approval velocity and EU MDR notified body capacity constraints.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-world evidence generation timelines for next-generation thrombectomy devices introduce uncertainty bands around flow diversion penetration assumptions. Forecasts reflect documented assumptions regarding reimbursement framework stability and fellowship pipeline expansion. A model refresh is warranted upon material change in Joint Commission certification mandates or PMDA accelerated pathway eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pulmonology Devices Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Bedwetting Alarm Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Transabdominal Retrieval Kits Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Chest Drainage System Market
Medical Devices
North America Cardiac Rhythm Management Devices Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Europe Breast Implant Market
Medical Devices
Clear Aligners Market
Medical Devices
Zygomatic and Pterygoid Implants Market