
 Chest Drainage Devices Market | 2026-2036
Chest Drainage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chest Drainage Devices Market Outlook
Hospital procurement of electronic drainage systems is collapsing toward integrated hybrid platforms that combine suction control with digital monitoring. Getinge leverages its intensive care portfolio to anchor premium positioning in European thoracic centers. Medtronic competes through broad catheter technology overlap that extends into cardiac surgery adjacencies. Smiths Medical specializes in compact disposable designs that dominate emergency transport applications.
Chest drainage devices are closed-circuit systems comprising catheters, collection chambers, and one-way valves engineered to evacuate air or fluid from the pleural space while preventing atmospheric ingress. Standard chest tubes range from 20 Fr to 36 Fr in diameter, constructed from radiopaque polyvinyl chloride or silicone with distal side ports to maintain patency. Thoracostomy kits command the largest revenue pool due to bundled pricing and institutional contract consolidation, while electronic drainage technology represents the fastest-expanding segment as pressure-regulated suction replaces water-seal gravity systems. Pleural effusion applications generate disproportionate procedure volume in oncology and heart failure patient populations.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercial launch sequencing for device manufacturers. The EPA regulates polyvinyl chloride waste streams from disposable drainage components, pushing material substitution toward silicone alternatives. ISO 13485 quality management certification functions as a baseline market access credential across all major jurisdictions. Stakeholders must monitor reimbursement coding shifts for outpatient thoracentesis and ambulatory chest tube management as these determine adoption velocity for home care drainage systems.
Market Dynamics
Electronic drainage systems are supplanting mechanical water-seal units as thoracic surgery departments prioritize digital pressure monitoring and automated suction regulation over gravity-dependent designs.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter conformity assessment requirements for Class IIa medical devices accelerate hospital replacement cycles as facilities seek compliant, future-proofed equipment.
- Silicone catheter materials:Radiopaque silicone construction improves biocompatibility and reduces trauma complications, driving preference in oncology and cardiac surgery patient populations.
- Japan's aging thoracic patient base:Elevated pleural effusion incidence among elderly populations sustains procedural volume in tertiary care centers.
Market Restraints
- Polyvinyl chloride input cost volatility:Petroleum-derived PVC pricing fluctuations compress margins on standard disposable drainage kits, the highest-volume product category.
- ISO 13485 certification timelines:Quality management system audits and technical file preparation extend product launch windows by 12-18 months for new market entrants.
- Water-seal gravity systems:Established low-cost mechanical designs retain foothold in resource-constrained settings, slowing premium electronic adoption in price-sensitive segments.
Strategic Opportunities
- Home care drainage systems:Reimbursement coding expansion for ambulatory chest tube management creates white space outside traditional inpatient settings.
- Hybrid platform convergence:Integration of suction control with digital monitoring and wireless connectivity enables premium positioning in intensive care environments.
- Germany's thoracic center consolidation:Bundled procurement contracts at centralized academic medical centers favor comprehensive system suppliers over component vendors.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in pneumatics, fluid dynamics, and regulatory affairs concentrates at established manufacturers, constraining R&D scaling.
- FDA 510(k) predicate device dependencies:Substantial equivalence pathways require careful navigation of evolving guidance documents for novel electronic drainage features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chest Drainage Devices Market |
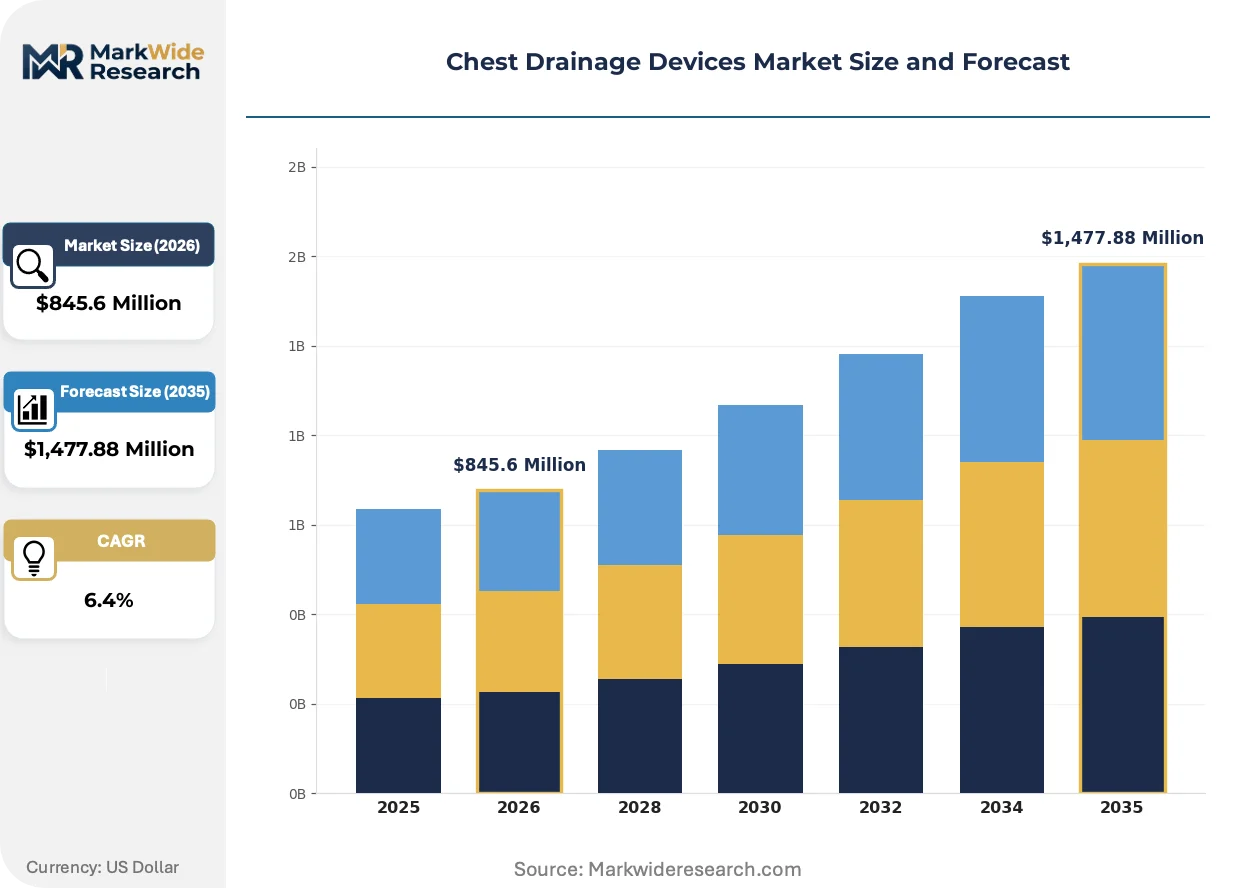
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $1,477.88 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thoracostomy Kits, Chest Tubes, Drainage Bags, One-Way Valves End User: Hospitals, Surgical Centers, Home Care, Emergency Services Technology: Mechanical, Electronic, Hybrid, Disposable Application: Pneumothorax, Hemothorax, Pleural Effusion, Post-Operative Care |
| Companies Covered | Getinge, Cook Medical, Medtronic, Stryker, Medela, Teleflex, Cardinal Health, Smiths Medical, Becton Dickinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chest Drainage Devices Market Strategic Shifts
Digitalization of pleural drainage is compressing the gap between critical care monitoring and surgical recovery, with sensor-enabled systems now transmitting real-time pressure data to centralized nursing stations.
Wireless telemetry modules embedded in electronic drainage canisters are supplanting manual charting workflows. Thoracic step-down units in United States academic medical centers deploy these systems to reduce nursing documentation burden. This connectivity infrastructure is compressing response times to air leaks and enabling predictive algorithms for chest tube removal timing.
EPA polyvinyl chloride waste stream regulations are tightening disposal requirements for disposable drainage components. Manufacturers face elevated compliance costs for hazardous waste characterization and treatment. Silicone alternative formulations are gaining traction as hospitals in California and Massachusetts anticipate stricter state-level environmental mandates.
Consolidated procurement through integrated delivery networks is compressing vendor rosters. Health systems in Texas and Florida now mandate single-source contracts covering catheters, collection chambers, and suction regulators. This concentration is forcing specialized component suppliers to partner with full-platform vendors or exit institutional channels entirely.
Chest Drainage Devices Market Segmentation
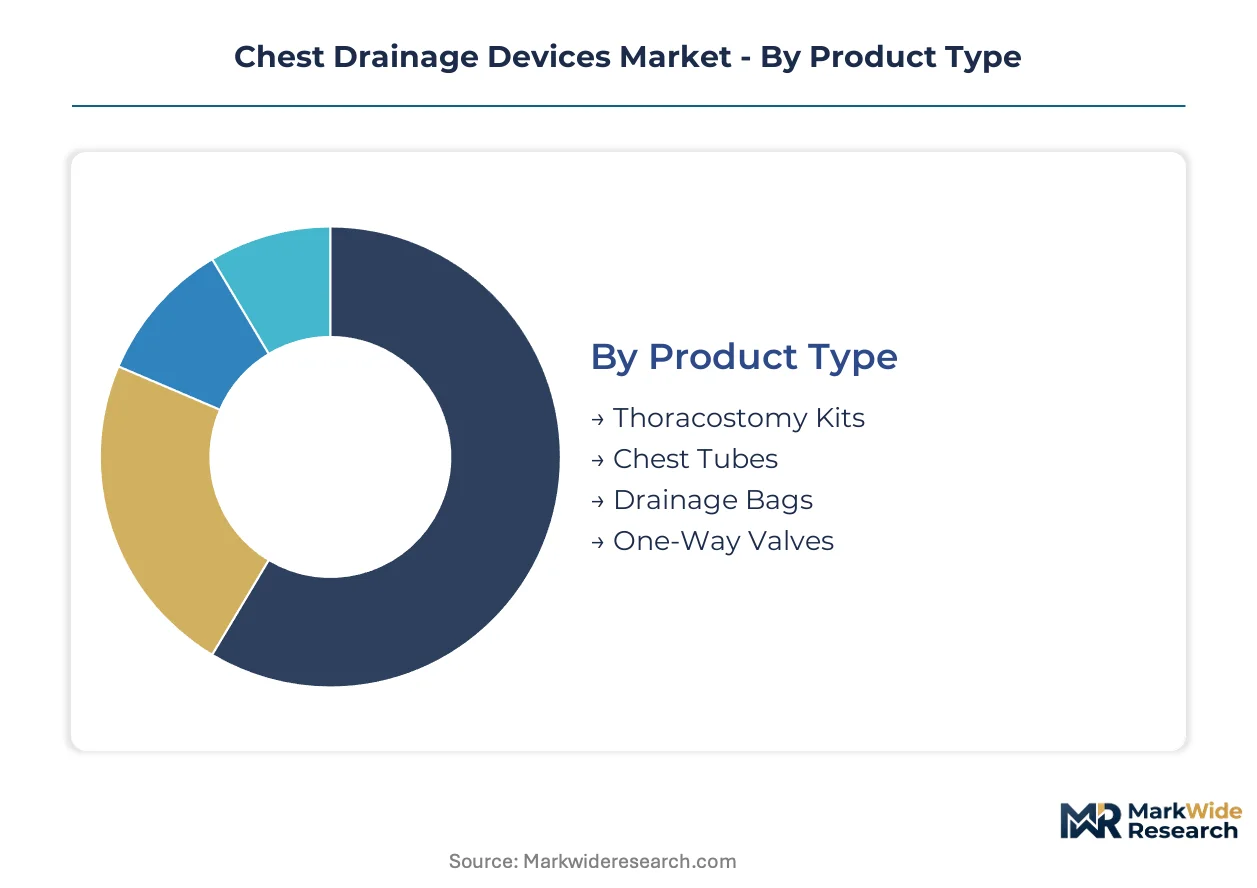
Chest drainage devices fragment across four distinct category axes, each mapping to different procurement budgets and clinical workflows. Product type determines capital versus disposable spend ratios. Technology tier separates gravity-based heritage systems from digitally integrated platforms. Understanding these splits reveals where procurement consolidation will concentrate vendor power.
Product Type:
Thoracostomy kits capture the deepest margin pools due to bundled institutional pricing and contract consolidation leverage.
- Thoracostomy Kits:Comprehensive procedural packages bundle catheters, collection chambers, and insertion instruments under single-source contracts. Academic medical centers in Germany and the United States favor these configurations for standardized thoracic service lines.
- Chest Tubes:Radiopaque polyvinyl chloride and silicone constructions range from 20 Fr to 36 Fr with distal side ports for patency maintenance. Demand clusters in cardiac surgery recovery units where biocompatibility requirements elevate silicone preference.
- Drainage Bags:Calibrated collection canisters with graduated volume markings support pleural fluid monitoring. Home care reimbursement expansion is pulling demand toward compact disposable designs.
- One-Way Valves:Mechanical flutter valves and digital pressure-regulated alternatives prevent atmospheric ingress. Emergency transport applications in Japan favor lightweight mechanical designs for field durability.
Thoracostomy kits hold installed capacity. Electronic drainage canisters are rotating up the share rankings.
End User:
Hospital procurement volumes dominate absolute spend, though home care channels are climbing fastest as ambulatory reimbursement codes expand.
- Hospitals:Tertiary thoracic centers drive electronic drainage adoption for ICU step-down monitoring. Bundled payment models in United States academic medical centers accelerate platform standardization decisions.
- Surgical Centers:Ambulatory thoracic procedures concentrate mechanical water-seal systems for cost containment. Day-case pneumothorax management in Germany leverages compact disposable kits.
- Home Care:Portable drainage systems with patient-managed suction regulation enable early discharge protocols. Medicare coding shifts in the United States are unlocking reimbursement for ambulatory chest tube management.
- Emergency Services:Pre-hospital thoracostomy demand prioritizes rapid-deployment mechanical systems. Air medical transport operators specify lightweight, impact-resistant designs.
Hospitals anchor current procurement volume. Home care is expanding most quickly as reimbursement infrastructure matures.
Technology:
Electronic systems command premium pricing while mechanical platforms retain volume leadership in price-constrained segments.
- Mechanical:Gravity-dependent water-seal chambers and spring-loaded suction regulators remain standard in resource-limited settings. Established low-cost designs retain foothold in emerging market procurement.
- Electronic:Pressure-regulated suction with digital monitoring interfaces enables automated air leak detection. United States thoracic ICUs prioritize these systems for nursing workflow efficiency.
- Hybrid:Converged platforms combine mechanical backup with electronic pressure sensing and wireless telemetry. European intensive care networks favor these configurations for redundancy assurance.
- Disposable:Single-use drainage canisters and catheter sets eliminate reprocessing costs. Oncology pleural effusion protocols in Japan drive preference for sterile disposable circuits.
Mechanical systems hold installed capacity. Hybrid platforms are gaining share fastest as ICU departments prioritize connectivity integration.
Application:
Pleural effusion generates disproportionate procedure volume through oncology and heart failure patient populations.
- Pneumothorax:Spontaneous and traumatic air leak management requires immediate chest decompression. Emergency departments favor rapid-insertion thoracostomy kits for first-line intervention.
- Hemothorax:Blood evacuation from pleural space demands large-bore catheter capacity and high-volume suction. Trauma centers specify reinforced silicone constructions for coagulated fluid management.
- Pleural Effusion:Malignant and congestive fluid accumulation drives recurrent drainage procedures. Oncology units in the United States and Germany generate sustained catheter consumption.
- Post-Operative Care:Cardiac and thoracic surgery recovery protocols mandate standardized drainage monitoring. Surgical step-down units deploy electronic systems for automated removal timing algorithms.
Pleural effusion holds installed capacity. Post-operative care applications are climbing the share rankings as enhanced recovery protocols shorten ICU stays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German thoracic device manufacturers export electronic drainage systems to United States academic medical centers, establishing the primary transatlantic trade corridor for premium ICU equipment. Japanese suppliers serve domestic tertiary care networks with compact mechanical designs optimized for aging patient populations. Production clusters concentrate where regulatory pathways align with reimbursement infrastructure.
United States
Medicare coding expansion for ambulatory chest tube management accelerates home care drainage adoption. FDA 510(k) clearance timelines shape product launch sequencing for electronic suction systems. The Texas Medical Center in Houston anchors procurement volume for hybrid platform standardization across thoracic service lines.
Germany
Academic medical center consolidation drives bundled thoracostomy kit contracts favoring comprehensive system suppliers. EU MDR technical documentation requirements elevate compliance costs for Class IIa drainage devices. The Ruhr Valley industrial corridor hosts specialized pneumatics engineering talent concentrated at established manufacturers.
Japan
Elevated pleural effusion incidence among elderly populations sustains procedural volume in tertiary care centers. PMDA regulatory pathways prioritize biocompatibility validation for silicone catheter materials. Tokyo metropolitan hospitals deploy compact disposable designs for oncology patient transport protocols.
United Kingdom
NHS procurement frameworks concentrate vendor selection through national competitive tendering for thoracic surgery equipment. MHRA post-Brexit regulatory alignment with EU MDR extends conformity assessment timelines. The Oxford-Cambridge-London golden triangle anchors digital health integration pilots for wireless telemetry drainage.
China
Domestic thoracic surgery volume expansion drives localization of mechanical water-seal production. NMPA Class II medical device registration requirements extend market entry timelines for foreign electronic system manufacturers. The Yangtze River Delta medical device cluster scales disposable component fabrication for cost-sensitive hospital procurement.
Chest Drainage Devices Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with intensive care portfolios anchoring premium positioning. Market structure concentrates around three strategic tiers: full-platform system suppliers commanding bundled institutional contracts, specialized catheter manufacturers focused on biocompatibility differentiation, and disposable component fabricators serving high-volume emergency applications. Dominant competitive moves include portfolio convergence through strategic partnerships and geographic expansion via regulatory pathway optimization.
Among diversified medical technology conglomerates, Getinge and Medtronic exemplify the full-platform archetype through intensive care portfolio breadth. Smiths Medical occupies a position within the specialized tier, representing compact disposable design expertise. These three anchors illustrate how vendor concentration follows procurement consolidation patterns in United States and German thoracic centers.
| Leading Market Players |
|---|
| Getinge |
| Cook Medical |
| Medtronic |
| Stryker |
| Medela |
| Teleflex |
| Cardinal Health |
| Smiths Medical |
| Becton Dickinson |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day silicone catheter lead times concentrate procurement leverage with German and Japanese suppliers, compressing margin pools for mechanical water-seal manufacturers while amplifying pricing power for electronic drainage platform vendors with captive polymer sourcing.
Pricing Analysis
Electronic-to-mechanical pricing gaps span three technology generations, with pressure-regulated digital systems commanding premium positioning against gravity-dependent water-seal units and emerging hybrid platforms occupying mid-tier positioning. Pricing stratifies across premium, standard, and economy tiers determined by FDA 510(k) clearance tier and ICU connectivity bundling. Cost compression in disposable PVC kits intensifies because petroleum feedstock volatility feeds through catheter fabrication. Emergency services buyers exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to bundled procurement contracts.
Supply Chain Analysis
Strategic stockpiling of silicone raw materials dominates inventory strategy among electronic drainage manufacturers, contrasting with just-in-time PVC sourcing for high-volume disposable kit producers. Supply concentrates in Germany, Japan, and the United States for precision pneumatics engineering. Raw material dependencies center on medical-grade silicone polymers, radiopaque PVC compounds, and electronic pressure sensors. Single-source vulnerability in specialized valve manufacturing creates structural risk. Distribution runs through group purchasing organizations and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chest drainage device economics are inflecting toward platform-based competition where interoperability with hospital electronic health record systems determines contract viability, mirroring the ecosystem shift already completed in patient monitoring and infusion pump categories.
For Market Incumbents: Secure FDA 510(k) clearance for next-generation wireless telemetry modules before EU MDR technical documentation deadlines compress launch windows. Deepen backward integration into silicone catheter manufacturing to offset PVC cost volatility. Defend against emerging Asian disposable specialists by anchoring premium positioning through intensive care portfolio bundling.
For New Entrants and Emerging Players: Lead with home care drainage systems where Medicare reimbursement coding expansion creates penetrable white space outside entrenched hospital procurement channels. Target ambulatory surgery centers in Florida and Texas with compact mechanical designs optimized for cost containment. Pursue strategic partnerships with full-platform vendors rather than direct institutional contracting.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electronic drainage system manufacturing as FDA and EU MDR compliance requirements elevate product validation costs. Long-term viability favors diversified medical technology conglomerates with intensive care portfolio breadth over specialized catheter manufacturers. Acquisition target archetype: mid-tier hybrid platform developers with wireless connectivity capabilities. Watch FDA guidance document evolution for novel electronic drainage features as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance timelines shape competitive positioning for electronic suction system launches. |
| EU MDR Technical Documentation | Conformity assessment requirements accelerate hospital replacement cycles toward compliant equipment. |
| Hospital System Partnership | Bundled procurement contracts at academic medical centers favor comprehensive platform suppliers. |
| Software Companion Development | Wireless telemetry integration enables predictive algorithms for chest tube removal timing. |
| Reimbursement Strategy | Medicare coding expansion for ambulatory chest tube management unlocks home care channel growth. |
Study Parameters
Cross-validation between primary interviews with thoracic surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers anchors the qualitative findings against secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement coding updates. Bottom-up demand modeling triangulates with top-down market sizing across product type, technology tier, end-user channel, and application segmentation.
Sensitivity analysis around silicone raw material cost assumptions and electronic drainage adoption velocity informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, technology generation, care setting, and clinical indication. CAGRs derive from procedure volume elasticity to thoracic surgery capacity expansion and technology substitution curves. Forecast inputs incorporate EU MDR implementation pacing and Medicare coding shift timelines.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR Class IIa device classification; material policy shifts would require re-modeling. Revision becomes warranted when electronic drainage system reimbursement thresholds cross institutional adoption tipping points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Sweden Ophthalmic Devices Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Europe Viscosupplementation Market
Medical Devices
Medical Device Outsourcing Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Germanium-68/Gallium-68 Generators Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
India Clear Aligners Market
Medical Devices
Hair Removal Devices Market