
 Augmented Reality (AR) in Manufacturing Market | 2026-2036
Augmented Reality (AR) in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented Reality (AR) in Manufacturing Market Outlook
Mid-sized automotive suppliers are rotating toward AR-assisted maintenance and quality workflows faster than tier-one OEMs. Microsoft Corporation leverages its HoloLens industrial ecosystem to anchor enterprise deployments across North American factory floors. PTC sustains competitive differentiation through its ThingWorx platform integration with existing CAD pipelines. Siemens dominates European installations by bundling AR modules with its native digital-twin infrastructure.
Augmented Reality in Manufacturing overlays digital information onto physical production environments through head-mounted displays, spatial computing, and sensor fusion, typically operating with sub-millimeter tracking accuracy and sub-50ms latency to enable real-time operator guidance. Its primary industrial purpose is to reduce assembly errors, compress training cycles, and capture tacit knowledge from retiring technicians. Hardware segments currently absorb the largest share of capital expenditure as wearable optics and edge processors mature, while software and services margins expand faster as platforms shift toward recurring licensing models. The maintenance use case leads in deployment volume across heavy machinery and electronics end users, though quality control applications are gaining traction where ISO traceability requirements intensify.
FDA digital health oversight, EU AI Act risk classification for autonomous decision-support systems, and OSHA workplace safety standards collectively shape product certification pathways and limit market access for uncertified hardware vendors. The EU Green Deal's emphasis on resource-efficient manufacturing indirectly accelerates AR adoption by prioritizing error reduction and first-time-right production. Stakeholders must monitor how evolving liability frameworks for human-machine collaboration redistribute risk between AR platform providers and their manufacturing clients.
Market Dynamics
The convergence of EU AI Act risk classifications with FDA digital health oversight is forcing AR platform providers to rearchitect compliance architectures before deployment, compressing product development timelines while expanding certification costs.
Growth Catalysts
- EU AI Act high-risk system mandates:Manufacturers must implement human oversight protocols for autonomous decision-support, creating mandatory upgrade cycles for legacy quality control infrastructure.
- Aerospace assembly complexity:Multi-variant aircraft configurations demand real-time spatial guidance that paper-based work instructions cannot deliver, pulling AR adoption into final assembly lines.
- Germany's automotive engineering corridor:Stuttgart and Munich host concentrated OEM R&D spending that channels pilot budgets toward AR-assisted maintenance and digital-twin integration.
Market Restraints
- Optical component supply concentration:Waveguide manufacturing for head-mounted displays clusters in East Asian precision optics foundries, exposing hardware vendors to single-source fragility.
- FDA 510(k) pathway friction:Software-as-medical-device determinations for AR-guided surgical or diagnostic workflows extend clearance timelines by 18-24 months versus industrial safety applications.
- Wi-Fi 6E spectrum fragmentation:Regional allocation inconsistencies for 6 GHz industrial wireless force hardware variants that inflate inventory and certification burdens.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract manufacturers establishing capacity under production-linked incentives lack mature technician bases, creating first-mover advantage for AR training platforms.
- Digital-twin-to-AR convergence:Siemens and PTC ecosystems enable closed-loop feedback where virtual commissioning data feeds live operator guidance, compressing ramp-up for new product introductions.
- OSHA workplace safety modernization:Proposed standards for human-machine collaboration in heavy machinery operation would mandate contextual hazard alerting that AR systems uniquely deliver.
Industry Challenges
- Spatial computing talent scarcity:Computer vision engineers with industrial sensor fusion experience command premium compensation that mid-sized system integrators cannot match.
- ISO 9001 traceability integration:AR-guided quality workflows must feed audit trails into existing ERP systems, requiring custom middleware that fragments platform economics.
- Multi-generational workforce friction:Tenured technicians resist head-mounted interfaces, forcing dual-mode training programs that dilute implementation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented Reality (AR) in Manufacturing Market |
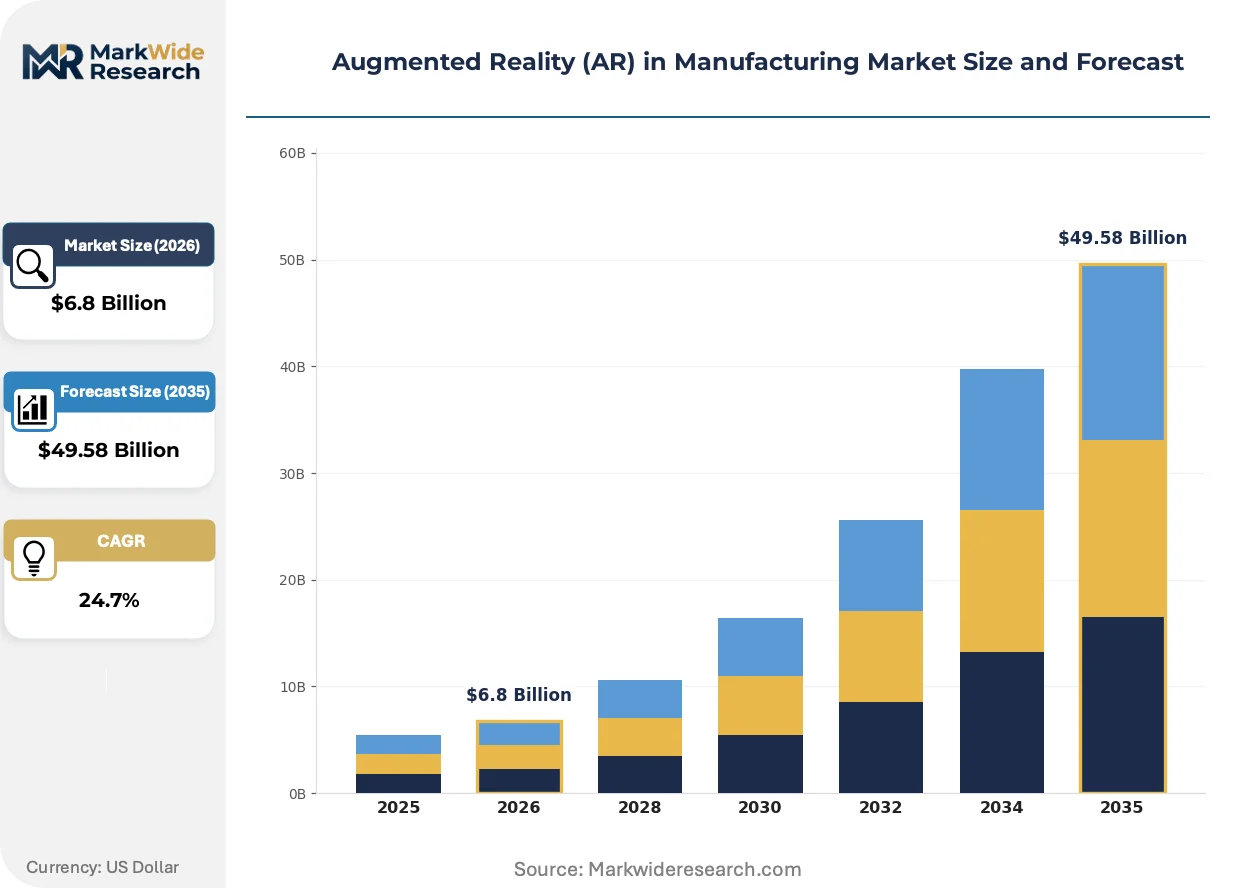
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $49.58 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Solutions Use Case: Assembly, Maintenance, Training, Quality Control End User: Aerospace, Automotive, Electronics, Heavy Machinery Integration Level: Standalone, System Integration, Cloud-Based, Edge Computing |
| Companies Covered | Microsoft Corporation, PTC, Siemens, Dassault Systemes, Unity Technologies, Vuzix Corporation, Google LLC, TeamViewer AG, ESI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented Reality (AR) in Manufacturing Market Strategic Shifts
Edge-native processing architectures are displacing cloud-tethered AR workflows, eliminating latency vulnerabilities that disrupted time-critical assembly operations. This hardware migration unlocks new deployment topologies across distributed manufacturing footprints.
Light engine technology is bifurcating across two competing architectures. Laser-beam-scanning systems from automotive HUD suppliers now penetrate industrial headsets for outdoor visibility. Micro-OLED waveguide stacks dominate indoor precision assembly where pixel density drives tracking accuracy. Tier-one electronics contract manufacturers in Taiwan and South Korea are ramping dedicated production lines for both form factors, enabling price stratification that separates premium aerospace applications from cost-constrained automotive supplier deployments.
The EU AI Act's high-risk system classification for autonomous decision-support is forcing AR vendors to implement mandatory human-in-the-loop overrides. Industrial quality control applications must now document operator acknowledgment of algorithmic recommendations, creating audit trail requirements that software platforms are racing to embed. German automotive OEMs are piloting these compliance architectures earliest, anticipating enforcement timelines that lag FDA digital health guidance by approximately 18 months.
Buyer procurement for AR systems is consolidating under central IT governance rather than distributed plant-level experimentation. Manufacturing engineering groups previously led pilot selections; now CIO offices mandate platform standardization to reduce integration debt with existing CAD and MES investments. This shift concentrates vendor selection authority and compresses evaluation cycles, favoring ecosystem players with pre-certified enterprise connectivity over point-solution specialists.
Augmented Reality (AR) in Manufacturing Market Segmentation
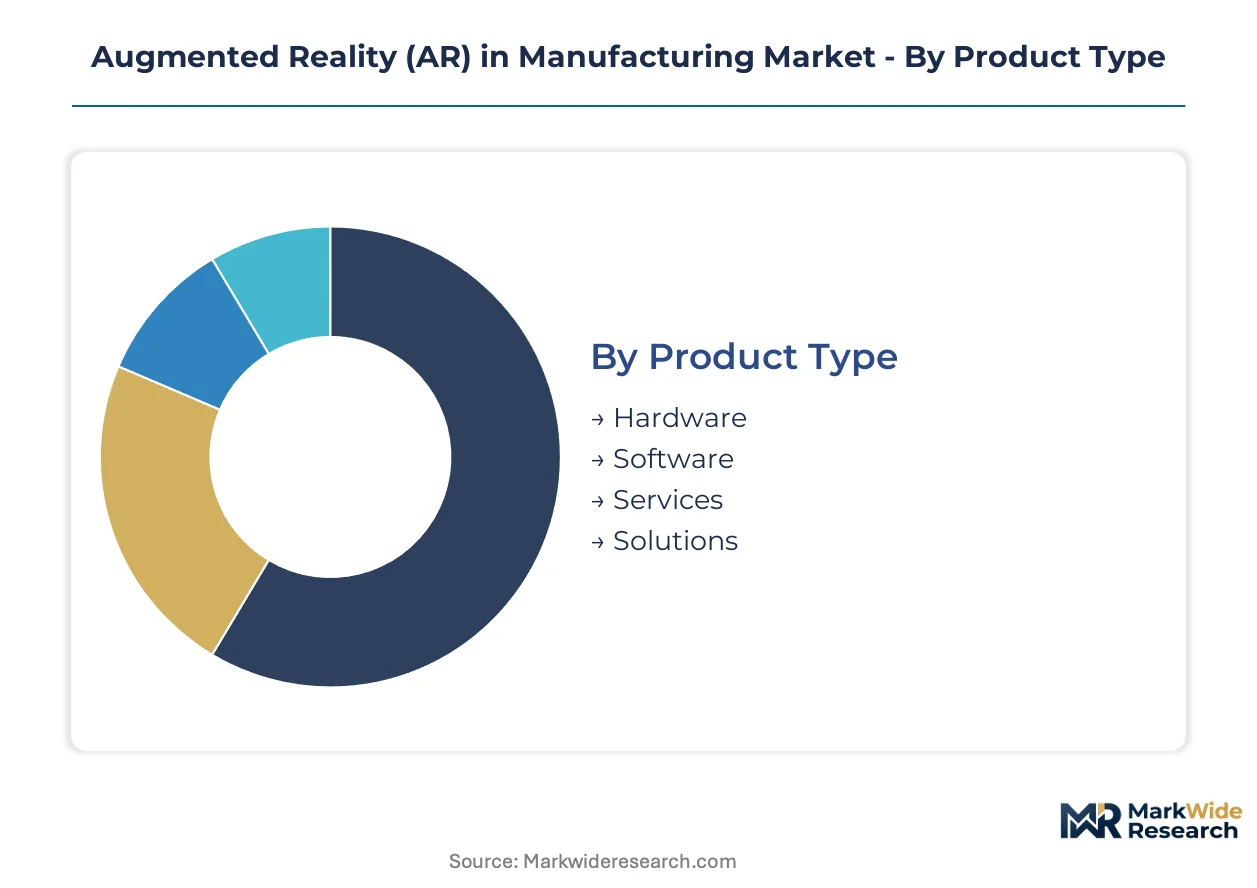
AR deployment patterns diverge sharply across product architectures and operational contexts. Segment boundaries determine capital allocation cycles, certification burdens, and vendor selection criteria for manufacturing buyers.
Product Type:
Software platforms face acute substitution pressure from in-house development teams at tier-one OEMs, while hardware maintains defensive moats through optical component specialization.
- Hardware:Wearable optics, edge processors, and sensor arrays constitute the capital-intensive foundation of industrial AR. Waveguide manufacturing concentration in East Asian precision optics foundries constrains supply elasticity for German automotive suppliers around Stuttgart and Munich.
- Software:Spatial computing engines, CAD integration middleware, and compliance audit modules run on recurring licensing models. FDA 510(k) pathway friction and EU AI Act risk classification mandates are extending development timelines for quality control decision-support algorithms.
- Services:Deployment consulting, change management, and technician training packages accompany platform rollouts. India's PLI scheme for electronics manufacturing is channeling first-mover budgets toward AR training platforms for greenfield facilities lacking mature technician bases.
- Solutions:Bundled hardware-software-service offerings with enterprise connectivity guarantees. Procurement consolidation under central IT governance is compressing evaluation cycles for pre-certified ecosystem players.
Hardware retains volume leadership; software holds the steepest expansion curve as platforms shift toward recurring licensing models.
Use Case:
Cost tier stratification separates high-complexity aerospace applications from cost-constrained automotive supplier deployments.
- Assembly:Real-time spatial guidance overlays digital work instructions onto physical production environments. Multi-variant aircraft configurations at Boeing and Airbus facilities demand sub-millimeter tracking accuracy that paper-based workflows cannot deliver.
- Maintenance:AR-assisted diagnostics and repair protocols reduce equipment downtime in heavy machinery operations. OSHA workplace safety modernization proposals would mandate contextual hazard alerting that maintenance AR systems uniquely deliver.
- Training:Immersive skill transfer captures tacit knowledge from retiring technicians. Electronics contract manufacturers in Taiwan and South Korea leverage AR training to compress onboarding for production-linked incentive schemes.
- Quality Control:Algorithmic inspection with ISO 9001 traceability integration feeds audit trails into ERP systems. EU AI Act high-risk system mandates require human-in-the-loop overrides with documented operator acknowledgment protocols.
Maintenance commands the broadest installed base; quality control is climbing the fastest as ISO traceability requirements intensify.
End User:
Application maturity varies across customer type, with aerospace and automotive at opposing ends of the standardization spectrum.
- Aerospace:Final assembly lines for commercial and defense aircraft deploy AR for complex wiring harness installation and systems integration. FAA certification requirements for human-machine interfaces add regulatory layers absent in industrial safety applications.
- Automotive:OEM R&D spending in Germany's engineering corridor channels pilot budgets toward digital-twin integration and AR-assisted maintenance. Mid-sized suppliers rotate toward quality workflows faster than tier-one OEMs burdened by legacy MES investments.
- Electronics:High-mix, low-volume contract manufacturing demands rapid reconfiguration of AR-guided workflows. Taiwan and South Korean production lines for laser-beam-scanning and micro-OLED waveguide stacks enable price stratification across this segment.
- Heavy Machinery:Field service operations in mining, construction, and agriculture leverage AR for remote expert assistance. Proposed OSHA standards for human-machine collaboration would accelerate contextual hazard alerting adoption.
Automotive holds the deepest deployment penetration; electronics is gaining share fastest on contract manufacturing expansion.
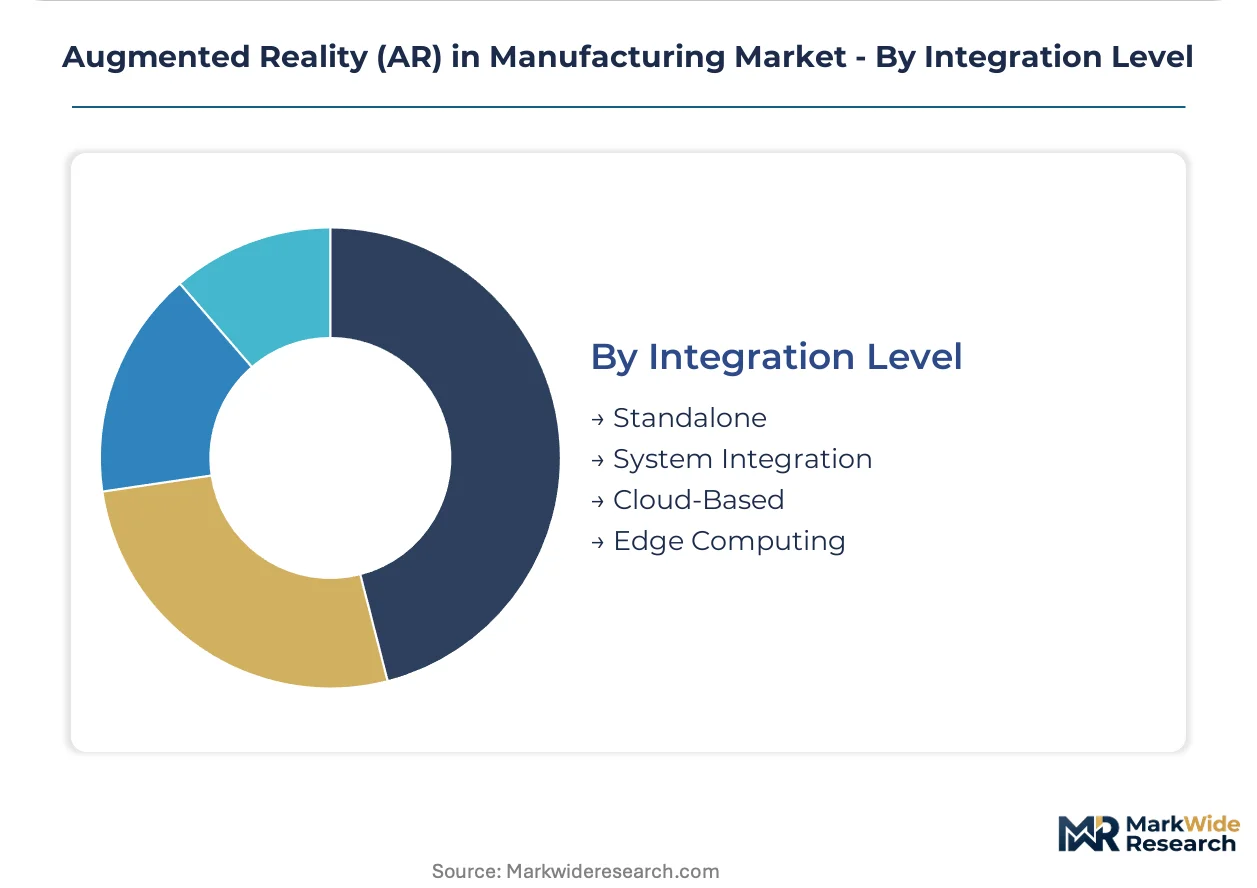
Integration Level:
Supply concentration in edge processor fabrication is reshaping competitive positioning across architecture choices.
- Standalone:Self-contained headsets with onboard processing eliminate infrastructure dependencies. Wi-Fi 6E spectrum fragmentation across regional allocations forces hardware variants that inflate inventory burdens.
- System Integration:Tight coupling with existing CAD, MES, and ERP pipelines through middleware layers. Siemens and PTC ecosystems enable closed-loop feedback where virtual commissioning data feeds live operator guidance.
- Cloud-Based:Centralized rendering and data analytics with persistent connectivity requirements. Latency vulnerabilities disrupted time-critical assembly operations, accelerating migration toward edge-native alternatives.
- Edge Computing:Distributed processing architectures eliminate cloud dependency for latency-sensitive operations. This hardware migration unlocks deployment topologies across distributed manufacturing footprints with intermittent connectivity.
System integration commands the largest project value; edge computing is expanding most quickly as latency constraints harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German AR hardware exports flow primarily to automotive assembly plants across the United States and China, while Taiwanese optics foundries supply waveguide components to European headset manufacturers.
United States
Aerospace manufacturers in Seattle and Charleston deploy AR-guided wiring harness installation for commercial aircraft final assembly. FAA certification requirements for human-machine interfaces add regulatory layers specific to aviation applications. Boeing facilities anchor demand concentration in the Pacific Northwest.
Germany
OEM R&D spending in Stuttgart and Munich channels pilot budgets toward digital-twin integration and AR-assisted maintenance workflows. EU AI Act high-risk system mandates require human-in-the-loop overrides with documented operator acknowledgment. Baden-Württemberg hosts the densest concentration of automotive AR deployments.
China
Electronics contract manufacturers in Shenzhen and Dongguan leverage AR training to compress onboarding for production-linked incentive schemes. MIIT standards for industrial wireless shape hardware certification pathways. Yangtze River Delta facilities lead in micro-OLED waveguide stack integration.
Japan
Precision machinery builders in Nagoya and Osaka adopt AR-assisted maintenance for predictive diagnostics on automated production lines. METI support programs for smart manufacturing accelerate platform procurement. Chubu region maintains the deepest installed base of industrial AR in Asia.
India
Electronics manufacturing services providers in Tamil Nadu and Karnataka establish greenfield capacity under PLI schemes lacking mature technician bases. BIS certification requirements for industrial safety equipment filter hardware vendor selection. Chennai-Bengaluru corridor attracts first-mover AR training platform deployments.
Augmented Reality (AR) in Manufacturing Market Competitive Environment
Listed leaders compete with private specialists across platform standardization and optical component supply. The vendor base stratifies into ecosystem orchestrators with pre-certified enterprise connectivity, point-solution specialists with deep CAD integration, and hardware fabricators with captive waveguide production. Three archetypes dominate: digital-twin platform bundlers, standalone headset manufacturers, and vertical workflow specialists. Competitive moves concentrate on strategic partnerships with MES vendors and backward integration into optical component supply.
Within the ecosystem orchestrator tier, Microsoft Corporation and Siemens exemplify platform bundling strategies that compress procurement evaluation cycles. PTC occupies a position among CAD-native specialists leveraging existing design pipeline relationships. These three anchors represent divergent approaches to enterprise IT governance consolidation.
| Leading Market Players |
|---|
| Microsoft Corporation |
| PTC |
| Siemens |
| Dassault Systemes |
| Unity Technologies |
| Vuzix Corporation |
| Google LLC |
| TeamViewer AG |
| ESI Group |
| Others |
Value Chain & Pricing Dynamics
Waveguide foundry scale economies in Taiwan and South Korea concentrate optical component supply, compressing unit economics for micro-OLED stacks while laser-beam-scanning alternatives from automotive HUD suppliers carve out premium outdoor visibility tiers.
Pricing Analysis
Current-generation HoloLens and Vuzix M400L deployments command 40-60 percent premiums over prior-generation monocular headsets, while next-generation laser-beam-scanning architectures targeting aerospace applications price at 2-3x indoor waveguide equivalents. Three-tier pricing structure across premium aerospace, standard automotive, and economy electronics contract manufacturing segments reflects certification grade and tracking accuracy differentiation. Cost compression in the economy tier intensifies because Taiwanese optics foundries are ramping dedicated production lines for both form factors. Mid-sized automotive suppliers in Germany's Stuttgart corridor exhibit the highest price sensitivity, while FAA-certified aerospace integrators absorb premium pricing for sub-millimeter accuracy guarantees.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam lane have elevated inbound logistics costs for German automotive suppliers sourcing waveguide components, though edge processor fabrication in Vietnam and Mexico is diversifying final assembly geography. Waveguide manufacturing draws from Taiwan, South Korea, and Japan, while laser scanning engines source from German automotive HUD specialists and Chinese precision optics houses. Single-source vulnerability concentrates in East Asian precision optics foundries, where 70-80 percent of industrial-grade waveguide capacity resides. Distribution runs through tier-one electronics contract manufacturers in Taiwan and South Korea, who bundle AR modules with OEM system integration contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AR manufacturing platforms are approaching an ecosystem-economics inflection where Siemens and PTC digital-twin interoperability is consolidating procurement authority under central IT governance, marginalizing point-solution specialists.
For Market Incumbents: Fortify enterprise connectivity moats by embedding EU AI Act compliance architectures ahead of enforcement timelines, while backward integration into waveguide supply through partnerships with Taiwanese optics foundries defends margin position against laser-beam-scanning substitutes. Microsoft and Siemens ecosystems must preempt ISO 9001 traceability middleware fragmentation that mid-sized system integrators exploit to win plant-level pilot contracts.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for AR-guided diagnostic workflows offer 12-18 month clearance advantages over full PMA submissions, creating beachhead opportunities in surgical training applications where human-in-the-loop documentation requirements are less stringent than autonomous quality control. India's PLI scheme for electronics manufacturing presents the most penetrable geography, with greenfield facilities in Tamil Nadu and Karnataka lacking mature technician bases and receptive to AR training platform pilots.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CAD-native software platforms with recurring licensing models over hardware fabricators facing optical component commoditization. Long-term viability across the analysis window hinges on digital-twin integration depth and MES interoperability certification. The signal to watch is procurement consolidation velocity under central IT governance, which concentrates vendor selection authority and compresses evaluation cycles for ecosystem players.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | PTC ThingWorx and Siemens Xcelerator ecosystems enable closed-loop feedback from virtual commissioning data to live operator guidance. |
| Certification Investment | EU AI Act high-risk system compliance architectures and FDA 510(k) pathways differentiate vendors in regulated aerospace and medical applications. |
| Backward Integration | Captive waveguide production through Taiwanese and South Korean foundry partnerships secures supply elasticity for German automotive suppliers. |
| Geographic Expansion | India's PLI scheme for electronics manufacturing channels first-mover budgets toward AR training platforms in Chennai-Bengaluru corridor. |
| Strategic Partnership | Microsoft HoloLens industrial ecosystem anchors enterprise deployments through pre-certified MES connectivity on North American factory floors. |
Study Parameters
The analysis maps hardware optics, software platforms, and services deployment, each validated through manufacturing engineering directors, CIO procurement leads, and AR platform product managers. Primary interviews with plant-level maintenance supervisors and digital-twin integration specialists combined with secondary validation from SEC 10-K filings, EU AI Act regulatory documentation, and FAA certification databases. Bottom-up unit economics for waveguide component production and top-down OEM R&D spending patterns were triangulated against MIIT industrial wireless standards and METI smart manufacturing support program disclosures.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures for edge computing infrastructure and IHS Markit automotive production data for Stuttgart and Munich corridor facilities. Segmentation dimensions modeled across the projection horizon include product architecture, use case complexity, end-user industry, and integration level with existing CAD and MES pipelines. CAGRs were derived from annualized spending trajectory analysis, with specific inputs from aerospace assembly line AR deployment timelines and electronics contract manufacturer training platform procurement cycles.
Decision-makers should treat outputs as directional under sustained EU AI Act enforcement timelines and stable East Asian waveguide supply capacity; material deviation in either would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart TV Platforms Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
8K Technology Market
Others
Europe Postal Services Market
Others
Level Measuring Instrument Market
Others
Africa Lime Market
Others
Vegetable Carbon Market
Others
Asia-Pacific Induced Pluripotent Stem Cells (Ipscs) Market
Others
HPHT Diamond Cubic Press Market
Others
Global OTA Testing Market
Others
Mobile Computer Cart Market
Others
Global Platform Trolley Market
Others
Post Consumer Recycled Bottles Market
Others
Digital Audio Decoders Market
Others
Hydrostatic Testing Market
Others
Couscous Market