
 Africa Lime Market | 2026-2036
Africa Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Lime Market Outlook
Water treatment plants is reorganizing procurement priorities across Africa, shifting volume toward quicklime and hydrated lime for municipal pH correction and sludge stabilization. Idwala Industrial Holdings (Pty) Ltd. anchors South African supply through integrated quarry-to-plant operations in the KwaZulu-Natal corridor. Afrimat Ltd. extends its reach via diversified industrial minerals infrastructure serving construction and agricultural buyers. Oyana Lime competes in West African markets through specialized logistics networks connecting Nigerian limestone deposits to regional industrial users.
Lime encompasses calcium oxide (quicklime) and calcium hydroxide (hydrated lime) produced by calcining limestone at temperatures exceeding 900 degrees Celsius, yielding products with 90-95% calcium content for industrial neutralization, soil amendment, and construction binding. Quicklime dominates value capture in mining-intensive economies where steel fluxing and gold processing absorb high-purity output, while hydrated lime generates expanding margin pools in water treatment applications across urbanizing regions. Construction companies and farmers represent the deepest end-user segments, with direct sales channels controlling bulk industrial volume and wholesalers managing fragmented agricultural demand.
South Africa's Department of Mineral Resources and Energy enforces mining charter compliance and environmental rehabilitation bonds for limestone extraction, while Nigeria's Federal Ministry of Mines and Steel Development imposes local content requirements on quarry licensing. Kenya's National Environment Management Authority regulates kiln emissions under air quality standards, pushing producers toward vertical shaft lime kilns with lower particulate profiles. Stakeholders must monitor how carbon border adjustment mechanisms in European export markets reshape process energy choices and product certification requirements for African lime destined for international industrial supply chains.
Market Dynamics
South Africa's Department of Mineral Resources and Energy has tightened mining licensing for limestone extraction, pushing operators toward cleaner processing methods while concentrating supply authority among integrated quarry-to-plant operators. This regulatory compression is restructuring competitive positioning across the continent.
Growth Catalysts
- Kenya's National Environment Management Authority air quality standards:Municipal water treatment facilities in Nairobi and Mombasa are scaling quicklime procurement for pH correction and sludge stabilization.
- East African infrastructure corridors:Road and rail construction projects across Tanzania, Uganda, and Ethiopia are absorbing high volumes of construction-grade lime for soil stabilization and asphalt binding.
- Vertical shaft lime kiln technology:Lower particulate emissions profiles are enabling producers to secure operating permits in urban-adjacent locations previously restricted by environmental enforcement.
Market Restraints
- Limestone feedstock concentration:High-calcium limestone deposits cluster in specific geological formations across the Northern Cape and Limpopo provinces, creating geographic supply vulnerability.
- Diesel and electricity cost volatility:Kiln operations and overland transport depend on petroleum derivatives and grid power subject to tariff fluctuations and load-shedding disruptions.
- Cement substitution in construction:Portland cement and pozzolanic binders capture volume in lower-specification applications where lime traditionally served as primary binder.
Strategic Opportunities
- Nigerian agricultural extension programs:Federal and state-level soil amendment initiatives are creating systematic demand for dolomitic lime in cocoa belt regions of Oyo and Osun states.
- Carbon border adjustment mechanism alignment:European export market access is incentivizing kiln energy efficiency retrofits and renewable fuel substitution for process heat.
- Direct-to-farmer digital channels:Mobile-enabled agronomy services are compressing distribution layers between producers and smallholder lime consumers in Kenya's Rift Valley.
Industry Challenges
- Kiln operator technical certification:Modern vertical shaft and rotary kiln technologies require specialized combustion engineering expertise scarce in regional labor markets.
- Environmental rehabilitation bond compliance:South African mining charter requirements demand upfront capital allocation for post-closure site remediation, straining balance sheets of mid-scale quarry operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Lime Market |
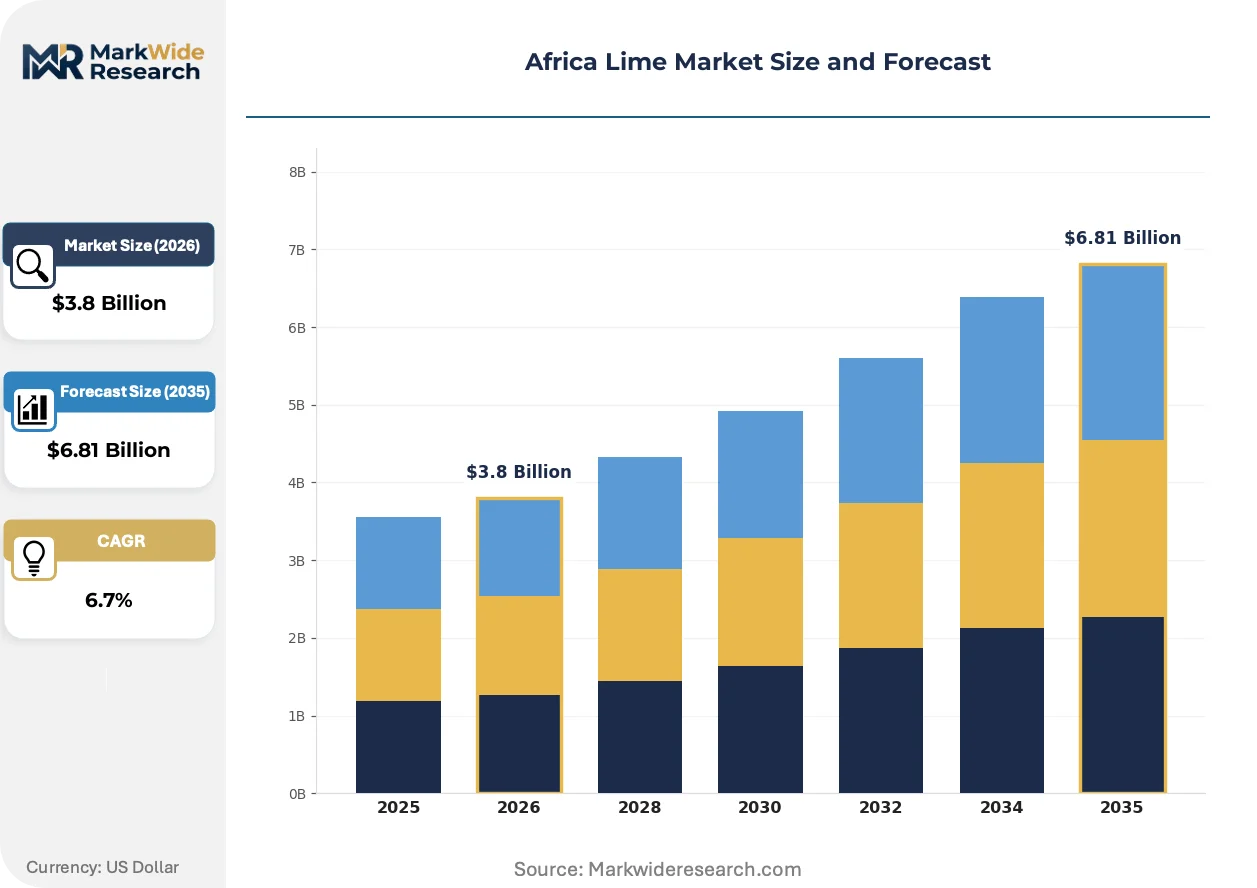
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Lime, Quicklime, Pulverized Lime, Limestone Application: Construction, Agriculture, Water Treatment, Industry End User: Construction Companies, Farmers, Water Treatment Plants, Industrial Manufacturers Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Platforms |
| Companies Covered | AFRILIME, Afrimat Ltd., Bontebok Limeworks Pty Ltd., GYPSOIL, Idwala Industrial Holdings (Pty) Ltd., Limeco, Omya International AG, Oyana Lime, SA Lime and Gypsum Pty Ltd., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Lime Market Strategic Shifts
Calcination technology and emissions control systems are actively restructuring production economics across African lime operations. Process intensification and digital kiln monitoring are compressing energy intensity while expanding output quality consistency.
Maerz parallel-flow regenerative kiln technology is supplanting traditional mixed-feed vertical kilns in high-purity quicklime applications. Gold processing facilities in Ghana and Burkina Faso are adopting these systems to meet metallurgical-grade specifications for cyanide leaching circuits. The technology is supplanting legacy kiln infrastructure by cutting fuel consumption per ton by roughly one-third while enabling automated temperature control.
Kenya's National Environment Management Authority enforces kiln emissions under air quality standards that mandate continuous particulate monitoring and baghouse filtration. Industrial lime producers in Athi River and Thika are retrofitting existing vertical shaft kilns with wet scrubber systems to secure operating licenses. Steel and water treatment buyers are now requiring emissions compliance documentation as a procurement gate.
Water treatment plants across Nigeria and Kenya are reorganizing procurement priorities, shifting volume toward quicklime and hydrated lime for municipal pH correction. Municipal buyers are consolidating supplier panels and demanding technical service support for dosing system integration. This concentration is most visible in Lagos and Nairobi, where metropolitan water authorities are issuing multi-year framework agreements to qualified chemical suppliers.
Africa Lime Market Segmentation
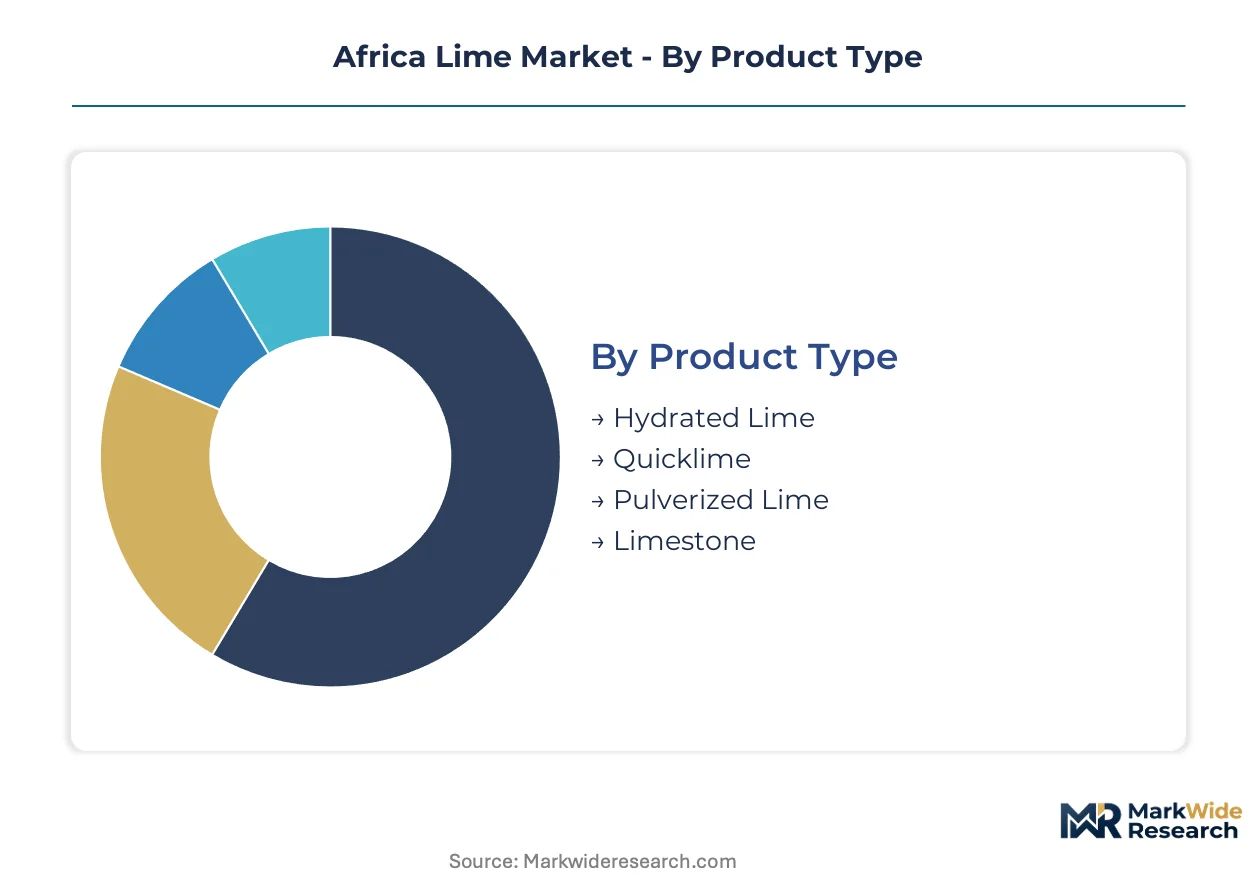
Lime products serve fundamentally different economic functions across Africa, from metallurgical fluxing to soil amendment. Segment boundaries reflect calcination intensity, purity grades, and the logistics networks required to reach dispersed agricultural buyers versus concentrated industrial offtake.
Product Type:
Margin pools concentrate in high-purity quicklime for gold processing and steel fluxing, where technical specifications command premium pricing over construction-grade alternatives.
- Quicklime:Calcium oxide produced at temperatures exceeding 900 degrees Celsius yields 90-95% calcium content for cyanide leaching circuits in Ghanaian gold mines and steel desulfurization. Demand concentrates in South Africa's Northern Cape mining belt, where metallurgical specifications filter out lower-grade suppliers.
- Hydrated Lime:Slaked calcium hydroxide delivers controlled reactivity for water treatment pH correction and flue gas desulfurization. Municipal procurement in Lagos and Nairobi is consolidating supplier panels around technical service capabilities for dosing system integration.
- Pulverized Lime:Finely ground agricultural grade spreads across cocoa belt regions of Oyo and Osun states under Nigerian federal soil amendment programs.
- Limestone:Unprocessed carbonate feedstock serves cement kiln input and dimensional stone applications, with extraction licensing tightening under South Africa's mining charter compliance requirements.
The dominant share belongs to Quicklime, while Hydrated Lime is closing the gap fastest as urban water treatment infrastructure expands.
Application:
Volume distribution tracks infrastructure investment cycles and agricultural extension program rollouts across East and West African markets.
- Construction:Soil stabilization for road and rail corridors across Tanzania, Uganda, and Ethiopia absorbs bulk construction-grade lime, though Portland cement substitution is eroding traditional binding applications in lower-specification projects.
- Water Treatment:Municipal pH correction and sludge stabilization in Nairobi and Mombasa is scaling procurement volumes, with Kenya's National Environment Management Authority air quality standards pushing producers toward vertical shaft kiln retrofits.
- Agriculture:Dolomitic lime application in Kenya's Rift Valley and Nigerian cocoa regions addresses soil acidity, with mobile-enabled agronomy services compressing distribution layers to smallholder farmers.
- Industry:Steel fluxing, gold processing, and chemical manufacturing absorb high-purity output from integrated quarry-to-plant operators in South Africa's KwaZulu-Natal corridor.
Construction retains volume leadership, though Water Treatment is expanding most quickly as metropolitan authorities issue multi-year framework agreements.
End User:
Customer concentration varies sharply between consolidated industrial buyers and fragmented agricultural demand requiring layered distribution infrastructure.
- Industrial Manufacturers:Steel mills and gold processing facilities in Ghana and Burkina Faso specify Maerz kiln output for metallurgical-grade consistency, with emissions compliance documentation now a procurement gate.
- Water Treatment Plants:Metropolitan water authorities in Lagos and Nairobi are reorganizing procurement priorities toward quicklime and hydrated lime, demanding technical service support that favors qualified chemical suppliers over commodity traders.
- Construction Companies:Road and rail contractors across East African infrastructure corridors absorb high volumes of construction-grade lime for soil stabilization and asphalt binding.
- Farmers:Smallholder cocoa producers in Oyo state and maize growers in Kenya's Rift Valley purchase through agricultural cooperatives and mobile-enabled direct channels.
Industrial Manufacturers command the highest per-ton margins, while Farmers represent the deepest volume pool despite distribution complexity.
Distribution Channel:
Channel economics reflect shipment density, technical service requirements, and the geographic dispersion of agricultural end users.
- Direct Sales:Bulk industrial contracts from integrated producers like Idwala Industrial Holdings serve steel mills and gold processing facilities with dedicated logistics and technical support.
- Wholesalers:Regional distributors manage fragmented agricultural demand across Nigeria's cocoa belt and Kenya's Rift Valley, aggregating smallholder orders into economic shipment sizes.
- Retailers:Agricultural supply stores in peri-urban areas stock bagged lime for immediate farmer pickup, though volume per transaction remains low.
- Online Platforms:Mobile-enabled agronomy services are emerging in Kenya, connecting producers directly to smallholders and compressing traditional distribution layers.
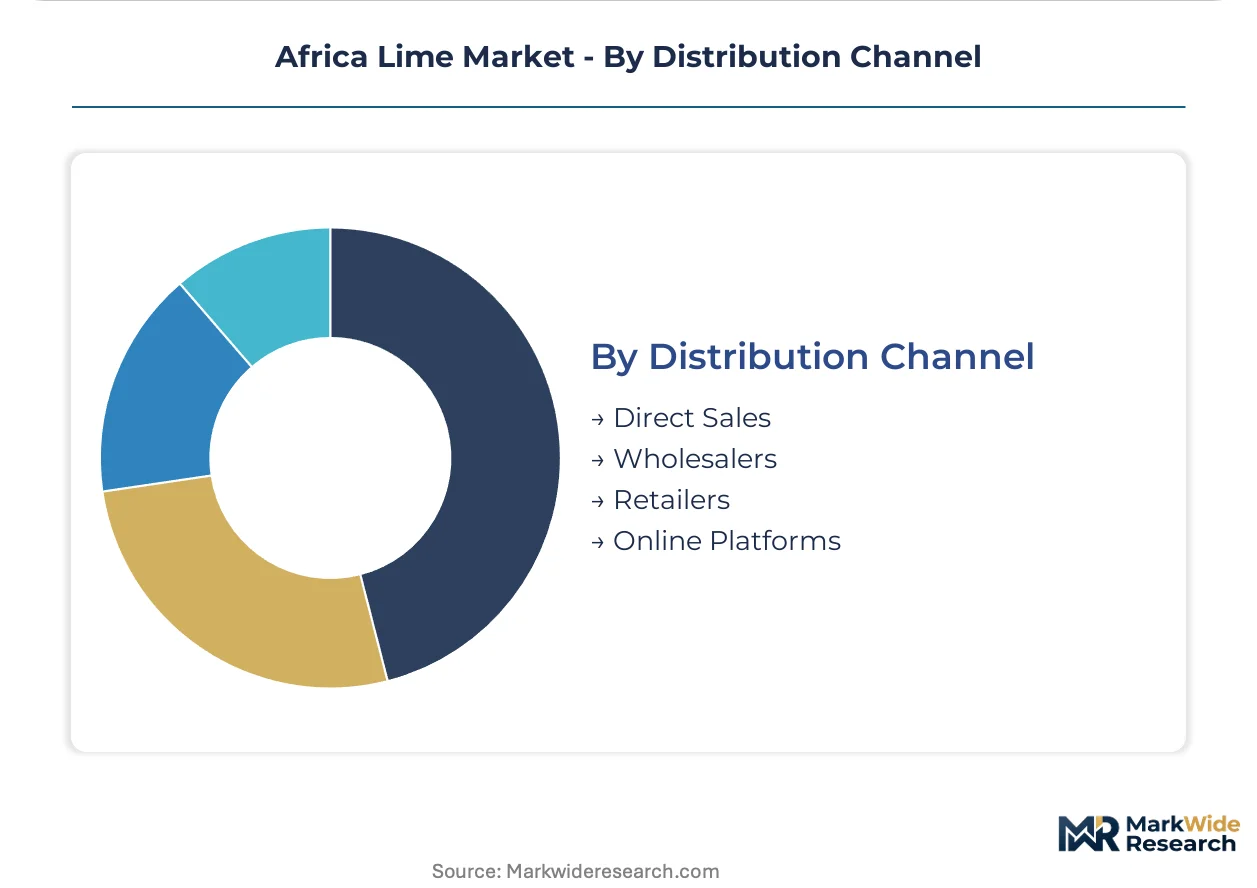
Direct Sales captures the highest value per ton, while Online Platforms are gaining traction fastest among digitally connected smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers concentrate procurement authority in South Africa's mining belt, while municipal water authorities in Nigeria and Kenya drive volume expansion through infrastructure modernization programs. Agricultural cooperatives across East and West Africa aggregate fragmented smallholder demand into economic shipment sizes.
South Africa
Gold processing facilities and steel mills in the Northern Cape absorb metallurgical-grade quicklime for cyanide leaching and desulfurization circuits. The Department of Mineral Resources and Energy enforces mining charter compliance and environmental rehabilitation bonds for limestone extraction. Integrated quarry-to-plant operators in the KwaZulu-Natal corridor control supply authority through captive limestone deposits.
Nigeria
Federal and state-level soil amendment initiatives in Oyo and Osun states generate systematic demand for dolomitic lime across cocoa belt regions. The Federal Ministry of Mines and Steel Development imposes local content requirements on quarry licensing for limestone extraction. Specialized logistics networks connect Nigerian limestone deposits to regional industrial users in Lagos and surrounding manufacturing zones.
Kenya
Metropolitan water authorities in Nairobi and Mombasa are scaling quicklime procurement for municipal pH correction and sludge stabilization. The National Environment Management Authority regulates kiln emissions under air quality standards mandating continuous particulate monitoring. Producers in Athi River and Thika are retrofitting vertical shaft kilns with wet scrubber systems to secure operating permits.
Ghana
Gold processing facilities are adopting Maerz parallel-flow regenerative kiln technology to meet metallurgical-grade specifications for cyanide leaching circuits. The country's national mining regulator enforces environmental standards for calcination operations near residential areas. Industrial lime demand concentrates around Obuasi and Tarkwa mining districts where high-purity output commands premium pricing.
Tanzania
Road and rail construction projects across central corridor infrastructure networks absorb construction-grade lime for soil stabilization and asphalt binding. The national environment authority mandates emissions documentation for kiln operations in urban-adjacent locations. Bulk material suppliers in Dar es Salaam coordinate overland shipment to interior project sites facing diesel cost volatility.
Africa Lime Market Competitive Environment
Player mix skews toward integrated quarry-to-plant operators controlling captive limestone reserves and specialized logistics networks serving fragmented agricultural demand. Market structure concentrates supply authority among South African industrial mineral conglomerates with backward integration into mining assets. Three archetypes dominate: metallurgical-grade specialists serving gold and steel processors, construction-grade bulk suppliers tied to infrastructure projects, and agricultural lime distributors leveraging cooperative networks. Competitive moves center on kiln technology licensing for emissions compliance and direct-to-farmer digital channel development compressing traditional wholesale layers.
Among South Africa-based integrated operators, Idwala Industrial Holdings (Pty) Ltd. and Afrimat Ltd. exemplify the quarry-to-plant archetype through diversified industrial minerals infrastructure. Oyana Lime occupies a position within the West African logistics-specialist tier, connecting Nigerian limestone deposits to regional industrial users. These three entities represent distinct competitive vectors: captive resource control, multi-mineral portfolio diversification, and geographic specialization through distribution network density.
| Leading Market Players |
|---|
| AFRILIME |
| Afrimat Ltd. |
| Bontebok Limeworks Pty Ltd. |
| GYPSOIL |
| Idwala Industrial Holdings (Pty) Ltd. |
| Limeco |
| Omya International AG |
| Oyana Lime |
| SA Lime and Gypsum Pty Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at South Africa's integrated quarry-to-plant operations anchors regional price floors, with kiln scale economics concentrating supply authority among operators controlling captive limestone deposits in the KwaZulu-Natal and Northern Cape corridors. This scale concentration feeds into contract structures that index fuel and electricity tariffs, transmitting diesel cost volatility and grid load-shedding disruptions directly into delivered lime pricing across municipal and industrial buyers.
Pricing Analysis
Cost-plus contracts with diesel and electricity indexation dominate bulk industrial procurement from integrated producers like Idwala Industrial Holdings and Afrimat Ltd. Price differentiation rests on calcium purity grade and emissions compliance certification, with metallurgical-grade quicklime for Ghanaian gold processing commanding substantial premiums over construction-grade alternatives. Pricing pressure stems from cement substitution in lower-specification binding applications, eroding traditional lime volume. Municipal water treatment authorities in Lagos and Nairobi exhibit the highest price sensitivity due to budget-constrained procurement frameworks, while gold processing facilities demonstrate lowest sensitivity given metallurgical-grade specifications that filter out lower-tier suppliers.
Supply Chain Analysis
South Africa and Nigeria anchor limestone extraction and calcination capacity across the continent, with Ghana and Kenya emerging as specialized processing hubs for metallurgical-grade and water-treatment applications respectively. Raw material dependencies center on high-calcium limestone feedstock from the Northern Cape and Limpopo geological formations, petroleum derivatives for kiln firing and overland transport, and grid electricity subject to tariff fluctuations. Single-source vulnerability concentrates in limestone deposit geography, with limited alternative high-calcium formations creating supply risk. Distribution runs through direct sales channels for consolidated industrial buyers and layered wholesale networks for fragmented agricultural demand across Nigeria's cocoa belt and Kenya's Rift Valley.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for dosing system integration and emissions compliance documentation represent a service-attach opportunity expanding faster than commodity lime sales, as metropolitan water authorities in Lagos and Nairobi consolidate supplier panels around qualified chemical suppliers with integrated support capabilities.
For Market Incumbents: Consolidate supply authority through captive limestone reserve acquisition in the Northern Cape and Limpopo provinces, while retrofitting vertical shaft kilns with wet scrubber systems to preempt Kenya's National Environment Management Authority enforcement actions. Cement substitution in road construction poses immediate volume threat; defend position through backward integration into agricultural lime distribution networks compressing wholesale layers to smallholder farmers in Oyo state and Kenya's Rift Valley. For New Entrants and Emerging Players: Kenya's National Environment Management Authority air quality compliance certification offers a fast-track entry path for urban-adjacent kiln operations previously restricted by particulate emissions enforcement. Target Nigerian agricultural extension programs in Osun state cocoa regions where systematic dolomitic lime demand outpaces established supply infrastructure. Deploy mobile-enabled agronomy platforms to establish direct-to-farmer channels, bypassing traditional cooperative aggregation layers that dominate incumbent distribution economics. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated quarry-to-plant operators with Maerz kiln licensing and captive high-calcium limestone deposits, as fuel efficiency retrofits and renewable fuel substitution become prerequisites for European carbon border adjustment mechanism alignment. Long-term viability rests on service-attach revenue from technical dosing support and emissions documentation rather than commodity volume alone. Watch for Kenya's National Environment Management Authority permit renewal cycles as inflection indicators for competitive repositioning among urban-adjacent producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Captive supply from Northern Cape deposits secures feedstock against South Africa's mining charter licensing compression. |
| Vertical Shaft Kiln Emissions Retrofit | Wet scrubber installation enables permit compliance under Kenya's National Environment Management Authority air quality standards. |
| Long-term Municipal Supply Agreement | Multi-year frameworks with Lagos and Nairobi water authorities lock in volume against cement substitution pressure. |
| Direct-to-Farmer Digital Channel | Mobile agronomy platforms compress distribution layers to smallholders in Nigeria's cocoa belt and Kenya's Rift Valley. |
| Maerz Kiln Technology Licensing | Parallel-flow regenerative systems cut fuel consumption by one-third for Ghanaian gold processing metallurgical-grade specifications. |
Study Parameters
A spread of perspectives from kiln operations managers, municipal water treatment procurement officers, agricultural cooperative aggregators, and mining charter compliance consultants converged on the working assumptions shaping this analysis. Primary field engagement with producers in Athi River, Thika, and the KwaZulu-Natal corridor combined with secondary validation from South Africa's Department of Mineral Resources and Energy licensing records, Nigeria's Federal Ministry of Mines and Steel Development quarry registrations, and Kenya's National Environment Management Authority emissions permits. Bottom-up shipment data triangulated against top-down infrastructure investment tracking across East African corridor projects.
Segmentation dimensions modeled include product type tier, application end-use, customer concentration archetype, and distribution channel structure across the projection horizon. CAGRs derived from regression analysis of historical volume trends against announced infrastructure spending and agricultural extension program rollouts. Industry-specific forecast inputs incorporated kiln capacity utilization rates and limestone deposit depletion schedules from mining charter compliance filings.
Underlying assumptions cover regulatory enforcement continuity, fuel tariff indexation patterns, and infrastructure project execution timelines, with deviation risk concentrated in South Africa's load-shedding severity and Nigeria's agricultural subsidy program sustainability. Recalibration cycles align with material shifts in mining charter compliance requirements and carbon border adjustment mechanism implementation schedules affecting European export market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Bitcoin Mining Hardware Market
Others
Asia-Pacific Intercom Devices Market
Others
Fenoxanil Market
Others
Vortexers Market
Others
Europe Refrigerated Display Cases Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Egg and Egg Products Market
Others
Silicone Molding Machinery Market
Others
Solar Panel Testers Market
Others
High-End Servers Market
Others
Pollen Allergy Market
Others
Rotary Union Market
Others
Signal Transformer Market
Others
Global Military Lighting Market
Others
Video Paas Market
Others
Wearable AI Market