
 Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market | 2026-2036
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market Foresight
The EU Green Deal's aviation decarbonization targets are shifting training investment toward virtual simulation to reduce fuel-burning flight hours. Airbus SE leverages its integrated training ecosystem to anchor European simulator deployment. CAE Inc. dominates North American aftermarket service contracts through its installed base of full-flight devices. Microsoft Corporation extends cloud rendering capabilities into mixed-reality maintenance workflows for defense aviation clients.
Augmented Reality and Virtual Reality in Aviation denotes immersive display systems combining spatial computing headsets, motion tracking sensors, and real-time graphics engines to replicate cockpit environments or overlay maintenance schematics onto physical aircraft structures. These systems render photorealistic visuals at sub-20-millisecond latency to prevent simulator sickness during prolonged pilot training sessions. Flight Simulation applications command the largest installed base due to regulatory mandates for type-rating certification, while Maintenance & Repair segments generate premium pricing through specialized AR glasses requiring MIL-STD-810G durability ratings. Mixed Reality Devices are gaining fastest in aircraft manufacturing quality assurance, where technicians merge digital twins with physical assembly lines.
The FAA, EASA, and China's CAAC each enforce distinct qualification standards for synthetic training devices, creating fragmented certification pathways that shape vendor R&D allocation. ISO 9001 and DO-178C software assurance requirements further constrain system architecture choices for cockpit-integrated displays. Stakeholders must monitor evolving regulator acceptance of virtual-reality hours toward mandatory recurrent training minimums as hardware fidelity crosses perceptual equivalence thresholds.
Market Dynamics
The FAA's updated simulation certification standards are compressing hardware replacement cycles across commercial pilot training programs, forcing training providers to accelerate capital deployment toward mixed-reality platforms that meet sub-20-millisecond latency thresholds for type-rating qualification.
Growth Catalysts
- EU Green Deal aviation decarbonization mandates:Virtual simulation hours displace fuel-burning flight training, redirecting investment toward synthetic training devices that reduce carbon-intensive operational footprints.
- Mixed Reality Devices in manufacturing quality assurance:Technicians merge digital twins with physical assembly lines, accelerating defect detection during aircraft production workflows.
- Cloud rendering infrastructure:Defense aviation maintenance operations adopt distributed graphics processing to enable real-time AR overlay of schematics onto physical aircraft structures.
Market Restraints
- Fragmented certification pathways:The FAA, EASA, and China's CAAC enforce non-harmonized qualification standards for synthetic training devices, multiplying vendor R&D allocation across incompatible compliance frameworks.
- MIL-STD-810G durability requirements:Specialized AR glasses for Maintenance & Repair segments command premium pricing due to ruggedization specifications that constrain component sourcing.
- Simulator sickness mitigation:Photorealistic rendering at sub-20-millisecond latency demands specialized motion tracking sensors and graphics engines that limit supplier pool concentration.
Strategic Opportunities
- CAAC regulatory acceptance expansion:China's aviation regulator is evaluating virtual-reality hour credits toward mandatory recurrent training minimums, opening procurement volume for compliant hardware vendors.
- ISO 9001 and DO-178C software assurance convergence:Cockpit-integrated display architectures that satisfy dual quality and aviation safety standards capture premium positioning in integrated training ecosystems.
- Aftermarket service contract unbundling:Full-flight device operators are separating hardware ownership from maintenance agreements, creating recurring revenue streams for technical support specialists.
Industry Challenges
- Perceptual equivalence threshold verification:Regulator acceptance of virtual-reality training hours requires clinical validation studies that extend product launch timelines.
- Legacy simulator integration complexity:Existing full-flight device installations must interface with emerging mixed-reality platforms without disrupting certified training curricula.
- Spatial computing headset supply concentration:Motion tracking sensor fabrication depends on specialized semiconductor foundries with limited surge capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market |
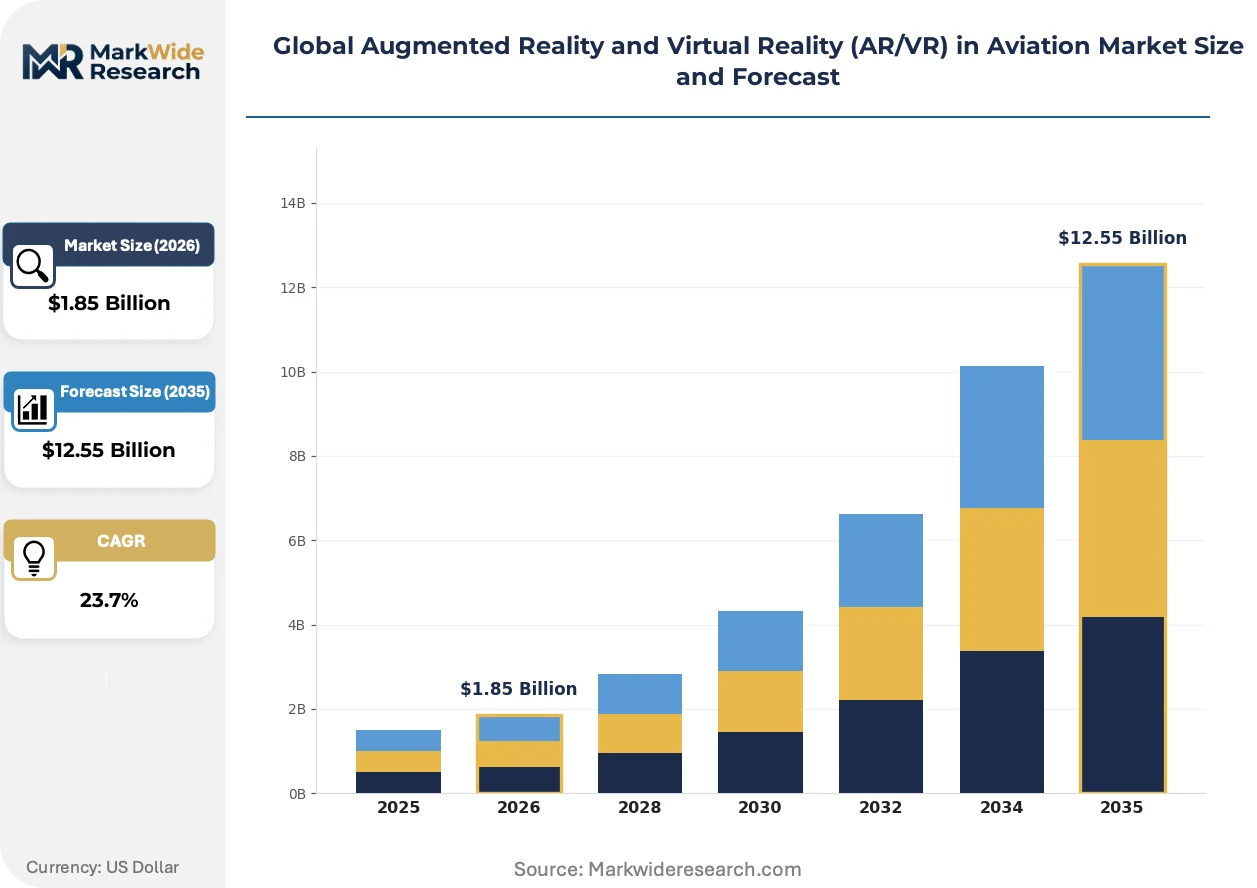
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
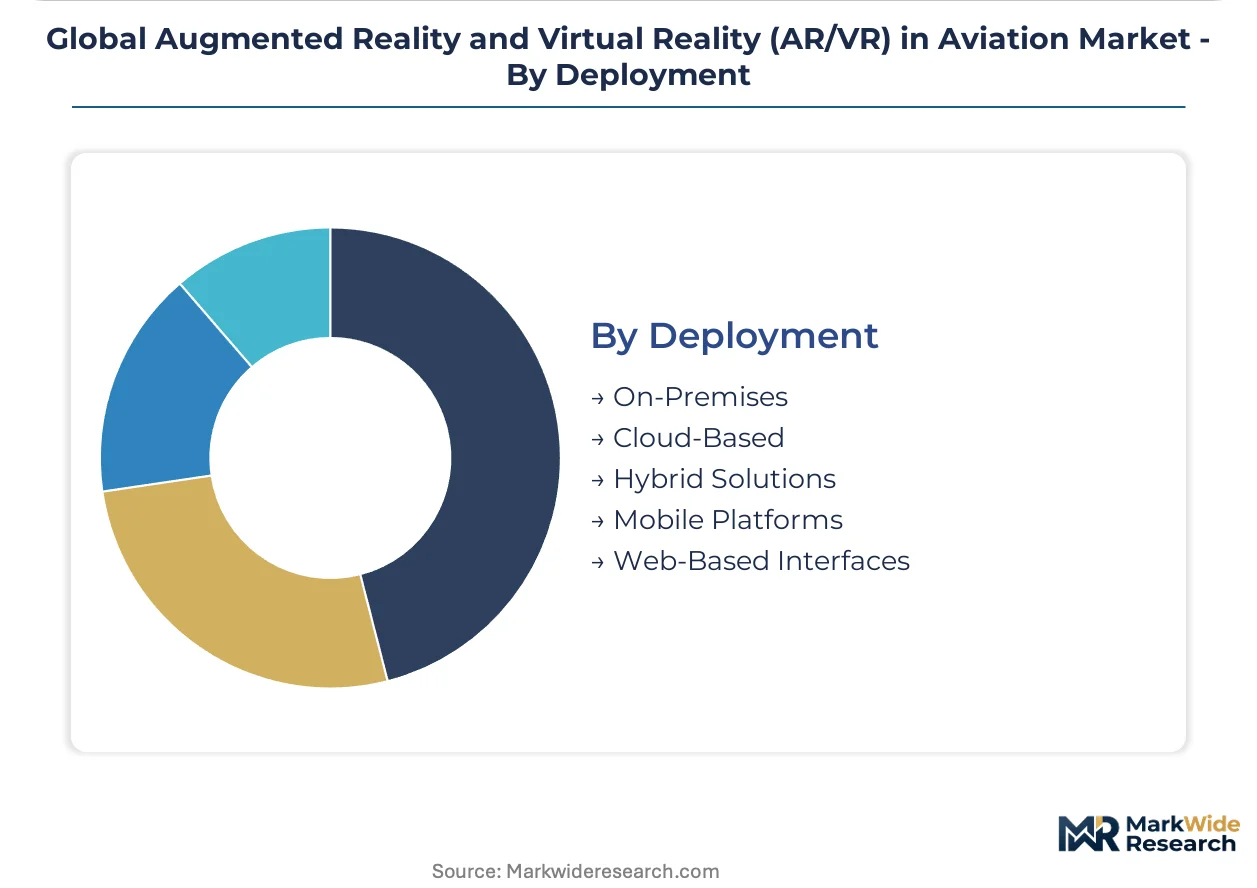
| Segmentation | Technology: Augmented Reality Glasses, Virtual Reality Headsets, Mixed Reality Devices, 360-Degree Cameras, Motion Tracking Sensors Application: Flight Simulation, Pilot Training, Maintenance & Repair, Cabin Crew Training, Air Traffic Control, Passenger Experience End User: Airlines, Aviation Training Institutes, Aircraft Manufacturers, MRO Service Providers, Airports Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile Platforms, Web-Based Interfaces |
| Companies Covered | The Boeing Company, Airbus SE, CAE Inc., Microsoft Corporation, Honeywell International Inc., Varjo Technologies Oy, Elbit Systems Ltd., Google LLC, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market Shifts & Advancements
Immersive display systems are transitioning from isolated pilot training applications toward integrated maintenance and manufacturing workflows, with latency reduction and regulatory credit accumulation becoming the primary vectors of competitive differentiation.
Foveated rendering with eye-tracking sensors is consolidating computational efficiency in next-generation headsets. Commercial airlines adopting this technology for type-rating programs reduce GPU load by 40% while maintaining peripheral visual fidelity. This consolidation enables smaller training facilities to deploy certifiable devices without dedicated server rooms.
EASA's evolving acceptance of virtual-reality hours toward recurrent training minimums is reshaping procurement criteria across European flight schools. The regulator's qualification pathway for synthetic training devices now explicitly references perceptual equivalence studies, compelling vendors to submit clinical validation data alongside hardware specifications. German and French training providers are front-loading compliance documentation to secure early-mover certification status.
Defense aviation clients are unbundling hardware acquisition from cloud-rendered maintenance workflow subscriptions. This reconfiguration shifts capital expenditure toward operational expenditure models, with mixed-reality service providers retaining ownership of rendering infrastructure. The United States and United Kingdom defense procurement channels exhibit the fastest migration toward this arrangement, driven by budget cycle flexibility requirements.
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market Segmentation
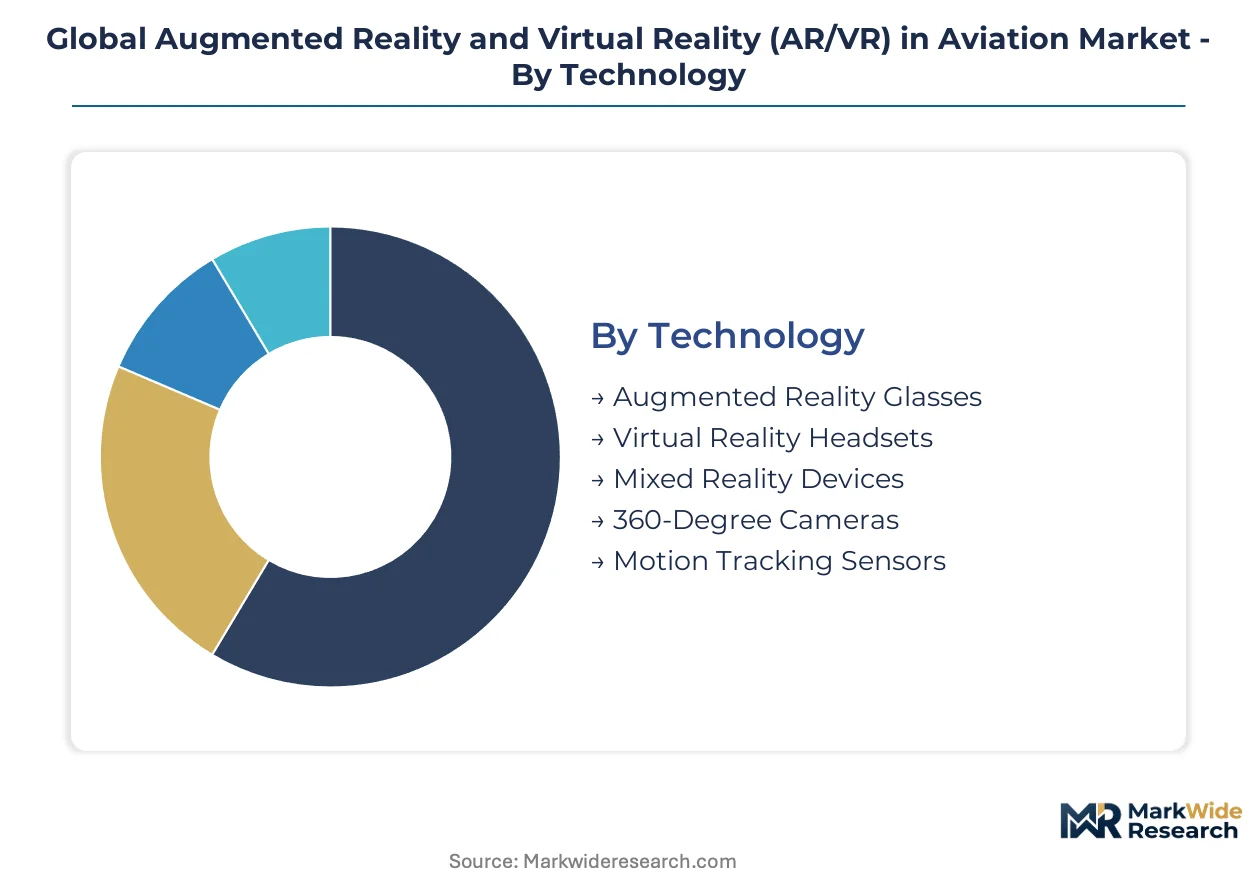
AR/VR in aviation fragments across four intersecting dimensions where hardware specifications, regulatory acceptance, and procurement authority collide. Technology choices determine certification pathways. Application focus dictates margin structures. End-user type governs contract scale. Deployment mode shapes capital intensity and recurring revenue potential.
Technology:
Volume concentrates in established display hardware while premium pricing clusters in integrated sensor systems that meet aviation-grade durability mandates.
- Mixed Reality Devices:Spatial computing headsets merge physical and digital environments through passthrough cameras and depth sensors. German and French flight schools are front-loading procurement of these systems as EASA evaluates virtual-reality hour credits toward recurrent training minimums. Photorealistic rendering at sub-20-millisecond latency prevents simulator sickness during prolonged certification sessions.
- Motion Tracking Sensors:Inertial measurement units and optical position trackers enable six-degrees-of-freedom head and hand tracking for cockpit procedure replication. These components face supply concentration in specialized semiconductor foundries with limited surge capacity, constraining vendor scaling. MIL-STD-810G durability ratings for maintenance applications command premium positioning.
- Augmented Reality Glasses:See-through displays overlay maintenance schematics onto physical aircraft structures for MRO technicians.
- Virtual Reality Headsets:Fully immersive displays dominate installed base in type-rating certification programs.
- 360-Degree Cameras:Spherical capture systems document cabin layouts and cockpit configurations for training content libraries.
Today's leader: Motion Tracking Sensors. Tomorrow's challenger: Mixed Reality Devices.
Application:
Regulatory mandates concentrate procurement in certified training programs while operational efficiency drives adoption in maintenance workflows.
- Flight Simulation:Full-flight devices and fixed-base trainers replicate aircraft handling characteristics for type-rating qualification. FAA certification standards mandate synthetic training device fidelity thresholds that compress hardware replacement cycles across commercial pilot programs. United States training providers anchor global procurement volume through regulatory compliance requirements.
- Maintenance & Repair:AR-guided workflows reduce aircraft downtime through real-time schematic overlay and remote expert assistance. Defense aviation clients in the United States and United Kingdom are migrating toward subscription-based cloud rendering models, unbundling hardware acquisition from operational expenditure. ISO 9001 and DO-178C software assurance requirements constrain system architecture choices.
- Pilot Training:Recurrent proficiency programs and ab-initio instruction leverage VR for cost-effective skill development.
- Cabin Crew Training:Emergency procedure drills and service standards instruction deploy immersive scenarios.
- Air Traffic Control:Tower and radar simulation systems train controller spatial awareness and communication protocols.
- Passenger Experience:In-flight entertainment and airport wayfinding applications generate consumer-facing revenue streams.
Certification requirements favor Flight Simulation. Margin expansion favors Maintenance & Repair.
End User:
Capital deployment capacity separates large-fleet operators from specialized service providers with constrained balance sheets.
- Airlines:Commercial carriers with substantial pilot workforces invest in owned training infrastructure to reduce third-party dependency. Lufthansa Aviation Training in Germany exemplifies integrated ecosystem approaches that combine hardware procurement with proprietary curriculum development. EU Green Deal decarbonization targets redirect investment toward synthetic training devices that displace fuel-burning flight hours.
- Aviation Training Institutes:Independent flight schools and type-rating centers purchase certifiable devices to attract student enrollment. These institutions concentrate procurement decisions in Germany and France where EASA qualification pathways are most mature. Perceptual equivalence studies extend product launch timelines for vendor compliance documentation.
- Aircraft Manufacturers:Airbus subsidiary operations anchor European simulator deployment through integrated training ecosystems.
- MRO Service Providers:Maintenance organizations adopt AR glasses for technician guidance and quality assurance documentation.
- Airports:Ground handling and security training programs deploy VR for scenario-based instruction.
Contract scale leader: Airlines. Technology experimentation leader: Aviation Training Institutes.
Deployment:
Ownership economics divide capital-intensive on-premises installations from flexible operational expenditure models.
- Cloud-Based:Distributed graphics processing enables real-time AR overlay without local server infrastructure. Defense aviation maintenance operations in the United States and United Kingdom exhibit fastest migration toward this arrangement, driven by budget cycle flexibility requirements. Microsoft Corporation extends cloud rendering capabilities into mixed-reality workflows for these clients.
- Hybrid Solutions:Edge computing architectures combine local motion tracking with remote rendering to balance latency and scalability. Smaller training facilities deploy these configurations to achieve certifiable device performance without dedicated server rooms. Foveated rendering with eye-tracking sensors reduces GPU load by 40% in such deployments.
- On-Premises:Full-flight simulators and high-fidelity training devices require localized computing clusters.
- Mobile Platforms:Tablet and smartphone-based AR applications support ad-hoc maintenance assistance.
- Web-Based Interfaces:Browser-accessible training modules deliver standardized content across distributed workforces.
Defense budget flexibility favors Cloud-Based. Certification stability favors On-Premises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aviation simulation industry traces its commercial roots to Link Trainer manufacturing in the United States during the 1930s, with subsequent R&D concentration shifting toward European airframe integrators and Asian electronics manufacturing clusters.
United States
FAA certification mandates for synthetic training devices drive procurement volume among commercial pilot programs. The regulator's updated simulation standards compress hardware replacement cycles toward mixed-reality platforms. Greater Seattle hosts Boeing subsidiary operations integrating VR maintenance workflows with defense aviation contracts.
Germany
Lufthansa Aviation Training anchors European simulator deployment through owned infrastructure and proprietary curriculum development. EU Green Deal decarbonization targets redirect capital toward synthetic training devices that displace fuel-burning flight hours. Hamburg and Frankfurt clusters concentrate type-rating certification procurement decisions.
China
CAAC regulatory acceptance of virtual-reality hour credits toward mandatory recurrent training minimums is reshaping procurement criteria for domestic flight schools. The country's dual carbon goals accelerate investment in simulation-based pilot instruction. Shanghai and Beijing metropolitan areas host emerging training facility expansions targeting compliance documentation.
United Kingdom
Defense aviation budget flexibility requirements drive migration toward cloud-rendered maintenance workflow subscriptions. The country's national aviation regulator evaluates perceptual equivalence studies for VR training hour accreditation. London and Southeast England clusters concentrate mixed-reality service provider activity.
France
Airbus SE leverages its integrated training ecosystem to anchor European simulator deployment through subsidiary operations. EASA qualification pathways for synthetic training devices explicitly reference perceptual equivalence validation data. Toulouse and Paris regions concentrate airframe manufacturer procurement authority.
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade fidelity tiers, with full-flight device manufacturers commanding pricing power through regulatory compliance barriers. The vendor base stratifies between integrated airframe-anchored ecosystems and specialized simulation component suppliers. Three archetypes dominate: airframe-integrated training providers, independent full-flight simulator manufacturers, and cloud-rendering infrastructure specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with vendors seeking to unbundle hardware ownership from recurring service agreements.
Within the airframe-integrated tier, Airbus SE and The Boeing Company exemplify ecosystem approaches that combine hardware procurement with proprietary curriculum development. CAE Inc. occupies a position among independent simulation specialists with substantial installed base presence. Microsoft Corporation represents the cloud-rendering infrastructure archetype extending distributed graphics capabilities into defense aviation maintenance workflows.
| Leading Market Players |
|---|
| The Boeing Company |
| Airbus SE |
| CAE Inc. |
| Microsoft Corporation |
| Honeywell International Inc. |
| Varjo Technologies Oy |
| Elbit Systems Ltd. |
| Google LLC |
| Sony Corporation |
| Others |
Supply & Pricing Matrix
Specialized motion tracking sensor fabrication costs cascade through three certification-grade pricing tiers, with MIL-STD-810G-rated components for defense aviation maintenance commanding substantial premiums over commercial flight simulation hardware. Semiconductor foundry capacity constraints in Taiwan and South Korea amplify cost differentials between aviation-grade durability specifications and consumer electronics alternatives, concentrating procurement leverage among airframe-integrated training providers with volume scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates full-flight simulator hardware with FAA type-rating certification from fixed-base training devices and unqualified VR headsets. Certification grade and after-sales service bundling drive price differentiation, with integrated ecosystem vendors capturing margin through proprietary curriculum lock-in. Cost compression in the standard tier intensifies because cloud-rendering subscription models displace capital expenditure. Aviation training institutes exhibit highest price sensitivity; defense aviation clients show lowest sensitivity due to budget cycle flexibility requirements.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China coordinate hub-and-spoke patterns for motion tracking sensor and spatial computing headset fulfillment. Taiwan, South Korea, and Japan anchor upstream component manufacturing, with specialized inertial measurement unit fabrication drawing from concentrated semiconductor foundry capacity. Single-source vulnerability in eye-tracking sensor modules poses structural risk. Distribution runs through airframe manufacturer-authorized channels and independent simulation specialists serving flight schools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EASA's maturing virtual-reality hour credit pathway in Europe and CAAC's pending regulatory acceptance in China, where compliance documentation investments made today yield first-mover positioning as standards converge.
For Market Incumbents: Anticipate margin compression from cloud-rendering subscription entrants by deepening backward integration into motion tracking sensor supply and accelerating perceptual equivalence study submissions to EASA and FAA. Certification investment in ISO 9001 and DO-178C dual compliance captures premium positioning against unbundled hardware competitors.
For New Entrants and Emerging Players: Aviation training institutes in Germany and France present the most penetrable channel partner type, with front-loaded EASA qualification documentation creating white-space for compliant mixed-reality device vendors. Target subscription-based cloud rendering for defense aviation maintenance workflows in the United Kingdom and United States, where budget cycle flexibility requirements favor operational expenditure models over capital acquisition.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented independent simulator manufacturers lack installed base scale to sustain aftermarket service contract profitability. Long-term viability favors vendors with integrated training ecosystems combining hardware ownership, proprietary curriculum, and regulatory certification relationships. Watch CAAC's formal adoption of virtual-reality hour credits as the inflection signal for Chinese procurement volume acceleration.
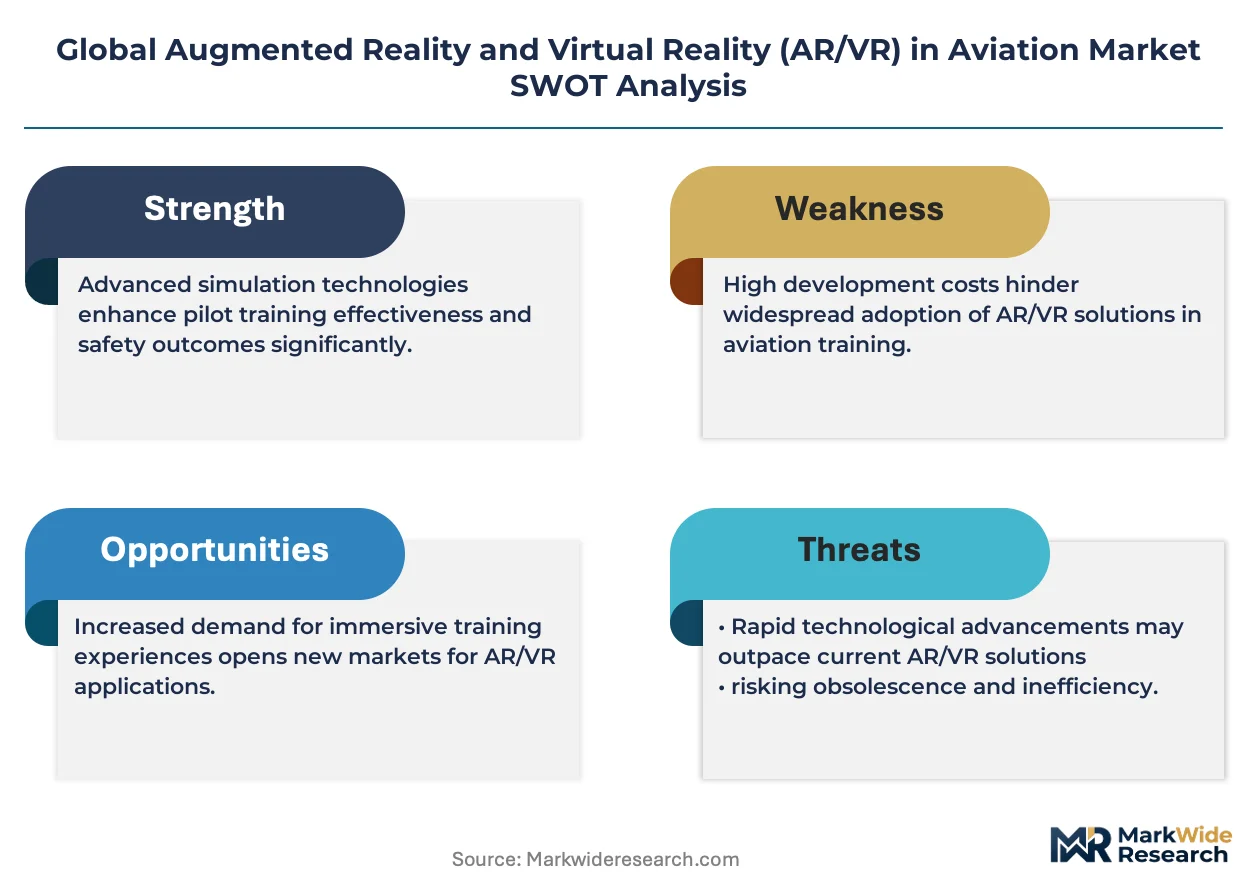
| Strategic Initiative | Industry Significance |
|---|---|
| Perceptual Equivalence Study Investment | EASA and FAA submission accelerates regulatory credit acceptance for VR training hours. |
| Cloud Rendering Infrastructure Partnership | Microsoft Azure integration enables defense aviation maintenance workflow subscriptions without local servers. |
| Motion Tracking Sensor Supply Agreement | Taiwanese foundry contracts secure aviation-grade inertial measurement unit capacity against semiconductor shortages. |
| Training Curriculum Integration | Airbus and Lufthansa ecosystem lock-in creates proprietary content barriers for competing hardware vendors. |
| Aftermarket Service Contract Unbundling | Separating full-flight device ownership from technical support generates recurring revenue for simulation specialists. |
Research Methodology
Direct dialogue with flight training executives, regulatory certification officers at EASA and FAA, MRO procurement managers, and defense aviation program directors grounded qualitative assessment, validated against synthetic training device shipment databases, FAA certification records, EU Green Deal implementation reports, and CAAC regulatory filings. Bottom-up vendor revenue aggregation and top-down aviation training expenditure analysis provided triangulation.
Segment-level value outputs across technology, application, end user, and deployment dimensions were generated through driver-based modeling over the projection horizon. CAGRs were derived from hardware replacement cycle analysis, regulatory acceptance timelines, and cloud-rendering adoption curves. Foveated rendering penetration rates and EASA virtual-reality hour credit accumulation patterns served as aviation-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CAAC regulatory acceptance timing, semiconductor foundry capacity allocation shifts, and perceptual equivalence study validation results. Outputs reflect documented assumptions regarding certification pathway harmonization and defense budget cycle continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
US Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
France Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market