
 Hydrostatic Testing Market | 2026-2036
Hydrostatic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrostatic Testing Market Outlook
Multi-source outsourcing of hydrostatic validation work is expanding across pipeline operators and pressure equipment owners who previously relied on captive testing crews. International Pipeline Products Limited leverages its specialized pipeline pigging and testing integration to anchor large-diameter transmission contracts. JM Test Systems sustains geographic density across the Gulf Coast through accredited calibration and field hydrostatic services. Rice HYDRO competes on portable high-pressure pump systems that reduce mobilization costs for remote construction sites.
Hydrostatic testing subjects pressure vessels, pipelines, and containment systems to water-filled pressurization above normal operating levels to verify structural integrity and identify leak paths. Test protocols typically apply pressures at 1.3 to 1.5 times maximum allowable working pressure while measuring deformation, weepage, or catastrophic failure modes across welded seams, flanges, and threaded connections. Pressure testing services within the service type dimension dominate current revenue pools due to recurring regulatory mandates, while pipeline integrity applications absorb the fastest-growing share of capital as aging gathering and transmission networks face accelerated replacement schedules. Hydraulic pumps within the equipment type category concentrate manufacturing margin with specialized plunger and intensifier designs rated above 10,000 psi.
PHMSA pipeline safety regulations, ASME Boiler and Pressure Vessel Code Section VIII, and API 510/570 inspection standards collectively shape compliance-driven demand cycles across the United States. OSHA process safety management requirements and EPA spill prevention mandates further tighten testing frequencies for facilities handling hazardous fluids above threshold quantities. Stakeholders must monitor evolving PHMSA rulemakings on class location changes and maximum operating pressure confirmations to anticipate surge demand for inline and standalone hydrostatic requalification services.
Market Dynamics
PHMSA-mandated integrity management programs are compressing testing cycles across midstream pipeline networks, forcing operators to outsource validation work at volumes exceeding captive crew capacity. This regulatory pressure is restructuring service procurement patterns across North America and Europe.
Growth Catalysts
- PHMSA Integrity Management:Mandatory requalification timelines for Class 3 and Class 4 locations generate recurring demand for inline and standalone hydrostatic services across high-consequence areas.
- Offshore Wind Installation:Subsea cable burial and platform foundation work requires pressure testing of hydraulic tensioning systems and grout lines at depths exceeding 500 meters.
- Hydrogen Infrastructure Readiness:Pipeline repurposing projects for hydrogen transport necessitate upgraded hydrostatic protocols to address embrittlement risks in high-strength steel grades.
Market Restraints
- Specialized Pump Supply Concentration:Manufacturing of plunger pumps rated above 15,000 psi concentrates among German and Italian component suppliers, creating lead time vulnerability.
- Water Disposal Costs:Test fluid treatment and discharge compliance under EPA NPDES permits add 12-18% to total project costs in environmentally sensitive watersheds.
- Ultrasonic Testing Substitution:Phased-array ultrasonic corrosion mapping reduces hydrostatic requalification frequency for certain pipeline segments under API 1163 guidelines.
Strategic Opportunities
- Brazil Pre-Salt Expansion:Petrobras-led development of ultra-deepwater fields creates demand for subsea manifold and flowline testing at pressures exceeding 10,000 psi.
- Digital Twin Integration:Real-time deformation monitoring during pressurization cycles enables predictive integrity modeling and reduces retest frequency.
- Modular Skid Packaging:Containerized pump and data acquisition systems reduce mobilization costs for remote shale gathering projects in the Permian and Bakken.
Industry Challenges
- ASME Authorized Inspector Shortage:Certification bottlenecks for Section VIII vessel inspectors extend project timelines by 3-6 weeks in active construction corridors.
- Legacy Documentation Gaps:Pre-1970 pipeline records often lack original mill test certificates, forcing conservative pressure ratings that inflate testing scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrostatic Testing Market |
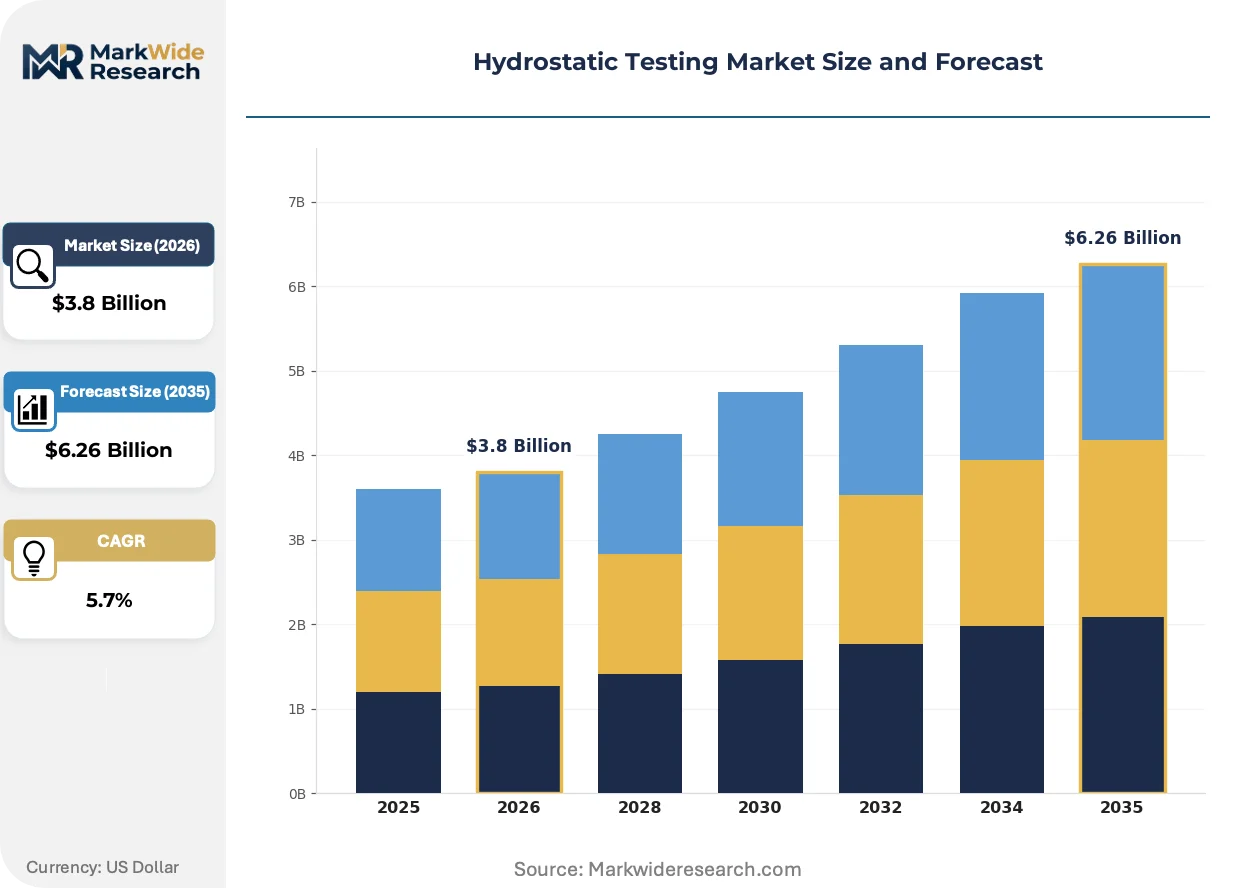
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pressure Testing, Leak Testing, Calibration, Inspection End User: Oil & Gas, Manufacturing, Construction, Marine Equipment Type: Hydraulic Pumps, Valves, Testers, Gauges Application: Pipeline Integrity, Vessel Testing, Fire Safety, Industrial Equipment |
| Companies Covered | International Pipeline Products Limited, JM Test Systems, Galiso, Rice HYDRO, Pumps Australia Pty Ltd, Hydro-Test Products, H. Lorimer Corp, COSMO INSTRUMENTS CO., LTD., Greene’s Energy Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrostatic Testing Market Strategic Shifts
Digital instrumentation and remote monitoring capabilities are displacing manual gauge reading and paper-based recording across field testing operations. This instrumentation shift is compressing data turnaround times and enabling real-time anomaly detection.
Automated pressure control systems with closed-loop servo valves are unifying pump operation, data logging, and safety interlock functions into single-skid platforms. Offshore contractors in the Gulf of Mexico and North Sea are adopting these integrated systems for platform hookup campaigns. The technology is unifying previously separate equipment procurement streams and reducing crew size requirements for complex multi-point tests.
EPA's proposed methane emissions reduction standards under the Clean Air Act are tightening leak detection and repair protocols for compressor stations and processing facilities. Facility operators must now document pressure boundary integrity on shorter cycles. Gas transmission utilities in the Appalachian and Permian basins are expanding hydrostatic scope to include station piping and vessel farm requalification.
Owner-operators are consolidating testing contracts under multi-year framework agreements with integrated service providers. This procurement consolidation displaces project-by-project bidding and favors vendors with accredited calibration laboratories and geographic density. The shift is most visible among midstream master limited partnerships seeking to standardize integrity management across dispersed asset portfolios.
Hydrostatic Testing Market Segmentation
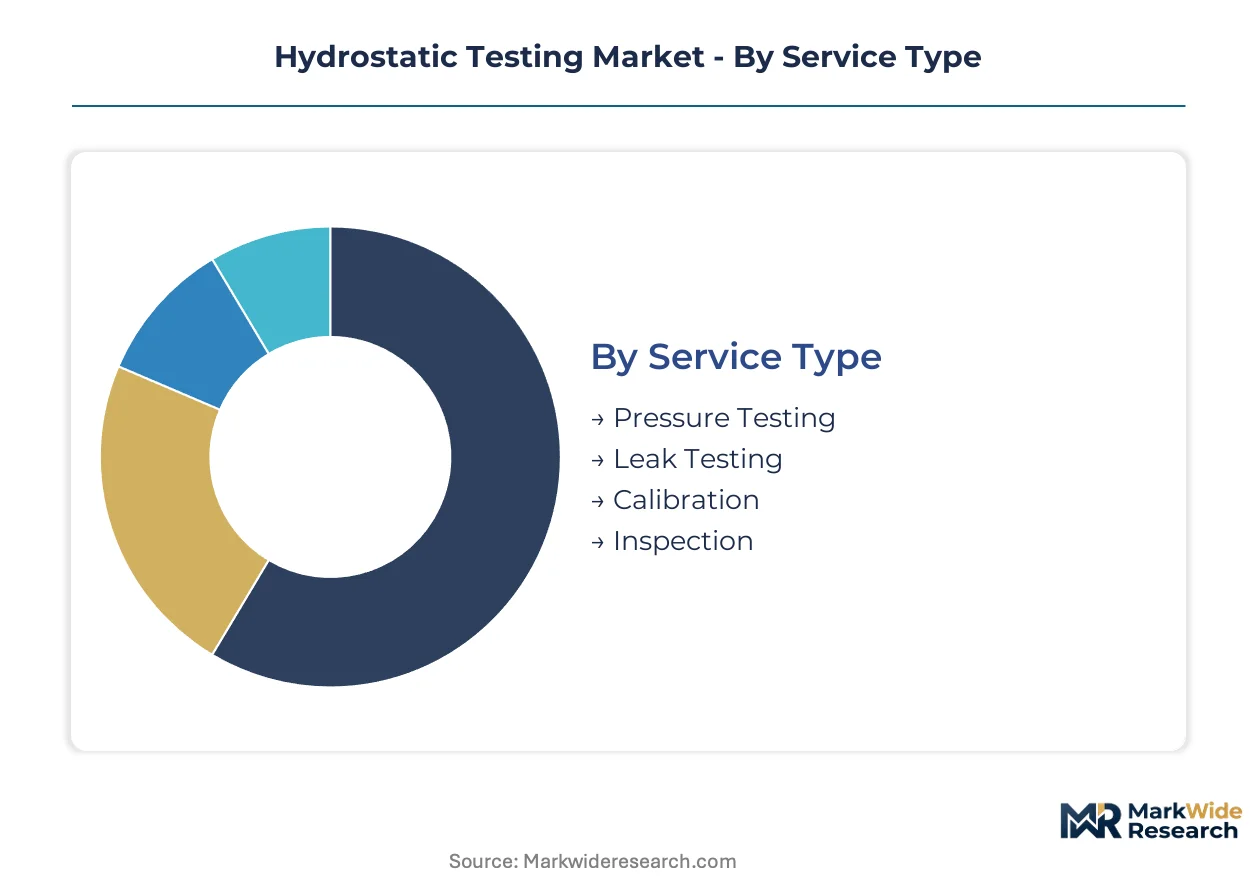
Segmentation in hydrostatic testing reflects divergent compliance burdens and capital intensity across service delivery modes. Equipment categories concentrate manufacturing margin in specialized high-pressure components, while service types map directly to regulatory requalification cycles.
Service Type:
ASME BPVC Section VIII and API 570/510 inspection codes impose distinct certification requirements across service modalities, with pressure testing bearing the heaviest third-party witness obligations.
- Pressure Testing:Water-filled pressurization to 1.3-1.5 times maximum allowable working pressure dominates revenue pools due to recurring PHMSA-mandated integrity management programs across United States transmission networks. Midstream operators outsource these services at volumes exceeding captive crew capacity.
- Leak Testing:Bubble emission and pressure decay methods verify seal integrity in flanged and threaded connections, with demand concentrating in Appalachian gas processing facilities facing EPA methane reduction protocols. Test documentation requirements have tightened under revised Clean Air Act standards.
- Calibration:Traceable gauge and transducer verification against NIST-standards sustains field measurement accuracy for construction contractors and maintenance crews.
- Inspection:Visual and dimensional examination of deformation, weepage, and crack propagation supports requalification decisions for aging vessel fleets.
Leading the category by volume: Pressure Testing. Growing fastest: Leak Testing.
End User:
Capital deployment cycles and regulatory exposure vary sharply across end-use sectors, with oil and gas absorbing the highest per-facility testing expenditure.
- Oil & Gas:Pipeline integrity programs and vessel requalification mandates under PHMSA and API standards generate sustained procurement of inline and standalone hydrostatic services. United States midstream replacement cycles sustain above-average service demand.
- Manufacturing:ASME-certified pressure vessel fabrication requires stage-gate testing during production, with boiler and heat exchanger OEMs integrating validation into quality systems.
- Construction:Fire suppression system commissioning and structural steel tensioning create project-based demand peaks tied to commercial and infrastructure build schedules.
- Marine:Subsea manifold, flowline, and platform foundation testing at depths exceeding 500 meters demands specialized hydraulic tensioning validation for offshore wind and pre-salt developments.
Revenue concentrates in Oil & Gas. Steepest expansion trajectory: Marine applications from offshore wind installation growth.
Equipment Type:
Manufacturing margin clusters in high-pressure pump systems where German and Italian component suppliers dominate specialized plunger and intensifier designs.
- Hydraulic Pumps:Plunger and intensifier designs rated above 10,000 psi command premium positioning due to supply concentration among European component specialists. Lead time vulnerability creates procurement risk for remote project mobilization.
- Valves:High-pressure isolation and control valves enable precise pressure boundary management during multi-point test sequences.
- Testers:Integrated skid platforms unifying pump operation, data logging, and safety interlock functions displace fragmented equipment procurement.
- Gauges:Digital instrumentation with remote telemetry capabilities compress data turnaround times and enable real-time anomaly detection.
Margin leadership: Hydraulic Pumps. Fastest technology refresh: Testers from automated control system adoption.
Application:
Testing protocols diverge between static pressure boundary validation and dynamic integrity monitoring, with pipeline applications facing the most compressed requalification timelines.
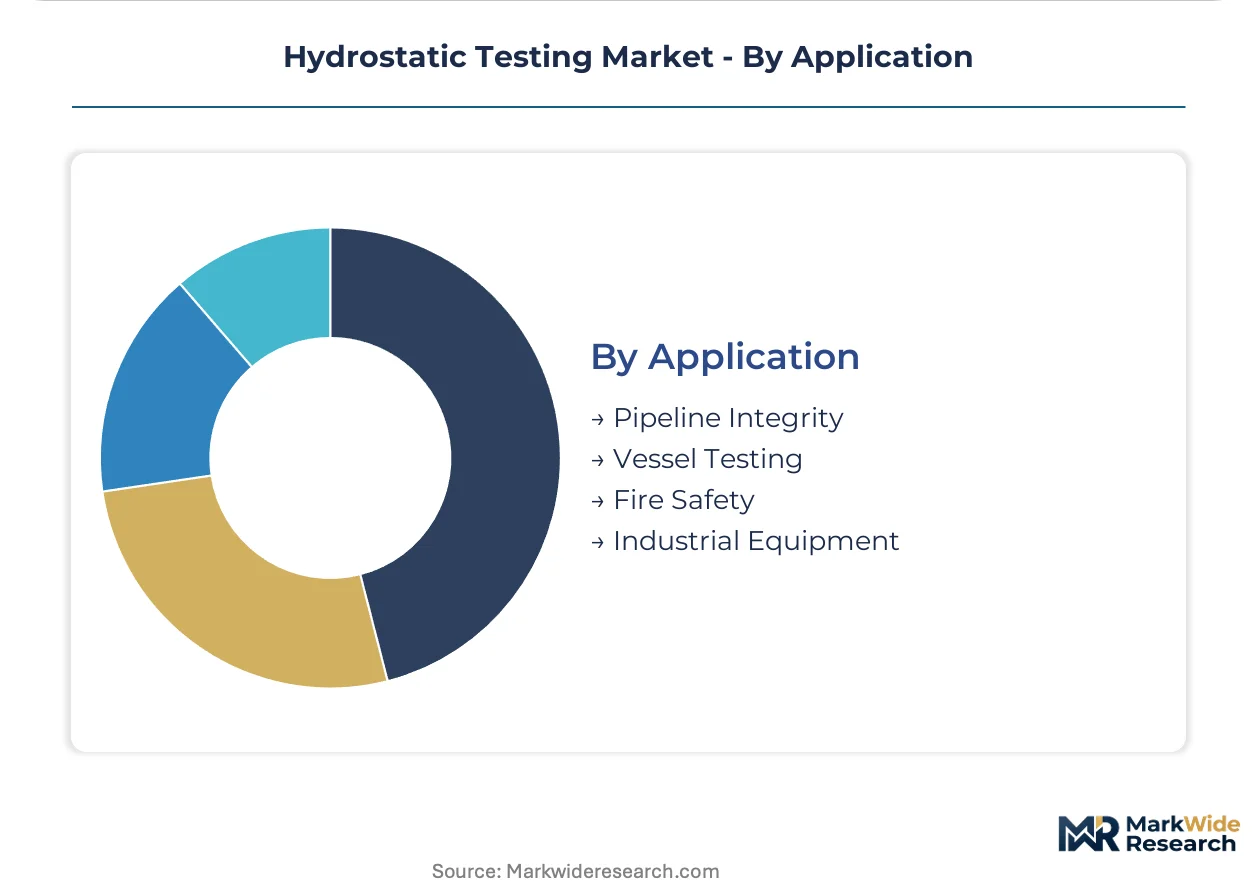
- Pipeline Integrity:Inline and standalone hydrostatic requalification for Class 3 and Class 4 high-consequence areas drives fastest-growing capital absorption as aging gathering and transmission networks face accelerated replacement schedules.
- Vessel Testing:ASME Section VIII pressure vessel requalification sustains steady demand from petrochemical and power generation facilities.
- Fire Safety:Sprinkler and standpipe system commissioning follows NFPA 13 and 25 protocols in commercial and institutional construction.
- Industrial Equipment:Hydraulic system validation for manufacturing and material handling equipment supports preventive maintenance programs.
Pipeline Integrity claims the steepest growth curve. Vessel Testing maintains the largest installed base requiring periodic requalification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mill clusters in the Ruhr Valley and Gulf Coast petrochemical corridors anchor hydrostatic testing infrastructure. Specialized pump fabrication concentrates near German industrial centers, while field service networks radiate from United States shale basins and North Sea offshore hubs.
United States
Midstream pipeline replacement cycles and PHMSA-mandated integrity management programs sustain above-average service procurement. The Pipeline and Hazardous Materials Safety Administration compresses requalification timelines for Class 3 and Class 4 high-consequence areas. Houston-Gulf Coast corridor operators outsource validation work at volumes exceeding captive crew capacity.
Germany
Industrial valve and pump OEMs drive recurring demand for ASME-certified pressure vessel validation. The country's national technical standards institute enforces strict conformity assessment for pressure equipment under the Pressure Equipment Directive implementation. Ruhr Valley manufacturing clusters host specialized plunger pump fabricators supplying global hydrostatic systems.
Brazil
Petrobras-led ultra-deepwater pre-salt development creates demand for subsea manifold testing above 10,000 psi. The national petroleum regulator mandates pressure boundary integrity verification for subsea production systems. Santos Basin offshore contractors procure specialized hydraulic tensioning validation for platform foundation work.
China
Pipeline network expansion for natural gas distribution and hydrogen transport readiness accelerates hydrostatic protocol adoption. The Ministry of Ecology and Environment tightens wastewater discharge standards for test fluid treatment under national pollution control mandates. Yangtze River Delta industrial zones concentrate domestic pump manufacturing capacity for mid-pressure applications.
United Kingdom
North Sea decommissioning and offshore wind installation sustain subsea testing demand for hydraulic tensioning systems. The Health and Safety Executive enforces pressure systems safety regulations across offshore asset integrity programs. Aberdeen energy service clusters anchor specialized diving support and subsea validation contractor networks.
Hydrostatic Testing Market Competitive Environment
Global majors compete with regional champions across equipment fabrication and field service delivery. The vendor base separates into three tiers: integrated pipeline service conglomerates, specialized testing equipment manufacturers, and regional calibration laboratories. Strategic archetypes include captive oilfield service divisions, independent accredited laboratories, and pump OEMs extending into service contracts. Competitive moves concentrate on multi-year framework agreements and geographic density expansion through accredited laboratory networks.
Among the named specialists, International Pipeline Products Limited and Rice HYDRO occupy positions within the integrated service tier, while JM Test Systems exemplifies the regional laboratory archetype with Gulf Coast density. These companies represent distinct strategic approaches to hydrostatic validation procurement consolidation among midstream operators.
| Leading Market Players |
|---|
| International Pipeline Products Limited |
| JM Test Systems |
| Galiso |
| Rice HYDRO |
| Pumps Australia Pty Ltd |
| Hydro-Test Products |
| H. Lorimer Corp |
| COSMO INSTRUMENTS CO., LTD. |
| Greene's Energy Group |
| Others |
Value Chain & Pricing Dynamics
Midstream master limited partnerships concentrate procurement authority under multi-year framework agreements, anchoring contract-based long-term pricing that bundles field services with accredited laboratory calibration. This buyer consolidation favors integrated vendors capable of delivering geographic density across dispersed shale basins.
Pricing Analysis
Warranty and service bundling separates premium-tier providers offering real-time telemetry and predictive maintenance from unbundled economy operators supplying bare equipment rental. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ASME certification grade and after-sales support depth. Cost compression in the economy tier is intensifying because Brazilian and Chinese pump manufacturers are expanding mid-pressure capacity. Pipeline operators with PHMSA-mandated integrity programs show lowest price sensitivity, while independent construction contractors exhibit highest sensitivity to mobilization cost variations.
Supply Chain Analysis
Local-content rules in Brazil's pre-salt development and China's hydrogen infrastructure programs are reshaping sourcing toward domestic pump fabricators and certified inspection personnel. Manufacturing of specialized plunger pumps rated above 15,000 psi concentrates in Germany, Italy, and the United States. Component supply draws from high-strength steel forgings, ceramic plungers, and precision servo valves. Single-source vulnerability persists for intensifier designs above 20,000 psi where two German OEMs control proprietary technology. Distribution runs through authorized service networks anchored in Houston, Aberdeen, and Singapore offshore hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated pressure control systems with closed-loop servo valves are displacing manual pump operation and paper-based data logging, compressing crew requirements and enabling real-time anomaly detection across field testing operations.
For Market Incumbents: To counter ultrasonic testing substitution under API 1163 guidelines, deepen integration into digital twin platforms that combine hydrostatic deformation data with predictive integrity modeling. Expand accredited calibration laboratory networks into the Permian and Bakken to capture modular skid packaging demand from remote shale gathering projects.
For New Entrants and Emerging Players: Capture white-space opportunity in subsea manifold testing for Brazil's pre-salt expansion, where pressure requirements exceeding 10,000 psi and local-content mandates create barriers for established North American vendors. Target Petrobras contractor qualification programs as the primary go-to-market pathway, partnering with existing diving support operators to bypass capital-intensive vessel ownership.
For Investors and Strategic Acquirers: The window for entry favors regional calibration laboratories with ASME Section VIII authorization and established relationships with midstream master limited partnerships. Monitor PHMSA rulemakings on class location changes and maximum operating pressure confirmations as the primary signal for surge demand inflection in inline and standalone hydrostatic requalification services.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Real-time deformation monitoring enables predictive integrity modeling and reduces retest frequency for pipeline operators. |
| Modular Skid Packaging | Containerized pump and data acquisition systems reduce mobilization costs for remote Permian and Bakken shale projects. |
| ASME Certification Investment | Section VIII vessel inspector accreditation addresses 3-6 week project timeline extensions from certification bottlenecks. |
| Local-Content Partnership | Brazilian pre-salt development mandates domestic sourcing for subsea manifold testing above 10,000 psi. |
| Hydrogen Protocol Development | Upgraded hydrostatic testing addresses embrittlement risks in high-strength steel pipeline repurposing projects. |
Study Parameters
Document review covered PHMSA incident databases, ASME BPVC Section VIII interpretation bulletins, and API 570/510 inspection code revisions, complemented by interviews with pipeline integrity managers, ASME authorized inspectors, hydrostatic service procurement leads at midstream operators, and specialized pump OEM technical directors. Secondary validation drew from EPA NPDES permit filings, FERC pipeline certification records, and offshore contractor equipment procurement disclosures. Bottom-up service provider revenue estimates and top-down regulatory mandate projections were triangulated to establish market sizing boundaries.
Historical spending patterns on integrity management programs were cross-referenced against expert panel assessments of regulatory enforcement intensity and replacement cycle timing. The analytical framework modeled service type, equipment category, application, and end-use industry dimensions across the projection horizon. CAGRs were derived from regression analysis of regulatory compliance cycle compression and capital deployment patterns in pipeline replacement. Industry-specific inputs included PHMSA class location reclassification frequency and subsea installation depth requirements for offshore wind foundation work.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ultrasonic testing substitution rates, hydrogen infrastructure buildout timing, and Brazilian pre-salt development pace. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and OEM supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Microcontroller Embedded Systems Market
Others
Brown Ht Market
Others
France Smart Home Market
Others
US Camping and Caravanning Market
Others
Digital Tattoos Market
Others
China Packaging Primers Market
Others
Bird Food Market
Others
Corn Fiber Market
Others
Industrial Gauges Market
Others
North America Smart Homes Market
Others
Global Contactless Biometrics Technology Market
Others
Underwater Lighting Market
Others
Mobile Computing Devices Market
Others
Hypersensitivity Market
Others
Security Envelopes Market
Others
Global Telemetry Market