
 Global Smart Glasses for Augmented Reality Market | 2026-2036
Global Smart Glasses for Augmented Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Glasses for Augmented Reality Market Outlook
ISO/IEC 15026 system safety certification is rotating as a gating standard for enterprise procurement cycles. Vuzix leverages its defense and industrial channel depth to sustain long-term contracts. Meta anchors consumer mindshare through Reality Labs hardware development. Xreal competes aggressively on price-performance in the tethered glasses segment for gaming and entertainment use.
Smart glasses for augmented reality integrate waveguide or birdbath optical engines with inertial measurement units, rendering digital overlays at 60-120 frames per second onto physical environments for hands-free information access. The primary commercial purpose spans remote expert guidance, procedural training, and spatial computing interfaces across factory floors and surgical suites. Tethered configurations currently dominate volume shipments due to lower bill-of-materials costs, while optical see-through technology leads in enterprise margins where transparency and situational awareness command premium positioning. Standalone headsets are gaining fastest in healthcare applications where cable-free mobility around patients is non-negotiable.
The FCC regulates radio frequency emissions from AR glasses in the United States, while the EU AI Act imposes conformity assessment burdens on biometric inference capabilities. Japan's METI promotes JIS-standardized interoperability frameworks to accelerate industrial adoption. Stakeholders must monitor how divergent electromagnetic compatibility and data governance regimes fragment certification roadmaps across target markets.
Market Dynamics
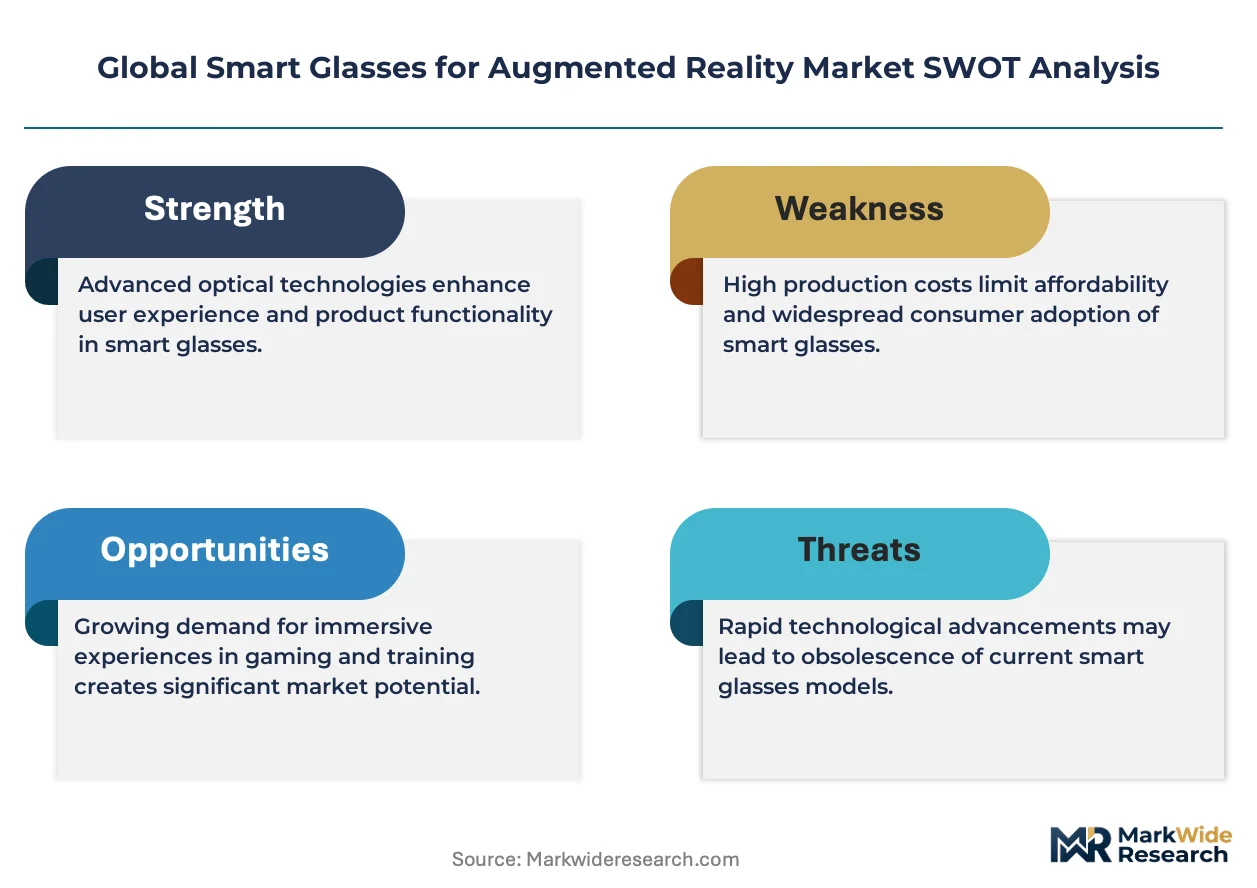
Enterprise procurement cycles for AR glasses are hardening around ISO/IEC 15026 system safety certification as a mandatory gating requirement, compressing vendor qualification timelines and elevating compliance costs for optical see-through hardware suppliers competing in defense and surgical verticals.
Growth Catalysts
- EU AI Act biometric inference rules:Germany's industrial manufacturing sector is accelerating head-mounted AR deployments for assembly line guidance to pre-empt conformity assessment deadlines and secure grandfathered operational approvals.
- Waveguide optical engine maturation:Shenzhen's hardware ecosystem is driving bill-of-materials compression for tethered configurations, expanding addressable volume in gaming and entertainment segments.
- JIS-standardized interoperability:Japan's METI framework is reducing integration friction for factory-floor AR systems, catalyzing cross-vendor procurement in automotive and electronics assembly.
Market Restraints
- Optical see-through yield volatility:Waveguide manufacturing defect rates in precision glass lamination constrain supply elasticity and inflate unit economics for enterprise-grade transparency systems.
- FDA Class II device pathway:Software validation requirements for surgical AR overlays extend regulatory timelines, delaying commercialization in North American healthcare markets.
- Smartphone tethering dependency:Consumer segment demand remains coupled to external compute devices, limiting standalone margin expansion and creating substitution exposure to tablet-based remote guidance.
Strategic Opportunities
- Standalone headset healthcare mobility:Cable-free configurations around patient bedsides in Japan and Germany command premium positioning where infection control and spatial flexibility are non-negotiable.
- California developer corridor concentration:Spatial computing interface talent pools in San Francisco and Los Angeles enable rapid prototyping partnerships for enterprise workflow customization.
- CSRD supply chain disclosure mandates:European enterprise buyers are prioritizing vendors with documented ethical mineral sourcing and carbon footprint transparency in AR hardware procurement.
Industry Challenges
- Electromagnetic compatibility fragmentation:Divergent FCC radio frequency emission limits and EU RED conformity assessment create multi-track certification roadmaps, inflating engineering overhead for simultaneous market entry.
- Optomechanical integration skill scarcity:Waveguide alignment and inertial measurement unit calibration expertise concentrates in Shenzhen and Tokyo, constraining rapid scaling in secondary manufacturing locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Glasses for Augmented Reality Market |
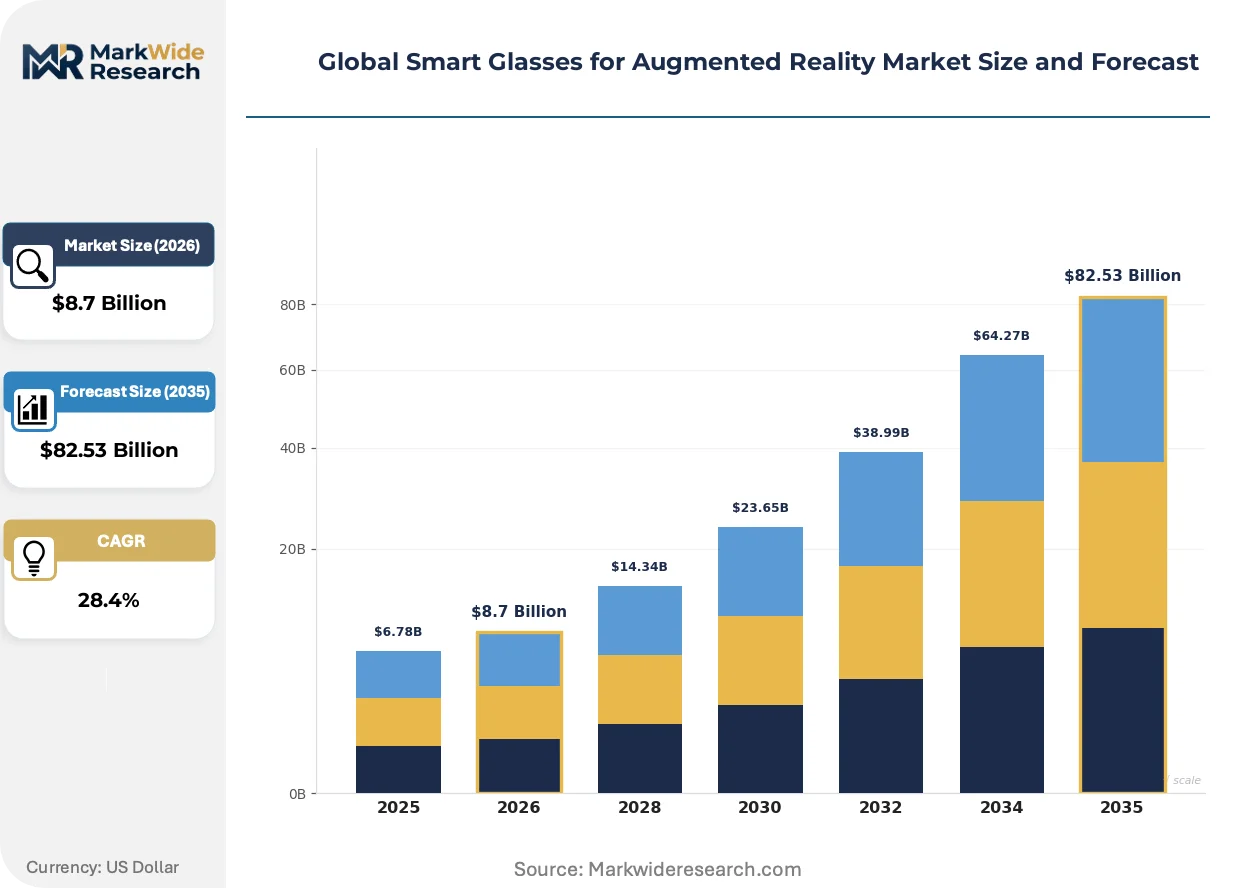
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
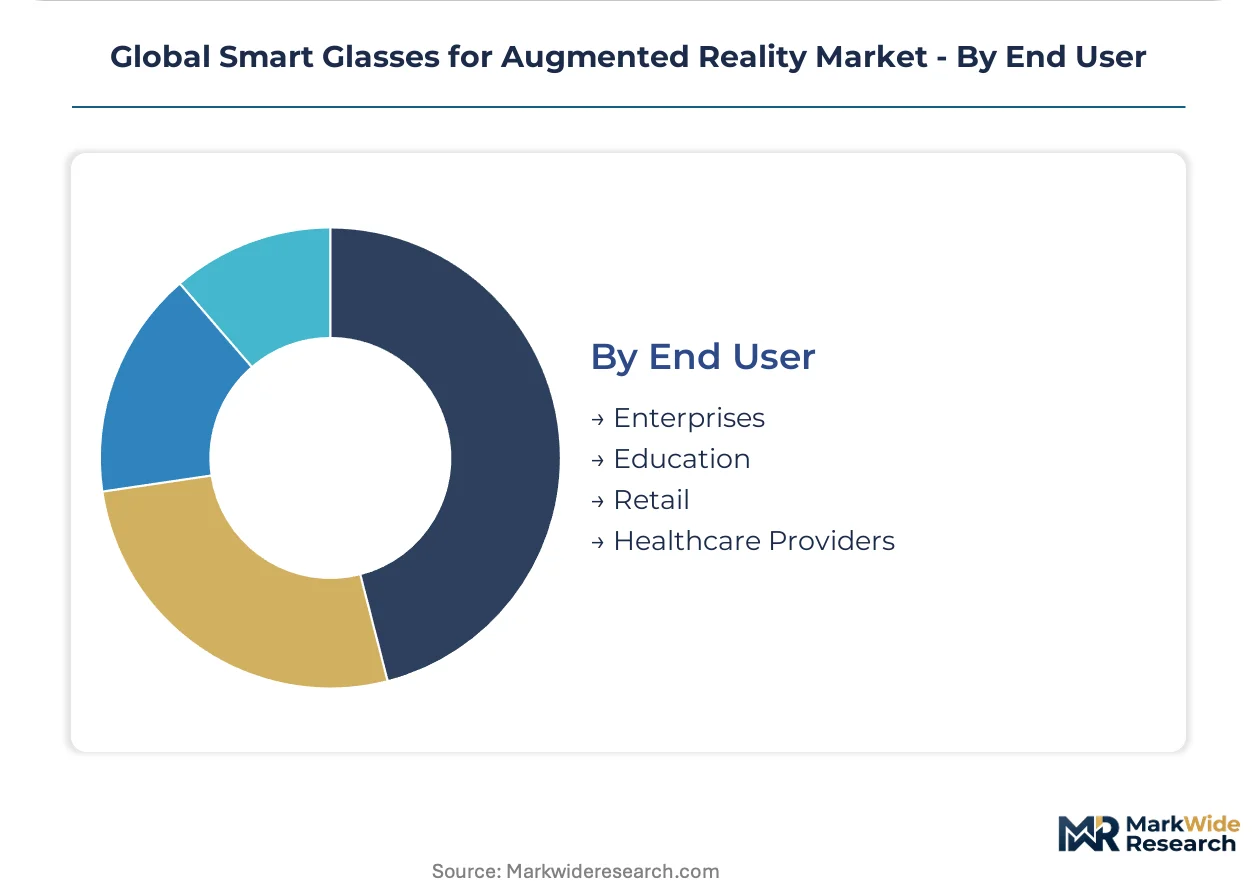
| Segmentation | Product Type: Standalone, Tethered, Smart Eyewear, Headset Technology: Optical See-Through, Video See-Through, Projection-Based, Holographic Application: Industrial Training, Healthcare, Gaming, Remote Assistance End User: Enterprises, Education, Retail, Healthcare Providers |
| Companies Covered | Vuzix, Amazon, Meta, Rokid, Varjo, Xreal, Snap Inc., XGIMI, RayNeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Glasses for Augmented Reality Market Strategic Shifts
Diffractive waveguide architectures and birdbath optical engines are compressing form factors while elevating field-of-view performance, reshaping competitive differentiation between tethered consumer devices and standalone enterprise systems.
Micro-LED display technology is miniaturizing emissive pixel arrays to sub-10-micron pitch, enabling brighter outdoor-readable overlays. Defense and industrial buyers in Germany and Japan are piloting these panels for harsh-environment deployments. The technology is miniaturizing thermal management requirements, allowing sealed ingress-protection ratings previously unattainable with liquid-crystal-on-silicon alternatives.
The EU AI Act's risk-based classification system is imposing algorithmic transparency obligations on biometric inference capabilities embedded in AR glasses. Optical see-through systems with facial recognition or emotion detection must undergo notified body assessment, compressing product development timelines. Enterprise vendors are responding by segregating compute architectures between EU and non-EU SKUs to isolate regulatory exposure.
Certification-driven procurement preferences are displacing price-primary evaluation in enterprise segments. Buyers in surgical and heavy manufacturing verticals are mandating ISO 13485 medical device quality management or IEC 61508 functional safety documentation prior to pilot deployment. This behavioral shift is most visible in German automotive supply chains and Japanese precision equipment sectors, where liability frameworks elevate documented traceability above unit cost minimization.
Global Smart Glasses for Augmented Reality Market Segmentation
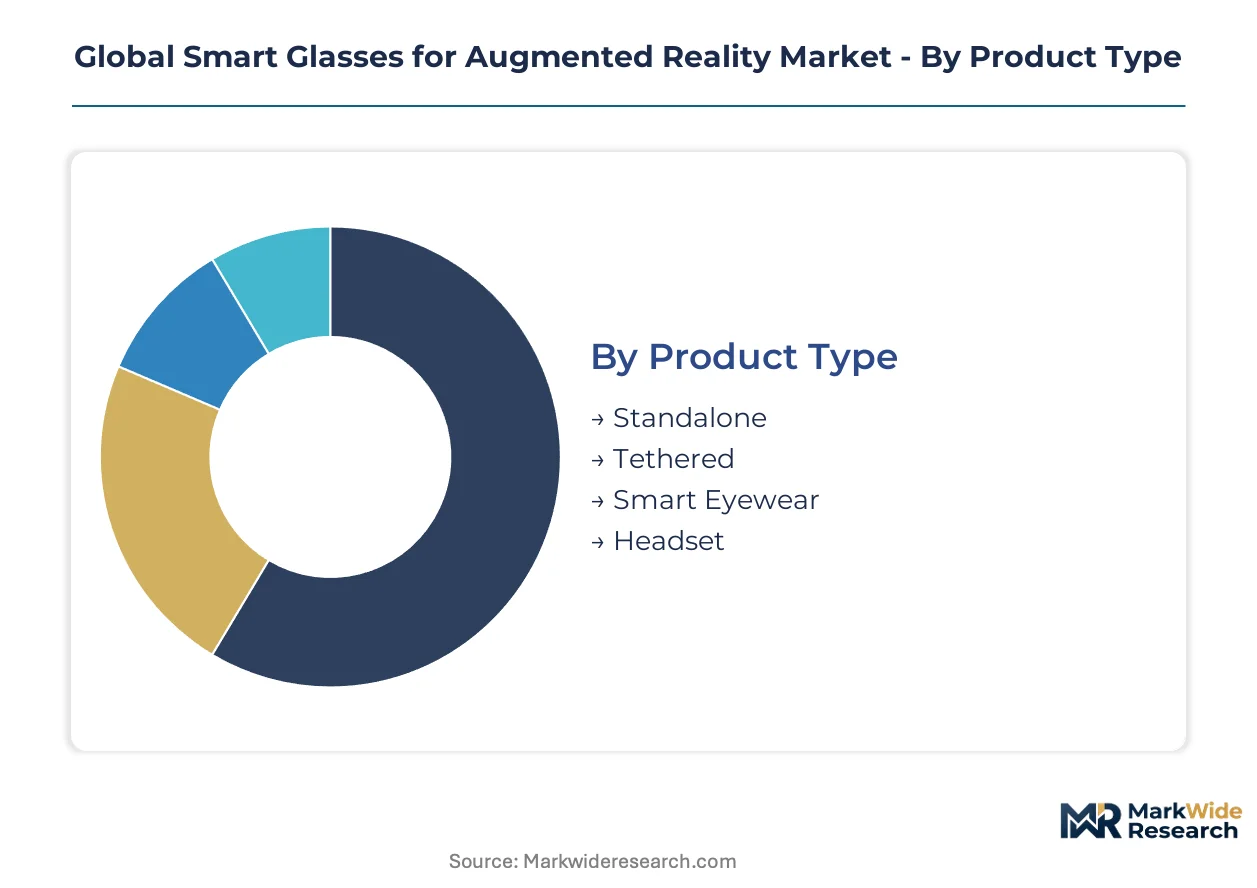
AR smart glasses segmentation reveals how hardware architecture, display technology, and use-case specificity determine procurement criteria and margin structures across defense, surgical, and consumer verticals. Understanding these partitions exposes where tethered configurations face displacement pressure from standalone alternatives and which optical engines command premium positioning.
Product Type:
Tethered configurations confront the most acute substitution pressure as smartphone compute dependency limits standalone margin expansion and creates vulnerability to tablet-based remote guidance alternatives.
- Standalone:Integrated SoC architectures with onboard rendering and battery systems enable cable-free mobility. Demand concentrates in Japanese and German healthcare settings where infection control protocols and patient bedside navigation are non-negotiable operational requirements.
- Tethered:External compute-dependent designs leverage smartphone or dedicated puck processing to minimize bill-of-materials costs. Shenzhen's hardware ecosystem drives volume production for gaming and entertainment segments where price-performance sensitivity dominates procurement decisions.
- Smart Eyewear:Lightweight notification-centric form factors prioritize all-day wearability over immersive AR capabilities. Early enterprise pilots in retail clienteling and logistics picking emphasize minimal visual obstruction.
- Headset:Over-ear audio-integrated designs target immersive training simulations and collaborative spatial computing environments. Bulkier profiles limit adoption outside controlled facility deployments.
Tethered configurations retain volume leadership; Standalone holds the steepest expansion curve.
Technology:
Cost tier stratification separates waveguide-based transparency systems from projection alternatives, with enterprise procurement gravitating toward optical see-through despite yield-driven unit economics premiums.
- Optical See-Through:Waveguide or birdbath architectures overlay digital content onto physical environments without camera mediation. German automotive supply chains and Japanese precision equipment sectors mandate ISO/IEC 15026 certification for these systems in assembly line guidance applications.
- Video See-Through:Camera-capture passthrough displays enable full environmental digitization and occlusion handling. Lower optical complexity reduces manufacturing defect exposure compared to precision glass lamination requirements.
- Projection-Based:Retinal or surface projection eliminates waveguide alignment tolerances. Emerging pilots in logistics and field service emphasize rapid deployment over optical fidelity.
- Holographic:Volumetric light-field generation enables focal plane variation without vergence-accommodation conflict. Research-stage deployments concentrate in California developer corridors for surgical planning and architectural visualization.
Optical See-Through commands enterprise margin premiums; Holographic displays the most aggressive R&D allocation trajectory.
Application:
Volume concentration in industrial training reflects ISO-standardized procurement maturation, while healthcare applications face elongated FDA and EU MDR validation timelines that compress commercialization velocity.
- Industrial Training:Procedural guidance and competency certification workflows leverage AR for hands-free instruction overlay. German manufacturing floors scale deployments ahead of EU AI Act biometric inference deadlines to secure operational grandfathering.
- Healthcare:Surgical navigation and remote expert consultation demand Class II device pathways and algorithmic transparency documentation. North American commercialization delays contrast with accelerated Japanese METI-standardized adoption.
- Gaming:Immersive entertainment experiences prioritize field-of-view expansion and latency minimization over enterprise-grade safety certification. Consumer price elasticity constrains optical engine selection to birdbath and simpler waveguide alternatives.
- Remote Assistance:Expert-guided field repair and maintenance workflows reduce technician dispatch requirements. Cross-vendor interoperability under JIS frameworks accelerates Japanese automotive and electronics assembly procurement.
Industrial Training anchors current shipment volumes; Healthcare applications face the most pronounced regulatory-induced expansion constraints.
End User:
Customer type determines certification burden distribution, with enterprise procurement hardening around documented quality management systems while education and retail segments prioritize deployment speed over liability documentation.
- Enterprises:Heavy manufacturing and defense buyers mandate IEC 61508 functional safety or ISO 13485 medical device quality documentation prior to pilot deployment. Procurement evaluation elevates traceability above unit cost minimization.
- Education:Vocational training institutions and research universities emphasize rapid prototyping partnerships over standardized validation. California spatial computing talent pools enable customized workflow development.
- Retail:Clienteling and inventory management applications prioritize lightweight form factors and minimal training requirements. CSRD supply chain disclosure mandates increasingly influence European vendor selection.
- Healthcare Providers:Hospital systems and surgical centers require FDA Class II clearance or EU MDR conformity assessment for diagnostic overlay applications. Software validation timelines extend procurement cycles substantially compared to industrial segments.
Enterprises dominate current revenue concentration; Healthcare Providers face the longest qualification intervals despite premium pricing tolerance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement archetypes concentrate in German automotive supply chains, Japanese precision manufacturing, and California spatial computing corridors, with regulatory divergence across FCC, EU AI Act, and METI frameworks fragmenting certification roadmaps.
United States
FDA Class II device pathways and FCC radio frequency emission limits govern surgical AR overlays and wireless connectivity. California developer corridors in San Francisco and Los Angeles anchor rapid prototyping partnerships for enterprise workflow customization. The analysis notes healthcare commercialization delays contrast with accelerated defense and industrial qualification.
Germany
Automotive supply chains and precision equipment sectors mandate ISO/IEC 15026 system safety certification for assembly line guidance. EU AI Act biometric inference deadlines are accelerating head-mounted AR deployments to secure grandfathered operational approvals. Industrial procurement in Bavaria and Baden-Württemberg elevates documented traceability above unit cost minimization.
Japan
METI promotes JIS-standardized interoperability frameworks to reduce integration friction for factory-floor systems. Automotive and electronics assembly in Kanto and Kansai regions catalyze cross-vendor procurement under unified technical specifications. Cable-free standalone configurations command premium positioning in Tokyo hospital systems where infection control protocols are non-negotiable.
China
Shenzhen's hardware ecosystem drives bill-of-materials compression for tethered configurations, expanding volume shipments in gaming and entertainment segments. MIIT standards and GB certification requirements shape electromagnetic compatibility compliance for domestic and export markets. Pearl River Delta manufacturing clusters concentrate waveguide alignment and optomechanical integration expertise.
United Kingdom
London and Southeast England anchor spatial computing talent pools for enterprise software development and AR interface design. CSRD supply chain disclosure mandates influence vendor selection criteria for European enterprise buyers with UK procurement operations. The analysis notes concentration in vocational training institutions emphasizing rapid prototyping over standardized validation.
Global Smart Glasses for Augmented Reality Market Competitive Environment
Player mix skews toward technology specialists with defense and industrial channel depth alongside consumer electronics conglomerates with Reality Labs-scale hardware development. The vendor base segments across three strategic archetypes: optical engine specialists, platform-integrated hardware developers, and price-performance challengers in tethered configurations. Dominant competitive moves include strategic partnerships for enterprise workflow customization and technology licensing for waveguide manufacturing scale.
Within the defense-industrial tier, Vuzix leverages long-term contract structures and established certification documentation. Meta anchors consumer mindshare through sustained hardware development investment. Xreal competes aggressively on price-performance metrics in tethered glasses segments. These three exemplify divergent strategic postures: certification-driven enterprise positioning, platform-integrated ecosystem development, and volume-focused consumer penetration.
| Leading Market Players |
|---|
| Vuzix |
| Amazon |
| Meta |
| Rokid |
| Varjo |
| Xreal |
| Snap Inc. |
| XGIMI |
| RayNeo |
| Others |
Value Chain & Pricing Dynamics
Ninety-day waveguide glass lamination lead times concentrate procurement leverage in Shenzhen and Tokyo manufacturing clusters, compressing margin buffers for optical see-through suppliers while elevating pricing power for certified component vendors serving German automotive and Japanese healthcare buyers.
Pricing Analysis
Cost-plus contracts with rare-earth oxide indexation dominate waveguide substrate procurement, insulating precision glass suppliers from lithium niobate spot volatility. Pricing stratifies across ISO 13485 medical device tiers, IEC 61508 functional safety grades, and uncertified consumer configurations. Cost compression in tethered birdbath configurations intensifies as Shenzhen ecosystem players expand wafer-level optics capacity. Gaming and entertainment segments exhibit acute price sensitivity, while surgical and defense buyers absorb premiums for documented traceability.
Supply Chain Analysis
Strait of Malacca transit underwrites micro-LED die and rare-earth magnet shipments to Shenzhen assembly floors, exposing AR hardware pipelines to maritime logistics congestion. Manufacturing gravity centers on China, Japan, and South Korea for waveguide lamination, precision IMU calibration, and display panel fabrication. Bill-of-materials volatility hinges on gallium arsenide wafer availability and precision glass substrate yields. Distribution runs through industrial integrators in Bavaria, METI-certified systems integrators in Kansai, and direct-to-consumer channels in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where FDA Class II and EU AI Act compliance documentation creates switching costs that lock enterprise buyers into validated supplier relationships.
For Market Incumbents: Shield certification-derived pricing power by accelerating ISO/IEC 15026 documentation breadth ahead of EU AI Act enforcement deadlines. Deepen backward integration into waveguide glass lamination to capture margin pools currently concentrated in Tokyo and Shenzhen specialty houses. Counter Xreal price-performance pressure in tethered segments through exclusive California developer corridor partnerships for enterprise workflow customization. For New Entrants and Emerging Players: Anchor in projection-based AR configurations where optical complexity barriers are lowest and rapid deployment cycles outpace waveguide yield constraints. Target logistics and field service applications where certification burdens remain minimal and JIS-standardized interoperability reduces integration friction. Pursue white-label manufacturing partnerships with Shenzhen ecosystem players to compress time-to-revenue. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across holographic display R&D, favoring patient capital deployment over near-term monetization pressure. Prioritize acquisition targets with established FDA 510(k) clearance pathways or grandfathered EU MDR technical documentation. Monitor EU AI Act notified body queue lengths as an inflection signal for enterprise procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 15026 Certification Investment | Unlocks German automotive supply chain procurement and commands premium positioning in surgical verticals. |
| Waveguide Manufacturing Scale-Up | Addresses yield volatility constraining optical see-through supply elasticity for enterprise transparency systems. |
| Strategic Partnership with California Developer Corridors | Accelerates spatial computing interface prototyping for customized enterprise workflow deployments. |
| Backward Integration into Precision Glass Lamination | Captures margin pools and reduces single-source dependency on Tokyo and Shenzhen specialty suppliers. |
| JIS-Standardized Interoperability Adoption | Reduces integration friction and catalyzes cross-vendor procurement in Japanese automotive assembly. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including AR hardware procurement managers at German automotive OEMs, biomedical engineers at Tokyo hospital systems, waveguide manufacturing directors in Shenzhen, and spatial computing software architects in San Francisco and Los Angeles. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, METI JIS standard publications, and SEC filings from publicly traded component suppliers. Bottom-up shipment estimates triangulated against top-down enterprise IT spending allocations across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs across product type segmentation, display technology tiers, application verticals, and end-user procurement archetypes. CAGRs were derived from fitted growth curves anchored to historical certification timeline data and enterprise pilot-to-deployment conversion rates. Industry-specific forecast inputs included waveguide yield improvement trajectories, EU AI Act notified body capacity constraints, and JIS standardization adoption curves in Japanese manufacturing.
Decision-makers should treat outputs as directional under base assumptions of sustained enterprise AR procurement acceleration and stable rare-earth supply; material deviation in waveguide yield breakthroughs or EU regulatory enforcement intensity would warrant model refresh. Practitioners should keep alternative scenarios live as FDA Class II clearance timelines and METI interoperability mandate schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
France Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality for Consumer Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Florida Augmented and Virtual Reality Market